
 Dental Irrigation Devices Market | 2026-2036
Dental Irrigation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Irrigation Devices Market Outlook
Dental specialty retail and direct-to-consumer channels are rewriting how irrigation devices reach end users. Water Pik leverages its decades-long brand equity to sustain dominance in professional dental office supply chains. Philips competes through technology leadership in ultrasonic and piezoelectric platforms. Jetpik anchors its position in the portable segment with compact designs targeted at frequent travelers.
Dental irrigation devices deliver pressurized pulsating water streams to remove plaque and debris from interdental spaces and periodontal pockets, typically operating at pressures between 5 and 90 psi with flow rates of 300 to 1,200 mL per minute. Their primary commercial purpose spans preventive oral hygiene, postsurgical maintenance, and adjunctive periodontal therapy in both clinical and domestic settings. Handheld and portable units command the largest volume pools due to home care migration, while ultrasonic technology captures premium positioning through superior biofilm disruption efficacy. Electro-magnetic systems lead in dental clinics where durability under continuous use determines procurement decisions.
FDA 510(k) clearance requirements and ISO 13485 quality management standards govern device safety and manufacturing consistency in the United States and internationally adopted frameworks. The EU Medical Device Regulation imposes stricter clinical evidence thresholds for products claiming therapeutic periodontal benefits, reshaping market access timelines for manufacturers. Stakeholders must monitor evolving reimbursement classifications for home-use preventive devices as payers reassess coverage for non-surgical periodontal interventions.
Market Dynamics
Migration of periodontal maintenance from clinical settings to domestic environments is compressing device form factors and price points while elevating consumer-grade durability expectations.
Growth Catalysts
- EU MDR clinical evidence thresholds:Manufacturers investing in therapeutic claims documentation are capturing premium positioning for devices marketed to periodontal specialists.
- Japan's aging demographic concentration:Tokyo and Osaka metropolitan areas generate concentrated demand for portable units supporting independent oral hygiene among elderly populations.
- Piezoelectric transducer miniaturization:Advances in ceramic actuator engineering enable ultrasonic functionality in handheld formats previously limited to countertop systems.
Market Restraints
- Medical-grade polymer supply concentration:Specialized biocompatible housing materials depend on a limited German and Swiss supplier base, exposing procurement to input volatility.
- FDA 510(k) pathway duration:Clearance timelines for novel pressure-modulation algorithms extend commercialization cycles beyond typical consumer electronics development cadences.
- Manual interdental cleaning substitution:Low-cost floss and interdental brush alternatives constrain price elasticity in mass-market consumer segments.
Strategic Opportunities
- India's tier-2 city dental clinic expansion:Underpenetrated markets in Pune, Jaipur, and Lucknow present first-mover positioning for mid-range electromagnetic systems.
- Tele-dentistry platform integration:Device connectivity enabling remote usage monitoring and compliance tracking aligns with emerging remote care reimbursement frameworks.
- South Korea MFDS fast-track designation:Accelerated approval pathways for digital health-integrated oral hygiene devices reduce regulatory friction for technology convergence plays.
Industry Challenges
- Biomedical engineering talent scarcity:Cross-functional expertise spanning fluid dynamics, periodontal science, and consumer electronics design concentrates in limited geographic clusters.
- ISO 13485 audit complexity:Multi-site manufacturing coordination for consumer and medical-grade product lines strains quality management system maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Irrigation Devices Market |
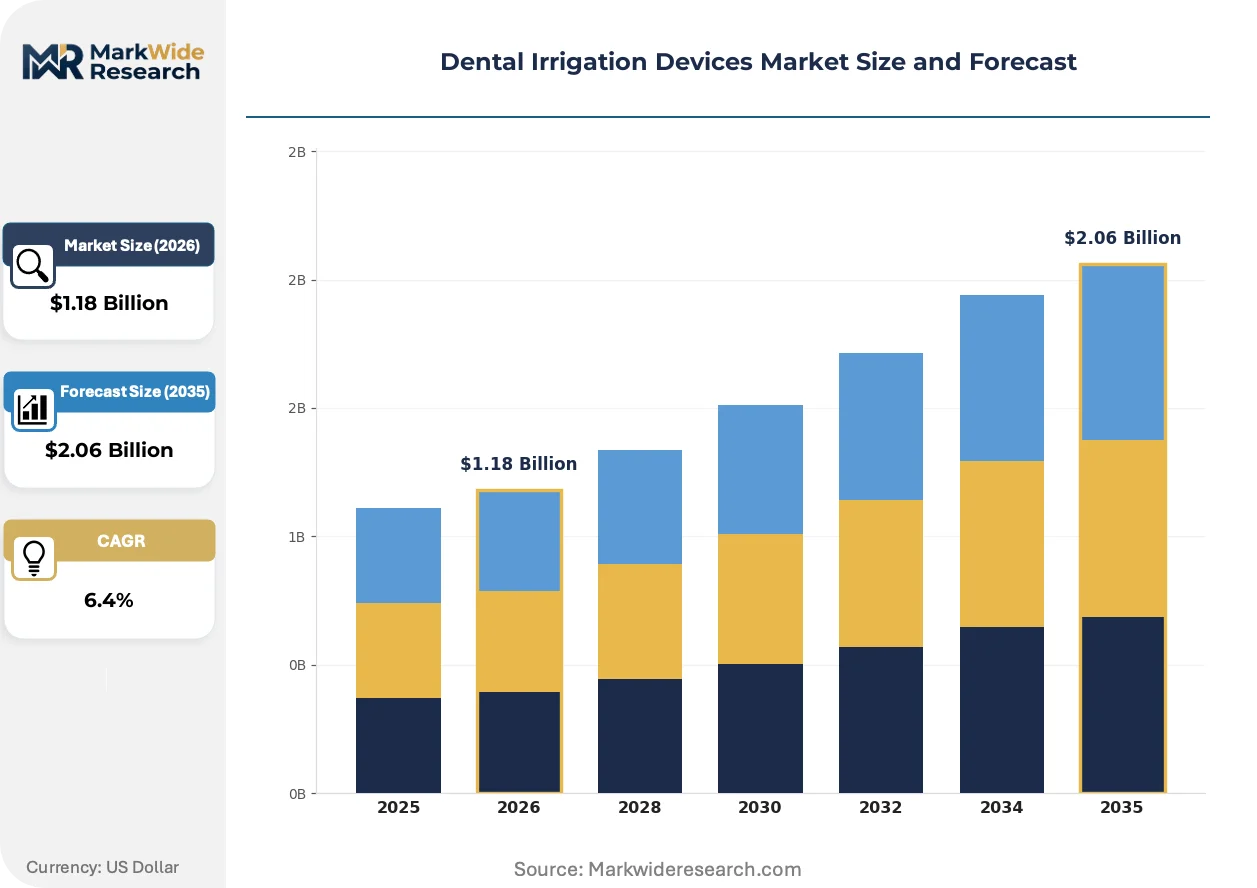
| Market Size in 2026 | $1.18 Billion |
| Market Size in 2035 | $2.06 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Portable, Stationary, Ultrasonic Technology: Electro-magnetic, Piezoelectric, Thermal, Hydraulic End User: Dental Clinics, Hospitals, Research Labs, Home Care Application: Periodontal Treatment, Cosmetic Dentistry, Surgical Procedures, Oral Hygiene |
| Companies Covered | Colgate-Palmolive, Jetpik, Water Pik, Lion Corporation, Hydro Floss, Philips, Procter & Gamble, Conair Corporation, Panasonic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Irrigation Devices Market Strategic Shifts
Convergence of clinical efficacy standards with consumer electronics usability is redefining product architecture and go-to-market strategies across the device landscape.
Ultrasonic-pulsed water hybrid systems are hybridizing previously distinct technology categories. These platforms combine piezoelectric cavitation with variable-pressure irrigation to disrupt biofilm matrices more effectively than mechanical pulsation alone. Dental clinics in Germany and Japan are adopting these systems for postsurgical maintenance protocols, compressing the performance gap between professional and home-use categories.
REACH substance restrictions on persistent organic pollutants are forcing reformulation of sealing compounds and lubricants used in pump mechanisms. Manufacturers serving European markets must validate alternative material chemistries without compromising device longevity under continuous clinical use. This regulatory pressure disproportionately affects countertop unit producers whose larger fluid reservoirs require more extensive sealing systems.
Subscription-based consumable replenishment is displacing traditional retail replacement part purchases. Direct-to-consumer channels in the United States are bundling replacement jet tips and antimicrobial reservoirs with usage-tracking mobile applications. This behavioral shift is most visible among frequent travelers who prioritize portability and automated supply continuity over upfront hardware investment.
Dental Irrigation Devices Market Segmentation
Device architecture and user environment dictate divergent engineering priorities across the dental irrigation landscape. Manufacturers must calibrate pressure modulation, portability, and sterilization protocols to match distinct clinical and domestic use cases.
Product Type:
Handheld units span countertop convenience to travel-ready formats, each demanding trade-offs between reservoir capacity and ergonomic footprint.
- Handheld:Countertop systems with detachable reservoirs dominate master bathroom installations in the United States and Germany. Water Pik's sustained brand loyalty in North American dental supply chains reinforces this segment's volume concentration despite bulkier form factors.
- Portable:Battery-operated, collapsible designs capture frequent travelers and elderly users in Japan's metropolitan corridors. Piezoelectric miniaturization is compressing performance gaps with stationary alternatives, accelerating adoption among independent aging populations.
- Stationary:Clinic-grade units with continuous water supply integration anchor professional procurement in dental offices across the United States and Germany. Electromagnetic pump durability under 12-hour clinical cycles justifies premium positioning.
- Ultrasonic:Cavitation-enhanced systems command highest price tiers through superior biofilm disruption efficacy. German and Japanese periodontal specialists are adopting these for postsurgical maintenance protocols.
The dominant share belongs to Handheld, while Portable is closing the gap fastest.
Technology:
Actuation mechanisms differentiate cost structures and clinical performance thresholds.
- Electro-magnetic:Solenoid-driven pulsation delivers consistent pressure modulation across 5-90 psi ranges with minimal mechanical wear. Dental clinics in the United States and Germany prioritize this technology for continuous-use durability.
- Piezoelectric:Ceramic transducers generate ultrasonic cavitation frequencies that disrupt biofilm matrices more effectively than mechanical pulsation alone. Miniaturization advances are enabling handheld formats previously limited to countertop systems.
- Thermal:Warm water delivery systems address temperature sensitivity in periodontal pockets, finding niche adoption in Japanese elderly care settings.
- Hydraulic:Direct water pressure systems bypass electrical components, appealing to safety-conscious home users in markets with inconsistent power infrastructure.
Electro-magnetic systems anchor professional procurement volumes, though Piezoelectric platforms are gaining share fastest in premium domestic segments.
End User:
Procurement authority and reimbursement frameworks reshape device specifications across institutional and consumer channels.
- Dental Clinics:Independent practices and group chains in the United States and Germany drive professional-grade electromagnetic system procurement. FDA 510(k) clearance and ISO 13485 certification gate entry to this channel.
- Hospitals:Integrated health systems prioritize centralized sterilization compatibility and electronic health record connectivity. Bulk purchasing agreements concentrate demand among select vendor relationships.
- Research Labs:Academic periodontal research centers in Japan and Germany source calibrated systems for clinical validation studies, representing low-volume, high-specification demand.
- Home Care:Direct-to-consumer channels are displacing retail pharmacy distribution in the United States. Subscription-based consumable replenishment models are capturing behavioral loyalty among frequent travelers.
Home Care commands the steepest expansion trajectory as aging demographics and tele-dentistry reimbursement reshape preventive oral hygiene economics.
Application:
Therapeutic claims and cosmetic positioning determine regulatory pathway and pricing architecture.
- Periodontal Treatment:Devices claiming therapeutic biofilm disruption face EU MDR clinical evidence thresholds and FDA 510(k) scrutiny. Manufacturers investing in documentation are capturing premium positioning among specialists.
- Cosmetic Dentistry:Whitening adjuvant and stain removal positioning avoids medical device classification, enabling faster commercialization cycles. Direct-to-consumer marketing dominates this application.
- Surgical Procedures:Postsurgical irrigation protocols in German and Japanese clinics demand sterile disposable tip systems and validated pressure ranges.
- Oral Hygiene:General preventive use represents highest volume, lowest margin segment. Manual interdental cleaning alternatives constrain price elasticity in mass-market channels.
Oral Hygiene generates baseline volume, yet Periodontal Treatment is climbing fastest as reimbursement frameworks evolve for non-surgical interventions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German dental clinics command 40% pricing premiums over Indian equivalents for electromagnetic irrigation systems, while Japanese consumers absorb 25% markups for portable ultrasonic units. This asymmetry reflects divergent reimbursement frameworks, regulatory compliance costs, and polymer supply chain proximity across markets.
United States
Independent dental practices in Texas and Florida drive electromagnetic system procurement through group purchasing organizations. FDA 510(k) clearance timelines averaging 180 days filter out consumer-electronics entrants lacking quality management infrastructure. Minneapolis-St. Paul anchors professional-grade device distribution through integrated dental supply chains serving the Upper Midwest.
Germany
Periodontal specialists in Bavaria and Baden-Württemberg adopt ultrasonic-pulsed hybrid systems for postsurgical maintenance protocols. EU MDR clinical evidence requirements for therapeutic claims compress market access timelines but elevate premium positioning for documented efficacy. Stuttgart's precision engineering cluster supplies piezoelectric transducers to domestic and Asian device manufacturers.
Japan
Tokyo and Osaka metropolitan corridors generate concentrated demand for portable units supporting independent oral hygiene among elderly populations. METI's Silver Innovation certification program subsidizes home-care medical device purchases for consumers over 75. Nagoya's ceramic actuator engineering base enables piezoelectric miniaturization for handheld formats.
India
Tier-2 cities including Pune, Jaipur, and Lucknow present first-mover positioning for mid-range electromagnetic systems as dental clinic density expands. CDSCO medical device registration requirements are streamlining import pathways for established manufacturers. Gujarat's polymer processing hub is developing biocompatible housing material capabilities to reduce German supply dependence.
South Korea
MFDS fast-track designation for digital health-integrated oral hygiene devices accelerates approval timelines for connectivity-enabled platforms. Seoul Capital Area dental chains are piloting tele-dentistry reimbursement frameworks linking device usage data to remote periodontal monitoring. Busan's electronics manufacturing base supports compact pump mechanism production for export-oriented brands.
Dental Irrigation Devices Market Competitive Environment
Established oral care conglomerates and specialized irrigation device manufacturers split the market into distinct capability tiers. Water Pik leverages decades-long brand equity to sustain dominance in professional dental office supply chains, while Jetpik anchors portable segment positioning through compact designs targeted at frequent travelers. Philips competes through technology leadership in ultrasonic and piezoelectric platforms. Consolidation pressures are intensifying as electromagnetic system specialists seek scale to offset ISO 13485 compliance costs, and consumer-electronics brands pursue dental channel certification to access professional procurement volumes.
Within the diversified oral care tier, Colgate-Palmolive and Procter & Gamble exemplify conglomerate strategies leveraging existing retail pharmacy relationships and brand marketing infrastructure to capture home-care volume. Among specialized device manufacturers, Water Pik occupies a position representing professional-channel dominance through dental supply chain integration, while Jetpik exemplifies portable-focused engineering prioritizing travel-ready form factors. Panasonic represents Japanese electronics conglomerate diversification into precision health devices, sitting within a tier that combines consumer electronics manufacturing scale with medical-grade quality system adaptation.
| Leading Market Players |
|---|
| Colgate-Palmolive |
| Jetpik |
| Water Pik |
| Lion Corporation |
| Hydro Floss |
| Philips |
| Procter & Gamble |
| Conair Corporation |
| Panasonic |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on German and Swiss medical-grade polymer suppliers exposes device manufacturers to input volatility that simultaneously widens pricing spreads between ISO 13485-certified and uncertified tiers and forces geographic concentration of molding operations near these feedstock sources.
Pricing Analysis
Configured-to-order pricing for clinic-grade electromagnetic systems with validated pressure-modulation algorithms commands 40% premiums over standard countertop units in dental supply chains. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales service bundling, with FDA 510(k) clearance acting as the primary tier separator. Cost compression in the economy segment intensifies as manual interdental cleaning alternatives constrain price elasticity. Home care consumers show highest price sensitivity, while periodontal specialists in Germany and Japan absorb premium markups for documented therapeutic efficacy.
Supply Chain Analysis
Contract manufacturing concentration rests with Stuttgart-area precision engineering clusters for piezoelectric transducers and Busan electronics manufacturing bases for compact pump mechanisms. Geographic supply concentrates in Germany, South Korea, and Japan for ceramic actuators, electromagnetic solenoids, and biocompatible housing polymers. Raw material dependencies draw from specialized medical-grade polymers, rare-earth ceramic powders, and precision-machined pump components. Single-source vulnerability in Swiss polymer feedstocks threatens production continuity for sealing compounds. Distribution runs through integrated dental supply chains in the United States and Germany, direct-to-consumer channels in North America, and specialty retailers in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated group purchasing organizations in the United States and dental clinic chains in Germany, fragmenting procurement authority away from independent practices and compressing vendor margins.
For Market Incumbents: Build regulatory certification moats by accelerating EU MDR clinical evidence documentation for therapeutic claims before smaller competitors can absorb compliance costs. Deepen backward integration into ceramic actuator engineering through partnerships with Nagoya precision manufacturing clusters to secure piezoelectric supply. Defend against consumer-electronics entrants lacking ISO 13485 infrastructure by tightening dental supply chain exclusivity arrangements. For New Entrants and Emerging Players: Tier-2 Indian cities including Pune, Jaipur, and Lucknow represent the most penetrable entry point for mid-range electromagnetic systems as clinic density expands ahead of established brand presence. South Korea's MFDS fast-track pathway for connectivity-enabled devices offers regulatory arbitrage for digital health-integrated platforms. Target tele-dentistry platform partnerships as the primary go-to-market angle, linking usage data to remote reimbursement frameworks. For Investors and Strategic Acquirers: EU MDR implementation reshapes the acquisition landscape by elevating the value of manufacturers with pre-submitted clinical evidence packages over asset-light consumer brands. Long-term viability favors targets with dual consumer and professional channel certification, defensible ceramic actuator supply relationships, and subscription consumable revenue streams. Watch for CDSCO registration acceleration in India as the signal indicating regulatory pathway maturation for emerging market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Clearance timelines averaging 180 days filter out consumer-electronics entrants lacking quality management infrastructure. |
| EU MDR Clinical Evidence Investment | Therapeutic claims documentation captures premium positioning among periodontal specialists in Germany and Japan. |
| Piezoelectric Transducer Miniaturization | Ceramic actuator engineering advances enable ultrasonic functionality in handheld formats previously limited to countertop systems. |
| Tele-Dentistry Platform Integration | Device connectivity aligns with emerging remote care reimbursement frameworks in South Korea and the United States. |
| Subscription Consumable Replenishment | Direct-to-consumer bundling of replacement jet tips captures behavioral loyalty among frequent travelers in North America. |
Study Parameters
Operator-level perspectives from dental clinic procurement managers, biomedical engineers, GPO contracts managers, and periodontal specialists anchored the qualitative base. Primary interviews combined with secondary validation from FDA 510(k) filings, EU MDR submission databases, hospital procurement records, and dental supply chain trade data. Bottom-up unit economics triangulated against top-down macroeconomic indicators across the analysis window.
Scenario-bracketing framed the analytical approach, modeling volume and value outputs across product type, technology platform, end-user environment, and application claim dimensions throughout the forecast period. CAGRs derived from segment-level growth trajectory analysis incorporating aging demographic projections, reimbursement framework evolution, and regulatory pathway maturation. Forecast inputs included piezoelectric miniaturization adoption curves and tele-dentistry reimbursement policy development.
Practitioners should monitor EU MDR clinical evidence requirement enforcement, MFDS fast-track pathway utilization rates, and polymer supply chain disruption indicators for early signals of forecast revision. Assumptions reflect current regulatory trajectories and reimbursement policy stances. Quarterly review of CDSCO registration timelines, METI Silver Innovation subsidy allocation, and REACH substance restriction implementation is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Malocclusion Market
Dental Devices
Dental Articulators Market
Dental Devices
Asia Pacific Acrylic Teeth Market
Dental Devices
3D-Printed Dental Restoration Market
Dental Devices
Saudi Arabia Dental Devices Market
Dental Devices
Electric Dental Handpieces Market
Dental Devices
Global Dental Turbine Market
Dental Devices
Dental Amalgamators Market
Dental Devices
Dental Caries and Endodontic Market
Dental Devices
US Dental Splint Market
Dental Devices
Periodontal Scalers and Curettes Market
Dental Devices
Dental Air Abrasion Market
Dental Devices
Digital Dental Cameras Market
Dental Devices
Dental Chair Market
Dental Devices
Dental Devices and Consumables Market
Dental Devices
Dental Radiometer Market