
 Clinical Chairs Market | 2026-2036
Clinical Chairs Market Size, Share, and Industry Trends Forecast 2026-2036
Clinical Chairs Market Outlook
Powered-adjustable specification tiers are redrawing competitive boundaries in clinical seating. A-dec, Inc. leverages captive manufacturing of hydraulic lift systems to control component quality from its Newberg, Oregon headquarters. Fresenius Medical Care anchors its position through dialysis chair specialization that integrates blood pressure monitoring and scale functions. Hill Laboratories Company competes on infection-control upholstery certifications that meet Joint Commission survey protocols.
Clinical chairs are height-adjustable, reclinable, or fixed-position seating systems engineered for patient examination, treatment delivery, and limited mobility support in healthcare settings, typically constructed with medical-grade vinyl or polyurethane surfaces that withstand disinfectant protocols and support load ratings exceeding 200 kilograms. The product-type dimension shows treatment chairs capturing the dominant margin pool due to embedded motorization and accessory integration, while mobility chairs represent the fastest-expanding category as aging populations require transfer-assist functions. End-user segmentation reveals dental offices as the most mature demand cluster, whereas physiotherapy centers are driving incremental volume through rehabilitation-specific tilt and traction configurations.
FDA 510(k) premarket notification requirements govern powered clinical chairs in the United States, while the EU Medical Device Regulation mandates clinical evaluation and post-market surveillance for Class I and II seating systems sold in Europe. ISO 13485 quality management certification has become a de facto market-access threshold for contract bidding at hospital purchasing cooperatives. Stakeholders must monitor evolving electrical safety standards for battery-powered chairs and antimicrobial surface claims that attract FTC scrutiny.
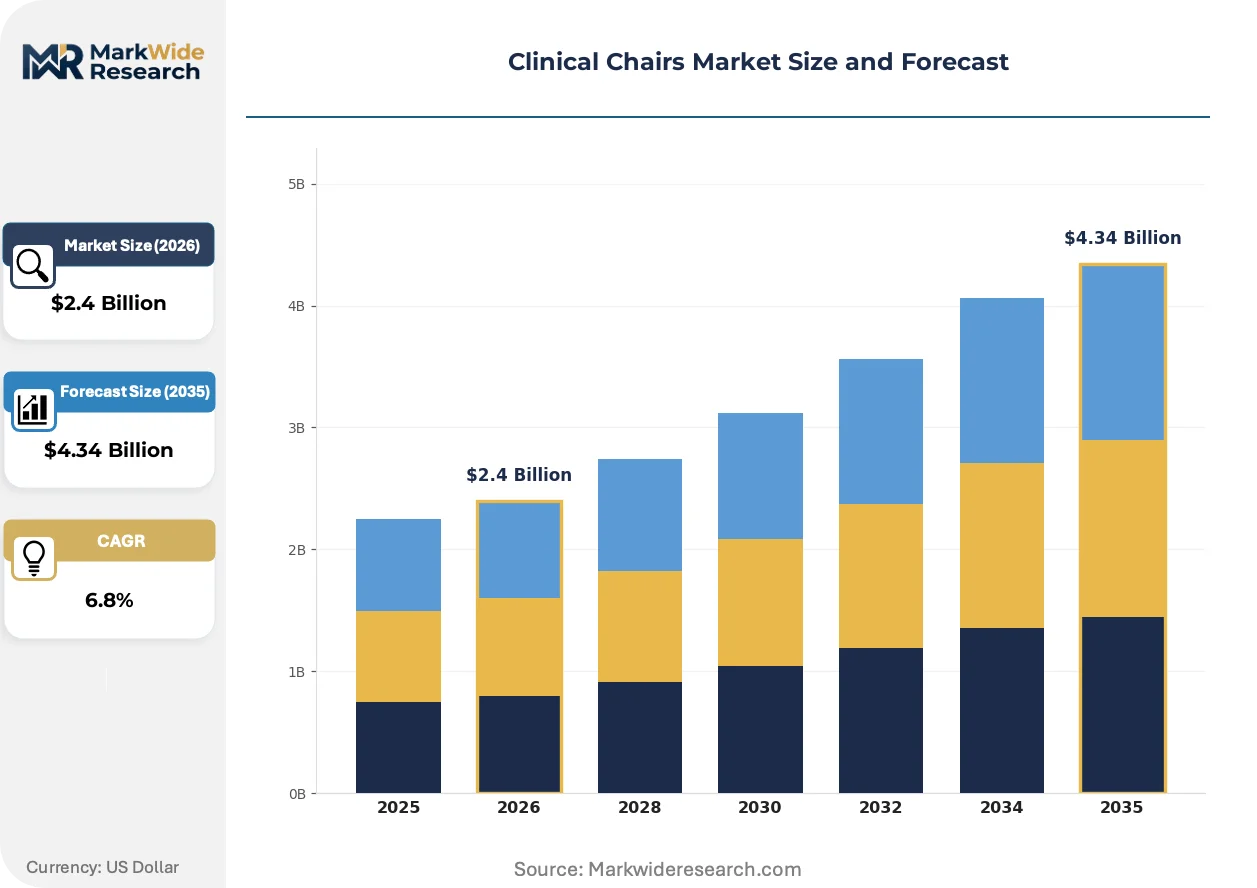
Market Dynamics
Powered-adjustable specification tiers are redrawing competitive boundaries in clinical seating, as hydraulic lift systems and embedded motorization separate premium treatment chairs from commodity examination furniture. Hospital purchasing cooperatives now mandate ISO 13485 certification as a baseline threshold, compressing margins for non-compliant suppliers while rewarding vertically integrated manufacturers with captive component production.
Growth Catalysts
- EU Medical Device Regulation:Post-market surveillance mandates for Class II seating systems are accelerating replacement cycles across European hospital networks, creating pull-through demand for certified upholstery and electrical safety upgrades.
- Ambulatory surgical centers:These facilities are expanding procurement of powered treatment chairs with integrated scale and blood pressure monitoring functions, prioritizing multi-functionality over single-purpose examination furniture.
- Germany's hospital modernization programs:Federal and state-level infrastructure investments prioritize ergonomic examination furniture, concentrating demand for height-adjustable and reclinable configurations in Europe's largest healthcare market.
Market Restraints
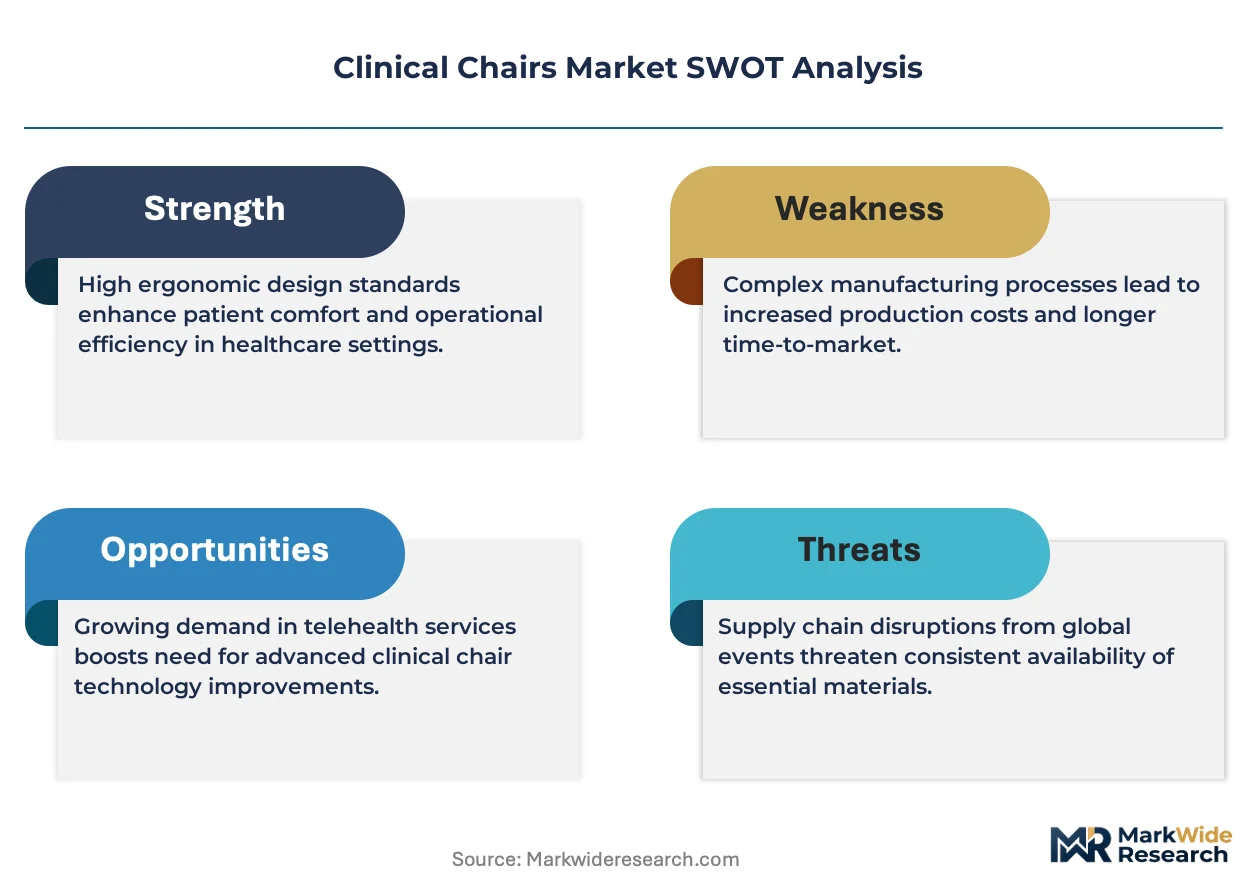
- Steel and aluminum price volatility:Frame construction materials face input cost swings that compress manufacturing margins, particularly for mid-tier producers without long-term supply contracts.
- FDA 510(k) clearance tightening:Upholstery and electrical safety requirements for Class II medical devices are extending approval timelines, creating regulatory friction for battery-powered chair introductions.
- Antimicrobial surface claim scrutiny:FTC enforcement against unsubstantiated infection-control marketing limits differentiation strategies for upholstery suppliers competing on hygiene credentials.
Strategic Opportunities
- Physiotherapy center expansion:Rehabilitation-specific tilt and traction configurations represent underpenetrated demand, with these centers driving incremental volume beyond mature dental office segments.
- Battery-powered mobility chairs:Convergence of lithium-ion power systems with transfer-assist functions opens white space in aging-population care settings, displacing manual transfer equipment.
- Joint Commission survey protocols:Infection-control upholstery certifications aligned with these standards create a regulatory tailwind for suppliers investing in antimicrobial surface validation.
Industry Challenges
- Electrical safety certification timelines:Battery-powered chairs face extended testing protocols for IEC 60601 compliance, delaying product launches and compressing revenue recognition windows.
- Legacy hydraulic system integration:Powered-adjustable platforms must interface with existing clinic infrastructure, creating technical complexity for retrofit installations in established healthcare facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clinical Chairs Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Examination Chairs, Treatment Chairs, Mobility Chairs, Specialty Chairs End User: Hospitals, Clinics, Dental Offices, Physiotherapy Centers Material: Leather, Faux Leather, Fabric, Plastic Functionality: Adjustable, Folding, Static, Reclining |
| Companies Covered | Planmeca OY, Danaher, Dentsply Sirona, Hill Laboratories Company, Topcon Corporation, A-dec, Inc., Fresenius Medical Care, DentalEZ, Inc., Midmark Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clinical Chairs Market Strategic Shifts
Modular component architecture is actively reshaping how clinical chairs are specified, manufactured, and serviced. Suppliers now compete on subsystem interoperability rather than complete-system lock-in, enabling end-users to upgrade motorization, upholstery, and monitoring functions independently.
Brushless DC motor systems with integrated position feedback are decomposing the traditional hydraulic lift architecture in premium treatment chairs. Ambulatory surgical centers in Germany and the United States are specifying these electromechanical configurations for 40% of new procurement. The technology is decomposing the aftermarket service revenue model, as modular motor replacements reduce field technician dependency and compress maintenance contract pricing.
EU Medical Device Regulation clinical evaluation requirements are mandating biocompatibility documentation for patient-contact surfaces. Upholstery suppliers must now submit cytotoxicity and sensitization test data to notified bodies, extending material qualification cycles by 8-12 months. Class II seating systems with polymer-based surfaces face the steepest compliance burden, driving consolidation toward suppliers with in-house polymer chemistry expertise.
Direct-to-facility digital specification tools are displacing traditional distributor-led configuration processes. Hospital purchasing cooperatives in North America and Western Europe are deploying online platforms that aggregate real-time inventory, pricing, and certification documentation from multiple suppliers. Dental office chains with standardized footprint requirements represent the most advanced adopters, using these channels to reduce procurement cycle times from 90 days to under 30 days.
Clinical Chairs Market Segmentation
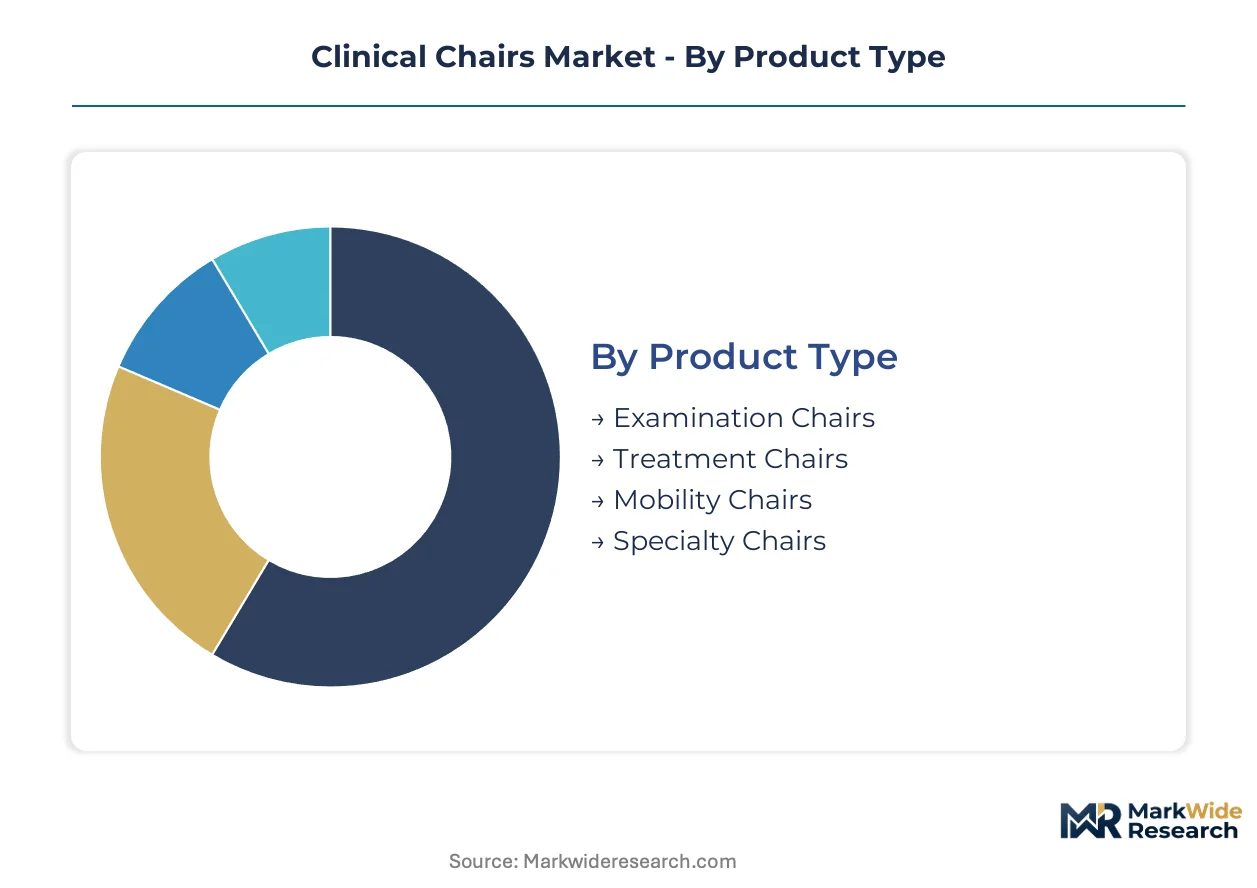
Segmentation in clinical seating reveals how regulatory requirements, material specifications, and end-use workflows create distinct margin profiles. Manufacturers configure product architectures around certification tiers rather than pursuing universal platforms.
Product Type:
FDA 510(k) clearance pathways and EU MDR clinical evaluation mandates create divergent compliance burdens across powered versus non-powered categories.
- Treatment Chairs:Embedded motorization, hydraulic lift systems, and integrated monitoring functions define this premium tier. Ambulatory surgical centers in Germany and the United States specify these configurations for multi-procedure efficiency, prioritizing blood pressure and scale integration over single-function alternatives.
- Mobility Chairs:Battery-powered transfer-assist platforms with lithium-ion systems and position feedback mechanisms serve aging-population care settings. Rehabilitation facilities and long-term care operators in Japan and Australia are displacing manual transfer equipment with these electromechanical configurations.
- Examination Chairs:Height-adjustable seating with manual or basic powered mechanisms serves primary care and general diagnostic workflows.
- Specialty Chairs:Procedure-specific designs including dialysis configurations with vascular access positioning and bariatric-rated frames exceeding 200 kilogram capacity.
Established volume favors treatment chairs; emerging adoption favors mobility chairs.
End User:
Procurement authority and specification complexity vary sharply across institutional purchasing versus independent practice decision-making.
- Hospitals:Centralized purchasing cooperatives mandate ISO 13485 certification and Joint Commission-aligned infection control protocols. German hospital modernization programs concentrate demand for ergonomic, height-adjustable configurations in Europe's largest healthcare infrastructure investment cycle.
- Physiotherapy Centers:Rehabilitation-specific requirements for tilt, traction, and resistance configurations drive incremental volume beyond mature segments. These centers in the United States and United Kingdom specify modular platforms allowing independent motorization and upholstery upgrades.
- Clinics:Multi-specialty outpatient facilities balance cost constraints against regulatory compliance for Class II seating systems.
- Dental Offices:Standardized footprint requirements and distributor-led procurement characterize this most mature demand cluster.
Procurement concentration favors hospitals; specification innovation favors physiotherapy centers.
Material:
Biocompatibility documentation requirements under EU MDR are extending material qualification cycles and consolidating supplier bases toward polymer chemistry specialists.
- Faux Leather:Medical-grade vinyl and polyurethane surfaces dominate clinical applications due to disinfectant protocol compatibility and cost positioning. Cytotoxicity and sensitization test data submissions to notified bodies now require 8-12 month qualification cycles.
- Leather:Natural material with limited clinical penetration due to moisture sensitivity and cleaning protocol incompatibility.
- Fabric:Breathable woven materials restricted to non-clinical or administrative seating applications.
- Plastic:Polymer-based structural components and surfaces facing steep MDR compliance burdens for Class II seating systems.
Cost efficiency favors faux leather; regulatory exposure concentrates in plastic-based surfaces.
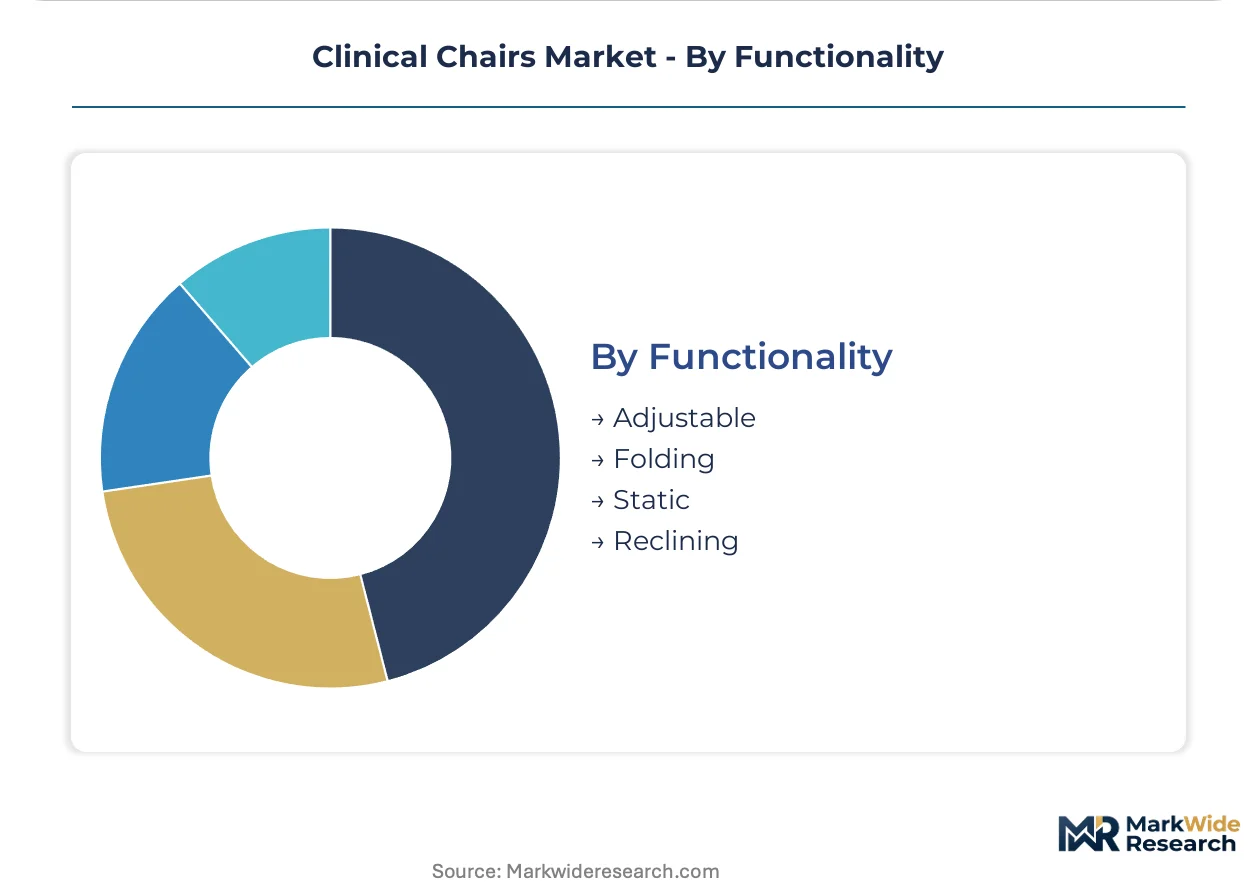
Functionality:
Electromechanical architectures are displacing hydraulic systems in premium tiers, while static configurations retain position in cost-sensitive procurement.
- Adjustable:Powered height and positioning mechanisms with brushless DC motor systems and integrated feedback. Ambulatory surgical centers in Germany and the United States specify these for 40% of new procurement, decomposing traditional aftermarket service revenue models.
- Reclining:Patient positioning for examination, minor procedures, and recovery workflows with manual or powered actuation.
- Folding:Space-constrained configurations for temporary or mobile clinical deployments.
- Static:Fixed-position seating for administrative, waiting area, or basic diagnostic applications with minimal specification complexity.
Technology transition favors adjustable platforms; residual demand stabilizes static configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of powered clinical seating concentrates in Germany, the United States, and Japan, where component suppliers cluster near precision motor and medical device ecosystems. Demand fragmentation across hospital networks, ambulatory surgical centers, and independent dental practices creates divergent procurement patterns by geography.
United States
Ambulatory surgical centers in Texas and Florida are expanding procurement of multi-function treatment chairs with integrated monitoring capabilities. FDA 510(k) clearance pathways for Class II medical devices are tightening upholstery and electrical safety requirements, extending approval timelines for battery-powered configurations. The Newberg, Oregon industrial cluster hosts captive manufacturing of hydraulic lift systems serving domestic hospital purchasing cooperatives.
Germany
Federal and state-level hospital modernization programs are concentrating demand for ergonomic, height-adjustable examination furniture in Europe's largest healthcare market. EU Medical Device Regulation post-market surveillance mandates for Class II seating systems are accelerating replacement cycles across hospital networks. The Baden-Württemberg region anchors precision motor component supply chains feeding powered-adjustable chair assembly operations.
Japan
Rehabilitation facilities and long-term care operators are displacing manual transfer equipment with battery-powered mobility chairs featuring lithium-ion systems. METI standards for medical electrical equipment are shaping electromechanical architecture specifications for domestic manufacturers. The Kansai industrial corridor around Osaka hosts polymer chemistry specialists supplying biocompatibility-certified upholstery materials.
China
Domestic hospital infrastructure investments are scaling procurement of manual and basic powered examination chairs for primary care networks. NMPA medical device registration requirements are consolidating supplier bases toward manufacturers with in-house quality management systems. The Yangtze River Delta manufacturing cluster is absorbing frame fabrication and motor assembly capacity for regional distribution.
Australia
Physiotherapy center expansion is driving incremental demand for rehabilitation-specific tilt and traction configurations beyond mature dental segments. TGA conformity assessment procedures for Class II medical devices are aligning with EU MDR technical documentation requirements. The Sydney-Melbourne healthcare corridor concentrates specialist rehabilitation equipment procurement authority.
Clinical Chairs Market Competitive Environment
Concentration sits with vertically integrated specialists controlling captive component production and diversified medical device conglomerates leveraging cross-selling infrastructure. The vendor base spans three tiers: premium manufacturers with in-house motorization systems, mid-tier assemblers sourcing modular subsystems, and regional fabricators competing on price-standard configurations. Hydraulic lift specialists, dialysis equipment integrators, and infection-control upholstery certifiers represent three dominant strategic archetypes. Competitive moves center on backward integration into precision motor manufacturing and geographic expansion through distributor acquisition in ambulatory care markets.
Among North American specialists, A-dec, Inc. and Hill Laboratories Company exemplify divergent positioning archetypes, with the former representing captive manufacturing of lift systems and the latter anchoring infection-control certification strategies. Fresenius Medical Care occupies a distinct position as a dialysis-focused integrator leveraging therapeutic equipment cross-selling infrastructure. These three entities illustrate how specialization depth, vertical integration scope, and regulatory compliance investment separate premium-tier competitors from commodity assemblers in hospital cooperative bidding processes.
| Leading Market Players |
|---|
| Planmeca OY |
| Danaher |
| Dentsply Sirona |
| Hill Laboratories Company |
| Topcon Corporation |
| A-dec, Inc. |
| Fresenius Medical Care |
| DentalEZ, Inc. |
| Midmark Corporation |
| Others |
Value Chain & Pricing Dynamics
Eight-to-twelve-month upholstery qualification cycles under EU MDR compress inventory turns for European distributors while amplifying pricing power for polymer chemistry specialists with in-house certification capabilities. This lead-time band concentrates procurement authority toward vertically integrated manufacturers who can absorb regulatory delay costs that mid-tier assemblers cannot shoulder.
Pricing Analysis
FDA 510(k) clearance pathways dictate the pricing tier structure across powered clinical seating, separating ISO 13485-certified manufacturers commanding premium positioning from uncertified competitors relegated to commodity manual chairs. Price differentiation rests on certification grade and after-sales service bundling, with hospital purchasing cooperatives paying substantial premiums for Joint Commission-aligned infection control documentation. Cost compression in mid-tier motorized configurations is intensifying because steel and aluminum input volatility erodes assembler margins without long-term supply contracts. Dental office chains exhibit highest price sensitivity due to standardized footprint requirements and distributor-led procurement, while ambulatory surgical centers demonstrate lowest sensitivity given multi-function efficiency priorities.
Supply Chain Analysis
Germany, the United States, and Japan anchor precision motor and medical device component manufacturing for powered clinical seating, with Baden-Württemberg, Newberg-Oregon, and Osaka-Kansai hosting captive lift system and polymer chemistry operations. Frame construction draws from steel and aluminum feedstocks, while brushless DC motor systems and lithium-ion battery packs represent critical electromechanical inputs. Single-source vulnerability concentrates in precision motor subsystems where German and Japanese suppliers dominate technical specifications. Distribution runs through hospital purchasing cooperatives in North America, direct-to-facility digital platforms in Western Europe, and specialized medical device distributors in Asia-Pacific rehabilitation markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clinical seating sits in early-cycle expansion as ambulatory surgical centers displace single-purpose examination furniture with multi-function powered configurations. Battery-powered mobility chairs for aging-population care settings represent substantial untapped penetration upside.
For Market Incumbents: Fortify backward integration into brushless DC motor manufacturing to control electromechanical subsystem quality and compress aftermarket service revenue dependency. Capture polymer chemistry expertise through selective acquisition to secure EU MDR biocompatibility documentation capabilities before qualification cycle extensions consolidate supplier bases. Defend against modular platform competitors by embedding proprietary position feedback protocols that complicate third-party motor replacements.
For New Entrants and Emerging Players: Aftermarket retrofit motorization kits for legacy hydraulic chairs in established European and North American clinics represent the most penetrable service-layer gap where incumbents under-serve. Target physiotherapy center expansion in Australia and the United Kingdom with rehabilitation-specific tilt and traction configurations that bypass saturated dental office procurement channels. Pursue direct-to-facility digital specification partnerships with hospital purchasing cooperatives to circumvent entrenched distributor relationships.
For Investors and Strategic Acquirers: Long-term, this sits as a demographic tailwind play because aging-population care infrastructure spending in Japan, Germany, and Australia structurally displaces manual transfer equipment with electromechanical alternatives. Acquisition candidates should demonstrate captive polymer chemistry expertise or precision motor manufacturing capabilities that regulatory compliance burdens are consolidating toward. Monitor ambulatory surgical center construction permits in Texas and Florida as inflection indicators for multi-function treatment chair procurement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR clinical evaluation documentation accelerates hospital network replacement cycles across German modernization programs. |
| Hospital System Partnership | Direct contracting with North American purchasing cooperatives bypasses distributor markups and compresses procurement cycles. |
| Backward Integration into Motors | Captive brushless DC production controls electromechanical quality and decomposes traditional aftermarket service dependencies. |
| Software Companion Development | Integrated blood pressure and scale monitoring functions differentiate treatment chairs in ambulatory surgical center procurement. |
| Reimbursement Strategy | Alignment with Medicare and private payer durable medical equipment codes expands battery-powered mobility chair addressable markets. |
Study Parameters
Initial hypotheses were tested against primary input from hospital purchasing committee directors, biomedical engineers, GPO contracts managers, and ambulatory surgical center operations leads and refined through secondary validation. Primary fieldwork combined structured interviews with secondary analysis of FDA 510(k) filings, EU MDR notified body documentation, hospital procurement databases, and GPO contract terms. Bottom-up volume estimates by product type and end-user segment were triangulated against top-down healthcare infrastructure spending data across the analysis window.
Variance decomposition across segmentation dimensions—product type, end user, material specification, and functionality tier—drove analytical framework construction throughout the projection horizon. CAGRs were derived from installed base replacement dynamics, ambulatory facility construction pipelines, and regulatory compliance-driven upgrade cycles. Modeled inputs included German hospital modernization program allocations, US ambulatory surgical center licensing data, and Japanese long-term care infrastructure investments.
Forecasts assume regulatory continuity in FDA 510(k) pathways and EU MDR post-market surveillance regimes; material policy shifts would require re-modeling of approval timeline and compliance cost assumptions. Specific risks include antimicrobial surface claim enforcement actions, battery safety standard revisions, and steel price volatility compression. Recalibration cycles align with material shifts in healthcare infrastructure spending, regulatory clearance velocity, and electromechanical technology substitution rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Furniture
North America Hospital Furniture Market
Medical Furniture
Asia-Pacific Hospital Bed Market
Medical Furniture
Medical Bed Market
Medical Furniture
Hospital Beds Market
Medical Furniture
Global Stretcher Chairs Market
Medical Furniture
Medical Walker Market
Medical Furniture
Healthcare Smart Beds Market
Medical Furniture
Global Medical Furniture Market
Medical Furniture
Electrical Hospital Beds Market
Medical Furniture
Infusion Chair Market
Medical Furniture
Global Automated Hospital Beds Market
Medical Furniture
Europe Hospital Furniture Market
Medical Furniture
Global Smart Hospital Bed Market
Medical Furniture
Medical Commodes Market
Medical Furniture
Hospital Bed Management Systems Market
Medical Furniture
Medical Mattress Market