
 Asia-Pacific Dental Lab Market | 2026-2036
Asia-Pacific Dental Lab Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Dental Lab Market Outlook
Digital workflow revenue is reconfiguring margin pools away from conventional hand-fabricated prosthetics toward software-integrated production platforms. Dentsply Sirona leverages its intraoral scanner installed base to pull through lab-side CAD/CAM subscriptions. Institut Straumann AG anchors premium implant-abutment workflows across Japan, South Korea, and Australia. 3Shape A/S competes through open-architecture design software that reduces switching costs for mid-size laboratories.
The Asia-Pacific dental lab sector encompasses facilities that manufacture custom oral prosthetics, restorative devices, and orthodontic appliances using precision-milled zirconia, cobalt-chrome alloys, and photopolymer resins to achieve biocompatibility standards of ISO 10993 and regional pharmacopeial requirements. These labs serve dentists, hospitals, and research institutions by translating patient-specific digital impressions into functional, aesthetic restorations that replace or support natural dentition. Implant-supported superstructures command premium pricing due to titanium-grade machining tolerances and osseointegration validation protocols. CAD/CAM technology leads volume throughput for crown and bridge production, while 3D printing captures fastest growth in denture base and surgical guide applications where layer-by-layer photopolymerization reduces material waste.
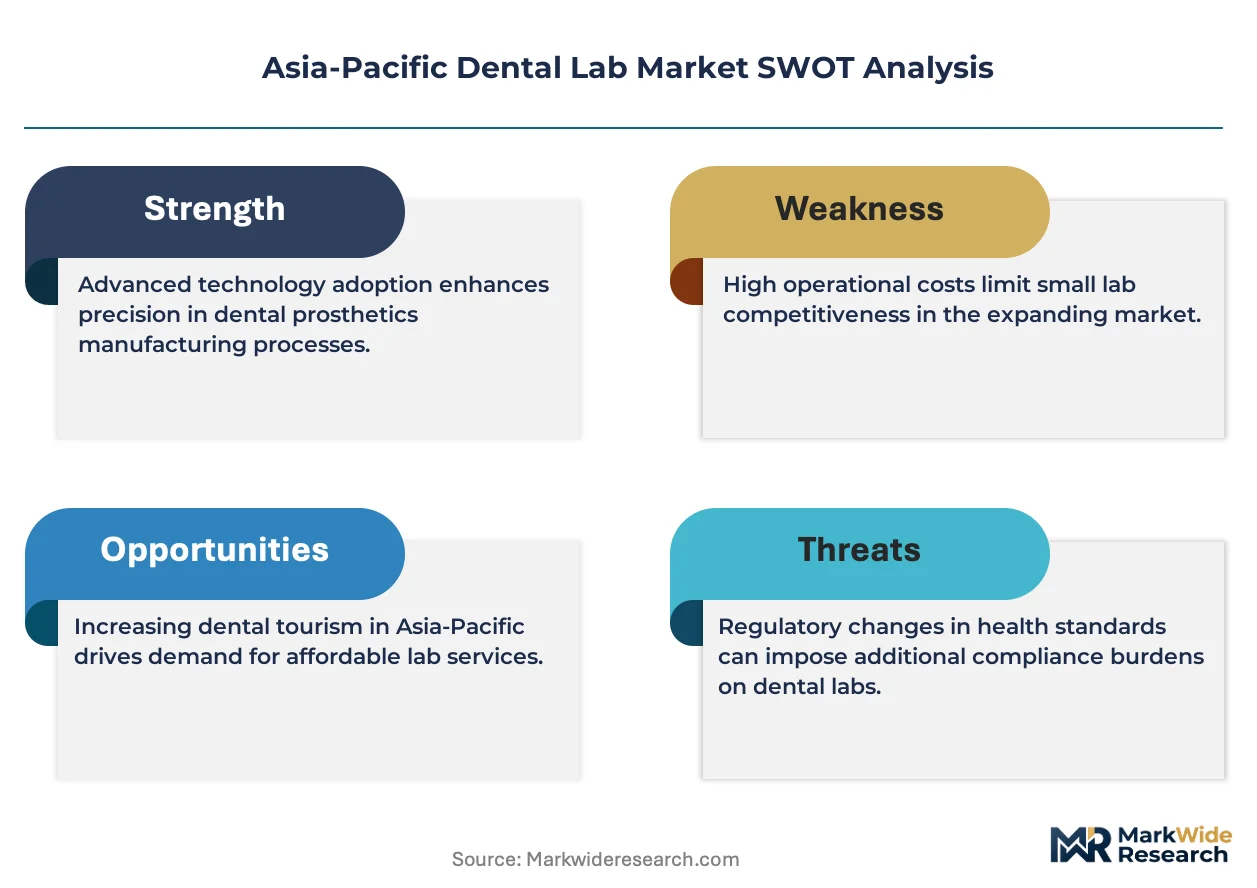
Japan's PMDA enforces pre-market approval for custom-made dental devices, elevating compliance costs but screening out substandard imports. Australia's TGA aligns with EU MDR equivalence pathways, streamlining market access for European-certified manufacturers while requiring local adverse-event reporting. China's NMPA implemented updated dental material registration rules that mandate domestic clinical data for novel ceramic formulations. Stakeholders must monitor how these divergent approval timelines reshape competitive entry strategies and outsourcing decisions across the region.
Market Dynamics
Digital workflow adoption is restructuring margin distribution across the Asia-Pacific dental lab sector, compressing traditional hand-fabricated prosthetics while elevating software-integrated production platforms that command recurring subscription revenue from laboratory clients.
Growth Catalysts
- Private dental chain expansion:China's government-backed oral health programs and proliferating private clinic networks concentrate demand for standardized, high-volume prosthetic production across tier-one and tier-two cities.
- CAD/CAM throughput leadership:Crown and bridge fabrication via computer-aided design and manufacturing platforms reduces labor intensity while improving margin capture for mid-size laboratories serving metropolitan dental clusters.
- Japan's PMDA pre-market pathways:Stringent device approval standards for custom-made dental devices screen out substandard imports, creating protected market access for compliant domestic and regional manufacturers.
Market Restraints
- Zirconia powder supply concentration:Precision-milled ceramic prosthetics depend on concentrated raw material suppliers, exposing laboratories to input cost volatility and supply security risks.
- Domestic clinical data mandates:China's NMPA registration rules for novel ceramic formulations require local validation studies, extending time-to-market and elevating compliance expenditure for foreign material innovators.
- Titanium-grade machining tolerance requirements:Implant-supported superstructures demand specialized CNC equipment and osseointegration validation protocols that limit supplier participation to capital-intensive specialists.
Strategic Opportunities
- 3D-printed surgical guide penetration:Layer-by-layer photopolymerization of denture bases and surgical guides captures fastest growth in Australia and South Korea where private implantology clinics seek workflow efficiency.
- Open-architecture software adoption:Design platforms reducing switching costs for mid-size laboratories enable vendor-agnostic equipment procurement, creating service and training revenue pools for software providers.
- EU MDR equivalence alignment:Australia's TGA streamlined pathways for European-certified manufacturers reduce redundant testing burdens, accelerating market access for premium implant-abutment workflows.
Industry Challenges
- Digital technician skill scarcity:Conventional ceramists require retraining in CAD/CAM interface management and 3D printing post-processing, creating workforce transition friction as laboratories automate production floors.
- Multi-system integration complexity:Laboratories operating hybrid workflows across intraoral scanners, design software, and milling units face interoperability failures that disrupt case turnaround commitments to dental clinics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Dental Lab Market |
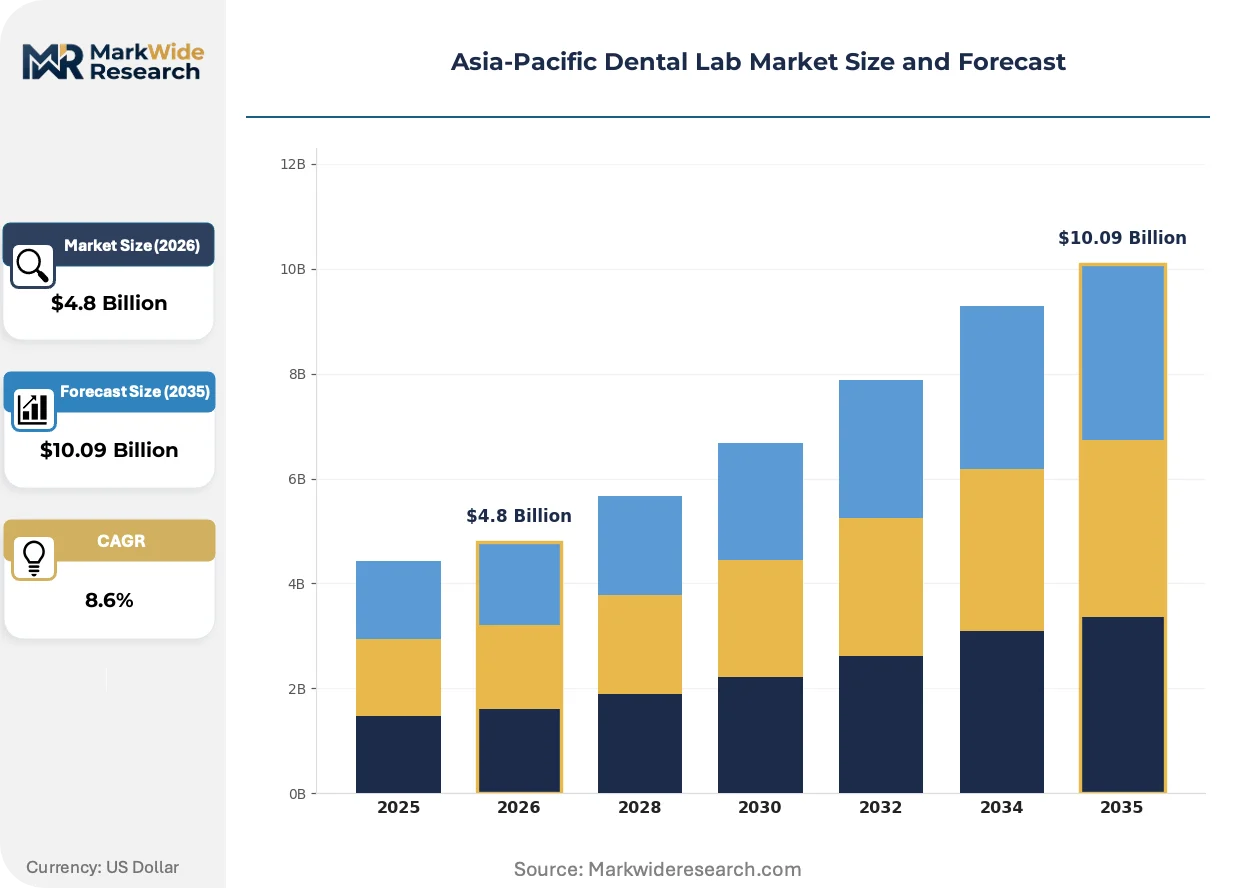
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.09 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crowns, Bridges, Dentures, Implants End User: Dental Clinics, Hospitals, Research Institutions, Laboratories Technology: CAD/CAM, 3D Printing, Milling, Casting Material: Metal Alloys, Ceramics, Composites, Polymers |
| Companies Covered | Dentsply Sirona, Envista Holdings Corporation, Ivoclar Vivadent, Institut Straumann AG, GC Corporation, Align Technology, 3Shape A/S, Planmeca Oy, OSSTEM IMPLANT CO., LTD., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Dental Lab Market Strategic Shifts
Cloud-connected design platforms and photopolymerization advances are compressing traditional fabrication timelines while regulatory data localization requirements reshape competitive entry strategies across national markets.
Intraoral scanning infrastructure is virtualizing the traditional impression-to-laboratory workflow. Dental clinics across Japan and South Korea deploy chairside scanners that transmit digital files directly to fabrication centers, eliminating physical mold shipping delays. This virtualization enables same-day crown production for high-volume metropolitan practices while reducing remake rates from distortion errors.
Australia's TGA maintains EU MDR equivalence pathways that streamline approval for European-certified dental device manufacturers. The alignment reduces redundant conformity assessment burdens while mandating local adverse-event reporting infrastructure. Premium implant-abutment suppliers leverage this regulatory bridge to accelerate market entry without duplicative clinical studies.
Subscription-based CAD/CAM software licensing displaces perpetual purchase models across mid-size Asia-Pacific laboratories. Monthly fee structures lower capital barriers for digital workflow adoption while locking in recurring vendor relationships. South Korean dental chains lead this transition, negotiating enterprise licenses that bundle design seats with maintenance and training services.
Asia-Pacific Dental Lab Market Segmentation
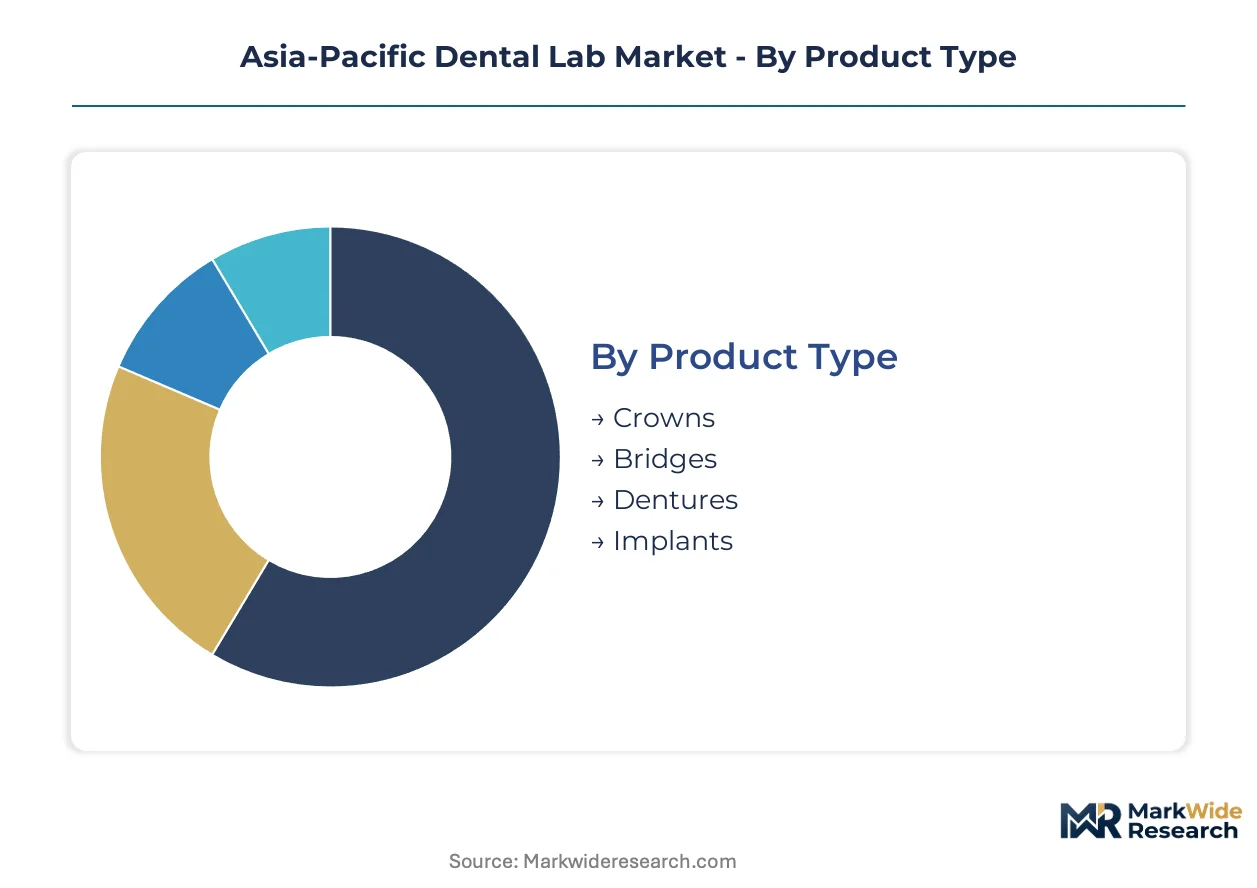
Segmentation in the Asia-Pacific dental lab market exposes how technology adoption, material science, and end-user concentration reshape procurement patterns across national boundaries. Laboratories and clinics prioritize different performance attributes, creating tiered demand structures that vendors must navigate.
Product Type:
Mature prosthetic categories dominate current revenue while emerging formats capture workflow innovation investments across the region.
- Implants:Titanium-grade superstructures and zirconia abutments command premium positioning due to osseointegration validation protocols and PMDA pre-market scrutiny in Japan. Australian implantology clinics drive demand for customized abutment geometries that match Straumann and Nobel Biocare platform specifications.
- Crowns:Precision-milled zirconia and lithium disilicate restorations constitute the highest throughput category, with CAD/CAM platforms enabling same-day production for South Korean and Chinese metropolitan dental chains. Margin compression intensifies as chairside milling penetrates larger clinic networks.
- Bridges:Multi-unit prosthetic frameworks leverage cobalt-chrome substructures veneered with ceramic layers, serving edentulous patient segments across Australia's aging demographic profile and Japan's senior population.
- Dentures:Conventional acrylic and flexible partial designs retain substantial volume in Southeast Asian markets where cost sensitivity delays digital workflow adoption, though 3D-printed baseplates gain traction in premium Australian practices.
Crowns retain volume leadership; implants hold the steepest expansion curve.
End User:
Customer type determines order scale, technical specification tolerance, and payment reliability across the fabrication ecosystem.
- Dental Clinics:Private chains across China and South Korea consolidate demand through centralized procurement, negotiating volume discounts for standardized crown and bridge specifications. Chairside scanning infrastructure reduces remake liability while accelerating case turnaround.
- Laboratories:Mid-size independent fabricators in Japan and Australia serve as production hubs for affiliated clinic networks, investing in open-architecture CAD/CAM systems to maintain equipment flexibility. These operators face margin pressure from vertically integrated dental chains bringing production in-house.
- Hospitals:Public and academic medical centers in Australia and South Korea manage complex maxillofacial reconstructions requiring custom titanium frameworks and surgical guides, with procurement governed by tender processes that favor established suppliers.
- Research Institutions:University dental schools and biomaterials laboratories in Japan and China pilot novel ceramic formulations and 3D-printed resin biocompatibility studies, generating small-batch demand for experimental prosthetic geometries.
Dental clinics concentrate order volume; laboratories face the most intense competitive restructuring.
Technology:
Production method selection hinges on capital intensity, technician skill availability, and regulatory validation requirements.
- CAD/CAM:Computer-aided design and manufacturing platforms dominate crown and bridge throughput, with 3Shape and exocad software ecosystems standard across Australian and South Korean mid-size laboratories. Subscription licensing models displace perpetual purchases, lowering entry barriers.
- 3D Printing:Photopolymerization systems capture fastest growth in surgical guide and denture base applications, with layer-by-layer fabrication reducing material waste versus subtractive methods. Australian implantology practices lead adoption for patient-specific drill guides.
- Milling:Subtractive machining of zirconia blanks and titanium stock remains essential for high-strength restorations requiring precise occlusal anatomy, though equipment costs limit participation to capitalized operations.
- Casting:Traditional lost-wax metal alloy techniques persist for removable partial frameworks and select crown substructures, particularly in Southeast Asian markets where digital infrastructure investment lags.
CAD/CAM anchors current production volume; 3D printing scales most rapidly.
Material:
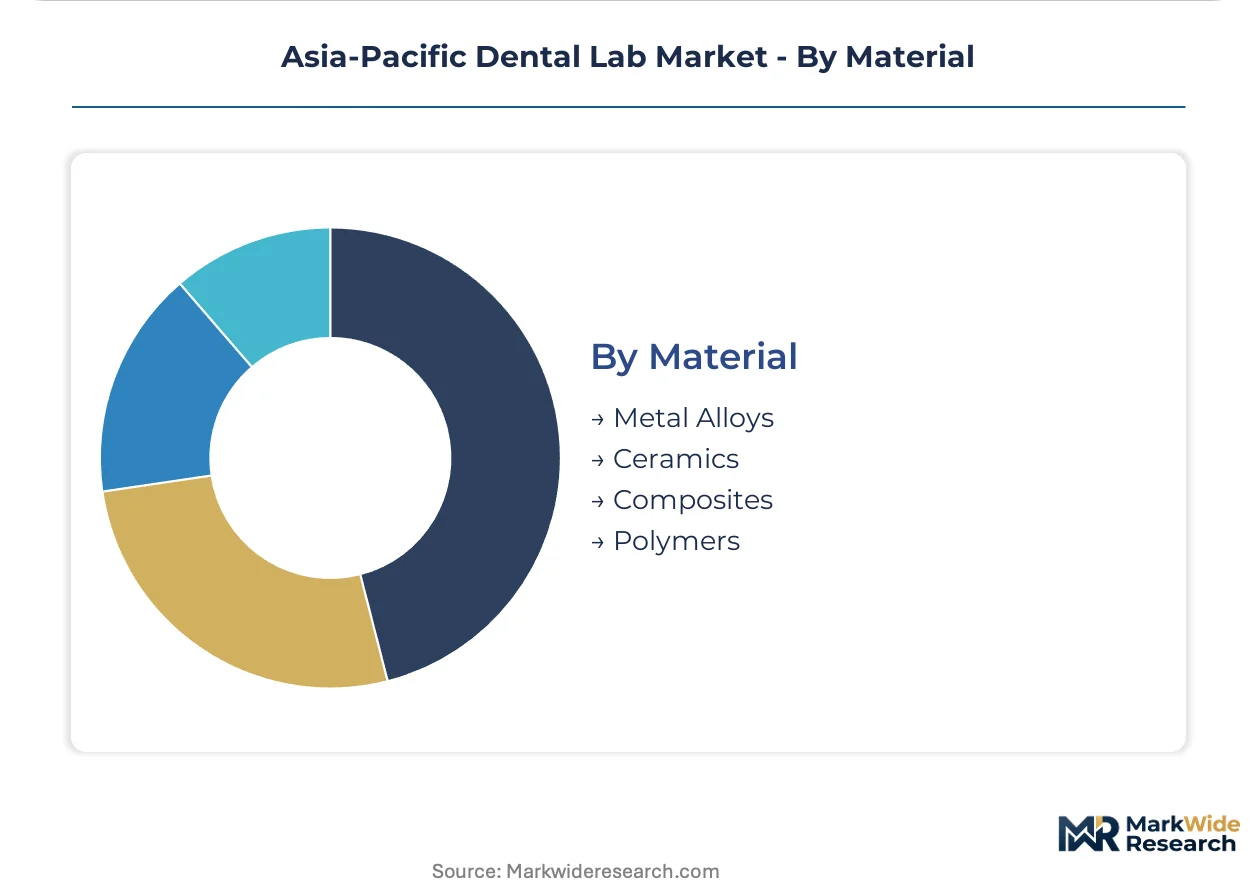
Substrate selection balances aesthetic performance, mechanical durability, and biocompatibility certification across regulatory jurisdictions.
- Ceramics:Zirconia and lithium disilicate formulations dominate anterior and posterior crown applications, with China's NMPA mandating domestic clinical data for novel ceramic compositions. Japanese laboratories prioritize translucent zirconia grades for aesthetic zone restorations.
- Metal Alloys:Cobalt-chrome and precious metal substructures serve bridge frameworks and implant superstructures, with Australia's TGA requiring adverse-event reporting that elevates compliance costs for non-EU-certified suppliers.
- Polymers:PMMA, PEEK, and flexible nylon resins enable denture bases, temporary crowns, and surgical guides, with photopolymer advances improving fracture resistance and color stability.
- Composites:Fiber-reinforced and particulate-filled materials address provisional restorations and specific aesthetic layering applications, though limited long-term clinical data constrains premium positioning.
Ceramics command revenue concentration; polymers expand application scope fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across the Asia-Pacific dental lab market, with Southeast Asian buyers exhibiting acute price sensitivity while Australian and Japanese clinics absorb premium pricing for validated implant workflows.
China
Private dental chain expansion and government-backed oral health programs concentrate prosthetic demand in tier-one and tier-two cities. NMPA registration rules for novel ceramic formulations mandate domestic clinical data, extending time-to-market for foreign material innovators. Shanghai and Beijing host the densest clusters of digital fabrication centers serving metropolitan clinic networks.
Japan
Aging demographics and high implant penetration sustain demand for precision-milled superstructures and aesthetic zone restorations. PMDA pre-market approval pathways for custom-made dental devices screen out substandard imports, protecting compliant domestic manufacturers. The Kanto region around Tokyo anchors premium prosthetic production for affiliated clinic chains.
Australia
Private implantology clinics drive fastest adoption of 3D-printed surgical guides and same-day crown workflows. TGA alignment with EU MDR equivalence pathways streamlines market access for European-certified device manufacturers while requiring local adverse-event reporting infrastructure. Sydney and Melbourne concentrate high-volume digital laboratories serving metropolitan dental clusters.
South Korea
Enterprise dental chains negotiate subscription-based CAD/CAM software licenses that bundle design seats with training services. MFDS oversight of dental device manufacturing maintains quality standards for export-oriented production. The Seoul Capital Area hosts the region's densest concentration of mid-size laboratories operating open-architecture digital workflows.
Asia-Pacific Dental Lab Market Competitive Environment
Integrated equipment-software conglomerates and specialized implant-abutment suppliers split the market between scale-driven platform plays and premium workflow anchoring. The vendor base stratifies across three tiers: multinational dental conglomerates with intraoral scanner installed bases pulling through lab-side subscriptions; premium implant specialists commanding superstructure margins through osseointegration validation; and regional material innovators navigating NMPA domestic data requirements. Dominant competitive moves include strategic partnerships between scanner manufacturers and CAD/CAM software providers, plus geographic expansion through distributor networks in tier-two Chinese cities.
Among multinational equipment-software conglomerates, Dentsply Sirona and 3Shape A/S occupy positions at opposite ends of the architecture spectrum, with the former representing closed-ecosystem vertical integration and the latter exemplifying open-architecture strategies that reduce laboratory switching costs. Institut Straumann AG anchors the premium implant-abutment tier across Japan, South Korea, and Australia, its position reinforced by platform specifications that Australian clinics specify for customized superstructure geometries.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Envista Holdings Corporation |
| Ivoclar Vivadent |
| Institut Straumann AG |
| GC Corporation |
| Align Technology |
| 3Shape A/S |
| Planmeca Oy |
| OSSTEM IMPLANT CO., LTD. |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in China's zirconia milling centers is compressing unit economics for crown and bridge fabricators while simultaneously elevating bargaining power for dental chain procurement offices across Shanghai and Beijing. This utilization imbalance forces mid-size laboratories to absorb input cost volatility or surrender margin through volume discounting.
Pricing Analysis
After-sales revenue from CAD/CAM software subscriptions and maintenance contracts now drives lifetime value more than equipment sales, with South Korean dental chains negotiating enterprise bundles that lock laboratories into recurring payment streams. Three-tier pricing structure across premium, standard, and economy levels separates PMDA-validated Japanese superstructures from TGA-aligned Australian workflows and unbranded Southeast Asian acrylics. Pricing pressure stems from chairside milling penetration in Chinese metropolitan clinics. Private dental chains exhibit acute price sensitivity; implantology specialists absorb premium positioning.
Supply Chain Analysis
Export-control scrutiny on precision CNC controllers and photopolymer resin formulations constrains technology transfer into domestic Chinese fabrication centers, forcing laboratories to source certified equipment through authorized distributors. Zirconia powder production concentrates in Japan and Germany; titanium stock feeds from Australian and South Korean smelters. Photopolymer resins and cobalt-chrome alloys draw from Chinese and Belgian chemical processors. Single-source vulnerability pervades zirconia blank supply. Distribution runs through regional distributor networks serving tier-one and tier-two city clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific dental lab market is cycling through post-pandemic equipment replacement demand, with deferred CAD/CAM upgrades now converging with government-backed oral health program procurement across China.
For Market Incumbents: Build switching-cost moats through deep software-hardware integration that captures laboratory technician training investment and locks in recurring subscription revenue. Dentsply Sirona's scanner-to-lab subscription pull-through exemplifies this architecture. Defend against open-architecture competitors by certifying exclusive workflows with Japan's PMDA and Australia's TGA. Prioritize backward integration into zirconia blank supply to offset raw material volatility. For New Entrants and Emerging Players: Build out white-space positions in 3D-printed surgical guide production for Australian implantology clinics, where photopolymerization adoption outpaces incumbent service coverage. Target Southeast Asian denture markets where cost sensitivity delays digital workflow penetration and conventional acrylic fabrication retains volume. Pursue distributor partnerships in tier-two Chinese cities rather than direct sales to saturated Shanghai and Beijing clusters. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across software-centric CAD/CAM platforms, reducing barrier-to-entry for cloud-connected design vendors while elevating returns for asset-light service models. Five-to-ten year viability favors laboratories with hybrid digital-conventional capabilities serving aging demographics in Japan and Australia. Acquisition screens should prioritize open-architecture software providers with established South Korean enterprise relationships. Monitor NMPA domestic clinical data rule enforcement as the signal for foreign material innovator exit timing.| Strategic Initiative | Industry Significance |
|---|---|
| CAD/CAM Platform Integration | Dentsply Sirona leverages intraoral scanner installed base to capture laboratory subscription revenue across Japan and South Korea. |
| Regulatory Certification Pathway | PMDA pre-market approval protects compliant manufacturers from substandard import competition in Japan's premium superstructure segment. |
| Open-Architecture Software Development | 3Shape A/S reduces laboratory switching costs, enabling vendor-agnostic equipment procurement across Australian mid-size fabricators. |
| Backward Integration into Zirconia Supply | Laboratories sourcing directly from Japanese powder producers mitigate input cost volatility threatening margin stability. |
| Geographic Expansion through Distribution | Regional distributor networks unlock tier-two Chinese cities where private dental chain concentration accelerates prosthetic demand. |
Study Parameters
Operator-level perspectives from dental laboratory technicians, CAD/CAM software implementation specialists, dental chain procurement directors, and regulatory affairs managers at implant manufacturers anchored the qualitative base. These primary insights were cross-validated against secondary sources including PMDA device registration databases, TGA adverse-event reporting archives, NMPA material approval filings, and trade flow records from Japanese and Australian customs authorities. Bottom-up laboratory capacity estimates were triangulated with top-down dental clinic procurement surveys.
Scenario-bracketing around regulatory approval timeline variations and digital workflow adoption curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-user category, production technology, and material substrate, with additional stratification by national regulatory cluster. CAGRs were derived from fitted adoption curves calibrated to historical equipment shipment data and software license renewal patterns. Forecast inputs incorporated zirconia powder price indices and intraoral scanner installation rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed dental equipment conglomerates would shift outcomes beyond modeled ranges. Material shifts in NMPA enforcement stringency or PMDA pre-market approval duration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Dental Devices and Consumables Market
Dental Devices
Global Professional Teeth Whitening and Power Toothbrushes Market
Dental Devices
Teeth Whitening Pen Market
Dental Devices
Prophy Dental Handpiece Market
Dental Devices
Dental Forceps Market
Dental Devices
Dental Impression System Market
Dental Devices
Dental Diamond Burs Market
Dental Devices
Dental Implants and Dental Prosthetics Market
Dental Devices
Dental 3D Scanners Market
Dental Devices
Dental Chair Market
Dental Devices
Global Dental Obturators Market
Dental Devices
Dental Liners and Bases Market
Dental Devices
Dental Piezoelectric Ultrasonic Unit Market
Dental Devices
Dental Regeneration Market
Dental Devices
US Orthodontics Market
Dental Devices
Dental Irrigation Devices Market