
 Global Dental Labs Market | 2026-2036
Global Dental Labs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dental Labs Market Foresight
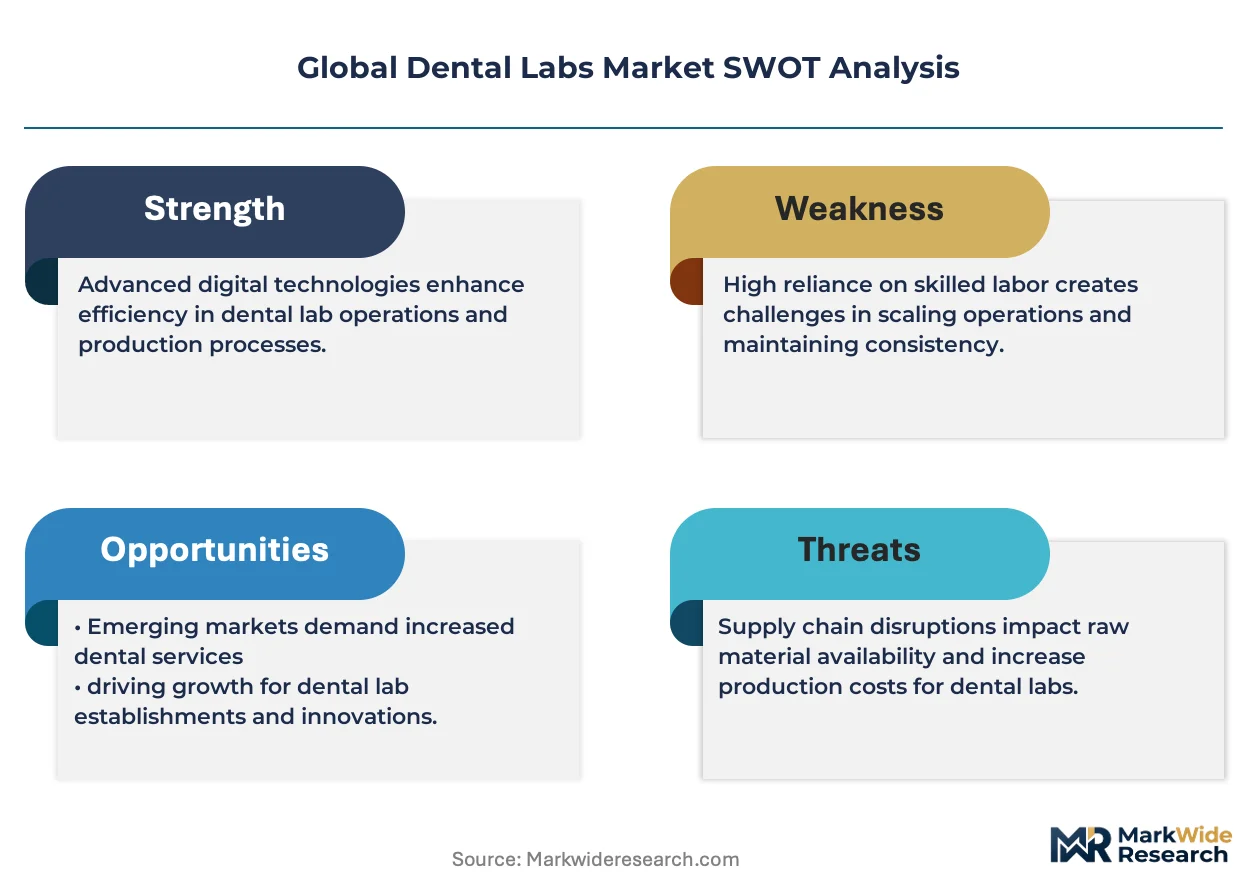
ISO 13485 certification is reorganizing competitive tiers in dental lab supply, forcing smaller operators into consolidation or contract manufacturing roles while accredited players capture hospital and institutional contracts. Dentsply Sirona leverages its integrated CAD/CAM hardware-software ecosystem to lock in lab customers. Ivoclar Vivadent sustains leadership in lithium disilicate and zirconia material science. Straumann Group anchors premium implant-abutment workflows through proprietary connections that labs must accommodate.
A dental laboratory fabricates custom oral prosthetics and restorative devices from biocompatible materials—zirconia, cobalt-chrome alloys, PMMA, and PEEK—using subtractive milling, additive sintering, or pressed ceramic techniques to achieve ISO-defined marginal fit tolerances. These facilities serve as the manufacturing backbone between clinician prescription and patient delivery. Ceramic CAD/CAM dominates value capture due to material margins and chairside integration, while 3D printing reshapes denture base and surgical guide production through speed advantages. Prosthodontics absorbs the largest volume share, though orthodontics is accelerating with clear aligner fabrication demand.
The FDA regulates dental lab output as medical devices under 21 CFR Part 820 quality system requirements, while the EU Medical Device Regulation (MDR) imposes stricter clinical evidence and post-market surveillance obligations on implantable prosthetics. China's NMPA now requires domestic registration for imported CAD/CAM blocks, altering sourcing patterns for multinational labs operating there. Stakeholders must monitor how evolving notified body capacity in Europe and state-level dental lab licensure expansion in the United States reshape compliance costs and competitive moats.
Market Dynamics
Digital workflows are compressing production timelines for custom oral prosthetics while ISO 13485 certification requirements force capital investments that separate accredited institutional suppliers from smaller regional operators.
Growth Catalysts
- FDA 510(k) Pathway:Streamlined clearance for CAD/CAM dental devices accelerates technology diffusion among prosthodontic centers seeking to outsource complex restoration work.
- Clear Aligner Fabrication:Orthodontic demand for transparent removable devices pulls volume into specialized labs equipped with thermoforming and 3D printing capabilities.
- German Lab Clustering:Dense concentrations of family-owned laboratories in Bavaria and Baden-Württemberg sustain premium implant-abutment expertise that attracts cross-border referrals.
Market Restraints
- Zirconia Powder Concentration:Sourcing of high-purity ceramic feedstock depends on limited suppliers in Japan and China, creating input cost volatility for milling centers.
- EU MDR Compliance Burden:Stricter clinical evidence requirements for implantable prosthetics extend certification timelines and raise documentation costs for European operators.
- Chairside Milling Substitution:In-office CAD/CAM units in large dental group practices capture single-unit crown work that previously flowed to external labs.
Strategic Opportunities
- India's Dental Tourism Corridor:Mumbai and Delhi labs can capture international patient workflows by aligning with medical travel facilitators and NABH-accredited clinics.
- PEEK Polymer Expansion:Biocompatible high-performance thermoplastics enable metal-free removable partial denture frameworks with favorable patient acceptance profiles.
- China NMPA Domestic Registration:Local certification requirements for imported CAD/CAM blocks create partnership openings for multinational labs establishing captive production.
Industry Challenges
- CAD/CAM Technician Scarcity:Digital design and milling operation skills outpace vocational training output in the United States and Western Europe.
- Legacy System Integration:Proprietary scanner file formats from Dentsply Sirona and 3Shape create workflow friction when labs serve multiple dentist software ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dental Labs Market |
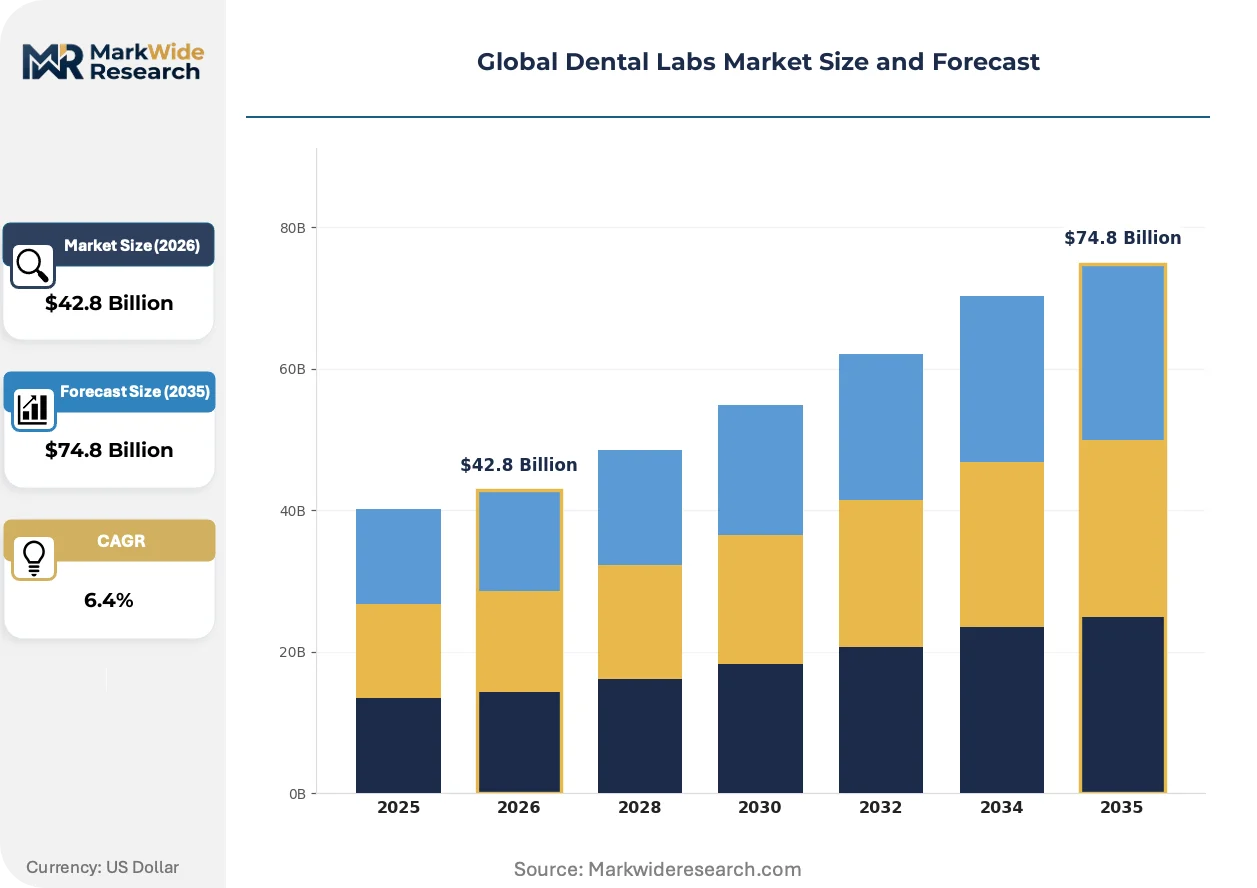
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $74.8 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crowns, Bridges, Dentures, Veneers, Implants Technology: Ceramic CAD/CAM, 3D Printing, Milling Machines, Laser Sintering Application: Orthodontics, Prosthodontics, Endodontics, Periodontics End User: Orthodontic Clinics, Prosthodontic Centers, Dental Institutes, Oral Surgery Facilities |
| Companies Covered | Dentsply Sirona, Envista, Ivoclar Vivadent, Planmeca Oy, Glidewell, Solventum, GC Corporation, National Dentex Labs, Straumann Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dental Labs Market Shifts & Advancements
Automation is redefining fabrication economics across restorative dentistry. Three concurrent developments are compressing traditional production models while opening new service categories.
Multi-material 3D printing is displacing conventional denture base processing. Labs in Germany and the United States adopt photopolymerization and selective laser sintering for monolithic try-ins and definitive prostheses. Chairside delivery timelines compress from two weeks to forty-eight hours, forcing wax-and-flask operations toward obsolescence in high-volume segments.
EU Medical Device Regulation enforcement is reshaping implant restoration supply chains. Notified body capacity constraints delay CE marking for novel abutment designs. German and Swiss labs with established MDR technical documentation capabilities capture hospital contracts that smaller competitors forfeit.
Subscription-based design services are emerging as an alternative to capital-heavy equipment ownership. Smaller prosthodontic practices in Australia and Canada outsource digital wax-ups to cloud-connected technicians rather than maintaining in-house milling infrastructure. This model concentrates design expertise in specialized hubs while distributing physical production to regional fulfillment centers.
Global Dental Labs Market Segmentation
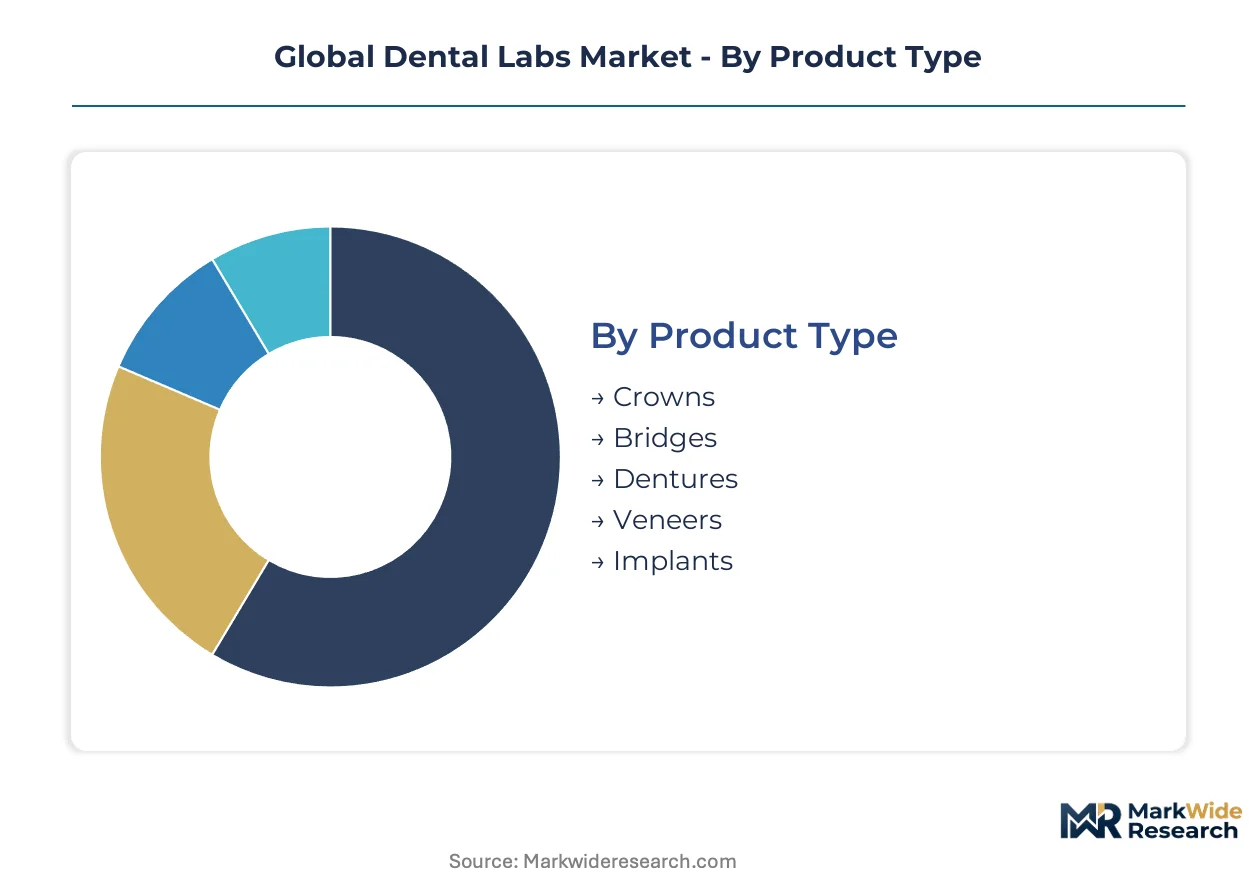
Segmentation reveals how substitution pressures reshape competitive positioning across the dental lab value chain. Technology choices determine margin capture, while product mix dictates exposure to chairside milling displacement.
Product Type:
Chairside CAD/CAM systems threaten single-unit restorations most directly, forcing external labs to defend volume in complex multi-unit cases.
- Crowns:Single-tooth restorations fabricated from zirconia, lithium disilicate, or PMMA using subtractive milling or pressed ceramic techniques. German and Swiss labs retain premium anterior work where shade matching demands technician artistry that automated systems cannot replicate.
- Bridges:Multi-unit fixed prostheses spanning edentulous spaces, requiring connector design strength verification and occlusal scheme coordination. Demand concentrates in prosthodontic centers serving aging populations in Japan and Italy, where implant-supported hybrid cases offset conventional tooth-borne volume erosion.
- Dentures:Removable full and partial arch prostheses traditionally processed through heat-cured acrylic. 3D-printed denture bases from Germany and the United States compress fabrication timelines from fourteen days to same-week delivery.
- Veneers:Thin ceramic laminates bonded to facial tooth surfaces for aesthetic enhancement. Labs in Beverly Hills and Dubai capture celebrity and medical tourism workflows demanding ultra-translucent feldspathic porcelain.
- Implants:Custom abutments and screw-retained crowns requiring platform-specific connection geometries. Straumann and Nobel Biocare proprietary interfaces force labs to maintain multiple hardware ecosystems or sacrifice referral relationships.
Bridges anchor the volume base while implants gain share at the steepest rate.
Technology:
Capital intensity separates institutional suppliers from regional competitors, with equipment ownership costs determining service tier access.
- Ceramic CAD/CAM:Subtractive milling of pre-sintered zirconia or glass-ceramic blocks using 3Shape, Dentsply Sirona, or Amann Girrbach hardware-software ecosystems. German labs dominate high-value anterior work through proprietary staining protocols that differentiate commodity mill output.
- 3D Printing:Photopolymerization and powder-bed fusion for denture bases, surgical guides, and orthodontic models. Clear aligner fabrication demand in California and Texas pulls volume toward specialized thermoforming and resin printing hubs.
- Milling Machines:5-axis machining centers processing titanium, cobalt-chrome, and PEEK for implant frameworks and removable partial denture structures. Japanese equipment from DMG Mori and Roland DG commands premium positioning in precision-critical implant-abutment workflows.
- Laser Sintering:Selective laser melting of cobalt-chrome and titanium powders for metal-ceramic frameworks and bar-retained overdentures. Italian labs leverage EOS and SLM Solutions equipment for dental-implant-specific parameter development.
Milling machines retain the largest installed base while 3D printing expands most quickly through aligner and denture fabrication demand.
Application:
Prosthodontic volume concentration masks orthodontic acceleration as clear aligner therapy displaces conventional bracket systems.
- Orthodontics:Clear aligner fabrication, indirect bonding trays, and retention appliances using thermoforming and 3D printing. Invisalign-certified labs in Mexico and Costa Rica capture North American outsourcing as Align Technology expands doctor network capacity.
- Prosthodontics:Crown, bridge, denture, and implant restoration fabrication representing the historical revenue core. Bavarian labs sustain premium positioning through Meisterprüfung-certified technician training and hospital contract relationships.
- Endodontics:Fiber post fabrication and custom obturation guides representing limited lab service penetration. Brazilian operators develop nickel-titanium instrument customization for complex canal anatomies.
- Periodontics:Surgical stent and guided tissue regeneration membrane production with emerging CAD/CAM integration. Korean labs partner with osseointegration research institutes for patient-specific implant site development tools.
Prosthodontics generates the largest case volume while orthodontics climbs the fastest on aligner fabrication expansion.
End User:
Institutional procurement standards separate accredited lab suppliers from commodity regional operators.
- Orthodontic Clinics:Clear aligner therapy providers and traditional bracket practices requiring model production and indirect bonding systems. Australian specialist practices outsource digital treatment planning to Philippine design hubs while retaining physical production locally.
- Prosthodontic Centers:Advanced restorative practices managing complex implant and full-mouth rehabilitation cases. University-affiliated centers in Boston and Stockholm mandate ISO 13485 certification for all external lab partnerships.
- Dental Institutes:Academic and research facilities requiring prototype fabrication and clinical trial device production. Singapore's National Dental Centre operates captive labs for biomaterial validation studies.
- Oral Surgery Facilities:Implant placement and maxillofacial reconstruction centers needing surgical guides and immediate-load provisional prostheses. Spanish maxillofacial units in Barcelona and Madrid source same-day guide production from integrated CAD/CAM facilities.
Prosthodontic centers command the highest per-case value while orthodontic clinics drive the steepest volume expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Prosthodontic centers in Germany, Japan, and the United States drive premium restoration outsourcing, while orthodontic demand pulls volume toward Mexico and India. Buyer concentration among implant-focused specialists and clear aligner therapy providers determines regional competitive positioning.
Germany
Dense clusters of family-owned laboratories in Bavaria and Baden-Württemberg sustain Meisterprüfung-certified technician expertise for complex implant-abutment workflows. The EU Medical Device Regulation imposes stricter clinical evidence requirements on implantable prosthetics, extending certification timelines for novel abutment designs. Stuttgart and Munich labs capture cross-border referrals from Switzerland and Austria through proprietary staining protocols that differentiate premium anterior work.
United States
Large dental group practices and prosthodontic centers in Boston, Los Angeles, and New York Metro outsource complex multi-unit cases while retaining single-unit crown work for in-office CAD/CAM units. The FDA's 510(k) clearance pathway accelerates technology diffusion among labs seeking institutional contracts. California and Texas hubs specialize in clear aligner fabrication for Invisalign-certified doctor networks, compressing delivery timelines through thermoforming and resin printing integration.
Japan
Aging demographics in Tokyo, Osaka, and Nagoya sustain demand for implant-supported hybrid prostheses as conventional tooth-borne bridge volume erodes. The Pharmaceuticals and Medical Devices Agency (PMDA) enforces quality system requirements aligned with ISO 13485 for imported CAD/CAM blocks. DMG Mori and Roland DG equipment from Chubu-region manufacturing anchors precision-critical milling operations for titanium and cobalt-chrome frameworks.
Mexico
Orthodontic labs in Mexico City and Guadalajara capture North American clear aligner outsourcing as Align Technology expands doctor network capacity. The country's national pharmaceutical regulator maintains streamlined registration pathways for dental device imports serving maquiladora production models. Tijuana and Monterrey facilities leverage proximity to California and Texas markets for same-week surgical guide delivery to oral surgery centers.
India
Mumbai and Delhi laboratories target medical tourism workflows by aligning with NABH-accredited clinics and international patient facilitators. The Central Drugs Standard Control Organization (CDSCO) requires domestic registration for imported CAD/CAM materials, altering sourcing patterns for multinational operators. Bangalore and Hyderabad hubs develop nickel-titanium instrument customization for complex endodontic anatomies, extending service penetration beyond traditional prosthodontic fabrication.
Global Dental Labs Market Competitive Landscape
Player mix skews toward integrated equipment-materials ecosystems alongside specialized regional fabricators and orthodontic-focused service providers. Consolidation pressures concentrate institutional contracts among ISO 13485-accredited operators while smaller regional labs defend position through niche expertise and speed-to-delivery. Strategic archetypes include captive hardware-software ecosystems, premium material science specialists, and scale-driven clear aligner production hubs. Dominant competitive moves encompass M&A to secure design software capabilities and capacity expansion into India and Mexico to capture outsourcing flows.
Among integrated equipment-materials providers, Dentsply Sirona and Ivoclar Vivadent occupy positions that exemplify the hardware-software ecosystem archetype, locking in lab customers through proprietary file formats and material supply agreements. Straumann Group represents the premium implant-abutment workflow specialist, forcing labs to accommodate proprietary connection geometries or sacrifice referral relationships. Envista sits within the orthodontic acceleration tier, capturing aligner fabrication demand through equipment and consumable bundling.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Envista |
| Ivoclar Vivadent |
| Planmeca Oy |
| Glidewell |
| Solventum |
| GC Corporation |
| National Dentex Labs |
| Straumann Group |
| Others |
Supply & Pricing Matrix
Equipment utilization rates above eighty percent at German and Japanese milling centers create scale economies that compress unit costs while elevating price floors for smaller regional competitors. This capacity concentration forces ISO 13485-accredited labs to index long-term contracts to zirconia powder and cobalt-chrome alloy spot markets, passing input volatility through to prosthodontic centers while defending margin through volume guarantees.
Pricing Analysis
Cost-plus contracts with zirconia powder indexation dominate institutional procurement between Bavarian labs and university-affiliated prosthodontic centers. Pricing stratifies across premium, standard, and economy tiers based on ISO 13485 certification status and chairside delivery speed. Cost compression in standard-tier crown fabrication is intensifying because Dentsply Sirona's integrated ecosystem locks in material sourcing. Price-sensitive orthodontic clinics in Mexico and India drive volume negotiations, while German implant-abutment specialists show minimal elasticity due to proprietary connection requirements.
Supply Chain Analysis
Inbound logistics costs from Yokohama and Shanghai ports constrain just-in-time zirconia block delivery to European milling centers, with container availability fluctuations amplifying inventory carrying costs. High-purity ceramic feedstock draws from Japanese and Chinese suppliers, while cobalt-chrome powders source from Italian and German metalworking clusters. Single-source vulnerability in yttria-stabilized zirconia creates exposure to export licensing shifts. Distribution runs through regional hub-and-spoke networks with Stuttgart, Dallas, and Nagoya serving as consolidation points for same-week surgical guide fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across the dental lab value chain creates acquisition opportunities as clear aligner demand pulls volume toward specialized thermoforming hubs that legacy prosthodontic labs cannot serve.
For Market Incumbents: Secure ISO 13485-accredited capacity in India and Mexico before CDSCO and COFEPRIS registration requirements harden competitive moats. Consolidate design software capabilities through targeted acquisition of 3Shape-compatible workflow specialists to counter Dentsply Sirona's proprietary format lock-in. Vertical integration into zirconia block distribution insulates margin from Japanese supplier concentration. For New Entrants and Emerging Players: Differentiate on same-day surgical guide production for oral surgery facilities in California and Texas, where Align Technology's doctor network expansion outpaces regional lab capacity. Target India's medical tourism corridor through NABH-accredited clinic partnerships, offering bundled crown-implant packages with international patient facilitators. Lead with cloud-connected design services to bypass capital-heavy milling infrastructure ownership. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors orthodontic-focused production hubs with thermoforming and resin printing capabilities over legacy wax-and-flask denture operations. Long-term viability rests on capturing clear aligner fabrication volume as Invisalign certification expands into Latin American and Southeast Asian markets. Watch FDA 510(k) clearance velocity for novel CAD/CAM devices as the inflection signal for technology substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Unlocks hospital and institutional contracts that commodity regional labs cannot access. |
| Clear Aligner Hub Capacity Expansion | Captures orthodontic volume migrating from conventional bracket systems to transparent removable devices. |
| Zirconia Powder Supply Agreement | Insulates margin from Japanese and Chinese supplier concentration and export licensing volatility. |
| Cloud-Connected Design Service Launch | Concentrates digital wax-up expertise in specialized hubs while distributing physical production regionally. |
| Prosthodontic Center Partnership Program | Locks in complex multi-unit case referrals threatened by in-office CAD/CAM chairside substitution. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR technical documentation, and hospital procurement databases. Interviews with prosthodontic center directors, dental lab operations managers, CAD/CAM equipment specialists, and GPO contracts managers informed demand-side validation. Customs records for zirconia block imports, SEC disclosures from integrated equipment providers, and notified body capacity reports supplied supply-side triangulation. Bottom-up case volume estimates and top-down equipment installed base calculations cross-validated market sizing.
Segmentation dimensions modeled include product type, fabrication technology, clinical application, and end-user procurement tier across the projection horizon. CAGRs derive from equipment replacement cycles, aligner therapy penetration curves, and implant restoration volume elasticities. Industry-specific inputs incorporate PMDA import registration timelines, CDSCO domestic manufacturing requirements, and Meisterprüfung-certified technician graduation rates.
The analysis sits within stated boundaries; outcomes outside sustained FDA 510(k) clearance velocity, stable zirconia powder trade flows, and Align Technology network expansion would require recalibration. Forecasts reflect documented assumptions regarding chairside milling substitution rates and EU MDR notified body capacity constraints. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Europe Dental Aligners Market
Dental Devices
China Dental Implants Market
Dental Devices
Dental Microsurgery Market
Dental Devices
Dental Handpieces Market
Dental Devices
Dental 3D Printing Market
Dental Devices
Orthodontic Wax Market
Dental Devices
RFID-Enabled Dental Printing Market
Dental Devices
Dental Autoclave Market
Dental Devices
Dental Implant Motors Market
Dental Devices
Europe Dental Implants Market
Dental Devices
Dental CAD Market
Dental Devices
Latin America Dental Devices Market
Dental Devices
Dental Air Abrasion Market
Dental Devices
Asia Pacific Acrylic Teeth Market
Dental Devices
GCC Dental Implants Market
Dental Devices
Dental Aligners Market