
 Dental Erbium Lasers Market | 2026-2036
Dental Erbium Lasers Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Erbium Lasers Market Insights
German precision optics manufacturers is recalibrating erbium laser source production to match rising dental OEM demand. BIOLASE leverages its installed base of waterlase systems to sustain recurring consumable revenue across North American dental clinics. Fotona anchors its competitive position through dual-wavelength platforms that integrate erbium and Nd:YAG capabilities. Elexxion AG differentiates via compact tabletop designs optimized for European practice footprints.
Dental erbium lasers generate pulsed mid-infrared radiation at 2,940 nm (Er:YAG) or 1,540 nm (Er,Cr:YSGG) wavelengths, ablating hard and soft oral tissues through thermomechanical interaction with water-rich biological structures while minimizing thermal collateral damage. Erbium YAG Laser systems command the dominant revenue share due to established clinical efficacy in enamel and dentin cutting, though Solid State Laser architectures gain traction for their superior beam quality and reduced maintenance intervals. Cavity Preparation applications retain the largest procedure volume, while Periodontal Treatment represents the fastest-expanding indication as minimally invasive sulcular debridement protocols displace conventional scaling and root planing in dental clinics and hospitals.
FDA 510(k) premarket notification requirements govern erbium laser commercialization in the United States, while the EU Medical Device Regulation (MDR) imposes strengthened clinical evidence and post-market surveillance obligations across European member states. ISO 13485 quality management certification and IEC 60601-1 electrical safety standards form baseline market access prerequisites for manufacturers targeting dental clinics and hospitals worldwide. Stakeholders must monitor evolving reimbursement coding for laser-assisted procedures across national health systems to anticipate demand inflection points and calibrate commercial investments accordingly.
Market Dynamics
Dual-wavelength platform architectures are compressing equipment replacement cycles across dental clinics, as practitioners consolidate multiple laser modalities into single-system footprints to optimize capital efficiency and operatory space utilization.
Growth Catalysts
- Minimally Invasive Periodontal Protocols:Laser-assisted sulcular debridement is displacing conventional scaling in dental clinics across Germany, where reimbursement frameworks now cover erbium-assisted periodontal therapy.
- FDA 510(k) Streamlining:Predicate device pathways for Class II medical devices accelerate clearance timelines for erbium laser manufacturers targeting United States dental clinics.
- Water-Rich Tissue Ablation Physics:Thermomechanical interaction mechanisms at 2,940 nm enable precise hard and soft tissue cutting with minimal thermal collateral damage, expanding procedure applicability.
Market Restraints
- Premium Optics Input Concentration:German and Swiss precision optics suppliers control erbium-doped crystal and resonator mirror supply, creating vulnerability for downstream OEMs.
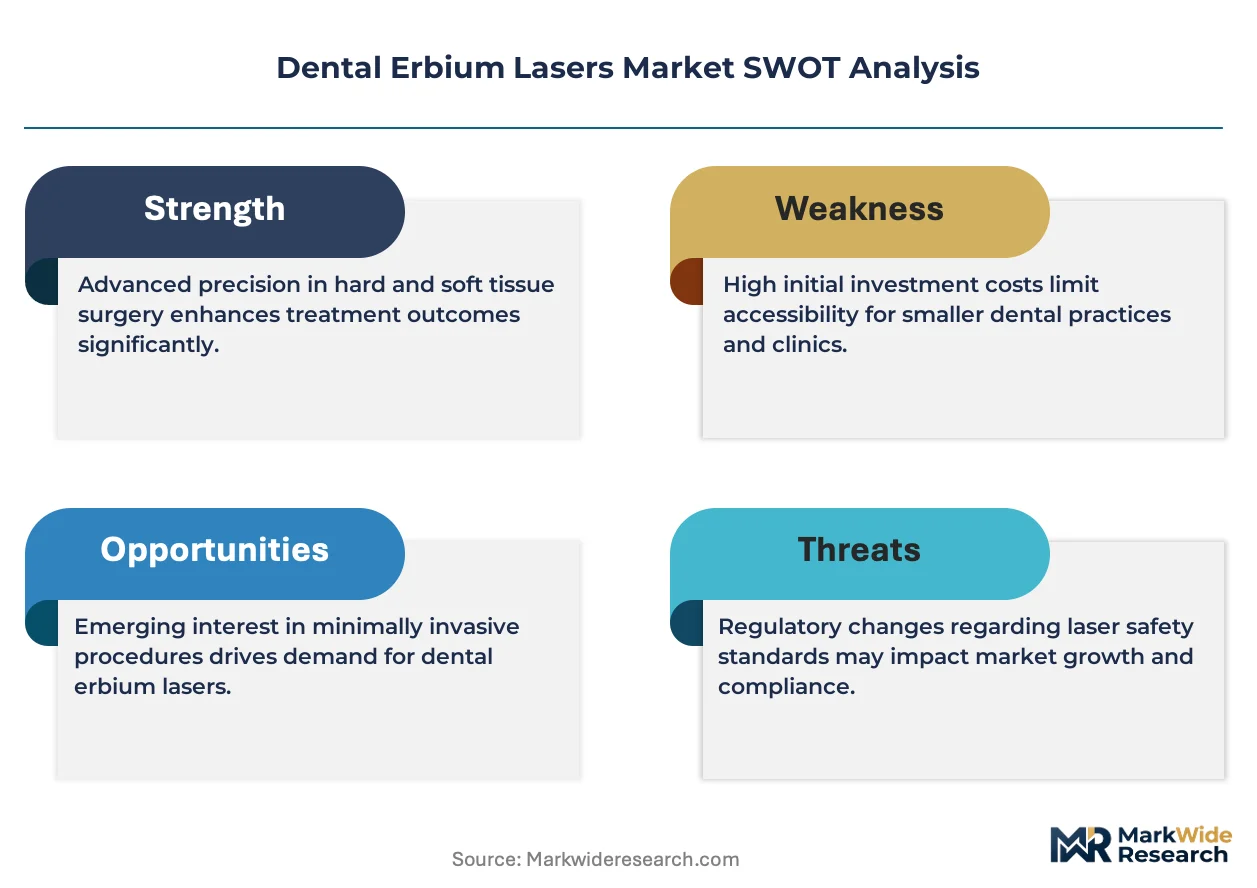
- Capital Equipment Intensity:Tabletop erbium laser systems require substantial upfront investment, constraining adoption among independent dental practices with constrained credit access.
- Conventional Handpiece Substitution:High-speed air turbine drills retain cost advantage for routine cavity preparation in price-sensitive clinic segments.
Strategic Opportunities
- Compact System Form Factors:European practice footprints favor space-optimized tabletop designs that integrate erbium and diode capabilities within single chassis architectures.
- Consumable Recurring Revenue Streams:Waterlase-compatible disposable tips and delivery fibers create annuity economics for installed base operators.
- EU MDR Clinical Evidence Pathways:Strengthened post-market surveillance obligations favor established manufacturers with robust clinical documentation and quality management systems.
Industry Challenges
- Laser Safety Certification Gaps:Dental hygienists and auxiliary staff require specialized training in beam hazard protocols and eye protection standards, extending staff onboarding timelines.
- Legacy Handpiece Integration:Fiber delivery systems must interface with existing dental unit water and air lines, complicating retrofit installations in older clinic infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Erbium Lasers Market |
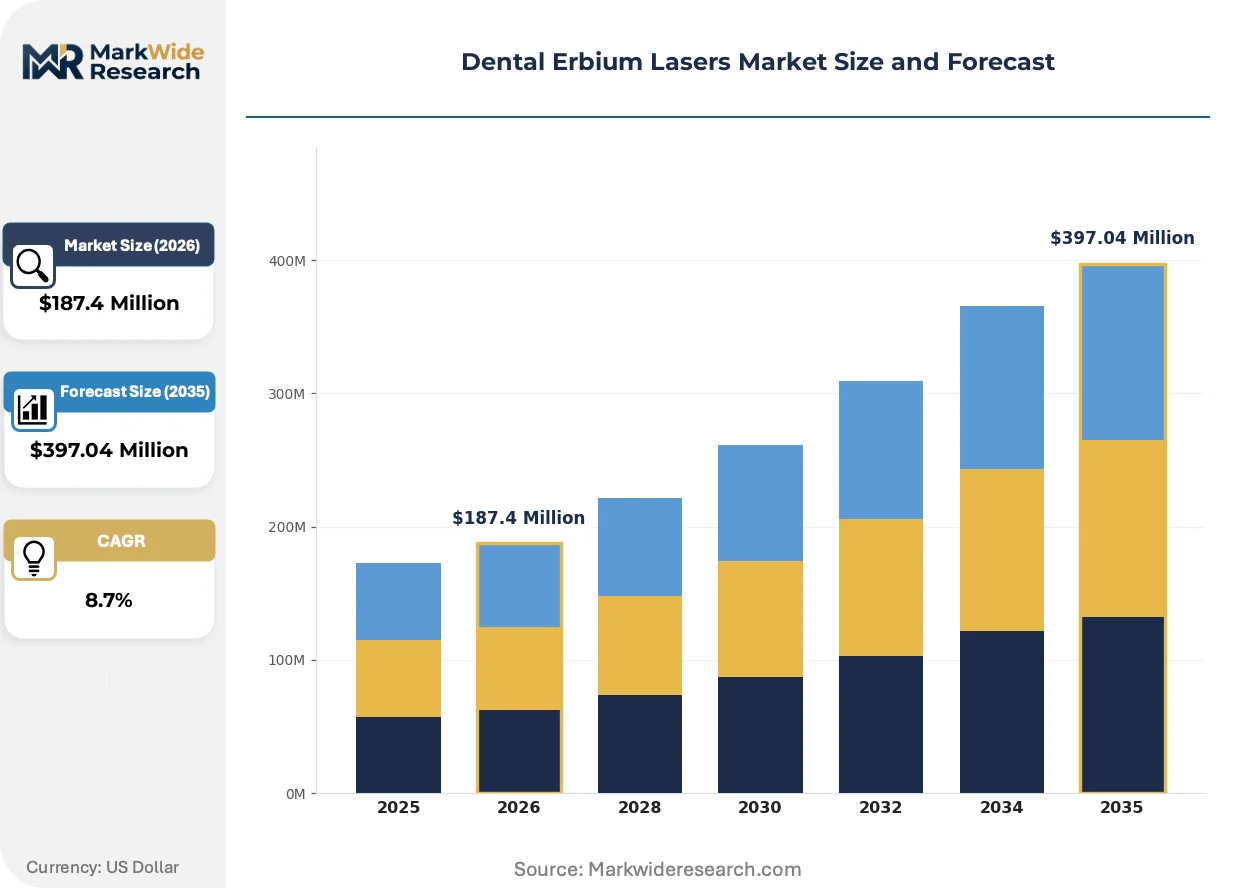
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Erbium YAG Laser, Erbium Glass Laser, Solid State Laser, Fiber Laser Application: Cavity Preparation, Periodontal Treatment, Soft Tissue Surgery, Teeth Whitening End User: Dental Clinics, Hospitals, Research Laboratories, Academic Institutions Distribution Channel: Direct Sales, Online Retail, Medical Distributors, Trade Shows |
| Companies Covered | BIOLASE, Fotona, Light Instruments, Lambda SpA, LIGHTMED, Elexxion AG, Ivoclar Vivadent, Lumenis, Convergent Dental, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Erbium Lasers Market Trends and Innovations
Platform convergence and regulatory harmonization are reshaping competitive positioning, as manufacturers engineer multi-modality systems that satisfy divergent safety standards while compressing total cost of ownership for clinic buyers.
Dual-wavelength erbium-Nd:YAG architectures are unifying hard tissue cutting and soft tissue coagulation within single delivery systems. Dental clinics in Germany and the United States are adopting these platforms at accelerating replacement cycles. This convergence is compressing demand for standalone single-wavelength systems and elevating R&D thresholds for pure-play erbium specialists.
EU MDR post-market surveillance obligations are intensifying clinical evidence requirements for active implantable medical devices. Manufacturers must now maintain systematic vigilance systems and periodic safety update reports across European member states. Dental laser OEMs with legacy ISO 13485 frameworks are restructuring quality management systems to satisfy strengthened notified body scrutiny.
After-sales service unbundling is fragmenting traditional equipment procurement models. Dental clinics now separately negotiate maintenance contracts, training packages, and consumable supply agreements rather than accepting bundled turnkey proposals. This pattern is most visible in United States group practice networks and German dental service organizations seeking operational transparency.
Dental Erbium Lasers Market Segmentation
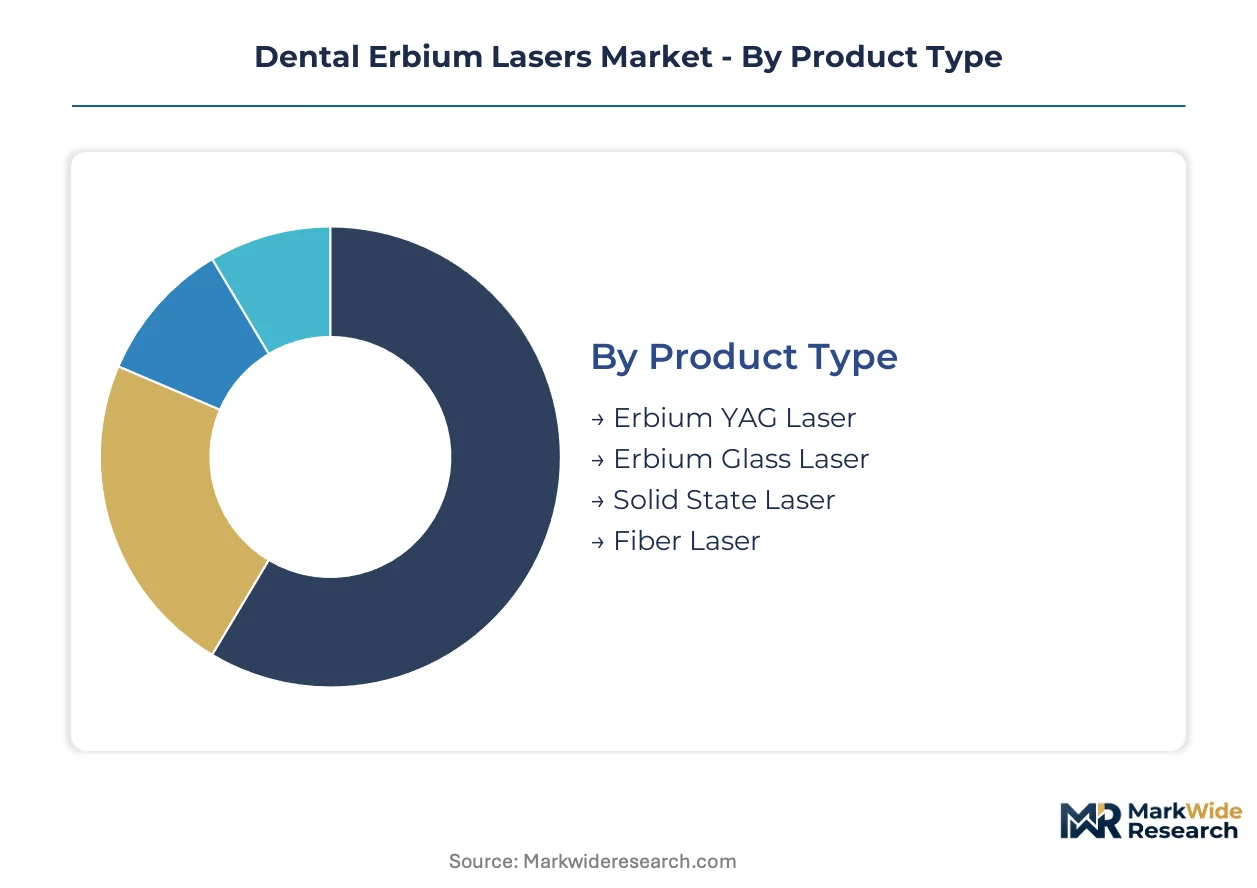
Erbium laser procurement patterns diverge sharply across clinical settings and technical specifications. Equipment buyers calibrate wavelength selection, application focus, and channel strategy against procedure volume, reimbursement frameworks, and capital constraints.
Product Type:
Wavelength architecture and resonator design determine thermal interaction profiles with oral tissues, driving differentiation in cutting precision, maintenance burden, and capital cost.
- Erbium YAG Laser:Operating at 2,940 nm, these systems exploit peak water absorption for thermomechanical ablation of enamel and dentin with minimal collateral thermal damage. Demand concentrates in German dental clinics where reimbursement for laser-assisted cavity preparation has matured, though premium crystal sourcing from Swiss optics suppliers constrains OEM margins.
- Solid State Laser:Diode-pumped architectures deliver superior beam quality and extended maintenance intervals compared to lamp-pumped alternatives. Adoption is climbing fastest among United States group practice networks seeking to compress total cost of ownership across high-volume operatory schedules.
- Erbium Glass Laser:Phosphate glass host matrices enable compact footprint designs suited to European practice spatial constraints. These systems trade peak power for portability.
- Fiber Laser:Ytterbium-doped fiber architectures remain peripheral in dental applications due to wavelength mismatch with water absorption peaks, limiting hard tissue efficacy.
Mature deployment sits with Erbium YAG Laser systems. Newer deployment is concentrated in Solid State Laser architectures.
Application:
Procedure reimbursement coding and clinical evidence depth shape application-level demand trajectories, with periodontal protocols gaining traction against established cavity preparation volumes.
- Cavity Preparation:Enamel and dentin cutting commands the largest procedure volume across installed erbium laser bases, leveraging established FDA 510(k) predicates and documented microleakage reduction versus conventional rotary instrumentation. Demand remains anchored in United States dental clinics where waterlase-compatible systems dominate.
- Periodontal Treatment:Laser-assisted sulcular debridement protocols displace conventional scaling and root planing through bactericidal action and reduced post-operative inflammation. German statutory health insurance reimbursement frameworks now cover these procedures, accelerating adoption across dental service organizations.
- Soft Tissue Surgery:Gingivectomy and frenectomy applications benefit from simultaneous cutting and coagulation, reducing operative bleeding and suture requirements.
- Teeth Whitening:Erbium laser activation of bleaching gels represents a marginal application segment constrained by diode laser cost competition and limited clinical differentiation.
Volume concentration remains with Cavity Preparation. Steepest expansion trajectory belongs to Periodontal Treatment.
End User:
Capital intensity and procedure specialization fragment end-user demand, with independent clinics prioritizing versatility and hospital systems emphasizing regulatory compliance documentation.
- Dental Clinics:Independent and group practices drive the majority of unit demand, selecting tabletop configurations optimized for space constraints and multi-procedure versatility. German and United States markets exhibit divergent preferences for dual-wavelength versus single-modality systems.
- Hospitals:Academic medical centers and oral surgery departments require comprehensive clinical evidence packages and ISO 13485 quality documentation to satisfy procurement committee standards, extending sales cycles.
- Research Laboratories:Preclinical investigation facilities source specialized wavelengths and pulse parameter configurations unavailable in commercial clinical systems.
- Academic Institutions:Dental schools balance training requirements against research agendas, favoring platforms with extensive educational support and standardized curriculum integration.
Installed base depth sits with Dental Clinics. Emerging procurement volume is concentrated in Hospitals.
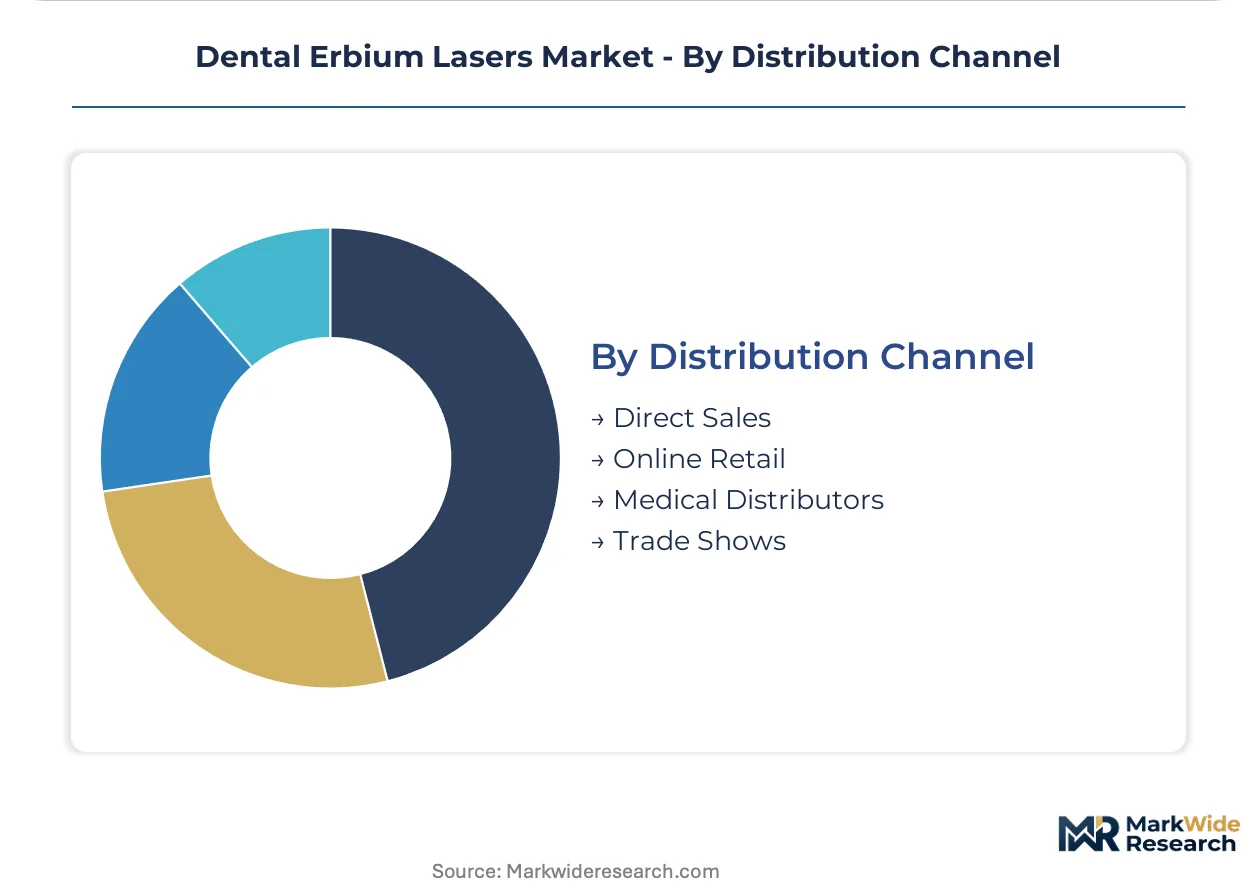
Distribution Channel:
Channel selection reflects buyer sophistication, with direct relationships dominating high-value capital equipment and distributor networks penetrating price-sensitive segments.
- Direct Sales:Manufacturer field organizations manage complex capital equipment transactions, providing site planning, installation supervision, and clinical training. United States group practice networks and German dental service organizations negotiate unbundled service and consumable contracts through direct channels.
- Medical Distributors:Regional specialty distributors penetrate independent dental practices with constrained capital budgets, offering equipment financing and trade-in programs.
- Online Retail:E-commerce penetration remains limited to consumables and replacement fibers, with capital equipment transactions requiring physical demonstration and installation support.
- Trade Shows:Industry exhibitions serve primarily as lead generation and competitive intelligence platforms rather than direct transaction venues.
Transaction value concentration sits with Direct Sales. Channel expansion is concentrated in Medical Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision optics manufacturers supply erbium-doped crystals and resonator mirrors that anchor global laser source production for dental OEMs.
United States
FDA 510(k) premarket notification pathways accelerate clearance timelines for Class II medical devices. Group practice networks in Texas and Florida drive replacement demand for dual-wavelength platforms. The Dallas-Fort Worth metroplex hosts specialized dental equipment distributors penetrating independent clinic segments.
Germany
Statutory health insurance reimbursement frameworks now cover laser-assisted periodontal therapy and cavity preparation procedures. EU MDR post-market surveillance obligations intensify clinical evidence requirements for active implantable devices. Stuttgart precision optics clusters supply erbium-doped YAG crystals to downstream laser OEMs.
Japan
PMDA marketing approval pathways govern medical device commercialization with emphasis on electrical safety and clinical performance documentation. Tokyo and Osaka dental clinics prioritize compact tabletop configurations optimized for spatial constraints. METI industrial standards shape quality management system expectations for imported laser systems.
China
NMPA medical device registration requirements impose clinical trial and manufacturing inspection obligations for imported active therapeutic equipment. Shanghai and Beijing dental service organizations consolidate procurement across multi-location practice networks. Domestic diode laser manufacturers compete on cost for soft tissue applications.
Switzerland
Swissmedic medical device regulations align with EU MDR requirements while maintaining independent conformity assessment procedures. Zurich and Basel precision manufacturing clusters produce high-damage-threshold resonator optics for erbium laser cavities. The country's optical component suppliers command premium positioning in global supply chains.
Dental Erbium Lasers Market Competitive Landscape
Global majors compete with regional champions across wavelength architecture and service bundling strategies. The vendor base stratifies between integrated platform specialists and pure-play erbium manufacturers. Three archetypes dominate: dual-wavelength convergers, compact tabletop optimizers, and consumable-anchored installed base operators. Capacity expansion in German crystal growth facilities and unbundled after-sales service contracts represent the primary competitive vectors reshaping positioning.
Within the dual-wavelength converger tier, Fotona exemplifies integrated platform architecture combining erbium and Nd:YAG capabilities. BIOLASE occupies a position anchored to recurring consumable revenue streams across North American installed bases. Elexxion AG represents the compact tabletop optimizer archetype calibrated for European practice spatial constraints. These three entities collectively illustrate the strategic segmentation between wavelength integration, consumable economics, and form factor specialization that defines competitive differentiation in this market.
| Leading Market Players |
|---|
| BIOLASE |
| Fotona |
| Light Instruments |
| Lambda SpA |
| LIGHTMED |
| Elexxion AG |
| Ivoclar Vivadent |
| Lumenis |
| Convergent Dental |
| Others |
Pricing and Supply Chain Analysis
German precision optics engineers concentrated in Stuttgart and the Black Forest region command wage premiums that compress pricing-tier spreads between premium erbium laser systems and mid-market alternatives. Labor-cost differentials between Swiss resonator mirror specialists and Asian assembly operations create three distinct pricing tiers that OEMs navigate through warranty bundling and service unbundling strategies.
Pricing Analysis
Warranty and preventive maintenance bundling versus unbundled after-sales contracts now drives price differentiation across German, United States, and Japanese dental clinic procurement. Three-tier pricing structure across premium, standard, and economy levels separates Fotona dual-wavelength platforms from Elexxion compact tabletop systems and distributor-sourced diode alternatives. Pricing pressure stems from capital equipment intensity constraining independent practice adoption. Group practice networks exhibit lowest price sensitivity; independent clinics with constrained credit access face highest budget elasticity.
Supply Chain Analysis
EU MDR local-content rules and Swissmedic domestic manufacturing documentation requirements are reshaping sourcing patterns for erbium-doped YAG crystals and resonator optics. Supply concentrates in Germany, Switzerland, and Japan for precision optics; China dominates fiber laser component fabrication. Raw material dependencies include erbium oxide rare earth elements, synthetic sapphire substrates, and high-damage-threshold dielectric coatings. Single-source vulnerability concentrates in Stuttgart crystal growth facilities. Distribution runs through direct manufacturer field organizations for capital equipment and regional specialty distributors for consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR post-market surveillance obligations and strengthened clinical evidence requirements are consolidating the vendor base, forcing pure-play erbium specialists without robust quality management systems toward acquisition or exit.
For Market Incumbents: Anchor competitive position through backward integration into German crystal growth capacity and dual-wavelength platform R&D to defend against standalone diode laser substitution. Extend ISO 13485 quality documentation depth to satisfy notified body scrutiny. Control consumable tip supply agreements across installed base operators to lock in recurring revenue streams. For New Entrants and Emerging Players: Enter via compact tabletop designs optimized for Japanese and Chinese dental clinic spatial constraints, where domestic diode laser competition has left erbium hard-tissue cutting underserved. Target hospital oral surgery departments requiring comprehensive clinical evidence packages. Pursue distributor financing partnerships to overcome capital equipment intensity barriers among independent practices. For Investors and Strategic Acquirers: Re-rating potential sits with dual-wavelength platform specialists given accelerating replacement cycles compressing single-modality demand. Long-term viability favors manufacturers with captive supply of erbium-doped crystals and established EU MDR quality frameworks. Monitor German statutory health insurance reimbursement coding expansions as inflection signal for periodontal treatment volume acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Wavelength Platform Development | Integrating erbium and Nd:YAG capabilities captures replacement demand from single-modality installed bases. |
| EU MDR Quality System Restructuring | ISO 13485 framework upgrades satisfy notified body scrutiny for active therapeutic device classifications. |
| Consumable Supply Agreement Expansion | Waterlase-compatible disposable tips generate annuity economics across North American dental clinic networks. |
| Compact Tabletop Form Factor Engineering | Space-optimized designs penetrate Japanese and European practices with constrained operatory footprints. |
| German Crystal Growth Capacity Addition | Captive supply of erbium-doped YAG crystals mitigates Swiss and German optics supplier concentration risk. |
Research Methodology
FDA 510(k) premarket notification databases, EU MDR notified body guidance documents, and German statutory health insurance reimbursement coding records formed the secondary backbone. Primary interviews with dental clinic procurement managers, hospital biomedical engineers, precision optics manufacturing executives, and GPO contracts administrators combined with secondary validation. Bottom-up equipment shipment tracking and top-down dental service organization capital expenditure analysis enabled triangulation across market sizing approaches.
Historical trendline analysis of erbium laser system deployments across German, United States, and Japanese dental clinics established baseline penetration rates. The analytical framework segmented by wavelength architecture, application indication, end-user setting, and regional regulatory cluster throughout the forecast period. CAGRs derived from procedure volume growth trajectories, reimbursement expansion schedules, and equipment replacement cycle compression. Forecast inputs incorporated EU MDR transition timelines and FDA predicate device pathway velocity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under reimbursement coding reversals or rare earth supply disruptions. Forecasts reflect assumptions around regulatory harmonization progress and clinical evidence accumulation rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Global Dental Bone Graft Substitutes Market
Dental Devices
Surgical Dental Loupes and Camera Market
Dental Devices
Dental Air Abrasion Market
Dental Devices
North America Dental Implants and Prosthetics Market
Dental Devices
Dental Impression Tray Market
Dental Devices
Dental Rapid Prototyping Systems Market
Dental Devices
Dental CAD/CAM Market
Dental Devices
Lights for Dental Healthcare Market
Dental Devices
Global Professional Teeth Whitening and Power Toothbrushes Market
Dental Devices
China Dental Implants Market
Dental Devices
South Africa Dental Devices Market
Dental Devices
Gingivitis Treatment Market
Dental Devices
Dental Etching Liquid Market
Dental Devices
Dental Devices and Consumables Market
Dental Devices
Dental Forceps Market
Dental Devices
Glenoid Fossa Prosthesis Market