
 United Kingdom Anesthesia Devices Market | 2026-2036
United Kingdom Anesthesia Devices Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Anesthesia Devices Market Analytics
The United Kingdom anesthesia devices market is consolidating around a widening gap between premium integrated anesthesia workstations and commodity delivery devices. Medtronic PLC leverages its end-to-end perioperative portfolio to anchor high-value hospital contracts across NHS England trusts. Draegerwerk AG competes through specialized ventilation-anesthesia convergence platforms that dominate critical care-adjacent surgical settings.
Anesthesia devices encompass mechanical systems, electronic monitors, and disposable components engineered to administer inhalational and intravenous anesthetics while maintaining precise control over gas mixtures, flow rates, and patient vital signs during surgical procedures. These systems integrate vaporizers, breathing circuits, and scavenging equipment to ensure safe, reversible unconsciousness and analgesia across operative environments. The anesthesia systems segment sustains the dominant revenue share as NHS capital budgets prioritize replacement of aging Datex-Ohmeda and Penlon legacy units with modular platforms. Wireless-enabled monitoring systems represent the fastest-expanding technology tier, driven by real-time data integration demands within digital operating theatres.
The UK's Medicines and Healthcare products Regulatory Agency (MHRA) now operates independent from EMA oversight, imposing UKCA marking requirements that reshape import compliance for EU-manufactured devices. NHS England's Medical Technology Procurement Framework further constrains market access through centralized tendering and value-based assessment criteria. Stakeholders must monitor MHRA convergence negotiations with FDA and TGA mutual recognition agreements to anticipate future conformity burden shifts.
Market Dynamics
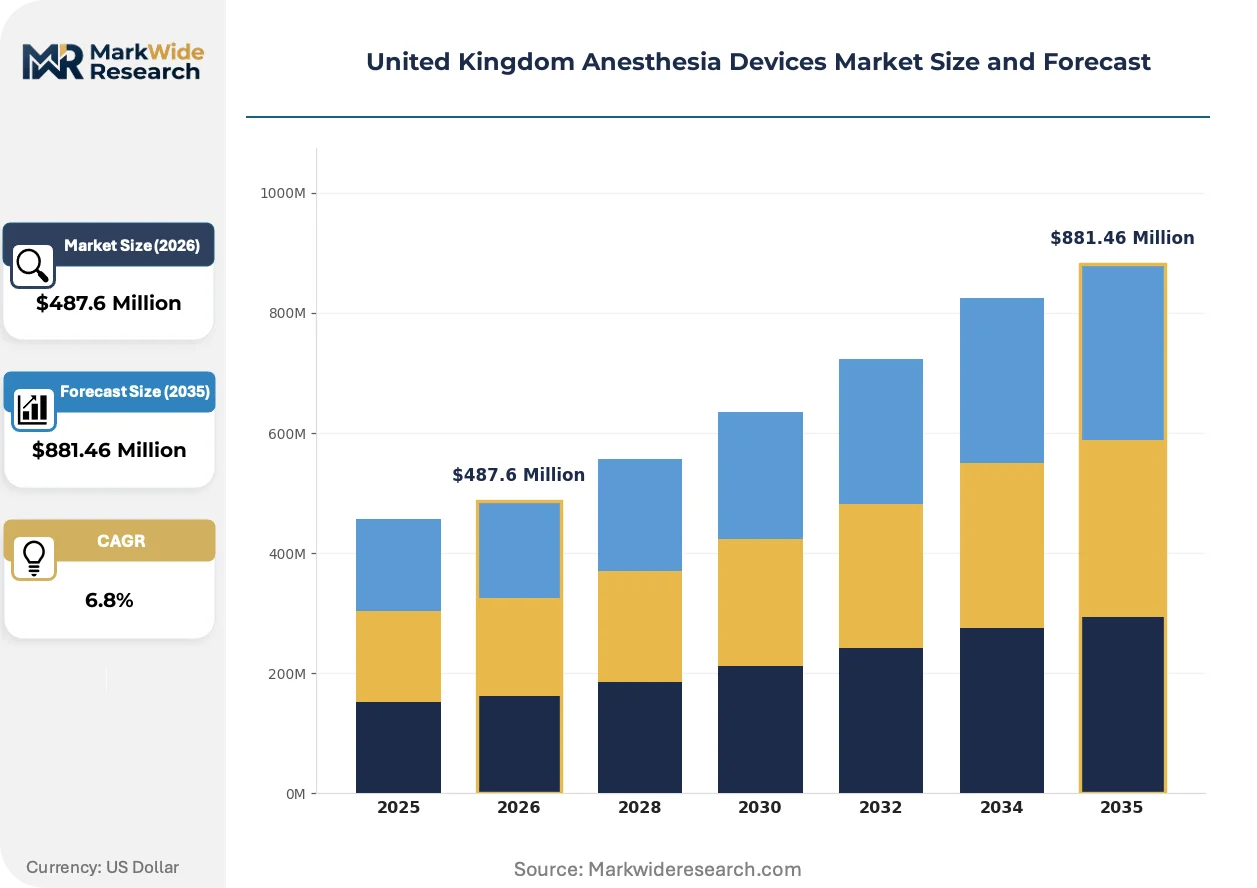
NHS England's capital replacement cycles for perioperative infrastructure are accelerating as trusts confront aging anesthesia workstation fleets and MHRA's post-Brexit UKCA marking deadlines force compliance-driven procurement decisions.
Growth Catalysts
- Digital Operating Theatre Mandates:NHS England's infrastructure modernization programs are embedding wireless-enabled monitoring systems into new hospital builds, creating pull-through demand for integrated anesthesia platforms.
- MHRA Regulatory Autonomy:The UK's independent device approval pathway is streamlining conformity assessment for domestic manufacturers while creating differentiated access conditions for EU-imported equipment.
- Tertiary Surgical Hub Concentration:England's Oxford-Cambridge-London corridor is consolidating complex procedures into high-volume centers, concentrating capital equipment procurement among trusts with expanded anesthesia capacity requirements.
Market Restraints
- Capital Budget Compression:NHS financial pressures are extending replacement cycles for anesthesia workstations beyond optimal technical lifespans, deferring revenue recognition for equipment suppliers.
- UKCA Transition Friction:EU-manufactured devices face dual certification burdens during the MHRA-EMA divergence period, elevating compliance costs and elongating market entry timelines.
- Disposable Component Cost Volatility:Polymer supply chain disruptions are compressing margins on breathing circuits and vaporizer accessories, offsetting gains from capital equipment sales.
Strategic Opportunities
- Scotland and Wales Trust Modernization:Devolved health authorities outside England's procurement frameworks present less contested tender environments for anesthesia workstation suppliers.
- Remote Monitoring Integration:Perioperative data platforms are converging with anesthesia delivery systems, enabling subscription-based service models that extend customer lifetime value.
- Day Surgery Expansion:NHS England's ambulatory surgical center rollout is creating demand for compact, portable anesthesia systems optimized for lower-acuity settings.
Industry Challenges
- Specialized Biomedical Engineering Talent Scarcity:NHS trusts face recruitment gaps for anesthesia equipment maintenance and calibration, forcing reliance on manufacturer service contracts that inflate total cost of ownership.
- Legacy System Integration Complexity:Replacement of Datex-Ohmeda and Penlon units requires costly interoperability testing with existing hospital information systems, delaying procurement decisions.
- UKCA Certification Timeline Uncertainty:MHRA's evolving mutual recognition negotiations with FDA and TGA are creating planning ambiguity for manufacturers structuring conformity assessment investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Anesthesia Devices Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anesthesia Systems, Delivery Devices, Monitoring Systems, Consumables End User: Hospitals, Surgical Centers, Clinics, Emergency Services Technology: Traditional, Electronic, Wireless, Modular Application: Pain Management, Surgery, Critical Care, Sedation |
| Companies Covered | Medtronic PLC, Draegerwerk AG, GE Healthcare, B. Braun SE, Koninklijke Philips NV, Fisher & Paykel Healthcare, Mindray Medical International Limited, Ambu AS, Smiths Group plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Anesthesia Devices Market Evolving Landscape
Perioperative care digitization is fundamentally restructuring anesthesia device value propositions, with hardware vendors competing on data integration capabilities rather than gas delivery specifications alone.
Closed-loop anesthesia delivery systems are converging with AI-driven pharmacokinetic modeling to enable automated titration of intravenous and inhalational agents. NHS England's innovation adoption programs are piloting these platforms in tertiary cardiac and neurosurgical units. The technology is converging with electronic health record architectures to compress documentation burden and reduce variability in anesthetic depth management.
MHRA's post-Brexit regulatory framework is diverging from EU MDR harmonization timelines, imposing UKCA marking requirements that reshape import compliance for continental European manufacturers. The industrial consequence is a bifurcation in device availability between UK and EU markets during transition periods. Anesthesia workstation suppliers with established UK notified body relationships are securing faster market access than competitors reliant on EU-based conformity assessment.
Trust-level procurement consolidation is compressing vendor diversity as NHS England's Medical Technology Procurement Framework centralizes anesthesia equipment tendering. Independent community hospitals and smaller district general hospitals are losing negotiation autonomy as regional procurement collaboratives aggregate purchasing power. The shift is most visible in England's Midlands and North regions where sustainability and transformation partnerships are standardizing equipment specifications across multiple trust boundaries.
United Kingdom Anesthesia Devices Market Segmentation
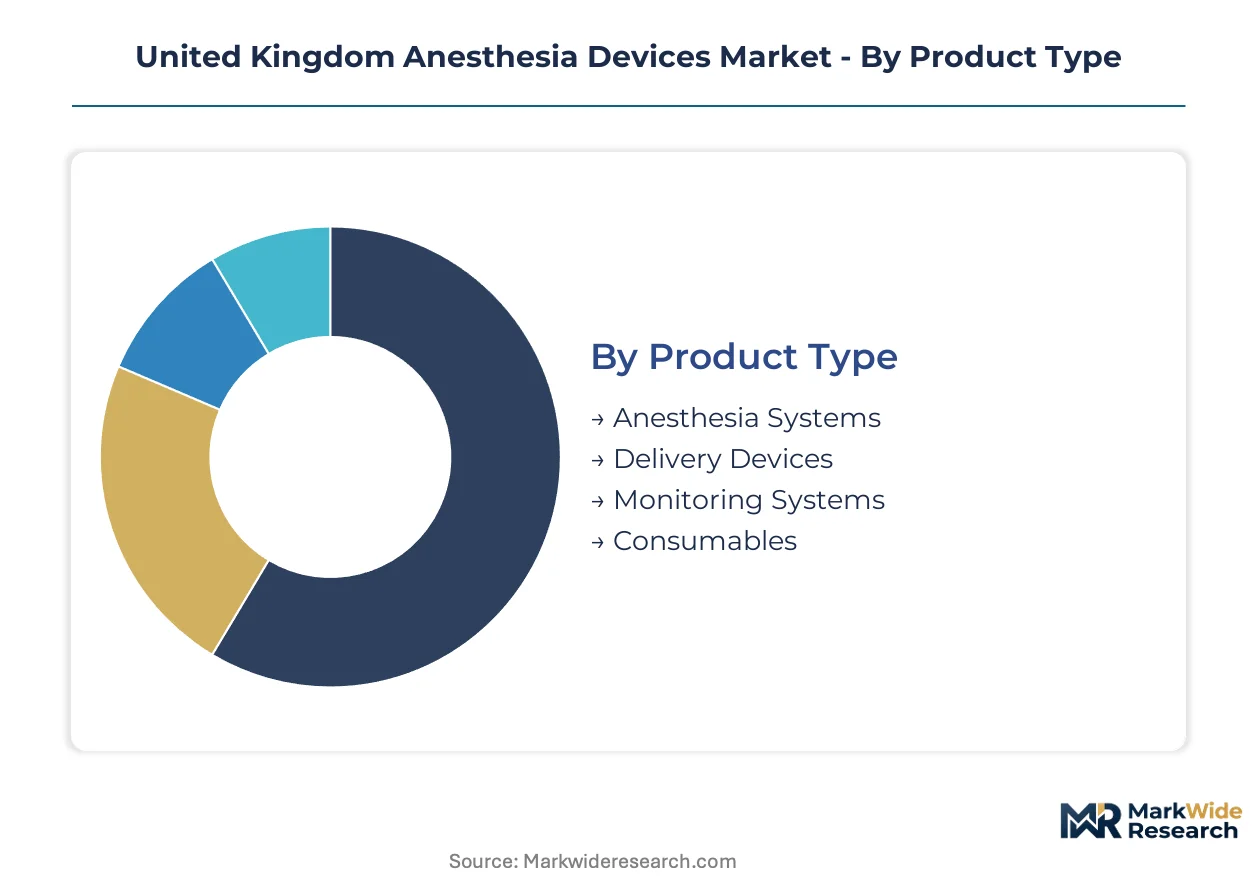
NHS capital replacement cycles and MHRA compliance deadlines are forcing trusts to prioritize specific equipment tiers. Segmentation reveals where procurement budgets concentrate and which technology trajectories align with England's digital operating theatre mandates.
Product Type:
Upgrade cycles favor integrated platforms over standalone components as trusts consolidate vendor relationships and reduce interoperability friction.
- Anesthesia Systems:Integrated workstations combining vaporizers, ventilators, and scavenging equipment dominate NHS England tenders. Oxford-Cambridge-London corridor trusts prioritize modular platforms with 15-year service lifecycles to amortize capital outlay across multiple replacement cycles.
- Monitoring Systems:Wireless-enabled platforms with real-time data integration capabilities are displacing hardwired legacy units. Demand concentrates in new hospital builds where digital infrastructure permits seamless electronic health record connectivity without retrofit costs.
- Delivery Devices:Portable vaporizers and gas delivery units serve ambulatory surgical centers with space-constrained environments.
- Consumables:Breathing circuits and vaporizer accessories face margin pressure from polymer supply volatility.
Anesthesia Systems sits at the top of the volume ranking, with Monitoring Systems climbing the fastest.
End User:
Procurement authority concentration determines access conditions, with centralized frameworks favoring suppliers capable of multi-site service contracts.
- Hospitals:NHS Foundation Trusts and acute teaching hospitals account for the bulk of capital expenditure on integrated anesthesia workstations. England's regional procurement collaboratives aggregate purchasing power across multiple trust boundaries, compressing vendor diversity.
- Surgical Centers:NHS England's day surgery expansion is creating demand for compact, portable systems optimized for lower-acuity settings with rapid turnover requirements.
- Clinics:Independent community hospitals outside centralized frameworks retain limited negotiation autonomy for specialty anesthesia equipment.
- Emergency Services:Air ambulance and mobile intensive care units require ruggedized portable delivery devices with extended battery operation.
Hospitals capture the dominant procurement volume, though Surgical Centers are expanding most quickly amid ambulatory care rollout.
Technology:
Cost tier stratification separates premium integrated platforms from commodity equipment, with mid-tier electronic systems facing displacement pressure.
- Wireless:Real-time data transmission architectures enable remote monitoring and predictive maintenance contracts. NHS digital operating theatre mandates embed these capabilities into new infrastructure specifications.
- Modular:Upgradeable component architectures allow trusts to extend platform lifecycles through phased capability additions rather than full replacement.
- Electronic:Microprocessor-controlled gas mixing and flow regulation systems occupy a contracting middle tier as trusts leapfrog to wireless-enabled alternatives.
- Traditional:Pneumatic-mechanical systems persist in resource-constrained settings and backup redundancy configurations.
Wireless platforms command the steepest expansion trajectory, while Traditional equipment retains residual presence in secondary care settings.
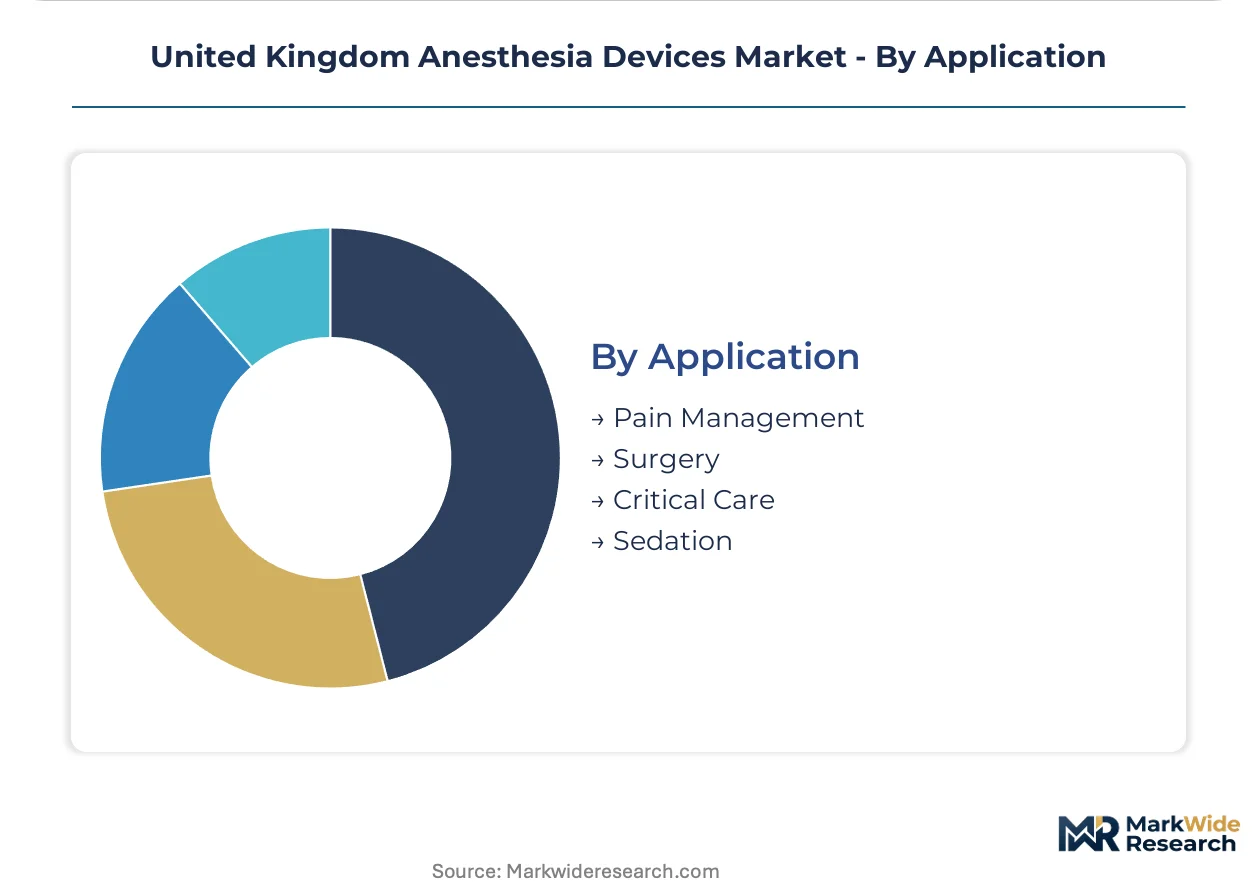
Application:
Clinical complexity requirements drive specification differentiation, with critical care convergence demanding ventilation-anesthesia integration.
- Surgery:General operative environments require full-spectrum anesthesia workstations with scavenging and multi-agent vaporizer capabilities. Tertiary cardiac and neurosurgical units pilot closed-loop automated delivery systems.
- Critical Care:ICU-adjacent surgical settings demand convergence platforms integrating anesthesia delivery with advanced ventilation modes for hemodynamically unstable patients.
- Pain Management:Chronic pain clinics utilize specialized infusion pumps and regional anesthesia delivery equipment with precise dosing control.
- Sedation:Endoscopy and interventional radiology suites require compact systems with rapid emergence profiles and minimal recovery infrastructure.
Surgery maintains the largest installed base, with Critical Care gaining share fastest through platform convergence with mechanical ventilation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Scotland's devolved procurement frameworks diverge sharply from NHS England's centralized tendering, creating differentiated access conditions for anesthesia workstation suppliers across the UK's internal borders.
London and the Southeast
Oxford-Cambridge-London corridor trusts concentrate capital expenditure on modular anesthesia platforms with 15-year service lifecycles. NHS England's Medical Technology Procurement Framework governs equipment acquisition, embedding wireless-enabled monitoring requirements into infrastructure specifications. Imperial College Healthcare and Guy's and St Thomas' NHS Foundation Trust anchor demand for integrated perioperative systems.
Midlands
Sustainability and transformation partnerships aggregate purchasing power across multiple trust boundaries, compressing vendor diversity in Birmingham and Leicester surgical hubs. MHRA's UKCA marking deadlines accelerate compliance-driven replacement of legacy Datex-Ohmeda units. University Hospitals Birmingham NHS Foundation Trust leads regional adoption of closed-loop anesthesia delivery pilots.
North England
Manchester and Leeds tertiary centers consolidate complex procedures into high-volume surgical hubs with expanded anesthesia capacity requirements. NHS capital budget pressures extend replacement cycles beyond optimal technical lifespans in smaller district general hospitals. The Northern Care Alliance NHS Foundation Trust drives standardization across Greater Manchester.
Scotland
NHS Scotland's devolved health authority operates outside England's procurement frameworks, presenting less contested tender environments for workstation suppliers. Scottish Health Technologies Group assessments determine equipment adoption timelines distinct from NICE pathways. Glasgow and Edinburgh teaching hospitals anchor capital expenditure on critical care-adjacent anesthesia platforms.
Wales
Velindre University NHS Trust and Cardiff and Vale University Health Board concentrate surgical capacity in South Wales with procurement autonomy from English frameworks. Welsh Government health technology assessments impose distinct value-based criteria on anesthesia equipment selection. Swansea Bay University Health Board pilots remote monitoring integration in perioperative settings.
United Kingdom Anesthesia Devices Market Competitive Landscape
Top-tier vendors anchor integrated workstation supply, while mid-tier specialists compete on ventilation-anesthesia convergence and portable delivery systems. Market structure consolidates around end-to-end perioperative portfolios and modular platform architectures. Two strategic archetypes dominate: diversified medical technology conglomerates with service contract capabilities, and focused anesthesia specialists with critical care adjacencies. Competitive moves center on multi-site NHS service agreements and phased capability upgrades extending platform lifecycles.
Within the diversified conglomerate tier, Medtronic PLC and GE Healthcare exemplify scale-driven positioning through comprehensive perioperative portfolios. Draegerwerk AG occupies a specialized position representing ventilation-anesthesia convergence expertise. These three anchors illustrate the market's bifurcation between full-service hospital contracts and critical care-integrated delivery platforms.
| Leading Market Players |
|---|
| Medtronic PLC |
| Draegerwerk AG |
| GE Healthcare |
| B. Braun SE |
| Koninklijke Philips NV |
| Fisher & Paykel Healthcare |
| Mindray Medical International Limited |
| Ambu AS |
| Smiths Group plc |
| Others |
Value Network & Pricing Analysis
Polymer price indices for medical-grade polymers and specialty resins cascade through anesthesia device manufacturing, compressing margins on breathing circuits and vaporizer accessories while amplifying cost differentials between integrated workstation platforms and commodity delivery systems.
Pricing Analysis
Capacity additions in German and Swiss precision manufacturing hubs are reshaping price floors for premium anesthesia workstations, enabling modular platform suppliers to defend premium positioning against mid-tier electronic system competitors. Three-tier pricing structure across premium, standard, and economy levels separates wireless-enabled integrated systems with 15-year service contracts from basic electronic units and legacy pneumatic-mechanical backups. Pricing pressure stems from NHS capital budget compression extending replacement cycles and forcing deferred procurement decisions. District general hospitals and smaller trusts exhibit highest price sensitivity, while Oxford-Cambridge-London corridor tertiary centers prioritize total cost of ownership over acquisition price.
Supply Chain Analysis
UKCA marking requirements and MHRA conformity assessment protocols gate market access for EU-manufactured anesthesia components, creating certification friction that advantages domestic UK notified body relationships. Component sourcing draws from Germany, Switzerland, and the United States for precision vaporizers, ventilator modules, and gas mixing systems. Supply chains rest on medical-grade polymer feedstocks, electronic sensor arrays, and specialized pneumatic valves. Single-source vulnerability concentrates in legacy Datex-Ohmeda and Penlon spare parts manufacturing. Distribution runs through NHS England's Medical Technology Procurement Framework and regional procurement collaboratives, consolidating vendor access points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom anesthesia devices market represents a late-cycle quality story as NHS trusts prioritize wireless-enabled monitoring integration and 15-year platform lifecycles over lowest-bid procurement.
For Market Incumbents: Deepen service contract penetration across NHS Foundation Trusts to lock out emerging ventilation-anesthesia convergence specialists. Anchor multi-site agreements through predictive maintenance capabilities and remote monitoring integration. Defend against mid-tier portable system competitors by accelerating closed-loop anesthesia delivery pilots in tertiary cardiac and neurosurgical units. Prioritize UKCA certification investment to maintain faster market access than EU-reliant competitors during MHRA mutual recognition negotiations. For New Entrants and Emerging Players: Regional procurement collaboratives in England's Midlands and North present undercontested entry points for modular platform suppliers capable of phased capability upgrades. Scotland and Wales devolved health authorities operate outside NHS England's centralized frameworks, offering less contested tender environments with distinct value-based assessment criteria. Target day surgery expansion segments with compact, portable anesthesia systems optimized for rapid turnover ambulatory settings. Pursue hospital system partnership models that bundle equipment with biomedical engineering training to address NHS talent scarcity. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized anesthesia workstation manufacturers possessing UK notified body relationships and critical care-adjacent platform convergence capabilities. Long-term viability over the projection horizon favors suppliers with software companion development competencies and subscription-based remote monitoring revenue streams. Acquisition target archetype: mid-cap specialists with established MHRA compliance pathways and NHS service infrastructure. Signal to watch: MHRA-FDA mutual recognition agreement progress as inflection indicator for conformity burden normalization.| Strategic Initiative | Industry Significance |
|---|---|
| MHRA UKCA Certification Investment | Accelerates market access timelines relative to EU-notified body dependent competitors during regulatory divergence. |
| Hospital System Partnership | Secures multi-site NHS Foundation Trust contracts through bundled service and predictive maintenance capabilities. |
| Software Companion Development | Enables subscription-based remote monitoring revenue streams extending customer lifetime value beyond hardware sales. |
| Closed-Loop Delivery Pilot Expansion | Positions suppliers for NHS England innovation adoption programs in tertiary cardiac and neurosurgical units. |
| Biomedical Engineering Training Programs | Addresses NHS trust talent scarcity while creating captive service relationship dependencies. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down anesthesia workstation shipment tracking forms the analytical core of this study. Primary interviews with NHS Foundation Trust procurement directors, biomedical engineering leads, hospital purchasing committee members, and GPO contracts managers combined with secondary validation against MHRA device registration databases, NHS England procurement framework disclosures, and hospital capital expenditure records. Triangulation across stakeholder inputs and documentary sources ensures segmentation integrity.
Historical trendline analysis of anesthesia system replacement cycles, monitoring technology adoption curves, and digital operating theatre infrastructure deployment patterns informed projection modeling. Segmentation dimensions span product type, end user, technology tier, and application complexity across the analysis window. CAGRs derive from equipment lifecycle analysis, capital budget trajectory assessment, and regulatory compliance deadline impact modeling. Forecast inputs incorporate MHRA-EMA divergence timelines, NHS procurement framework evolution, and polymer supply chain volatility indicators.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to MHRA mutual recognition negotiations, NHS capital allocation shifts, and closed-loop anesthesia technology adoption rates. Projections reflect assumptions regarding UKCA marking enforcement consistency, procurement framework centralization trajectories, and perioperative digitization investment priorities. A model refresh is warranted upon material change in MHRA-FDA regulatory convergence progress or NHS England Medical Technology Procurement Framework restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Bluetooth Hearing Aids Market
Medical Devices
Tissue Expanders Market
Medical Devices
Coronary Guidewires Market
Medical Devices
Interphalangeal Fusion Market
Medical Devices
Artificial Urinary Sphincters Market
Medical Devices
Semiconductor Laser Therapeutic Device Market
Medical Devices
Argentina Aesthetic Devices Market
Medical Devices
Middle East and Africa Medical Device Regulatory Affairs Outsourcing Market
Medical Devices
Infant Incubator Market
Medical Devices
Global Endovenous Ablation Devices Market
Medical Devices
Tracheobronchial Suction Catheters Market
Medical Devices
Global Stroke Assistive Devices Market
Medical Devices
Eye Massage Device Market
Medical Devices
Medical Puncture Navigation Robot Market
Medical Devices
Chile Respiratory Devices Market
Medical Devices
Respiratory Devices Market