
 Electric Dental Handpieces Market | 2026-2036
Electric Dental Handpieces Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Dental Handpieces Market Analysis
The premium-speed specification tier is collapsing the gap between entry-level and high-performance electric handpieces. NSK Dental leverages ceramic bearing technology to sustain torque consistency across extended clinical cycles. Dentsply Sirona anchors its position through integrated CAD/CAM workflows that bundle handpiece hardware with digital impression systems. W&H Dentalwerk differentiates via Austrian manufacturing scale and direct distribution control across Central European dental chains.
An electric dental handpiece is a motorized rotary instrument powered by an electric micromotor, typically operating at 5,000 to 200,000 RPM with adjustable torque output for cutting, polishing, or surgical preparation of hard and soft oral tissues. Brushless motor systems now dominate the technology segment due to reduced heat generation, extended sterilization cycle tolerance, and programmable speed-torque curves that match specific clinical applications. Surgical handpieces command the strongest margin pools within product type segmentation, driven by implantology and oral surgery volume, while restorative handpieces maintain the largest installed base across general practice settings.
FDA 510(k) clearance pathways and the EU MDR's Class IIa device reclassification shape product development timelines and clinical evidence requirements for electric handpiece manufacturers. ISO 14457 standards for dental handpieces establish dimensional, performance, and sterilization benchmarks that determine market access across regulated jurisdictions. Stakeholders must monitor how MDR notified body capacity constraints and evolving electrical safety harmonization between IEC 60601 and national standards reshape certification costs and competitive entry barriers.
Market Dynamics
Brushless motor electrification is compressing the performance gap between premium and mid-tier handpiece tiers, forcing incumbents to defend margin pools through software-integrated service contracts rather than hardware differentiation alone.
Growth Catalysts
- EU MDR Class IIa Reclassification:Stricter clinical evidence requirements for reusable surgical instruments are accelerating replacement cycles as clinics preempt compliance-driven obsolescence of legacy motor systems.
- Ceramic Bearing Adoption:Sintered silicon nitride bearings extend sterilization tolerance beyond 1,000 autoclave cycles, reducing total cost of ownership for high-volume implantology practices.
- German Precision Manufacturing Clusters:Concentrated supplier ecosystems around Tuttlingen and Munich enable rapid prototyping of custom torque curves for specialized oral surgery applications.
Market Restraints
- Rare Earth Magnet Supply Concentration:Neodymium-iron-boron magnet sourcing depends on Chinese processing capacity, exposing brushless motor producers to export quota volatility and forced technology transfer requirements.
- ISO 14457 Dimensional Tolerances:Strict collet and chuck interface specifications limit third-party attachment compatibility, locking clinics into proprietary consumable ecosystems.
- Autoclave-Compatible Polymer Degradation:Repeated steam sterilization cycles degrade PEEK housing materials faster than manufacturer warranty periods, creating latent liability exposure.
Strategic Opportunities
- Indian Dental Clinic Expansion:Underpenetrated tier-2 and tier-3 cities present volume opportunities as CDSCO streamlines medical device registration pathways for Class A and B electric instruments.
- CAD/CAM Workflow Convergence:Integration of torque-feedback handpieces with intraoral scanning systems enables real-time cutting force optimization during chairside milling procedures.
- Subscription-Based Maintenance Models:Predictive motor health monitoring via embedded Hall-effect sensors allows manufacturers to unbundle capital sales from recurring calibration and bearing replacement revenue.
Industry Challenges
- MDR Notified Body Capacity Bottlenecks:Extended technical documentation review timelines delay product launches as TÜV SÜD and BSI prioritize higher-risk device categories.
- Legacy Pneumatic Infrastructure Stranding:Dental practices with sunk investments in air compressor systems face elevated retrofit costs for electric micromotor adoption.
- Cross-Contamination Protocol Complexity:Differentiated sterilization requirements between high-speed cutting and surgical implant handpieces strain central sterile supply department workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Dental Handpieces Market |
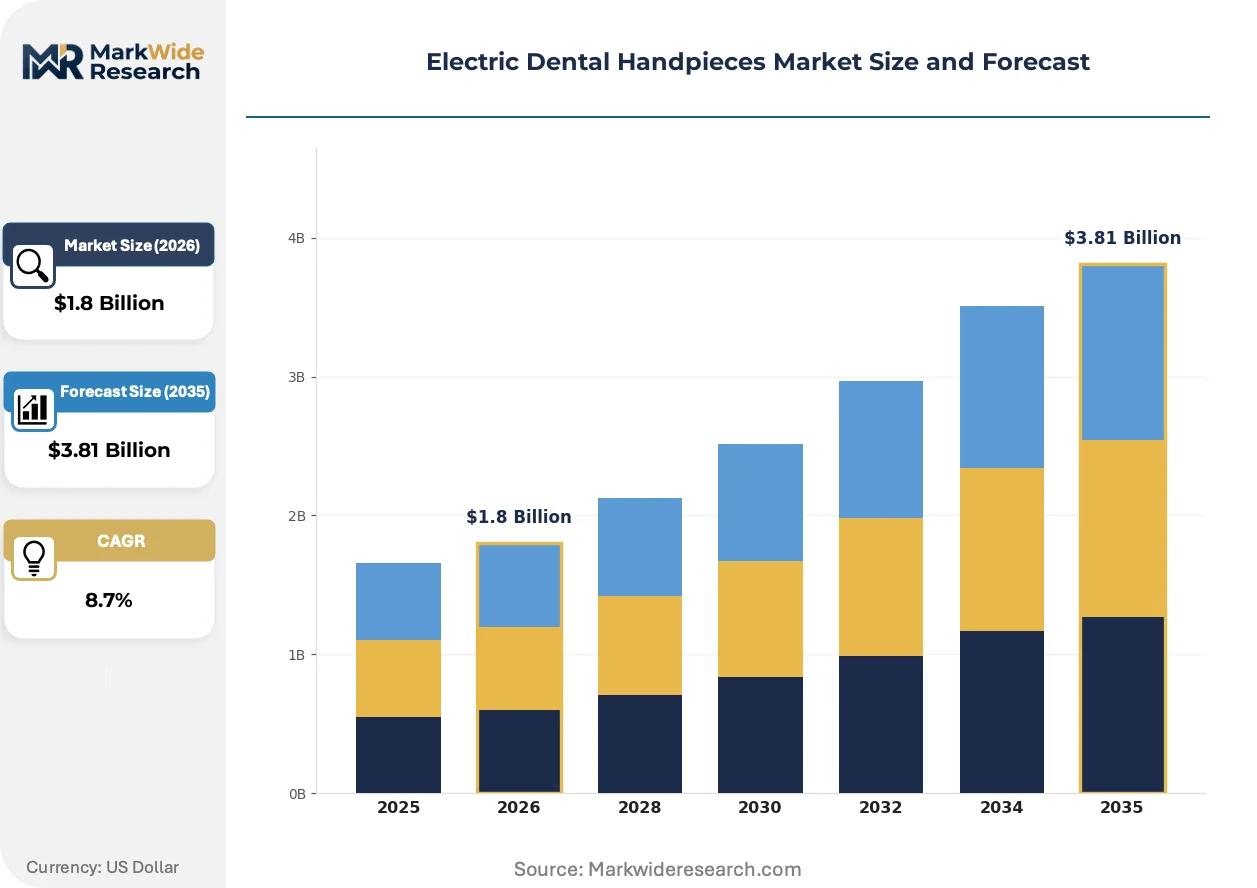
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Handpieces, Surgical Handpieces, Restorative Handpieces, Specialty Handpieces End User: Dental Clinics, Hospitals, Academic Institutions, Research Labs Technology: Brushless Motors, Turbine Technology, Micro Motor Systems, Pneumatic Systems Application: Cosmetic Dentistry, Orthodontics, Endodontics, Periodontics |
| Companies Covered | KaVo Kerr, NSK Dental, Dentsply Sirona, Bien-Air Dental, W&H Dentalwerk, Morita Corporation, A-dec Inc., SciCan Ltd., Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Dental Handpieces Market Emerging Trajectories
Digital torque telemetry and predictive maintenance algorithms are redefining how manufacturers capture lifetime value from hardware installations, shifting competitive advantage from mechanical precision to data-enabled service continuity.
Programmable speed-torque curve software is fragmenting the traditional three-tier product architecture. Mid-market clinics in Spain and Italy now access performance profiles previously restricted to premium surgical tiers through firmware licensing rather than hardware upgrades. This capability compression is eroding the price elasticity that sustained premium positioning for decades.
EU MDR Article 10 post-market surveillance obligations are forcing manufacturers to maintain active implant registries linking handpiece serial numbers to specific surgical outcomes. German notified bodies now require real-world performance data as a condition of certificate renewal, extending development timelines by eighteen to twenty-four months for new motor platforms. Surgical handpiece categories face the steepest documentation burdens.
Direct procurement from manufacturer digital portals is displacing traditional dental distributor networks in Scandinavia and the Netherlands. Large dental service organizations negotiate enterprise pricing through centralized purchasing platforms, extracting volume discounts that independent practices cannot match. This channel consolidation concentrates pricing power among buyers representing fifteen to twenty percent of national installed base.
Electric Dental Handpieces Market Segmentation
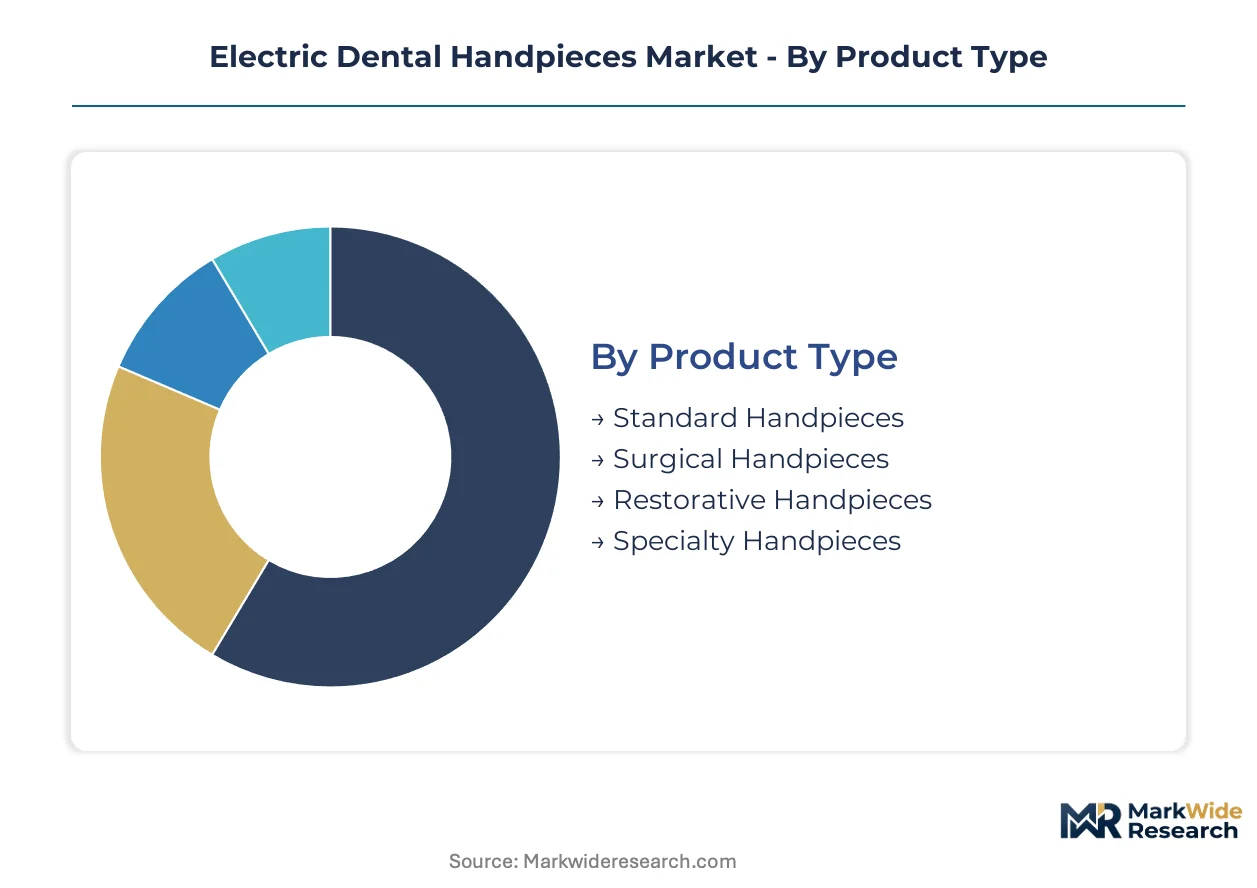
Segmentation in the electric dental handpiece market reveals how procurement priorities diverge across clinical settings and technological sophistication. Manufacturers must align torque specifications, sterilization protocols, and software integration capabilities to distinct end-user workflows rather than pursuing uniform platform strategies.
Product Type:
Margin pools concentrate in surgical and specialty configurations where precision tolerances and extended autoclave cycles justify premium positioning over standard restorative alternatives.
- Surgical Handpieces:These instruments deliver sustained torque output for implantology and bone-cutting procedures, typically operating between 40,000 and 200,000 RPM with programmable speed curves. Demand clusters in German oral surgery centers where reimbursement stability supports equipment refresh cycles. FDA 510(k) clearance timelines and EU MDR clinical evidence requirements extend development lead times for new motor platforms.
- Restorative Handpieces:General practice workhorses dominate installed base volume across North American and European dental clinics, with brushless motor retrofits replacing legacy pneumatic systems. Procurement concentrates in multi-chair group practices seeking standardized maintenance contracts across locations.
- Standard Handpieces:Entry-level electric configurations serve price-sensitive solo practitioners and emerging market clinics.
- Specialty Handpieces:Niche instruments for endodontic microsurgery and periodontal procedures command the highest unit margins.
The dominant share belongs to Restorative Handpieces, while Surgical Handpieces is closing the gap fastest.
End User:
Procurement scale and decision-making authority vary sharply across institutional categories, with dental service organizations rewriting traditional distributor relationships.
- Dental Clinics:Independent and group practices generate the majority of replacement demand, with German chains leveraging direct manufacturer portals to bypass traditional distribution. CDSCO registration streamlining in India is unlocking tier-2 and tier-3 city expansion for mid-tier equipment suppliers.
- Hospitals:Centralized sterile supply departments and capital budget cycles drive enterprise purchasing agreements, with academic medical centers requiring integrated CAD/CAM compatibility.
- Academic Institutions:Training programs prioritize durability and standardization over cutting-edge features.
- Research Labs:Biomechanical testing facilities and material science departments purchase specialized units for protocol development.
Dental Clinics command the volume base, though Hospitals are expanding procurement most aggressively through consolidation.
Technology:
Brushless architectures are displacing legacy systems across all price tiers, compressing the performance gap that once separated premium from standard offerings.
- Brushless Motors:Sintered silicon nitride bearings and rare earth magnet rotors enable 1,000+ autoclave cycles with minimal torque degradation. German precision manufacturing clusters around Tuttlingen supply rapid prototyping capabilities for custom torque curves.
- Micro Motor Systems:Compact electric drive units with integrated control electronics serve as the backbone for convertible handpiece platforms.
- Turbine Technology:Legacy air-driven systems persist in practices with sunk compressor investments.
- Pneumatic Systems:Declining installed base faces stranded asset risk as electric retrofit costs fall.
Brushless Motors holds the technology lead, with Micro Motor Systems gaining traction fastest through platform standardization.
Application:
Clinical workflow integration requirements shape handpiece specification priorities, with cosmetic and orthodontic segments driving demand for precision torque feedback.
- Cosmetic Dentistry:Chairside milling and veneer preparation demand consistent cutting force across varying enamel densities. Italian and Spanish clinics access premium performance profiles through firmware licensing rather than hardware tier upgrades.
- Endodontics:Microsurgical procedures require specialized torque-limiting mechanisms and ultrasonically activated irrigation compatibility.
- Orthodontics:Debonding and interproximal reduction procedures favor lightweight, high-speed configurations.
- Periodontics:Soft tissue management and root planing applications prioritize low-speed, high-torque delivery.
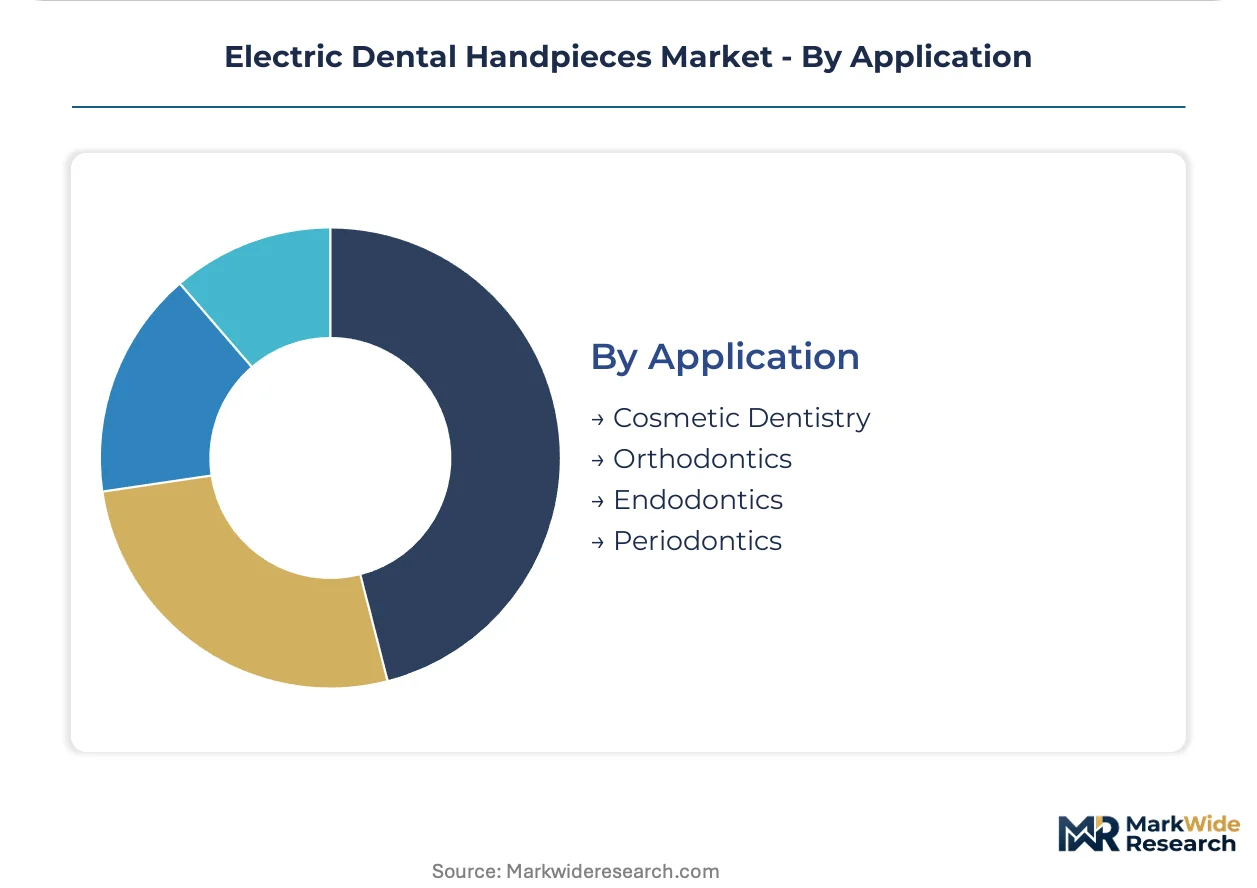
Cosmetic Dentistry generates the strongest margin contribution, while Endodontics is expanding fastest through microsurgical technique adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented German manufacturers supply precision handpiece systems to dental clinics worldwide, while the United States and China represent the largest import markets for premium electric instrumentation. Trade flows concentrate on brushless motor platforms certified under divergent regulatory regimes.
Germany
Tuttlingen and Munich manufacturing clusters produce surgical-grade handpieces for implantology practices across Europe and North America. The EU MDR's Class IIa reclassification accelerates replacement demand as clinics retire legacy pneumatic systems. Bavarian precision engineering firms prototype custom torque curves for specialized oral surgery applications.
United States
FDA 510(k) clearance pathways shape product development timelines for brushless motor platforms targeting high-volume dental service organizations. Reimbursement stability under Medicare dental expansion provisions supports equipment refresh cycles in group practices. California and Texas dental chains negotiate enterprise pricing through centralized procurement platforms.
China
Domestic manufacturers scale brushless motor production for price-sensitive clinics in tier-2 and tier-3 cities. NMPA registration requirements for Class II medical devices streamline as the national regulator harmonizes with ISO 14457 sterilization benchmarks. Yangtze River Delta precision component suppliers feed both domestic assembly and export markets.
Japan
PMDA quality management system inspections enforce stringent electrical safety standards for micromotor systems used in academic medical centers. METI industrial policy supports ceramic bearing research through university-industry partnerships. Osaka-based dental equipment distributors maintain direct technical service relationships with manufacturer engineering teams.
India
CDSCO streamlined registration for Class A and B electric instruments unlocks procurement growth in underpenetrated secondary cities. Maharashtra and Karnataka dental clinic chains import German and Japanese handpieces for premium patient segments. Domestic assemblers in Gujarat target mid-tier restorative applications with localized maintenance networks.
Electric Dental Handpieces Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and regulatory compliance capabilities. The vendor base organizes into three tiers: multinational platform conglomerates with integrated CAD/CAM workflows, mid-cap precision manufacturers with captive ceramic bearing supply, and regional assemblers serving price-sensitive emerging markets. Dominant competitive moves include strategic partnerships with dental service organizations for predictive maintenance contracts and technology licensing agreements for programmable torque curve software.
Within the premium-tier vector, NSK Dental and Dentsply Sirona occupy positions defined by ceramic bearing integration and digital workflow bundling respectively. W&H Dentalwerk exemplifies the Central European manufacturing archetype through Austrian production scale and direct distribution control. KaVo Kerr represents the platform conglomerate model with diversified dental equipment portfolios spanning multiple clinical applications.
| Leading Market Players |
|---|
| KaVo Kerr |
| NSK Dental |
| Dentsply Sirona |
| Bien-Air Dental |
| W&H Dentalwerk |
| Morita Corporation |
| A-dec Inc. |
| SciCan Ltd. |
| Danaher Corporation |
| Others |
Supply Flow & Price Mechanics
EU MDR Class IIa reclassification gates supply qualification and price differentiation simultaneously, forcing manufacturers to absorb certification costs into premium surgical tiers while mid-market restorative handpieces compete on firmware-enabled performance licensing.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on ISO 14457 certification grade and ceramic bearing sterilization cycle tolerance. Cost compression in mid-tier restorative configurations is intensifying because brushless motor commoditization erodes hardware-based tier separation. Solo practitioners in price-sensitive emerging markets exhibit highest price sensitivity, while German oral surgery centers show lowest elasticity due to reimbursement stability and precision requirements.
Supply Chain Analysis
Rare earth magnet processing concentration in China underwrites brushless motor cost structures across the industry. Neodymium-iron-boron magnet sourcing draws from Chinese processing capacity, Austrian precision manufacturing clusters, and Japanese ceramic bearing foundries. Single-source vulnerability in magnet supply exposes producers to export quota volatility. Distribution runs through direct manufacturer portals displacing traditional dental distributor networks in consolidated European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based predictive maintenance contracts represent a faster-expanding recurring-revenue layer than hardware sales, as embedded Hall-effect sensors enable motor health monitoring and calibration scheduling.
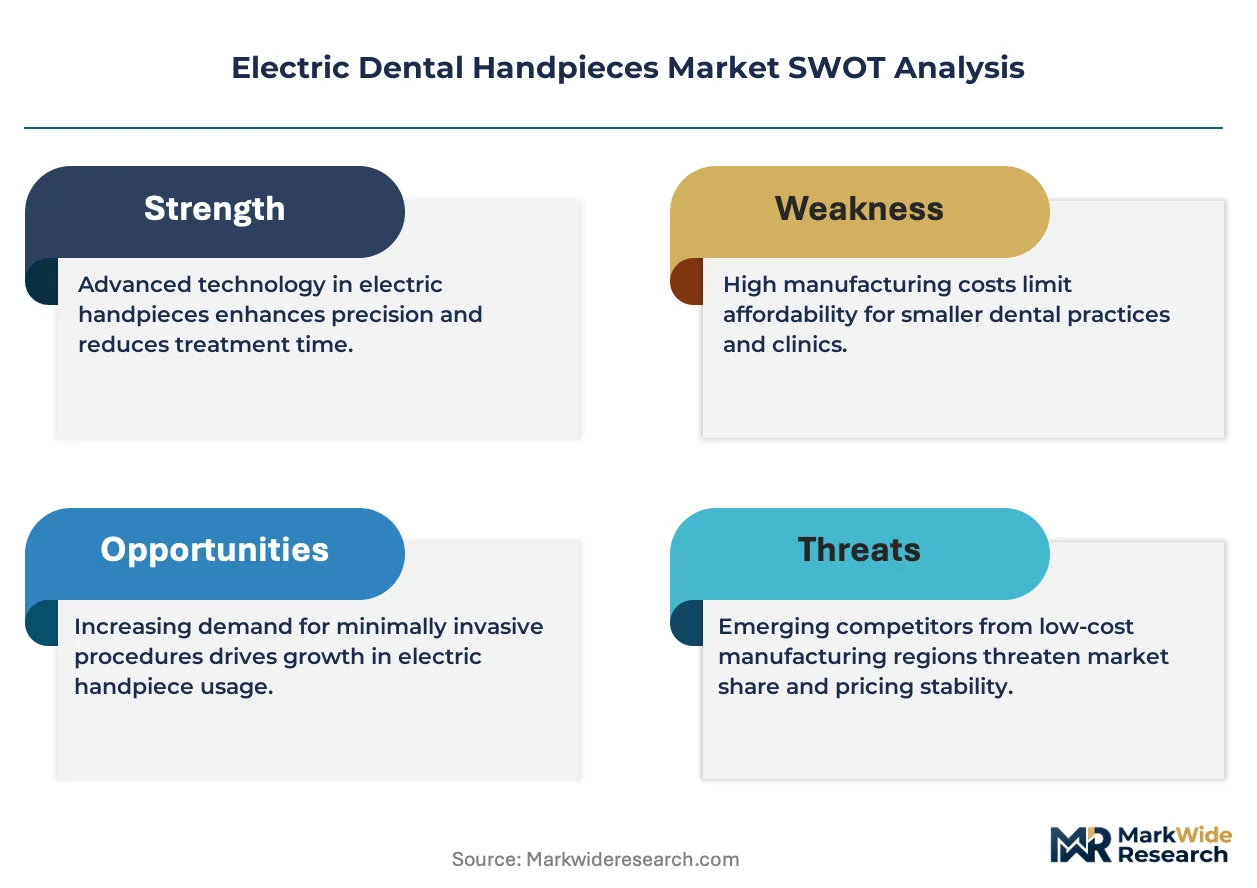
For Market Incumbents: Shield margin pools by deepening captive ceramic bearing supply through backward integration into sintered silicon nitride manufacturing, and accelerate software-integrated service contract penetration before firmware licensing commoditizes performance tier differentiation. The threat of programmable torque curve software eroding price elasticity demands preemptive bundling of predictive maintenance with hardware sales. For New Entrants and Emerging Players: Differentiate on localized maintenance networks targeting India's tier-2 and tier-3 dental clinic expansion, where CDSCO registration streamlining opens procurement pathways underserved by German and Japanese incumbents. The penetrable white-space sits in mid-tier restorative handpieces with convertible platform architectures. A direct-to-clinic digital portal strategy bypasses stranded distributor relationships in underpenetrated secondary cities. For Investors and Strategic Acquirers: EU MDR notified body capacity bottlenecks reshape the acquisition landscape by extending certificate renewal timelines and elevating regulatory compliance capabilities above manufacturing scale as valuation drivers. Long-term viability centers on platforms with active implant registries and real-world performance data infrastructure. The signal to watch is MDR certificate renewal delays forcing distressed divestitures of legacy motor platforms.| Strategic Initiative | Industry Significance |
|---|---|
| CAD/CAM Workflow Integration | Bundles handpiece hardware with Dentsply Sirona digital impression systems to lock in enterprise procurement. |
| Ceramic Bearing Backward Integration | Captures sintered silicon nitride supply to sustain 1,000+ autoclave cycle tolerance and margin control. |
| Predictive Maintenance Subscription | Converts Hall-effect sensor telemetry into recurring calibration and bearing replacement revenue streams. |
| Direct Portal Distribution | Bypasses dental distributor networks to capture enterprise pricing with Scandinavian and Dutch clinic chains. |
| EU MDR Certificate Renewal Investment | Maintains market access as German notified bodies demand real-world performance data for surgical tiers. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR technical documentation, ISO 14457 sterilization benchmarks, and dental equipment customs records. Interviews with oral surgeons, hospital purchasing committees, biomedical engineers, GPO contracts managers, and aftermarket service heads informed demand-side validation. Bottom-up installed base modeling triangulated against top-down manufacturer shipment data across brushless motor, micro motor, and legacy pneumatic technology segments.
Segmentation dimensions modeled include product type tier, end-user institutional category, motor technology architecture, and clinical application workflow. CAGRs derive from weighted average replacement cycle analysis and procurement elasticity parameters across the projection horizon. Forecast inputs incorporate EU MDR compliance-driven obsolescence curves and ceramic bearing adoption penetration rates by practice volume tier.
Material uncertainties — rare earth export quota volatility, notified body capacity constraints, and autoclave-compatible polymer degradation liability — sit outside the modeled envelope. Forecasts reflect assumptions about reimbursement stability and regulatory harmonization timing. Practitioners should keep alternative scenarios live as MDR implementation timelines and magnet supply chain restructuring evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
North America Dental Aligners Market
Dental Devices
North America Dental Lab Market
Dental Devices
Global Dental Burs Market
Dental Devices
Global Dental Endodontics Market
Dental Devices
Italy Dental Devices Market
Dental Devices
Dental Units Market
Dental Devices
Dental Veneers Market
Dental Devices
Periodontal Scalers and Curettes Market
Dental Devices
Europe Dental Lab Market
Dental Devices
Intraoral Dental Scanner Market
Dental Devices
Dental Forceps Market
Dental Devices
Dental Amalgamators Market
Dental Devices
Dental Needle Market
Dental Devices
Global Dental Restorative Market
Dental Devices
North America Dental Lasers Market
Dental Devices
Dental Prosthetics Market