
 Dental Apex Locator Market | 2026-2036
Dental Apex Locator Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Apex Locator Market Analysis
The dental apex locator category is recalibrating around a widening gap between premium digital systems with integrated Bluetooth connectivity and basic electromagnetic units sold on price. Dentsply Sirona leverages its integrated endodontic platform to bundle apex locators with rotary file systems, while Morita sustains its position through precision manufacturing heritage in Japanese dental electronics. Woodpecker Medical competes aggressively on cost-engineered digital units that target price-sensitive clinic chains across Asia-Pacific.
A dental apex locator is an electronic instrument that measures electrical impedance between a file inserted in the root canal and an oral electrode to determine working length within 0.5 mm accuracy; its primary purpose is to reduce radiographic exposure and improve endodontic treatment outcomes. Digital apex locators occupy the dominant revenue tier due to multi-frequency signal processing and LCD interfaces that command higher clinic budgets. Frequency-based technology represents the fastest-growing segment as manufacturers integrate adaptive algorithms that filter conductive interference from blood and irrigants. Wireless technology remains nascent but captures margin pools in premium installations where cable management and infection control priorities align.
The FDA regulates apex locators as Class II medical devices requiring 510(k) premarket notification, while the EU Medical Device Regulation imposes stricter clinical evidence standards through notified body conformity assessments. Japan's PMDA maintains rigorous electromagnetic compatibility testing that shapes product redesign cycles for manufacturers seeking Asian market access. Stakeholders must monitor how regulatory divergence between FDA streamlined pathways and EU MDR expanded requirements influences go-to-market sequencing and certification investment priorities.
Market Dynamics
Endodontic precision requirements are intensifying as dental clinics face mounting pressure to reduce patient radiation exposure while maintaining treatment accuracy, forcing equipment procurement decisions toward multi-frequency digital systems and away from legacy single-frequency units.
Growth Catalysts
- EU MDR clinical evidence mandates:Stricter conformity assessment standards under the Medical Device Regulation are accelerating replacement cycles for older apex locator models in German and French dental clinics.
- Multi-frequency impedance processing:Adaptive signal algorithms that filter conductive interference from blood and irrigants are electrifying demand among endodontic specialists seeking sub-millimeter working length accuracy.
- Asia-Pacific clinic chain expansion:Consolidated procurement by multi-location dental groups in India and China is creating volume pull for standardized electronic apex locator deployments.
Market Restraints
- Copper and semiconductor input volatility:Apex locator PCB manufacturing depends on refined copper pricing and microcontroller chip availability, exposing producers to electronics supply chain shocks.
- Japanese electromagnetic compatibility testing:PMDA certification requirements impose redesign cycles that extend product launch timelines by 8-14 months for manufacturers without established Tokyo laboratory partnerships.
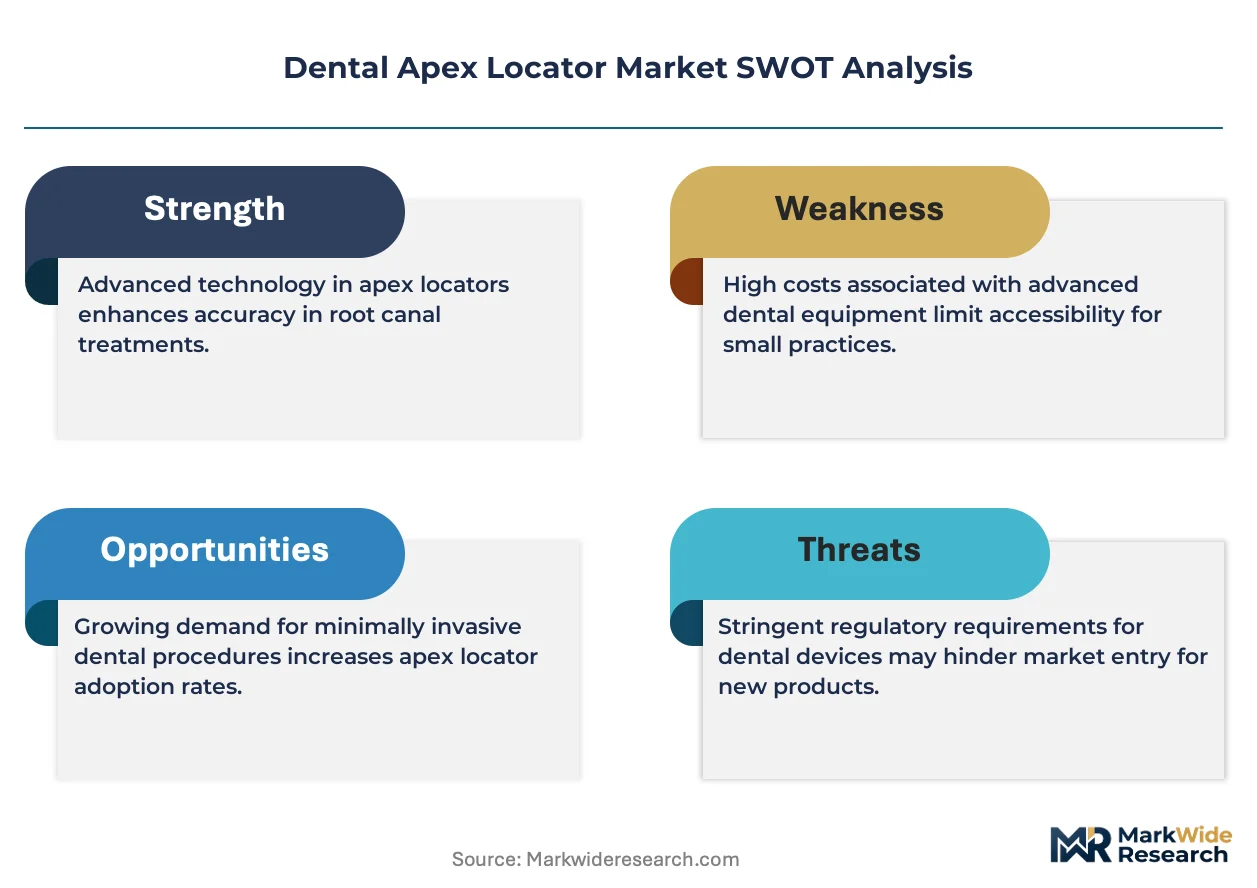
- Handheld radiography substitution:Portable digital X-ray units with reduced exposure profiles are competing for capital allocation in budget-constrained private practices.
Strategic Opportunities
- Brazilian endodontic specialty growth:ANVISA regulatory streamlining and expanding private dental insurance coverage are opening procurement channels in São Paulo and Rio de Janeiro clinic networks.
- Bluetooth-integrated workflow convergence:Wireless data transmission to practice management software is creating premium tier differentiation for manufacturers bundling apex locators with file tracking systems.
- India PLI scheme localization:Production-linked incentives for medical device manufacturing are enabling cost-engineered unit assembly for domestic consumption and Southeast Asian export.
Industry Challenges
- Endodontic technician calibration expertise:Proper apex locator maintenance requires specialized bioelectrical troubleshooting skills that general dental equipment service networks lack.
- 510(k) predicate device navigation:FDA clearance pathways demand substantial equivalence demonstrations that complicate novel algorithm introductions and extend regulatory investment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Apex Locator Market |
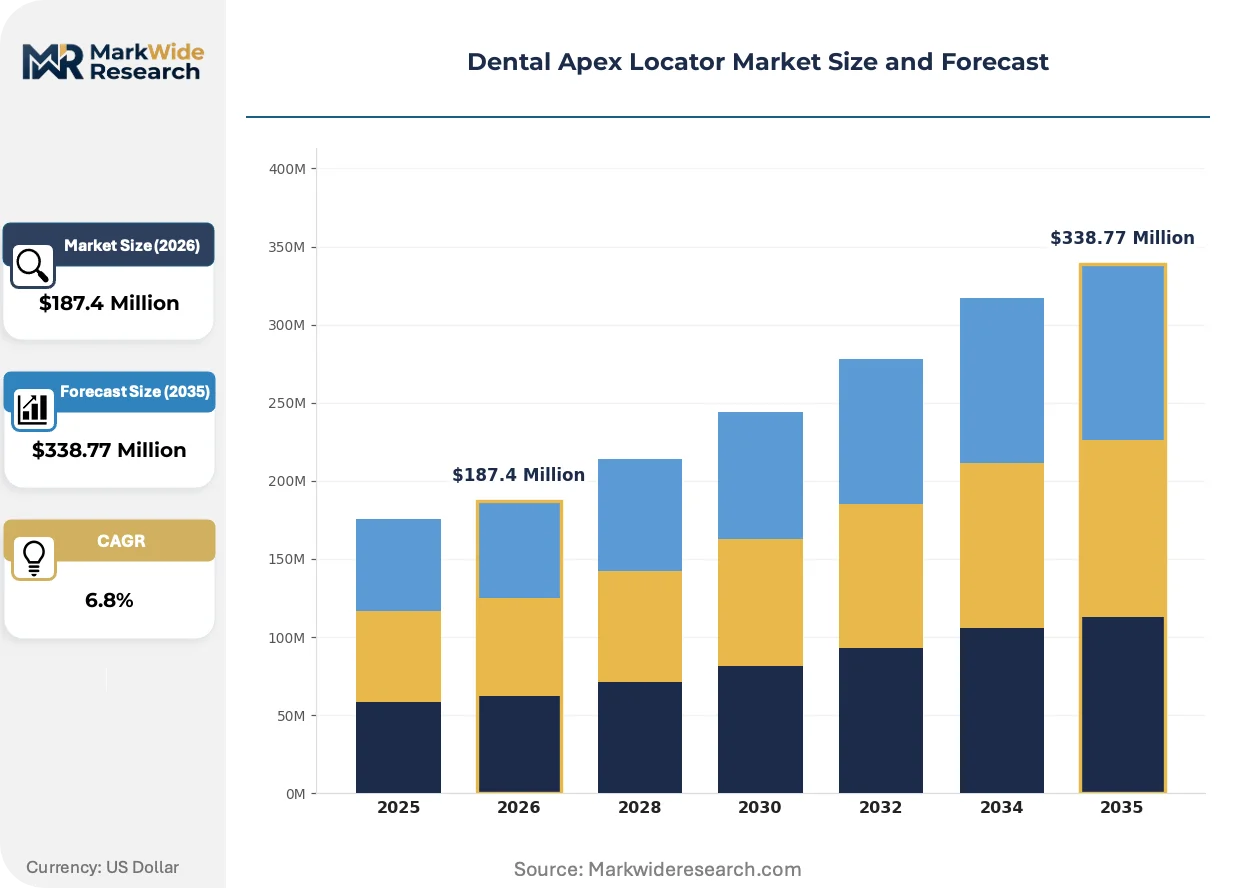
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Apex Locators, Digital Apex Locators, Electromagnetic Apex Locators, Measurement Techniques Technology: Bio-Compatibility Technology, Wireless Technology, Frequency-Based Technology, Advanced Algorithms End User: Dental Clinics, Hospitals, Dental Schools, Research Institutes Sales Channel: Online Retail, Direct Sales, Distributors, Others |
| Companies Covered | Dentsply Sirona, Morita, Kerr Dental, META BIOMED, NSK-Nakanishi International, Woodpecker Medical, Eighteeth, Micro-Mega, Cicada Dental, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Apex Locator Market Emerging Trajectories
Signal processing architectures and connectivity protocols are redefining competitive differentiation in dental apex locators, with manufacturers racing to integrate adaptive filtering and wireless interoperability before regulatory frameworks harden around established technical standards.
Multi-frequency apex locator technology is electrifying clinical workflow efficiency through simultaneous impedance measurement at multiple frequencies, enabling real-time compensation for conductive canal contents. Endodontic specialists in high-volume German and Japanese clinics are adopting these systems at replacement rates exceeding legacy single-frequency units by substantial margins. This capability compression is forcing price reductions on basic electromagnetic models while expanding margin pools for algorithm-intensive premium tiers.
EU MDR notified body conformity assessments are restructuring product development resource allocation toward clinical evidence generation and post-market surveillance systems. Manufacturers targeting European dental markets must now maintain technical documentation and vigilance reporting capabilities that exceed FDA 510(k) requirements. Digital apex locator categories with established predicate histories are adapting through supplementary clinical data collection, while novel wireless architectures face extended certification timelines.
After-sales service unbundling is fragmenting traditional equipment vendor relationships as dental clinic groups negotiate separate calibration and maintenance contracts with third-party biomedical service providers. Distributor margins on apex locator hardware are compressing as procurement teams at large United States and United Kingdom clinic chains centralize technical support purchasing. This disintermediation is most visible in corporate dental platforms operating 50-plus locations, where standardized equipment fleets create economies of scale in preventive maintenance scheduling.
Dental Apex Locator Market Segmentation
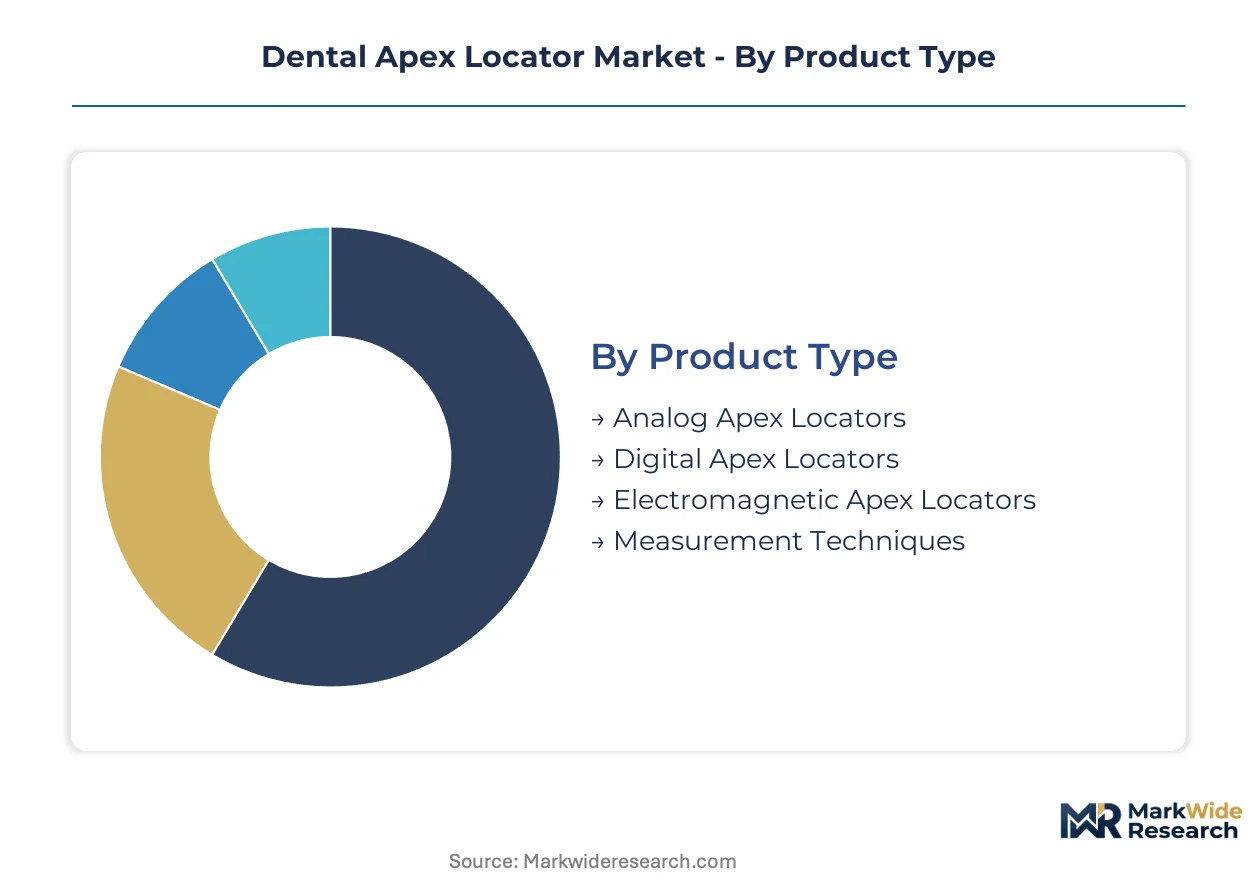
Dental apex locator procurement splits sharply between premium digital systems and cost-engineered analog units. End-use concentration in private dental clinics versus institutional buyers reshapes feature priorities across every segment category.
Product Type:
Volume concentration favors electromagnetic and basic digital units, while premium multi-frequency systems command margin pools in specialty endodontic practices.
- Digital Apex Locators:Multi-frequency impedance processing with LCD interfaces and adaptive filtering algorithms enables sub-millimeter working length accuracy. Demand concentrates in German and Japanese private endodontic clinics where precision requirements justify premium procurement budgets and regulatory compliance investments.
- Analog Apex Locators:Single-frequency electromagnetic measurement with needle-display readouts persists in price-sensitive installations. Volume deployment is accelerating in Indian and Chinese dental clinic chains where standardized equipment procurement prioritizes capital efficiency over algorithmic sophistication.
- Electromagnetic Apex Locators:Legacy single-frequency units with basic conductivity detection serve budget-constrained general dentistry practices in Southeast Asian markets.
- Measurement Techniques:Hybrid systems combining electronic apex location with tactile feedback mechanisms address training environments in Brazilian and Mexican dental schools.
Mature deployment sits with analog electromagnetic units. Newer deployment is concentrated in multi-frequency digital systems with integrated connectivity protocols.
Technology:
Algorithm sophistication and wireless capability now separate premium tier positioning from commodity hardware competition.
- Frequency-Based Technology:Simultaneous impedance measurement across multiple frequencies filters conductive interference from blood, irrigants, and pulp tissue in real time. German endodontic specialists are replacing legacy single-frequency units at accelerated rates as EU MDR clinical evidence requirements favor validated algorithm performance.
- Wireless Technology:Bluetooth-enabled data transmission to practice management software and file tracking systems eliminates cable clutter and supports infection control protocols. Premium installation demand is climbing the fastest in United Kingdom and United States corporate dental platforms operating standardized multi-location fleets.
- Bio-Compatibility Technology:Medical-grade housing materials and sterilization-resistant components meet FDA Class II and EU MDR biocompatibility testing standards for reusable instrument classification.
- Advanced Algorithms:Machine learning-enhanced signal processing adapts to canal morphology variations and apex constriction patterns in complex root canal anatomies.
Established regulatory clearance favors bio-compatible hardware designs. Steepest expansion trajectory belongs to wireless-enabled algorithmic systems.
End User:
Procurement authority and maintenance capability diverge sharply between independent private practices and institutional buyers with captive biomedical engineering support.
- Dental Clinics:Independent and corporate private practices generate the dominant equipment volume, with multi-location chains in India and China consolidating procurement around standardized digital apex locator fleets. These buyers prioritize cost-engineered units with third-party service contracts over manufacturer-integrated support.
- Hospitals:Academic medical center dental departments and outpatient surgery centers require FDA 510(k) cleared devices with established predicate histories for capital committee approval processes. Procurement cycles extend 12-18 months due to clinical engineering review and infection control committee validation.
- Dental Schools:Training institutions in São Paulo, Tokyo, and Mumbai balance durability requirements against student learning curve accommodations, favoring robust analog units for preclinical laboratories and digital systems for graduate endodontic programs.
- Research Institutes:University-based endodontic research centers in Zurich and Boston drive early adoption of experimental wireless architectures and novel signal processing algorithms ahead of commercial regulatory clearance.
Volume procurement authority rests with dental clinic chains. Technical validation requirements are most stringent in hospital settings.
Sales Channel:
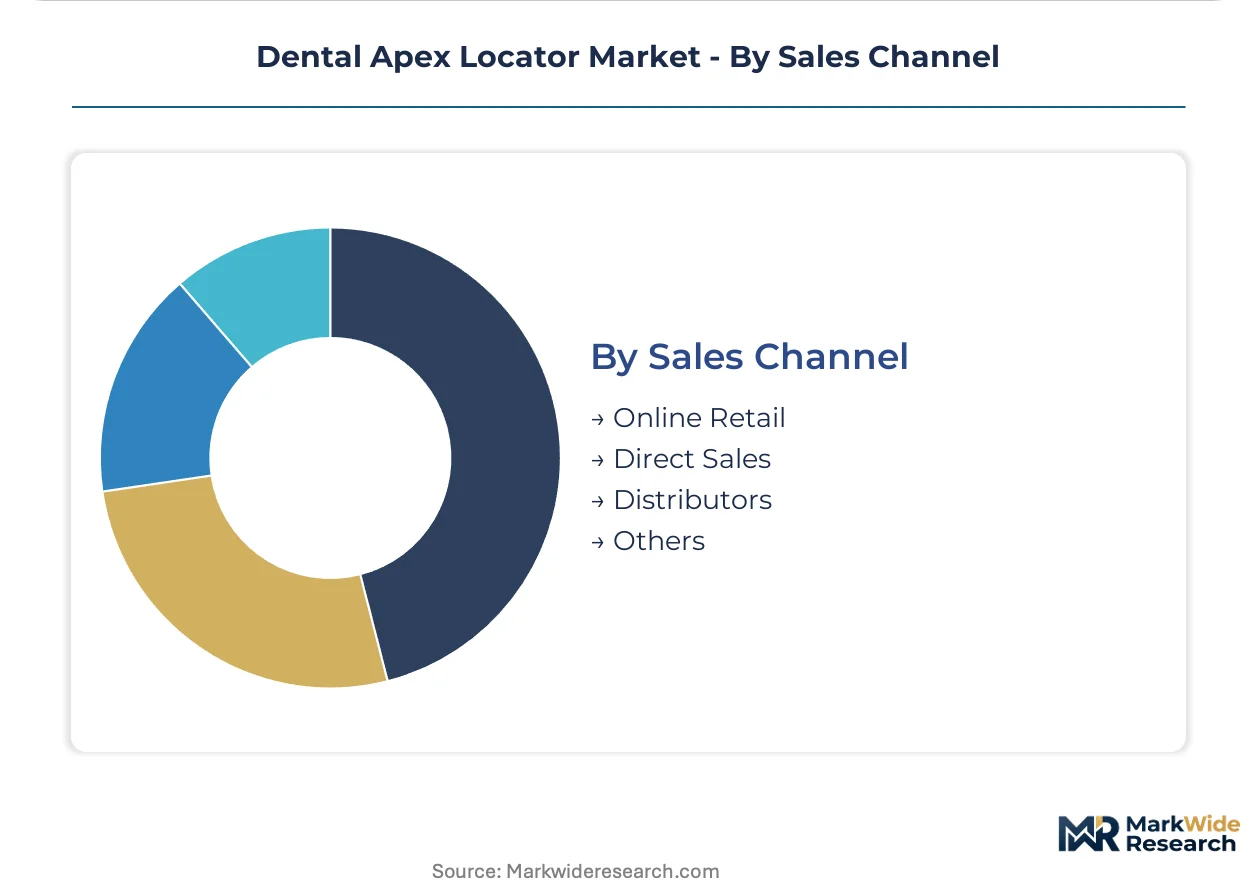
Channel structure reflects geographic market maturity and the prevalence of consolidated procurement versus fragmented independent purchasing.
- Distributors:Regional dental equipment distributors with calibration and maintenance capabilities dominate in Europe, Latin America, and Asia-Pacific markets where manufacturer direct presence remains limited. German and Brazilian distributors bundle apex locators with rotary file systems and obturation equipment.
- Direct Sales:Manufacturer field organizations serve large United States and United Kingdom corporate dental platforms with 50-plus location fleets, negotiating enterprise pricing and standardized preventive maintenance schedules.
- Online Retail:E-commerce penetration is expanding most quickly in Indian and Chinese markets where clinic chains and individual practitioners source cost-engineered digital units through specialized dental supply marketplaces with domestic warranty support.
- Others:Group purchasing organizations and dental association procurement cooperatives aggregate demand in fragmented markets including Italy, Spain, and South Korea.
Established channel control sits with regional distributors. Digital procurement migration is concentrated in Asia-Pacific clinic chain expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European dental technology manufacturing, housing precision electronics clusters that supply componentry for multi-frequency apex locator systems deployed across German endodontic practices.
Germany
Baden-Württemberg's dental equipment corridor drives demand for FDA-cleared and EU MDR-validated multi-frequency systems. The EU MDR notified body conformity assessment process accelerates replacement cycles in Frankfurt and Munich clinic networks. Bavarian endodontic specialists prioritize adaptive algorithm units with established clinical evidence packages.
United States
Corporate dental platforms in Texas and Florida consolidate procurement for standardized apex locator fleets across 50-plus location networks. The FDA's 510(k) premarket notification pathway shapes product entry timelines for manufacturers targeting the United States. Greater Boston's academic medical centers demand predicate-established devices for capital committee approvals.
Japan
Tokyo and Osaka dental clinics sustain replacement demand for precision-manufactured electronic apex locators. PMDA electromagnetic compatibility testing requirements extend product launch timelines for manufacturers without established Tokyo laboratory partnerships. Nagoya's dental electronics heritage supports component sourcing for domestic and export markets.
China
Shanghai and Beijing clinic chains drive volume procurement of cost-engineered digital units. The MIIT medical device registration framework and NMPA quality management system requirements shape domestic manufacturing standards. Shenzhen's electronics manufacturing base enables PCB assembly for regional supply.
India
Mumbai and Delhi-NCR dental clinic chains consolidate procurement around standardized equipment fleets. The PLI scheme for medical device manufacturing enables cost-engineered unit assembly for domestic consumption and Southeast Asian export. Karnataka's emerging medtech corridor attracts component localization investments.
Dental Apex Locator Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across tiered market positions. Integrated dental equipment conglomerates bundle apex locators with rotary file systems and obturation equipment, while specialized electronics manufacturers focus on precision signal processing components. Three archetypes dominate: full-platform integrators, precision component specialists, and cost-engineered volume producers. Competitive moves concentrate on regulatory clearance stacking across FDA, EU MDR, and PMDA jurisdictions, plus third-party service contract disintermediation.
Within the integrated-platform tier, Dentsply Sirona and Morita occupy positions defined by endodontic system bundling and precision manufacturing heritage respectively. Woodpecker Medical exemplifies the cost-engineered archetype targeting price-sensitive clinic chains. These three anchors illustrate how geographic origin and corporate structure map to divergent competitive vectors: US-based conglomerate integration, Japanese electronics precision, and Chinese volume manufacturing.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Morita |
| Kerr Dental |
| META BIOMED |
| NSK-Nakanishi International |
| Woodpecker Medical |
| Eighteeth |
| Micro-Mega |
| Cicada Dental |
| Others |
Supply Flow & Price Mechanics
Backward integration into precision signal processing componentry anchors supply positions for Japanese and German manufacturers while compressing margins for assemblers dependent on imported PCBs and microcontrollers. This captive production of impedance measurement modules enables premium-tier pricing power for multi-frequency systems targeting endodontic specialists in Stuttgart and Tokyo clinic networks.
Pricing Analysis
Outcome-based pricing tied to working length accuracy certification separates premium multi-frequency units from basic electromagnetic models. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance status, EU MDR conformity assessment completion, and Bluetooth connectivity integration. Price erosion runs through analog electromagnetic tiers as Indian and Chinese clinic chains consolidate procurement around standardized digital units. Corporate dental platforms with 50-plus locations exhibit lowest price sensitivity due to enterprise service bundling, while independent Southeast Asian general dentists drive cost-engineered volume.
Supply Chain Analysis
Regional distribution centers in Frankfurt, Singapore, and São Paulo maintain calibrated instrument inventories for same-day clinic fulfillment across European, Asia-Pacific, and Latin American markets. PCB assembly concentrates in Shenzhen, Nagoya, and Stuttgart, with refined copper sourcing from Chilean and Zambian mining operations. Semiconductor microcontroller availability from Taiwanese foundries presents single-source vulnerability for manufacturers lacking secondary qualification programs. Distribution runs through specialized dental equipment distributors with in-house biomedical calibration capabilities rather than general medical supply wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a vertical-integration race where control over impedance algorithm development and electromagnetic compatibility testing laboratories determines regulatory clearance velocity and margin retention.
For Market Incumbents: Deploy captive calibration service networks to lock in clinic chain renewals and offset hardware margin compression from Asian cost-engineered entrants. Dentsply Sirona and Morita should deepen backward integration into multi-frequency signal processing chip design to accelerate PMDA and FDA submission timelines. Consolidate distributor relationships in Brazil and India before ANVISA and CDSCO regulatory streamlining attracts new domestic competitors. For New Entrants and Emerging Players: CDSCO medical device registration simplification under India's PLI scheme opens a window for cost-engineered digital apex locator assembly targeting Southeast Asian export markets. White-space concentration sits with wireless-enabled units for United Kingdom corporate dental platforms seeking practice management software integration. Pursue direct online retail channels through specialized dental supply marketplaces in Shanghai and Mumbai rather than competing for distributor shelf space. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated dental equipment conglomerates seeking endodontic platform completeness. Five-to-ten year viability favors precision electronics specialists with established Tokyo laboratory partnerships and EU MDR technical documentation capabilities. Monitor FDA 510(k) predicate device accumulation rates as inflection signal for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Conformity Assessment Acceleration | Notified body pre-submission meetings in Berlin and Munich compress certification timelines for algorithm-validated systems. |
| Bluetooth-Integrated Workflow Development | Wireless data transmission to Dentsply Sirona and Kerr Dental file tracking systems creates premium tier lock-in. |
| Indian PLI Scheme Localization | Karnataka medtech corridor assembly reduces landed cost for Southeast Asian clinic chain procurement. |
| Third-Party Service Contract Disintermediation | Independent biomedical calibration providers fragment traditional distributor margins in United States and United Kingdom. |
| PMDA Electromagnetic Compatibility Pre-Certification | Tokyo laboratory partnerships extend product launch timelines but secure Japanese domestic market access. |
Methodological Framework
Independent corroboration across endodontic equipment distributors, biomedical calibration service technicians, and dental clinic procurement managers underwrites the qualitative findings in this study. Primary interviews with German and Japanese endodontic specialists, United States GPO contracts managers, and Chinese clinic chain operations directors combined with secondary validation from FDA 510(k) premarket notification databases, EU MDR notified body conformity assessment records, and PMDA electromagnetic compatibility test reports. Bottom-up unit shipment estimates from regional distributor channels triangulated against top-down equipment procurement budgets from corporate dental platforms.
Comparable-period anchoring to historical replacement cycle data from German and Japanese endodontic practices established the forecast baseline across the projection horizon. Segmentation modeling incorporated product type tiers, frequency-based versus wireless technology adoption curves, end-user procurement authority structures, and sales channel evolution patterns. CAGRs derived from fitted growth curves applied to validated installed base estimates and replacement rate assumptions. Multi-frequency impedance algorithm penetration rates and Bluetooth connectivity integration timelines served as primary demand-side forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for wireless-enabled apex locators with machine learning-enhanced signal processing would alter the outlook if regulatory frameworks harden around established technical standards before commercial clearance. Forecasts reflect documented assumptions regarding EU MDR clinical evidence requirements, copper and semiconductor supply stability, and handheld radiography substitution rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
3D Printing Dental Device Market
Dental Devices
Global Veterinary Dentistry Instruments and Equipment Market
Dental Devices
Netherlands Dental Devices Market
Dental Devices
Orthodontics Market
Dental Devices
Self-Ligating Bracket Sales Market
Dental Devices
United Kingdom Dental Devices Market
Dental Devices
Dental CAD Market
Dental Devices
Chile Dental Market
Dental Devices
Dental Veneers Market
Dental Devices
Gingivitis Treatment Market
Dental Devices
Intraoral Dental Scanner Market
Dental Devices
Digital Dental Cameras Market
Dental Devices
Dental Implant Motors Market
Dental Devices
Electric Dental Handpieces Market
Dental Devices
Europe Dental Implants and Prosthetics Market
Dental Devices
Dental Implants Market