
 Dental Curing Lights Market | 2026-2036
Dental Curing Lights Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Curing Lights Market Analysis
LED wavelength engineering is fragmenting the technology stack as manufacturers race to optimize 450-470 nanometer blue-light output for composite polymerization efficiency. Dentsply Sirona leverages its integrated CAD/CAM ecosystem to bundle curing lights with chairside workflows. Ivoclar Vivadent anchors its position through proprietary light-guide designs that sustain margin pools in premium segments. Kerr Corporation differentiates via ergonomic cordless platforms that compete on clinician fatigue reduction rather than irradiance specifications alone.
Dental curing lights are handheld devices that emit calibrated electromagnetic radiation, typically in the 400-500 nanometer range, to photoinitiate cross-linking in resin-based restorative materials; modern LED variants achieve 1,000-2,300 milliwatts per square centimeter while generating minimal infrared heat compared to legacy halogen sources. The LED product category leads in value terms due to superior energy efficiency and bulb longevity, while the rechargeable power-source segment captures the fastest growth as battery chemistry improvements eliminate cord dependency during multi-quadrant procedures. Digital technology integration, including built-in radiometers and curing-time algorithms, sits at the margin-rich intersection where dental clinics pay premiums for traceability and protocol compliance.
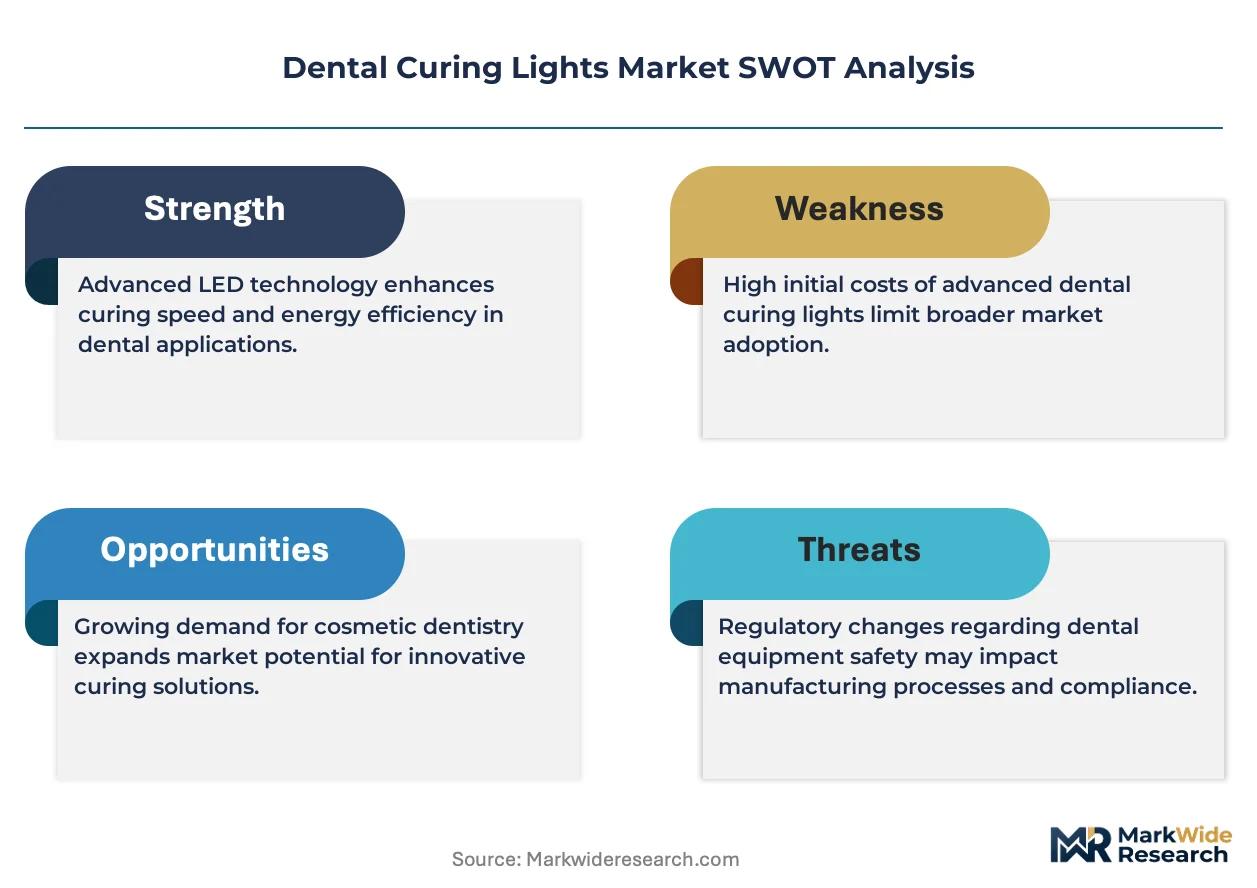
FDA 510(k) premarket notification governs device clearance in the United States, while the EU MDR requires updated technical documentation and clinical evaluation reports for CE marking renewal, tightening market access for smaller manufacturers. ISO 10650 standards define testing protocols for light output and beam uniformity, directly shaping R&D investment allocation across the competitive set. Stakeholders must monitor how Japan's PMDA aligns its dental device classification rules with emerging LED-UV hybrid technologies that blur traditional regulatory boundaries.
Market Dynamics
LED wavelength engineering is collapsing the performance gap between premium and mid-tier curing lights, forcing manufacturers to differentiate through ergonomic design and digital integration rather than irradiance specifications alone.
Growth Catalysts
- FDA 510(k) pathway streamlining:Expedited clearance for LED-based devices accelerates product cycles in the United States, allowing manufacturers to introduce iterative improvements faster than halogen-era timelines permitted.
- Cosmetic dental center expansion:Rising procedural volumes in aesthetic-focused practices across Germany and Japan drive unit placement growth as clinics upgrade to cordless rechargeable systems.
- ISO 10650 standardization:Unified testing protocols for light output and beam uniformity reduce R&D fragmentation, enabling smaller manufacturers to compete on validated performance metrics.
Market Restraints
- EU MDR clinical evidence requirements:Updated technical documentation and evaluation report mandates for CE marking renewal tighten market access, disproportionately burdening smaller manufacturers with limited regulatory resources.
- Battery chemistry concentration:Dependence on lithium-ion cell suppliers in East Asia creates input cost volatility and supply security exposure for cordless platform producers.
- Halogen inventory lock-in:Aging but functional installed bases in cost-sensitive dental clinics delay replacement cycles, compressing near-term addressable demand.
Strategic Opportunities
- Japan PMDA alignment on LED-UV hybrids:Regulatory clarity on emerging dual-wavelength technologies that blur traditional classification boundaries creates first-mover advantage for compliant entrants.
- Digital workflow integration:Convergence of curing lights with CAD/CAM chairside systems and built-in radiometers opens premium pricing in protocol-driven practices.
- Direct-to-clinic distribution:Bypassing traditional dental supply distributors through manufacturer e-commerce platforms captures margin and builds direct customer data assets.
Industry Challenges
- Photobiology expertise scarcity:Shortage of engineers capable of optimizing 450-470 nanometer output for polymerization efficiency without thermal damage limits R&D velocity.
- Legacy system integration friction:New LED platforms require workflow retraining and compatibility verification with existing composite material inventories, slowing adoption in established practices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Curing Lights Market |
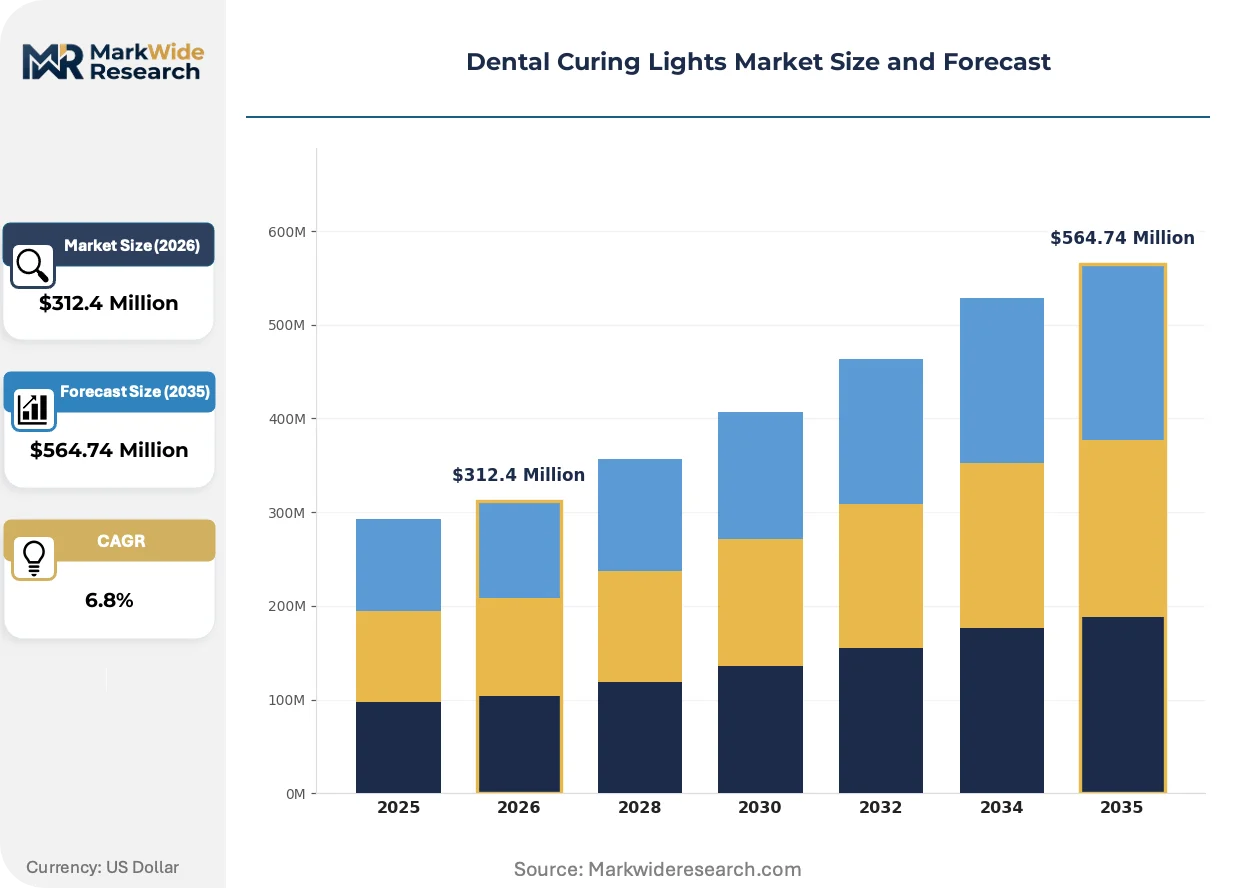
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Halogen, Plasma Arc, Laser Technology: Light Emitting Diode, Digital, Rechargeable, Infrared End User: Dental Clinics, Hospitals, Research Laboratories, Cosmetic Dental Centers Power Source: Battery Operated, Plug-in, Hybrid, Cordless |
| Companies Covered | 3M Company, Dentsply Sirona, Ivoclar Vivadent, Kerr Corporation, Ultradent Products, Henry Schein, GC Corporation, A-dec, VOCO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Curing Lights Market Emerging Trajectories
Active wavelength optimization and embedded diagnostics are transforming curing lights from passive tools into intelligent devices that enforce clinical protocols and capture procedure data.
Multi-peak LED engines is collapsing the distinction between single-wavelength and broad-spectrum curing systems. Dental clinics in Germany and Japan are adopting these platforms at replacement-cycle pace. The technology is collapsing the premium segment's irradiance-based pricing power by delivering equivalent polymerization depth across material brands.
EU MDR's clinical evaluation requirements are forcing manufacturers to generate real-world performance data rather than relying on bench testing equivalence. This industrial consequence extends development timelines by twelve to eighteen months for new entrants. The rechargeable LED segment is responding by consolidating technical files through notified body partnerships before market launch.
Outcome-based equipment procurement is replacing capital purchase models in multi-location dental groups. Equipment-as-a-service contracts with per-procedure fees are displacing upfront unit sales in United States dental service organizations. This shift is most visible in California and Texas where private equity-backed clinic rollouts prioritize predictable operating expenditures over balance-sheet asset ownership.
Dental Curing Lights Market Segmentation
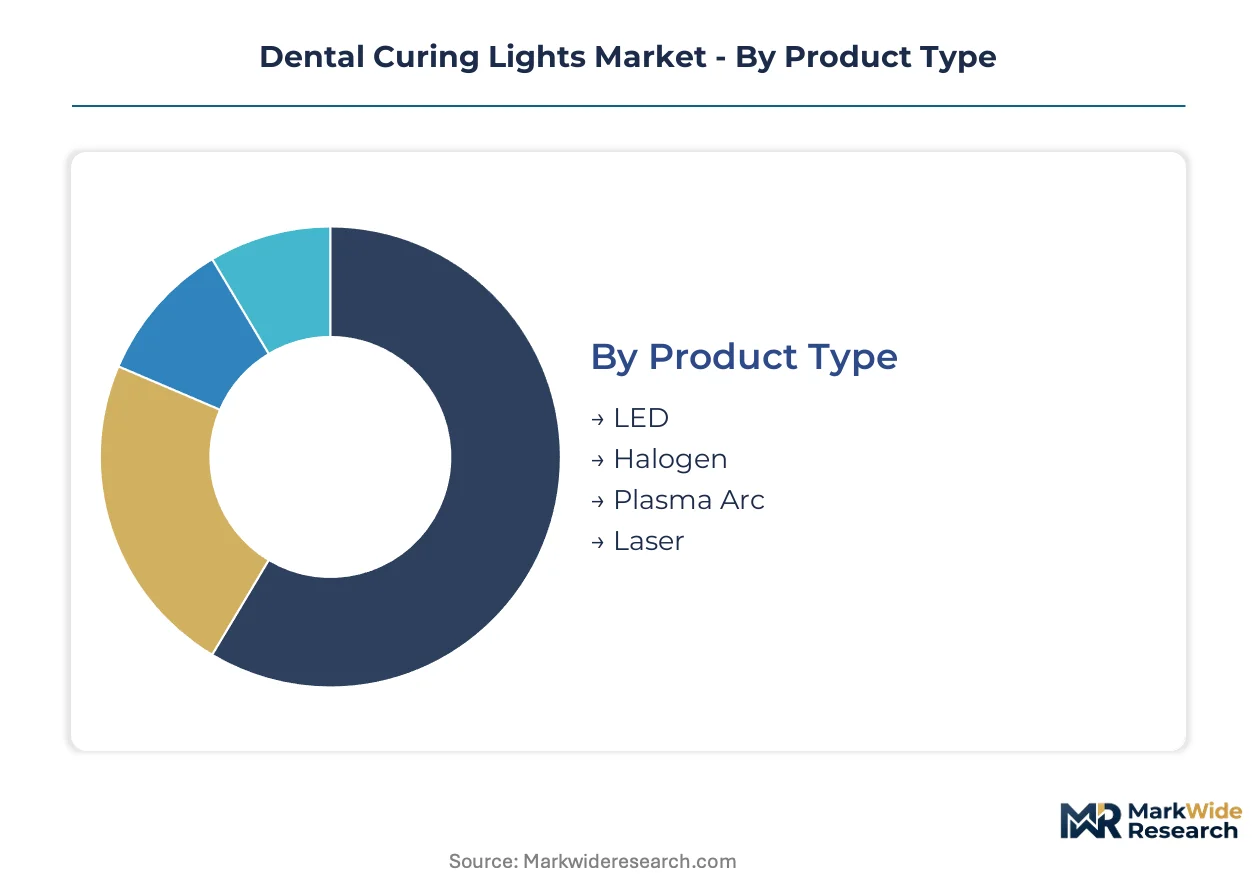
Segmentation in dental curing lights reveals distinct service intensity profiles across product architectures. LED platforms demand minimal recalibration but require periodic light-guide replacement, while rechargeable cordless systems create recurring battery service revenue streams that alter manufacturer-customer economics.
Product Type:
After-sales-service intensity varies sharply across light-source technologies, with bulb-based systems generating replacement-part revenue and solid-state platforms locking in lower lifetime maintenance.
- LED:Solid-state semiconductor arrays emitting 450-470 nanometer wavelengths achieve 1,000-2,300 milliwatts per square centimeter with 10,000+ hour operational lifespans. Demand concentrates in Germany and Japan where clinics prioritize energy efficiency and thermal safety during multi-quadrant procedures.
- Halogen:Tungsten-filament sources filtered for blue-light output require bulb replacement every 50-100 hours and generate substantial heat. Aging installed bases in cost-sensitive United States dental clinics delay replacement cycles despite inferior polymerization consistency.
- Plasma Arc:High-intensity discharge systems deliver rapid curing for bulk-fill composites through filtered xenon arc output.
- Laser:Semiconductor diode lasers operating at specific resin-absorption peaks enable targeted polymerization with minimal collateral thermal transfer.
By volume, LED leads. By growth pace, halogen replacement demand is ahead.
Technology:
Cost tier stratification separates premium digital-integrated platforms from basic analog alternatives, with rechargeable battery systems commanding mid-tier positioning.
- Light Emitting Diode:Gallium nitride chip architectures dominate wavelength engineering with 405-480 nanometer tunable output. United States cosmetic dental centers drive premium adoption for CAD/CAM workflow compatibility.
- Digital:Microprocessor-controlled units with embedded radiometers and curing algorithms enable protocol traceability. German university hospitals prioritize these platforms for research reproducibility and liability documentation.
- Rechargeable:Lithium-ion cell integration eliminates cord dependency during chairside mobility.
- Infrared:Thermal management systems using near-infrared feedback loops prevent pulpal temperature elevation.
By installed base, Light Emitting Diode dominates. By expansion trajectory, Digital is climbing the fastest.
End User:
Application context dictates performance requirements, with high-throughput cosmetic centers prioritizing speed and research laboratories demanding irradiance precision.
- Dental Clinics:General practice settings performing 15-25 restorative procedures daily require reliable mid-tier platforms with rapid autoclave compatibility. United States private practices drive volume through equipment-as-a-service procurement models.
- Cosmetic Dental Centers:Aesthetic-focused facilities performing veneer and bonding procedures demand premium cordless systems with consistent beam uniformity. Japan's metropolitan clinics lead regional adoption of multi-peak LED engines.
- Hospitals:Academic medical centers with dental residency programs require durable platforms for training environments.
- Research Laboratories:Materials science facilities studying photopolymerization kinetics need calibrated radiometric output.
By procedure volume, Dental Clinics lead. By equipment spend per operator, Cosmetic Dental Centers are gaining share fastest.
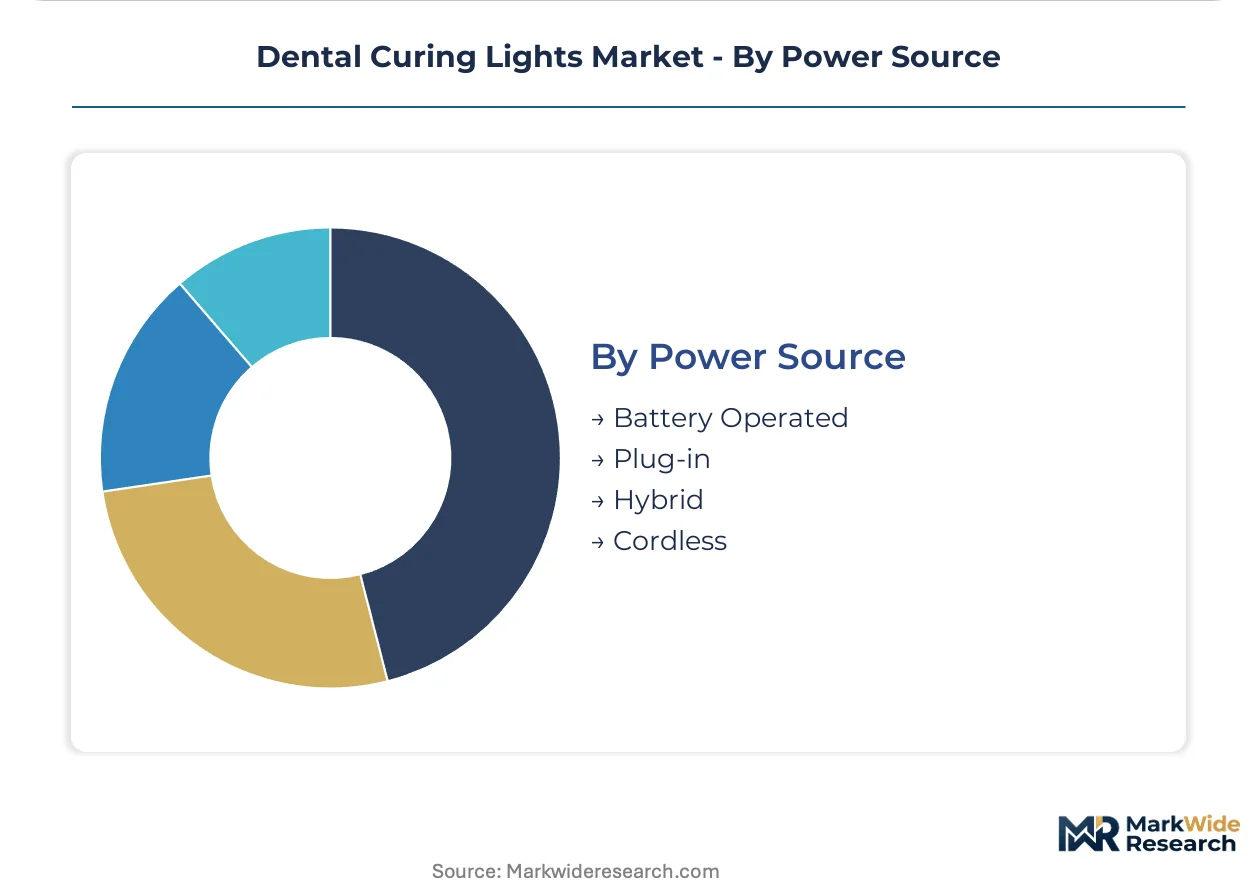
Power Source:
Customer type bifurcation separates mobile-dependent operators from fixed-station practices, with hybrid architectures bridging workflow flexibility needs.
- Cordless:Battery-integrated handheld units with docking stations enable unrestricted chairside positioning. Germany's multi-chair clinics prioritize these for ergonomic efficiency across operator rotations.
- Battery Operated:Removable cell systems allow field replacement during extended procedural days. United States dental service organizations favor standardization on specific battery formats for fleet maintenance economies.
- Plug-in:AC-powered units with transformer isolation deliver consistent output without charge-cycle management.
- Hybrid:Dual-mode systems switching between battery and line power accommodate varying clinical schedules.
By shipment volume, Cordless leads. By growth pace, Hybrid is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export LED curing light platforms to Japanese cosmetic dental centers, establishing the primary trade corridor in this medical device segment.
United States
Cosmetic dental centers in California and Texas drive cordless rechargeable system demand through equipment-as-a-service procurement models. FDA 510(k) premarket notification governs device clearance, streamlining iterative product introductions. Dallas-Fort Worth dental service organizations prioritize predictable operating expenditures over capital ownership.
Germany
Multi-chair clinics across Bavaria and North Rhine-Westphalia prioritize ergonomic cordless platforms for operator rotation efficiency. EU MDR clinical evidence requirements tighten CE marking renewal standards, extending development timelines. Munich's university hospitals anchor research reproducibility demand for microprocessor-controlled units with embedded radiometers.
Japan
Metropolitan cosmetic clinics in Tokyo and Osaka lead regional adoption of multi-peak LED engines for veneer procedures. PMDA alignment on LED-UV hybrid classification creates regulatory clarity for dual-wavelength entrants. Nagoya's dental equipment distributors consolidate technical files through notified body partnerships.
China
Domestic dental clinic chains in Shanghai and Guangzhou upgrade aging halogen inventories amid rising procedural volumes. NMPA medical device registration requirements shape local manufacturing compliance priorities. Shenzhen's electronics clusters supply lithium-ion cells for cordless platform producers serving Southeast Asian export markets.
South Korea
Seoul Capital Area aesthetic practices demand premium beam uniformity for bonding-intensive procedures. MFDS medical device classification rules influence regional product development specifications. Busan-Ulsan industrial zones manufacture LED semiconductor arrays for integration into mid-tier curing light platforms.
Dental Curing Lights Market Vendor Landscape
On the supply side, the industry is consolidating around integrated dental equipment conglomerates and specialized photopolymerization technology developers. Tiered competitive positioning separates premium digital-integrated platforms from mid-tier ergonomic specialists and economy bulb-replacement service providers. Strategic archetypes include CAD/CAM ecosystem bundlers, proprietary light-guide designers, and cordless mobility innovators. Dominant competitive moves encompass vertical integration into LED semiconductor sourcing and direct-to-clinic distribution channel development.
Among North American dental equipment conglomerates, 3M Company and Dentsply Sirona occupy positions as scale-driven ecosystem integrators. Kerr Corporation exemplifies the ergonomic specialization archetype through cordless platform development. Ivoclar Vivadent anchors the premium light-guide technology tier. These three entities represent distinct competitive vectors: ecosystem breadth, mobility engineering, and optical component proprietary control.
| Leading Market Players |
|---|
| 3M Company |
| Dentsply Sirona |
| Ivoclar Vivadent |
| Kerr Corporation |
| Ultradent Products |
| Henry Schein |
| GC Corporation |
| A-dec |
| VOCO |
| Others |
Supply Flow & Price Mechanics
Lithium-ion cell production clusters in Shenzhen and Busan-Ulsan concentrate upstream margin capture for cordless platform manufacturers, forcing downstream pricing discipline on OEMs while rewarding brands that backward integrate into battery management systems.
Pricing Analysis
Current-generation LED curing lights command premium positioning against halogen legacy tiers and emerging hybrid-architecture next-gen platforms. Three-tier pricing structure across premium, standard, and economy levels separates digital-integrated systems with embedded radiometers from basic cordless units and bulb-replacement service contracts. Price differentiation rests on ISO 10650 certification grade and after-sales service bundling rather than irradiance specifications alone. Pricing pressure stems from multi-peak LED engines collapsing performance gaps between mid-tier and premium segments. Dental service organizations exhibit highest price sensitivity through equipment-as-a-service procurement, while German university hospitals show lowest sensitivity prioritizing research reproducibility.
Supply Chain Analysis
Contract manufacturing capacity concentrates with Foxconn Health Technology and Jabil Healthcare serving tier-one dental equipment brands. Geographic supply concentration centers on China for lithium-ion cells and LED semiconductor arrays, South Korea for gallium nitride chip fabrication, and Germany for precision light-guide optics. Raw material dependencies include rare-earth phosphors for wavelength tuning, medical-grade aluminum for thermal management housings, and lithium cobalt oxide for rechargeable power systems. Single-source vulnerability in East Asian battery chemistry suppliers creates supply security exposure. Distribution runs through Henry Schein and Patterson Dental supply networks reaching United States private practices, with direct-to-clinic e-commerce emerging as secondary channel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dental curing lights are approaching a platform-economics inflection where CAD/CAM ecosystem interoperability determines vendor lock-in strength, shifting procurement criteria from standalone device performance to workflow integration depth.
For Market Incumbents: Insulate installed base relationships by deepening proprietary light-guide technology control and securing exclusive battery format standardization with dental service organization fleets. LED-UV hybrid regulatory uncertainty from Japan's PMDA poses substitution threat from adjacent photopolymerization technologies. Backward integration into gallium nitride semiconductor sourcing secures wavelength engineering autonomy against mid-tier competitors. For New Entrants and Emerging Players: Build out direct-to-clinic distribution infrastructure targeting United States dental service organizations in Texas and California where equipment-as-a-service procurement displaces traditional distributor relationships. Cosmetic dental centers in Japan's metropolitan markets represent most penetrable geography given multi-peak LED engine adoption velocity. Lead with ergonomic cordless platforms competing on clinician fatigue reduction rather than irradiance specifications. For Investors and Strategic Acquirers: Capital is best deployed toward photobiology engineering specialists with 450-470 nanometer optimization capabilities and regulatory filing expertise for FDA 510(k) and EU MDR pathways. Long-term viability across the analysis window favors platforms with embedded diagnostics and procedure data capture enabling outcome-based contracting. Watch for Japan PMDA classification clarity on LED-UV hybrids as signal for technology convergence inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Workflow Integration | Bundling curing lights with Dentsply Sirona CAD/CAM ecosystems captures chairside protocol lock-in. |
| EU MDR Technical File Consolidation | Notified body partnerships before market launch compress CE marking renewal timelines for rechargeable LED entrants. |
| Direct-to-Clinic Distribution | Manufacturer e-commerce platforms bypass Henry Schein margins and build proprietary customer data assets. |
| Photobiology R&D Investment | In-house 450-470 nanometer engineering teams overcome talent scarcity limiting polymerization efficiency optimization. |
| Outcome-Based Equipment Procurement | Per-procedure fee contracts align with United States dental service organization operating expenditure preferences. |
Methodological Framework
Operator-level perspectives from cosmetic dental center clinicians, biomedical engineers at German university hospitals, GPO contracts managers at United States dental service organizations, and regulatory affairs leads at LED curing light manufacturers anchored the qualitative base. Primary interview insights combined with secondary validation from FDA 510(k) premarket notification databases, EU MDR technical documentation filings, ISO 10650 testing protocol records, and hospital procurement database extracts. Bottom-up unit shipment estimates by product architecture and technology tier triangulated against top-down market value reconstruction.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions spanning light-source technology, power-source architecture, end-user facility type, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating procedural volume trajectories, replacement cycle dynamics, and technology substitution elasticities. Forecast inputs included lithium-ion battery cost decline curves, LED semiconductor efficiency improvement rates, and dental clinic capital expenditure survey data.
The forecast holds incumbent behavior within observed patterns; aggressive ecosystem bundling moves by CAD/CAM platform owners or rapid LED-UV hybrid regulatory clearance would shift outcomes beyond modeled ranges. Quarterly review of Japan PMDA classification guidance, EU MDR notified body backlog indicators, and United States dental service organization procurement contract announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Prophylaxis Pastes Market
Dental Devices
Dental Fittings Market
Dental Devices
Asia Pacific Dental Market
Dental Devices
Dental Regeneration Market
Dental Devices
Global Veterinary Dentistry Instruments and Equipment Market
Dental Devices
Dental Forceps Market
Dental Devices
Dental Needle Market
Dental Devices
Dental Whitening Lamps Market
Dental Devices
Toothbrush Sterilizer Market
Dental Devices
Dental Caries Market
Dental Devices
Dental Articulators Market
Dental Devices
Asia-Pacific Dental Lab Market
Dental Devices
Global Dental Lasers Market
Dental Devices
Surgical Dental Loupes and Camera Market
Dental Devices
Dental Diagnostic and Surgical Market
Dental Devices
Dental Inlays and Onlays Market