
 Dental Healing Caps Market | 2026-2036
Dental Healing Caps Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Healing Caps Market Outlook
Asset-light leasing models for dental CAD/CAM equipment are reshaping which practices can offer in-house custom healing caps, eroding the traditional distributor gatekeeper role. Straumann Group leverages its vertical integration from implant systems to final prosthetics to sustain margin capture across the workflow. Hiossen competes aggressively on price in the stock healing cap segment while building brand strength in emerging Asian markets. Zimmer Biomet anchors its position through hospital system contracts that bundle healing caps with broader orthopedic and dental portfolios.
A dental healing cap is a provisional component placed atop an endosseous implant during osseointegration, typically manufactured from titanium alloy, medical-grade zirconia, or high-performance polymers with precision tolerances of 10-20 micrometers to ensure soft-tissue contouring and biological seal formation. Custom healing caps milled from zirconia command premium positioning due to superior esthetics and biocompatibility in anterior applications, while stock titanium variants dominate volume in posterior placements where cost sensitivity prevails. The material dimension reveals titanium retaining structural leadership for its osseointegration track record, though zirconia posts the fastest growth trajectory as patient-driven esthetic demands intensify in private practice settings.
The FDA regulates dental healing caps as Class II medical devices under 510(k) premarket notification requirements, while the EU Medical Device Regulation imposes stricter clinical evidence standards through notified body conformity assessments that lengthen approval timelines for new entrants. ISO 13485 quality management certification functions as a de facto market access threshold for suppliers serving multinational dental corporations. Stakeholders must monitor how evolving biocompatibility testing protocols and sustainability mandates for medical polymers reshape material selection decisions across the value chain.
Market Dynamics
Asset-light leasing for dental CAD/CAM equipment is dismantling traditional distributor control over custom healing cap workflows, enabling mid-sized practices to bypass third-party milling centers and capture margin directly from chairside production.
Growth Catalysts
- Implant procedure volume:Rising edentulism rates among aging populations in Germany, Japan, and the United States are expanding the addressable patient base for osseointegration protocols requiring provisional components.
- FDA 510(k) pathway:The streamlined premarket notification process for titanium-based dental devices accelerates product entry timelines, reducing regulatory friction for manufacturers targeting the US private practice segment.
- Zirconia milling advances:Five-axis CAD/CAM systems with sub-10-micron precision tolerances now enable same-day custom healing cap production, compressing treatment cycles and improving soft-tissue esthetic outcomes.
Market Restraints
- Titanium powder cost volatility:Sponge titanium feedstock prices fluctuate with aerospace demand cycles, squeezing margin predictability for manufacturers dependent on Ti-6Al-4V alloy stock.
- EU MDR compliance burden:The Medical Device Regulation's stricter clinical evidence standards through notified body conformity assessments lengthen approval timelines and raise capital requirements for new entrants targeting European markets.
- Polymer substitution threat:High-performance PEEK materials with comparable biocompatibility profiles threaten to displace zirconia in posterior applications where esthetic demands are lower.
Strategic Opportunities
- India's dental infrastructure buildout:Government health spending expansion and private clinic chain formation in Mumbai, Delhi, and Bangalore create underpenetrated demand for stock titanium healing caps at volume price points.
- Chairside 3D printing convergence:Integration of photopolymerization and selective laser sintering technologies enables same-day custom component production without external milling laboratory dependency.
- Brazil's ANVISA regulatory alignment:Streamlined import pathways for ISO 13485-certified manufacturers reduce market access friction in Latin America's largest dental implant market.
Industry Challenges
- CAD/CAM technician scarcity:Shortages of operators proficient in dental design software and five-axis milling equipment constrain practice-level adoption of in-house custom production.
- Biocompatibility testing backlog:ISO 10993 cytotoxicity and sensitization protocol completion delays product launch schedules, particularly for novel zirconia formulations or surface-modified titanium alloys.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Healing Caps Market |
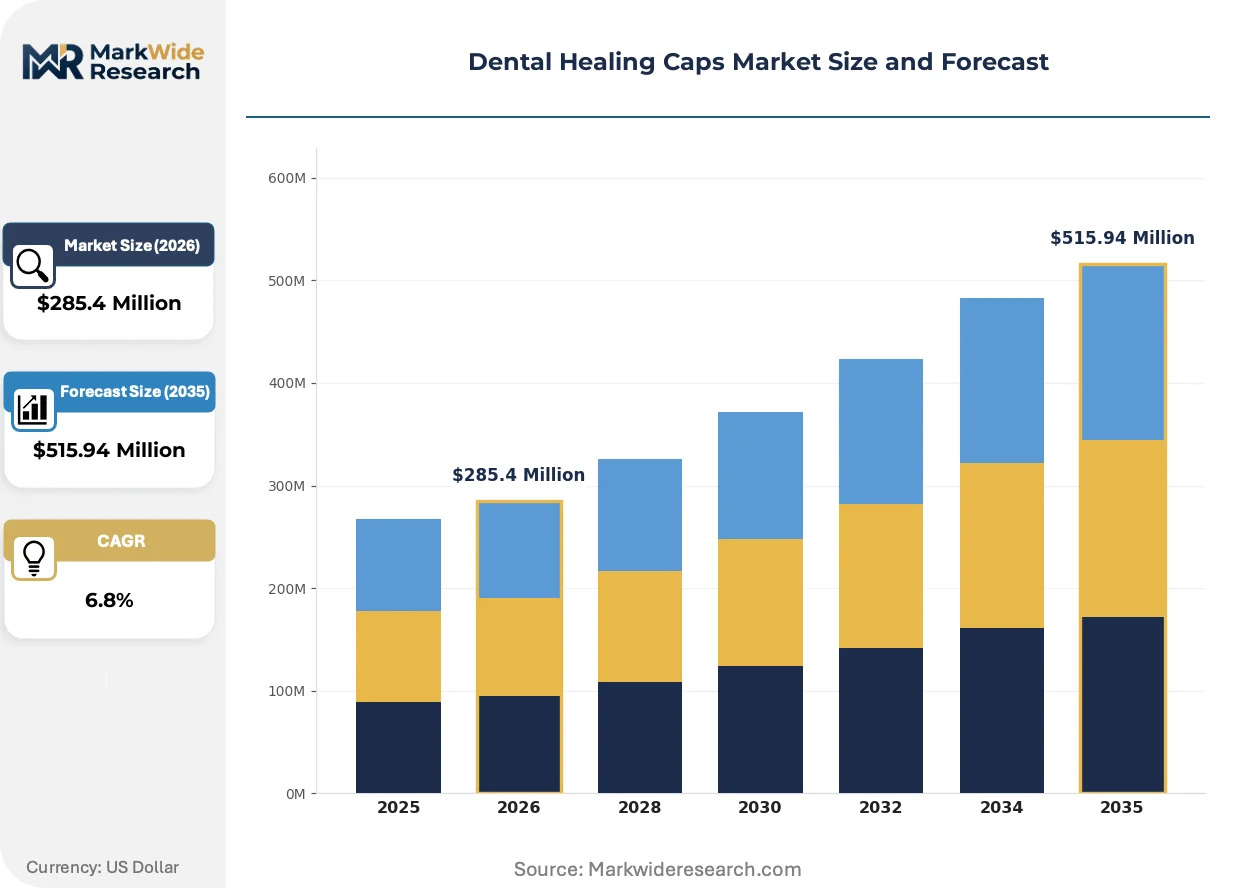
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Custom Healing Caps, Stock Healing Caps, Temporary Healing Caps, Abutment Caps Material: Plastic, Titanium, Zirconia, Composite End User: Dental Clinics, Hospitals, Research Laboratories, Private Practices Distribution Channel: Online Retail, Direct Sales, Dental Distributors, Medical Supply Stores |
| Companies Covered | Zimmer Biomet, Hiossen, Straumann Group, Osstem, MegaGen, Nobel Biocare, BioHorizons, Bego, Dentsply Sirona, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Healing Caps Market Strategic Shifts
Digital workflow integration is compressing the traditional healing cap supply chain from laboratory-dependent models to chairside production systems, reshaping competitive positioning around speed and customization rather than distributor relationships alone.
Intraoral scanning combined with chairside milling is digitizing the impression-to-component workflow, enabling private practices in the United States and Germany to produce patient-specific zirconia healing caps within single-visit protocols. Mid-sized dental groups with 5-15 locations are deploying this capability fastest, leveraging equipment leasing arrangements to avoid capital intensity. The technology is digitizing margin capture previously retained by external dental laboratories, forcing traditional milling centers to pivot toward complex multi-unit cases or risk volume erosion.
The EU Medical Device Regulation's clinical evidence requirements are tightening conformity assessment standards for custom-made device classifications, extending notified body review timelines for healing cap manufacturers seeking CE marking. This regulatory friction is concentrating market access among established suppliers with dedicated regulatory affairs functions and documented clinical histories. Smaller manufacturers are responding by partnering with authorized representatives or withdrawing from European markets to focus on FDA-regulated jurisdictions with lighter evidentiary burdens.
Direct-to-practice digital platforms are disintermediating traditional dental distributors by enabling manufacturers to sell healing caps through e-procurement portals with real-time inventory visibility and automated reorder algorithms. This channel shift is most visible in the United States, where dental service organizations with centralized purchasing functions negotiate system-wide contracts bypassing regional distributor networks. Independent practices in suburban and rural markets remain partially dependent on distributor field support, creating a bifurcated channel structure where scale determines procurement model selection.
Dental Healing Caps Market Segmentation
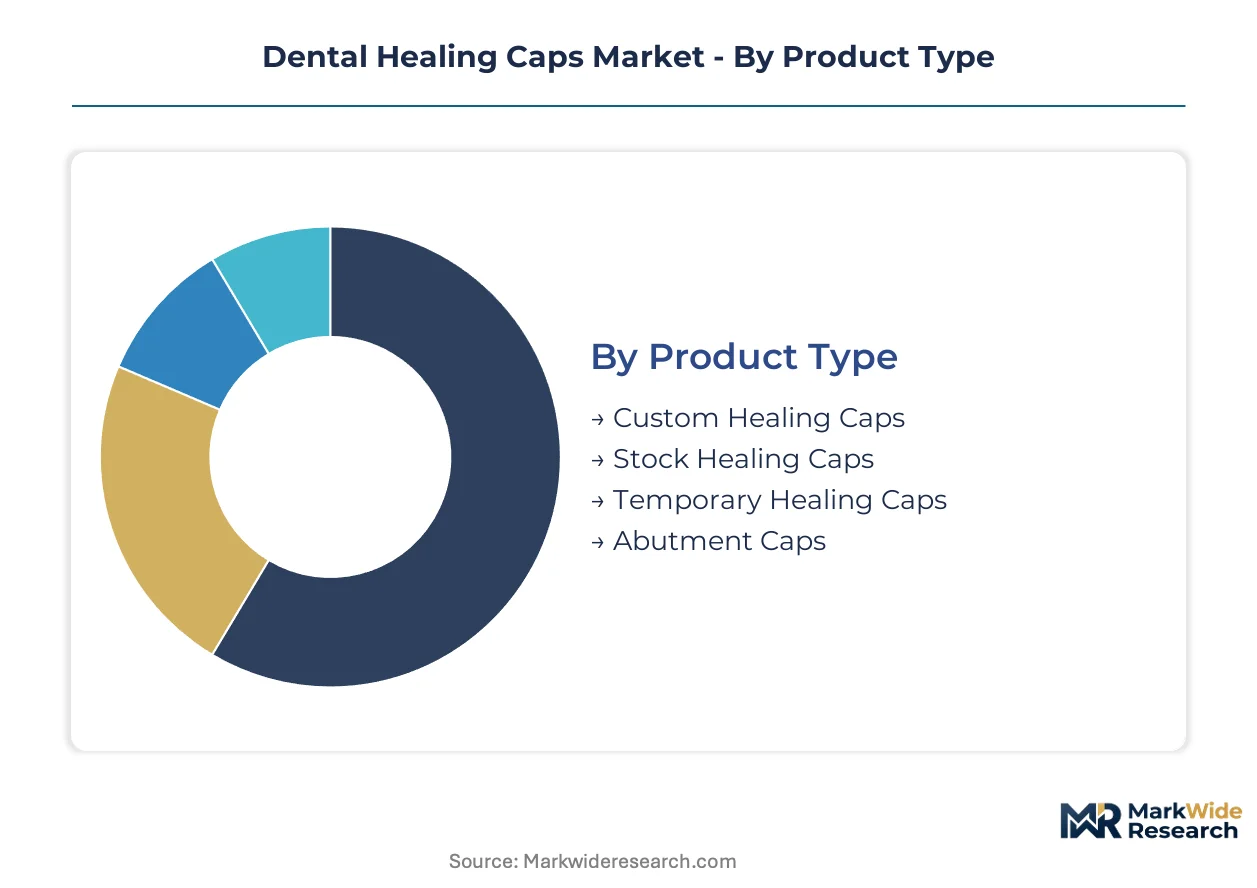
Dental healing caps fragment across four structural dimensions that determine margin capture, regulatory pathway complexity, and after-sales service intensity. Product type and material selection drive technical differentiation, while end-user concentration and channel configuration shape commercial execution requirements.
Product Type:
After-sales service intensity varies sharply across product types, with custom healing caps demanding chairside technical support and rapid remanufacturing turnaround that stock variants do not require.
- Custom Healing Caps:Patient-specific components milled from digital impressions to achieve sub-20-micron tissue interface precision. Demand concentrates in US private practices deploying chairside CAD/CAM systems, where same-day production eliminates external laboratory dependency and captures premium margin.
- Stock Healing Caps:Pre-manufactured standardized geometries in diameter-height combinations for immediate chairside selection. Volume concentrates in hospital dental departments and emerging market clinics where cost sensitivity prevails and procedure throughput prioritizes speed over customization.
- Temporary Healing Caps:Short-term provisional components designed for immediate post-implant placement before definitive restoration. These bridge osseointegration periods with simplified geometries that prioritize soft-tissue emergence profile over long-term durability.
- Abutment Caps:Interface components connecting implant fixtures to final prosthetic restorations, often dual-purposed as healing-phase provisionals. These serve hybrid workflows where single components span provisional and definitive treatment stages.
Stock healing caps hold the largest share; momentum sits with custom healing caps.
Material:
Cost tier stratification separates premium biocompatible ceramics from commodity metals and polymers, with material selection directly determining reimbursement eligibility and patient out-of-pocket exposure.
- Titanium:Ti-6Al-4V alloy dominates posterior applications with decades of osseointegration data and favorable mechanical properties. FDA 510(k) pathways for titanium devices accelerate manufacturer entry into US private practice channels where clinical familiarity reduces adoption friction.
- Zirconia:Yttria-stabilized tetragonal zirconia polycrystal commands anterior premium positioning for superior esthetics and soft-tissue response. German and Japanese private practices drive fastest adoption where patient-driven esthetic demands justify higher material costs.
- Plastic:Provisional polymers including PMMA and PEEK serve short-term healing phases where mechanical demands are minimal. These materials enable low-cost experimentation with emergence profiles before definitive zirconia or titanium component placement.
- Composite:Reinforced resin formulations offer intermediate esthetics and cost positioning for mid-market practices balancing patient expectations against material budgets. These materials face durability limitations in extended healing protocols exceeding twelve weeks.
Titanium holds the largest share; steepest expansion trajectory belongs to zirconia.
End User:
Customer type determines procurement sophistication, with dental service organizations negotiating system-wide contracts that independent practices cannot replicate.
- Dental Clinics:Multi-chair facilities with centralized purchasing functions and established CAD/CAM infrastructure. These settings favor custom healing cap workflows where volume justifies equipment investment and technical staff specialization.
- Hospitals:Academic medical centers and community hospital dental departments with orthopedic and dental bundled procurement. Zimmer Biomet anchors position through system contracts that extend healing cap supply across broader implant portfolios.
- Research Laboratories:University and corporate R&D settings evaluating novel surface modifications and biocompatibility profiles. These users drive early validation of next-generation materials before commercial scale-up.
- Private Practices:Solo and small-group practitioners with heterogeneous technology adoption and distributor-dependent supply chains. Straumann and Hiossen compete for loyalty through differentiated premium versus value positioning.
Dental clinics hold the largest share; momentum sits with private practices deploying chairside production.
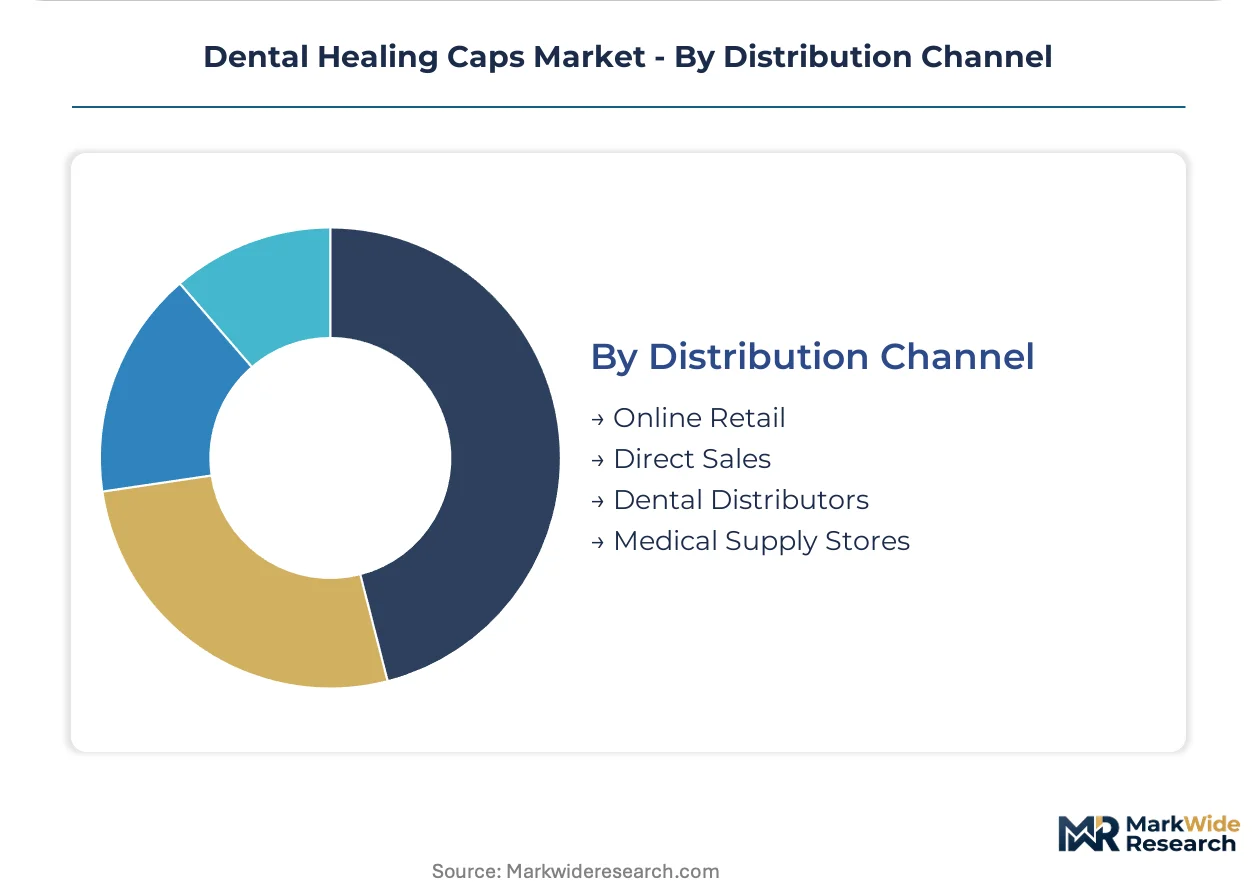
Distribution Channel:
Supply concentration in distributor networks is fragmenting as direct digital platforms capture dental service organization procurement.
- Dental Distributors:Traditional field-sales organizations with inventory warehousing and chairside technical support. Henry Schein and Patterson dominate US independent practice supply with established credit terms and same-day delivery logistics.
- Direct Sales:Manufacturer-to-practice relationships bypassing distributor margin capture. Straumann leverages vertical integration from implant systems to healing caps to sustain direct channel economics.
- Online Retail:E-procurement portals with real-time inventory visibility and automated reorder algorithms. Dental service organizations with centralized purchasing deploy these platforms to standardize supply across multi-location footprints.
- Medical Supply Stores:General healthcare distributors serving rural and underserved markets with limited dental-specialized inventory. These channels stock predominantly titanium stock healing caps with minimal custom capability.
Dental distributors hold the largest share; fastest share gains belong to direct sales platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics favor established manufacturing bases with titanium alloy supply chains and precision milling infrastructure. Germany and the United States run structural surpluses in custom healing cap components, while emerging markets import stock titanium variants to bridge domestic production gaps.
United States
Private dental practices in Texas and Florida drive demand for chairside-milled zirconia healing caps as patient esthetic expectations intensify. FDA 510(k) premarket notification pathways accelerate product entry timelines for titanium-based devices targeting the domestic private practice segment. The Dallas-Fort Worth metroplex anchors distributor consolidation as Henry Schein and Patterson optimize same-day delivery logistics for independent practitioners.
Germany
Aging demographics in Bavaria and North Rhine-Westphalia expand implant procedure volumes requiring provisional components with sub-20-micron precision tolerances. EU Medical Device Regulation notified body conformity assessments impose stricter clinical evidence standards that lengthen approval timelines for new market entrants. The Stuttgart industrial corridor concentrates five-axis CAD/CAM equipment manufacturing, enabling dental laboratories to supply custom healing caps across Central European markets.
Japan
Metropolitan Tokyo and Osaka dental clinics prioritize zirconia healing caps for anterior applications where soft-tissue response and esthetic outcomes command premium positioning. PMDA regulatory frameworks align with ISO 13485 quality management certification requirements that function as de facto market access thresholds. The Nagoya manufacturing belt supplies precision-milled titanium components to domestic implant manufacturers with vertical integration into final prosthetic workflows.
India
Government health spending expansion and private clinic chain formation in Mumbai and Delhi generate underpenetrated demand for stock titanium healing caps at volume price points. CDSCO import regulations for medical devices require local authorized representative partnerships that extend market access timelines for foreign manufacturers. Bangalore's medical device startup ecosystem incubates domestic milling capabilities targeting mid-tier dental practices with cost-sensitive procurement profiles.
Brazil
São Paulo and Rio de Janeiro dental service organizations negotiate centralized contracts for healing cap supply across multi-location footprints. ANVISA regulatory alignment with ISO 13485 certification standards streamlines import pathways for multinational manufacturers targeting Latin America's largest implant market. The Campinas industrial cluster hosts contract manufacturers producing titanium stock components for regional distribution through dental distributor networks.
Dental Healing Caps Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with narrower scope but deeper technical focus. Market structure concentrates around implant system manufacturers with captive healing cap portfolios, while independent suppliers compete on material specialization and price positioning in stock variants. Three archetypes dominate: vertically integrated implant-to-prosthetic platforms, precision milling specialists, and value-positioned stock component fabricators. Competitive moves center on CAD/CAM equipment leasing partnerships and direct-to-practice digital procurement platforms that disintermediate traditional distributor relationships.
Among vertically integrated platforms, Straumann Group, Zimmer Biomet, and Hiossen occupy positions spanning implant fixtures through final restorative components. Straumann exemplifies the premium-tier archetype with system-level workflow control, while Zimmer Biomet anchors hospital system contracting through bundled orthopedic and dental portfolios. Hiossen represents aggressive price positioning in volume segments alongside brand development in emerging Asian markets. These three companies illustrate how scale and integration depth determine margin capture across the provisional-to-definitive treatment continuum.
| Leading Market Players |
|---|
| Zimmer Biomet |
| Hiossen |
| Straumann Group |
| Osstem |
| MegaGen |
| Nobel Biocare |
| BioHorizons |
| Bego |
| Dentsply Sirona |
| Others |
Value Chain & Pricing Dynamics
Titanium powder cost volatility from aerospace demand cycles determines both pricing tier spreads and supply chain shape in dental healing caps. Manufacturers dependent on Ti-6Al-4V alloy stock face margin unpredictability that compresses standard-tier pricing while premium zirconia variants capture wider spreads through material substitution.
Pricing Analysis
Private dental practices anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation stems from certification grade—FDA 510(k) versus EU MDR pathways—and customization level from stock geometries to patient-specific milled components. Cost compression in the standard titanium tier is intensifying because aerospace sponge titanium feedstock prices fluctuate with defense procurement cycles. Hospital dental departments exhibit highest price sensitivity through bundled orthopedic contracts, while US private practices show lowest sensitivity for chairside zirconia production.
Supply Chain Analysis
Extended payment terms from dental distributors to mid-sized practices now stretch 60-90 days, constraining manufacturer working capital. Geographic supply concentration centers on Germany, the United States, and Japan for precision five-axis milling equipment and titanium alloy feedstock. Raw material dependencies include yttria-stabilized zirconia powder, Ti-6Al-4V alloy bar stock, and high-performance PEEK polymer resin. Single-source vulnerability runs through aerospace-linked titanium sponge suppliers. Distribution runs through Henry Schein and Patterson field-sales networks for independent practices, with direct digital platforms capturing dental service organization procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PEEK polymer substitution threatens zirconia positioning in posterior applications where esthetic demands relax, forcing incumbents to defend material-tier differentiation through clinical evidence investment.
For Market Incumbents: Pre-empt PEEK displacement by commissioning ISO 10993 biocompatibility studies that document soft-tissue response differentials against polymer alternatives. Capture margin through backward integration into chairside CAD/CAM equipment leasing, locking practices into captive consumable supply. The priority defensive lever rests on regulatory dossier depth that new entrants cannot replicate within EU MDR timelines. For New Entrants and Emerging Players: Mid-tier dental clinics in India's Mumbai-Delhi corridor represent the most penetrable entry point for stock titanium healing caps at volume price points below Straumann and Zimmer Biomet positioning. Brazil's ANVISA-aligned import pathways offer secondary white-space access with reduced conformity assessment friction. A direct-to-practice digital procurement platform bypasses distributor margin capture and aligns with dental service organization centralized purchasing trends. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision milling specialists with ISO 13485 certification and documented FDA 510(k) histories. Acquisition targets should demonstrate chairside CAD/CAM workflow integration capabilities or established hospital system contracts. The signal to watch is CDSCO regulatory alignment progress in India, which would unlock volume-scale manufacturing investment rationale.| Strategic Initiative | Industry Significance |
|---|---|
| Chairside CAD/CAM Equipment Leasing | Asset-light models enable mid-sized practices to bypass external milling laboratories and capture margin directly. |
| EU MDR Conformity Assessment Investment | Notified body relationships and clinical evidence dossiers create regulatory moats against faster FDA pathways. |
| Direct-to-Practice Digital Platform Launch | E-procurement portals with automated reorder algorithms disintermediate Henry Schein and Patterson field-sales networks. |
| PEEK Biocompatibility Testing Program | ISO 10993 cytotoxicity validation enables posterior-segment positioning where titanium cost pressure intensifies. |
| India CDSCO Authorized Representative Partnership | Local regulatory liaison relationships compress import pathway timelines for Mumbai and Delhi clinic chain supply. |
Study Parameters
Desk research of FDA 510(k) premarket notification databases, EU MDR notified body conformity assessment records, and ISO 13485 certification registries preceded structured interviews with dental implant system product managers, CAD/CAM equipment leasing executives, hospital dental department procurement leads, and dental laboratory milling technicians. Secondary validation drew from customs trade data for titanium alloy and zirconia powder shipments, SEC filings of publicly traded dental device manufacturers, and dental distributor inventory turnover disclosures. Bottom-up procedure volume estimates triangulated against top-down implant manufacturer revenue segmentation.
Forecasts assume stable FDA 510(k) pathway timelines, continued EU MDR notified body capacity constraints, and titanium sponge price correlation with aerospace demand cycles across the analysis window. Segmentation dimensions modeled include product type hierarchy, material tier stratification, end-user procurement sophistication, and distribution channel configuration. CAGRs derived from implant procedure volume elasticity to aging demographic penetration and chairside production adoption curves. Industry-specific inputs incorporated five-axis milling equipment deployment rates and dental service organization consolidation trajectories.
Macroeconomic conditions sit as an overlay; deviation in aerospace defense procurement cycles or titanium sponge spot pricing would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway stability and biocompatibility testing protocol evolution. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Global Endodontics Market
Dental Devices
Dental Composite Filling Market
Dental Devices
Turkey CAD/CAM Dental Devices Market
Dental Devices
US Orthodontics Market
Dental Devices
Sleep Apnea Oral Appliances Market
Dental Devices
Dental Inlays and Onlays Market
Dental Devices
Dental CAD/CAM Market
Dental Devices
Orthodontic Wax Market
Dental Devices
Dental Diagnostic and Surgical Market
Dental Devices
Acrylic Teeth Market
Dental Devices
Asia Pacific Acrylic Teeth Market
Dental Devices
Endodontics and Orthodontics Market
Dental Devices
Global Digital Dentistry Market
Dental Devices
Global Dental Restorative Market
Dental Devices
Americas Acrylic Teeth Market
Dental Devices
Dental Amalgamators Market