
 US Orthodontics Market | 2026-2036
US Orthodontics Market Size, Share, and Industry Trends Forecast 2026-2036
US Orthodontics Market Intelligence
Multi-source procurement among orthodontic practices is shifting toward consolidated distributor relationships with select manufacturer-direct programs. Align Technology Inc. dominates clear aligner fabrication through its proprietary thermoplastic forming process and integrated digital scanning ecosystem. Henry Schein leverages its dental distribution infrastructure to control supply chain access for private practices nationwide. Ormco Corporation specializes in conventional bracket systems and sustains R&D intensity in self-ligating archwire technologies.
Orthodontics encompasses the diagnosis, prevention, and correction of misaligned teeth and jaws using fixed appliances, removable devices, and adjunctive components typically fabricated from stainless steel, nickel-titanium alloys, or medical-grade polymers. The discipline serves both functional restoration of masticatory efficiency and aesthetic improvement of dental arches. Clear aligners now capture the fastest-expanding margin pool within product type segmentation as patient preference shifts toward removable, near-invisible treatment modalities. Archwires and brackets retain volume leadership in adolescent cases where complex malocclusion correction demands precise mechanical control. End-user concentration favors orthodontic clinics over general dental practices for comprehensive case management requiring specialized cephalometric analysis and treatment planning.
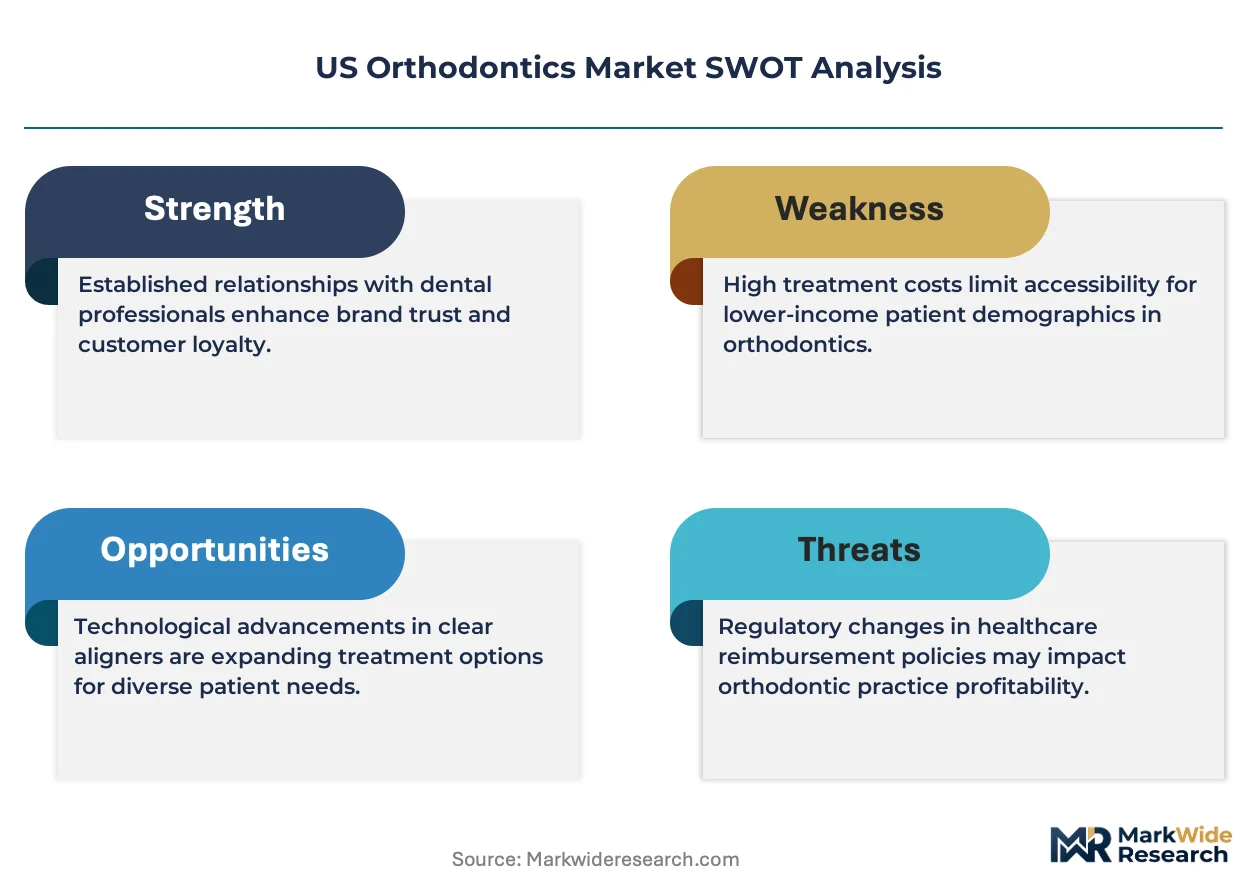
FDA 510(k) premarket notification requirements govern orthodontic device commercialization and shape product development timelines for manufacturers seeking US market entry. State dental boards in California, Texas, and New York enforce continuing education mandates for orthodontic specialists that indirectly steer adoption toward digitally integrated treatment systems. OSHA bloodborne pathogen standards and state-level infection control protocols impose material sterilization and office design requirements that filter equipment purchasing decisions. Stakeholders must monitor evolving teledentistry reimbursement policies and state scope-of-practice expansions that could redistribute case volume between specialist clinics and generalist providers.
Market Dynamics
Teen and young adult demand for aesthetic alternatives to metal braces is compressing traditional bracket volumes while accelerating clear aligner fabrication capacity expansion across US manufacturing networks.
Growth Catalysts
- California specialist density:Dense orthodontic specialist networks in Los Angeles and San Francisco metro corridors generate referral volume that sustains premium clear aligner uptake and digital scanner deployment.
- FDA 510(k) pathway acceleration:Streamlined premarket notification requirements for novel thermoplastic forming devices compress commercialization timelines from 18 months to under 8 months for qualified submissions.
- Nickel-titanium archwire alloys:Superelastic wire formulations enable longer adjustment intervals and reduce chair time, driving adoption among private practices seeking operational efficiency.
Market Restraints
- Aligner fabrication concentration:Proprietary thermoplastic forming ecosystems controlled by single-source patent holders create supply vulnerability for practices dependent on integrated digital workflows.
- Medical-grade polymer input costs:Petroleum-derived multilayer polymer sheet stock faces price volatility tied to feedstock fluctuations, squeezing margin on custom-fabricated appliances.
- OSHA bloodborne pathogen compliance:Sterilization infrastructure mandates for intraoral scanner sleeves and impression material handling add fixed cost per procedure that disadvantages smaller practices.
Strategic Opportunities
- Texas suburban corridor expansion:Austin and Dallas-Fort Worth metro areas exhibit specialist-to-population ratios below national benchmarks, presenting whitespace for de novo clinic development.
- Teledentistry reimbursement evolution:State-level scope-of-practice expansions in New York and Florida enable remote treatment monitoring that extends geographic reach without physical chair expansion.
- AI-powered cephalometric analysis:Machine learning diagnostic tools are converging with cloud-based treatment planning platforms to reduce specialist labor hours per case intake.
Industry Challenges
- Digital workflow integration:Legacy practice management systems require costly middleware development to synchronize intraoral scan data with third-party aligner fabrication portals.
- Orthodontic specialist training pipelines:Residency program output constraints limit availability of practitioners certified in complex malocclusion management and skeletal anchorage techniques.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Orthodontics Market |
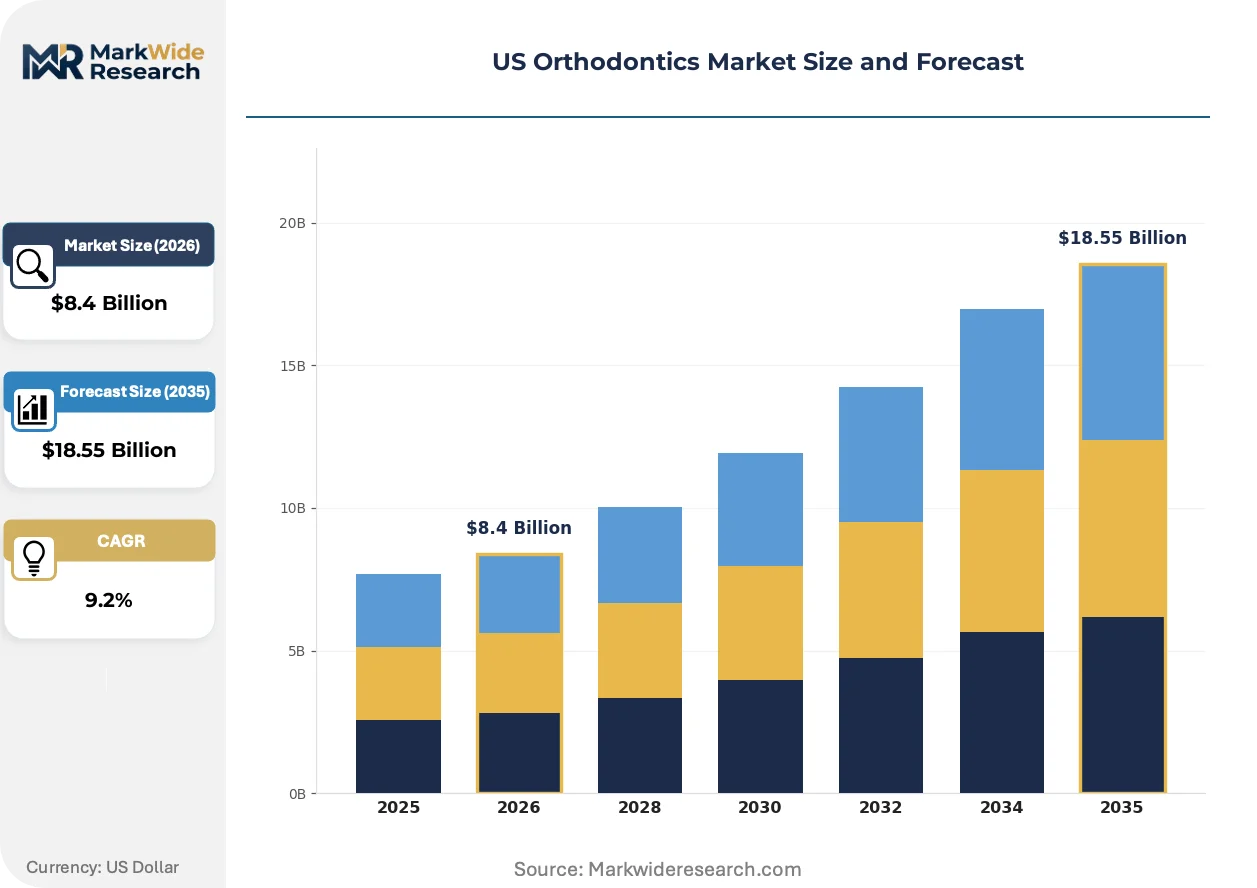
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $18.55 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brackets, Archwires, Elastics, Retainers, Clear Aligners Application: Malocclusion Correction, Jaw Alignment, Space Maintenance, Teeth Straightening, Palate Expansion End User: Orthodontic Clinics, Specialty Dental Centers, Private Dental Practices, Educational Institutions Distribution Channel: Direct Sales, Dental Distributors, Online Platforms, Retail Pharmacies, Medical Supply Stores |
| Companies Covered | Ormco Corporation, Dentsply, Align Technology Inc., Western Dental, GC Orthodontics, 3M Unitek, Henry Schein, Dental Care Alliance, American Orthodontics Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Orthodontics Market Strategic Shifts & Innovations
Digital scanning ecosystems are displacing physical impression workflows while compressing the time between initial consultation and appliance delivery.
Intraoral scanning hardware is converging with cloud-based treatment planning software to eliminate alginate impression steps entirely. Orthodontic clinics in California and Texas are adopting these integrated systems at replacement cycles of 36-48 months. The technology is converging with automated staging algorithms that reduce manual tooth-movement planning from hours to minutes per case.
FDA enforcement discretion policies for artificial intelligence-enabled diagnostic tools are reshaping software-as-a-medical-device pathways for orthodontic applications. The agency's evolving guidance on machine learning-based cephalometric landmark identification is accelerating 510(k) submission volumes from digital dentistry vendors. Specialist practices in New York and Illinois are prioritizing platforms with established FDA clearances over experimental diagnostic modules.
Direct-to-consumer aligner brands are fragmenting traditional referral pathways by capturing mild malocclusion cases before specialist consultation. General dental practices in Florida and Arizona are responding by integrating limited orthodontic services to retain patient lifetime value. This channel disruption is most visible in Sun Belt metropolitan areas where marketing spend per capita on aesthetic dental services exceeds national medians by substantial margins.
US Orthodontics Market Segmentation
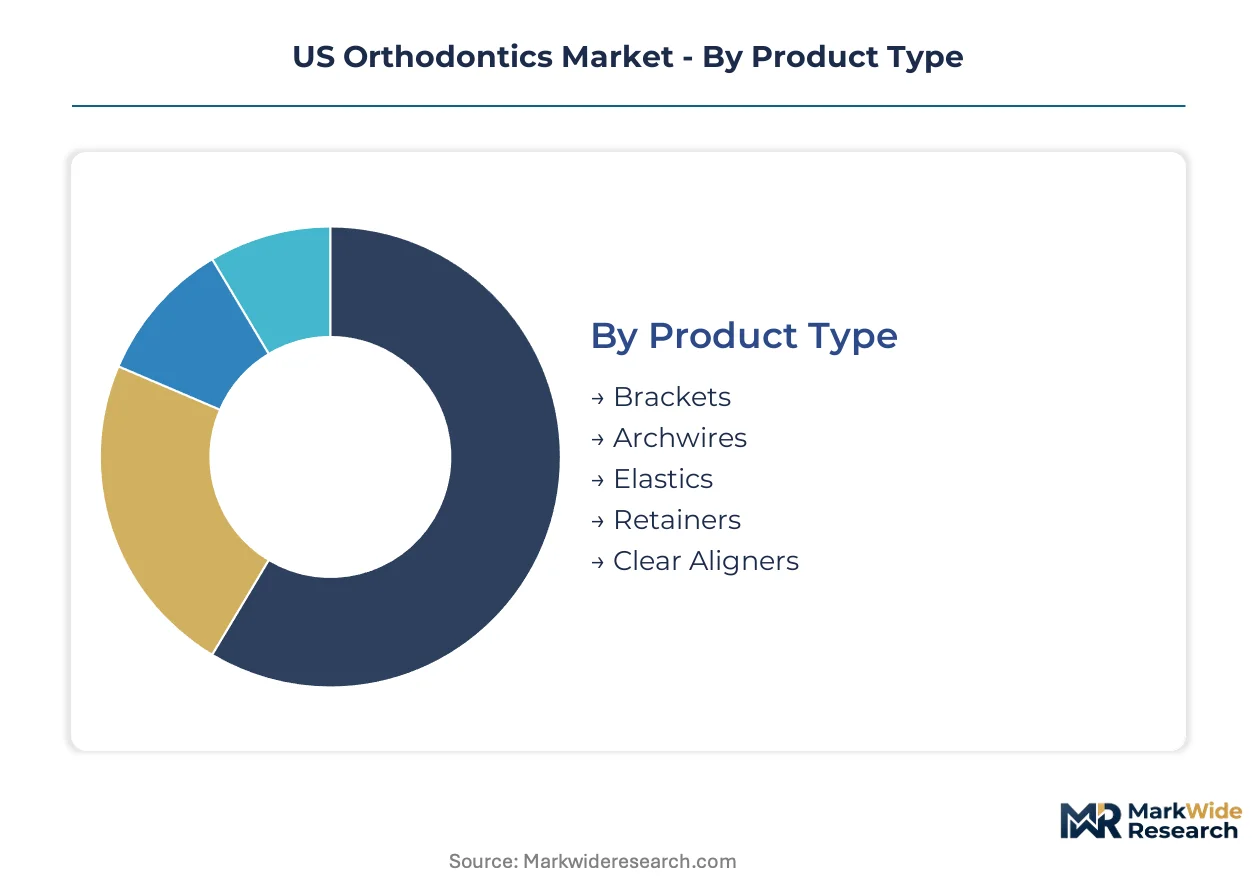
Orthodontic device segmentation reveals divergent margin profiles across fabrication methods, with digitally integrated systems commanding premium positioning against commodity hardware. Treatment modality selection hinges on case complexity thresholds, patient age demographics, and specialist versus generalist practice capabilities.
Product Type:
Customization intensity spans from patient-specific thermoplastic forming to mass-produced stainless steel components, creating distinct production economics and inventory models across the category.
- Clear Aligners:Multilayer medical-grade polymers fabricated through proprietary thermoplastic forming processes enable removable, near-invisible treatment. Demand concentrates in California and New York metro corridors where teen and young adult patients prioritize aesthetic outcomes over mechanical precision.
- Brackets:Bonded stainless steel or ceramic attachments serve as fixed anchorage points for archwire engagement, with self-ligating variants reducing friction and adjustment frequency. Volume leadership persists in adolescent cases across Texas and Florida where complex malocclusion correction demands precise three-dimensional control.
- Archwires:Nickel-titanium alloys deliver superelastic force delivery for predictable tooth movement.
- Elastics:Latex or synthetic rubber chains apply interarch traction forces.
- Retainers:Removable or fixed appliances maintain post-treatment positioning.
Leading the category by volume: Brackets. Expanding most quickly: Clear Aligners.
Application:
Case complexity tiers separate routine aesthetic intervention from skeletal discrepancy correction requiring interdisciplinary coordination.
- Teeth Straightening:Crowding and spacing correction through controlled crown repositioning represents the highest-volume application. California orthodontic clinics drive uptake of digitally planned clear aligner protocols for mild-to-moderate cases.
- Malocclusion Correction:Class I, II, and III bite discrepancy management demands comprehensive diagnosis through cephalometric analysis and study model evaluation. Texas specialty centers concentrate capacity for complex skeletal pattern modification.
- Jaw Alignment:Orthognathic surgical coordination or functional appliance therapy.
- Space Maintenance:Interceptive pediatric procedures preserving arch perimeter.
- Palate Expansion:Rapid maxillary expansion for transverse deficiency correction.
Volume concentration: Teeth Straightening. Steepest expansion trajectory: Malocclusion Correction.
End User:
Credential requirements and capital intensity stratify delivery settings from hospital-affiliated residency programs to solo practitioner offices.
- Orthodontic Clinics:Specialist-owned practices with dedicated cephalometric radiography and intraoral scanning infrastructure capture premium case flow. New York and Illinois markets exhibit highest specialist density per capita.
- Private Dental Practices:General dentists integrating limited orthodontic services through aligner therapy partnerships. Florida and Arizona lead this channel's expansion as patient acquisition costs for aesthetic services remain below specialist clinic thresholds.
- Specialty Dental Centers:Multi-specialty group practices with shared diagnostic equipment.
- Educational Institutions:University-affiliated residency programs with Medicaid case obligations.
Revenue share leader: Orthodontic Clinics. Gaining share fastest: Private Dental Practices.
Distribution Channel:
Supply chain proximity to fabrication centers determines fulfillment velocity and minimum order economics.
- Dental Distributors:Henry Schein and regional intermediaries maintain same-day delivery networks to practices in California, Texas, and New York. Inventory pooling across metropolitan hubs reduces working capital requirements for bracket and wire replenishment.
- Direct Sales:Manufacturer-aligned field forces serve high-volume orthodontic clinics with consignment inventory and clinical education support. Align Technology's integrated scanner-aligner ecosystem exemplifies this channel's captive supply model.
- Online Platforms:E-commerce portals for consumables and replacement appliances.
- Retail Pharmacies:Limited over-the-counter retainer and elastic availability.
- Medical Supply Stores:Regional brick-and-mortar procurement for emergency replacements.
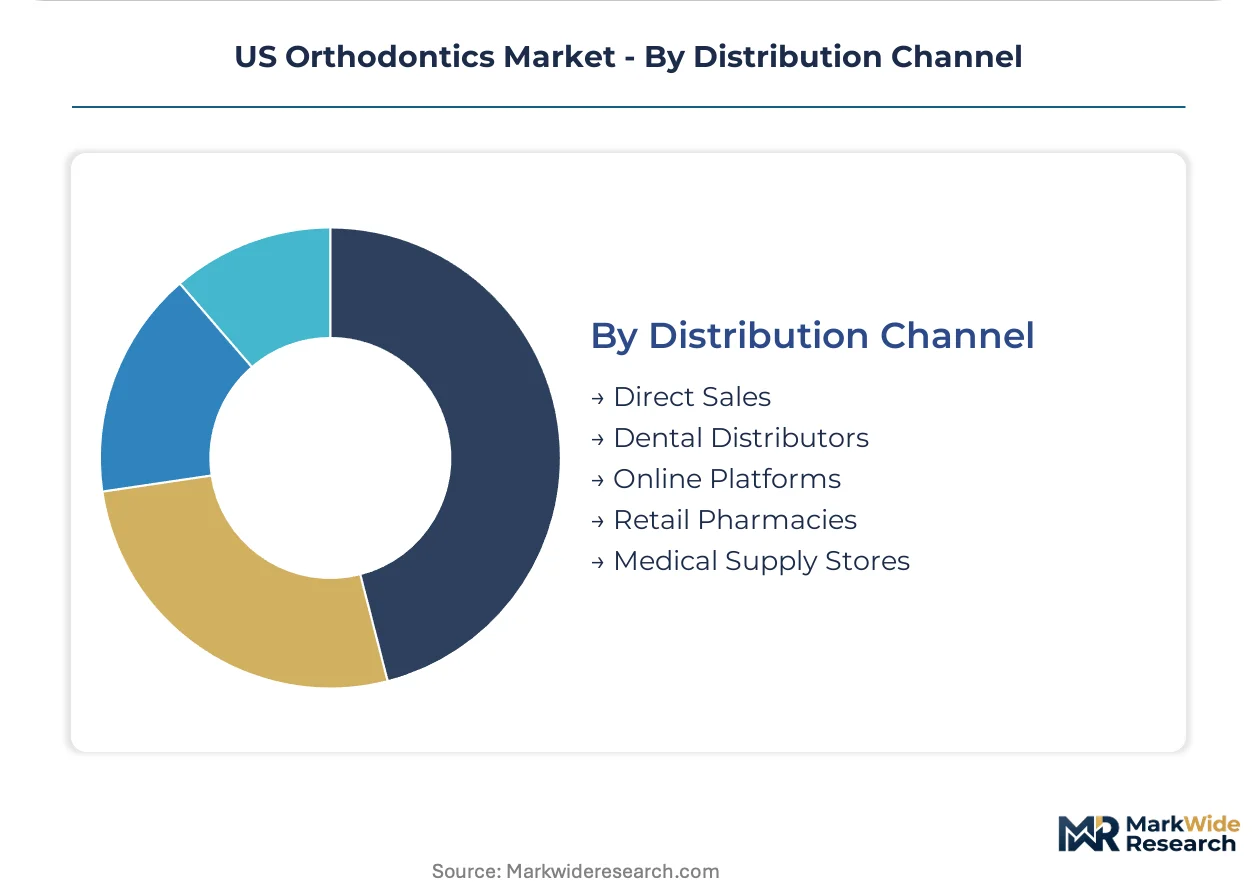
Dominant channel by transaction volume: Dental Distributors. Climbing the fastest: Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for orthodontic services concentrates in coastal and Sun Belt metropolitan corridors where specialist density intersects with elevated disposable income. California, Texas, and New York collectively anchor treatment volume through distinct patient acquisition patterns and regulatory environments.
California
Los Angeles and San Francisco metro corridors generate the highest per-capita clear aligner adoption among teen and young adult demographics. California Dental Board continuing education mandates steer practitioners toward digitally integrated treatment systems. San Diego and Orange County specialist clusters sustain premium pricing through concierge-style patient experiences.
Texas
Austin and Dallas-Fort Worth suburban corridors exhibit specialist-to-population ratios below national benchmarks, creating whitespace for de novo clinic development. Texas State Board of Dental Examiners enforces teledentistry scope-of-practice protocols that enable remote monitoring expansion. Houston's medical center corridor concentrates academic orthodontic residency programs that feed regional practitioner supply.
New York
Manhattan and Brooklyn orthodontic clinics capture premium case flow through dense specialist networks and elevated aesthetic service demand. New York State Education Department dental division regulates teledentistry reimbursement evolution that extends geographic reach. Long Island and Westchester County exhibit highest specialist density per capita nationally.
Florida
Miami and Tampa metro areas lead Sun Belt expansion of general dental practices integrating limited orthodontic services. Florida Board of Dentistry scope-of-practice expansions enable aligner therapy partnerships outside specialist clinics. Orlando's tourism economy supports cash-pay aesthetic treatment models.
Illinois
Chicago metropolitan area concentrates academic medical center orthodontic programs with Medicaid case obligations. Illinois Department of Financial and Professional Regulation oversees continuing education requirements for digital diagnostic tool adoption. Suburban collar counties exhibit growing private practice consolidation trends.
US Orthodontics Market Key Industry Players
Patent-protected thermoplastic forming ecosystems dominate the current landscape through integrated digital scanning and fabrication workflows. The vendor base stratifies between proprietary platform holders, diversified dental distributors, and conventional hardware specialists. Three archetypes prevail: captive supply chain operators, multi-brand distributors, and bracket-wire traditionalists. Competitive moves center on vertical integration into scanner-aligner ecosystems and geographic expansion through de novo clinic partnerships.
Within the proprietary platform tier, Align Technology Inc. occupies a position exemplifying closed-loop digital integration. Among diversified distributors, Henry Schein anchors supply chain access for private practices nationwide. On the conventional hardware vector, Ormco Corporation represents sustained R&D intensity in self-ligating archwire technologies. These three entities collectively illustrate the market's tripartite competitive structure.
| Leading Market Players |
|---|
| Ormco Corporation |
| Dentsply |
| Align Technology Inc. |
| Western Dental |
| GC Orthodontics |
| 3M Unitek |
| Henry Schein |
| Dental Care Alliance |
| American Orthodontics Corporation |
| Others |
Cost & Logistics Intelligence
Orthodontic specialist clinics concentrated in California, Texas, and New York metro corridors anchor premium pricing power through bundled digital workflow packages that integrate intraoral scanning hardware with per-case aligner fabrication fees. This buyer archetype concentration sustains a subscription-anchored model where equipment leases and per-aligner royalties combine, while general dental practices face unbundled transactional pricing for commodity brackets and archwires without service wrap.
Pricing Analysis
Warranty and clinical education bundling separates premium clear aligner ecosystems from unbundled conventional hardware procurement. Three-tier pricing structure across premium, standard, and economy levels tracks FDA 510(k) clearance tier and integration depth with practice management systems. Cost compression in nickel-titanium alloy brackets is intensifying because petroleum-derived feedstock volatility squeezes margin on superelastic wire formulations. General dental practices in Florida and Arizona exhibit highest price sensitivity due to cash-pay patient bases, while Manhattan orthodontic clinics show lowest sensitivity through concierge service premiums.
Supply Chain Analysis
Freight costs for medical-grade polymer sheet stock from Germany and Japan amplify landed cost volatility for domestic thermoplastic forming operations. Manufacturing concentration spans Costa Rica, Mexico, and China for bracket injection molding, while aligner fabrication draws from US-based proprietary forming centers. Single-source vulnerability pervades scanner-aligner integrated ecosystems where patent-protected workflows lock practices into captive supply. Distribution runs through Henry Schein's regional hubs for same-day bracket replenishment, with direct sales channels capturing high-volume clinic consignment arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Residency program output constraints create a supply-constrained practitioner pipeline that props pricing power for established orthodontic clinics despite direct-to-consumer channel pressure. This capacity bottleneck in specialist certification sustains premium capture for incumbents with established referral networks.
For Market Incumbents: Extend digital ecosystem lock-in through proprietary scanner-aligner integration that raises switching costs for affiliated practices. Add captive fabrication capacity in Texas suburban corridors where specialist-to-population ratios lag national benchmarks. Direct-to-consumer aligner brands pose substitution threat in mild malocclusion segments; defend through exclusive partnerships with dental schools feeding practitioner supply.
For New Entrants and Emerging Players: Dental distributors with established private practice relationships offer the most penetrable channel partnership for commodity bracket and wire entry. Target Austin and Dallas-Fort Worth metro whitespace where de novo clinic development faces lower incumbent density. AI-powered cephalometric analysis platforms present fastest-expanding margin pool for software-as-a-device entrants seeking FDA 510(k) clearance differentiation.
For Investors and Strategic Acquirers: The window for entry favors vertically integrated platform operators with scanner hardware and aligner fabrication under single control. Long-term viability hinges on orthodontic specialist density expansion outpacing direct-to-consumer capture in aesthetic segments. Monitor teledentistry reimbursement policy evolution in New York and Florida as inflection signal for remote monitoring platform valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Acceleration | Streamlined premarket notification compresses commercialization timelines for novel thermoplastic forming devices below eight months. |
| Scanner-Aligner Ecosystem Integration | Closed-loop digital workflows raise switching costs and capture recurring per-case revenue from affiliated specialist practices. |
| Texas Suburban Clinic Expansion | Austin and Dallas-Fort Worth metro corridors exhibit specialist-to-population ratios below national benchmarks, presenting whitespace. |
| AI Diagnostic Module Development | Machine learning cephalometric tools reduce specialist labor hours per case while requiring FDA enforcement discretion navigation. |
| Teledentistry Reimbursement Strategy | State-level scope-of-practice expansions in New York and Florida enable remote monitoring without physical chair investment. |
Research Approach
Document review covered FDA 510(k) premarket notification databases, state dental board continuing education mandates, and orthodontic residency program output statistics, complemented by interviews with orthodontic clinic owners, dental distributor procurement managers, intraoral scanner platform engineers, and GPO contracts specialists. Secondary validation drew from SEC filings of listed dental device manufacturers, CMS teledentistry reimbursement policy trackers, and OSHA bloodborne pathogen compliance guidance. Bottom-up practice-level demand estimates triangulated against top-down manufacturer shipment data across the analysis window.
Cross-referencing historical clear aligner adoption curves against panel input from orthodontic specialists and general dental practitioners shaped the analytical framework. Segmentation dimensions modeled include product type, application complexity tier, end-user credential requirements, and distribution channel proximity to fabrication centers. CAGRs were derived through iterative convergence of demand-side procedure volume projections and supply-side manufacturing capacity expansion plans, with nickel-titanium alloy pricing volatility and polymer feedstock cost trajectories as key forecast inputs.
Caveats apply where FDA enforcement discretion policy shifts, state teledentistry scope-of-practice rollbacks, or orthodontic specialist residency output expansion could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Intraoral Dental Sensors Market
Dental Devices
Asia Pacific Acrylic Teeth Market
Dental Devices
Prophy Dental Handpiece Market
Dental Devices
Europe Dental Aligners Market
Dental Devices
Chile Dental Market
Dental Devices
Global Endodontics Market
Dental Devices
Dental Restoration Market
Dental Devices
Dental Articulators Market
Dental Devices
Dental Amalgamators Market
Dental Devices
Guided Biofilm Therapy Market
Dental Devices
North America Dental Lasers Market
Dental Devices
Dental Apex Locator Market
Dental Devices
Europe CBCT Dental Imaging Market
Dental Devices
Dental Sealants Market
Dental Devices
Global Dental Burs Market
Dental Devices
Endodontics and Orthodontics Market