
 China Dental Devices Market | 2026-2036
China Dental Devices Market Size, Share, and Industry Trends Forecast 2026-2036
China Dental Devices Market Outlook
China's dual carbon goals under the national green development framework is hardening material sourcing requirements for dental device manufacturers. Fujian Meisheng Medical Science & Technology Co., Ltd. leverages domestic polymer supply chains to control restorative material costs. Mindray anchors hospital-grade digital imaging sales through direct channel control in provincial capitals. Sinol Dental Limited specializes in orthodontic appliance production at scale for distributor networks across eastern provinces.
Dental devices encompass instruments, equipment, and consumables engineered from biocompatible ceramics, titanium alloys, and medical-grade polymers for diagnosis, treatment, and restoration of oral conditions. These products typically operate under precision tolerances of 10-50 micrometers for implant interfaces and require sterilization validation to 134°C saturated steam standards. Orthodontic Devices and Dental Implants command the deepest margin pools due to recurring consumable attachment sales and premium titanium fixture pricing. CAD/CAM Systems within the technology dimension are displacing conventional lab workflows as chairside milling units penetrate mid-tier clinic budgets. Preventive Care Devices remain volume-led but price-constrained in public health procurement tenders.
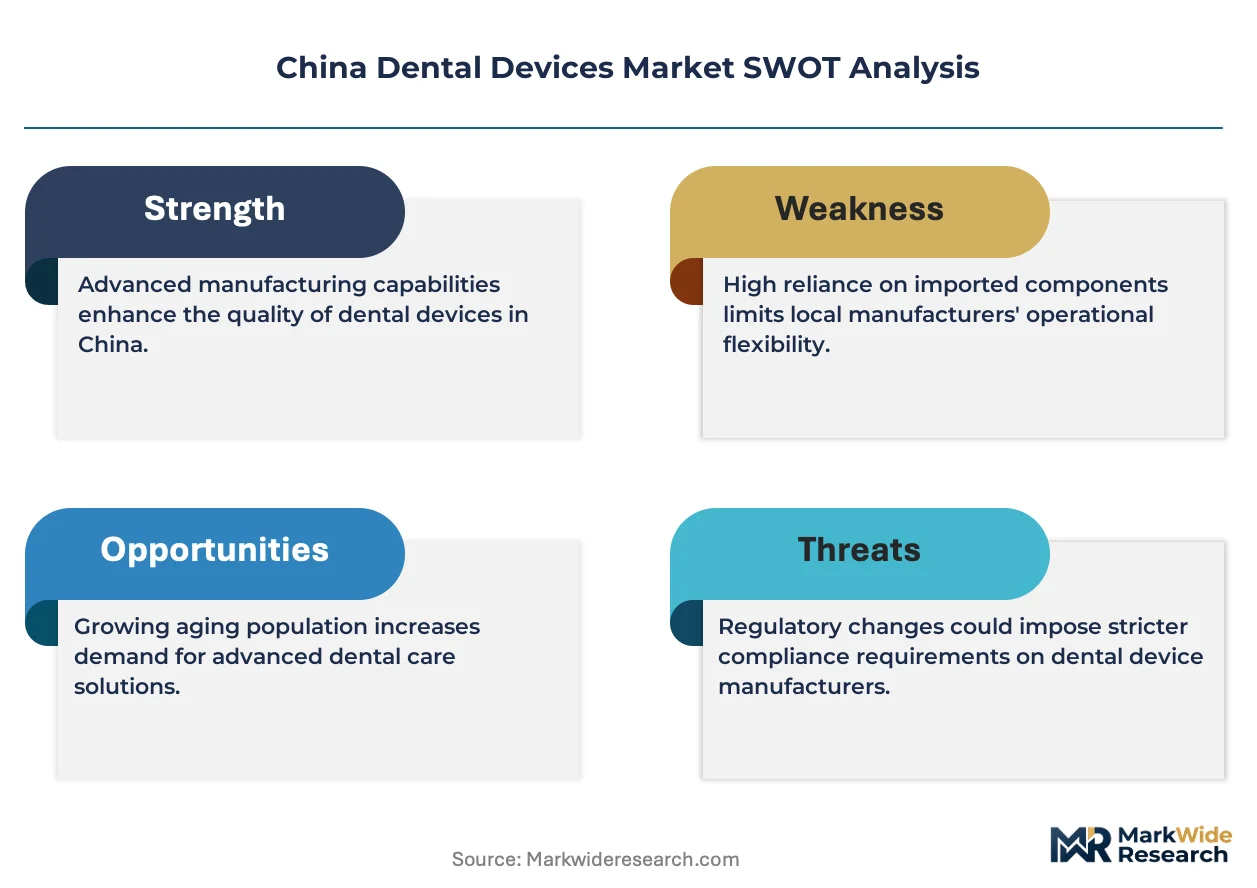
NMPA enforces Class III registration requirements for implantable dental devices, mandating clinical trial data and biocompatibility testing under GB/T 16886 standards. SAMR coordinates pricing surveillance through centralized provincial procurement platforms, compressing margins on standard restorative materials while exempting innovative digital equipment. China's GB standards for dental unit waterline sterilization are tightening bacterial load thresholds, forcing equipment upgrade cycles. Stakeholders must monitor NMPA's evolving equivalence determination pathways for imported versus domestically manufactured implant systems.
Market Dynamics
Chairside CAD/CAM systems are compressing traditional dental laboratory workflows as private clinic chains in Shanghai and Beijing accelerate capital deployment toward same-day restoration capabilities.
Growth Catalysts
- Dual carbon goals:China's national green development framework is hardening material sourcing requirements, favoring domestic polymer supply chains for restorative materials.
- Tier-one hospital networks:Oral surgery applications concentrate demand for implantable devices within provincial capital hospital systems.
- GB/T 16886 standards:Biocompatibility testing mandates under NMPA Class III pathways are elevating quality benchmarks for imported and domestic implant systems alike.
Market Restraints
- Titanium alloy supply concentration:Premium fixture pricing depends on concentrated raw material sourcing channels vulnerable to geopolitical friction.
- SAMR pricing surveillance:Centralized provincial procurement platforms compress margins on standard restorative materials through transparent tender mechanisms.
- Clinical trial data requirements:NMPA Class III registration mandates extensive biocompatibility validation, extending time-to-market for novel implant designs.
Strategic Opportunities
- Eastern province distributor networks:Orthodontic appliance production at scale targets underpenetrated mid-tier cities beyond Beijing and Shanghai.
- Digital equipment exemption:SAMR pricing surveillance exempts innovative digital equipment from centralized procurement compression.
- GB standards for waterline sterilization:Tightening bacterial load thresholds force equipment upgrade cycles across existing installed bases.
Industry Challenges
- CAD/CAM technician scarcity:Chairside milling unit operation requires specialized digital dentistry skills absent from conventional dental technician training pipelines.
- Legacy lab workflow integration:Conventional crown-and-bridge laboratories face stranded asset risk as clinic chains internalize production.
- NMPA equivalence determination uncertainty:Evolving pathways for imported versus domestically manufactured implant systems create regulatory navigation complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Dental Devices Market |
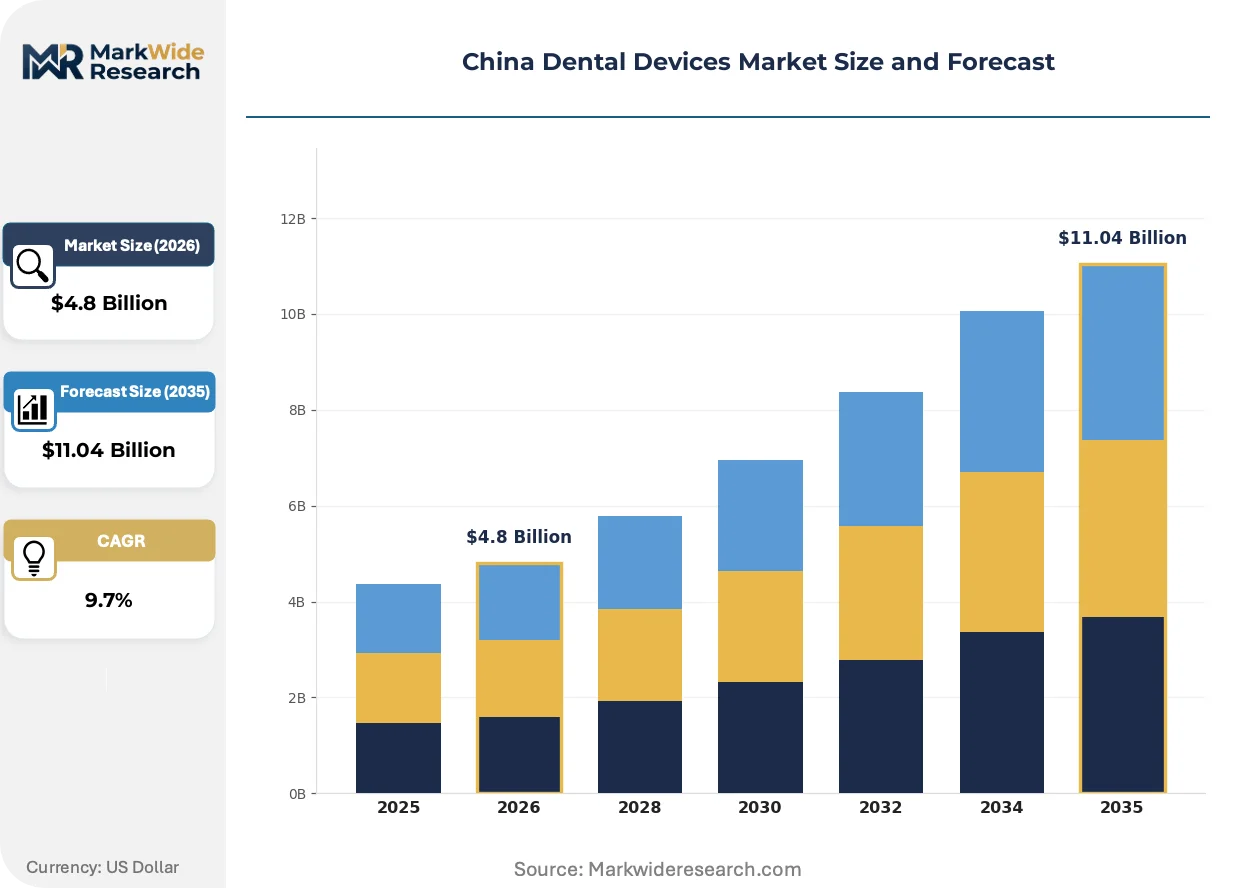
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Orthodontic Devices, Dental Implants, Restorative Materials, Preventive Care Devices End User: Dental Clinics, Hospitals, Research Institutions, Mobile Dental Units Technology: 3D Printing, Laser Dentistry, CAD/CAM Systems, Digital X-ray Application: Cosmetic Dentistry, Periodontics, Oral Surgery, Pediatric Dentistry |
| Companies Covered | Fujian Meisheng Medical Science & Technology Co., Ltd., Sinol Dental Limited, Guilin Woodpecker Medical Instrument Co., Ltd., Guangzhou Ajax Medical Equipment Co., Ltd., Chengdu Sani Medical Equipment Co., Ltd., Shenzhen Rogin Medical Co., Ltd., Ningbo Runyes Medical Instrument Co., Ltd., Mindray, Foshan ANLE Dental Equipment Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Dental Devices Market Strategic Shifts
Digital dentistry workflows are restructuring competitive positioning across material suppliers, equipment manufacturers, and service providers as precision tolerances tighten and speed expectations compress.
Chairside CAD/CAM milling units are absorbing conventional laboratory crown production by enabling single-visit ceramic restorations. Private dental clinic chains in tier-one cities deploy these systems to differentiate patient experience and capture margin previously allocated to external labs. The technology is absorbing technician labor costs while compressing turnaround times from two weeks to under two hours.
NMPA's tightening Class III registration pathways for implantable devices are elevating clinical evidence requirements beyond biocompatibility testing alone. Domestic manufacturers must now generate indigenous clinical trial data rather than relying solely on foreign equivalence determinations. Imported implant systems face extended review timelines as regulators scrutinize manufacturing quality system alignment with GB standards.
Hospital-grade digital imaging procurement is consolidating around direct manufacturer relationships rather than layered distributor networks. Provincial capital hospital networks negotiate imaging system acquisitions through centralized technical evaluation committees. Beijing and Shanghai municipal health authorities pilot subscription-based equipment service models that unbundle capital expenditure from maintenance obligations.
China Dental Devices Market Segmentation
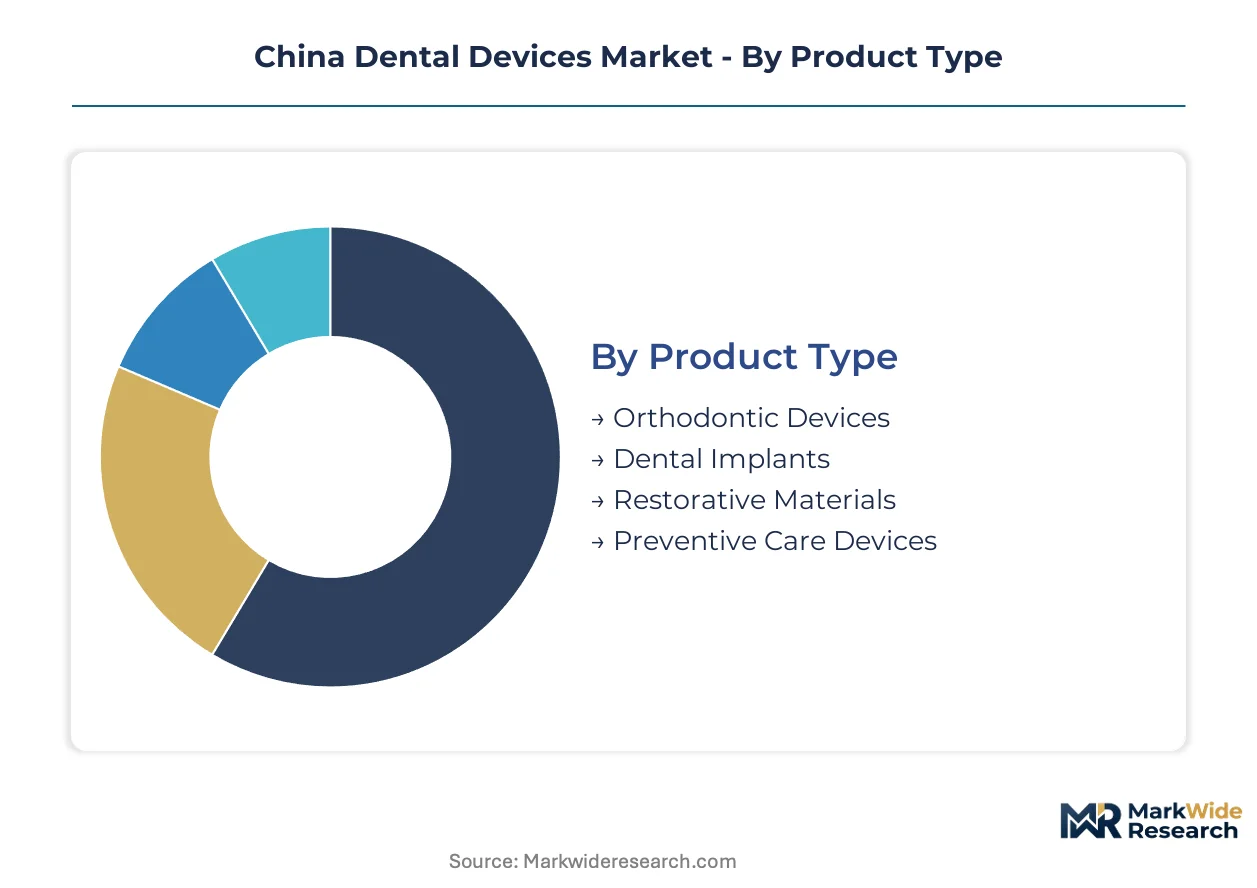
Segmentation in China's dental devices market reveals how procurement authority, clinical workflow integration, and regulatory classification intersect to determine commercial access. Each axis exposes distinct margin structures and competitive barriers that shape vendor strategy.
Product Type:
Material composition and implantable status determine NMPA registration intensity and recurring revenue potential across this axis.
- Dental Implants:Titanium alloy fixtures with precision-machined surfaces require Class III NMPA registration and biocompatibility validation under GB/T 16886. Tier-one hospital networks in Beijing and Shanghai concentrate procurement for oral surgery applications, though SAMR pricing surveillance compresses margins on standard designs.
- Orthodontic Devices:Clear aligners and fixed appliances leverage medical-grade polymer supply chains with shorter regulatory pathways than implantables. Private clinic chains drive volume through recurring attachment sales and direct-to-consumer marketing channels.
- Restorative Materials:Ceramic blocks and composite resins face centralized provincial tender pressure.
- Preventive Care Devices:Sealants and prophylaxis equipment serve public health programs at price-constrained terms.
Dental Implants leads on scale; Orthodontic Devices leads on momentum.
End User:
Procurement sophistication and capital availability vary sharply across institutional types, dictating sales channel design.
- Dental Clinics:Private chains in Shanghai and Beijing deploy chairside CAD/CAM systems to capture same-day restoration premiums. Fujian Meisheng and similar domestic suppliers target mid-tier clinic expansion with cost-optimized polymer restorative portfolios.
- Hospitals:Provincial capital networks anchor demand for hospital-grade digital imaging through centralized technical evaluation committees. NMPA Class III implant registrations concentrate within tier-one hospital oral surgery departments.
- Research Institutions:Clinical trial sponsorship and indigenous data generation support domestic manufacturer equivalence pathways.
- Mobile Dental Units:Rural outreach programs prioritize portable preventive equipment over capital-intensive digital systems.
Hospitals dominate absolute procurement value; Dental Clinics represents the steepest expansion trajectory.
Technology:
Digital workflow penetration is restructuring competitive positioning between equipment vendors and traditional laboratory service providers.
- CAD/CAM Systems:Chairside milling units enable single-visit ceramic restorations, compressing conventional laboratory turnaround from weeks to hours. Private clinic chains absorb technician labor costs internally while differentiating patient experience through same-day delivery.
- 3D Printing:Resin and metal additive manufacturing supports surgical guide production and custom appliance fabrication at lower unit volumes than milling.
- Digital X-ray:Sensor-based imaging systems replace phosphor plate technology across provincial hospital upgrade cycles.
- Laser Dentistry:Soft-tissue applications remain niche due to capital intensity and training requirements.
CAD/CAM Systems commands the deepest installed base investment; 3D Printing gains share fastest in orthodontic and surgical guide applications.
Application:
Clinical specialty determines reimbursement environment, procedure complexity, and consumable attachment economics.
- Oral Surgery:Implant placement and bone grafting procedures concentrate within tier-one hospital networks, requiring Class III device registrations and sterile field protocols. NMPA's tightening quality benchmarks elevate barriers for novel fixture designs.
- Cosmetic Dentistry:Veneer and whitening procedures drive discretionary spending in private clinic chains, with CAD/CAM-enabled same-day restorations capturing premium positioning.
- Periodontics:Regenerative therapies and maintenance protocols generate recurring consumable demand.
- Pediatric Dentistry:Preventive-focused programs align with public health procurement at standardized pricing.
Oral Surgery anchors high-value device consumption; Cosmetic Dentistry climbs fastest as private clinic chains expand aesthetic service portfolios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dental devices industry traces its modern scaling to the 1990s when state-owned factories in Guangdong and Jiangsu provinces began manufacturing basic dental chairs and handpieces for domestic hospital networks. These early production clusters laid the groundwork for today's tiered supply base serving both public procurement and private clinic expansion.
Yangtze River Delta
Shanghai anchors chairside CAD/CAM system deployment through private dental clinic chains seeking same-day restoration capabilities. SAMR pricing surveillance exempts innovative digital equipment from centralized procurement compression, allowing premium technology penetration. Suzhou and Hangzhou manufacturing zones supply medical-grade polymer feedstocks for orthodontic appliance production at scale.
Pearl River Delta
Guangzhou and Shenzhen concentrate hospital-grade digital imaging procurement through provincial technical evaluation committees. GB standards for dental unit waterline sterilization are tightening bacterial load thresholds, forcing equipment upgrade cycles across existing installed bases. Dongguan fabricators specialize in titanium alloy machining for implant fixture production serving tier-one hospital oral surgery departments.
Beijing-Tianjin-Hebei
Beijing municipal health authorities pilot subscription-based equipment service models that unbundle capital expenditure from maintenance obligations. NMPA Class III registration pathways concentrate clinical trial sponsorship within tier-one hospital networks. Tianjin port logistics facilitate imported implant system distribution while domestic manufacturers establish equivalence determination documentation.
Sichuan-Chongqing
Chengdu anchors western China demand for orthodontic devices through distributor networks targeting underpenetrated mid-tier cities. Dual carbon goals harden material sourcing requirements, favoring domestic polymer supply chains for restorative materials. Chongqing's medical device industrial park hosts assembly operations for preventive care equipment serving rural outreach programs.
Shandong Peninsula
Qingdao and Yantai manufacturing bases produce sterilization equipment meeting GB standards for saturated steam validation at 134°C. Provincial procurement platforms compress margins on standard restorative materials through transparent tender mechanisms. Weihai fabricators supply ceramic blocks for CAD/CAM milling units deployed across eastern province dental clinics.
China Dental Devices Market Competitive Environment
Capital-heavy producers compete with asset-light designers across China's dental devices sector, with domestic manufacturers controlling mid-tier equipment fabrication while multinational affiliates retain premium imaging technology positions. The vendor base organizes around three strategic archetypes: provincial equipment assemblers serving public hospital tenders, specialized polymer suppliers for orthodontic consumables, and digital workflow integrators targeting private clinic chains. Capacity expansion and strategic partnerships dominate competitive moves as firms navigate NMPA registration complexity and SAMR pricing surveillance.
Among domestic manufacturers, Fujian Meisheng Medical Science & Technology Co., Ltd. and Sinol Dental Limited exemplify the provincial specialist archetype, while Mindray occupies a position bridging hospital-grade equipment and direct channel control in provincial capitals. These three anchors illustrate the tiered structure where geography-linked production, regulatory navigation capability, and channel strategy determine competitive positioning against both domestic peers and imported alternatives.
| Leading Market Players |
|---|
| Fujian Meisheng Medical Science & Technology Co., Ltd. |
| Sinol Dental Limited |
| Guilin Woodpecker Medical Instrument Co., Ltd. |
| Guangzhou Ajax Medical Equipment Co., Ltd. |
| Chengdu Sani Medical Equipment Co., Ltd. |
| Shenzhen Rogin Medical Co., Ltd. |
| Ningbo Runyes Medical Instrument Co., Ltd. |
| Mindray |
| Foshan ANLE Dental Equipment Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Titanium alloy feedstock costs cascade through implant fixture pricing tiers as Dongguan machining clusters absorb raw material volatility and pass compressed margins to tier-one hospital procurement committees. SAMR centralized tendering amplifies this transmission mechanism by exposing standard restorative materials to transparent price competition while exempting digital equipment from equivalent pressure.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by NMPA registration tier and clinical evidence depth. Premium titanium fixtures with indigenous trial data command hospital network loyalty; economy-grade polymer restorations face tender compression. Pricing pressure stems from SAMR provincial platform transparency. Public health programs exhibit highest price sensitivity; private clinic chains prioritize same-day service premiums over unit cost.
Supply Chain Analysis
Freight cost differentials between coastal manufacturing zones and inland hospital networks favor regional polymer suppliers over imported ceramic block distributors. Raw material sourcing concentrates in Jiangsu titanium processing, Fujian polymer synthesis, and Shandong sterilization equipment fabrication. Single-source vulnerability concentrates in medical-grade titanium alloy channels. Distribution runs through provincial technical evaluation committees for hospital-grade equipment and layered distributor networks for mid-tier clinic consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's dental devices sector represents a late-cycle quality story as chairside CAD/CAM penetration shifts procurement criteria from unit cost toward precision tolerance and same-day service capability. This specification upgrade rewards manufacturers with indigenous clinical data and direct hospital relationships.
For Market Incumbents: Lock in hospital system partnerships through subscription-based equipment service models that unbundle capital expenditure from maintenance obligations. Defend against emerging domestic polymer suppliers by deepening backward integration into medical-grade titanium alloy sourcing. Prioritize NMPA Class III registration renewal investments to maintain equivalence pathway advantages over imported competitors.
For New Entrants and Emerging Players: Launch via eastern province distributor networks targeting orthodontic appliance demand in underpenetrated mid-tier cities beyond Beijing and Shanghai. Exploit the CAD/CAM technician scarcity gap with training-bundled equipment offerings. Prioritize clear aligner production at scale where regulatory pathways remain shorter than implantable device categories.
For Investors and Strategic Acquirers: Consolidation pressure builds where NMPA registration complexity strands sub-scale domestic manufacturers lacking indigenous clinical trial capabilities. Long-term viability favors asset-light designers with proprietary polymer formulations and direct clinic channel control. Watch for SAMR pricing surveillance expansion into digital equipment categories as the inflection signal for margin compression timing.
| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Class III Registration Investment | Indigenous clinical trial data satisfies tightening equivalence requirements for implant system market access. |
| Chairside CAD/CAM Deployment Partnership | Private clinic chains in Shanghai and Beijing capture same-day restoration premiums from laboratory outsourcing. |
| Domestic Polymer Supply Chain Integration | Fujian and Jiangsu feedstock control reduces restorative material cost exposure under dual carbon compliance. |
| Hospital System Direct Channel Development | Provincial capital technical evaluation committees consolidate procurement around manufacturer relationships. |
| Digital Dentistry Technician Training Program | Skill pipeline development addresses CAD/CAM operator scarcity constraining mid-tier clinic adoption. |
Study Parameters
Bottom-up dental clinic and hospital procurement modeling reconciled against top-down equipment manufacturer shipment tracking forms the analytical core of this study. Primary interviews with oral surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers combined with secondary validation from NMPA registration filings, SAMR procurement platform disclosures, and provincial health authority equipment tender databases. Triangulation across these sources calibrated segment-level volume estimates.
Historical trendline analysis of titanium alloy pricing, CAD/CAM system deployment rates, and orthodontic appliance production volumes established baseline growth trajectories. The forecast framework models product type, end user institution, technology adoption stage, and clinical application dimensions across the projection horizon. CAGRs derive from regression-adjusted trend extrapolation incorporating NMPA regulatory timeline assumptions and SAMR pricing surveillance scope expansion.
Forecast precision tightens around the base case; tail outcomes carry wider variance under NMPA equivalence determination delays or sudden titanium supply channel disruptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Dental Diamond Burs Market
Dental Devices
CBCT Dental Imaging Market
Dental Devices
Dental Scalers Market
Dental Devices
Dental Liners and Bases Market
Dental Devices
Prophy Dental Handpiece Market
Dental Devices
Dental Laboratory Handpiece Market
Dental Devices
Dental Implant Motors Market
Dental Devices
Dental Healing Caps Market
Dental Devices
Dental Sealants Market
Dental Devices
Global Endodontics Market
Dental Devices
Sleep Apnea Oral Appliances Market
Dental Devices
Global Dental Endodontics Market
Dental Devices
Dental Aligners Market
Dental Devices
Dental Delivery System Market
Dental Devices
Dental Caries Market
Dental Devices
Intraoral Dental Sensors Market