
 Germany Pharmaceutical 3PL Market | 2026-2036
Germany Pharmaceutical 3PL Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Pharmaceutical 3PL Market Foresight
EU Good Distribution Practice certification is unwinding the competitive field, as smaller regional carriers lose hospital pharmacy contracts to qualified operators. DB Schenker leverages its Frankfurt air freight hub to dominate temperature-sensitive biopharmaceutical flows. DHL Logistics sustains multi-temperature zone capacity across Bavaria and Baden-Württemberg manufacturing corridors. Kuehne + Nagel anchors specialized clinical trial logistics through its Stuttgart operations center.
Pharmaceutical third-party logistics encompasses the outsourced management of temperature-controlled storage, transport, and value-added services for medicinal products, typically maintaining validated cold chains between 2°C and 8°C for biologics and sub-zero conditions for certain cell therapies. Its primary commercial purpose is ensuring compliance with product integrity requirements while converting fixed warehouse and fleet assets into variable costs for drug manufacturers. Cold chain logistics captures the highest margin pools due to specialized refrigeration infrastructure and real-time monitoring investments, while warehousing solutions remains the volume backbone serving generic drug distribution through the wholesale distributor channel. Clinical trial logistics represents the fastest-growing application segment, driven by decentralized trial designs requiring direct-to-patient temperature-controlled shipments.
Germany's Federal Institute for Drugs and Medical Devices enforces GDP compliance through facility inspections that determine market access for 3PL operators serving pharmaceutical manufacturers. The EU F-Gas Regulation progressively restricts hydrofluorocarbon-based cooling systems, forcing warehouse operators toward CO2 or ammonia refrigeration retrofits that reshape capital deployment timelines. Stakeholders must monitor how the German Medicines Act amendment affects liability allocation between drug makers and their logistics subcontractors.
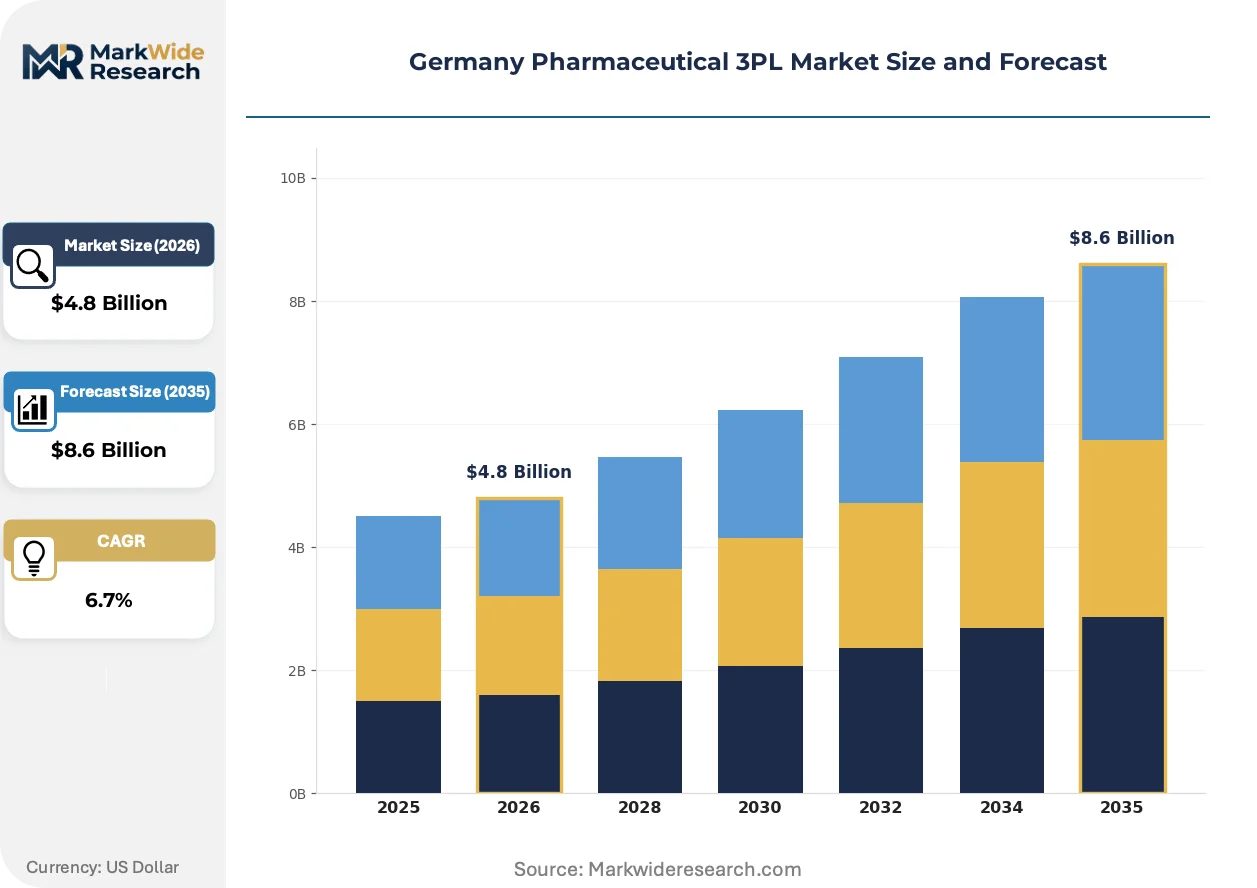
Market Dynamics
EU Good Distribution Practice certification is compressing the competitive field, forcing pharmaceutical manufacturers to consolidate logistics contracts with qualified operators capable of validated cold chain management across the Rhine-Ruhr corridor.
Growth Catalysts
- EU F-Gas Regulation:The progressive phase-down of hydrofluorocarbon refrigerants is accelerating warehouse modernization toward CO2 and ammonia systems, creating retrofit demand for specialized infrastructure providers.
- Decentralized clinical trials:Direct-to-patient temperature-controlled shipments are expanding logistics requirements beyond traditional site-based distribution models.
- Rhine-Ruhr pharmaceutical cluster:Proximity concentration of biopharmaceutical manufacturing near Frankfurt Airport cargo infrastructure enables just-in-time cold chain capabilities.
Market Restraints
- Capital intensity of refrigeration retrofits:CO2 and ammonia system conversions require substantial upfront investment, extending payback periods for mid-scale warehouse operators.
- Qualified carrier scarcity:GDP certification requirements are reducing the pool of eligible subcontractors, concentrating risk with fewer validated partners.
- Energy cost volatility:Sustained refrigeration for 2°C to 8°C biologics storage exposes operators to electricity price fluctuations without pass-through mechanisms.
Strategic Opportunities
- Cell therapy logistics:Sub-zero cryogenic transport requirements for CAR-T and regenerative medicines represent unmet specialized capacity.
- Baden-Württemberg manufacturing corridor:Underpenetrated 3PL presence relative to Bavaria creates whitespace for multi-temperature zone facilities.
- German Medicines Act amendment:Evolving liability allocation between drug makers and logistics subcontractors may favor certified 3PL operators with documented quality systems.
Industry Challenges
- GDP qualification timelines:Federal Institute for Drugs and Medical Devices inspection backlogs delay market access for new warehouse entrants.
- Real-time monitoring integration:Legacy warehouse management systems require costly upgrades to support continuous temperature logging and automated alert protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Pharmaceutical 3PL Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cold Chain Logistics, Warehousing Solutions, Transportation Services, Packaging & Labeling, Inventory Management Application: Clinical Trial Logistics, Generic Drug Distribution, Biopharmaceutical Supply, OTC Medication Handling, Nutraceutical Transport End User: Pharmaceutical Manufacturers, Biotechnology Firms, Medical Device Companies, Research Organizations, Government Health Agencies Distribution Channel: Hospital Pharmacies, Retail Drugstores, Online Pharmacies, Wholesale Distributors, Specialized Clinics |
| Companies Covered | DB Schenker, Ceva Logistics, DHL Logistics, Dachser, FedEx Logistics, DSV, Rhenus Logistics, UPS, Kuehne + Nagel, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Pharmaceutical 3PL Market Shifts & Advancements
Digital traceability and sustainable refrigeration are converging to reshape capital deployment and service differentiation across German pharmaceutical logistics.
IoT-enabled temperature monitoring is displacing manual logging and periodic checkpoint verification in cold chain operations. Biopharmaceutical manufacturers are mandating real-time data streams for high-value biologics shipments. This shift is compressing competitive differentiation toward telemetry sophistication rather than fleet scale alone.
The EU F-Gas Regulation is forcing refrigeration asset obsolescence across warehouse portfolios. Operators face accelerated depreciation of hydrofluorocarbon-based systems ahead of 2030 phase-down milestones. Bavaria-based cold storage facilities are responding with ammonia refrigeration conversions to maintain operational continuity.
Hospital pharmacy consolidation is concentrating purchasing power and logistics specification authority. Regional pharmacy cooperatives are displacing individual hospital procurement of distribution services. This pattern is most visible in North Rhine-Westphalia, where centralized tendering favors GDP-certified operators with multi-site coverage.
Germany Pharmaceutical 3PL Market Segmentation
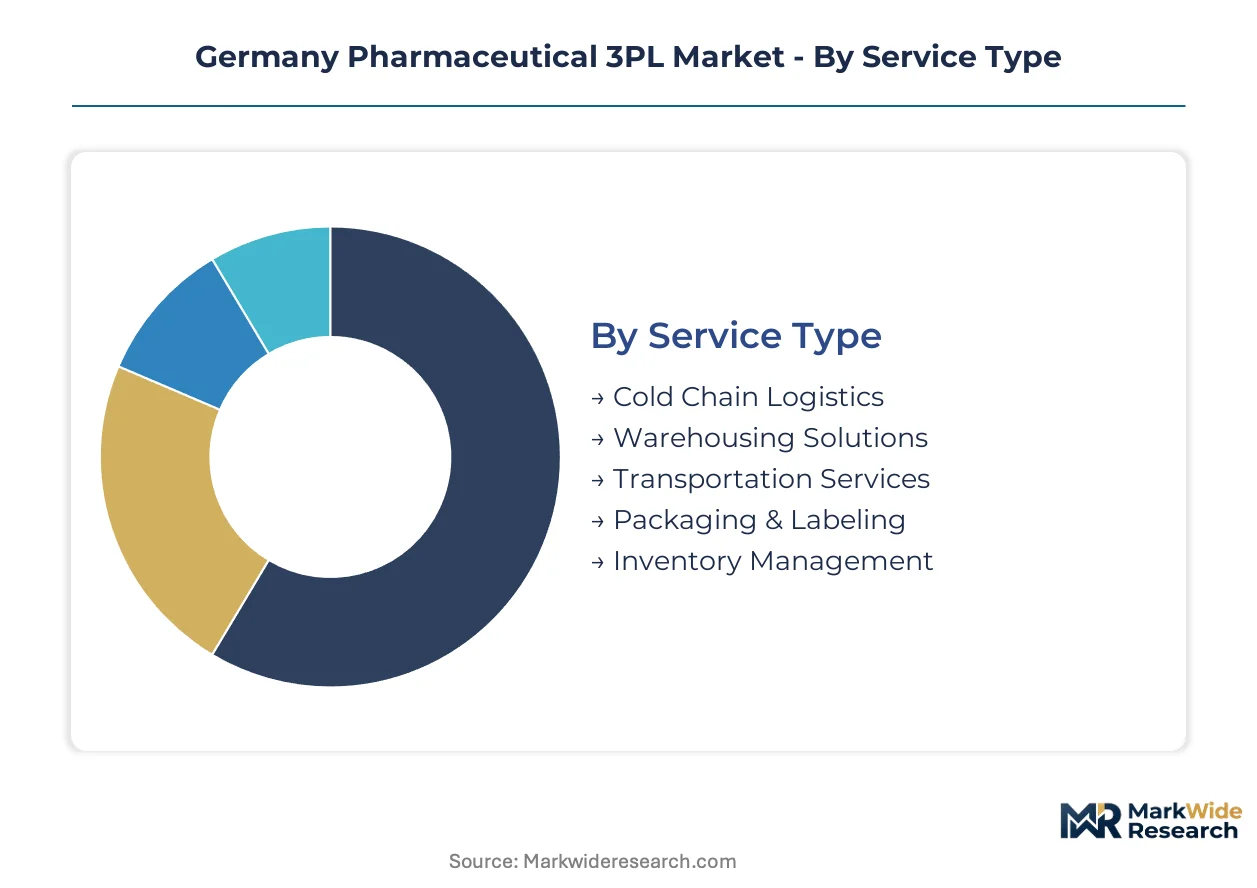
Segmentation in Germany's pharmaceutical 3PL market reflects divergent compliance burdens and capital intensity across service types, with GDP certification requirements reshaping competitive viability in each category. Service providers must match infrastructure investments to the specific temperature and documentation standards demanded by biologics versus generics distribution.
Service Type:
GDP qualification thresholds separate compliant operators from excluded competitors across service categories, with cold chain capabilities commanding premium positioning due to validated infrastructure requirements.
- Cold Chain Logistics:Temperature-controlled transport and storage maintaining 2°C to 8°C for biologics and sub-zero conditions for cell therapies, requiring continuous monitoring and redundant refrigeration systems. Rhine-Ruhr biopharmaceutical manufacturers concentrate demand here, driven by just-in-time delivery requirements to Frankfurt Airport cargo hubs and the EU F-Gas Regulation forcing CO2 refrigeration retrofits.
- Warehousing Solutions:Multi-temperature zone storage facilities serving as the volume backbone for pharmaceutical distribution, with validated cold rooms and ambient storage zones. Bavaria and Baden-Württemberg manufacturing corridors drive facility placement decisions, constrained by Federal Institute for Drugs and Medical Devices inspection backlogs that delay new entrant market access.
- Transportation Services:GDP-certified fleet operations covering road, air, and rail modalities for time-sensitive pharmaceutical movements.
- Packaging & Labeling:Secondary packaging, kitting, and serialization services ensuring regulatory compliance for market entry.
- Inventory Management:Vendor-managed inventory and demand forecasting systems reducing working capital requirements for drug manufacturers.
Established volume favors warehousing solutions; emerging adoption favors cold chain logistics.
Application:
Clinical complexity and product value determine logistics specification intensity, with decentralized trial designs expanding addressable market scope beyond traditional site-based distribution.
- Clinical Trial Logistics:Direct-to-patient and site-to-site temperature-controlled shipments supporting decentralized trial protocols, requiring specialized packaging and real-time tracking. Stuttgart operations centers anchor this segment, with Kuehne + Nagel and competitors investing in patient-centric delivery capabilities as trial designs fragment geographically.
- Generic Drug Distribution:High-volume, lower-margin storage and transport through wholesale distributor channels with standard ambient temperature requirements. North Rhine-Westphalia hospital pharmacy cooperatives concentrate procurement power here, squeezing margins through centralized tendering that favors multi-site GDP-certified operators.
- Biopharmaceutical Supply:Cold chain-dependent logistics for monoclonal antibodies, vaccines, and recombinant proteins with strict stability requirements.
- OTC Medication Handling:Ambient-temperature distribution of non-prescription medicines through retail and online channels.
- Nutraceutical Transport:Cross-border logistics for dietary supplements and functional foods with varying regulatory classifications.
Generic drug distribution commands current volume share; clinical trial logistics is climbing the fastest.
End User:
Outsourcing depth varies by organizational scale and internal logistics asset base, with biotechnology firms showing highest propensity for full-service 3PL engagement.
- Pharmaceutical Manufacturers:Large drug makers converting fixed warehouse and fleet assets to variable costs through comprehensive outsourcing agreements. DB Schenker and DHL Logistics dominate contract awards here, leveraging Frankfurt air freight hub access and multi-temperature zone capacity across southern Germany manufacturing belts.
- Biotechnology Firms:Emerging biopharma companies lacking internal distribution infrastructure, requiring specialized cold chain partners from first commercial launch. Cell therapy developers in the Rhine-Ruhr cluster represent unmet cryogenic transport demand, with sub-zero logistics capabilities still developing.
- Medical Device Companies:Sterile supply chain and implant logistics with distinct temperature and cleanliness protocols.
- Research Organizations:Academic and contract research institutions requiring clinical sample transport and investigational product storage.
- Government Health Agencies:Strategic stockpiling and emergency distribution contracts with stringent security requirements.
Pharmaceutical manufacturers anchor current revenue; biotechnology firms are gaining share fastest.
Distribution Channel:
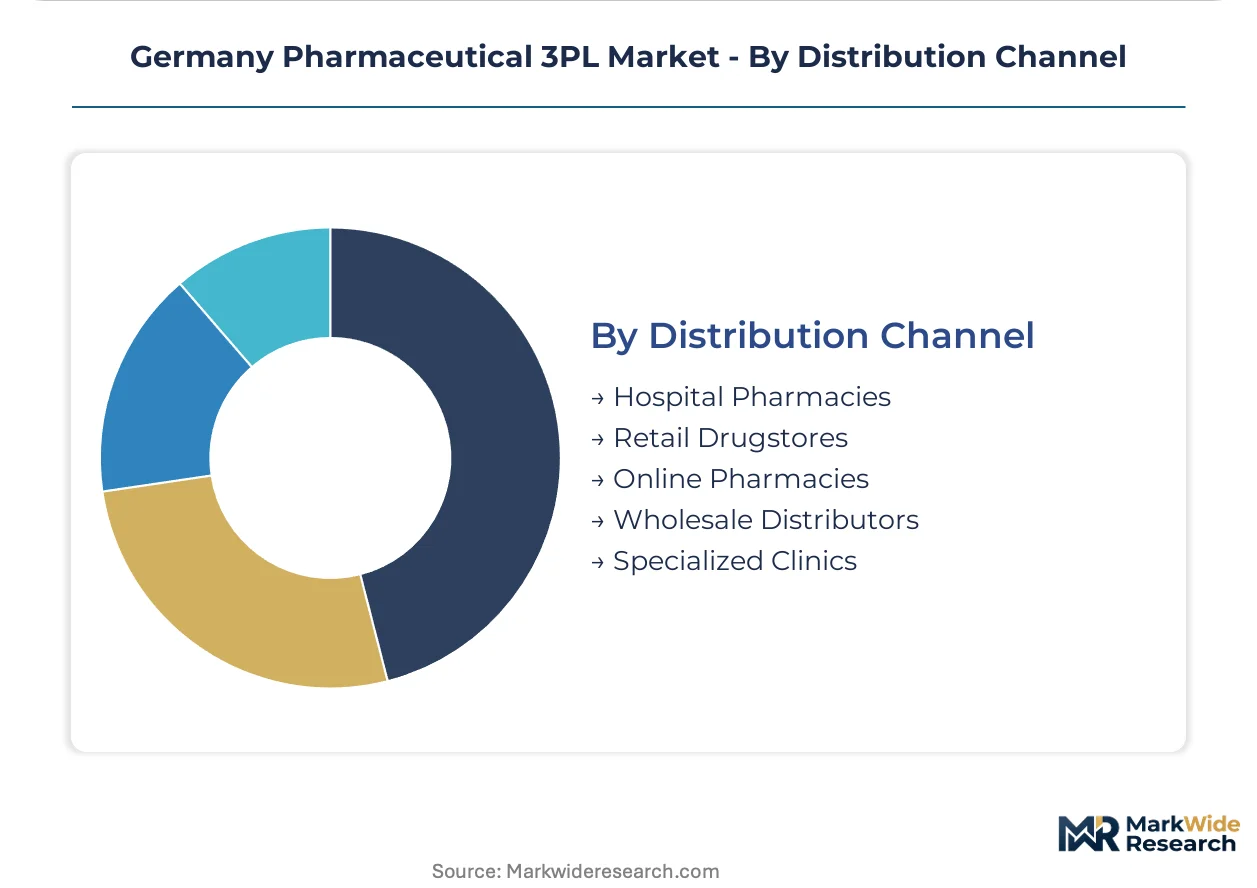
Channel consolidation and e-commerce penetration are reshaping last-mile requirements, with hospital pharmacy centralization and online pharmacy growth driving divergent infrastructure investments.
- Hospital Pharmacies:Centralized purchasing by regional pharmacy cooperatives in North Rhine-Westphalia and other states, requiring GDP-certified operators with multi-site coverage and just-in-time delivery capabilities. Tender specifications increasingly mandate real-time temperature monitoring and automated alert protocols.
- Retail Drugstores:High-frequency, small-batch distribution to pharmacy chains with strict delivery window compliance.
- Online Pharmacies:Direct-to-consumer shipment growth demanding parcel-level cold chain solutions and signature-verified delivery.
- Wholesale Distributors:Bulk consolidation points for generic drug flows with efficiency-focused logistics requirements.
- Specialized Clinics:Direct delivery to outpatient infusion centers and specialized care facilities with patient appointment synchronization.
Wholesale distributors maintain volume dominance; online pharmacies show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biopharmaceutical manufacturers concentrate procurement authority near manufacturing clusters and airport cargo infrastructure, driving 3PL contract consolidation toward qualified operators with validated cold chain capabilities across southern and western Germany.
North Rhine-Westphalia
Hospital pharmacy cooperatives in Düsseldorf and Cologne centralize tendering for generic drug distribution, mandating GDP certification and multi-site coverage. The Federal Institute for Drugs and Medical Devices enforces compliance through facility inspections that determine contract eligibility. The Rhine-Ruhr pharmaceutical cluster leverages proximity to Frankfurt Airport for just-in-time biopharmaceutical deliveries.
Bavaria
Monoclonal antibody and vaccine manufacturers in Munich and Nuremberg require multi-temperature zone warehousing with redundant refrigeration systems. The EU F-Gas Regulation accelerates warehouse modernization toward CO2 and ammonia cooling systems. Bavaria-based cold storage facilities face accelerated depreciation of hydrofluorocarbon assets ahead of 2030 phase-down milestones.
Baden-Württemberg
Clinical trial logistics demand expands around Stuttgart and Mannheim as decentralized protocols fragment patient recruitment geographically. The German Medicines Act amendment shifts liability considerations between drug makers and logistics subcontractors. Stuttgart operations centers anchor specialized direct-to-patient temperature-controlled shipment capabilities.
Hesse
Frankfurt Airport cargo infrastructure enables time-sensitive biopharmaceutical flows to European and intercontinental destinations. The EU GDP revision tightens qualification requirements for warehouse operators serving export markets. The Frankfurt-Rhine-Main logistics corridor concentrates air freight capacity for temperature-sensitive cell therapies and biologics.
Lower Saxony
Generic pharmaceutical manufacturing in Hanover and Braunschweig drives volume demand for ambient-temperature warehousing and wholesale distribution. Energy cost volatility exposes mid-scale warehouse operators to electricity price fluctuations without full pass-through mechanisms. The region's pharmaceutical production base supports consolidation trends favoring GDP-certified operators with scale efficiencies.
Germany Pharmaceutical 3PL Market Competitive Landscape
Player mix skews toward diversified logistics conglomerates with pharmaceutical-specialized divisions, creating a tiered structure where GDP certification separates qualified operators from excluded regional carriers. Three strategic archetypes dominate: integrated freight forwarders with air hub control, specialized healthcare logistics divisions, and regional carriers pursuing certification upgrades. Competitive moves concentrate on M&A to acquire GDP-compliant facilities and strategic partnerships to secure Frankfurt air freight capacity.
Among integrated freight forwarders, DB Schenker, DHL Logistics, and Kuehne + Nagel exemplify the archetype of operators leveraging airport hub access and multi-temperature zone networks. DB Schenker occupies a position tied to Frankfurt air freight dominance. DHL Logistics represents scale-driven capacity across southern manufacturing corridors. Kuehne + Nagel anchors clinical trial specialization through dedicated operations infrastructure. These three sit within the premium tier where GDP certification and validated cold chain capabilities determine contract access.
| Leading Market Players |
|---|
| DB Schenker |
| Ceva Logistics |
| DHL Logistics |
| Dachser |
| FedEx Logistics |
| DSV |
| Rhenus Logistics |
| UPS |
| Kuehne + Nagel |
| Others |
Supply & Pricing Matrix
Facility scale economies across the Rhine-Ruhr corridor compress unit costs for GDP-certified operators while erecting price floors that exclude sub-scale competitors from hospital pharmacy tenders. Frankfurt Airport cargo concentration amplifies this dynamic, as just-in-time cold chain capabilities require dedicated refrigeration assets that amortize across high-throughput volumes.
Pricing Analysis
Cost-plus contracts with energy indexation dominate pharmaceutical 3PL agreements, passing through electricity volatility while capping operator margins. Price differentiation rests on GDP certification tier and real-time monitoring capability, with certified cold chain operators commanding premium positioning over ambient-only competitors. Cost compression in generic drug distribution intensifies as North Rhine-Westphalia pharmacy cooperatives consolidate tendering power. Biotechnology firms show lowest price sensitivity due to product integrity requirements, while wholesale distributors face acute margin pressure.
Supply Chain Analysis
Germany anchors pharmaceutical manufacturing across Bavaria and Baden-Württemberg, producing monoclonal antibodies, vaccines, and cell therapies that demand validated cold chain infrastructure. The supply chain draws from specialized refrigeration equipment manufacturers in Denmark and industrial gas suppliers for cryogenic transport. Single-source vulnerability concentrates in qualified GDP-certified carrier capacity, where Federal Institute for Drugs and Medical Devices inspection backlogs constrain new entrant expansion. Distribution runs through hospital pharmacy cooperatives in North Rhine-Westphalia and wholesale distributor consolidation points for generic flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Validated cold chain capability scarcity separates contract-eligible operators from excluded regional carriers, with GDP certification backlogs and refrigeration retrofit requirements compounding the asset gap.
For Market Incumbents: Compound Frankfurt air freight hub control through dedicated temperature-controlled capacity expansion, defending against specialized healthcare logistics divisions encroaching on biopharmaceutical flows. Prioritize ammonia refrigeration conversions ahead of EU F-Gas Regulation phase-down milestones to maintain operational continuity. Secure multi-year contracts with Rhine-Ruhr biotechnology clusters to lock in cell therapy logistics demand. For New Entrants and Emerging Players: Lead with clinical trial logistics specialization in Baden-Württemberg, where decentralized protocol expansion outpaces incumbent direct-to-patient capabilities. Target underpenetrated Stuttgart-area operations with GDP-certified facilities positioned for patient-centric delivery. Differentiate through sub-zero cryogenic transport capacity for CAR-T developers. For Investors and Strategic Acquirers: Mid-scale GDP-certified warehouse operators with ammonia refrigeration assets and established Federal Institute for Drugs and Medical Devices inspection records represent priority acquisition targets. Long-term viability hinges on regulatory compliance durability rather than scale alone. Monitor German Medicines Act amendment implementation as liability allocation inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| GDP Certification Investment | Federal Institute for Drugs and Medical Devices qualification unlocks hospital pharmacy contract eligibility. |
| Refrigeration Retrofit Program | CO2 and ammonia system conversions maintain operational continuity under EU F-Gas Regulation phase-down. |
| Clinical Trial Logistics Expansion | Direct-to-patient capabilities capture decentralized protocol demand beyond traditional site-based distribution. |
| Multi-Temperature Zone Facility Buildout | Baden-Württemberg manufacturing corridor presence addresses whitespace relative to Bavaria saturation. |
| Real-Time Monitoring Integration | IoT-enabled telemetry meets biopharmaceutical manufacturer mandates for continuous cold chain visibility. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pharmaceutical logistics directors, biopharmaceutical supply chain executives, hospital pharmacy procurement managers, and cold chain operations specialists. Secondary validation drew from Federal Institute for Drugs and Medical Devices inspection records, EU GDP regulatory filings, EMA distribution guidance documents, and trade customs data. Bottom-up facility capacity assessments and top-down pharmaceutical production value estimates were triangulated to establish market boundaries.
Across the analysis window, forecasts modeled service type segmentation by temperature requirement and compliance burden, application segmentation by clinical complexity and product value, end user segmentation by outsourcing depth and internal asset base, and regional segmentation by manufacturing cluster proximity and airport cargo access. CAGRs were derived from pharmaceutical production growth trajectories, clinical trial protocol expansion patterns, and regulatory compliance investment cycles. Energy cost volatility and GDP certification timeline assumptions shaped scenario boundaries.
The analysis sits within stated boundaries; outcomes outside sustained EU F-Gas Regulation enforcement, stable electricity pricing frameworks, or unchanged German Medicines Act liability provisions would require recalibration. Forecasts reflect documented assumptions regarding inspection backlog resolution rates and biotechnology manufacturing expansion trajectories. Recalibration cycles align with material shifts in regulatory enforcement intensity and pharmaceutical outsourcing preference patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Epigenetics Drugs and Diagnostic Technologies Market
Pharmaceuticals
Opium Tincture Market
Pharmaceuticals
Targeted Liposomes Drug Delivery Market
Pharmaceuticals
India Opioids Market
Pharmaceuticals
France Diabetes Drugs Market
Pharmaceuticals
Bacterial Vaginosis Treatment Market
Pharmaceuticals
3D Printing Drug Market
Pharmaceuticals
Asia-Pacific Anesthesia Drugs Market
Pharmaceuticals
Azathioprine API Market
Pharmaceuticals
Cough Oral Solution Market
Pharmaceuticals
Europe Sodium-Dependent Glucose Cotransporter 2 Market
Pharmaceuticals
Global Novel Drug Delivery Systems (NDDS) Market
Pharmaceuticals
Global Hormonal Contraceptives Market
Pharmaceuticals
Retinal Drugs and Biologics Market
Pharmaceuticals
Lipid Injectable Market
Pharmaceuticals
Theophylline and Aminophylline Market