
 Intraoral Dental Scanner Market | 2026-2036
Intraoral Dental Scanner Market Size, Share, and Industry Trends Forecast 2026-2036
Intraoral Dental Scanner Market Insights
Buyer consolidation among multi-location dental service organizations is restructuring procurement patterns across the scanner installed base. Dentsply Sirona leverages its chairside ecosystem to sustain recurring consumable revenue from scanner users. 3Shape anchors its position through open-architecture software that interoperates with third-party milling systems. Shining 3D competes aggressively on hardware cost, extending its reach into price-sensitive clinic networks across Asia and Latin America.
An intraoral dental scanner captures three-dimensional surface geometry of teeth and soft tissues through non-contact optical or laser-based measurement, typically achieving accuracy thresholds of 10-50 micrometers for clinical-grade restorations. The device eliminates physical impression materials, reducing patient discomfort and laboratory turnaround times for crown, bridge, and aligner fabrication. Handheld scanners dominate current shipment volumes while wireless variants represent the fastest-expanding configuration category as practices prioritize mobility and infection control protocols. Optical scanning technology occupies the largest installed base, though structured light approaches are gaining share in premium segments where speed and full-arch capture reliability determine purchasing decisions.
The FDA regulates these devices as Class II medical devices under 510(k) premarket notification, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for new scanner introductions across European markets. ISO 12836 standards govern accuracy testing protocols, shaping manufacturer R&D priorities and creating compliance barriers for entrants lacking metrology validation infrastructure. Stakeholders must monitor evolving cybersecurity requirements for networked scanner-to-cloud workflows as patient data transmission becomes integral to digital dentistry platforms.
Market Dynamics
Dental service organization consolidation is restructuring procurement authority away from individual practitioners toward centralized purchasing committees that negotiate enterprise-wide scanner deployments and locked-in consumable contracts.
Growth Catalysts
- MDR Compliance Deadlines:The EU Medical Device Regulation's 2024-2026 transition window is forcing clinic upgrades to certified digital impression systems, accelerating replacement cycles across Germany, France, and Italy.
- Chairside Milling Integration:Same-day crown fabrication workflows are pulling scanner adoption into general dentistry practices previously served exclusively by laboratory outsourcing.
- Clear Aligner Volume Surge:Orthodontic case volumes for transparent aligner therapy are expanding scanner utilization beyond restorative applications into treatment planning and monitoring stages.
Market Restraints
- Optical Component Supply Concentration:Specialized CMOS sensors and precision optics for sub-20-micron accuracy depend on a limited supplier base concentrated in East Asian manufacturing clusters.
- 510(k) Clinical Evidence Burden:FDA's evolving expectations for comparative effectiveness data against predicate devices are extending clearance timelines and inflating regulatory submission costs.
- Physical Impression Persistence:Alginate and polyether materials retain cost advantages for full-denture cases and certain edentulous arch captures, limiting scanner addressable market.
Strategic Opportunities
- Tele-dentistry Infrastructure:Remote consultation platforms are creating demand for home-use scanning peripherals that transmit diagnostic data to centralized treatment planning hubs.
- AI-Assisted Caries Detection:Convolutional neural networks trained on intraoral scan datasets are enabling automated pathology flagging, opening subscription revenue streams adjacent to hardware sales.
- India's PLI Scheme:Production-linked incentives for medical device manufacturing are attracting assembly investments that could localize supply for South Asian and Middle Eastern clinic networks.
Industry Challenges
- CAD/CAM Workflow Certification:Technician training bottlenecks for digital design software are creating implementation delays even where hardware procurement budgets exist.
- Cybersecurity Validation:Cloud-connected scanner architectures require HIPAA-compliant data transmission protocols that smaller manufacturers struggle to architect without third-party infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intraoral Dental Scanner Market |
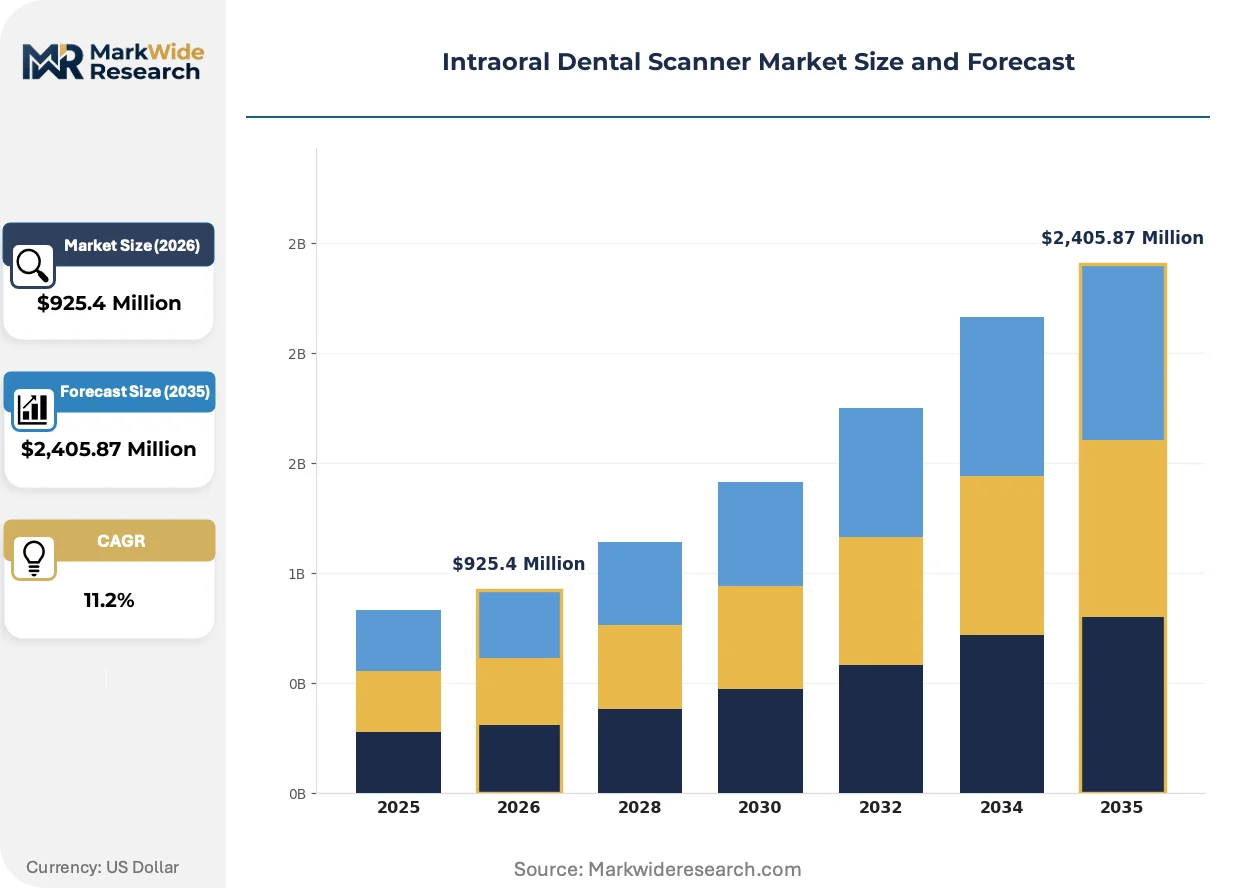
| Market Size in 2026 | $925.4 Million |
| Market Size in 2035 | $2,405.87 Million |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Scanners, Tabletop Scanners, Wireless Scanners, Extraoral Scanners Technology: Optical Scanning, Laser Scanning, Structured Light, Triangulation End User: Dental Clinics, Hospitals, Research Institutions, Laboratories Application: Orthodontics, Prosthodontics, Cosmetic Dentistry, Implantology |
| Companies Covered | Medit Corp., Carestream Dental, Dentsply Sirona, Dental Wings, Straumann Group, Align Technology, Planmeca Oy, Shining 3D, 3Shape, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intraoral Dental Scanner Market Trends and Innovations
Digital dentistry platforms are absorbing adjacent diagnostic functions, transforming standalone scanning hardware into nodes within integrated treatment ecosystems that span imaging, design, and production.
Structured light projection is converging with confocal microscopy in hybrid scanning architectures that capture both surface geometry and subsurface enamel characteristics. Premium segment buyers in the United States and Switzerland are adopting these multi-modal systems for complex aesthetic cases. The technology convergence is compressing the distinction between diagnostic imaging and restorative impression capture, consolidating capital equipment footprints.
REACH restrictions on fluorinated polymers are compelling manufacturers to reformulate scanner housing materials and cable sheathing ahead of 2025 enforcement deadlines. Industrial designers are pivoting toward glass-filled thermoplastics and bio-based alternatives that maintain sterilization durability. European manufacturers face accelerated R&D timelines compared to counterparts in jurisdictions without equivalent chemical restrictions.
Group purchasing organizations are aggregating scanner procurement across multi-state dental practice networks, displacing individual clinic vendor relationships with centralized contract administration. Equipment lessors and managed service providers are capturing placement decisions previously controlled by practice owners. This channel transformation is most visible in the United States where dental support organizations now influence scanner selection for thousands of affiliated locations.
Intraoral Dental Scanner Market Segmentation
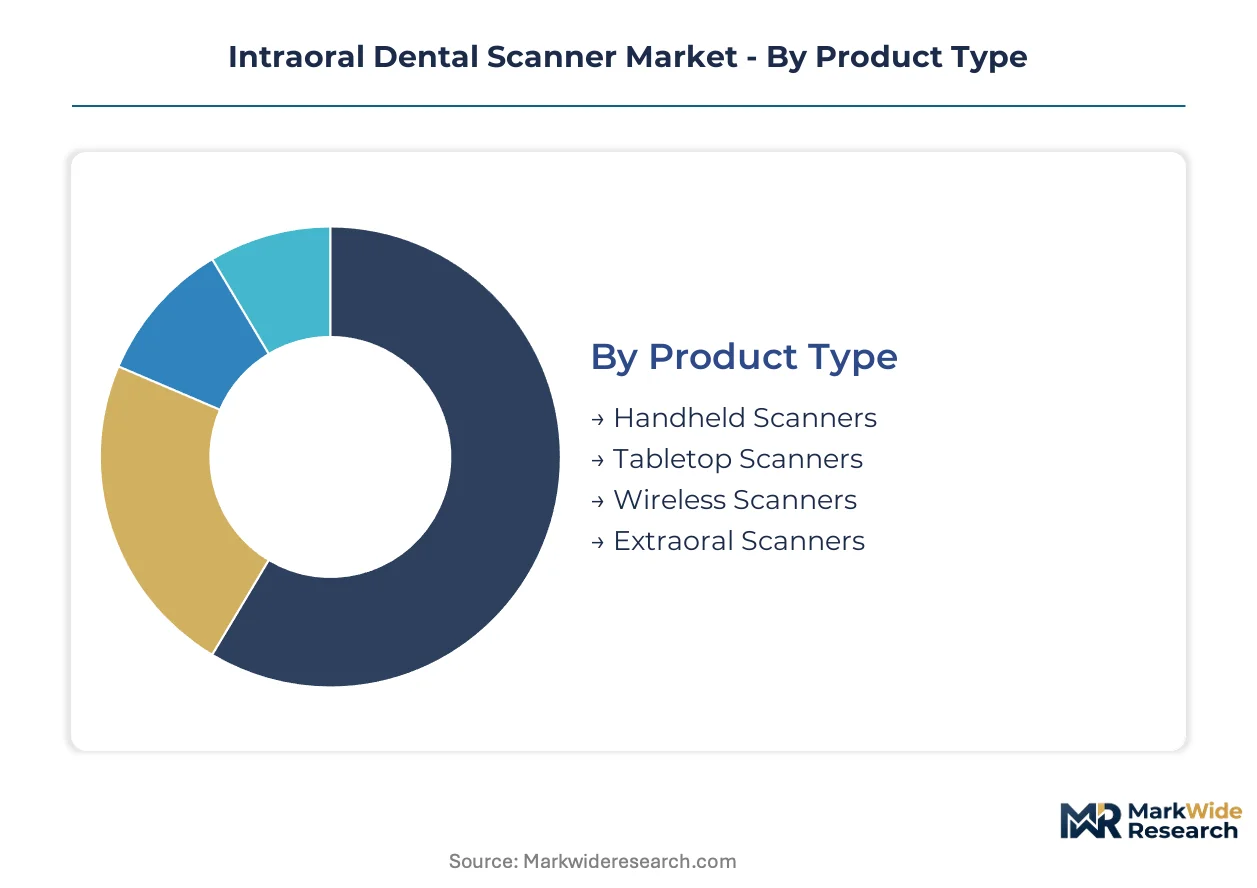
Scanner procurement patterns diverge sharply across hardware configurations, optical architectures, and clinical workflows. Understanding these fault lines exposes where margin pools concentrate and which technology transitions threaten incumbent positions.
Product Type:
Supply concentration for precision optical assemblies favors manufacturers with captive CMOS sensor sourcing and in-house calibration infrastructure.
- Handheld Scanners:Pistol-grip form factors integrate confocal microscopy arrays into sub-400-gram enclosures for direct intraoral manipulation. Dental clinics across the United States and Germany account for the dominant installed base, driven by ergonomic demands in high-volume restorative practices where operator fatigue determines throughput ceilings.
- Wireless Scanners:Battery-powered variants eliminate tethered cable constraints and simplify sterilization protocols between patients. Demand concentrates in group dental practices prioritizing operatory flexibility, with procurement committees favoring sealed-unit designs that withstand autoclave cycles without connector degradation.
- Tabletop Scanners:Stationary benchtop units process plaster casts and impression materials for laboratory workflows.
- Extraoral Scanners:Facial-arch capture systems support orthodontic treatment planning and orthognathic surgery simulation.
Today's leader: Handheld Scanners. Tomorrow's challenger: Wireless Scanners.
Technology:
Cost tier differentiation separates premium systems with sub-10-micron accuracy from mid-range offerings serving general dentistry price sensitivity.
- Optical Scanning:Confocal imaging and active wavefront sampling dominate current shipment volumes through mature supply chains for LED illumination modules and precision optics. ISO 12836 validation protocols favor established metrology laboratories in Switzerland and Japan, creating certification barriers for new entrants lacking traceable accuracy documentation.
- Structured Light:Projected pattern triangulation achieves full-arch capture speeds under 60 seconds, commanding premium positioning in aesthetic-focused practices. Demand clusters in Swiss and US metropolitan markets where same-day crown fabrication workflows justify capital intensity.
- Laser Scanning:Coherent light sources penetrate translucent enamel for subsurface feature detection in caries assessment applications.
- Triangulation:Stereoscopic camera arrays offer cost-engineered alternatives for entry-level digital impression systems.
Premium positioning favors Structured Light. Volume scaling depends on Optical Scanning cost curves.
End User:
Customer type fragmentation creates divergent purchasing rhythms between capital-constrained independents and centralized procurement at multi-location networks.
- Dental Clinics:Solo and small-group practices drive replacement cycles for aging optical impression systems, with purchasing authority shifting toward dental service organization administrators who negotiate enterprise-wide scanner deployments and locked-in consumable contracts across hundreds of affiliated locations.
- Hospitals:Academic medical centers and oral surgery departments integrate scanners into multidisciplinary craniofacial treatment planning, with procurement governed by biomedical engineering committees prioritizing interoperability with PACS infrastructure and EMR systems.
- Laboratories:Commercial dental labs deploy benchtop systems for die scanning and restoration verification.
- Research Institutions:Universities and teaching hospitals utilize metrology-grade systems for validation studies and algorithm development.
Consolidation is concentrating volume with Dental Clinics. Hospitals represent the stickiest long-term contracts.
Application:
Application maturity determines whether scanner utilization expands treatment capacity or merely displaces analog workflows.
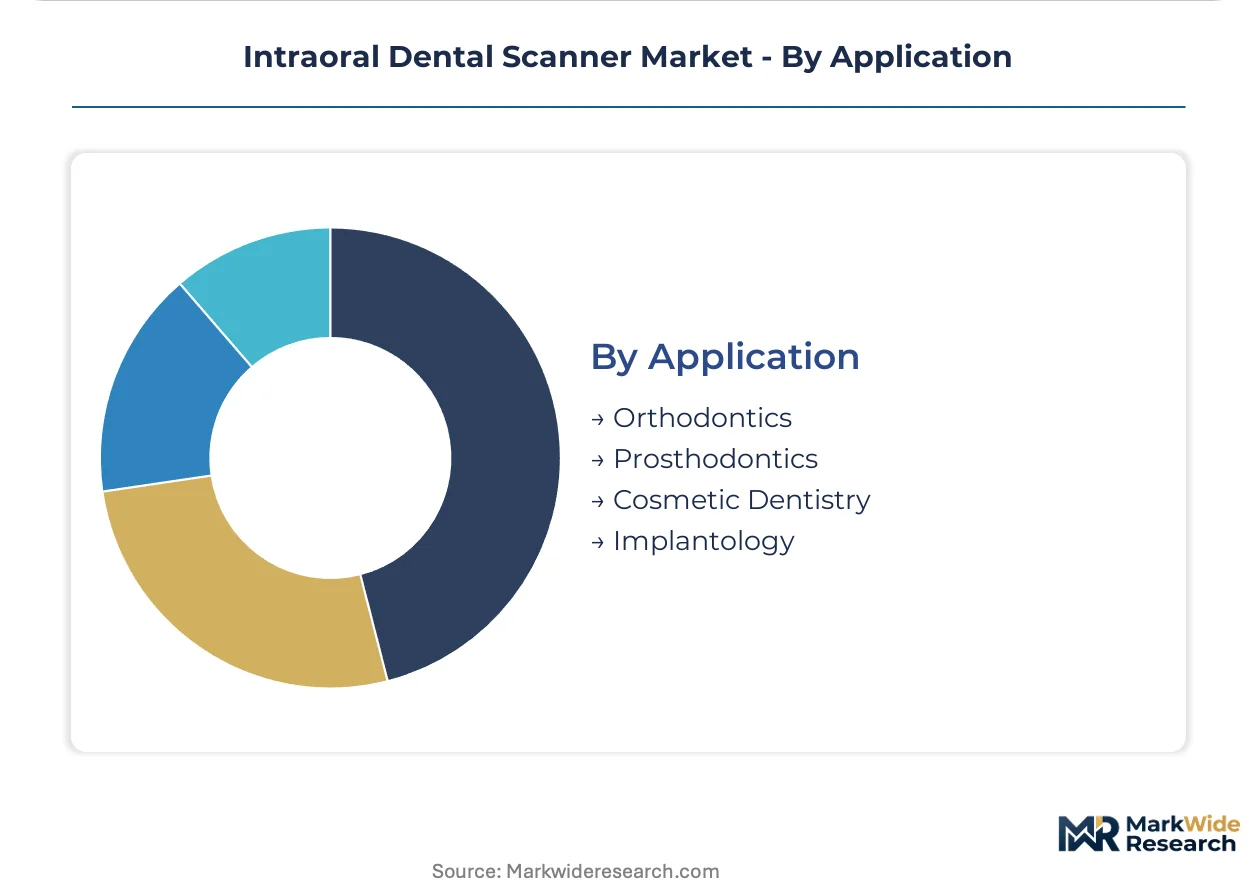
- Orthodontics:Clear aligner therapy has transformed scanner deployment from diagnostic adjunct to production-critical infrastructure, with case submission volumes requiring weekly scan throughput that strains wired-system workflows and drives wireless upgrade decisions at high-volume practices.
- Prosthodontics:Crown and bridge fabrication remains the core revenue justification for scanner acquisition, with chairside milling integration compressing turnaround from two weeks to single-visit delivery and recapturing laboratory margin into practice economics.
- Implantology:Surgical guide fabrication and prosthetic-driven planning require sub-50-micron accuracy thresholds.
- Cosmetic Dentistry:Veneer and aesthetic restoration planning leverages scan data for digital smile design visualization.
Orthodontics is expanding the addressable base. Prosthodontics defends the core margin pool.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Scanner procurement intensity diverges sharply between the United States and Germany, with American group practices driving enterprise-scale deployments while German clinics navigate stricter MDR compliance timelines.
United States
Dental service organization consolidation is concentrating purchasing authority across multi-state networks, with centralized committees negotiating locked-in consumable contracts. The FDA's 510(k) clearance pathway accelerates product entry for manufacturers meeting predicate device benchmarks. Dallas and Phoenix metropolitan clusters host the densest scanner installed bases among high-volume group practices.
Germany
EU Medical Device Regulation transition deadlines through 2026 are forcing clinic upgrades to certified digital impression systems across Bavaria and North Rhine-Westphalia. The BfArM enforces stricter clinical evidence requirements than predecessor directives, extending validation timelines for new entrants. Stuttgart's precision optics manufacturing corridor supplies calibration infrastructure for metrology-grade systems serving premium dental laboratories.
China
Domestic manufacturers are capturing price-sensitive clinic networks through localized assembly and reduced import duty exposure. The NMPA's Class II medical device registration process is streamlining for digital dentistry equipment amid national oral health initiative expansion. Shenzhen's electronics manufacturing ecosystem supports CMOS sensor sourcing for sub-20-micron accuracy systems targeting tier-two city dental chains.
Switzerland
Aesthetic-focused practices in Zurich and Geneva command premium positioning for multi-modal hybrid scanners integrating structured light with confocal microscopy. Swissmedic maintains alignment with EU MDR standards while preserving faster market access for CE-marked devices. The Basel pharmaceutical-industrial corridor is spawning dental technology spinoffs leveraging existing precision manufacturing capabilities.
India
Production-linked incentive schemes for medical device manufacturing are attracting assembly investments targeting South Asian and Middle Eastern export markets. The CDSCO is harmonizing device classification with international standards to reduce regulatory fragmentation. Mumbai and Bangalore dental chains are piloting scanner-to-cloud workflows for aligner therapy case submission.
Intraoral Dental Scanner Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The installed base concentrates among three to four manufacturers with captive consumable ecosystems, while mid-tier challengers compete on hardware cost and open-architecture interoperability. Strategic archetypes include chairside ecosystem integrators, open-platform software anchors, and price-disrupting hardware specialists. Competitive moves center on M&A for digital workflow consolidation and strategic partnerships with clear aligner manufacturers for case volume capture.
Among ecosystem-integrated conglomerates, Dentsply Sirona and Align Technology exemplify archetypes leveraging recurring consumable revenue and orthodontic case flow respectively. Shining 3D occupies a position among cost-engineered hardware specialists competing aggressively in price-sensitive clinic networks across Asia and Latin America.
| Leading Market Players |
|---|
| Medit Corp. |
| Carestream Dental |
| Dentsply Sirona |
| Dental Wings |
| Straumann Group |
| Align Technology |
| Planmeca Oy |
| Shining 3D |
| 3Shape |
| Others |
Pricing and Supply Chain Analysis
Wireless scanner adoption is compressing manufacturing cost curves while simultaneously redistributing optical component demand toward East Asian sensor foundries. This technology transition concentrates supply leverage among CMOS manufacturers in Taiwan and South Korea, enabling tier-one brands to extract volume discounts that mid-tier competitors cannot match.
Pricing Analysis
Capacity additions in Shenzhen and Dongguan are reshaping price floors for entry-level handheld units. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared systems with ISO 12836 validation from uncertified alternatives. Price differentiation hinges on metrology-grade accuracy certification and captive consumable ecosystem lock-in. Pricing pressure stems from Shining 3D's aggressive hardware cost positioning in Latin American and Southeast Asian clinic networks. Solo practitioners in India and Brazil exhibit highest price sensitivity, while Swiss and American group practices prioritize workflow integration over acquisition cost.
Supply Chain Analysis
Dual-sourcing mandates from DSO procurement committees require qualified secondary suppliers for precision optics and CMOS sensors. Geographic supply concentration centers on Taiwan for semiconductor fabrication, Japan for metrology-grade calibration equipment, and Germany for precision mechanical assemblies. Raw material dependencies include fluoropolymer cable sheathing facing REACH restriction deadlines, rare-earth phosphors for LED illumination modules, and borosilicate glass for optical windows. Single-source vulnerability persists for sub-20-micron accuracy CMOS arrays from specialized foundries. Distribution runs through dental supply distributors and direct manufacturer sales teams serving group purchasing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Manufacturers can exploit arbitrage between the FDA's streamlined 510(k) pathway and the EU MDR's stricter clinical evidence requirements, front-loading American market entry while European competitors absorb validation delays.
For Market Incumbents: Anchor consumable revenue streams through chairside milling ecosystem lock-in and software subscription tiers that raise switching costs for affiliated clinic networks. Defend against open-architecture challengers by acquiring specialized CAD/CAM software firms. Prioritize backward integration into CMOS sensor sourcing to neutralize East Asian supply leverage. For New Entrants and Emerging Players: The $8,000-$15,000 price-point gap between premium structured-light systems and economy optical scanners creates white-space opportunity for mid-tier hybrid architectures. Target Indian dental chains benefiting from PLI scheme localization and Middle Eastern clinic networks seeking CE-marked alternatives to American brands. Pursue aligner manufacturer partnerships for case volume commitment that justifies hardware subsidy models. For Investors and Strategic Acquirers: Roll-up economics work for dental technology platforms because DSO consolidation concentrates procurement authority and creates captive distribution channels for acquired scanner portfolios. Five-to-ten year viability favors manufacturers with software recurring revenue exceeding hardware dependency. Monitor FDA 510(k) clearance velocity for Chinese entrants as inflection indicator for pricing pressure trajectory in American markets.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerated market entry enables first-mover capture of DSO procurement cycles before MDR-constrained European rivals. |
| CE Marking Pathway | MDR clinical evidence requirements extend validation timelines, favoring incumbents with existing technical documentation. |
| Hospital System Partnership | Academic medical center integration anchors craniofacial surgery workflows and resident training program adoption. |
| Software Companion Development | AI-assisted caries detection modules create subscription revenue streams adjacent to capital hardware sales. |
| Reimbursement Strategy | Aligner therapy coverage expansion by commercial payers directly expands scanner utilization in orthodontic practices. |
Research Methodology
Direct dialogue with dental service organization procurement directors, biomedical engineers at academic medical centers, GPO contracts managers, and regulatory affairs specialists at scanner manufacturers grounded qualitative findings. Secondary validation drew from FDA 510(k) premarket notification database, EU MDR technical documentation filings, hospital procurement contract disclosures, and ISO 12836 metrology validation records. Bottom-up shipment estimates triangulated against top-down dental clinic digital adoption benchmarks.
Installed base projections and revenue forecasts across the analysis window reflect segment-level modeling of hardware configuration, optical architecture, and end-user procurement authority dimensions. CAGRs derived from replacement cycle analysis of aging optical impression systems and penetration modeling for wireless variants in group practice networks. Forecast inputs incorporated clear aligner case volume trajectories and EU MDR compliance-driven replacement deadlines.
Caveats apply where FDA evidentiary requirement evolution or REACH fluoropolymer enforcement delays could materially shift the outlook. Deviation in DSO consolidation velocity or CMOS sensor supply disruption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Dental Implants and Abutment Systems Market
Dental Devices
Global Dental Burs Market
Dental Devices
Middle East and Africa Dental Lab Market
Dental Devices
Global Digital Dentistry Market
Dental Devices
Dental Microsurgery Market
Dental Devices
Dental Air Polishers Market
Dental Devices
Asia Pacific Acrylic Teeth Market
Dental Devices
Dental Composite Resin Filling Market
Dental Devices
Global Professional Teeth Whitening and Power Toothbrushes Market
Dental Devices
Dental Anaesthetic Market
Dental Devices
Chile Dental Market
Dental Devices
Dental Diamond Burs Market
Dental Devices
Surgical Dental Loupes and Camera Market
Dental Devices
Saudi Arabia Dental Devices Market
Dental Devices
Asia-Pacific Dental Aligners Market
Dental Devices
GCC Dental Implants Market