
 Saudi Arabia Dental Devices Market | 2026-2036
Saudi Arabia Dental Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Dental Devices Market Analytics
Digital dentistry is tilting the technology stack toward intraoral scanning and CAD/CAM workflows that replace conventional physical impressions. Dentsply Sirona leverages its integrated imaging and milling ecosystem to anchor premium positioning in Saudi dental clinics. Institut Straumann AG specializes in implantology and digital prosthetic solutions that compete directly with regional distributors of European systems.
Dental devices encompass instruments, consumables, equipment, and implants engineered from biocompatible ceramics, titanium alloys, and polymer composites for oral diagnosis, treatment, and restoration. The primary commercial purpose centers on enabling precise, repeatable clinical outcomes while reducing chair time and material waste. Equipment and implants capture the deepest margin pools as hospitals and specialized clinics in Riyadh prioritize advanced imaging and osseointegration technologies. Consumables sustain higher turnover velocity through recurring purchases of bonding agents, impression materials, and sterilization products across the clinic network.
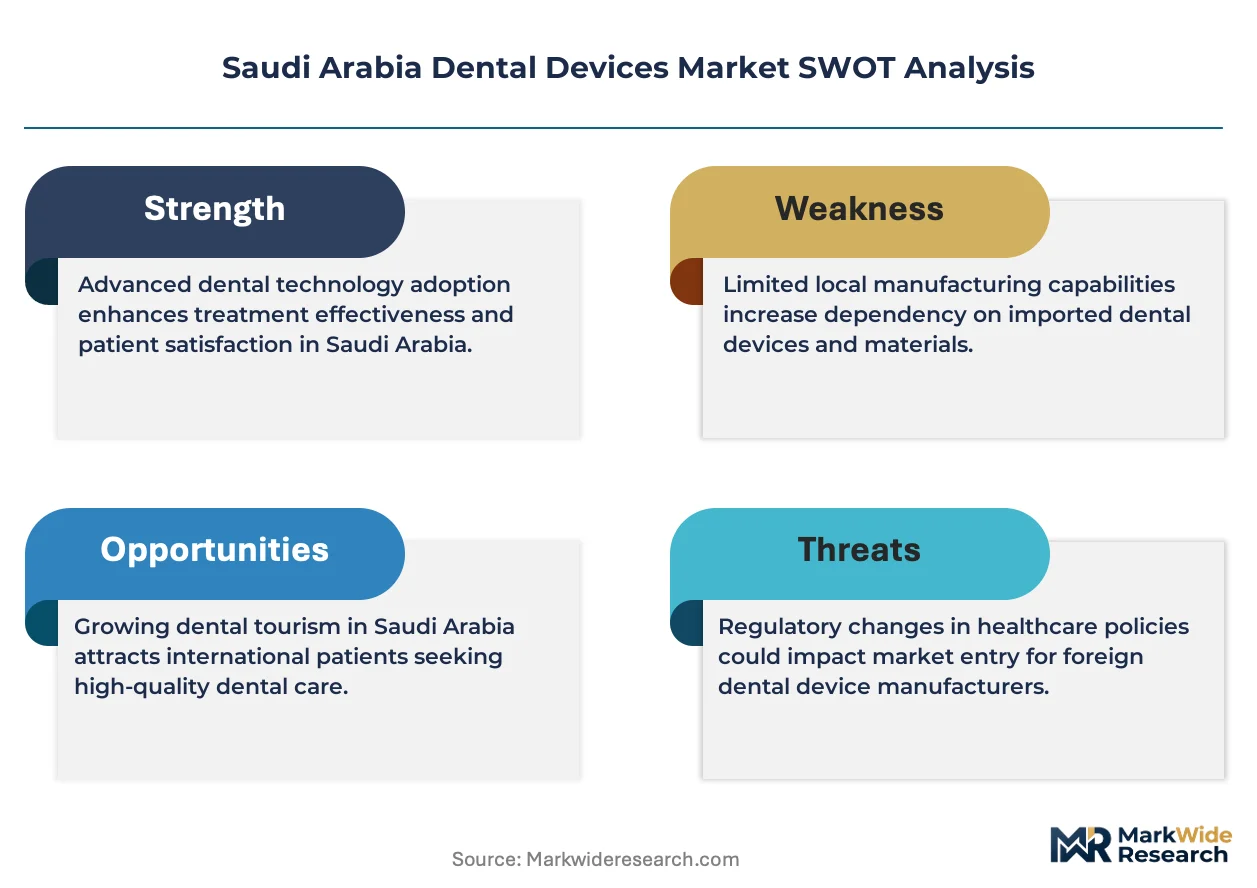
SFDA medical device registration requirements and SASO technical conformity standards govern market access, compelling manufacturers to establish local authorized representatives and quality management systems. The NIDLP localization incentives and increasing preference for direct sales channels reshape how foreign suppliers structure distribution and service capabilities. Stakeholders must monitor evolving reimbursement frameworks under the Health Sector Transformation Program and assess whether to deepen local assembly partnerships or maintain pure import models.
Market Dynamics
The Saudi dental devices sector is pivoting around the Health Sector Transformation Program's push toward private-sector care delivery, which concentrates capital investment in Riyadh and Jeddah clinic networks while tightening SFDA compliance requirements for imported equipment.
Growth Catalysts
- SFDA Medical Device Registration Streamlining:The regulator's risk-based classification system accelerates approvals for Class II imaging equipment, reducing time-to-market for digital intraoral scanners targeting private dental chains.
- Central Province Clinic Density:Riyadh's concentration of specialized implantology centers drives recurring demand for titanium alloy fixtures and CAD/CAM milling units that integrate with existing chairside workflows.
- NIDLP Localization Incentives:The National Industrial Development and Logistics Program offers tariff relief and land allocation for foreign manufacturers establishing Saudi-based assembly operations for consumables and sterilization products.
Market Restraints
- Import Dependency for Precision Components:Ceramic milling burs and optical scanning sensors rely on German and Swiss suppliers, exposing distributors to euro-denominated cost volatility and extended lead times.
- SASO Technical Conformity Complexity:The Saudi Standards, Metrology and Quality Organization's electromagnetic compatibility testing requirements for digital radiography units create bottlenecks that delay clinic equipment upgrades.
- Polymer Composite Substitution Pressure:Zirconia-reinforced lithium silicate ceramics are displacing traditional PFM restorations in premium cosmetic segments, compressing margins for conventional alloy suppliers.
Strategic Opportunities
- Eastern Province Underpenetration:Dammam and Khobar host fewer specialized prosthodontic clinics per capita than Riyadh, creating whitespace for mobile diagnostic units and teledentistry-linked impression services.
- AI-Assisted Treatment Planning Convergence:Machine learning algorithms integrated with cone-beam computed tomography systems enable automated nerve canal mapping, reducing surgical planning time for complex implant cases.
- Direct-to-Clinic Distribution Channels:Manufacturers are bypassing traditional Jeddah-based medical device distributors to establish dedicated sales teams serving hospital dental departments under long-term equipment lease arrangements.
Industry Challenges
- Digital Workflow Integration Complexity:Private clinics struggle to synchronize legacy panoramic radiography units with new intraoral scanning platforms, requiring costly middleware investments and staff retraining programs.
- Biocompatibility Certification Timelines:SFDA's expanded testing requirements for titanium-zirconium alloy implants extend regulatory approval cycles, delaying product launches against European competitors already holding CE marking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Dental Devices Market |
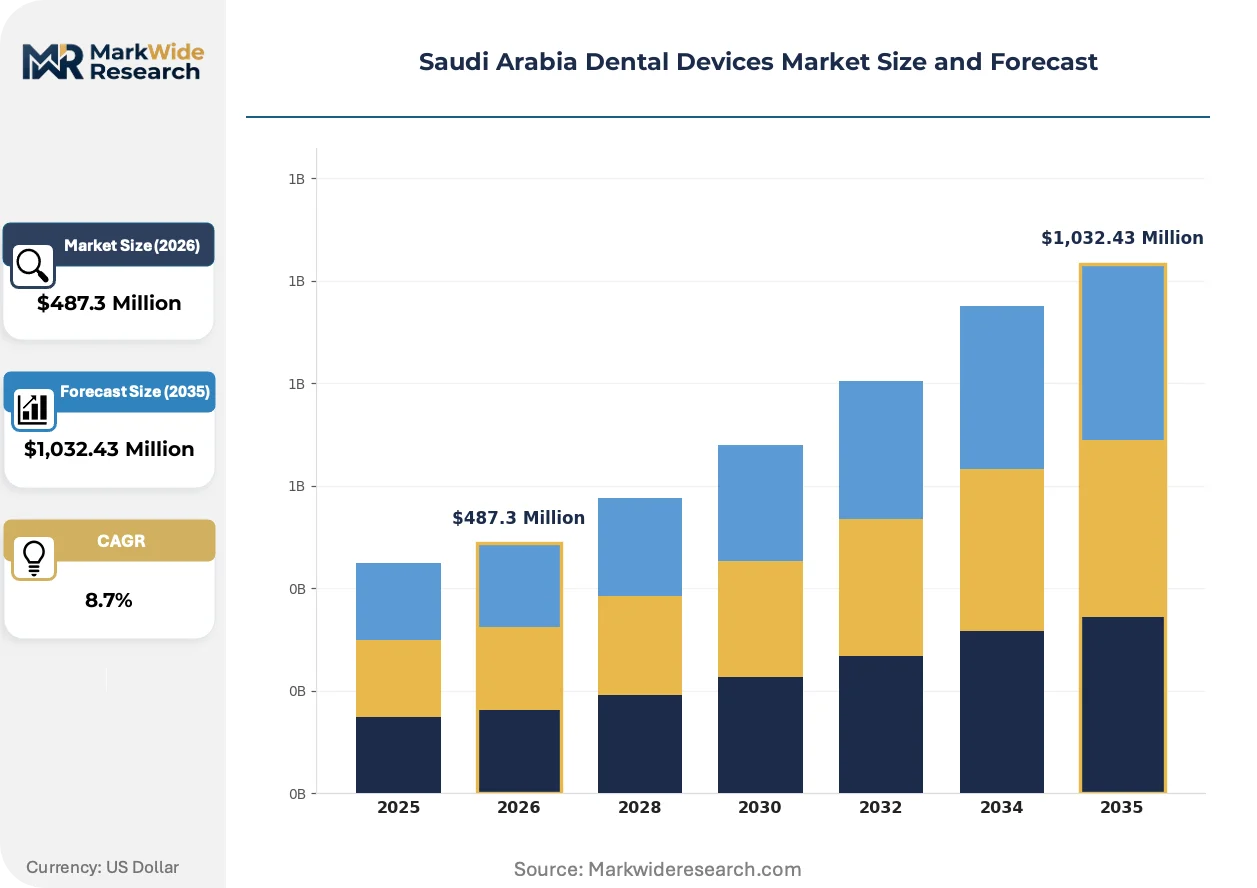
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instruments, Consumables, Equipment, Implants Delivery Mode: Online, Offline, Direct Sales, Distributors End User: Clinics, Hospitals, Laboratories, Dental Schools Technique: Orthodontics, Periodontics, Implantology, General Dentistry |
| Companies Covered | 3M Company, Dentsply Sirona, Institut Straumann AG, Zimmer Biomet, Planmeca, Align Technology, Nobel Biocare, Ivoclar Vivadent AG, Carestream Health, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Dental Devices Market Evolving Landscape
Digital dentistry workflows are compressing treatment timelines from initial impression to final restoration, while regulatory localization mandates and shifting procurement authority reshape how suppliers structure their Saudi market presence.
Intraoral scanning technology is migrating from conventional silicone-based physical impressions toward optical capture systems that generate immediate STL files for chairside milling. Premium private clinics in Riyadh's Al Olaya district are adopting these systems at accelerated replacement cycles, compressing the traditional two-week laboratory turnaround into same-day crown delivery and reducing patient chair time by eliminating secondary appointments.
SFDA's implementation of the Medical Device Marketing Authorization pathway aligns Saudi requirements with International Medical Device Regulators Forum standards, forcing European and American manufacturers to restructure quality management documentation. This regulatory convergence most impacts imaging equipment suppliers, who must now maintain parallel technical files for CE marking and Saudi registration, increasing compliance staffing costs but reducing future market entry barriers for multi-territory product launches.
Clinic procurement authority is consolidating from individual practitioner purchasing decisions toward centralized buying committees within multi-location dental chains. Western Province groups like those operating across Jeddah's Al Rawdah corridor now negotiate enterprise-level service contracts that bundle equipment, consumables, and preventive maintenance, displacing the traditional distributor-led transactional model and pressuring standalone suppliers to develop direct clinical support capabilities.
Saudi Arabia Dental Devices Market Segmentation
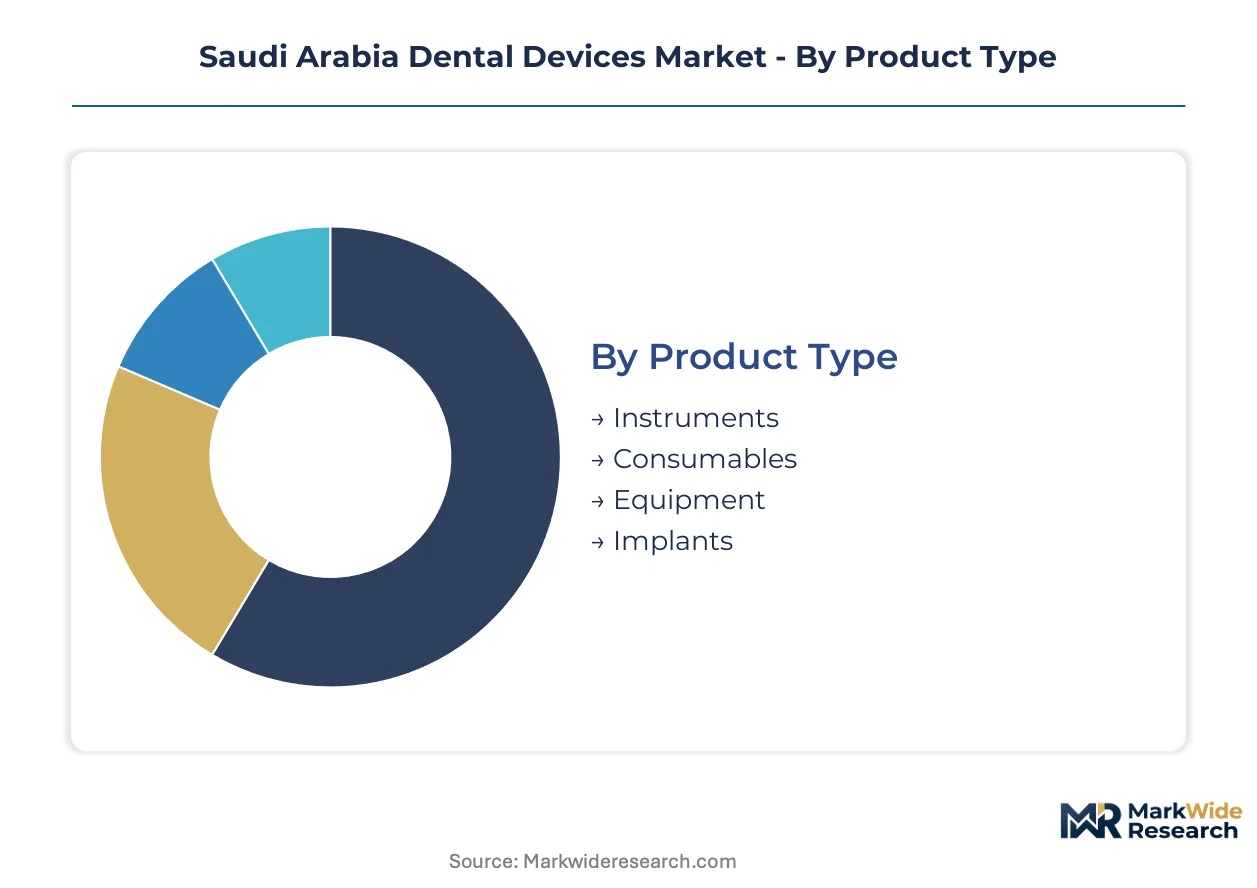
Saudi Arabia's dental devices market segments along four critical dimensions that determine procurement patterns, margin structures, and service intensity requirements. Each category reveals distinct pathways for supplier positioning and customer engagement strategies.
Product Type:
After-sales service intensity varies dramatically across product categories, with capital equipment demanding dedicated technical support teams while consumables rely on rapid replenishment logistics.
- Equipment:Digital intraoral scanners, cone-beam computed tomography systems, and CAD/CAM milling units require calibration technicians and preventive maintenance contracts. Riyadh's Al Olaya district dental chains negotiate multi-year service agreements that bundle equipment leasing with consumable supply, locking in supplier relationships through embedded technical dependency.
- Implants:Titanium-zirconium alloy fixtures and abutments demand surgical training support and inventory management for size-specific components. Central Province implantology centers in Riyadh drive premium positioning through osseointegration guarantees and immediate-loading protocols that require intensive clinical education programs.
- Instruments:Handpieces, scalers, and extraction forceps need sterilization validation and periodic refurbishment services.
- Consumables:Bonding agents, impression materials, and sterilization products sustain recurring purchase velocity through distributor stock-and-defer arrangements.
Equipment holds the largest share; momentum sits with implants as private clinic chains expand specialized surgical capabilities.
Delivery Mode:
Channel economics reflect customer scale and purchase complexity, with direct sales penetrating hospital dental departments while distributors retain fragmented clinic networks.
- Direct Sales:Manufacturer field teams serve Ministry of Health hospital dental departments and large multi-location clinic groups under long-term equipment lease arrangements. Western Province groups across Jeddah's Al Rawdah corridor now centralize procurement through enterprise contracts that displace traditional distributor relationships.
- Distributors:Jeddah-based medical device wholesalers retain transactional relationships with standalone practitioners and smaller clinics requiring credit terms and mixed-product baskets.
- Online:E-procurement platforms target consumables replenishment for clinic chains with predictable demand patterns.
- Offline:Traditional showroom and trade exhibition channels persist for equipment demonstration and practitioner relationship building.
Direct sales commands the premium segment; distributors retain volume leadership across fragmented clinic networks.
End User:
Customer type determines product mix and decision-making authority, with hospitals prioritizing imaging integration and clinics emphasizing chairside efficiency.
- Clinics:Private dental practices in Riyadh and Jeddah concentrate demand for digital impression systems and same-day restoration capabilities. These facilities prioritize workflow compression and reduced patient appointment counts over capital cost minimization.
- Hospitals:Ministry of Health facilities and private hospital dental departments require enterprise-scale imaging systems with electronic health record integration and centralized sterilization protocols.
- Laboratories:Prosthetic fabrication centers serve as intermediaries for conventional impression workflows, though their role diminishes as chairside milling expands.
- Dental Schools:King Saud University and other institutions drive training equipment demand and influence future practitioner technology preferences.
Clinics generate the deepest revenue pool; hospitals present the steepest expansion trajectory as the Health Sector Transformation Program expands facility networks.
Technique:
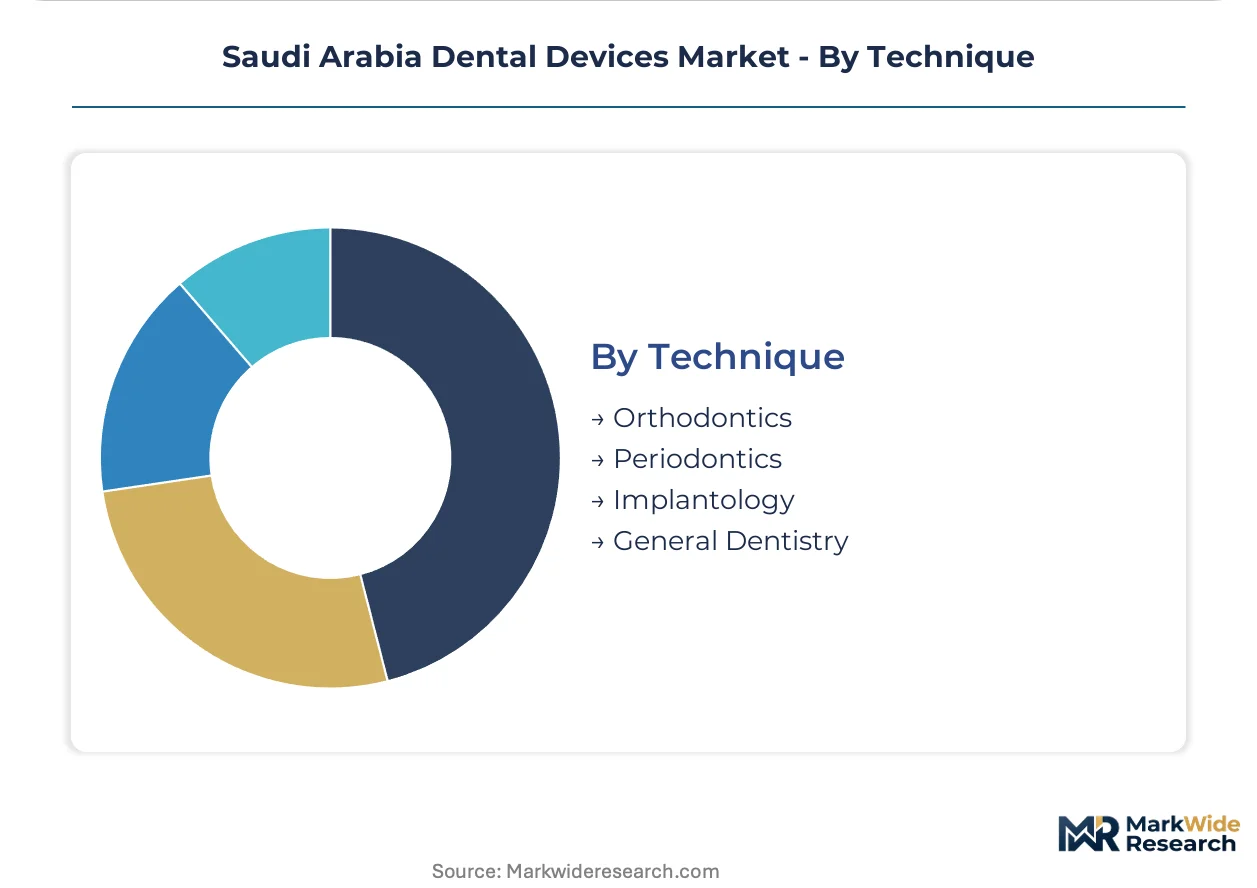
Clinical specialization determines equipment specifications and consumable requirements, with implantology and cosmetic segments commanding premium pricing.
- Implantology:Surgical planning software, guided surgery kits, and immediate-loading protocols require integrated digital workflows from cone-beam imaging through prosthetic delivery. Central Province specialized centers cluster around Riyadh's medical district.
- General Dentistry:Restorative and preventive procedures sustain baseline demand for diagnostic equipment and routine consumables across the broadest clinic network.
- Orthodontics:Clear aligner systems and digital treatment planning tools compete with conventional bracket-and-wire approaches.
- Periodontics:Regenerative procedures and laser-assisted therapies target specialized referral practices.
General dentistry anchors volume; implantology captures the fastest margin expansion as private investment concentrates in specialized surgical centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's dental devices market remains import-dependent for precision components, with German and Swiss suppliers dominating ceramic milling burs and optical sensors. The NIDLP localization push is gradually shifting assembly operations for consumables and sterilization products to domestic facilities.
Riyadh
The Central Province capital concentrates specialized implantology centers and premium private dental chains in the Al Olaya medical district. SFDA's risk-based classification system accelerates approvals for Class II imaging equipment targeting these facilities. Enterprise procurement committees now negotiate multi-year service agreements bundling equipment leasing with consumable supply.
Eastern Province
Dammam and Khobar host fewer specialized prosthodontic clinics per capita than Riyadh, creating whitespace for mobile diagnostic units. The NIDLP offers tariff relief for foreign manufacturers establishing Saudi-based assembly operations in this industrial zone. Direct-to-clinic distribution channels are bypassing traditional Jeddah-based wholesalers to serve hospital dental departments.
Western Region
Jeddah's Al Rawdah corridor anchors multi-location dental chains centralizing procurement through enterprise contracts. SASO electromagnetic compatibility testing requirements for digital radiography units create bottlenecks delaying equipment upgrades. Private clinic networks here prioritize workflow compression and same-day restoration capabilities.
NEOM Northwest
The giga-project zone is attracting preventive dentistry investment aligned with Health Sector Transformation Program preventive care mandates. Land allocation incentives under NIDLP target manufacturers of biocompatible polymer composites for regional supply. Regulatory sandbox provisions may streamline SFDA registration pathways for AI-assisted treatment planning systems.
Saudi Arabia Dental Devices Market Competitive Landscape
On the supply side, the industry is consolidating around integrated digital workflow providers while fragmenting across specialized implant and consumable niches. Two strategic archetypes dominate: full-stack imaging-to-milling ecosystem vendors and focused implantology specialists with surgical training infrastructures. Competitive moves center on direct sales channel establishment and long-term equipment lease arrangements that embed technical dependency.
Among Swiss-anchored implantology specialists, Institut Straumann AG occupies a position exemplifying premium osseointegration technology positioning. Dentsply Sirona represents the integrated ecosystem archetype, spanning imaging capture through chairside restoration delivery. Zimmer Biomet sits within the diversified orthopedic-to-dental convergence tier, leveraging scale across musculoskeletal and oral reconstruction applications.
| Leading Market Players |
|---|
| 3M Company |
| Dentsply Sirona |
| Institut Straumann AG |
| Zimmer Biomet |
| Planmeca |
| Align Technology |
| Nobel Biocare |
| Ivoclar Vivadent AG |
| Carestream Health |
| Others |
Value Network & Pricing Analysis
German and Swiss precision component suppliers anchor upstream concentration for ceramic milling burs and optical scanning sensors, channeling margin capture toward downstream equipment integrators who bundle service contracts with hardware leases. This geographic supply lock concentrates pricing power among European specialty manufacturers while forcing Saudi distributors to absorb euro-denominated cost volatility.
Pricing Analysis
Private dental clinic chains anchor a contract-based pricing structure that bundles multi-year equipment leasing with consumable supply agreements. Price differentiation hinges on after-sales service intensity and SFDA registration tier, with premium positioning tied to embedded technical support teams. Cost compression in the standard equipment tier is intensifying as clinic procurement committees consolidate purchasing authority and demand volume discounts. Standalone practitioners show highest price sensitivity, while hospital dental departments prioritize integration guarantees over unit cost.
Supply Chain Analysis
Titanium alloy feedstock and zirconia ceramic powders draw from German, Swiss, and Japanese specialty suppliers before reaching Saudi assembly operations. Optical scanning sensors and precision milling spindles rest on single-source dependencies that expose distributors to extended lead times. Tariff exposure runs through euro-denominated component contracts that NIDLP localization incentives aim to partially offset. Distribution runs through Jeddah-based medical device wholesalers for fragmented clinics, while direct manufacturer teams serve consolidated hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Saudi dental devices sector represents a high-growth disruption as SFDA regulatory convergence with IMDRF standards accelerates market entry for digitally integrated workflow providers. This regulatory inflection compresses approval timelines for Class II imaging equipment while elevating compliance costs for legacy importers.
For Market Incumbents: Entrench service-embedded relationships by expanding calibration technician teams across Riyadh's Al Olaya district clinic chains. Deepen backward integration into consumables assembly through NIDLP-partnered Saudi facilities to offset euro-denominated component exposure. Lock in multi-year enterprise contracts before procurement authority consolidates further.
For New Entrants and Emerging Players: Eastern Province cities Dammam and Khobar present whitespace for mobile diagnostic units and teledentistry-linked impression services where specialized prosthodontic clinic density lags Riyadh. Target hospital dental departments with direct sales teams offering equipment lease arrangements that bypass traditional Jeddah distributor networks. Lead with AI-assisted treatment planning as a differentiated entry wedge.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated digital workflow providers possessing both imaging hardware and chairside milling capabilities, as clinic demand concentrates around same-day restoration delivery. The long-term viability window favors suppliers with established SFDA quality management systems and direct clinical support infrastructure. Watch for Health Sector Transformation Program reimbursement framework shifts as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Marketing Authorization Pathway Investment | Accelerates time-to-market for digital intraoral scanners targeting private clinic chains. |
| NIDLP Localization Partnership | Secures tariff relief for consumables assembly operations in Eastern Province industrial zones. |
| Direct-to-Clinic Distribution Buildout | Bypasses Jeddah-based wholesalers to capture enterprise procurement committee contracts. |
| AI-Assisted Treatment Planning Integration | Differentiates cone-beam CT systems through automated nerve canal mapping capabilities. |
| Multi-Year Service Contract Expansion | Locks in supplier relationships through embedded technical dependency across Riyadh clinic networks. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SFDA registration databases, SASO technical conformity filings, and NIDLP industrial incentive disclosures. Primary inputs drew from interviews with biomedical engineers at Ministry of Health hospital dental departments, procurement managers at multi-location clinic chains, and regulatory affairs specialists navigating Medical Device Marketing Authorization pathways. Secondary validation incorporated customs trade data for dental equipment imports, GPO contract repositories, and European manufacturer CE marking technical files. Bottom-up clinic network sizing and top-down import value triangulation anchored market estimates.
Forecast inputs considered equipment replacement cycles, implantology center expansion plans, and digital workflow adoption curves across the projection horizon. Segmentation modeling captured product type, delivery mode, end user category, and clinical technique specialization. CAGRs derived from regression analysis against historical import growth and forward-looking capital expenditure intentions. Specific inputs included SFDA approval velocity trends and Health Sector Transformation Program facility network expansion targets.
The forecast holds incumbent behavior within observed patterns; aggressive direct sales investments by European imaging equipment manufacturers or accelerated NIDLP assembly subsidies would shift outcomes. Cross-checking against Saudi customs import value series and hospital procurement database spending patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Dental Aligners Market
Dental Devices
Dental Laboratory Handpiece Market
Dental Devices
Dental Composite Filling Market
Dental Devices
Dental Devices and Consumables Market
Dental Devices
Dental Splints Market
Dental Devices
Middle East and Africa Dental Lab Market
Dental Devices
Dental 3D Printing Market
Dental Devices
Latin America Dental Devices Market
Dental Devices
Europe Dental Aligners Market
Dental Devices
Chile Dental Devices Market
Dental Devices
Global Dental Hygiene Devices Market
Dental Devices
Dental Piezoelectric Ultrasonic Unit Market
Dental Devices
Dental Radiometer Market
Dental Devices
Europe CBCT Dental Imaging Market
Dental Devices
Dental Impression Tray Market
Dental Devices
Dental Calipers Market