
 Dental Contouring Market | 2026-2036
Dental Contouring Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Contouring Market Intelligence
Buyer concentration among large dental service organizations is restructuring procurement patterns across the dental contouring landscape. Dentsply Sirona leverages its integrated CAD/CAM workflow to dominate chairside restoration systems. Henry Schein anchors North American distribution through its extensive dental supply network. 3M Company competes on material science strength in cosmetic fillings and adhesive technologies.
Dental contouring comprises the precise reshaping of enamel and dentin surfaces using diamond burs, sanding discs, or laser ablation to correct minor imperfections in tooth length, shape, or surface texture, with procedures typically removing 0.2 to 0.5 millimeters of enamel per treatment. The technique serves primarily aesthetic and minor occlusal adjustment purposes in outpatient dental settings. Veneers sustain premium positioning due to porcelain durability and patient preference for permanent solutions over composite alternatives. Digital imaging leads technology adoption as intraoral scanners displace traditional impression materials in private practices. Dental clinics occupy the largest end-user channel, though specialized cosmetic centers differentiate on concierge service models and celebrity clientele.
FDA 510(k) clearance requirements govern laser treatment devices and CAD/CAM milling systems in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence standards on contouring instruments entering European markets. ISO 13485 quality management certification shapes supplier qualification criteria for dental OEMs sourcing consumables and capital equipment. Stakeholders must monitor evolving reimbursement codes for aesthetic versus restorative indications as payers tighten coverage distinctions.
Market Dynamics
Digital intraoral scanners are compressing treatment timelines and displacing traditional impression workflows across private dental practices, forcing capital equipment refresh cycles and reshaping supplier-buyer power dynamics in the restorative segment.
Growth Catalysts
- FDA 510(k) streamlined pathways:Expedited clearance for CAD/CAM milling systems accelerates product commercialization timelines for device manufacturers targeting the United States market.
- Private dental practice digitalization:Chairside restoration systems reduce laboratory dependency and capture higher-margin procedures within clinic walls.
- Working-age adult aesthetic demand:Cosmetic contouring procedures gain traction among professionals seeking minimally invasive smile enhancements without orthodontic intervention.
Market Restraints
- Capital intensity of laser systems:Erbium and diode laser platforms require substantial upfront investment, limiting adoption to high-volume practices in metropolitan clusters.
- EU MDR clinical evidence requirements:Stricter conformity assessment procedures for contouring instruments delay European market entry and inflate regulatory compliance costs.
- Enamel thickness constraints:Biological limits of 0.2-0.5 millimeter safe removal restrict indication scope and eliminate candidates with thin enamel or pre-existing wear.
Strategic Opportunities
- Brazil private practice upgrade wave:São Paulo and Rio de Janeiro dental clinics are investing in digital imaging capabilities, creating demand for integrated CAD/CAM workflows.
- AI-powered treatment planning:Machine learning algorithms integrated with intraoral scanning software enable predictive enamel reduction mapping and outcome visualization.
- Concierge cosmetic center channel:Premium service models targeting celebrity and high-net-worth clientele command price multiples over standard clinic offerings.
Industry Challenges
- CAD/CAM technician training gaps:Shortage of certified operators for chairside milling systems constrains utilization rates and return on capital equipment investments.
- ISO 13485 supplier qualification complexity:Dental OEMs impose stringent quality management requirements on consumable vendors, extending onboarding timelines for new entrants.
- Reimbursement code ambiguity:Payer distinctions between aesthetic and restorative indications create claim denial risk and revenue recognition uncertainty for providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Contouring Market |
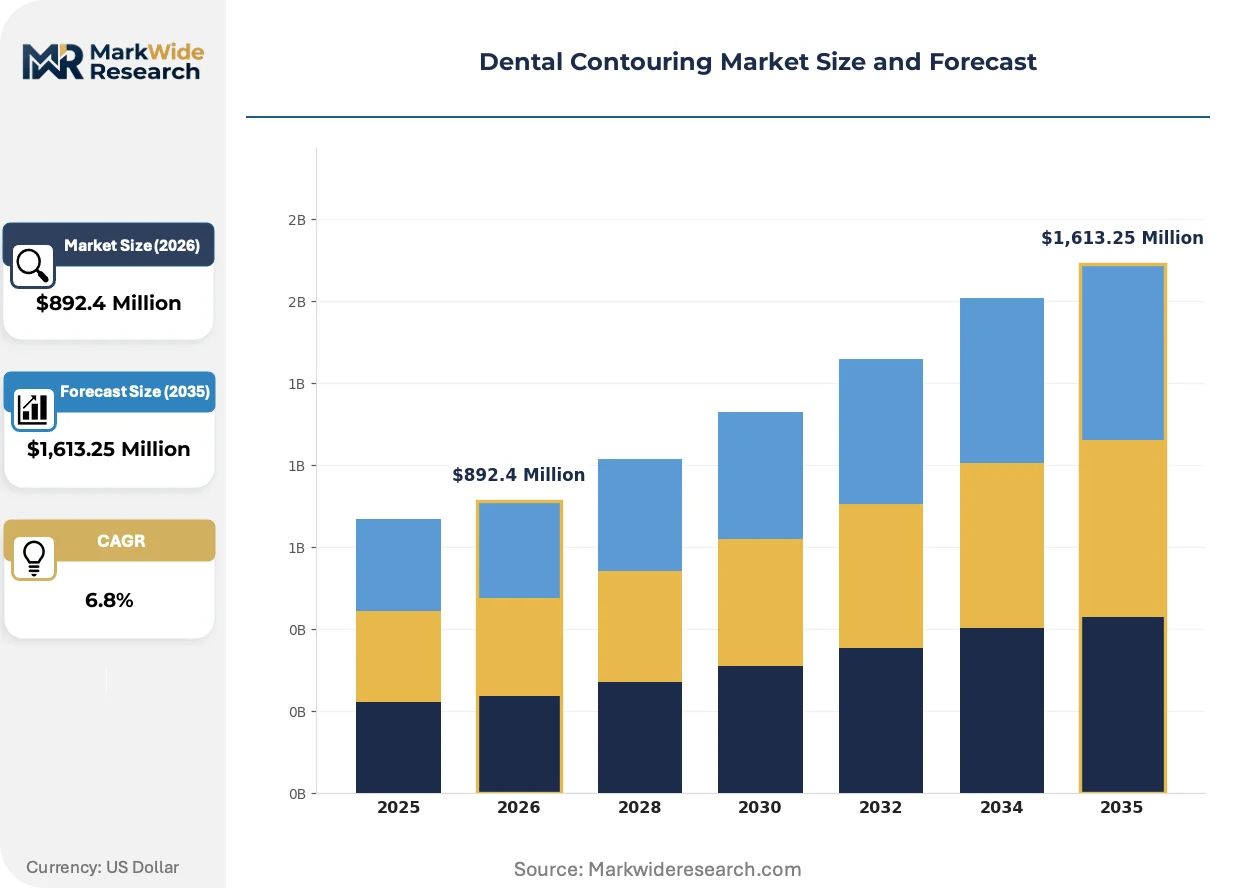
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $1,613.25 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Veneers, Cosmetic Fillings, Crowns, Braces Application: Aesthetic Enhancement, Restorative Dentistry, Aligner Therapy, Procedures End User: Dental Clinics, Hospitals, Specialized Cosmetic Centers, Private Practices Technology: CAD/CAM, Laser Treatments, 3D Printing, Digital Imaging |
| Companies Covered | Dentsply Sirona, 3M Company, Henry Schein, Planmeca Group, Cleveland Clinic, Mayo Clinic Dentistry, All Smiles Dental, Elleven Dental, Abano Healthcare Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Contouring Market Strategic Shifts & Innovations
Laser ablation systems are reshaping enamel modification protocols by enabling micron-precision tissue removal without mechanical vibration, fundamentally altering patient comfort expectations and clinical technique training curricula across outpatient settings.
Ultrafast pulse laser technology is electrifying hard-tissue applications in cosmetic dentistry. Erbium-doped systems operate at 2,940 nanometers wavelength for selective enamel vaporization. High-volume aesthetic practices in Germany and Japan are retrofitting operatories with these platforms. The technology is electrifying competitive differentiation as clinics market anesthesia-free procedures to anxiety-sensitive patient segments.
The EU Medical Device Regulation imposes enhanced clinical evidence standards on laser contouring instruments entering European markets. Manufacturers must compile post-market surveillance data and biological safety documentation beyond predecessor directives. German and French notified bodies are interpreting MDR Annex XVI aesthetic device classifications most stringently, forcing design dossier resubmissions for legacy product lines.
Patients now research providers through digital smile simulation platforms before scheduling consultations, compressing the traditional referral pathway. Social media-driven before-and-after galleries displace word-of-mouth recommendations among younger demographics. This behavioral shift is most pronounced in urban United States markets where Instagram and TikTok visibility directly correlates with appointment booking velocity for cosmetic contouring specialists.
Dental Contouring Market Segmentation
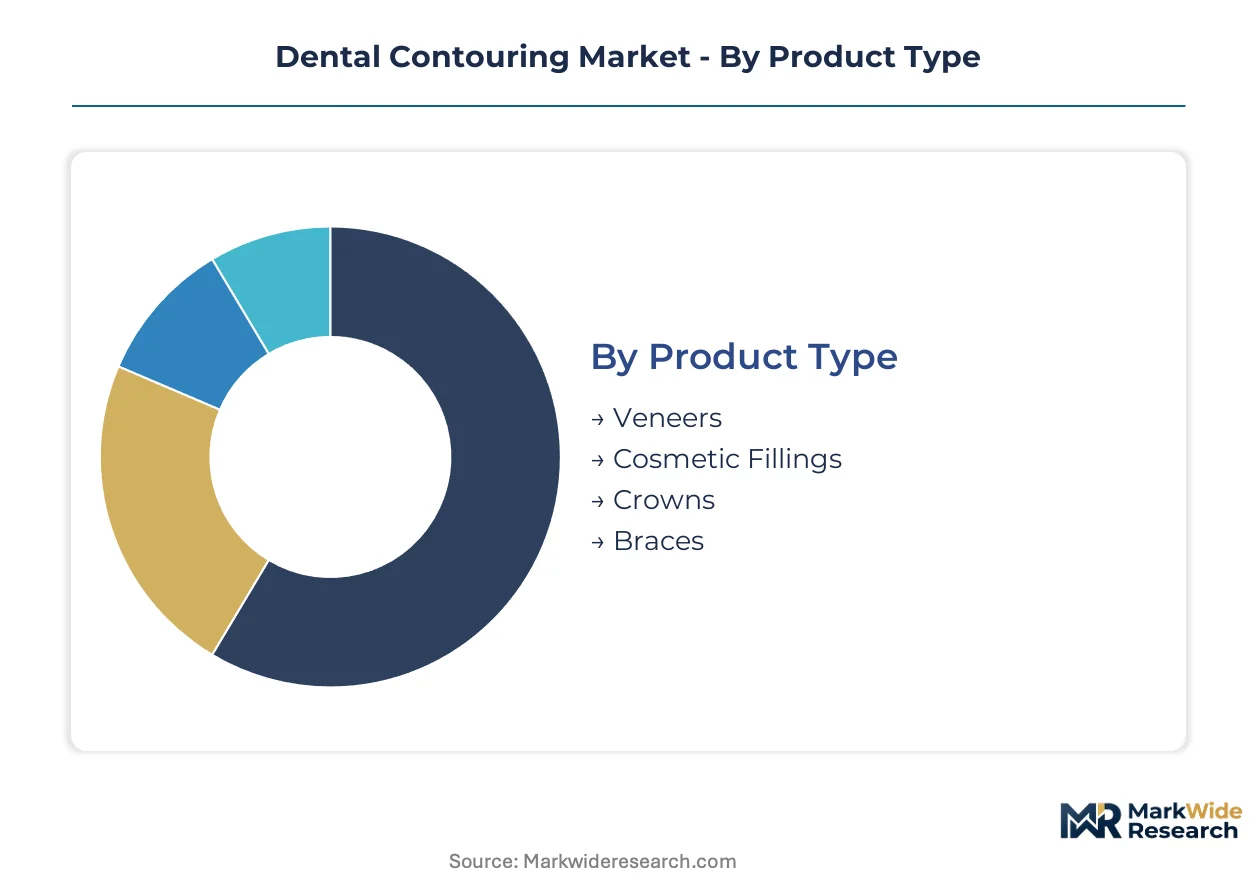
Segmentation reveals how capital equipment investments, clinical workflow preferences, and patient payment capacity fragment demand across the dental contouring landscape. Understanding these divisions exposes where supplier power concentrates and which channels warrant differentiated product positioning.
Product Type:
Supply concentration tilts toward porcelain-based solutions where material science barriers protect incumbent manufacturers from commoditization.
- Veneers:Thin porcelain or composite laminates bond to facial tooth surfaces for permanent aesthetic transformation. German and Japanese private practices drive premium porcelain demand, constrained by laboratory turnaround times and ceramic fracture risks in bruxism patients.
- Crowns:Full-coverage restorations encase prepared teeth to restore morphology and function following substantial structural loss. Brazilian clinics in São Paulo and Rio de Janeiro are upgrading to chairside milling for same-day crown delivery, bypassing traditional laboratory outsourcing.
- Cosmetic Fillings:Tooth-colored composite resins repair minor defects and close diastemas through direct application. Chairside polymerization systems dominate outpatient settings.
- Braces:Orthodontic appliances reposition teeth through mechanical force, occasionally combined with selective enamel reduction. Clear aligner integration is displacing fixed brackets in adult aesthetic cases.
Veneers absorb the bulk of installed capacity; crowns are expanding most quickly through CAD/CAM adoption in high-volume practices.
Application:
Cost tier stratification separates elective cash-pay procedures from insurance-reimbursed interventions, reshaping provider marketing investments and equipment amortization schedules.
- Aesthetic Enhancement:Elective procedures including enameloplasty, diastema closure, and incisal edge refinement for smile symmetry. Working-age professionals in United States urban clusters pay out-of-pocket, with Instagram visibility directly influencing provider selection.
- Restorative Dentistry:Medically indicated contouring to restore occlusal function or repair fractured tooth structure. Reimbursement codes vary by payer, creating revenue recognition complexity for United States providers navigating aesthetic versus functional claim distinctions.
- Aligner Therapy:Interproximal reduction and enamel reshaping to facilitate orthodontic tooth movement. Clear aligner manufacturers specify reduction protocols.
- Procedures:General category encompassing diagnostic wax-ups, trial smile mockups, and provisional restorations. Digital workflow integration is compressing traditional multi-appointment sequences.
Restorative dentistry commands the largest procedure volume; aesthetic enhancement is gaining share fastest among younger demographics.
End User:
Customer type determines capital intensity thresholds, with large dental service organizations extracting procurement scale advantages unavailable to independent operators.
- Dental Clinics:Multi-provider outpatient facilities offering comprehensive restorative and cosmetic services. These settings concentrate laser system investments in Germany, Japan, and Brazil metropolitan markets.
- Private Practices:Solo or small-group practitioner offices where chairside CAD/CAM systems reduce laboratory dependency. United States private practices lead intraoral scanner penetration rates.
- Specialized Cosmetic Centers:Concierge facilities targeting celebrity and high-net-worth clientele with premium service models. São Paulo and Los Angeles clusters command price multiples over standard clinic offerings.
- Hospitals:Academic medical centers and hospital-based dental departments handling complex multidisciplinary cases. These settings prioritize training value over throughput metrics.
Dental clinics deploy the majority of capital equipment; specialized cosmetic centers are climbing the fastest on margin expansion.
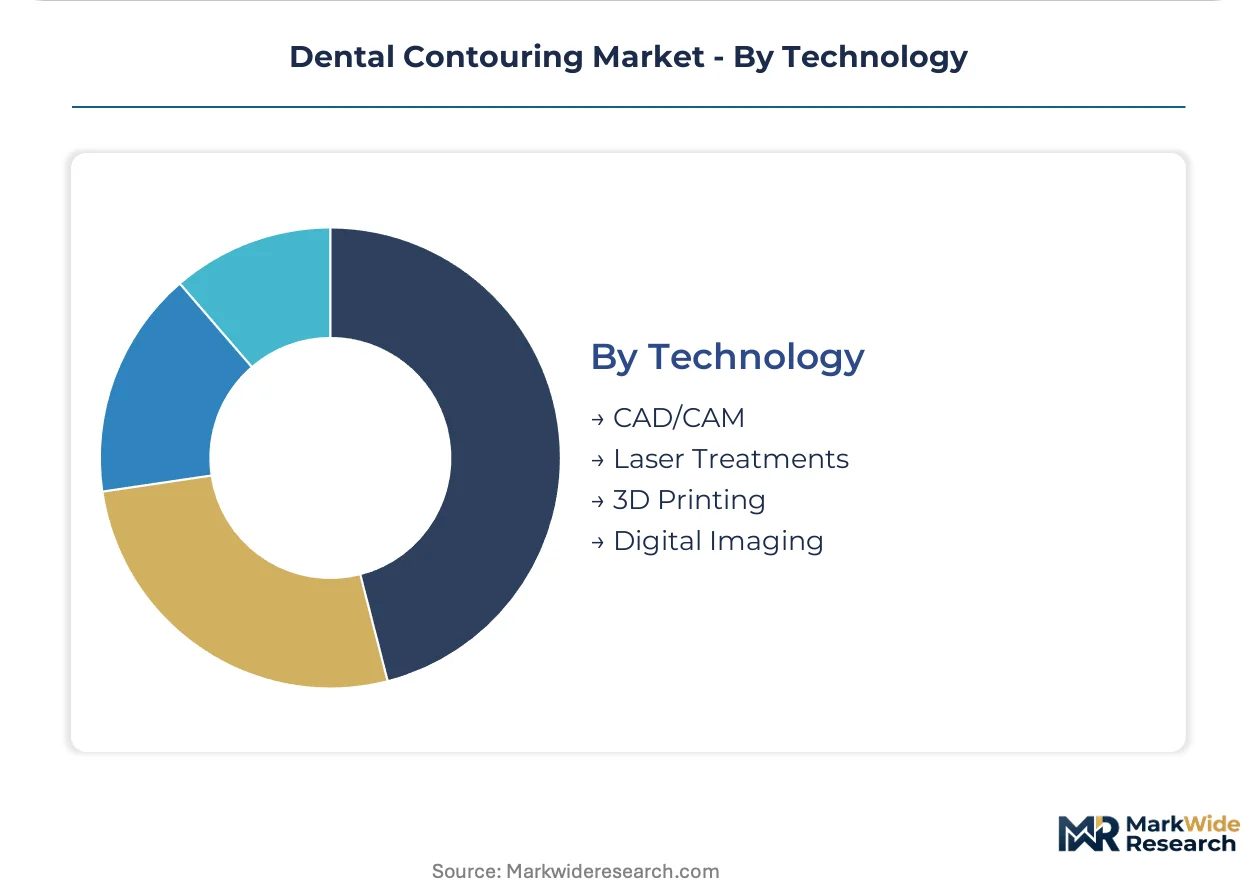
Technology:
Maturity curves diverge sharply, with digital imaging already pervasive while 3D printing remains nascent in direct restorative applications.
- Digital Imaging:Intraoral scanners, cone-beam computed tomography, and digital radiography systems capturing three-dimensional oral anatomy. United States and German private practices have largely displaced traditional impression materials.
- CAD/CAM:Computer-aided design and manufacturing workflows for chairside restoration milling and laboratory communication. Japanese clinics are retrofitting operatories with integrated systems to capture higher-margin procedures.
- Laser Treatments:Erbium and diode laser platforms for hard-tissue ablation and soft-tissue contouring. FDA 510(k) clearance pathways expedite United States commercialization.
- 3D Printing:Additive manufacturing for surgical guides, provisional restorations, and orthodontic models. Direct printing of permanent restorations awaits biocompatible resin maturation.
Digital imaging saturates installed base; laser treatments are gaining share fastest among anxiety-sensitive patient segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Working-age professionals seeking aesthetic enhancements cluster in metropolitan dental markets across Germany, Japan, Brazil, and the United States, with private practice digitalization driving capital equipment procurement in urban centers.
United States
FDA 510(k) clearance pathways expedite commercialization timelines for CAD/CAM milling systems and laser contouring devices. Working-age adults in urban clusters pay out-of-pocket for elective enameloplasty procedures, with Instagram visibility directly influencing provider selection in Los Angeles and New York Metro markets.
Germany
EU MDR clinical evidence requirements impose stricter conformity assessments on contouring instruments entering European markets. German notified bodies interpret aesthetic device classifications stringently, forcing design dossier resubmissions for legacy laser platforms in Bavaria and North Rhine-Westphalia dental clusters.
Japan
PMDA regulatory oversight governs medical device approvals for hard-tissue laser systems and intraoral scanners. Japanese private practices in Tokyo and Osaka metropolitan areas lead chairside restoration adoption, retrofitting operatories with integrated CAD/CAM workflows to capture higher-margin procedures.
Brazil
ANVISA registration requirements structure market entry protocols for imported dental equipment and consumables. São Paulo and Rio de Janeiro dental clinics are investing in digital imaging capabilities, creating concentrated demand for laser ablation platforms and same-day crown milling systems.
United Kingdom
MHRA post-Brexit regulatory frameworks now govern device approvals independently from EU MDR harmonization. London-based cosmetic centers and private Harley Street practices command premium pricing for concierge enamel contouring services targeting high-net-worth clientele.
Dental Contouring Market Key Industry Players
German and Japanese producers anchor precision equipment tiers; United States specialists hold distribution and materials science positions. Market structure tilts toward consolidated supply in capital equipment segments, with fragmented competition in consumables and clinical services. Three archetypes dominate: integrated CAD/CAM workflow providers, dental supply distributors with extensive logistics networks, and specialized cosmetic clinic operators with celebrity clientele. Competitive moves concentrate on strategic partnerships between technology vendors and large dental service organizations, plus portfolio diversification into chairside restoration systems.
Within the integrated workflow tier, Dentsply Sirona and Planmeca Group exemplify capital equipment specialists with CAD/CAM positioning. Among materials and distribution anchors, 3M Company and Henry Schein occupy positions spanning adhesive technologies and North American supply chain infrastructure. These three entities represent the dominant competitive archetypes: technology-integrated systems, material science strength, and distribution scale.
| Leading Market Players |
|---|
| Dentsply Sirona |
| 3M Company |
| Henry Schein |
| Planmeca Group |
| Cleveland Clinic |
| Mayo Clinic Dentistry |
| All Smiles Dental |
| Elleven Dental |
| Abano Healthcare Group |
| Others |
Cost & Logistics Intelligence
ISO 13485 certification mandates gate qualified supply access for dental OEMs, separating premium-tier pricing for certified consumables from uncertified alternatives while elevating procurement qualification costs for new market entrants.
Pricing Analysis
Volume concentrates in standard-grade porcelain veneers and composite fillings, while margin pools in premium-tier chairside CAD/CAM systems and laser ablation platforms. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales service bundling. Cost compression in economy-tier consumables intensifies as Brazilian and Indian manufacturers expand ceramic powder supply. Large dental service organizations exhibit lowest price sensitivity; independent private practices in tier-two United States metros face acute budget constraints.
Supply Chain Analysis
Regional distribution centers in Frankfurt, Tokyo, and São Paulo anchor hub-and-spoke patterns for capital equipment, with spoke nodes reaching private practices through Henry Schein and dental supply cooperatives. Manufacturing concentrates in Germany for precision milling spindles, Japan for optical scanning components, and the United States for laser resonator assemblies. Raw material dependencies span yttria-stabilized zirconia from Australian mines, erbium-doped laser crystals from Russian suppliers, and diamond bur blanks from South African sources. Single-source vulnerability in erbium crystal supply creates procurement risk for laser system OEMs. Distribution runs through authorized dealer networks with factory-direct bypass emerging for high-volume clinic chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dental contouring sector sits in a technology-transition phase where intraoral scanners and chairside milling systems displace traditional laboratory outsourcing, compressing treatment timelines and restructuring provider economics.
For Market Incumbents: Acquire AI-powered treatment planning software assets to defend against algorithm-native entrants threatening diagnostic workflow control. Consolidate backward integration into yttria-stabilized zirconia supply to offset raw material price volatility from Australian concentrate markets. Expand ISO 13485-certified manufacturing footprint in Brazil to capture ANVISA-registered demand growth in São Paulo and Rio de Janeiro metropolitan clusters. For New Entrants and Emerging Players: FDA 510(k) streamlined pathways in the United States open a window for laser device specialists to commercialize erbium platforms ahead of EU MDR dossier completion timelines. Target private dental practices in secondary United States metros where incumbent CAD/CAM penetration remains below coastal saturation levels. Deploy subscription-based software companion models to bypass capital equipment procurement committees and establish recurring revenue anchors. For Investors and Strategic Acquirers: Chairside restoration adoption velocity in Japanese private practices is the leading indicator that integrated workflow providers will consolidate laboratory-independent market share. Five-to-ten year viability favors capital equipment specialists with captive consumable streams over pure-play device vendors exposed to replacement cycle compression. Monitor PMDA approval timelines for hard-tissue laser systems as inflection signal for competitive positioning shifts in Asia-Pacific aesthetic dentistry.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Expedited clearance timelines accelerate United States commercialization for laser contouring platforms. |
| Chairside CAD/CAM Integration | Japanese private practices capture higher-margin crown procedures through same-day milling workflows. |
| AI Treatment Planning Partnership | Predictive enamel reduction mapping differentiates software offerings in anxiety-sensitive patient segments. |
| Brazil Distribution Expansion | ANVISA-registered supply networks penetrate São Paulo and Rio de Janeiro digital upgrade cycles. |
| ISO 13485 Certification Investment | Quality management credentials unlock dental OEM procurement contracts for consumable vendors. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with dental clinic operators, biomedical equipment procurement managers, CAD/CAM technician trainers, and GPO contracts specialists. FDA 510(k) databases, PMDA approval registries, ANVISA import records, and EU MDR notified body documentation provided device commercialization timelines. Bottom-up procedure volume estimates from private practice surveys triangulated against top-down capital equipment shipment data from German and Japanese trade associations.
Granularity-level modeling distinguished product type, application indication, end-user channel, and technology platform dimensions across the projection horizon. CAGRs derived from procedure volume growth rates, equipment replacement cycles, and consumable attach rates. Forecast inputs incorporated working-age adult aesthetic demand elasticity, laser system capital intensity constraints, and reimbursement code ambiguity effects on provider revenue recognition.
The model assumes a particular technology adoption path; alternative pathways for ultrafast pulse laser systems would alter the outlook if anesthesia-free protocols accelerate beyond current metropolitan cluster penetration. Forecasts reflect documented assumptions regarding EU MDR implementation stringency and Brazilian private practice digitalization velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Global Dental Obturators Market
Dental Devices
Global Dental Turbine Market
Dental Devices
Intraoral Dental Sensors Market
Dental Devices
Dental Prosthetics Market
Dental Devices
Subperiosteal Dental Implants Market
Dental Devices
Italy Dental Devices Market
Dental Devices
Dental CAD Market
Dental Devices
Dental Suction Systems Market
Dental Devices
Dental Chair Market
Dental Devices
Dental Whitening Lamps Market
Dental Devices
US Orthodontics Market
Dental Devices
Dental Autoclave Market
Dental Devices
Global Dental Burs Market
Dental Devices
Electric Dental Handpieces Market
Dental Devices
Gingivitis Treatment Market
Dental Devices
Asia-Pacific Dental Lab Market