
 Lidocaine Ointment Market | 2026-2036
Lidocaine Ointment Market Size, Share, and Industry Trends Forecast 2026-2036
Lidocaine Ointment Market Analysis
Single-use sachet and unit-dose pouch configurations is consolidating buyer preference away from bulk jars in institutional channels. Glenmark Pharmaceuticals U.S. Inc. leverages its dermatology portfolio to sustain shelf presence across retail pharmacy chains. Taro Pharmaceutical Industries Ltd. anchors its position through specialized topical manufacturing capabilities in North American facilities. Sandoz AG competes aggressively on cost positioning through its generic infrastructure.
Lidocaine ointment is a topical amide-type local anesthetic formulation, typically containing lidocaine base in concentrations ranging from two to five percent within hydrophilic or hydrophobic bases, manufactured through compounding or sterile processing to achieve uniform drug distribution for cutaneous anesthesia and pain relief. Its primary commercial purpose spans pre-procedural numbing, post-herpetic neuralgia management, and minor surgical analgesia across outpatient settings. The pain management application segment leads volume consumption due to chronic condition prevalence, while the patch product type captures premium positioning through extended-release transdermal delivery. Hospital end users dominate procurement scale, though home care channels are expanding fastest as self-administration protocols gain clinical acceptance.
The FDA enforces bioequivalence and Current Good Manufacturing Practice standards that govern topical drug approval and facility inspection schedules, directly shaping product development timelines and market entry costs for new entrants. Health Canada's PMRA and the European Medicines Agency maintain parallel quality frameworks that influence export-oriented manufacturers' compliance investments. Stakeholders must monitor evolving compendial standards for topical drug performance testing as regulatory convergence between major agencies accelerates formulation investment requirements.
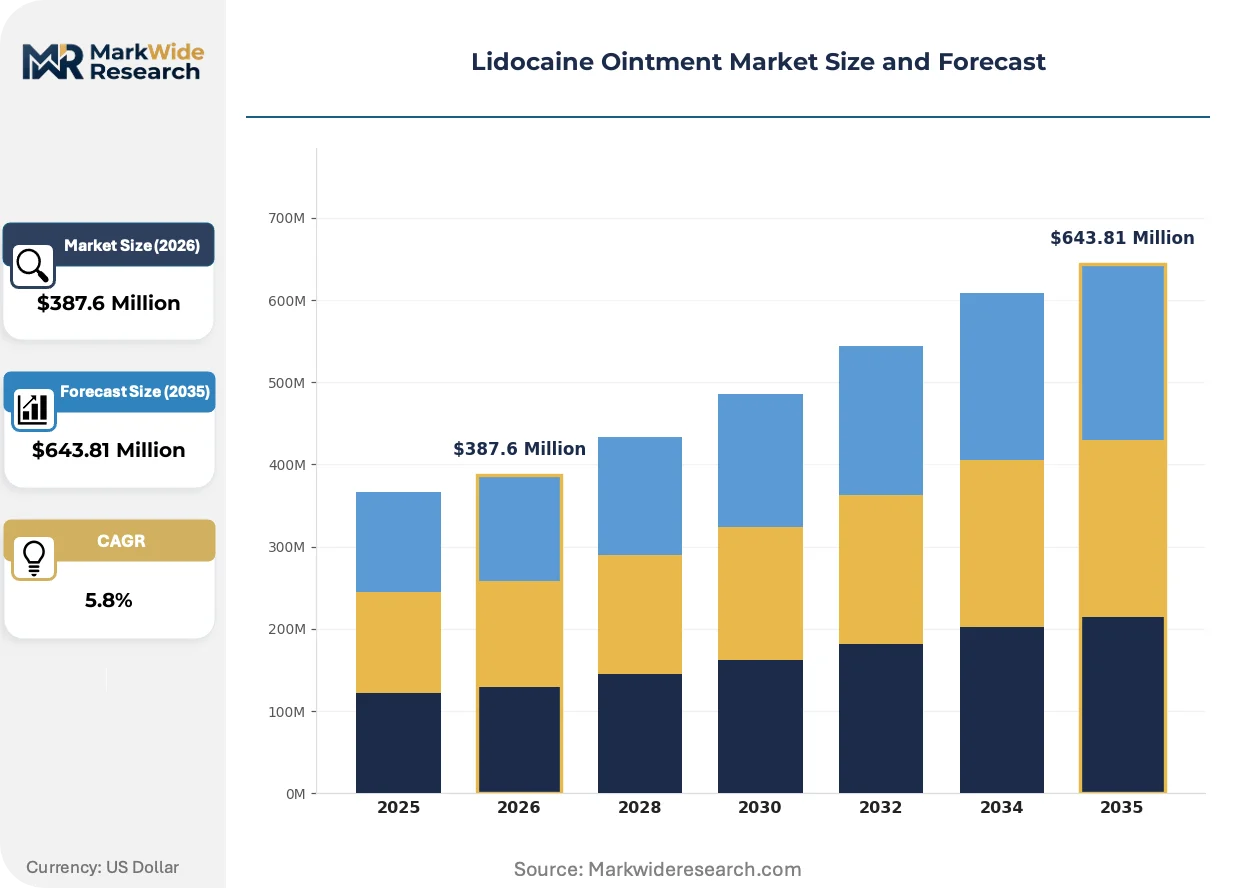
Market Dynamics
The FDA's tightening bioequivalence standards for topical generics is compressing approval timelines and elevating facility compliance costs, forcing manufacturers to accelerate sterile processing investments or exit institutional procurement channels entirely.
Growth Catalysts
- Outpatient procedural volume:Ambulatory surgical centers in the United States are expanding lidocaine ointment procurement for same-day minor surgeries, creating pull-through demand for unit-dose packaging formats.
- EMA's Q1 2024 topical drug guidance:The European Medicines Agency's clarified bioequivalence pathways for semisolid dosage forms is streamlining market entry for specialized manufacturers targeting European hospital networks.
- Transdermal delivery innovation:Liposomal encapsulation technologies are extending lidocaine release profiles, enabling patch manufacturers to capture premium positioning in chronic pain management segments.
Market Restraints
- API supply concentration:Lidocaine base production clusters in Chinese chemical manufacturing zones, exposing formulators to export license volatility and shipping cost spikes.
- FDA facility inspection backlog:Extended FDA Current Good Manufacturing Practice audit queues are delaying product launches and freezing capital in work-in-process inventory.
- Topical NSAID substitution:Diclofenac gel formulations are capturing share in osteoarthritis pain management, pressuring lidocaine ointment volume in retail pharmacy channels.
Strategic Opportunities
- Home care self-administration:Post-operative pain protocols in Germany and France are shifting toward patient-managed topical anesthesia, opening direct-to-patient subscription channels bypassing hospital procurement.
- Compounding pharmacy exemption pathways:Section 503A of the Federal Food, Drug, and Cosmetic Act creates regulatory shelter for customized lidocaine strength formulations in the United States.
- Telehealth-integrated prescribing:Virtual dermatology consultations are generating electronic prescriptions for lidocaine ointment, linking diagnostic platforms to mail-order pharmacy fulfillment.
Industry Challenges
- Sterile processing certification timelines:ISO 14644 cleanroom validation for topical drug manufacturing extends facility commissioning by 14-18 months, delaying revenue recognition on capital deployments.
- Bioequivalence study recruitment:FDA-required pharmacokinetic endpoint trials for generic lidocaine ointment face volunteer enrollment bottlenecks, compressing ANDA submission windows against patent cliff timing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lidocaine Ointment Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Cream, Gel, Liquid, Patch Application: Dermatology, Pain Management, Dental Care, Minor Surgery End User: Hospitals, Clinics, Home Care, Pharmacies Distribution Channel: Online Retail, Drug Stores, Supermarkets, Specialty Pharmacies |
| Companies Covered | Glenmark Pharmaceuticals U.S. Inc., Taro Pharmaceutical Industries Ltd., Amneal Pharmaceuticals LLC., Teligent Inc., Centura Pharmaceuticals Inc., AstraZeneca Canada Inc., Novocol Pharma, Sandoz AG, Alembic Pharmaceuticals Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lidocaine Ointment Market Emerging Trajectories
Formulation science and regulatory convergence are compressing product lifecycles while opening white space in patient-administered care models.
Liposomal lidocaine delivery systems are rewriting competitive positioning in extended-release topical anesthesia. Hospital outpatient departments are piloting these formulations for multi-hour procedural coverage, displacing conventional ointment reapplication protocols. The technology is compressing per-procedure product volume while capturing price premiums through reduced nursing labor intensity.
REACH's microplastic restriction amendments are forcing European manufacturers to reformulate hydrophobic ointment bases, accelerating substitution of traditional petrolatum carriers with biodegradable alternatives. Specialty chemical suppliers in the Netherlands and Belgium are scaling plant-derived excipient production to capture this forced transition. German topical drug facilities are absorbing 12-15% raw material cost increases during qualification of compliant base formulations.
Direct contracting between ambulatory surgical centers and generic manufacturers is disintermediating traditional wholesale distribution in the United States. GPO-negotiated lidocaine ointment contracts are losing share to two-step direct purchasing agreements that exchange volume commitments for price protection clauses. This behavior is most visible in Florida and Texas ASC clusters, where procurement officers are consolidating formulary decisions across multi-site networks.
Lidocaine Ointment Market Segmentation
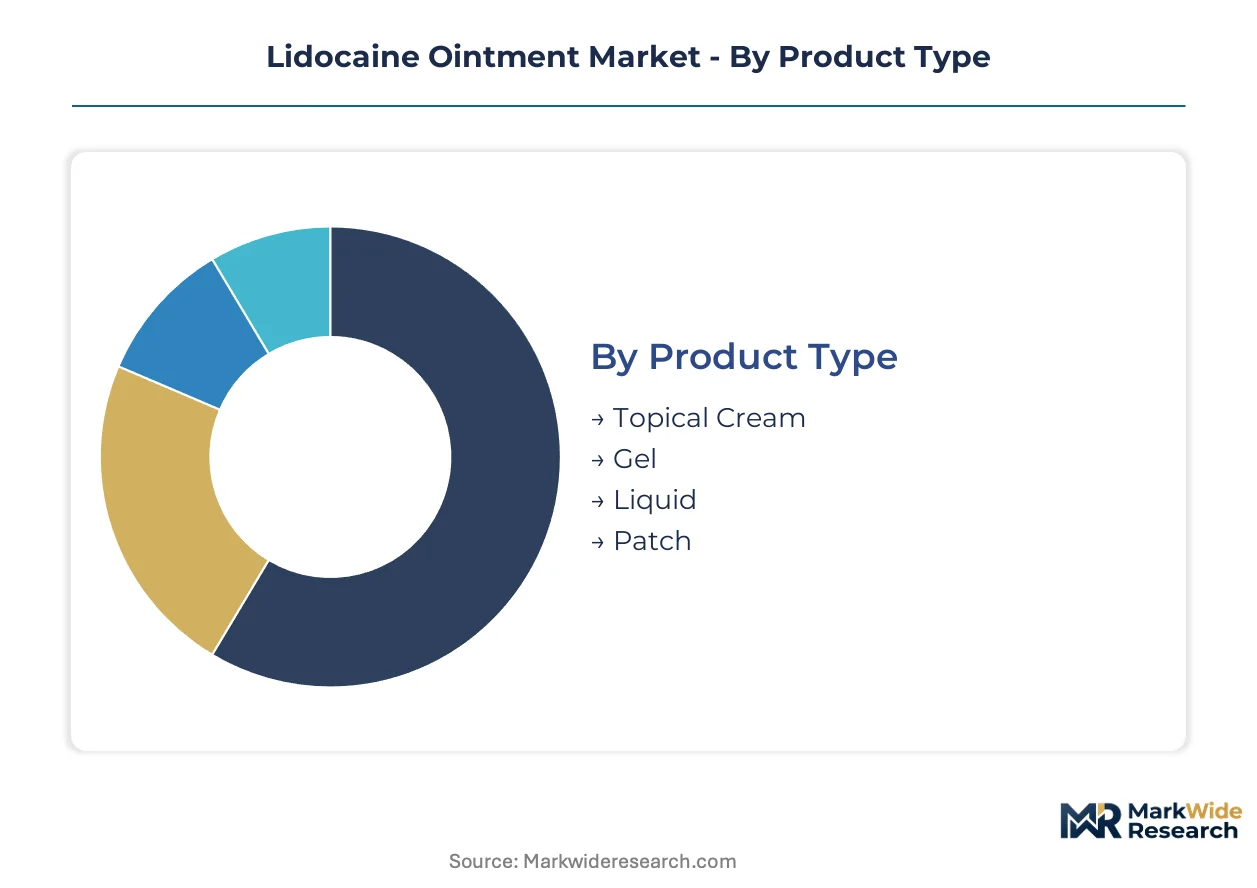
Lidocaine ointment segmentation reveals divergent regulatory pathways across product formats, with transdermal patches requiring extensive bioequivalence documentation while compounded creams operate under exemption frameworks. Understanding these certification tiers enables manufacturers to allocate R&D capital toward segments with the clearest approval trajectories and fastest commercialization timelines.
Product Type:
Patch formulations carry the heaviest FDA bioequivalence burden through pharmacokinetic endpoint trials, while gels and liquids navigate abbreviated approval pathways under semisolid guidance. Creams and compounded liquids exploit Section 503A exemptions in the United States.
- Patch:Transdermal matrix systems with extended-release lidocaine base require rigorous in vitro permeation studies and clinical endpoint trials for ANDA submission. Hospital outpatient departments in Germany and France are adopting these for multi-hour procedural coverage, displacing repeated ointment applications through reduced nursing labor.
- Gel:Hydrogel carriers with rapid skin penetration characteristics qualify for streamlined FDA bioequivalence under semisolid guidance when matched to reference listed drugs. Ambulatory surgical centers in Texas and Florida are consolidating procurement of unit-dose gel sachets for same-day minor surgeries.
- Topical Cream:Oil-in-water emulsions with 2-5% lidocaine base dominate retail pharmacy shelves through abbreviated new drug application pathways.
- Liquid:Aqueous or alcoholic solutions for mucosal application exploit compounding exemptions in the United States and simplified quality documentation in Canada.
Patch sits at the top of the volume ranking, with Gel climbing the fastest.
Application:
Cost tiering separates chronic condition management from acute procedural use, with pain management commanding premium pricing through repeat prescription volumes while dental applications compete on per-procedure unit economics.
- Pain Management:Post-herpetic neuralgia and chronic musculoskeletal indications drive recurring prescription volumes through Medicare Part D and private insurance formularies. Home care protocols in France and Germany are expanding patient self-administration, opening direct-to-patient subscription channels that bypass hospital procurement entirely.
- Dermatology:Pre-procedural numbing for cosmetic and therapeutic skin procedures requires rapid-onset formulations with documented dermal penetration rates. Telehealth-integrated prescribing through virtual dermatology platforms is generating electronic prescriptions linked to mail-order pharmacy fulfillment in the United States.
- Minor Surgery:Same-day procedural anesthesia in ambulatory settings prioritizes unit-dose packaging and rapid onset characteristics.
- Dental Care:Gingival and mucosal applications favor liquid and gel formats with taste-masking excipients for pediatric compliance.
Pain Management leads value concentration, with Dermatology expanding most quickly.
End User:
Customer type determines packaging scale and sterility requirements, with hospitals mandating bulk institutional formats and ISO 14644 cleanroom certification while home care channels accept non-sterile compounded alternatives.
- Hospitals:Inpatient and surgical departments require sterile-processed lidocaine ointment in bulk jars or unit-dose formats with full FDA Current Good Manufacturing Practice compliance. Extended FDA facility inspection backlogs are delaying product launches and freezing capital in work-in-process inventory for hospital-focused manufacturers.
- Home Care:Post-operative pain protocols and chronic condition self-management favor patient-friendly packaging with simplified dosing instructions. Direct contracting between patients and mail-order pharmacies is disintermediating traditional wholesale distribution in United States Medicare Advantage networks.
- Clinics:Outpatient procedure centers balance sterility requirements against cost constraints through group purchasing organization negotiations.
- Pharmacies:Retail and specialty dispensaries stock over-the-counter and prescription-strength formulations for walk-in demand.
Hospitals dominate procurement scale, with Home Care gaining share fastest.
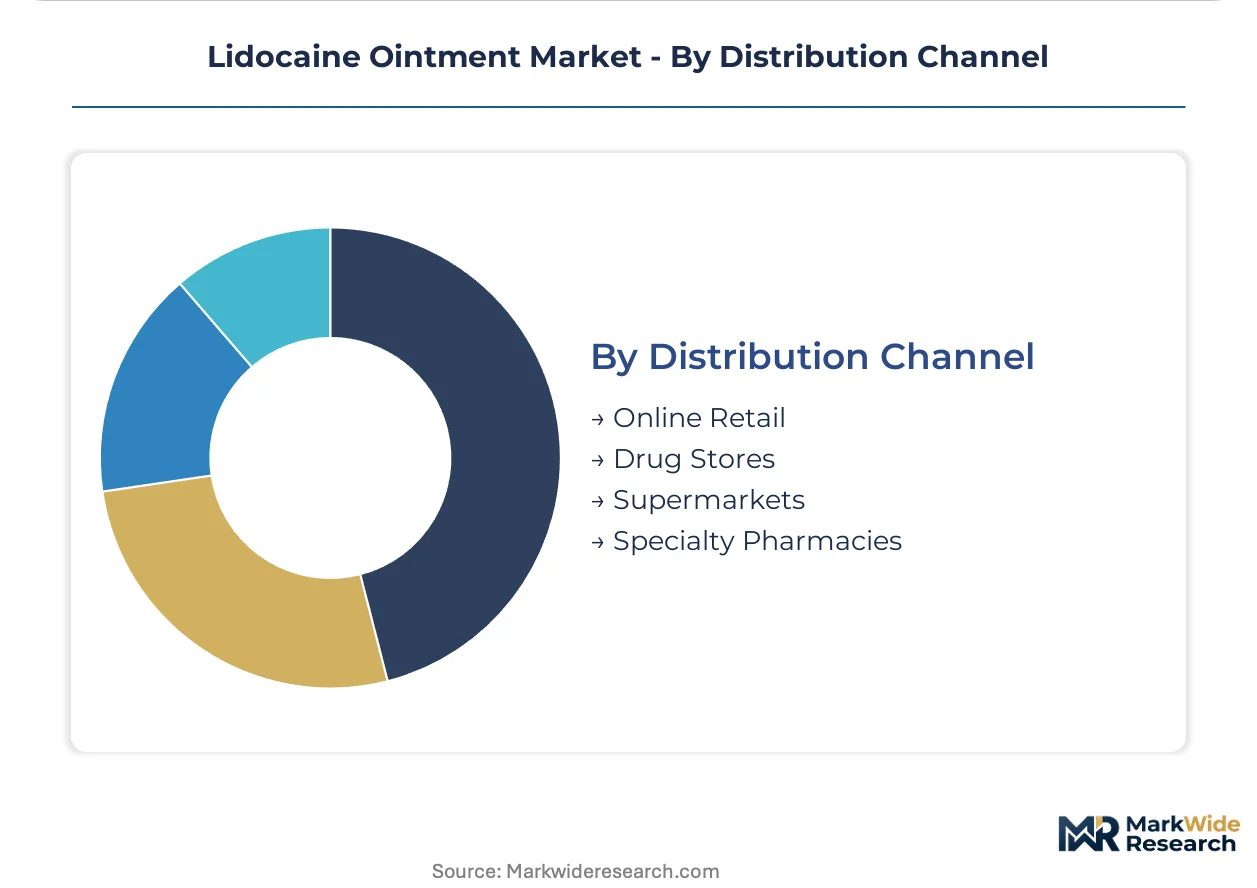
Distribution Channel:
Channel selection reflects patient access preferences and reimbursement mechanics, with online retail capturing subscription-driven chronic pain management while drug stores retain acute demand capture.
- Online Retail:Mail-order and direct-to-patient platforms exploit telehealth prescribing integration and automated refill protocols for chronic pain patients. Virtual dermatology consultations in the United States are generating electronic prescriptions fulfilled through integrated pharmacy networks.
- Drug Stores:Chain and independent pharmacies maintain immediate availability for acute procedural needs and same-day prescription fulfillment. CVS and Walgreens formulary placement determines manufacturer shelf presence in United States retail channels.
- Supermarkets:Mass-market retailers stock over-the-counter lidocaine formulations alongside first-aid and analgesic categories.
- Specialty Pharmacies:Compounding-focused dispensaries customize lidocaine strength formulations under Section 503A regulatory shelter.
Drug Stores anchor volume leadership, with Online Retail on the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lidocaine ointment manufacturing traces its industrial roots to post-war pharmaceutical corridors in the United States and Germany, where topical anesthetic formulation science first achieved commercial scale. These foundational clusters continue to anchor production expertise and regulatory precedent-setting.
United States
Ambulatory surgical centers in Florida and Texas drive institutional procurement volumes for unit-dose lidocaine formulations. FDA Current Good Manufacturing Practice enforcement and bioequivalence standards for topical generics shape facility investment requirements and approval timelines. Glenmark Pharmaceuticals U.S. Inc. maintains shelf presence across retail pharmacy chains through dermatology portfolio leverage.
Germany
Hospital outpatient departments in Bavaria and North Rhine-Westphalia pilot liposomal lidocaine delivery systems for multi-hour procedural coverage. EMA Q1 2024 guidance on semisolid dosage form bioequivalence streamlines market entry pathways for specialized manufacturers. REACH microplastic restriction amendments force reformulation of hydrophobic ointment bases, accelerating biodegradable excipient adoption.
France
Post-operative pain protocols shift toward patient-managed topical anesthesia, opening direct-to-patient subscription channels. ANSM oversight aligns with EMA quality frameworks while maintaining national pharmacovigilance requirements for topical drug adverse event reporting. Paris and Lyon metropolitan areas concentrate compounding pharmacy networks serving home care segments.
Canada
Health Canada PMRA maintains parallel quality frameworks to FDA standards, influencing export-oriented manufacturers' compliance investments. AstraZeneca Canada Inc. represents multinational presence in prescription topical anesthesia distribution. Ontario and Quebec hospital networks standardize procurement through provincial group purchasing organizations.
India
CDSCO regulates domestic topical drug manufacturing while Indian chemical zones supply lidocaine base API to global formulators. Alembic Pharmaceuticals Limited exemplifies domestic manufacturers expanding into regulated export markets. Gujarat and Maharashtra host specialized topical manufacturing facilities serving North American and European contract demand.
Lidocaine Ointment Market Vendor Landscape
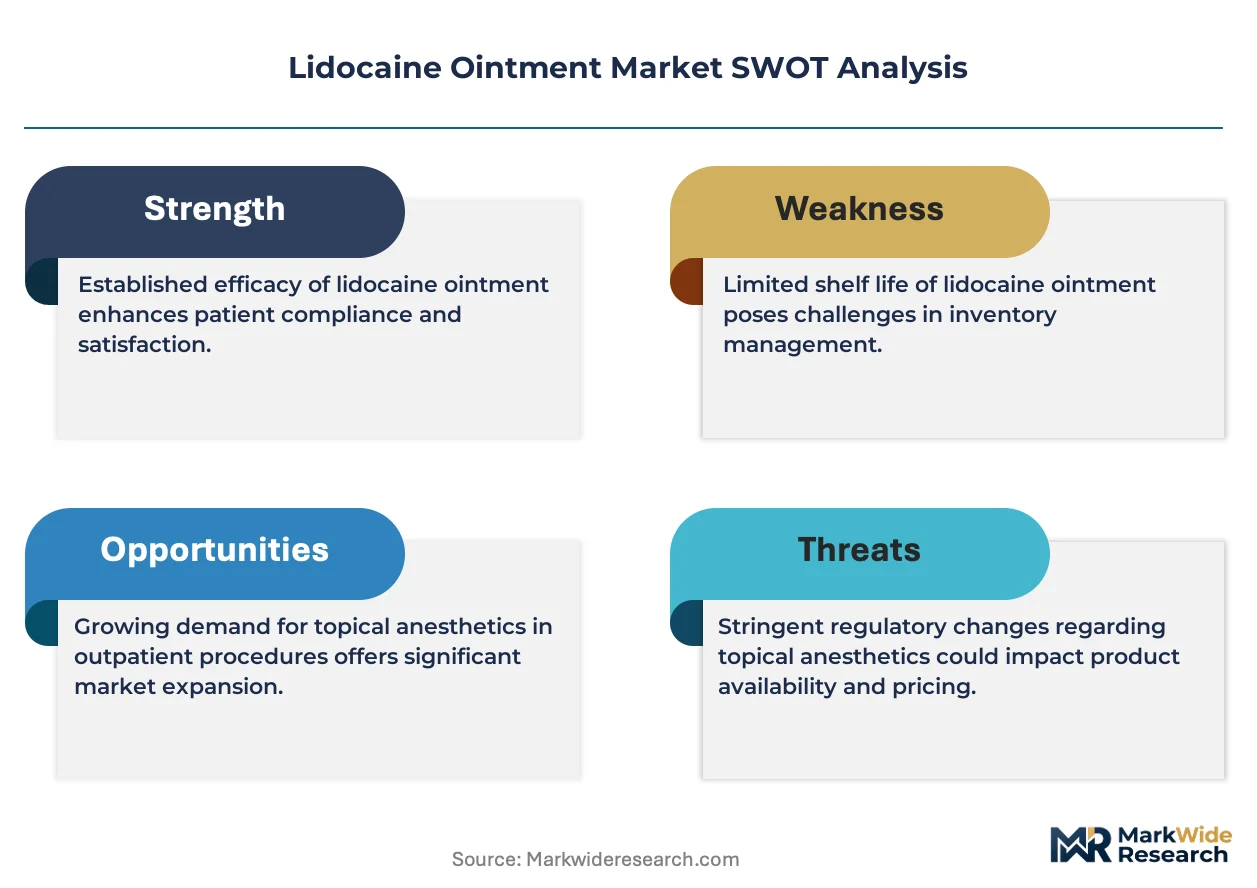
Premium-margin players sit above commodity-margin players across formulation complexity and regulatory certification tiers. The market exhibits moderate consolidation with three to four manufacturers capturing institutional procurement volumes while fragmented compounding pharmacies serve customized strength demand. Strategic archetypes include specialized topical manufacturers with sterile processing capabilities, diversified pharmaceutical conglomerates leveraging dermatology portfolios, and generic specialists competing on cost positioning. Dominant competitive moves encompass direct contracting with ambulatory surgical centers and accelerated sterile facility investments to meet tightening FDA inspection standards.
Among North American-based specialists, Taro Pharmaceutical Industries Ltd. anchors its position through specialized topical manufacturing capabilities, while Amneal Pharmaceuticals LLC and Teligent Inc. occupy positions within the generic infrastructure tier competing on abbreviated new drug application pathways. Sandoz AG represents the European generic specialist archetype with cost-positioning emphasis. These named entities exemplify how geographic manufacturing concentration and regulatory compliance specialization determine competitive viability rather than scale alone.
| Leading Market Players |
|---|
| Glenmark Pharmaceuticals U.S. Inc. |
| Taro Pharmaceutical Industries Ltd. |
| Amneal Pharmaceuticals LLC. |
| Teligent Inc. |
| Centura Pharmaceuticals Inc. |
| AstraZeneca Canada Inc. |
| Novocol Pharma |
| Sandoz AG |
| Alembic Pharmaceuticals Limited |
| Others |
Supply Flow & Price Mechanics
Specialized sterile processing technicians in Gujarat and Maharashtra pharmaceutical corridors command wage premiums that compress margin spreads between premium sterile formulations and standard compounded alternatives. Labor-cost differentials between Indian API manufacturing zones and North American sterile facilities drive three-tier pricing stratification across institutional procurement channels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates liposomal patch formulations from conventional ointments and compounded creams. Price differentiation hinges on FDA Current Good Manufacturing Practice certification tier and volume scale commitments through group purchasing organizations. Pricing pressure stems from topical NSAID substitution in osteoarthritis segments, compressing lidocaine gel margins. Ambulatory surgical centers exhibit highest price sensitivity through direct contracting negotiations, while hospital systems accept premium positioning for reduced nursing labor protocols.
Supply Chain Analysis
Workforce availability constraints in ISO 14644 cleanroom-certified facilities limit sterile processing capacity expansion in the United States and Germany. Lidocaine base API production concentrates in Chinese chemical manufacturing zones and Indian pharmaceutical corridors, with hydrophilic and hydrophobic excipient sourcing anchored in European specialty chemical suppliers. Supply chain risk centers on export license volatility from API manufacturing regions. Distribution runs through wholesale networks disintermediated by direct ambulatory surgical center contracting in Florida and Texas clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where FDA bioequivalence tightening for topical generics accelerates consolidation among sterile-capable manufacturers. EMA Q1 2024 guidance on semisolid dosage forms creates immediate demand pull for specialized European entrants.
For Market Incumbents: Lock in ambulatory surgical center formulary decisions through multi-site direct purchasing agreements with price protection clauses. Accelerate sterile facility investments ahead of FDA inspection backlog resolution to capture institutional procurement volumes. Vertical integration into liposomal encapsulation technology defends margin position against generic cost competitors. For New Entrants and Emerging Players: Liposomal delivery innovation offers technology-first wedge into hospital outpatient departments seeking multi-hour procedural coverage. Target home care self-administration channels in France and Germany where patient-managed protocols bypass traditional procurement. Pursue telehealth-integrated prescribing partnerships with virtual dermatology platforms for electronic prescription fulfillment. For Investors and Strategic Acquirers: Specialized generic manufacturers with sterile processing capabilities are the most active acquirer in this space, consolidating fragmented compounding pharmacy networks. Long-term viability favors facilities with dual FDA-EMA certification trajectories and established GPO relationships. Watch FDA facility inspection queue clearance velocity as inflection indicator for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Sterile Processing Certification | ISO 14644 cleanroom validation enables hospital procurement channel access and premium pricing capture. |
| Liposomal Formulation Development | Extended-release delivery systems displace conventional ointment protocols in German and French outpatient departments. |
| Direct ASC Contracting | Two-step purchasing agreements with Florida and Texas surgical networks disintermediate wholesale distribution. |
| Telehealth Platform Integration | Electronic prescribing through virtual dermatology consultations links diagnostic platforms to mail-order fulfillment. |
| EMA Bioequivalence Pathway Navigation | Q1 2024 semisolid guidance streamlines market entry for specialized manufacturers targeting European hospital networks. |
Methodological Framework
Multiple input streams — regulatory filing databases, hospital procurement records, and API trade flow documentation — were reconciled through bottom-up and top-down triangulation. Primary interviews with sterile facility operations directors, GPO contracts managers, and formulary pharmacists informed capacity and pricing assumptions. Secondary validation drew from FDA ANDA submissions, EMA marketing authorization applications, ClinicalTrials.gov topical anesthesia protocols, and CMS Medicare Part D formulary data.
Data-stream reconciliation across product type, application segment, end-user category, and regional regulatory cluster enabled consistent volume and value modeling throughout the forecast period. CAGRs were derived from segment-level growth rate reconciliation against macro healthcare expenditure trends. Industry-specific forecast inputs incorporated ambulatory surgical center expansion trajectories and FDA facility inspection queue dynamics.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to API export licensing volatility and topical NSAID substitution rates. Projections reflect assumptions around regulatory convergence pace and sterile processing capacity expansion timelines. Material deviation in FDA inspection clearance velocity or REACH microplastic enforcement stringency warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
India Over-The-Counter Drugs (OTC) Market
Pharmaceuticals
Targeted Therapeutics Market
Pharmaceuticals
Dopamine and Norepinephrine Reuptake Inhibitor Market
Pharmaceuticals
Cefdinir API Market
Pharmaceuticals
Pharma 4.0 Market
Pharmaceuticals
Mouth Ulcers Treatment Market
Pharmaceuticals
Global BHK Rabies Vaccine Market
Pharmaceuticals
Global DNA Repair Drugs Market
Pharmaceuticals
Systemic Antibiotics Market
Pharmaceuticals
Apalutamide API Market
Pharmaceuticals
Global Ebola Virus Vaccine Market
Pharmaceuticals
HPV Vaccines Market
Pharmaceuticals
Europe Adenomyosis Drugs Market
Pharmaceuticals
Global Anti-Neoplastic Agents Market
Pharmaceuticals
Injectable Ketamine Market
Pharmaceuticals
Lansoprazole API Market