
 Dental Biomaterials Market | 2026-2036
Dental Biomaterials Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Biomaterials Market Intelligence
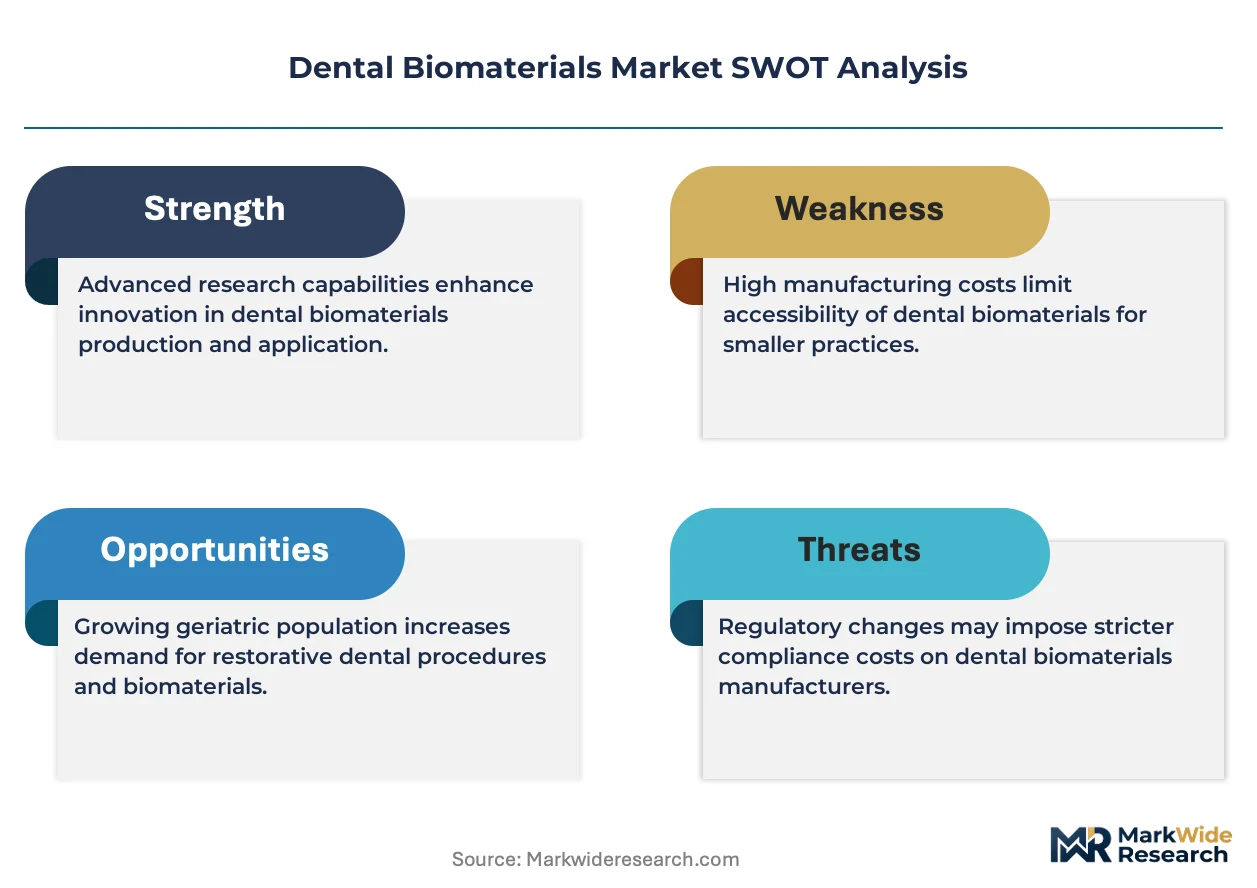
The EU MDR is decoupling legacy product lines from European market access, forcing reformulation of permanent implant surfaces and traceability systems. Dentsply Sirona leverages its integrated digital workflow platform to sustain laboratory partnerships across regulated markets. Straumann Group anchors premium titanium implant demand through captive research on surface osseointegration protocols. Geistlich Pharma differentiates its xenogeneic bone substitute portfolio with proprietary collagen matrix stabilization technology.
Dental biomaterials comprise engineered substances—ceramics, polymers, metals, and composites—formulated to interact with oral tissues for restoration, regeneration, or replacement of dental structures, typically meeting ISO 10993 biocompatibility thresholds and specified mechanical properties such as flexural strength exceeding 100 MPa for load-bearing applications. These materials serve prosthodontic, orthodontic, and implantological interventions where biological integration and functional longevity determine clinical success. Ceramics dominate anterior aesthetic restorations due to translucency matching natural dentition, while polymer-based resins and glass ionomer cements capture expanding share in pediatric and minimally invasive procedures. Metal alloys, particularly titanium and cobalt-chrome, retain structural primacy in subgingival implant fixtures and removable partial denture frameworks where fatigue resistance governs selection criteria.
FDA 510(k) clearance pathways and EU MDR conformity assessment shape product development timelines and clinical evidence requirements for dental biomaterial manufacturers seeking multi-jurisdiction commercialization. ISO 10993 biological evaluation standards and ASTM F67/F136 titanium specifications define the testing hierarchy that determines regulatory submission strategy. Japan's PMDA maintains distinct pharmaceutical affairs consultation requirements for novel bone graft substitutes, adding complexity to Asia-Pacific entry. Stakeholders must monitor evolving notified body capacity constraints in Europe and FDA digital health pre-certification expansions that could accelerate software-integrated biomaterial delivery systems.
Market Dynamics
The EU MDR's biocompatibility recertification mandate is fragmenting legacy product portfolios and forcing manufacturers to rebuild surface engineering capabilities from substrate chemistry through post-market surveillance systems.
Growth Catalysts
- Implantology workflow digitization:Chairside CAD/CAM systems are compressing restoration turnaround times from weeks to hours in United States specialty clinics.
- ISO 10993-23 in vitro testing harmonization:The updated biological evaluation standard is reducing animal testing requirements and accelerating regulatory submission timelines for novel ceramic formulations.
- China's hospital-based oral surgery expansion:Centralized procurement programs in tier-one cities are consolidating demand for premium titanium implant fixtures.
Market Restraints
- Zirconia powder supply concentration:Sinter-grade ceramic feedstock production clusters in limited Japanese and German chemical processing facilities.
- EU MDR notified body capacity constraints:The contraction of designated conformity assessment organizations is extending certification timelines for permanent implantable devices.
- Polymer degradation in moist environments:Hydrolytic instability limits long-term performance of resorbable synthetic membranes in guided bone regeneration procedures.
Strategic Opportunities
- India's dental tourism corridor:Mumbai and Bangalore surgical centers are capturing international patients seeking cost-advantaged implantology at quality-certified facilities.
- AI-assisted biomaterial selection:Machine learning algorithms trained on patient-specific anatomical data are converging with cloud-based treatment planning platforms.
- Brazil's ANVISA fast-track pathway:The priority review mechanism for breakthrough regenerative products is incentivizing local clinical trial investment.
Industry Challenges
- Biomaterials engineering talent scarcity:The intersection of dental clinical knowledge and polymer chemistry expertise remains underrepresented in European and North American labor markets.
- Legacy practice management integration:Digital workflow adoption requires retraining of laboratory technicians accustomed to conventional lost-wax casting protocols.
- Cross-border reimbursement fragmentation:Variability in national health system coverage for regenerative procedures complicates pricing standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Biomaterials Market |
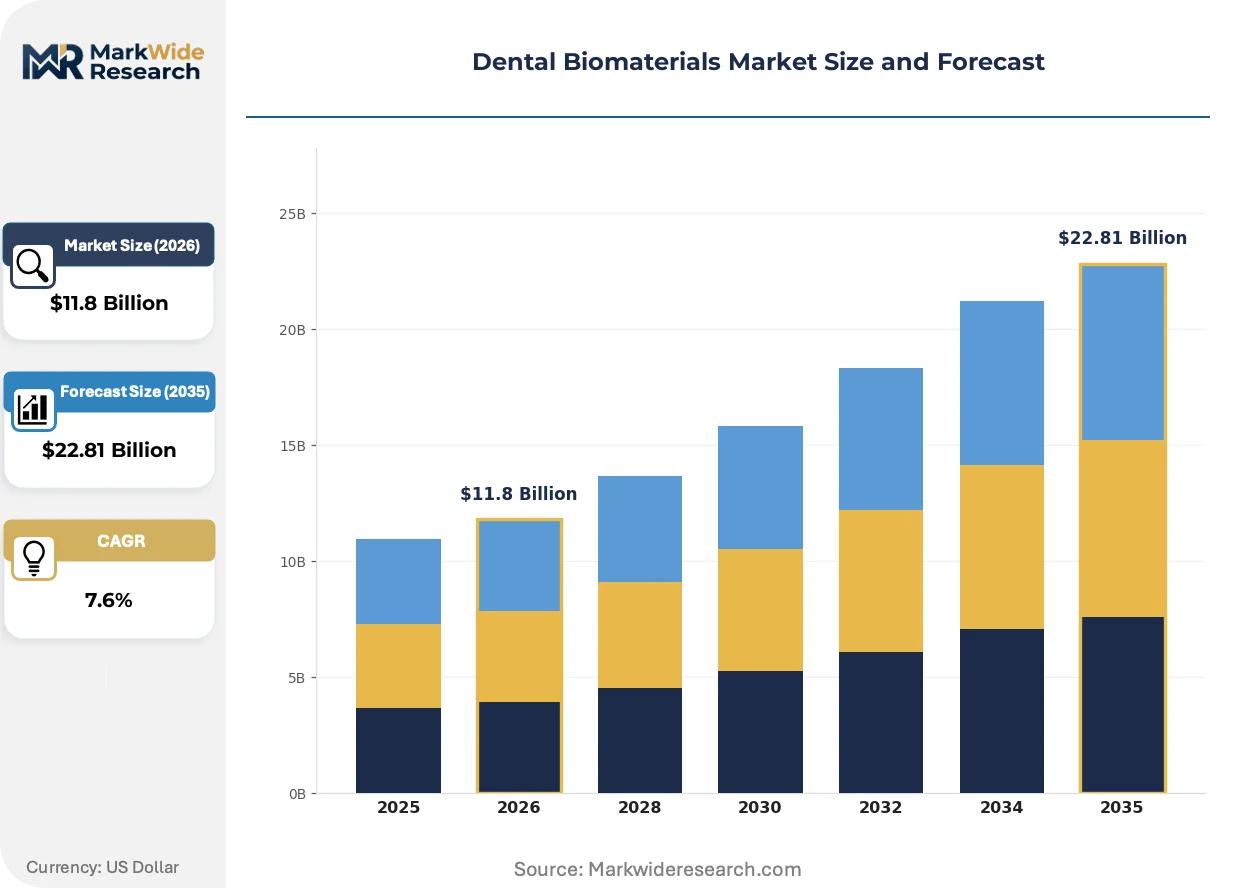
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $22.81 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceramics, Polymers, Metals, Composites Application: Restorative Procedures, Orthodontics, Prosthodontics, Endodontics, Periodontics End User: Dental Clinics, Dental Laboratories, Hospitals, Specialty Clinics Form: Powder, Liquid, Paste, Solid |
| Companies Covered | Dentsply Sirona, 3M, Straumann Group, Ivoclar Vivadent, Geistlich Pharma, Zimmer Biomet, GC Corporation, Kuraray Co., Ltd., Henry Schein, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Biomaterials Market Strategic Shifts & Innovations
Digital dentistry infrastructure is reconfiguring how biomaterials are specified, manufactured, and delivered, compressing the value chain between raw material suppliers and chairside application.
Bioactive glass formulations are regenerating mineralized tissue through controlled ion release kinetics. German and Swiss dental laboratories are adopting these materials for direct pulp capping and root canal sealing applications. The technology is converging with 3D-printed scaffold architectures to enable patient-specific defect reconstruction.
The EU MDR's Unique Device Identification mandate is imposing traceability requirements from raw material batch through explant documentation. Manufacturers must reconfigure quality management systems to capture device history records across multi-tier supply networks. Permanent implantable categories face the steepest compliance burden, with notified bodies demanding expanded clinical evidence portfolios.
Group purchasing organizations in United States dental service organizations are consolidating supplier relationships and unbundling technical service components from material procurement. Large multi-site practices in Texas and Florida are negotiating direct manufacturer contracts that bypass traditional distributor markups. This concentration is compressing margins for mid-tier ceramic and composite resin suppliers dependent on independent dealer networks.
Dental Biomaterials Market Segmentation
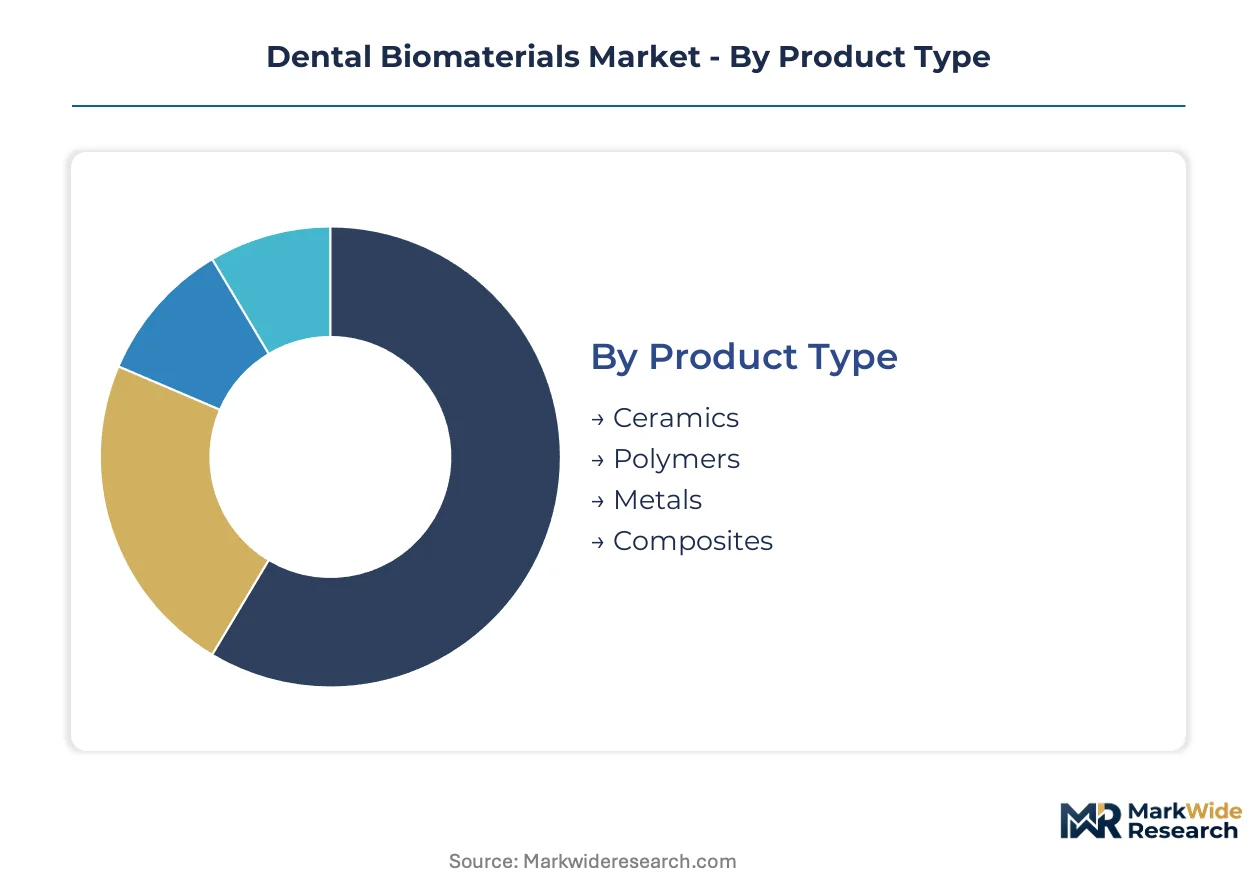
Biomaterial selection in dentistry hinges on mechanical load requirements, biological integration timelines, and manufacturing compatibility with digital workflows. Segmentation reveals how surface engineering capabilities and regulatory certification tiers partition commercial opportunity across material classes and clinical settings.
Product Type:
Cost tier structures procurement decisions, with premium formulations commanding differential pricing based on osseointegration performance and aesthetic matching precision.
- Ceramics:Zirconia and lithium disilicate formulations deliver translucency gradients matching natural dentition for anterior crowns and veneers. Demand concentrates in German and Swiss aesthetic-focused practices where chairside milling systems require sinter-grade powder consistency.
- Metals:Titanium alloys per ASTM F136 specifications and cobalt-chrome frameworks dominate subgingival implant fixtures and removable partial dentures. United States oral surgery centers prioritize these materials for fatigue resistance under masticatory loads exceeding 500N.
- Polymers:Methacrylate resins and PEEK polymers serve provisional restorations and implant abutments where machinability and biocompatibility intersect.
- Composites:Particle-filled resin systems capture direct restorative applications and core buildup procedures in pediatric and geriatric demographics.
Volume sits with metals; growth tilts toward ceramics.
Application:
Procedure reimbursement codes and clinical evidence requirements determine manufacturer R&D allocation across intervention categories.
- Restorative Procedures:Direct and indirect fillings, inlays, onlays, and crowns constitute the highest-frequency biomaterial consumption. China's tier-one hospital dental departments are scaling centralized procurement for bulk composite and glass ionomer cements.
- Prosthodontics:Fixed and removable prostheses require material systems spanning substructure metals through veneering ceramics. German dental laboratories are converging on monolithic zirconia to eliminate porcelain chipping failures.
- Implantology:Osseointegration surface protocols and regenerative membranes demand titanium substrate optimization and collagen stabilization chemistry.
- Orthodontics:Clear aligner thermoplastics and bracket adhesives represent polymer formulation specialization with distinct biomechanical requirements.
- Endodontics:Root canal sealers and obturation materials prioritize dimensional stability and antibacterial ion release kinetics.
- Periodontics:Guided tissue regeneration membranes and bone graft substitutes require resorption rate matching to defect healing timelines.
Procedure frequency favors restorative applications; margin expansion concentrates in implantology.
End User:
Customer type dictates service bundling expectations and technical support intensity from material suppliers.
- Dental Clinics:Chairside CAD/CAM adoption is compressing restoration turnaround from laboratory-dependent weeks to same-day delivery. United States specialty clinics in Texas and Florida are negotiating direct manufacturer contracts bypassing distributor networks.
- Dental Laboratories:Conventional lost-wax casting technicians require retraining for digital design workflows and milling center integration.
- Hospitals:China's hospital-based oral surgery expansion is consolidating demand for premium titanium fixtures through centralized procurement programs.
- Specialty Clinics:Mumbai and Bangalore implantology centers are capturing international dental tourism patients seeking cost-advantaged procedures.
Transaction volume aggregates at dental clinics; value capture concentrates in hospital procurement.
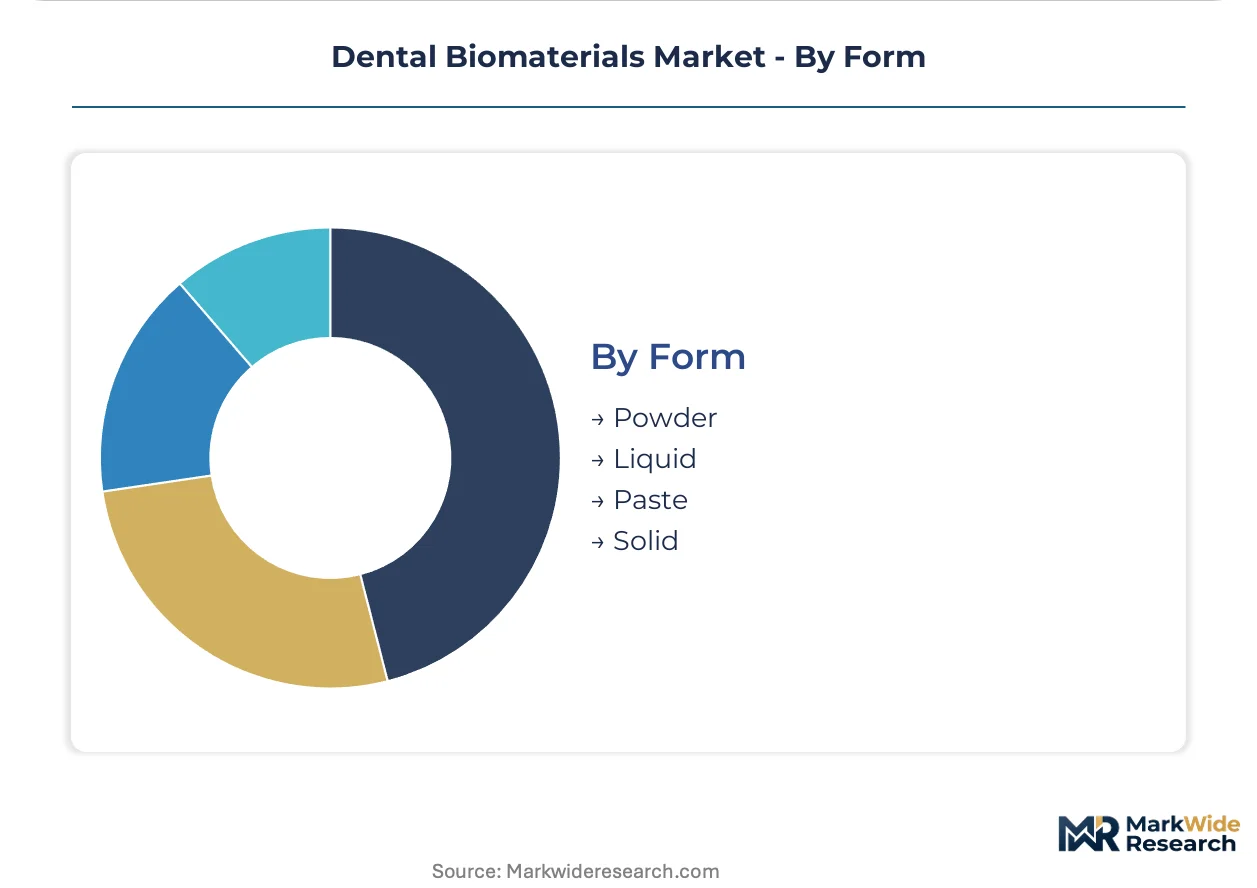
Form:
Supply chain configuration and shelf-life stability determine geographic distribution economics for physical material states.
- Powder:Sinter-grade zirconia and titanium feedstock require controlled atmosphere packaging and batch traceability per EU MDR Unique Device Identification mandates.
- Liquid:Monomer systems and etching solutions face shipping restrictions on volatile organic compound content.
- Paste:Pre-mixed composite and cement formulations reduce chairside mixing variability for direct restorative procedures.
- Solid:Milling blanks and pre-sintered zirconia discs enable CAD/CAM subtractive manufacturing with predictable shrinkage compensation.
Distribution complexity rises with powder; paste formulations are gaining share in chairside workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Basel anchors European dental biomaterials innovation through Straumann Group's surface osseointegration research and Geistlich Pharma's xenogeneic bone substitute development. The Swiss corridor concentrates premium titanium implant fixture manufacturing and collagen matrix stabilization chemistry expertise.
United States
Texas and Florida dental service organizations negotiate direct manufacturer contracts that bypass traditional distributor markups. FDA 510(k) clearance pathways shape product development timelines for multi-jurisdiction commercialization. Chairside CAD/CAM adoption in United States specialty clinics compresses restoration turnaround from weeks to hours.
Germany
German dental laboratories converge on monolithic zirconia to eliminate porcelain chipping failures in fixed prosthodontics. EU MDR biocompatibility recertification mandates fragment legacy product portfolios and force surface engineering capability rebuilds. The Stuttgart-Munich corridor houses sinter-grade ceramic feedstock processing facilities serving aesthetic-focused practices.
China
Tier-one cities scale centralized procurement for premium titanium implant fixtures through hospital-based oral surgery expansion. NMPA regulatory consultation requirements add complexity to novel bone graft substitute entry. Shanghai and Beijing surgical departments consolidate demand for bulk composite and glass ionomer cements.
Japan
PMDA maintains distinct pharmaceutical affairs consultation requirements for regenerative products entering Asia-Pacific markets. Japanese chemical processing facilities concentrate sinter-grade zirconia powder production for CAD/CAM milling systems. Tokyo-Osaka dental laboratories adopt bioactive glass formulations for direct pulp capping applications.
India
Mumbai and Bangalore implantology centers capture international dental tourism patients seeking cost-advantaged procedures at quality-certified facilities. CDSCO regulatory frameworks govern import and distribution of permanent implantable devices. Maharashtra and Karnataka surgical clusters scale capacity for guided bone regeneration membrane procedures.
Dental Biomaterials Market Key Industry Players
The competitive structure tilts toward integrated workflow platform providers with captive laboratory partnerships. Tiered player concentration separates premium titanium implant specialists from mid-tier ceramic suppliers and commodity resin formulators. Strategic archetypes span surface engineering specialists, digital workflow integrators, and regenerative membrane developers. Dominant competitive moves include M&A for CAD/CAM software capabilities and strategic partnerships with dental service organizations.
Among Switzerland-based specialists, Straumann Group and Geistlich Pharma exemplify premium-tier positioning through substrate optimization and collagen stabilization chemistry respectively. Dentsply Sirona anchors the integrated digital workflow archetype with laboratory partnership networks across regulated markets. These three entities represent distinct competitive vectors: surface science depth, regenerative biologics expertise, and end-to-end digital infrastructure control.
| Leading Market Players |
|---|
| Dentsply Sirona |
| 3M |
| Straumann Group |
| Ivoclar Vivadent |
| Geistlich Pharma |
| Zimmer Biomet |
| GC Corporation |
| Kuraray Co., Ltd. |
| Henry Schein |
| Others |
Cost & Logistics Intelligence
Chairside CAD/CAM milling adoption is simultaneously compressing restoration turnaround economics and concentrating procurement power among dental service organizations capable of direct manufacturer negotiations. This technology shift reconfigures cost structures from laboratory-mediated markups toward powder-to-blank supply efficiencies, while EU MDR traceability mandates layer compliance costs onto raw material batch documentation.
Pricing Analysis
Osseointegration performance metrics anchor value-based pricing for titanium implant fixtures, with premium tiers commanding differential positioning based on surface protocol clinical evidence and ISO 10993 certification depth. Price differentiation separates FDA 510(k) cleared devices from economy-tier alternatives lacking comparable biocompatibility portfolios. Cost compression in mid-tier ceramic restorations is intensifying because United States group purchasing organizations consolidate supplier relationships and unbundle technical service components. Pediatric and geriatric direct restorative segments exhibit highest price sensitivity, while hospital-based oral surgery centers in China prioritize fatigue resistance specifications over unit cost.
Supply Chain Analysis
EU MDR Unique Device Identification mandates and ISO 10993 biological evaluation standards gate supplier qualification, forcing tiered documentation from raw material batch through explant. Sinter-grade zirconia powder production clusters in Japanese and German chemical processing facilities, while titanium feedstock draws from specialized alloy producers meeting ASTM F136 specifications. Single-source vulnerability concentrates in sinter-grade ceramic feedstock, with limited qualified suppliers for CAD/CAM milling consistency. Distribution runs through dental service organization procurement platforms in Texas and Florida, alongside traditional laboratory dealer networks serving independent practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race, with players pursuing captive control over surface engineering protocols and digital workflow software to defend margin structures against procurement consolidation.
For Market Incumbents: Anticipate margin compression from dental service organization direct contracting by securing exclusive CAD/CAM software partnerships and deepening in-house production of sinter-grade zirconia blanks. Surface osseointegration research capabilities and EU MDR notified body relationships represent critical defensive moats against emerging ceramic specialists. For New Entrants and Emerging Players: Dental laboratories transitioning from lost-wax casting to digital workflows present partnership opportunities for bioactive glass formulation specialists and 3D-printed scaffold developers. India's Mumbai and Bangalore surgical corridors offer the most penetrable geography for cost-advantaged guided bone regeneration membrane entry, with CDSCO regulatory pathways enabling quality-certified positioning at price points below Swiss and German incumbents. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated workflow platform providers seeking regenerative biologics or surface engineering depth. Long-term viability favors targets with proprietary collagen matrix stabilization or titanium substrate optimization IP, alongside FDA 510(k) and EU MDR certification portfolios. Watch ANVISA fast-track pathway utilization in Brazil as inflection signal for emerging market clinical trial investment intensity.| Strategic Initiative | Industry Significance |
|---|---|
| CAD/CAM Software Acquisition | Dentsply Sirona's platform control demonstrates workflow integration value for laboratory retention. |
| Surface Engineering R&D Expansion | Straumann Group's captive osseointegration protocols anchor premium titanium implant pricing power. |
| EU MDR Certification Investment | Notified body capacity constraints extend timelines, rewarding early compliance expenditure. |
| Hospital System Partnership | China's centralized procurement programs consolidate demand for premium fixture suppliers. |
| Regenerative Biologics Pipeline | Geistlich Pharma's xenogeneic bone substitutes capture margin expansion in guided tissue regeneration. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with dental laboratory technicians, biomedical procurement managers at hospital systems, GPO contracts specialists, and surface engineering R&D directors. FDA 510(k) clearance databases, EU MDR notified body documentation, NMPA consultation records, and ISO 10993 biological evaluation standards provided certification pathway validation. Bottom-up demand modeling from procedure volume and material consumption rates triangulated against top-down manufacturer revenue estimates.
Granularity-level modeling disaggregated the market by material class, application procedure, end-user facility type, and physical form across the projection horizon. Ceramic, metal, polymer, and composite resin segments were analyzed separately for digital workflow compatibility and regulatory submission requirements. CAGRs derived from procedure frequency trends, reimbursement code evolution, and adoption curves for chairside CAD/CAM systems. Forecast inputs incorporated dental service organization consolidation rates and tier-one city hospital procurement scaling in China.
Caveats apply where EU MDR notified body capacity constraints, zirconia powder supply disruptions, or reimbursement code revisions for regenerative procedures could materially shift the outlook. A model refresh is warranted upon material change in FDA digital health pre-certification expansion or ANVISA fast-track pathway utilization rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Materials
Oral Bone Implant Material Market
Dental Materials
Australia and New Zealand Dental Biomaterials Market
Dental Materials
Sensitive Toothpaste Market
Dental Materials
Dental Fluoride Varnish Market
Dental Materials
Dental Restorative and Regenerative Material Market
Dental Materials
Artificial Teeth Market
Dental Materials
Asia-Pacific Toothpaste Market
Dental Materials
Dental Matrix Systems Market
Dental Materials
Global Endodontic Consumables Market
Dental Materials
Dental Composites Market
Dental Materials
Cold Light Teeth Whitening Kit Market
Dental Materials
Global Zirconia Based Dental Materials Market
Dental Materials
Dental Bleaching Materials Market
Dental Materials
Dental Alloys Market
Dental Materials
Toothpaste Market
Dental Materials
Dental Fiber Posts Market