
 Global Endodontic Consumables Market | 2026-2036
Global Endodontic Consumables Market Size, Share, and Industry Trends Forecast 2026-2036
Global Endodontic Consumables Market Foresight
EU MDR is realigning the cost-of-entry calculus for endodontic consumables manufacturers seeking CE marking in Europe. Dentsply Sirona leverages its vertically integrated manufacturing network to absorb compliance costs across multiple product lines. Envista anchors its competitive position through sustained R&D investment in nickel-titanium file metallurgy. Septodont differentiates by concentrating its formulation expertise in bioceramic sealer chemistry.
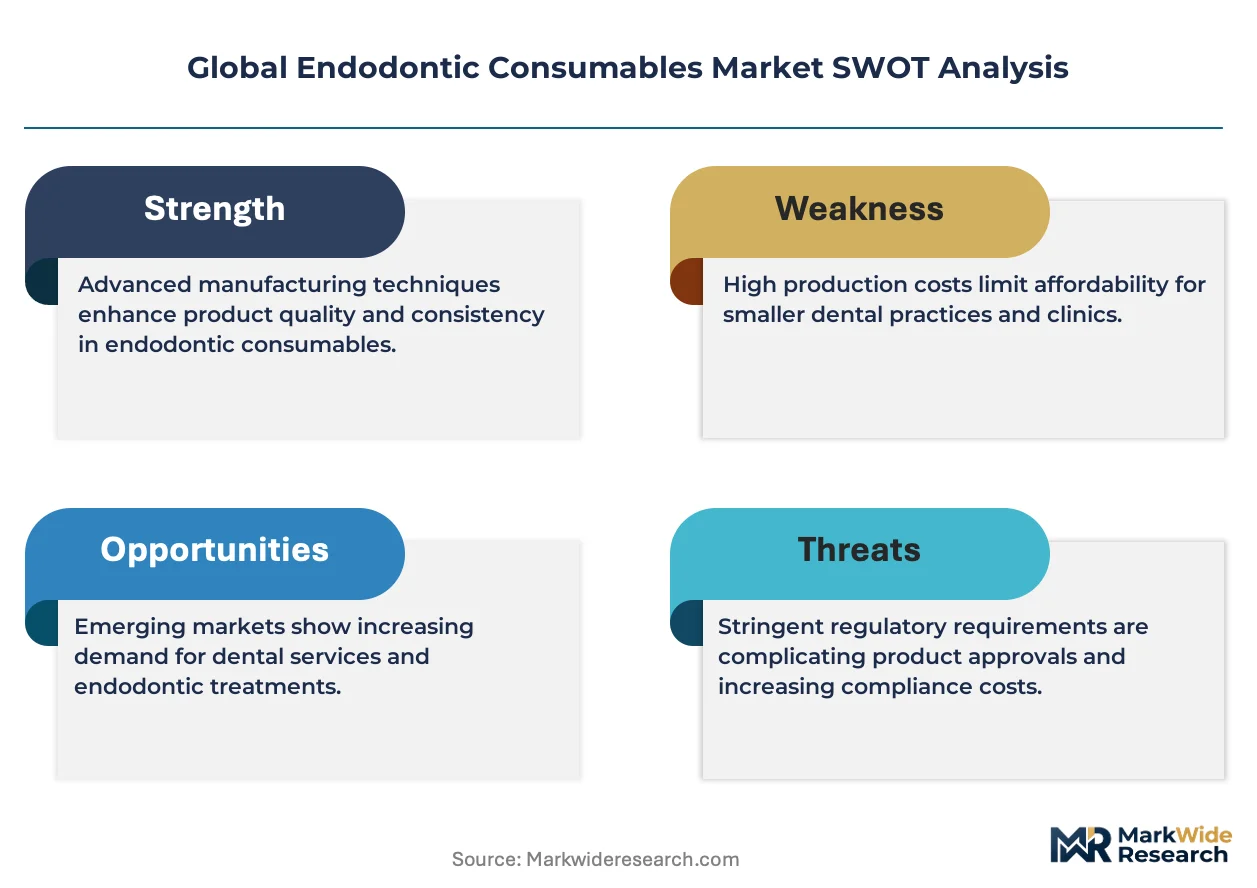
Endodontic consumables encompass sterile instruments and materials engineered for root canal therapy, including nickel-titanium rotary files with taper geometries between 0.04 and 0.12, gutta-percha obturation points, and sodium hypochlorite-based irrigants formulated at 2.5% to 5.25% concentrations. These products serve the primary purpose of disinfecting, shaping, and sealing the root canal system to preserve natural dentition. Endodontic files dominate product-type revenue due to their single-use disposability and continuous metallurgical upgrades, while bioceramic sealers represent the fastest-expanding category as clinicians shift from resin-based to hydrophilic sealing platforms. Specialty clinics command the highest per-procedure consumable intensity among end-user segments, driven by complex retreatment caseloads and dedicated microscope-assisted workflows.
FDA 510(k) clearance pathways govern U.S. market access for endodontic files and obturation materials, while Japan's PMDA enforces Japan Industrial Standards for nickel-titanium alloy composition in rotary instruments. ISO 3630-1 sets dimensional and functional benchmarks for endodontic instruments that manufacturers must meet for international commercialization. Stakeholders must monitor how China's NMPA accelerates its standards harmonization with ISO frameworks, as this convergence will reshape which suppliers qualify for the country's expanding hospital procurement tenders.
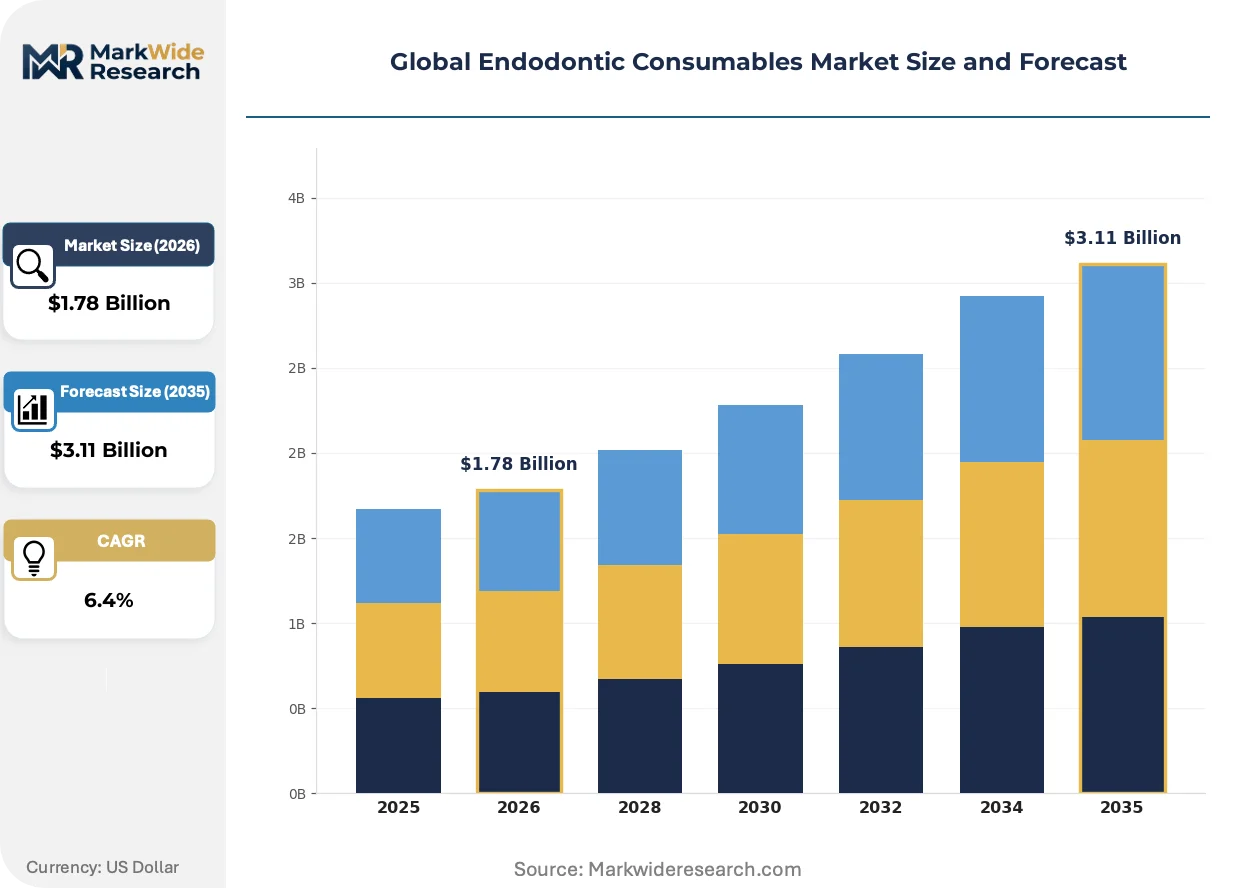
Market Dynamics
EU MDR's biocompatibility testing mandates are compressing margins for intracanal material suppliers while accelerating consolidation among file manufacturers unable to absorb compliance costs across limited product portfolios.
Growth Catalysts
- China's tier-one city consolidation:Private dental chains in Shanghai, Beijing, and Guangzhou are centralizing procurement into multi-year supply agreements, locking in volume commitments that stabilize manufacturer revenue visibility.
- Nickel-titanium metallurgy advances:Heat-treated rotary files with controlled memory properties now enable single-visit retreatment protocols, expanding addressable procedure volume in specialty clinics.
- ISO 3630-1 harmonization:China's NMPA is accelerating alignment with international dimensional standards, reducing technical barriers for foreign file manufacturers seeking hospital tender qualification.
Market Restraints
- Nickel price volatility:Nickel-titanium alloy feedstock costs fluctuate with Indonesian and Philippine ore export policies, compressing gross margins for file producers without captive metallurgy capacity.
- EU MDR notification bottlenecks:Designated body capacity constraints in Germany and the Netherlands are extending CE marking timelines for bioceramic sealers by 12-18 months.
- Resin sealer substitution resistance:Established clinicians in Japan and Brazil continue favoring epoxy resin-based obturation systems despite bioceramic hydrophilicity advantages.
Strategic Opportunities
- Brazil's specialty clinic expansion:São Paulo and Rio de Janeiro are witnessing rapid endodontic service capacity additions, creating first-mover advantage for irrigant suppliers establishing direct distribution.
- Digital workflow integration:Cone-beam computed tomography-guided file selection is converging with 3D-printed obturation guides, enabling precision-matched consumable bundles.
- Japan's PMDA fast-track pathway:METI's innovation review program for nickel-titanium instruments offers accelerated market access for novel taper geometries.
Industry Challenges
- Microscope-assisted technique certification:Specialty clinics face acute shortages of endodontists trained in dental operating microscopy, limiting consumable utilization rates despite equipment installation.
- Legacy file inventory stranding:Clinicians holding pre-heat-treated stainless steel instrument stocks resist metallurgical upgrades, delaying single-use rotary file adoption in cost-sensitive practices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Endodontic Consumables Market |
| Market Size in 2026 | $1.78 Billion |
| Market Size in 2035 | $3.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endodontic Files, Gutta Percha, Irrigants, Sealers, Paper Points Application: Pulpitis Treatment, Root Canal Therapy, Apicoectomy Support, Dental Trauma Management, Pulp Regeneration End User: Dental Laboratories, Specialty Clinics, General Dentistry Practices, Academic Institutions, Dental Hospitals Distribution Channel: Dental Wholesale Distributors, Direct-to-Clinic Sales, Online Medical Platforms, Dental Supply Stores, Medical Distributors |
| Companies Covered | Dentsply Sirona, Envista, Septodont, Brasseler USA, Ultradent Products, COLTENE Holding, Ivoclar Vivadent, FKG Dentaire, Danaher, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Endodontic Consumables Market Shifts & Advancements
Digital imaging integration and hydrophilic material chemistry are converging to reshape procedural protocols, while regulatory harmonization is redrawing competitive qualification barriers across major economies.
Bioceramic sealers with mineral trioxide aggregate chemistry are displacing resin-based obturation systems in retreatment cases. German specialty clinics are adopting these platforms at the fastest pace in Europe. This shift is decentralizing sealer supply relationships away from traditional dental conglomerates toward formulation specialists with ceramic processing expertise.
EU MDR's tightened biocompatibility testing protocols for intracanal materials are forcing reformulation of legacy sealer compositions. Manufacturers must now submit extended cytotoxicity and mutagenicity data packages to notified bodies. Bioceramic categories face the steepest compliance burden, yet their hydrophilic properties align more naturally with MDR's biological safety emphasis than epoxy resin alternatives.
Direct purchasing by consolidated dental chains is compressing distributor margins and shortening order cycles. China's tier-one private networks now negotiate annual frame contracts with file manufacturers, bypassing traditional dental supply houses. This pattern is most visible in Shanghai, where chain procurement officers centralize specification decisions across 40-plus clinic locations.
Global Endodontic Consumables Market Segmentation
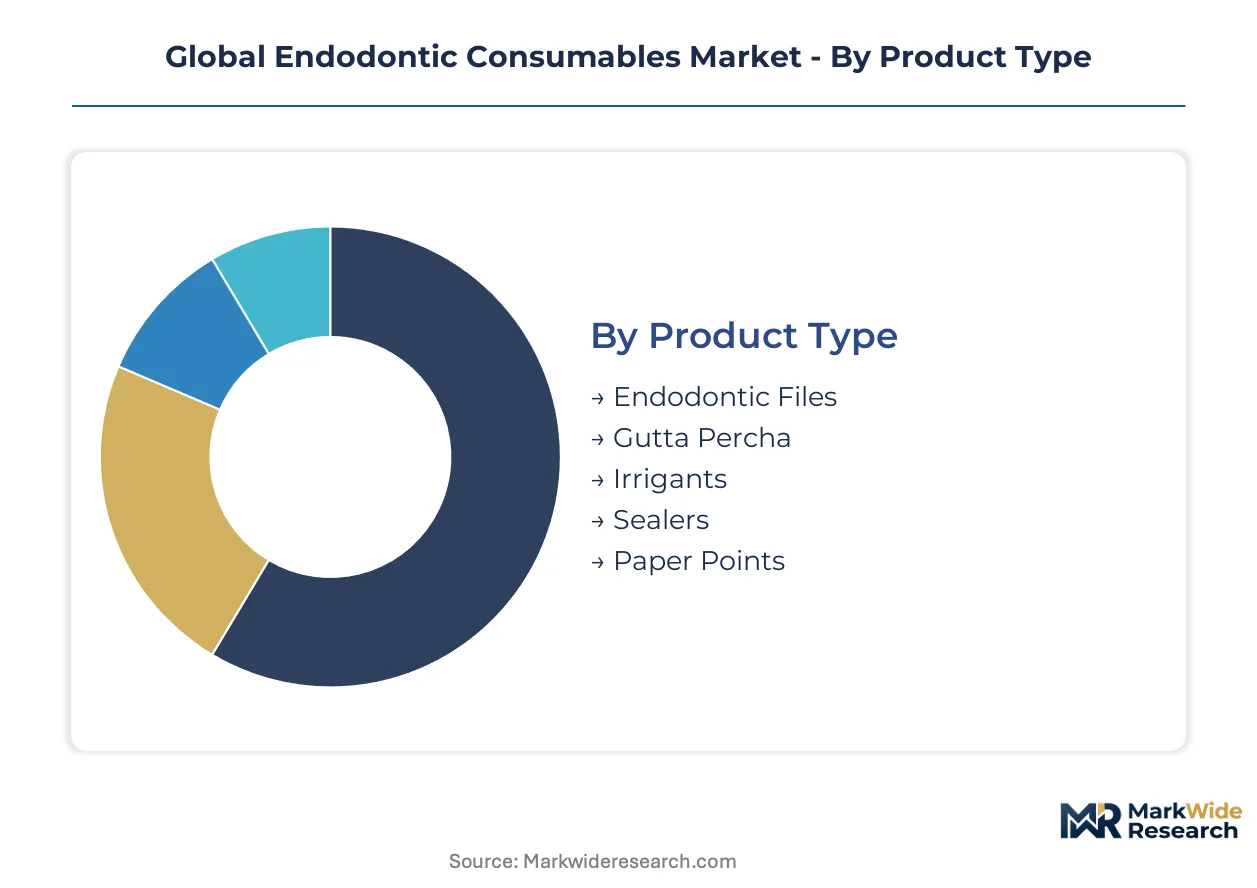
Segmentation in the Global Endodontic Consumables Market reveals how procurement patterns diverge across clinical settings and how metallurgical innovation reshapes product hierarchies. Understanding these divides helps suppliers align R&D investments with where procedural volume and margin concentration actually sit.
Product Type:
Upgrade cycles vary dramatically across instrument categories, with metallurgical advances forcing faster replacement timelines for nickel-titanium files than for legacy obturation materials.
- Endodontic Files:Nickel-titanium rotary instruments with controlled memory properties now dominate specialty clinic procurement in Germany and Japan. Heat-treated alloys enabling single-visit retreatment protocols are displacing stainless steel inventories in Shanghai's consolidated dental chains.
- Sealers:Bioceramic formulations with mineral trioxide aggregate chemistry are gaining share fastest in retreatment applications. German clinics lead European adoption, while Japanese clinicians resist switching from epoxy resin systems despite hydrophilic performance advantages.
- Gutta Percha:Standardized obturation points remain the reference material for canal sealing across Brazil's expanding specialty clinic network.
- Irrigants:Sodium hypochlorite solutions at 2.5% to 5.25% concentrations anchor disinfection protocols in hospital-based endodontic departments.
- Paper Points:Absorbent cellulose instruments for canal drying face margin compression as clinics bundle procurement toward comprehensive file-irrigation-sealer systems.
Endodontic files sit at the top of the volume ranking, with sealers climbing the fastest as clinicians shift from resin-based to hydrophilic sealing platforms.
Application:
Procedure complexity determines consumable intensity, with retreatment cases demanding specialized file geometries and bioceramic compatibility that primary therapy rarely requires.
- Root Canal Therapy:Primary disinfection, shaping, and sealing procedures generate the baseline demand that sustains file and gutta-percha volume across general dentistry practices in China's tier-one cities.
- Pulpitis Treatment:Inflammatory pulp conditions in vital teeth require conservative instrument selection, limiting file diameter range and preserving per-procedure material economy.
- Apicoectomy Support:Surgical endodontic interventions demand microsurgical instruments and retrograde filling materials that specialty clinics source through direct manufacturer relationships.
- Dental Trauma Management:Emergency procedures for luxation and avulsion injuries require rapid-access irrigant and sealer inventories in hospital emergency departments.
- Pulp Regeneration:Experimental revascularization protocols in academic institutions drive demand for bioceramic scaffolds and specialized file systems with minimal canal wall engagement.
Root canal therapy commands the highest absolute volume, with apicoectomy support expanding most quickly as microscope-assisted surgical technique training expands in São Paulo and Rio de Janeiro.
End User:
Customer type dictates purchasing power and specification sophistication, with consolidated chains extracting volume discounts that independent practices cannot match.
- Specialty Clinics:Dedicated endodontic practices with microscope-assisted workflows achieve the highest per-procedure consumable intensity. Complex retreatment caseloads in Germany and Japan drive premium file and sealer specification.
- General Dentistry Practices:Cost-sensitive operators in Brazil and China's lower-tier cities delay metallurgical upgrades, maintaining stainless steel instrument inventories longer than clinically optimal.
- Dental Hospitals:Academic medical centers in Beijing and Shanghai centralize procurement through tender processes that favor suppliers with NMPA-ISO harmonized certification.
- Dental Laboratories:Indirect fabrication facilities consume minimal endodontic materials directly, functioning primarily as downstream recipients of impression and model work.
- Academic Institutions:Training programs in Tokyo and São Paulo generate demand for educational file assortments and simulation-compatible irrigant formulations.
Specialty clinics generate the highest revenue per procedure, with dental hospitals climbing fastest as China's hospital procurement centralization accelerates.
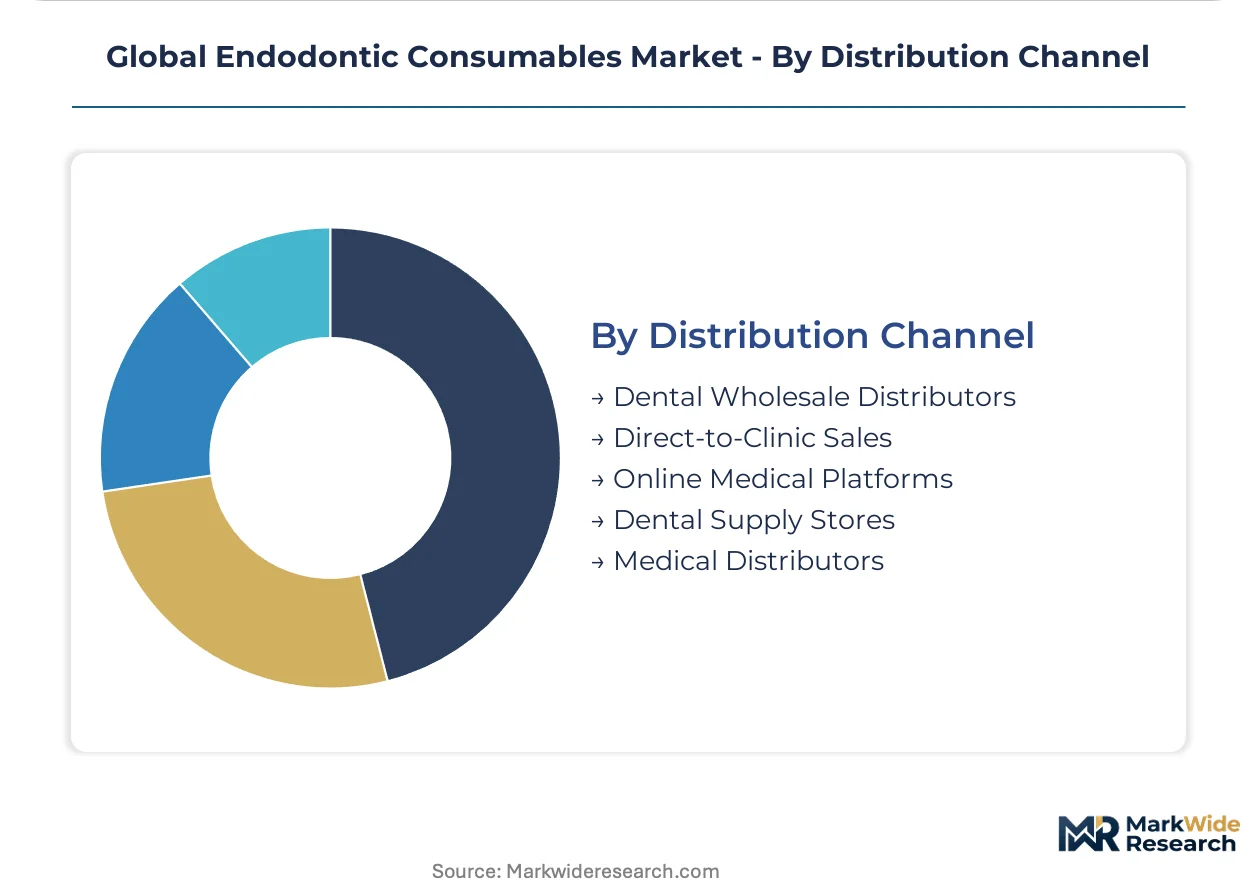
Distribution Channel:
Channel structure is fragmenting as consolidated clinic networks bypass traditional intermediaries, compressing distributor margins while shortening manufacturer cash conversion cycles.
- Direct-to-Clinic Sales:China's tier-one private dental chains in Shanghai and Beijing negotiate annual frame contracts with file manufacturers, centralizing specification decisions across 40-plus locations and eliminating wholesale markups.
- Dental Wholesale Distributors:Traditional supply houses retain relevance in fragmented markets like Brazil, where independent specialty clinics lack procurement scale for direct manufacturer engagement.
- Online Medical Platforms:Digital procurement channels gain traction among smaller Japanese general practices seeking price transparency on standardized irrigant and paper point replenishment.
- Medical Distributors:Broad-line healthcare suppliers serve hospital-based dental departments through integrated contracts that bundle endodontic consumables with broader surgical material portfolios.
- Dental Supply Stores:Retail-format channels persist in emergency replenishment scenarios, though their share erodes as inventory management shifts toward scheduled direct delivery.
Direct-to-clinic sales sit at the top of the volume ranking, with online medical platforms climbing fastest as procurement digitization penetrates cost-sensitive practice segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered precision endodontic instrument manufacturing through its industrial clusters in Baden-Württemberg and Bavaria, establishing metallurgical standards that shaped global rotary file design. This engineering heritage now competes with Asian manufacturing scale and North American regulatory innovation in a multi-polar market structure.
United States
Specialty endodontic practices in Texas and Florida drive premium consumable adoption through microscope-assisted retreatment volumes. FDA 510(k) clearance pathways for nickel-titanium files maintain stringent biocompatibility benchmarks that filter supplier qualification. The Greater Boston corridor anchors academic research into regenerative endodontic protocols.
Germany
Baden-Württemberg's precision engineering clusters supply heat-treated rotary files with controlled memory properties to European specialty clinics. EU MDR notification bottlenecks in German designated bodies extend CE marking timelines by 12-18 months for bioceramic sealers. Stuttgart-based manufacturers absorb compliance costs across diversified dental portfolios.
China
Shanghai and Beijing private dental chains centralize procurement into multi-year frame contracts covering 40-plus clinic locations each. NMPA accelerates standards harmonization with ISO 3630-1 dimensional benchmarks for nickel-titanium instruments. Yangtze River Delta manufacturing zones produce file blanks for global heat-treatment finishing.
Japan
Tokyo and Osaka specialty clinics resist bioceramic sealer adoption despite hydrophilic performance advantages, preserving epoxy resin system relationships. METI's innovation review program offers PMDA fast-track pathways for novel nickel-titanium taper geometries. Kanto region academic hospitals generate demand for educational file assortments.
Brazil
São Paulo and Rio de Janeiro specialty clinics expand endodontic service capacity through microscope-assisted technique investments. ANVISA enforcement of biocompatibility protocols lags EU MDR stringency, enabling faster market entry for reformulated sealers. Independent clinics in fragmented markets retain traditional dental wholesale distributor relationships.
Global Endodontic Consumables Market Competitive Landscape
The competitive structure tilts toward diversified dental conglomerates with metallurgy and formulation capabilities spanning multiple consumable categories. Three archetypes dominate: vertically integrated instrument manufacturers controlling nickel-titanium alloy supply chains, bioceramic formulation specialists with ceramic processing expertise, and broad-line dental suppliers bundling endodontic portfolios into integrated contracts. M&A activity concentrates among file manufacturers seeking metallurgy capacity, while strategic partnerships link digital imaging platforms with precision-matched consumable bundles.
Among diversified dental technology groups, Dentsply Sirona and Envista occupy positions reflecting scale-driven consolidation across rotary instrument and obturation material lines. Septodont exemplifies the formulation-specialist archetype through concentrated expertise in intracanal material chemistry. These three anchors represent distinct competitive vectors: manufacturing integration, metallurgical R&D investment, and ceramic sealer innovation.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Envista |
| Septodont |
| Brasseler USA |
| Ultradent Products |
| COLTENE Holding |
| Ivoclar Vivadent |
| FKG Dentaire |
| Danaher |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap specialists in Germany and Switzerland anchor premium-tier pricing discipline through captive metallurgy operations, while private-equity-rolled-up distributors in China's tier-one cities compress margins via centralized frame contracting. This ownership bifurcation shapes how nickel-titanium file producers allocate capacity between CE-marked European output and NMPA-registered hospital supply.
Pricing Analysis
Three-tier pricing structure across premium heat-treated rotary files, standard nickel-titanium instruments, and economy stainless steel alternatives governs procurement decisions. Price differentiation rests on ISO 3630-1 certification tier and after-sales technical support bundling. Cost compression in the economy tier intensifies as Yangtze River Delta manufacturers expand file blank capacity. Dental hospitals in Beijing and Shanghai exhibit lowest price sensitivity due to tender-based procurement, while independent general practices in Brazil's interior remain most cost-conscious.
Supply Chain Analysis
EU MDR biocompatibility testing and NMPA-ISO harmonization requirements gate qualified supplier access, concentrating finished instrument supply in Germany, Switzerland, and China's Yangtze River Delta. Raw material dependencies draw from Indonesian nickel ore, Japanese titanium sponge, and German precision grinding equipment. Single-source vulnerability runs through heat-treatment furnace operators in Baden-Württemberg. Distribution runs through direct-to-clinic frame contracts in consolidated markets and wholesale distributors in fragmented regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Endodontic Consumables Market reads as a late-cycle quality story, with retreatment volume growth and microscope-assisted technique diffusion tilting procurement toward heat-treated file geometries and bioceramic sealer platforms.
For Market Incumbents: Hedge nickel price exposure through long-term offtake agreements with Philippine and Indonesian ore processors. Absorb EU MDR compliance costs across diversified dental portfolios rather than siloing file-specific investments. Backward integration into heat-treatment furnace capacity in Baden-Württemberg defends margin position against toll-manufacturing dependency. For New Entrants and Emerging Players: Launch via direct distribution partnerships with São Paulo and Rio de Janeiro specialty clinics expanding microscope-assisted capacity. Target Brazil's fragmented independent clinic segment where ANVISA biocompatibility enforcement lags EU stringency, enabling faster sealer reformulation cycles. White-space exists in educational file assortments for Tokyo and São Paulo academic training programs. For Investors and Strategic Acquirers: Valuations sit cheapest among bioceramic formulation specialists lacking scale manufacturing infrastructure. Long-term viability favors ceramic processing expertise over commodity file production. Watch PMDA fast-track approvals for novel taper geometries as signal of Japan's openness to metallurgical innovation.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR notification bottlenecks reward early compliance investment with 12-18 month first-mover advantage. |
| Hospital System Partnership | China's NMPA-ISO harmonization enables foreign manufacturers to qualify for Beijing and Shanghai tender processes. |
| Backward Integration into Metallurgy | Captive nickel-titanium alloy supply insulates margin from Indonesian ore export policy volatility. |
| Software Companion Development | Cone-beam CT-guided file selection platforms enable precision-matched consumable bundle pricing. |
| Bioceramic Formulation Expansion | German specialty clinic adoption of MTA chemistry displaces legacy epoxy resin supplier relationships. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with endodontic instrument product managers, hospital purchasing committee members, GPO contracts managers, and bioceramic formulation chemists with secondary validation against FDA 510(k) filings, NMPA registration databases, EU MDR notified body decisions, and ISO 3630-1 technical committee documentation. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue disclosures.
Historical reference periods anchored growth rate derivation across the projection horizon, with segmentation modeling across product type, application complexity tier, end-user purchasing power, and distribution channel structure. CAGRs emerged from clinician adoption curve analysis for heat-treated file geometries and bioceramic sealer substitution patterns. Forecast inputs incorporated nickel price volatility scenarios and regulatory harmonization timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden nickel export restrictions or EU MDR designated body capacity collapse. Model assumptions reflect current metallurgical upgrade cycles and procurement centralization trajectories. A model refresh is warranted upon material change in China's NMPA-ISO harmonization pace or Japan's PMDA fast-track approval volume.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Materials
Dental Materials for 3D Printing Market
Dental Materials
Global Teeth Whitening Product Market
Dental Materials
Global Dental Bone Void Filler Market
Dental Materials
Calcium Hydroxylapatite Fillers Market
Dental Materials
Dental Alloys Market
Dental Materials
Global Zirconia Based Dental Materials Market
Dental Materials
Global Demineralized Bone Matrix Market
Dental Materials
Charcoal Teeth Whitening Powder Market
Dental Materials
Cold Light Teeth Whitening Kit Market
Dental Materials
Acrylic Dental Material Market
Dental Materials
Australia and New Zealand Dental Biomaterials Market
Dental Materials
Dental Fiber Posts Market
Dental Materials
Global Dental Zirconia Block Market
Dental Materials
Dental Zirconia Powder Market
Dental Materials
Sensitive Toothpaste Market
Dental Materials
Dental Bleaching Materials Market