
 Recycled Glass Aggregates Market | 2026-2036
Recycled Glass Aggregates Market Size, Share, and Industry Trends Forecast 2026-2036
Recycled Glass Aggregates Market Analytics
ASTM C33-grade specification upgrades for processed cullet is unwinding traditional barriers to structural concrete adoption. Strategic Materials Inc. leverages its nationwide collection infrastructure to secure post-consumer feedstock at scale. AeroAggregates specializes in ultra-lightweight foamed glass aggregate for geotechnical fill, while Momentum Recycling operates vertically integrated processing facilities that control quality from curbside collection to finished specification.
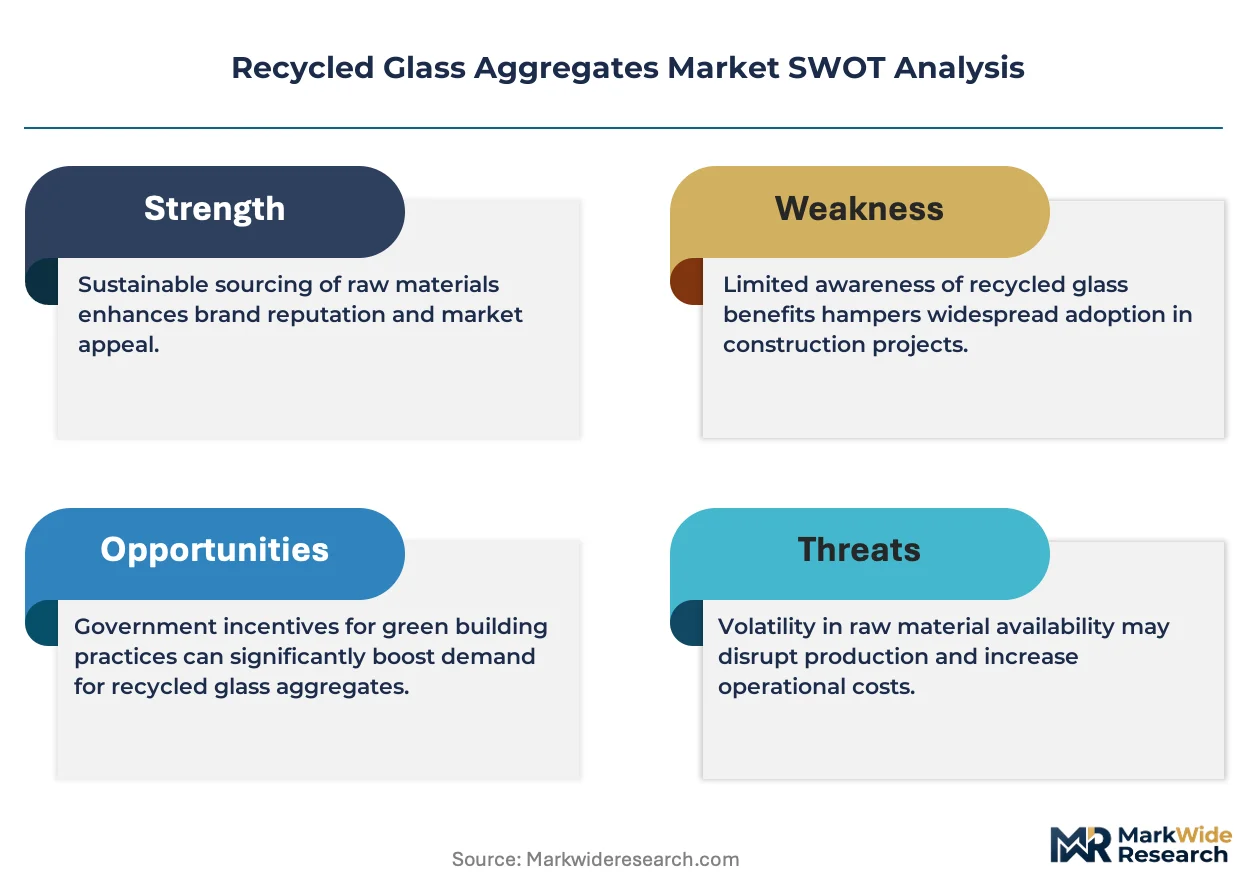
Recycled glass aggregates consist of post-consumer or post-industrial glass processed through crushing, screening, and beneficiation to achieve controlled gradation, low organic content, and minimal deleterious substances for engineered fill and bound applications. The material substitutes for natural aggregates in concrete, asphalt, drainage media, and pipe bedding where particle shape, abrasion resistance, and chemical stability meet project specifications. Crushed glass dominates volume throughput due to established crushing infrastructure and broad compatibility with existing handling equipment, while granulated glass captures premium positioning in decorative exposed-aggregate finishes and specialty mortar blends. Contractors represent the most price-sensitive procurement channel, whereas municipalities increasingly specify recycled content minimums that lock in demand irrespective of spot pricing.
EPA landfill diversion targets, state DOT supplemental specifications for glass in asphalt and unbound base courses, and ASTM D1241 gradation requirements collectively shape product acceptance and batch qualification protocols across the United States. State environmental agencies enforce post-consumer content thresholds that effectively mandate processor investment in optical sorting and contaminant removal. Stakeholders must monitor evolving performance-based specifications for alkali-silica reaction mitigation and freeze-thaw durability as the material penetrates load-bearing structural applications beyond its historical non-structural niche.
Market Dynamics
Federal infrastructure spending and municipal recycling mandates are compressing specification timelines, forcing processors to scale optical sorting capacity faster than landfill diversion rates can supply clean cullet feedstock.
Growth Catalysts
- LEED v4.1 Materials and Resources credit:The credit rewards projects using recycled content, pushing architects to specify processed cullet in concrete and asphalt applications where performance testing now validates structural equivalence.
- Road base engineering:State DOTs in Texas, California, and Florida have issued supplemental specifications permitting glass in unbound aggregate courses, opening volume demand from highway contractors.
- Alkali-silica reaction mitigation:Beneficiation technologies now reliably remove reactive silica phases, enabling processed cullet to meet ASTM C1260 standards for load-bearing concrete.
Market Restraints
- Contaminant removal capex:Ceramic, stone, and metal inclusions require density-based and optical sorting equipment that raises processing costs above virgin aggregate benchmarks in regions with weak landfill tipping fees.
- Feedstock geography:Post-consumer glass collection concentrates in coastal urban corridors, forcing inland processors to absorb freight costs or rely on lower-quality industrial scrap.
- Natural aggregate substitution:Crushed limestone and river gravel retain cost advantages in markets without recycled content mandates or carbon pricing mechanisms.
Strategic Opportunities
- Precast concrete penetration:Controlled-curing environments in precast plants allow producers to validate ASR-resistant glass blends before field deployment, bypassing contractor risk aversion.
- Foamed glass aggregate in geotechnical fill:Ultra-lightweight material addresses settlement-sensitive applications where conventional aggregate density creates structural loading problems.
- Buy Clean California Act:Embodied carbon thresholds for public projects create procurement preference for low-carbon aggregate alternatives with Environmental Product Declarations.
Industry Challenges
- Beneficiation technician scarcity:Optical sorter calibration and cullet quality control require specialized skills not covered in standard materials engineering curricula.
- ASTM specification lag:Committee C09 deliberations on performance-based glass aggregate standards move slower than state DOT adoption timelines, creating jurisdictional patchwork.
- Batch qualification protocols:Each project requires testing for deleterious substances and gradation compliance, extending pre-construction timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recycled Glass Aggregates Market |
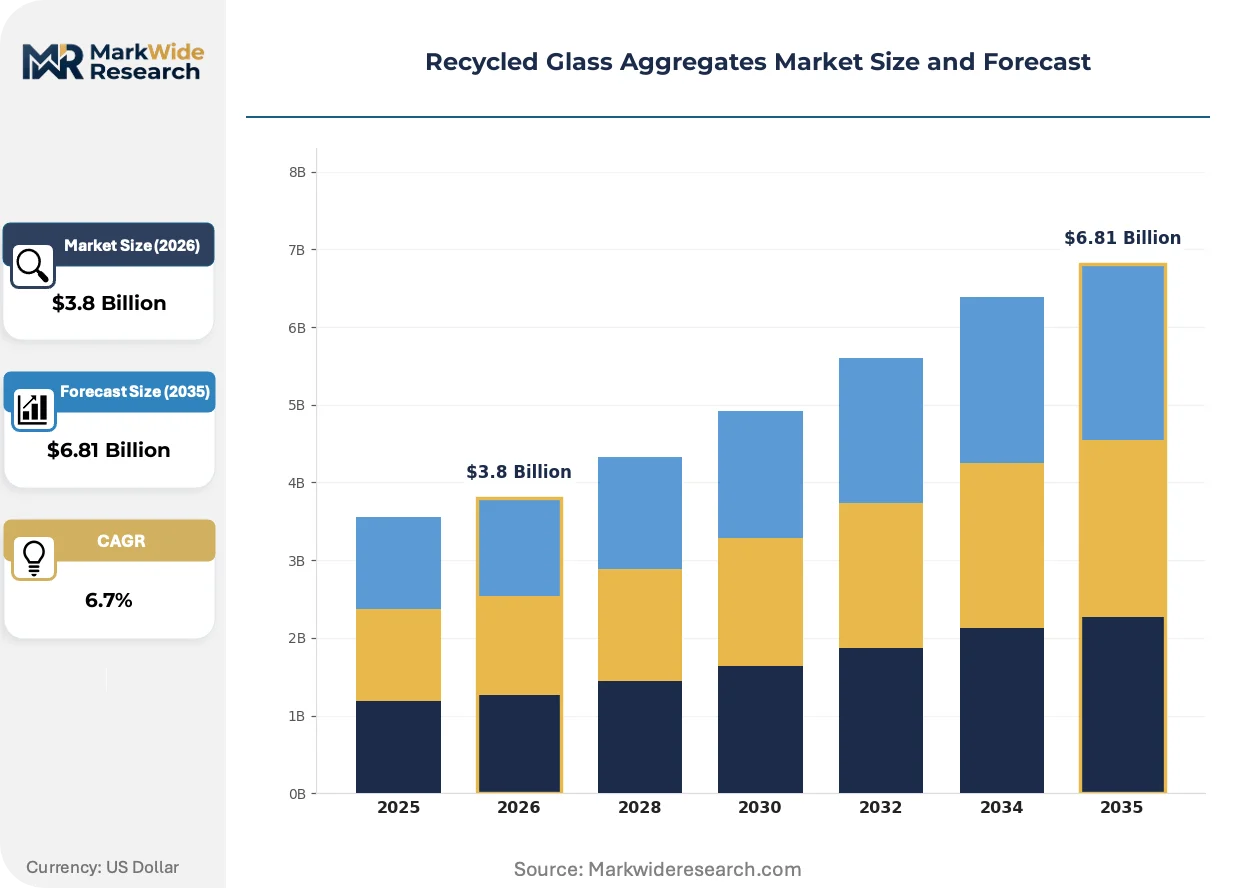
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crushed Glass, Granulated Glass, Mixed Color Glass, Clear Glass Application: Construction, Landscaping, Concrete Production, Road Base End User: Contractors, Architects, Builders, Municipalities Packaging Type: Bulk Bags, Pallets, Bags, Containers |
| Companies Covered | Strategic Materials Inc., Vetropack Holding, Owens-Illinois, Ardagh Group, AeroAggregates, Coloured Aggregates, Momentum Recycling, Glass Aggregate Systems, Rubble Master, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recycled Glass Aggregates Market Evolving Landscape
Beneficiation technology and specification science are converging to displace virgin aggregate in structural applications historically closed to recycled glass. Three forces are compressing the gap between laboratory validation and field deployment.
Optical sorting with near-infrared detection is miniaturizing from centralized MRF installations to mobile processing units that deploy directly at demolition sites. Contractors in Florida and Texas are piloting these units to produce specification-grade cullet without double-handling to fixed plants. The technology is compressing supply chain node counts and capturing margin previously lost to transportation.
EPA landfill diversion targets and state-level post-consumer content mandates are tightening in parallel, creating overlapping compliance obligations for processors serving public infrastructure. The intersection is forcing investment in contaminant detection beyond historical visual inspection protocols. Municipal procurement offices in the Northeast are now rejecting loads with ceramic content above 1% by mass.
Contractor procurement departments are consolidating specifications around performance-tested glass aggregate blends rather than prescriptive origin requirements. Master spec writers in commercial construction are inserting recycled content minimums that lock out virgin-only bids. The shift is most visible in federal GSA projects where Embodied Carbon in Construction Calculator scores influence award decisions.
Recycled Glass Aggregates Market Segmentation
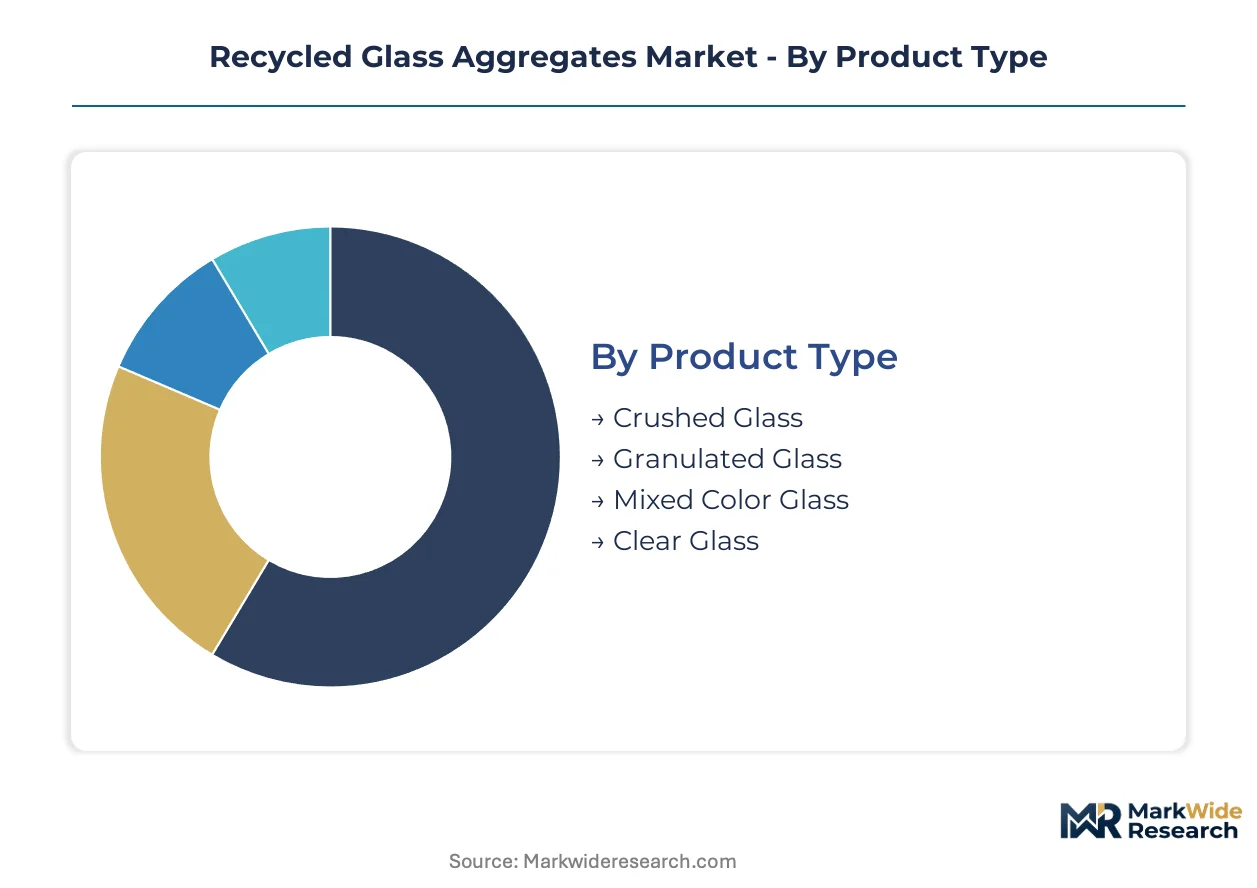
Segmentation in recycled glass aggregates reveals where specification science and procurement economics intersect. Product grades, application requirements, and end-user risk tolerance create distinct competitive arenas with diverging margin structures and substitution vulnerability.
Product Type:
Substitution pressure from virgin aggregates intensifies as product processing depth decreases—unbeneficiated mixed color glass faces the strongest displacement threat from limestone and river gravel.
- Crushed Glass:Produced through mechanical crushing and screening to achieve controlled gradation for engineered fill and bound applications. Demand concentrates in Texas and Florida highway projects where state DOT supplemental specifications now permit glass in unbound base courses, though contractors remain price-sensitive to virgin aggregate benchmarks.
- Granulated Glass:Finely processed material with uniform particle size distribution for specialty mortar blends and decorative exposed-aggregate finishes. Architects in California specify this grade for LEED v4.1 Materials and Resources credit compliance, locking in premium positioning despite higher unit costs.
- Mixed Color Glass:Unsegregated post-consumer cullet with limited beneficiation, primarily serving non-structural drainage media and pipe bedding where aesthetic requirements are minimal.
- Clear Glass:High-purity feedstock from container deposit programs, commanding price premiums in architectural concrete and specialty precast where color consistency matters.
Crushed glass retains volume leadership; granulated glass holds the steepest expansion curve.
Application:
Application segments diverge sharply in specification maturity—road base and landscaping operate under performance-tested protocols while structural concrete remains gated by ASR validation timelines.
- Construction:General fill and engineered applications including foundation backfill and utility trench bedding. Contractors in the Northeast favor this segment for municipal recycling mandate compliance, though batch qualification protocols extend pre-construction timelines.
- Concrete Production:Bound applications in ready-mix and precast where ASTM C1260 alkali-silica reaction testing determines eligibility. Precast plants in controlled-curing environments validate ASR-resistant blends before field deployment, bypassing contractor risk aversion.
- Landscaping:Decorative mulch, pathway surfacing, and drainage features with minimal structural requirements. This segment captures volume in coastal urban corridors where landfill diversion targets concentrate supply.
- Road Base:Unbound aggregate courses in highway construction where state DOT specifications permit glass substitution. Texas, California, and Florida have issued supplemental specifications opening volume demand from highway contractors.
Construction commands the largest revenue pool; concrete production is climbing the fastest as beneficiation technology matures.
End User:
End-user segments separate by procurement sophistication—municipalities lock in demand through recycled content mandates while contractors optimize on spot pricing.
- Contractors:Price-sensitive procurement channel optimizing for lowest delivered cost per ton. This segment resists glass aggregate premiums unless public specifications mandate compliance.
- Architects:Specification gatekeepers embedding recycled content minimums in master specifications for commercial and federal GSA projects. Embodied Carbon in Construction Calculator scores increasingly influence award decisions.
- Builders:Midstream procurement actors balancing cost control with project certification requirements. This segment responds to Buy Clean California Act thresholds with preference for low-carbon alternatives bearing Environmental Product Declarations.
- Municipalities:Public procurement offices enforcing post-consumer content thresholds that effectively mandate processor investment in optical sorting. Northeast municipal offices now reject loads with ceramic content above 1% by mass.
Municipalities anchor demand stability; architects drive the steepest specification upgrade trajectory.
Packaging Type:
Packaging configuration tracks supply chain node concentration—bulk formats dominate where processors control logistics while bagged formats serve fragmented contractor demand.
- Bulk Bags:Flexible intermediate bulk containers for large-volume highway and infrastructure projects. State DOT contractors in Texas and Florida specify this format for road base applications.
- Pallets:Unitized loads for precast plants and ready-mix facilities with mechanized handling systems. This format supports just-in-time delivery protocols.
- Bags:Small-format packaging for landscaping contractors and retail distribution. Higher per-ton packaging costs limit this format to premium decorative grades.
- Containers:Intermodal shipping units for coastal export and long-haul inland distribution. Containerization enables supply from coastal urban collection corridors to inland processors.
Bulk bags retain volume leadership; containers are gaining share fastest as coastal supply seeks inland markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contractor procurement in inland states remains acutely price-sensitive to virgin aggregate benchmarks, while coastal municipalities with landfill diversion mandates absorb recycled glass premiums without demand elasticity.
United States
Federal infrastructure spending and state DOT supplemental specifications drive specification-grade cullet demand. EPA landfill diversion targets overlap with Buy Clean California Act embodied carbon thresholds. Processors in Texas and Florida deploy mobile optical sorting units at demolition sites to supply highway road base projects.
Germany
Precast concrete manufacturers validate ASR-resistant glass blends under controlled curing protocols. REACH compliance obligations and EU Green Deal circular economy targets mandate post-consumer content in public construction. The Rhine-Ruhr industrial corridor concentrates beneficiation capacity serving Dutch and Belgian cross-border demand.
China
Dual carbon goals and GB standards for construction materials accelerate specification development for processed cullet. MEE enforcement of construction waste diversion targets creates feedstock security for coastal processors. Yangtze River Delta municipalities pilot glass aggregate in sponge city drainage infrastructure.
India
LEED v4.1 adoption among commercial developers creates specification pull for granulated glass in architectural concrete. BIS standards development for recycled aggregates lags state-level mandates in Maharashtra and Gujarat. The Delhi-Mumbai Industrial Corridor concentrates precast demand from infrastructure megaprojects.
United Kingdom
Environment Agency landfill diversion targets and PAS 2030 retrofit standards create overlapping compliance for construction waste processors. CSRD disclosure requirements push developers toward Environmental Product Declarations for aggregate procurement. Greater Manchester and West Midlands cluster road base demand from highway maintenance programs.
Recycled Glass Aggregates Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, fragmenting competitive dynamics across the value chain. The vendor base separates into three tiers: nationwide collection infrastructure operators, regional beneficiation specialists with optical sorting capabilities, and mobile processing contractors deploying at demolition sites. Consolidation pressure concentrates among collection-scale players securing post-consumer feedstock, while technology licensing agreements proliferate among equipment manufacturers seeking to standardize optical sorter calibration protocols.
Within the collection-scale tier, Strategic Materials Inc. and Owens-Illinois occupy positions securing post-consumer feedstock through deposit program relationships and municipal contracts. AeroAggregates exemplifies the specialization archetype, anchoring premium positioning in ultra-lightweight foamed glass aggregate for geotechnical fill applications where density constraints exclude conventional material. Momentum Recycling represents vertical integration, controlling quality protocols from curbside collection through finished specification. These three company types illustrate how competitive advantage separates across feedstock security, product engineering, and supply chain control vectors.
| Leading Market Players |
|---|
| Strategic Materials Inc. |
| Vetropack Holding |
| Owens-Illinois |
| Ardagh Group |
| AeroAggregates |
| Coloured Aggregates |
| Momentum Recycling |
| Glass Aggregate Systems |
| Rubble Master |
| Others |
Value Network & Pricing Analysis
Sixty-day inventory cycles for specification-grade cullet concentrate pricing power with coastal processors serving municipal mandates, while inland buyers face freight-adjusted premiums that erode substitution economics against virgin aggregate benchmarks.
Pricing Analysis
After-sales revenue from beneficiation service contracts and long-term offtake agreements drives lifetime value for optical sorting operators. Three-tier pricing structure across premium specification-grade, standard construction-grade, and economy drainage-grade levels stratifies by ASTM certification tier and contaminant thresholds. Cost compression in standard-grade material is intensifying because ceramic removal capex spreads across thinner volumes in regions with weak landfill tipping fees. Contractors represent the most price-sensitive procurement channel, whereas municipalities absorb premiums through recycled content mandates that lock out virgin-only bids.
Supply Chain Analysis
Inventory concentration at coastal MRFs creates lead-time vulnerability for inland precast plants sourcing specification-grade feedstock. Post-consumer cullet supply concentrates in the United States, Germany, and China where deposit programs and municipal collection infrastructure secure feedstock security. Beneficiation equipment, optical sorter consumables, and freight logistics constitute the critical input dependencies. Single-source vulnerability runs through concentrated optical sorter manufacturers in Germany and Japan. Distribution runs through processor-direct bulk contracts for highway projects, with bagged retail channels serving fragmented landscaping demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment creates durable defensive moats for processors with municipal collection contracts, as switching costs for public procurement offices rise with embedded recycled content mandates and qualification protocol investments.
For Market Incumbents: Consolidate feedstock security through exclusive municipal collection contracts in coastal urban corridors where EPA landfill diversion targets concentrate supply. Anchor backward integration into mobile optical sorting units to capture margin previously lost to transportation double-handling. Ceramic inclusion detection technology represents the critical R&D lever for maintaining specification-grade positioning against emerging beneficiation specialists. For New Entrants and Emerging Players: Lead with foamed glass aggregate specialization for geotechnical fill applications where density constraints exclude conventional material and incumbent processors lack product engineering depth. The precast concrete segment offers the most penetrable entry point because controlled-curing environments allow ASR validation before field deployment, bypassing contractor risk aversion that gates ready-mix adoption. Target state DOT supplemental specification development in Texas, California, and Florida where highway road base demand concentrates volume. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across optical sorting capacity expansion as ceramic removal standards tighten and equipment calibration requires specialized technician labor. Five-to-ten year viability favors processors with captive municipal feedstock contracts rather than merchant beneficiation operators exposed to spot cullet pricing. Acquisition targets should display integrated collection-to-specification control or proprietary foamed glass engineering. The signal to watch is state DOT adoption timelines for structural concrete specifications outpacing ASTM C09 committee deliberations, creating temporary jurisdictional arbitrage for early movers.| Strategic Initiative | Industry Significance |
|---|---|
| Mobile Optical Sorting Deployment | Compresses supply chain nodes by processing cullet at demolition sites, capturing margin from transportation elimination in Texas and Florida highway projects. |
| ASR-Resistant Blend Validation | Enables precast concrete penetration through controlled-curing protocol development, bypassing contractor risk aversion that gates ready-mix specification. |
| Municipal Collection Contract Extension | Locks in feedstock security through exclusive curbside agreements where EPA landfill diversion targets concentrate post-consumer glass supply. |
| Foamed Glass Aggregate Capacity Buildout | Addresses settlement-sensitive geotechnical applications where conventional aggregate density creates structural loading problems excluded from incumbent portfolios. |
| Environmental Product Declaration Investment | Secures procurement preference under Buy Clean California Act embodied carbon thresholds for public infrastructure bidding. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EPA landfill diversion reports, state DOT supplemental specifications, ASTM committee proceedings, and trade customs data for processed cullet shipments. Primary interviews engaged beneficiation plant managers, municipal recycling coordinators, precast concrete procurement directors, highway contractor estimators, and optical sorting equipment engineers. Secondary validation drew from SEC filings of public glass processors, GSA procurement databases for federal construction projects, and Environmental Product Declaration registries. Bottom-up volume modeling triangulated against top-down spending flow analysis across construction, concrete production, and road base application segments.
Segmentation dimensions modeled include product type hierarchy from crushed through granulated grades, application maturity from road base through structural concrete, end-user procurement sophistication from contractor spot-buying through municipal mandate compliance, and packaging configuration from bulk bags through containerized export. CAGRs were derived from elasticity-adjusted substitution curves against virgin aggregate pricing and regulatory mandate adoption schedules. Industry-specific forecast inputs incorporated state-level recycled content threshold implementation timelines and ASTM specification upgrade trajectories across the analysis window.
Forecasts assume regulatory continuity in EPA landfill diversion targets, state DOT supplemental specifications, and Buy Clean California Act embodied carbon thresholds; material policy shifts would require re-modeling. Specific risks include ceramic content standard tightening beyond current optical sorting capability, alkali-silica reaction test failure rates in field deployment, and natural aggregate price collapse in regions without carbon pricing mechanisms. Revision becomes warranted when ASTM C09 performance-based standard adoption crosses thresholds that eliminate jurisdictional specification patchwork.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Glass Reactors Market
Glass
Middle-East and Africa Flat Glass Market
Glass
Paper Glass Maker Market
Glass
Dynamic Glazing Market
Glass
Global Silicone Structural Glazing Market
Glass
GCC Flat Glass Market
Glass
Glass Product Market
Glass
Silica Sand for Glass Making Market
Glass
Latin America Flat Glass Market
Glass
Europe Glassware Market
Glass
Foam Glass Granulate Market
Glass
Glass Prepreg Market
Glass
Global Vacuum Insulated Glass Market
Glass
Silica Market
Glass
Antiglare Glass Market
Glass
Birefringent Crystals Market