
 South America Pressure Sensitive Adhesives (PSA) Market | 2026-2036
South America Pressure Sensitive Adhesives (PSA) Market Size, Share, and Industry Trends Forecast 2026-2036
South America Pressure Sensitive Adhesives (PSA) Market Analytics
Asset-light leasing models for coating equipment is reconfiguring competitive entry barriers across the South America PSA landscape. Henkel AG & Co. KGaA leverages its regional logistics network to sustain supply continuity for Brazilian converters. Avery Dennison Corporation dominates specialty film adhesive segments through localized technical service centers. Dow Inc. positions its water-based resin portfolio to capture demand from sustainability-driven packaging buyers.
Pressure Sensitive Adhesives bond substrates upon light pressure without solvent activation or heat curing, typically formulated from acrylic, rubber, or silicone polymers with tackifier resins and applied via slot-die or roll coating at thicknesses between twenty and one hundred micrometers. Water-based adhesives lead volume share due to lower volatile organic compound emissions and compatibility with Brazil's evolving environmental enforcement, while hot melt adhesives represent the fastest-expanding category driven by high-speed packaging line retrofits across Argentine food processors. Medical-grade film adhesives command the deepest margin pools given ANVISA certification requirements and limited qualified supply.
ANVISA governs medical adhesive biocompatibility through Resolution RDC 56, while Brazil's CONAMA standards restrict solvent emissions from adhesive manufacturing facilities. Argentina's Secretariat of Environment and Sustainable Development enforces comparable volatile organic compound limits for industrial coatings. Stakeholders must monitor regulatory harmonization progress between Mercosur member states to anticipate cross-border product registration requirements and manufacturing location decisions.
Market Dynamics
ANVISA's Resolution RDC 56 biocompatibility mandates are forcing Brazilian medical adhesive producers to rebuild formulation portfolios, while Argentine packaging converters accelerate hot melt line retrofits to capture export competitiveness. These dual regulatory and operational pressures are restructuring regional supply chains around certified supply nodes.
Growth Catalysts
- Automotive lightweighting mandates:Brazilian OEMs are bonding composite panels with structural acrylic PSAs to meet fuel efficiency targets, expanding consumption beyond traditional mechanical fasteners.
- ANVISA Resolution RDC 56:Medical device adhesive certification requirements are creating captive demand for qualified suppliers with validated biocompatibility testing protocols.
- Water-based resin compatibility:São Paulo state's environmental enforcement alignment with CONAMA standards is accelerating solvent-to-water formulation conversions in coating operations.
Market Restraints
- Petrochemical feedstock volatility:Acrylic monomer and tackifier resin costs fluctuate with Brazilian naphtha import dependencies, compressing converter margins unpredictably.
- Qualified supply concentration:Medical-grade film adhesive production concentrates among ANVISA-certified facilities in São Paulo and Minas Gerais, creating single-source vulnerability.
- Hot melt temperature performance ceiling:Ethylene-vinyl acetate formulations face substitution pressure from reactive urethanes in high-temperature automotive applications.
Strategic Opportunities
- Colombian packaging export corridor:Underdeveloped domestic PSA capacity creates import substitution potential for Brazilian and Argentine producers with Mercosur trade access.
- Silicone medical skin adhesive convergence:Wearable device manufacturers are blending breathable film technologies with gentle-removal chemistries for chronic patient monitoring applications.
- Asset-light coating equipment leasing:Regional equipment financiers are enabling mid-tier converters to access slot-die coating capability without full capital commitment.
Industry Challenges
- Formulation chemist scarcity:Brazilian universities produce limited polymer science graduates with PSA-specific tackifier compatibility expertise, forcing recruiters to target Argentine and Chilean talent pools.
- ANVISA certification timeline compression:Medical adhesive biocompatibility testing cycles extend 18-24 months, delaying product launches and freezing working capital in regulatory queues.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Pressure Sensitive Adhesives (PSA) Market |
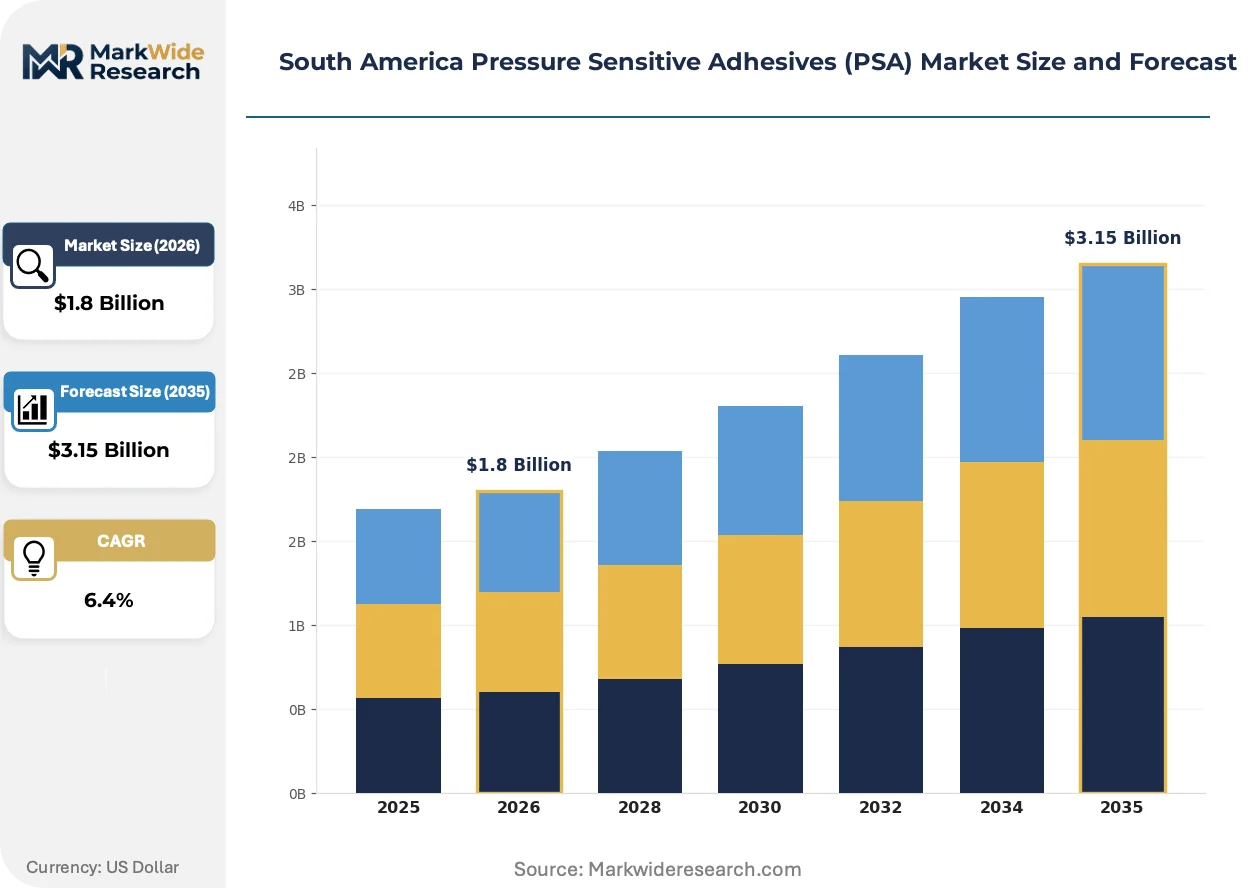
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based Adhesives, Solvent-Based Adhesives, Hot Melt Adhesives, Film Adhesives Application: Packaging, Automotive, Electronics, Medical End User: Manufacturers, Retailers, Distributors, Contractors Technology: Coating Technology, Printing Technology, Film Casting, Laminating |
| Companies Covered | 3M, Jowat SE, Sika AG, Arkema Group, Henkel AG & Co. KGaA, H.B. Fuller Company, Avery Dennison Corporation, Dow Inc., BASF SE, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Pressure Sensitive Adhesives (PSA) Market Evolving Landscape
Formulation chemistry and coating process control are converging to redefine performance thresholds across South American PSA applications. These developments are compressing traditional supplier advantages while opening entry paths for technology-specialized competitors.
UV-curable acrylic hot melt systems are eliminating thermal degradation risks in temperature-sensitive substrate bonding. Argentine food packaging converters operating high-speed label applicators are adopting these chemistries to reduce energy consumption and line downtime. Solvent-based adhesive drying ovens are rendering obsolete in facilities where carbon footprint compliance intersects with throughput demands.
CONAMA's volatile organic compound emission limits for industrial coatings are tightening enforcement timelines across Brazilian manufacturing zones. Adhesive producers must retrofit solvent recovery systems or reformulate entirely to water-based or hot melt platforms. São Paulo state's environmental agency is conducting the most aggressive facility audits, pushing regional supply concentration toward compliant coating operations.
Converter procurement committees are consolidating adhesive supplier rosters from multiple regional vendors to single-source partnerships with technical service capabilities. Brazilian automotive tier-one suppliers are demanding localized application engineering support for bonding process validation. This consolidation pattern is most visible in São Paulo's industrial corridor, where OEM direct engagement is displacing distributor-mediated relationships.
South America Pressure Sensitive Adhesives (PSA) Market Segmentation
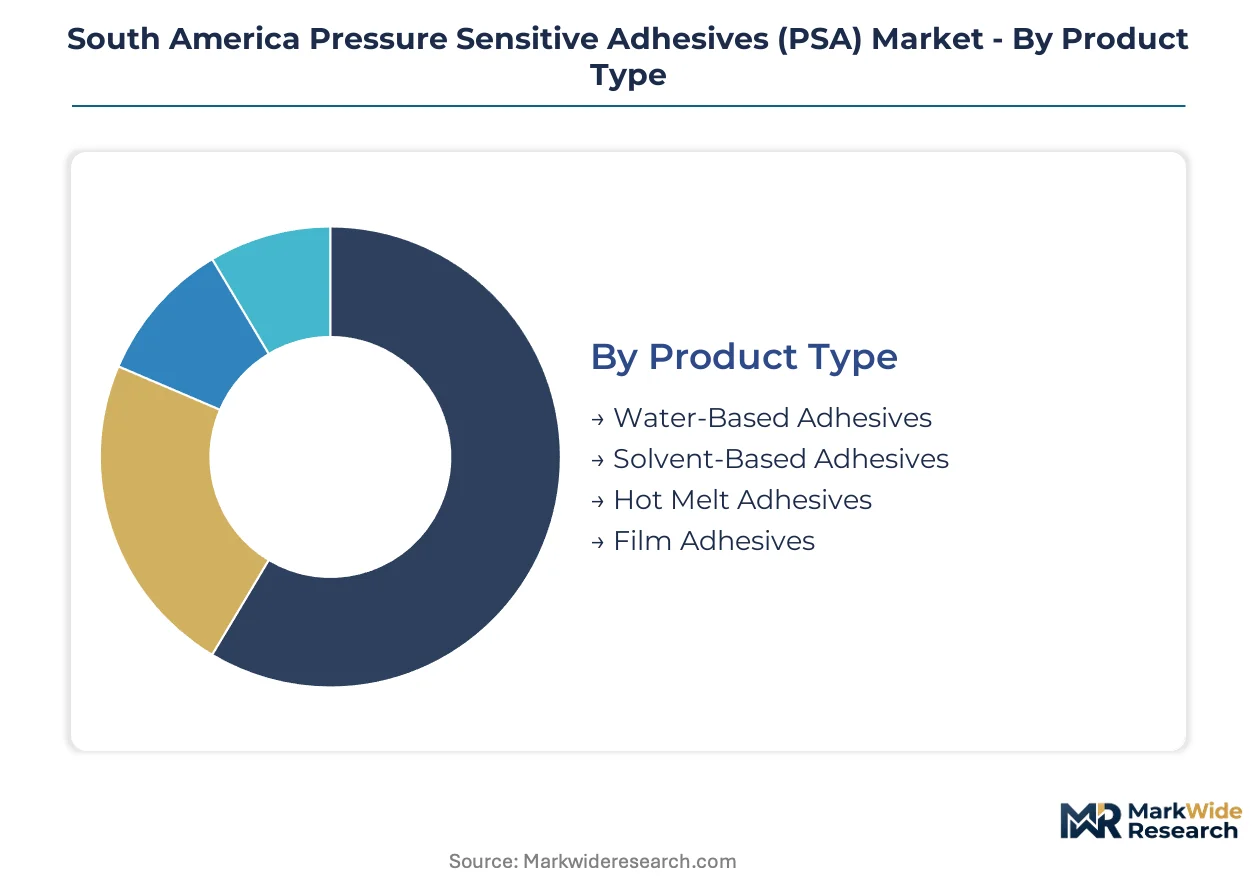
PSA segmentation across South America reflects divergent technical requirements and regulatory exposure. Cycle times vary dramatically—packaging converters refresh formulations quarterly while medical adhesive certifications lock suppliers into multi-year validation cycles.
Product Type:
Water-based systems turn inventory fastest due to regulatory pressure, while film adhesives sit longest in qualification queues for ANVISA medical approvals.
- Water-Based Adhesives:Acrylic emulsion and natural rubber latex formulations dominate São Paulo coating operations. Brazilian packaging converters facing CONAMA enforcement are converting solvent lines to these systems, though drying energy costs erode margin at smaller scale.
- Hot Melt Adhesives:Ethylene-vinyl acetate and metallocene polyolefin chemistries bond corrugated and flexible packaging without solvent emissions. Argentine food processors retrofitting high-speed label applicators are driving steepest regional demand acceleration for these systems.
- Solvent-Based Adhesives:Acrylic and rubber solutions in aromatic hydrocarbon carriers retain niche in automotive interior lamination where aggressive tack development matters.
- Film Adhesives:Medical-grade silicone and acrylic transfer films require 18-24 month ANVISA biocompatibility validation, freezing working capital and concentrating supply among São Paulo-certified facilities.
Water-based adhesives anchor the volume base while hot melt adhesives gain share at the steepest rate.
Application:
Cost tiers separate commodity packaging from certified medical applications, with automotive and electronics occupying intermediate value positions.
- Packaging:Corrugated case sealing and flexible label bonding consume the highest PSA tonnage across Brazil and Argentina. São Paulo state's industrial corridor concentrates converter demand, with sustainability mandates pushing water-based and hot melt substitution for solvent systems.
- Automotive:Structural acrylic PSAs bond composite body panels and interior trim for Brazilian OEM lightweighting mandates. Tier-one suppliers demand localized application engineering support, consolidating supplier relationships around technical service capabilities.
- Electronics:Optically clear adhesives for display lamination and thermal interface materials for battery assembly serve growing Brazilian consumer electronics manufacturing.
- Medical:Wearable device skin adhesives and surgical drape films command deepest margin pools. ANVISA Resolution RDC 56 biocompatibility requirements restrict qualified supply to certified São Paulo and Minas Gerais facilities.
Packaging commands absolute volume leadership while medical applications deliver the highest value per kilogram.
End User:
Procurement scale and technical sophistication stratify this category, from multinational manufacturers to fragmented contractor bases.
- Manufacturers:Brazilian automotive OEMs and Argentine food processors drive specification authority, consolidating adhesive supplier rosters from multiple regional vendors to single-source partnerships with localized engineering support.
- Distributors:Regional logistics networks bridge certified coating operations to mid-tier converters lacking direct supplier relationships, with Henkel's Brazilian distribution infrastructure sustaining supply continuity.
- Retailers:Private-label packaging converters serving mass-market consumer goods represent price-sensitive demand with limited formulation loyalty.
- Contractors:Construction and signage applicators purchase PSA tapes and films through wholesale channels, with demand concentrated in Brazilian urban renovation cycles.
Manufacturers dictate technical specifications while distributors capture margin in supply chain intermediation.
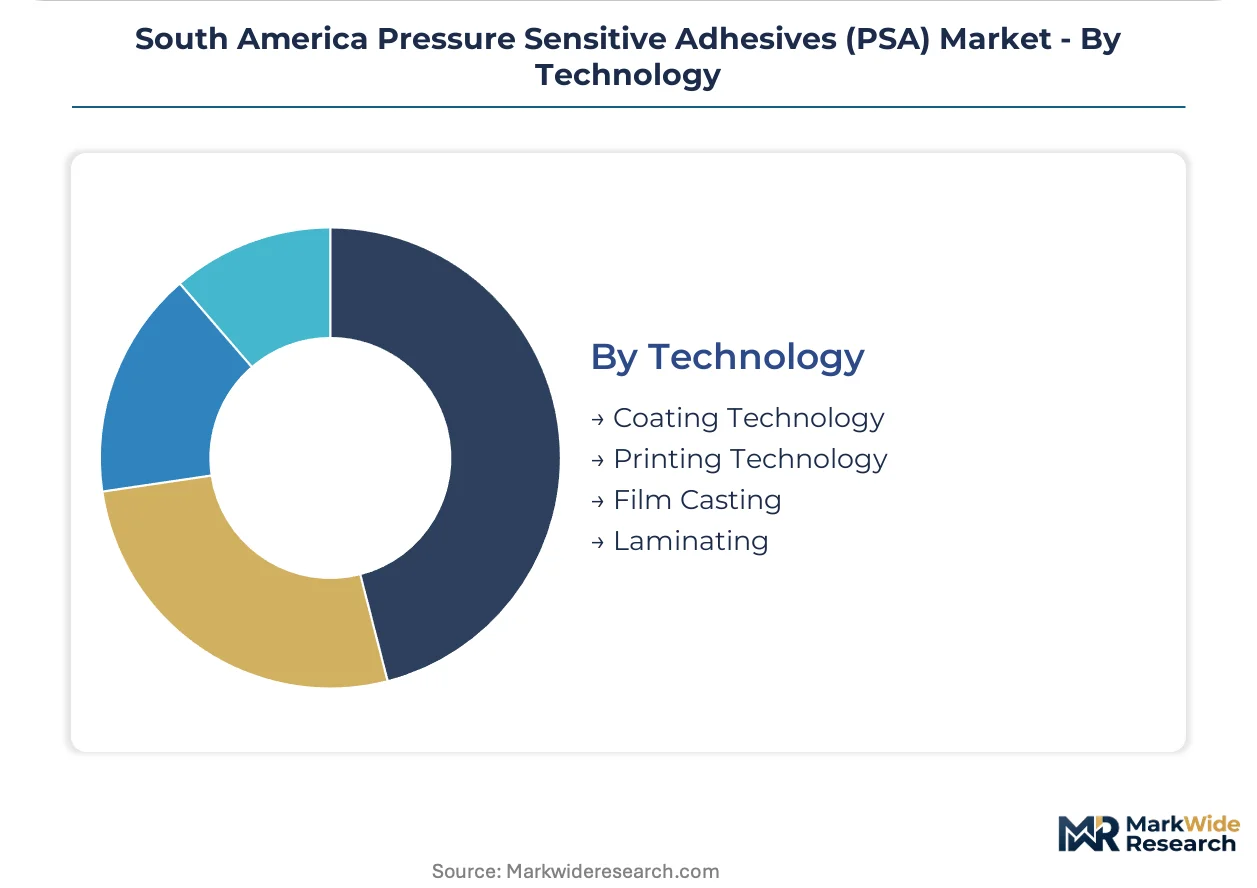
Technology:
Capital intensity and process control requirements separate coating operations from downstream converting technologies.
- Coating Technology:Slot-die and roll coating systems apply adhesive films at 20-100 micrometer thicknesses. Asset-light leasing models are reconfiguring competitive entry barriers, enabling mid-tier converters to access precision coating without full capital commitment.
- Laminating:Multi-layer web bonding for flexible packaging and medical barrier films requires tension control and adhesive compatibility expertise. Brazilian universities produce limited polymer science graduates with PSA-specific tackifier knowledge, forcing recruiters toward Argentine and Chilean talent pools.
- Printing Technology:Flexographic and gravure systems apply pressure-sensitive inks and varnishes, with demand tied to label and decorative film production.
- Film Casting:Extrusion of carrier films and release liners supplies upstream materials to adhesive coaters, with petrochemical feedstock volatility compressing margins unpredictably.
Coating technology concentrates value capture while laminating represents the most talent-constrained process node.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mercosur trade harmonization and national environmental enforcement are redrawing supply chain boundaries across South American PSA markets. Brazil's regulatory tightening anchors regional compliance standards while Argentine industrial policy and Colombian import substitution create divergent entry paths.
Brazil
Automotive OEMs in São Paulo's ABC industrial corridor are bonding composite body panels with structural acrylic PSAs to meet fuel efficiency mandates. ANVISA Resolution RDC 56 governs medical adhesive biocompatibility through 18-24 month validation cycles. São Paulo state's environmental agency enforces CONAMA volatile organic compound limits most aggressively, pushing coating operations toward water-based formulation conversions.
Argentina
Food packaging converters in Buenos Aires province are retrofitting high-speed label applicators with hot melt systems to capture export competitiveness. The Secretariat of Environment and Sustainable Development enforces volatile organic compound limits comparable to Brazilian standards. Rosario's agro-industrial hub concentrates demand for corrugated case sealing adhesives serving grain export logistics.
Colombia
Bogotá-based packaging manufacturers rely on imported PSA capacity from Mercosur trade partners due to underdeveloped domestic coating infrastructure. The national environmental licensing authority requires industrial adhesive facilities to demonstrate emission control compliance. Medellín's manufacturing belt is emerging as a secondary demand node for tape and label converting serving Andean distribution networks.
Chile
Santiago's electronics assembly sector consumes optically clear adhesives for display lamination in consumer device manufacturing. The national environmental regulator monitors solvent emissions from industrial coating operations under progressively tightening standards. Valparaíso's port logistics cluster drives demand for pressure-sensitive labeling systems in export-oriented wine and fruit packaging.
Peru
Lima's construction sector purchases PSA tapes and films through wholesale channels during urban renovation cycles. The national health authority maintains pharmaceutical and medical device regulations that reference international biocompatibility standards. Callao's port industrial zone concentrates converting operations for import-dependent adhesive product distribution.
South America Pressure Sensitive Adhesives (PSA) Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure that concentrates certified supply among ANVISA-validated facilities while fragmenting commodity packaging supply. Three archetypes dominate: multinational chemical conglomerates with regional logistics networks, mid-tier converters accessing precision coating through asset-light leasing, and specialty film adhesive producers serving medical validation queues. Competitive moves center on technical service localization and formulation portfolio rebuilding around water-based and hot melt platforms.
Within the multinational tier, 3M, Henkel AG & Co. KGaA, and Dow Inc. anchor regional supply continuity through established distribution infrastructure. 3M exemplifies the diversified technology conglomerate with broad adhesive and tape portfolios spanning industrial and consumer applications. Henkel AG & Co. KGaA occupies a position representing European chemical majors with integrated adhesive and sealant operations. Dow Inc. sits within the petrochemical-derived materials supplier archetype, positioning resin portfolios for sustainability-driven formulation conversions.
| Leading Market Players |
|---|
| 3M |
| Jowat SE |
| Sika AG |
| Arkema Group |
| Henkel AG & Co. KGaA |
| H.B. Fuller Company |
| Avery Dennison Corporation |
| Dow Inc. |
| BASF SE |
| Others |
Value Network & Pricing Analysis
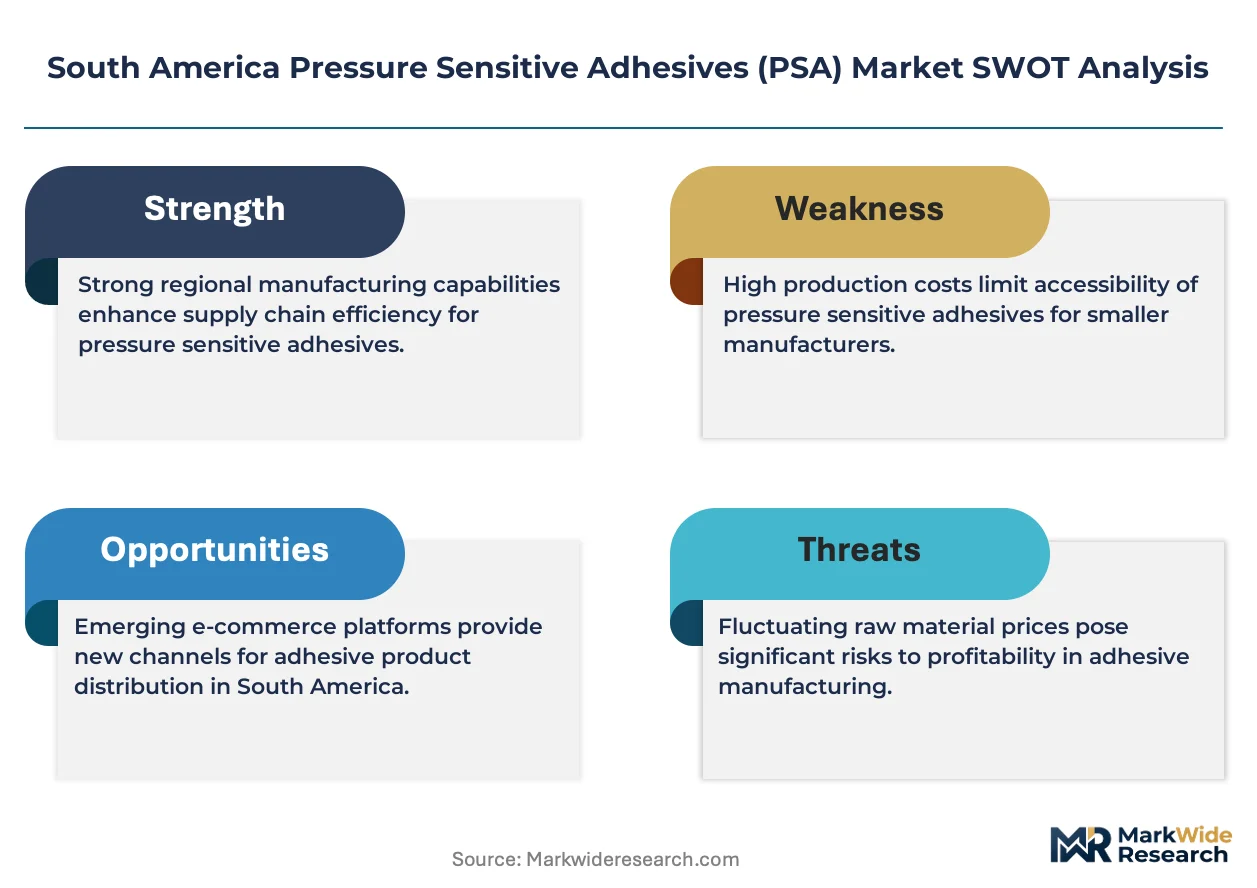
São Paulo's certified coating corridor concentrates ANVISA-validated medical adhesive capacity, translating supply scarcity into sustained pricing leverage for qualified producers serving Brazilian healthcare device manufacturers.
Pricing Analysis
Certification level creates the primary spread across South American PSA tiers. Three-tier pricing structure separates ANVISA-validated medical grades from industrial packaging formulations and commodity hot melts. Acrylic monomer and tackifier resin costs fluctuate with Brazilian naphtha import dependencies, compressing converter margins unpredictably. Retailers and private-label packaging converters exhibit highest price sensitivity, while medical device OEMs absorb premiums for biocompatibility-assured supply.
Supply Chain Analysis
Extended payment terms from multinational resin suppliers are easing working capital pressure for mid-tier Brazilian converters upgrading to water-based coating lines. Raw material supply draws from Argentine petrochemical complexes, US Gulf Coast monomer producers, and Asian silicone feedstock sources. Single-source vulnerability concentrates in ANVISA-certified medical film facilities across São Paulo and Minas Gerais. Distribution runs through Henkel's regional logistics network and specialized medical adhesive distributors serving hospital device procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South American PSA market sits in a cyclical recovery phase as Brazilian automotive OEMs accelerate composite bonding adoption and Argentine food processors retrofit packaging lines for export competitiveness.
For Market Incumbents: Build regulatory moats through ANVISA certification expansion into Minas Gerais secondary facilities. Deepen backward integration into acrylic emulsion production to offset naphtha import cost volatility. Capture Argentine hot melt demand by localizing technical service teams in Rosario's agro-industrial hub.
For New Entrants and Emerging Players: Colombian packaging manufacturers in Bogotá represent the most penetrable entry point given underdeveloped domestic coating infrastructure and Mercosur trade access. Asset-light leasing of slot-die coating equipment enables mid-tier positioning without full capital commitment. Target wearable medical device skin adhesives where silicone formulation expertise gaps limit qualified competition.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because converter procurement committees are consolidating supplier rosters toward single-source partnerships with technical service capabilities. Acquisition targets should exhibit ANVISA-validated facilities or established logistics networks bridging certified coating operations to mid-tier demand. Watch Argentine Secretariat of Environment enforcement timelines as signal for hot melt substitution acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Certification Expansion | Secondary facility validation in Minas Gerais reduces single-source vulnerability for medical-grade supply. |
| Backward Integration into Acrylic Emulsion | In-house production of water-based resin feedstock insulates margin from Brazilian naphtha import volatility. |
| Asset-Light Coating Equipment Leasing | Regional equipment financiers enable mid-tier converter access to precision slot-die capability without full capital commitment. |
| Hot Melt Line Retrofit Partnerships | Argentine food processors gain export competitiveness through high-speed label applicator upgrades with metallocene polyolefin systems. |
| Silicone Medical Skin Adhesive Development | Wearable device manufacturers demand breathable film technologies with gentle-removal chemistries for chronic patient monitoring. |
Research Methodology
Operator-level perspectives from coating plant managers, procurement leads at Brazilian automotive tier-one suppliers, ANVISA regulatory affairs specialists, and Argentine food packaging converters anchored the qualitative base. Secondary validation drew from ANVISA Resolution RDC 56 filings, CONAMA enforcement records, Brazilian customs trade data, and SEC 10-K disclosures from multinational adhesive producers. Bottom-up demand modeling across end-use segments triangulated with top-down petrochemical feedstock flow analysis.
Scenario-bracketing around regulatory enforcement intensity and automotive lightweighting adoption shaped the analytical framework across the projection horizon. Segmentation dimensions included product chemistry, application vertical, certification tier, and regional production hub. CAGRs were derived from elasticity-adjusted demand curves and capacity utilization trajectories. Forecast inputs incorporated ANVISA validation queue lengths and São Paulo state environmental audit schedules.
Macroeconomic conditions sit as an overlay; deviation in Brazilian real exchange rates or Mercosur trade harmonization progress would shift the trajectory. Forecasts reflect assumptions about petrochemical feedstock cost stability and regulatory timeline adherence. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Middle-East and Africa Cyanoacrylate Adhesives Market
Adhesives & Sealants
Global Hygiene Adhesives Market
Adhesives & Sealants
Global Anti-Tack Agents Market
Adhesives & Sealants
Italy Sealants Market
Adhesives & Sealants
Acetate Silicone Sealant Market
Adhesives & Sealants
Light Curing Adhesives Market
Adhesives & Sealants
Urea Formaldehyde Concrete Market
Adhesives & Sealants
North America Construction Adhesives Market
Adhesives & Sealants
Silicone Sealants Market
Adhesives & Sealants
Wood to Metal Glue Market
Adhesives & Sealants
Global Elastic Adhesive Market
Adhesives & Sealants
Leather Glue Market
Adhesives & Sealants
Foam Adhesive Market
Adhesives & Sealants
Gasket and Seal Material Market
Adhesives & Sealants
Middle-East and Africa Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Low VOC Adhesive Market