
 Dental Fluoride Varnish Market | 2026-2036
Dental Fluoride Varnish Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Fluoride Varnish Market Outlook
Germany is narrowing the competitive gap in European fluoride varnish supply as VOCO GmbH leverages its R&D hub in Cuxhaven to develop resin-based carrier systems with extended fluoride release profiles. GC Corporation anchors the Asia-Pacific positioning through its Osaka manufacturing complex, which specializes in glass ionomer-compatible varnish formulations. Colgate-Palmolive Company competes across multiple price tiers through its integrated oral care distribution network, while 3M Company differentiates via proprietary adhesion technology that extends contact time on enamel surfaces.
Dental fluoride varnish is a professionally applied, highly viscous topical treatment containing sodium fluoride or difluorsilane in a resin or synthetic base, typically delivering 22,600 ppm fluoride in a 0.5 mL unit dose; the formulation cures on contact with saliva to form a temporary adhesive film that releases ionic fluoride over 4-6 hours for enamel remineralization and caries arrest. The product serves primary prevention in high-caries-risk populations, particularly children and orthodontic patients with bracket-induced demineralization. Varnish dominates the product type landscape due to its superior retention compared to rinse or foam alternatives, while pediatric dentistry generates the deepest margin pools as public health programs mandate school-based application protocols. Dental clinics represent the most concentrated end-user channel, though mobile dental units are gaining traction in rural access programs.
The FDA regulates professional fluoride varnish as a medical device under 510(k) clearance pathways, while the EPA monitors fluoride discharge limits from manufacturing facilities under Clean Water Act provisions. The ADA Council on Scientific Affairs issues clinical guidelines that directly influence payer reimbursement decisions for professional application procedures. Stakeholders must monitor evolving state-level Medicaid dental benefit expansions and the trajectory of teledentistry-enabled preventive care models that could reshape clinic visit frequency and product procurement cycles.
Market Dynamics
Medicaid dental benefit expansions for children are compressing procurement cycles and forcing manufacturers to reconfigure unit-dose packaging for high-volume clinic dispensing, fundamentally altering how fluoride varnish flows through professional channels.
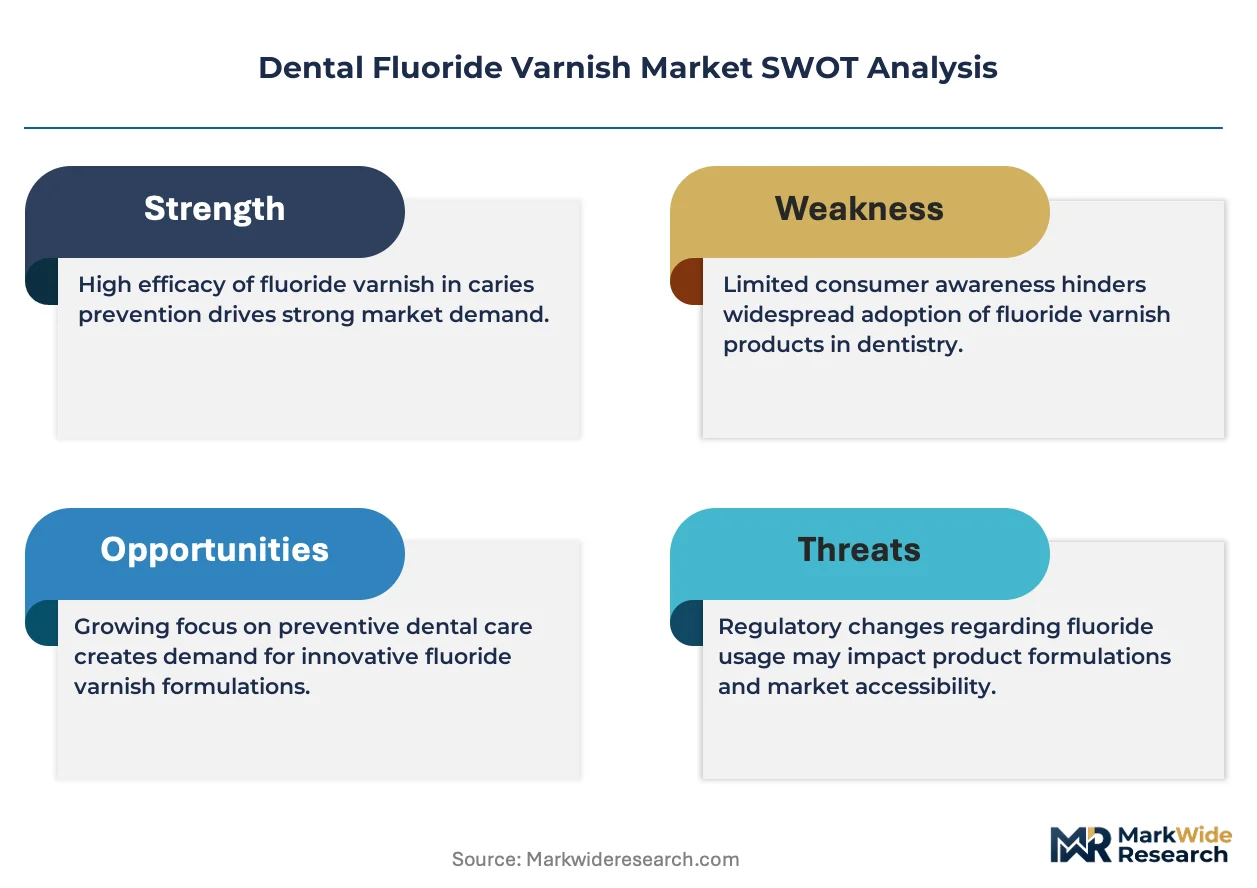
Growth Catalysts
- School-Based Prevention Mandates:State-level public health programs in the United States now require fluoride varnish application in Head Start centers, creating institutional procurement pipelines that bypass traditional dental distributors.
- FDA 510(k) Pathway Efficiency:Streamlined medical device clearance for higher-concentration sodium fluoride formulations accelerates professional-grade product launches without full premarket approval timelines.
- Resin Carrier Innovation:Extended-release polymer matrices developed in German R&D hubs extend enamel contact time from 4 hours to 8+ hours, improving clinical efficacy metrics that drive payer reimbursement.
Market Restraints
- Fluoride Raw Material Concentration:Sodium fluoride supply chains cluster in Chinese industrial zones, exposing manufacturers to export quota volatility and freight cost spikes.
- Substitution by Silver Diamine Fluoride:SDF solutions arrest caries without resin application, threatening varnish volumes in pediatric Medicaid programs seeking single-visit protocols.
- EPA Discharge Compliance:Manufacturing facilities face Clean Water Act limits on fluoride wastewater, requiring capital-intensive treatment systems that elevate fixed costs for domestic production.
Strategic Opportunities
- Teledentistry-Enabled Preventive Models:Remote oral health screening platforms in rural Texas and Alaska identify high-caries-risk children, triggering mobile unit varnish deployment without traditional clinic infrastructure.
- Orthodontic Demineralization Protocols:Bracket-induced white spot lesions create a secondary application channel as aligner and fixed-appliance providers bundle varnish into treatment packages.
- Medicaid Adult Dental Expansion:Arizona and Virginia recently added fluoride varnish to covered benefits for pregnant women and adults with diabetes, opening age-segments previously excluded from public program procurement.
Industry Challenges
- Dental Hygienist Scope-of-Practice Variability:State boards in Tennessee and Florida restrict varnish application to dentist supervision, limiting clinic throughput where hygienist-led prevention could scale volume.
- ADA Guideline Revision Cycles:Council on Scientific Affairs updates to clinical recommendations occur every 5-7 years, creating reimbursement uncertainty during evidence-review windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Fluoride Varnish Market |
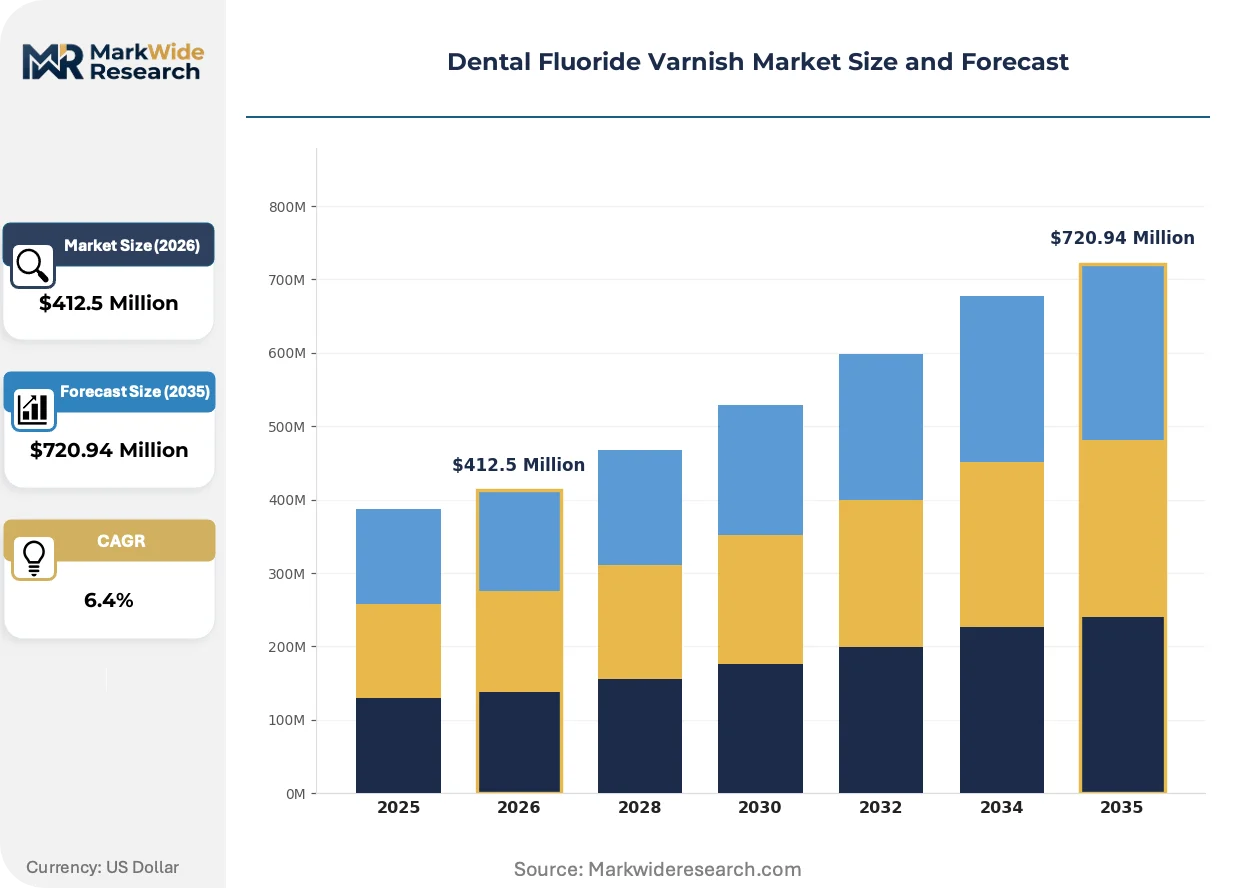
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $720.94 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rinse, Gel, Foam, Varnish Application: Pediatric Dentistry, Geriatric Dentistry, Preventive Care, Orthodontics End User: Dental Clinics, Hospitals, Mobile Dental Units, Research Institutes Distribution Channel: Online, Direct Sales, Distributors, Retail Pharmacies |
| Companies Covered | 3M Company, Colgate-Palmolive Company, Dentsply Sirona, VOCO GmbH, Ultradent Products Inc., Ivoclar Vivadent, GC Corporation, DMG Dental, Young Dental, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Fluoride Varnish Market Strategic Shifts
Formulation chemistry and application protocols are converging around extended-contact systems and digitized compliance tracking, shifting competitive advantage from basic fluoride concentration to delivery precision and outcome documentation.
Resin-based carrier systems incorporating nano-hydroxyapatite are digitizing how clinicians monitor remineralization progress. Pediatric dental groups in California and New York deploy intraoral scanners to baseline enamel density before varnish application, then re-scan at 90-day intervals to quantify treatment response. This digitizing of outcome verification is compressing the traditional 6-month recall cycle and forcing manufacturers to reformulate for measurable mineral gain rather than simple caries arrest.
REACH regulation updates in the European Union now classify certain varnish resin monomers as substances of very high concern, compelling reformulation away from bisphenol-A-derived polymers. German manufacturers VOCO GmbH and DMG have accelerated bio-based resin development in Cuxhaven facilities to maintain CE marking compliance. The regulatory pressure is fragmenting formulation standards between EU and US markets, requiring dual-SKU strategies that elevate inventory complexity.
Clinic procurement teams are consolidating supplier relationships around distributors offering inventory management software with automated reorder triggers. Dental service organizations in Texas and Florida now mandate electronic data interchange connections for varnish suppliers, replacing phone-fax procurement with real-time consumption tracking. This behavioral shift concentrates purchasing power among integrated distributors while squeezing regional rep-driven vendors unable to invest in EDI infrastructure.
Dental Fluoride Varnish Market Segmentation
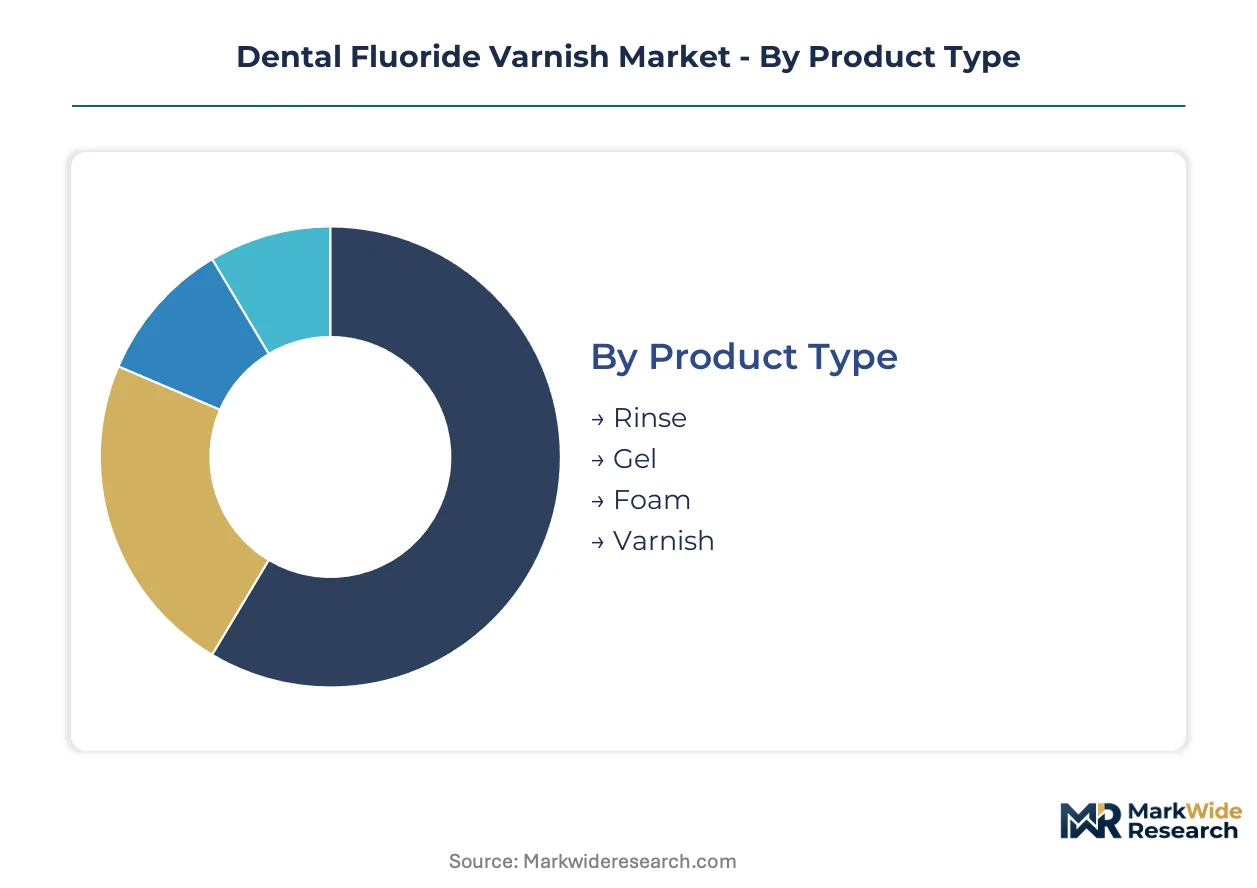
Segmentation in the dental fluoride varnish market determines procurement specifications, reimbursement pathways, and formulation requirements across professional channels. Product viscosity, fluoride concentration, and setting characteristics must align with specific application settings and operator scope-of-practice regulations.
Product Type:
After-sales service intensity varies sharply across product types, with varnish requiring minimal technical support while foam and gel systems demand equipment calibration and training maintenance.
- Varnish:Highly viscous resin-based formulations containing 22,600 ppm sodium fluoride that polymerize on enamel contact with saliva. Demand concentrates in Medicaid-funded school-based programs across Texas and Florida, driven by superior retention characteristics that satisfy public health efficacy mandates.
- Gel:Thixotropic fluoride suspensions applied via tray systems requiring precise timing controls. Pediatric dental clinics in California favor gel for high-volume prophylaxis appointments where chair time compression matters.
- Foam:Air-entrained fluoride delivery systems compatible with disposable tray technologies. Mobile dental units operating in rural Alaska deploy foam for its lightweight logistics and reduced shipping costs.
- Rinse:Aqueous fluoride solutions for patient self-application under professional supervision. Research institutes studying compliance behavior favor rinse for controlled protocol standardization.
Varnish holds the largest share; momentum sits with foam as mobile unit deployment accelerates.
Application:
Application segmentation tracks reimbursement complexity, with pediatric and geriatric dentistry facing distinct prior authorization requirements that shape product selection criteria.
- Pediatric Dentistry:Early childhood caries prevention protocols targeting high-risk populations under age five. State Medicaid expansions in Arizona and Virginia now cover varnish for pregnant women, extending the addressable patient base.
- Orthodontics:Bracket-induced demineralization management during fixed-appliance therapy. Aligner providers in New York bundle varnish into comprehensive treatment packages as white spot lesion prevention.
- Preventive Care:Routine prophylaxis applications for general patient populations. Dental service organizations standardize on unit-dose varnish for inventory control across multi-clinic networks.
- Geriatric Dentistry:Root caries intervention for patients with gingival recession and xerostomia. Long-term care facilities in Florida face staffing constraints that favor single-visit varnish over multi-step alternatives.
Pediatric dentistry commands the deepest margin pools; preventive care applications are expanding most quickly into teledentistry-enabled screening protocols.
End User:
End user concentration determines packaging formats and procurement cycle frequency, with dental clinics demanding high-volume unit doses while research institutes require batch consistency documentation.
- Dental Clinics:Private and group practices performing the majority of professional fluoride applications. Electronic data interchange mandates from Texas dental service organizations now require real-time inventory tracking from suppliers.
- Mobile Dental Units:Transportable clinics serving rural and underserved populations. Alaska's tribal health consortium operates the largest mobile varnish deployment program in the United States.
- Hospitals:Operating room and emergency department settings managing dental trauma. Pediatric hospitals in California integrate varnish into pre-surgical dental clearance protocols.
- Research Institutes:Academic centers conducting clinical trials on remineralization efficacy. NIH-funded studies at New York universities drive demand for standardized batch documentation.
Dental clinics represent the dominant procurement channel; mobile dental units are gaining share fastest through rural access program expansion.
Distribution Channel:
Distribution channel selection reflects buyer scale and technical support requirements, with large clinic groups consolidating around integrated distributors while independent practices retain direct supplier relationships.
- Distributors:Dental supply intermediaries offering inventory management software with automated reorder triggers. Patterson and Henry Schein dominate varnish distribution to dental service organizations.
- Direct Sales:Manufacturer-to-clinic relationships for high-volume accounts. Colgate-Palmolive maintains direct sales teams for its PreviDent varnish line.
- Online:E-commerce platforms serving small independent practices. Amazon Business and Dental City capture growing share among solo practitioners.
- Retail Pharmacies:Limited over-the-counter availability for consumer-grade fluoride products. CVS and Walgreens stock lower-concentration alternatives not requiring professional application.
Distributors control the largest volume flow; direct sales channels are climbing the fastest as manufacturers invest in customer relationship management infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA clearance pathways for higher-concentration fluoride formulations anchor the United States as the dominant geography, with Medicaid dental benefit expansions compressing procurement cycles and reshaping how varnish flows through professional channels.
United States
Medicaid dental benefit expansions for children in Arizona and Virginia now cover pregnant women and adults with diabetes, extending addressable patient bases beyond traditional pediatric segments. State-level public health programs mandate fluoride varnish application in Head Start centers, creating institutional procurement pipelines that bypass traditional dental distributors. Texas and Florida dental service organizations now mandate electronic data interchange connections for suppliers, replacing phone-fax procurement with real-time consumption tracking.
Germany
VOCO GmbH leverages its Cuxhaven R&D hub to develop resin-based carrier systems with extended fluoride release profiles, narrowing the competitive gap in European supply. REACH regulation updates classify certain varnish resin monomers as substances of very high concern, compelling reformulation away from bisphenol-A-derived polymers. DMG has accelerated bio-based resin development in Cuxhaven facilities to maintain CE marking compliance, fragmenting formulation standards between EU and US markets.
Japan
GC Corporation anchors Asia-Pacific positioning through its Osaka manufacturing complex, which specializes in glass ionomer-compatible varnish formulations. PMDA regulatory frameworks align with international standards for professional fluoride devices, facilitating product registration for export-oriented manufacturers. The Osaka cluster concentrates formulation expertise for extended-release polymer matrices that extend enamel contact time.
China
Sodium fluoride supply chains cluster in Chinese industrial zones, exposing manufacturers to export quota volatility and freight cost spikes. NMPA medical device classification for professional fluoride products requires domestic clinical trial data, creating regulatory barriers for foreign entrants. Manufacturing facilities face MEE monitoring of fluoride wastewater discharge limits, requiring capital-intensive treatment systems that elevate fixed costs.
Canada
Health Canada regulates professional fluoride varnish as a medical device, with PMRA oversight of fluoride discharge from manufacturing facilities. Provincial health programs in Ontario and Quebec have expanded school-based prevention mandates, creating institutional procurement channels similar to US Medicaid structures. The Greater Toronto Area concentrates distribution infrastructure serving North American markets.
Dental Fluoride Varnish Market Competitive Environment
Integrated oral care conglomerates and specialized dental materials manufacturers split the market into distinct competitive spheres. The vendor base concentrates around resin-formulation specialists with proprietary adhesion technologies and diversified consumer health companies with established professional distribution networks. Two strategic archetypes dominate: technology-differentiated specialists competing on extended-release performance metrics, and scale-driven integrators leveraging procurement consolidation trends. Competitive moves center on dual-SKU strategies for regulatory compliance fragmentation and EDI infrastructure investments to capture dental service organization contracts.
Within the technology-differentiated tier, 3M Company and VOCO GmbH exemplify archetypes anchored in proprietary formulation science and regional R&D hub concentration. Colgate-Palmolive Company occupies a position across multiple price tiers through integrated oral care distribution networks. These three entities represent the competitive spectrum from specialized adhesion technology to diversified consumer health platforms, each responding to Medicaid procurement compression and REACH-driven reformulation pressures through distinct capability configurations.
| Leading Market Players |
|---|
| 3M Company |
| Colgate-Palmolive Company |
| Dentsply Sirona |
| VOCO GmbH |
| Ultradent Products Inc. |
| Ivoclar Vivadent |
| GC Corporation |
| DMG Dental |
| Young Dental |
| Others |
Value Chain & Pricing Dynamics
Chinese export quota volatility on sodium fluoride concentrates determines both pricing tier spreads and supply chain shape, forcing manufacturers to absorb freight cost spikes or reformulate around alternative fluoride sources while Medicaid procurement compression squeezes margin buffers across all product grades.
Pricing Analysis
Geographic price spreads between German resin-based formulations and Chinese commodity-grade alternatives reflect REACH compliance costs and extended-release performance premiums. Three-tier pricing structure across premium, standard, and economy levels segments on certification grade and volume scale, with dental service organizations extracting discounts through EDI-mandated procurement while independent clinics face sticker prices. Pricing pressure stems from silver diamine fluoride substitution in single-visit Medicaid protocols. Pediatric dental programs demonstrate highest price sensitivity; orthodontic bundled packages show lowest.
Supply Chain Analysis
Export-control regimes on fluorochemical precursors limit raw material flows from Chinese industrial zones to European and North American formulation facilities. Manufacturing concentrates in China, Germany, and Japan; sodium fluoride feedstock draws from Henan and Shandong provinces; resin carriers rest on petrochemical complexes in Rotterdam and Houston. Single-source vulnerability concentrates in Chinese fluoride refining. Distribution runs through integrated dental supply distributors with automated inventory management systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a Medicaid expansion cyclical recovery, with state-level dental benefit mandates for children and pregnant women driving procurement volume normalization after pandemic-era service disruptions.
For Market Incumbents: Harden formulation differentiation through bio-based resin development in Cuxhaven-style R&D hubs to preempt REACH-driven reformulation mandates. Anchor backward integration into sodium fluoride supply through long-term offtake agreements with Chinese refiners to offset export quota volatility. Consolidate distributor relationships around EDI-capable partners as dental service organizations consolidate procurement.
For New Entrants and Emerging Players: Pursue mobile dental unit channels in rural Alaska and Texas tribal health consortiums where incumbent distributor relationships remain underdeveloped. Target teledentistry-enabled screening protocols as the most penetrable entry point, leveraging remote caries risk identification to trigger varnish deployment without traditional clinic infrastructure investment. Lead with lightweight foam formulations optimized for air-freight logistics.
For Investors and Strategic Acquirers: The market sits at a mid-cycle expansion phase that favors specialized resin-formulation specialists with proprietary extended-release technology over diversified consumer health platforms. Long-term viability hinges on regulatory compliance agility across FDA and REACH frameworks. Watch Medicaid adult dental expansion announcements in additional states as the inflection signal for addressable market step-change.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Resin Reformulation | CE marking retention in EU markets hinges on eliminating bisphenol-A-derived polymer carriers. |
| EDI Infrastructure Investment | Real-time inventory tracking capabilities secure dental service organization contracts in Texas and Florida. |
| Extended-Release Polymer Development | 8+ hour enamel contact time metrics drive payer reimbursement and clinical preference. |
| Mobile Unit Channel Partnership | Alaska tribal health consortium deployment programs bypass traditional distributor markups. |
| Teledentistry Platform Integration | Remote screening protocols in rural Texas trigger varnish deployment without clinic infrastructure. |
Study Parameters
Cross-validation between primary interviews with dental materials procurement managers, pediatric clinic operations directors, Medicaid program administrators, and resin formulation chemists and secondary validation through FDA 510(k) filings, EPA discharge compliance records, and state Medicaid dental benefit expansion announcements anchors the qualitative findings. Bottom-up clinic-level procurement volume estimates triangulate against top-down manufacturer shipment data reported in trade publications.
Calibration against historical Medicaid enrollment trends and school-based prevention program adoption curves shapes the analytical framework across product type, application segment, end-user channel, and regional regulatory cluster dimensions. CAGRs derive from segmented growth rate reconciliation with macroeconomic healthcare expenditure projections. Forecast inputs incorporate teledentistry platform deployment trajectories and REACH substance classification update timelines.
Sensitivities concentrate around state-level Medicaid dental benefit expansion reversals, Chinese sodium fluoride export quota tightening, and silver diamine fluoride clinical guideline revisions. Forecasts reflect assumptions on regulatory stability and raw material trade flow continuity. Material shifts in FDA fluoride concentration clearance pathways or EPA discharge limit enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Materials
Australia and New Zealand Dental Biomaterials Market
Dental Materials
Dental Alginate Market
Dental Materials
Fluoride-Free Toothpaste Market
Dental Materials
Dental Fiber Posts Market
Dental Materials
Global Dental Zirconia Block Market
Dental Materials
Dental Plaster Market
Dental Materials
Acrylic Dental Material Market
Dental Materials
Dental Impression Material Market
Dental Materials
Dental Wax Market
Dental Materials
Global Dental Adhesive Market
Dental Materials
Crack Tooth Syndrome Market
Dental Materials
Dental Bleaching Materials Market
Dental Materials
Global Endodontic Consumables Market
Dental Materials
Remineralizing Gum Market
Dental Materials
Asia-Pacific Toothpaste Market
Dental Materials
Dental Biomaterials Market