
 Dental Matrix Systems Market | 2026-2036
Dental Matrix Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Matrix Systems Market Intelligence
CE marking under the EU Medical Device Regulation is unwinding competitive access for uncertified matrix system suppliers. Dentsply Sirona leverages its vertically integrated manufacturing footprint across stainless steel and composite matrix lines. Kerr Dental anchors its position through intensive R&D in self-contained matrix mechanisms. Polydentia competes on specialized preformed matrix geometries tailored to aesthetic restoration workflows.
Dental matrix systems comprise mechanical devices and bands that establish temporary proximal walls during Class II and other cavity restorations, with stainless steel variants typically measuring 0.05 mm thickness and plastic alternatives offering radiolucency for post-operative verification. Their primary commercial purpose centers on enabling anatomically correct contact point formation while containing restorative materials during condensation and curing. The preformed matrix segment leads volume due to chairside time savings in high-throughput clinics, while composite material formulations capture expanding margin pools as dentists shift toward tooth-colored restorations. Self-contained systems represent the fastest-growing structural category by installation base, driven by ergonomic preferences among orthodontists and dental clinics seeking reduced instrument inventory.
The FDA governs 510(k) clearance pathways for matrix systems sold in the United States, while the EU MDR and ISO 13485 quality management standards shape biocompatibility and traceability obligations across European supply chains. These frameworks elevate compliance costs for smaller manufacturers but simultaneously protect incumbent positions for firms with established regulatory infrastructure. Stakeholders must monitor evolving FDA guidance on additive-manufactured dental devices and EU MDR delegated acts affecting polymer-based matrix materials to anticipate certification bottlenecks and supply reallocations.
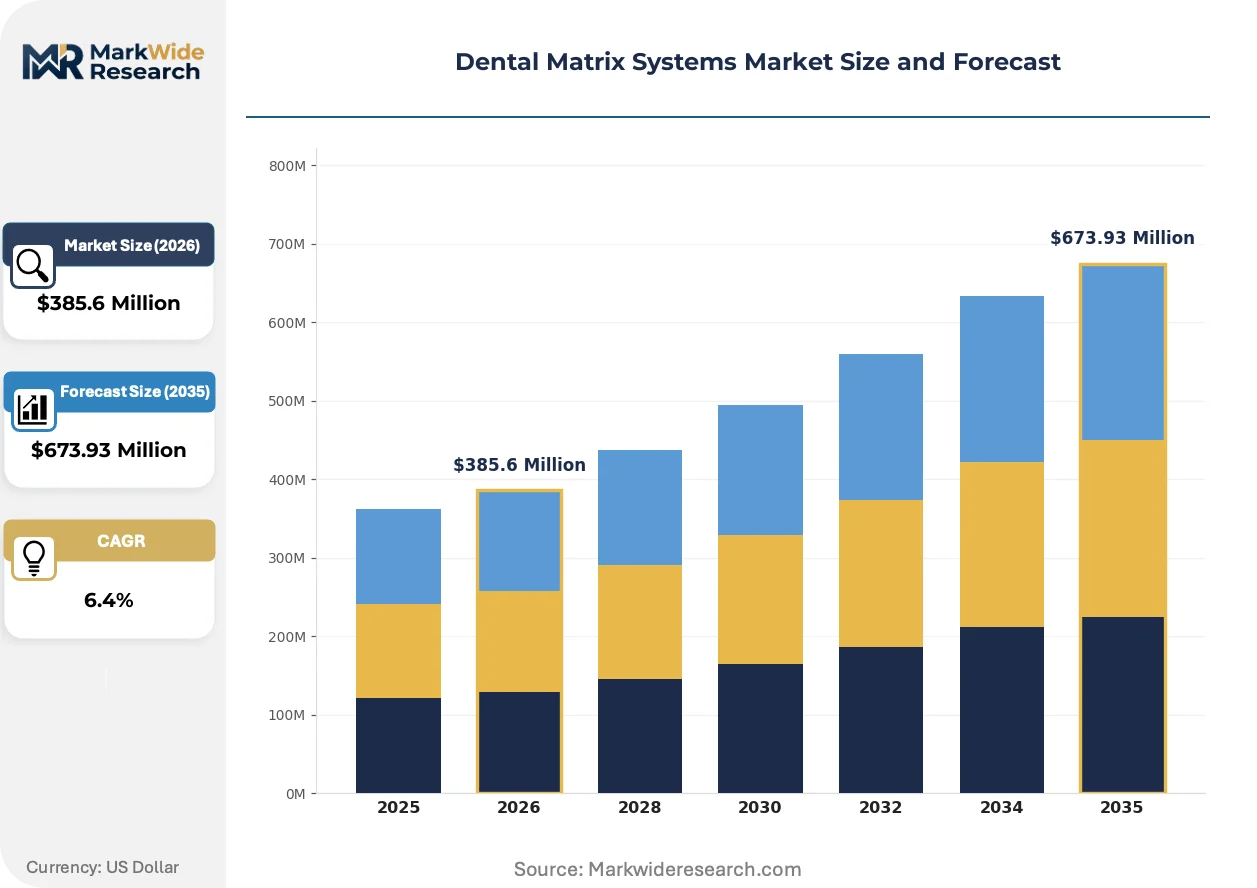
Market Dynamics
Preformed matrix geometries are compressing chairside preparation time in high-throughput dental clinics, forcing manufacturers to reconfigure product portfolios around single-use convenience and anatomical precision.
Growth Catalysts
- EU MDR biocompatibility mandates:Tighter material traceability requirements are filtering out uncertified suppliers and consolidating procurement toward validated manufacturers with established quality management systems.
- Tooth-colored restoration workflows:Patient preference shifts toward aesthetic outcomes are expanding demand for radiolucent plastic matrix alternatives that enable post-operative radiographic verification.
- Multi-location dental service organizations:Centralized purchasing power across clinic networks in the United States is standardizing matrix system specifications and accelerating volume commitments to preferred suppliers.
Market Restraints
- Stainless steel input volatility:Fluctuations in specialty alloy pricing compress margin stability for manufacturers dependent on thin-gauge strip production.
- Regulatory friction from EU MDR transition:Extended certification timelines and notified body capacity constraints are delaying market access for redesigned matrix products.
- Substitute containment methods:Advanced sectional matrix systems with integrated rings are displacing traditional circumferential bands in select restoration protocols.
Strategic Opportunities
- Underpenetrated German dental laboratories:Outsourced restoration workflows in Europe's largest dental market present untapped volume for specialized preformed matrix geometries.
- Digital dentistry convergence:Integration of intraoral scanning with chairside milling systems is creating demand for matrix systems compatible with CAD/CAM restoration protocols.
- US FDA 510(k) pathway optimization:Streamlined clearance mechanisms for substantially equivalent devices offer faster commercialization timelines for incremental product innovations.
Industry Challenges
- Polymer chemistry expertise gaps:Shortages of formulation specialists familiar with biocompatible resin systems for radiolucent matrix production constrain R&D throughput.
- ISO 13485 certification timeline compression:Accelerated audit cycles and documentation requirements strain quality management resources at mid-scale manufacturers.
- Legacy instrument compatibility:New matrix system designs must maintain interoperability with existing retainer mechanisms and tensioning devices already installed in clinic inventories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Matrix Systems Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $673.93 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tofflemire System, Self-Contained Matrix, Preformed Matrix, Copper Band Material: Stainless Steel, Plastic, Composites, Aluminum End User: Dentists, Orthodontists, Dental Clinics, Hospitals Application: Fillings, Repairs, Aesthetic Restorations, Preventive Care |
| Companies Covered | Dentsply Sirona, Polydentia, Kerr Dental, Garrison Dental Solutions, Scott's Dental Supply, Dr. Walser Dental GmbH, Clinician's Choice Dental Products Inc., 3M, Premier Dental, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Matrix Systems Market Strategic Shifts & Innovations
Material science advances and ergonomic design priorities are restructuring how dental professionals establish proximal walls during restorative procedures.
Self-contained matrix mechanisms are decomposing the traditional multi-instrument setup by integrating tensioning, adaptation, and stabilization functions into single-handled devices. Orthodontists and high-volume general practitioners in the United States are adopting these systems at accelerating rates. This convergence is compressing supplier margins on standalone matrix retainers and forcing portfolio consolidation around integrated solutions.
EU MDR delegated acts on polymer-based medical devices are tightening post-market surveillance obligations for matrix manufacturers using composite materials. Industrial consequence includes mandatory clinical follow-up data collection and enhanced adverse event reporting infrastructure. German and French dental suppliers are responding by restructuring regulatory affairs departments and preemptively withdrawing legacy product lines from European distribution.
Centralized procurement by dental service organizations is consolidating vendor relationships around multi-year supply agreements with standardized specification matrices. Traditional distributor networks serving independent practitioners are losing volume to direct manufacturer contracts. This pattern is most visible in the southwestern and southeastern United States, where DSO penetration rates exceed national averages.
Dental Matrix Systems Market Segmentation
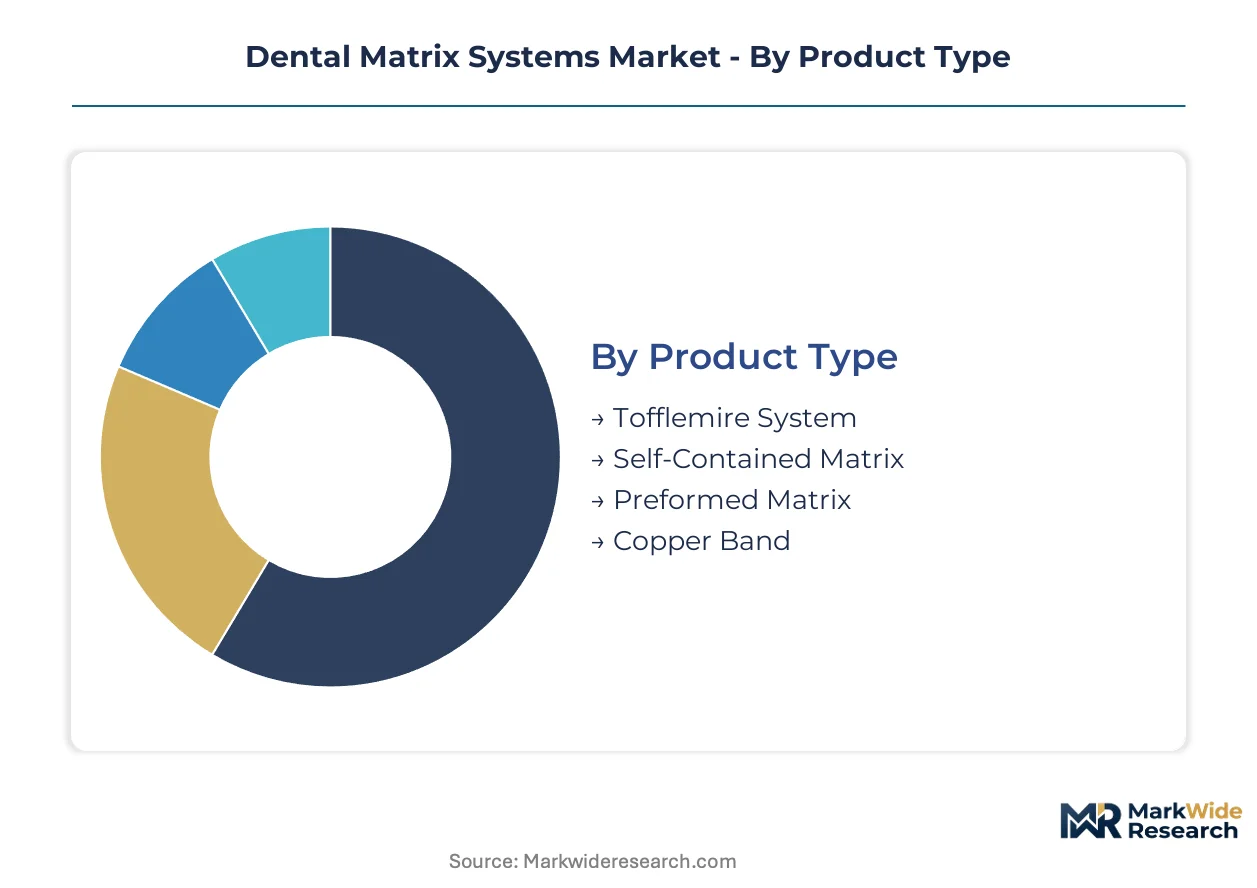
Dental matrix systems fragment across four structural dimensions that determine procurement patterns and margin capture. Product architecture dictates clinical workflow integration, while material selection governs regulatory compliance burden and radiographic verification capability.
Product Type:
Channel mix varies sharply by system complexity, with self-contained mechanisms flowing direct-to-clinic through DSO procurement offices while traditional Tofflemire retainers persist through dental distributor networks serving independent practitioners.
- Preformed Matrix:Anatomically contoured bands manufactured in standardized mesiodistal and buccolingual dimensions eliminate chairside adaptation time. Dental clinics in Germany and the United States are standardizing on these geometries for high-throughput Class II restoration workflows, compressing procedure time by eliminating manual band shaping.
- Self-Contained Matrix:Integrated devices combining matrix band, retainer, and tensioning mechanism into single-handled instruments. Orthodontists and multi-location dental service organizations in the southwestern United States are displacing multi-instrument setups with these ergonomic alternatives, reducing sterilization burden and instrument inventory.
- Tofflemire System:Traditional circumferential retainers requiring separate band selection and mechanical adaptation remain prevalent in cost-sensitive procurement channels.
- Copper Band:Specialty matrices for large cavity preparations and provisional restorations occupy niche application segments with limited volume concentration.
Preformed matrices dominate installed base. Self-contained systems are where expansion concentrates.
Material:
Cost tier stratification separates premium radiolucent formulations from commodity stainless steel, with composite materials commanding margin premiums in aesthetic-focused practices.
- Stainless Steel:Thin-gauge strips measuring 0.05 mm thickness provide rigidity and spring memory for proximal wall adaptation. German dental laboratories and high-volume clinics in the United States specify these alloys for durability in metal matrices, though input price volatility compresses manufacturer margins.
- Plastic:Radiolucent polymers enable post-operative radiographic verification without artifact interference. Patient preference for tooth-colored restorations in France and the United States is accelerating specification of these materials in aesthetic restoration workflows.
- Composites:Engineered resin formulations balance translucency with mechanical strength for specialized matrix applications.
- Aluminum:Lightweight alternatives for specific clinical protocols occupy limited procurement volume in select European markets.
Stainless steel anchors volume throughput. Plastic alternatives are climbing the fastest on aesthetic demand.
End User:
Customer type determines specification complexity, with hospitals and DSO-affiliated dental clinics demanding standardized SKUs while independent dentists retain preference for instrument flexibility.
- Dental Clinics:High-throughput facilities prioritize single-use preformed matrices and self-contained systems to compress chairside time and sterilization logistics. Centralized procurement across clinic networks in the United States is consolidating vendor relationships around multi-year supply agreements.
- Dentists:Independent general practitioners maintain diversified instrument inventories, sustaining demand for traditional Tofflemire retainers and sectional matrix systems.
- Orthodontists:Specialized practitioners in the United States specify ergonomic self-contained mechanisms for orthodontic band placement and temporary restorative procedures.
- Hospitals:Institutional procurement channels emphasize disposable preformed matrices for infection control compliance in surgical dentistry settings.
Dental clinics capture the steepest volume trajectory. Dentists retain the broadest SKU fragmentation.
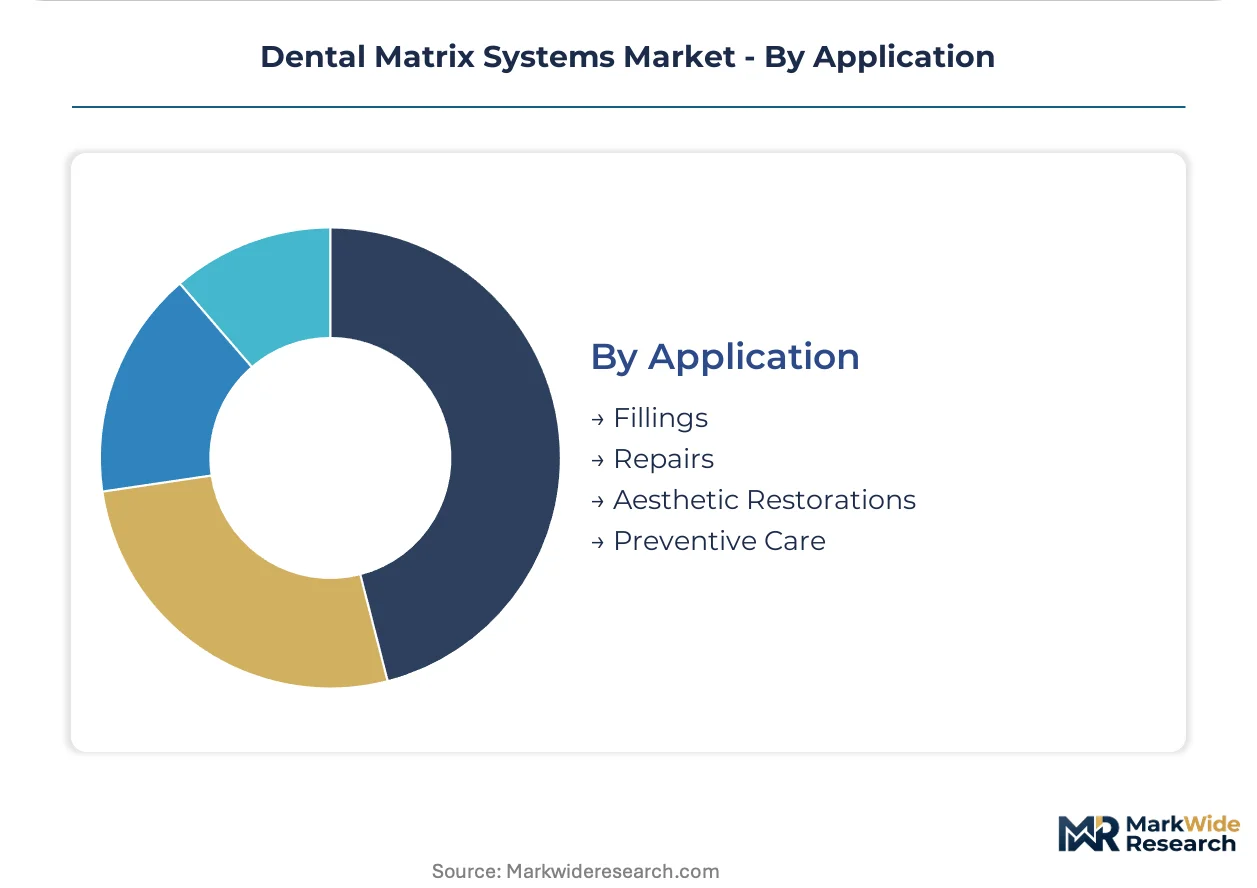
Application:
Procedure type governs matrix specification, with aesthetic restorations demanding radiolucent materials and preventive care protocols favoring cost-optimized disposable bands.
- Fillings:Class II cavity restorations represent core volume for circumferential and sectional matrix systems. Dental clinics in Germany are expanding adoption of preformed matrices for amalgam and composite filling procedures to standardize contact point formation.
- Aesthetic Restorations:Tooth-colored composite and ceramic procedures require radiolucent plastic matrices for post-operative verification. Demand concentrates in private practices across France and the United States where patient preference drives material specification.
- Repairs:Fracture restoration and provisional matrix applications sustain demand for adaptable Tofflemire and copper band systems.
- Preventive Care:Sealant placement and minimal intervention procedures utilize simplified matrix configurations with limited adaptation requirements.
Fillings anchor procedure volume. Aesthetic restorations are gaining share fastest on material substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways and EU MDR biocompatibility mandates are restructuring competitive access across major dental device markets, with procurement consolidation favoring manufacturers with established regulatory infrastructure.
United States
Multi-location dental service organizations in Texas and Florida are standardizing matrix system specifications through centralized procurement offices. The FDA maintains 510(k) clearance requirements for matrix bands and retainers sold interstate. Greater Boston and the Pacific Northwest host specialized dental device distributors serving high-throughput clinic networks with direct manufacturer contracts.
Germany
Dental laboratories in Bavaria and North Rhine-Westphalia are expanding adoption of preformed matrix geometries for outsourced restoration workflows. The EU MDR tightened biocompatibility traceability requirements for polymer-based matrix materials in 2021. Stuttgart and Frankfurt concentrate precision metalworking suppliers serving thin-gauge stainless steel matrix production.
France
Private practices in Île-de-France prioritize radiolucent plastic matrices for aesthetic restoration workflows driven by patient preference. ANSM enforces post-market surveillance obligations under EU MDR delegated acts for composite matrix devices. Lyon and Marseille host regional dental supply distributors consolidating procurement for independent practitioners.
Japan
Metropolitan Tokyo dental clinics specify ergonomic self-contained matrix mechanisms to reduce instrument inventory and sterilization burden. PMDA regulates matrix systems as Class II medical devices requiring pre-market certification. Osaka and Nagoya concentrate precision instrument manufacturers supplying orthodontic and general practice channels.
India
Dental colleges in Maharashtra and Karnataka are expanding preformed matrix adoption for student training in high-volume restorative procedures. CDSCO oversees import licensing and quality standards for foreign-manufactured dental devices. Ahmedabad and Delhi-NCR host domestic distributors serving cost-sensitive procurement channels with stainless steel matrix alternatives.
Dental Matrix Systems Market Key Industry Players
Player mix skews toward diversified dental conglomerates with matrix systems as portfolio components alongside broader restorative and consumable lines. Market structure concentrates around three to five integrated manufacturers with captive distribution networks and regulatory affairs infrastructure. Strategic archetypes include vertically integrated device conglomerates, specialized matrix geometry innovators, and regional precision metalworkers. Competitive moves center on portfolio consolidation around self-contained ergonomic systems and direct procurement relationships with dental service organizations bypassing traditional distributor networks.
Within the diversified conglomerate tier, Dentsply Sirona and 3M occupy positions spanning stainless steel and composite matrix lines with established FDA and EU MDR certification infrastructure. Kerr Dental exemplifies the specialized innovator archetype, anchoring market presence through intensive development in self-contained matrix mechanisms. Polydentia represents the precision geometry specialist segment, competing on anatomically contoured preformed bands tailored to aesthetic restoration workflows in European and North American markets.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Polydentia |
| Kerr Dental |
| Garrison Dental Solutions |
| Scott's Dental Supply |
| Dr. Walser Dental GmbH |
| Clinician's Choice Dental Products Inc. |
| 3M |
| Premier Dental |
| Others |
Cost & Logistics Intelligence
Radiolucent polymer substitution for stainless steel in aesthetic restoration workflows simultaneously shifts supply geography toward German and US resin compounders and compresses pricing premiums on commodity metal matrices. This material transition rewards manufacturers with captive polymer chemistry capabilities while squeezing margins for thin-gauge steel processors dependent on volatile specialty alloy inputs.
Pricing Analysis
Certification level creates the primary spread between EU MDR-compliant CE-marked systems and uncertified alternatives, with FDA 510(k) clearance commanding additional premiums in US procurement channels. Three-tier pricing structure across premium radiolucent composites, standard stainless steel preformed bands, and economy Tofflemire retainers reflects differentiation by biocompatibility grade and ergonomic integration. Pricing pressure intensifies in the stainless steel tier as Indian and Chinese metalworkers expand export capacity, while dental service organizations extract volume discounts through multi-year direct contracts. Independent practitioners in France and Germany exhibit highest price sensitivity, whereas US orthodontists purchasing self-contained systems show lowest elasticity due to ergonomic preference and sterilization cost avoidance.
Supply Chain Analysis
Just-in-time inventory preferences dominate among high-throughput dental clinics seeking to minimize sterilization logistics, while strategic stockpiling persists among German dental laboratories buffering against EU MDR certification delays. Geographic supply concentrates in Germany for precision metalworking, the United States for polymer compounding and self-contained system assembly, and China for commodity stainless steel strip production. Raw material dependencies center on specialty stainless steel alloys from European mills, biocompatible resins from German and US chemical suppliers, and precision injection molding components from Japanese instrument manufacturers. Single-source vulnerability in notified body capacity for EU MDR conformity assessments creates regulatory chokepoint risk. Distribution runs through direct manufacturer contracts with dental service organizations in the United States and specialized dental distributors serving independent practitioners across Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across procurement channels creates niche opportunities as centralized dental service organization purchasing displaces traditional distributor relationships in the United States while independent practitioners in Europe retain specification autonomy.
For Market Incumbents: Fortify regulatory infrastructure investments to exploit EU MDR certification bottlenecks filtering out uncertified competitors, while accelerating backward integration into polymer compounding to capture margin pools shifting from metal to radiolucent matrices. Dentsply Sirona and Kerr Dental should preemptively withdraw legacy steel product lines from European distribution to avoid post-market surveillance liabilities under delegated acts on polymer-based devices. For New Entrants and Emerging Players: Anchor in German dental laboratory outsourcing workflows where preformed matrix adoption lags clinic penetration, offering specialized geometries for CAD/CAM-compatible restoration protocols. Target direct procurement relationships with mid-size dental service organizations in the southwestern United States seeking alternatives to incumbent supply agreements, leveraging ergonomic self-contained system designs as the primary go-to-market wedge. For Investors and Strategic Acquirers: Capital is best deployed toward precision geometry specialists with established EU MDR technical documentation and ISO 13485 quality management systems already operational. Long-term viability favors acquisition targets with polymer chemistry expertise transferable to radiolucent matrix production, as stainless steel-dependent metalworkers face structural margin compression. Watch FDA guidance evolution on additive-manufactured dental devices as the signal indicating whether incumbent certification advantages will persist or erode through technological disruption.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Establishes competitive moat against uncertified suppliers facing notified body capacity constraints. |
| Direct DSO Procurement Contracting | Bypasses traditional distributor networks capturing volume concentration in Texas and Florida clinic networks. |
| Polymer Chemistry Capability Acquisition | Secures formulation expertise for radiolucent matrices demanded by French and US aesthetic restoration workflows. |
| CAD/CAM Protocol Compatibility Development | Positions preformed geometries for digital dentistry convergence in German laboratory outsourcing channels. |
| Self-Contained System Ergonomic Innovation | Captures orthodontist preference in the United States displacing multi-instrument setups and reducing inventory burden. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearances, EU MDR technical documentation filings, and ISO 13485 certification registries. Primary interviews engaged dental clinic procurement managers, biomedical engineers at German dental laboratories, regulatory affairs specialists at notified bodies, and GPO contracts managers at US dental service organizations. Secondary validation drew from customs trade data for thin-gauge stainless steel strip imports, hospital procurement database extracts, and CMS Medicare dental procedure utilization records. Bottom-up demand modeling triangulated against top-down manufacturer shipment estimates.
Segmentation dimensions modeled include product architecture complexity, material composition, end-user procurement channel, and application procedure type across the projection horizon. CAGRs were derived from installation base growth rates, procedure volume elasticities, and material substitution curves calibrated to aesthetic restoration workflow adoption patterns. Forecast inputs incorporated EU MDR transition timelines, dental service organization penetration rates by US metropolitan statistical area, and polymer chemistry specialist labor market tightness.
Decision-makers should treat outputs as directional under assumptions of stable FDA 510(k) pathway continuity and EU MDR notified body capacity recovery; material deviation in either regulatory trajectory would warrant model refresh. Specific risk factors include accelerated composite matrix adverse event reporting triggering product withdrawals, and sudden stainless steel alloy price spikes compressing manufacturer margins beyond pricing power recovery. Revision becomes warranted when DSO procurement concentration in the United States crosses threshold levels eliminating independent practitioner channel viability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Materials
Dental Resins Market
Dental Materials
Acrylic Dental Material Market
Dental Materials
Fluoride Mouthwash Market
Dental Materials
Asia-Pacific Toothpaste Market
Dental Materials
Dental Restorative and Regenerative Material Market
Dental Materials
Dental Gypsum Market
Dental Materials
Dental Bleaching Materials Market
Dental Materials
Global Dental Membrane and Bone Graft Substitutes Market
Dental Materials
Zirconia Based Dental Ceramics Market
Dental Materials
Dental Composites Market
Dental Materials
Nanotechnology Toothpaste Formulations Market
Dental Materials
Global Endodontic Consumables Market
Dental Materials
Global Teeth Whitening Product Market
Dental Materials
Cold Light Teeth Whitening Kit Market
Dental Materials
Crack Tooth Syndrome Market
Dental Materials
Dental Wax Market