
 Artificial Teeth Market | 2026-2036
Artificial Teeth Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Teeth Market Analysis
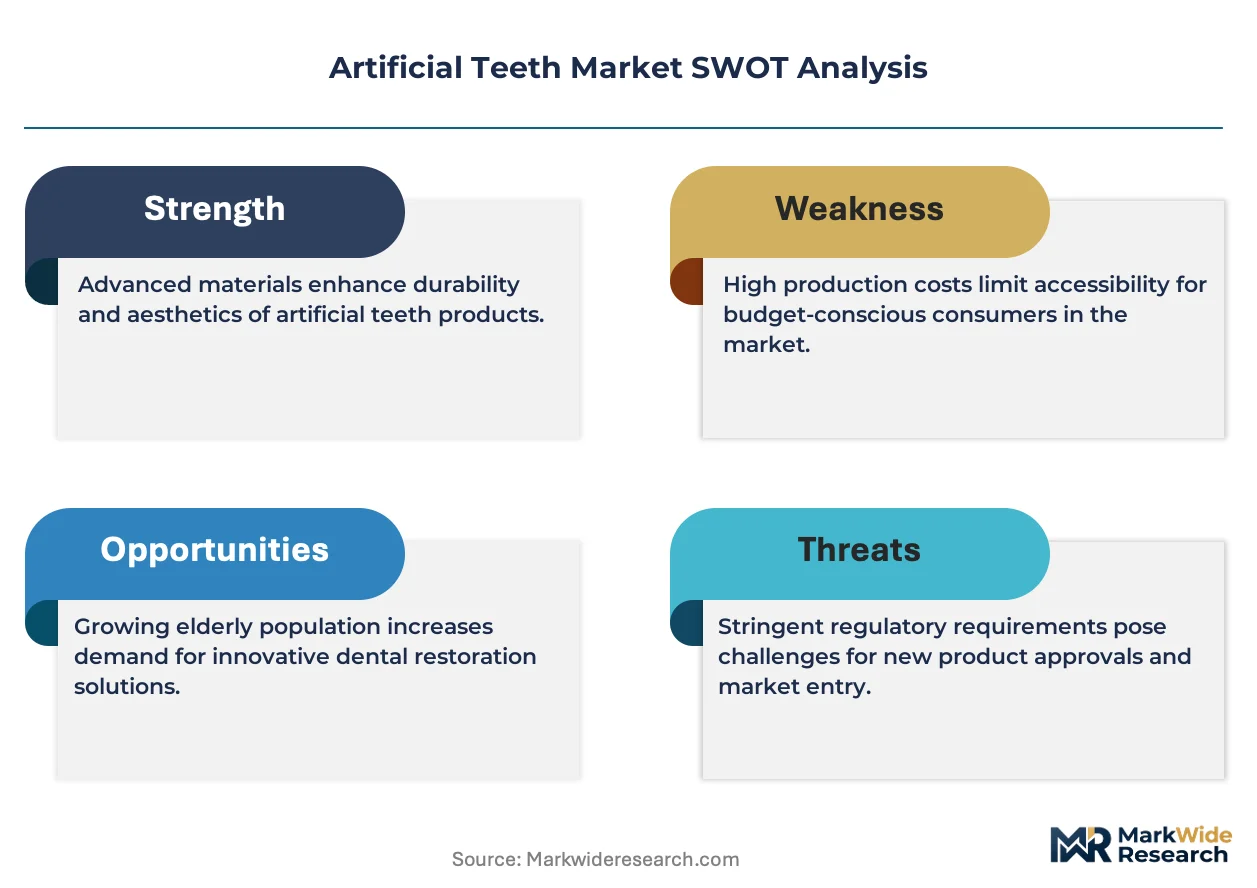
MDR compliance in Europe is shifting the cost-of-entry calculus for artificial teeth manufacturers, forcing smaller laboratories to outsource validation or exit the market entirely. Institut Straumann AG leverages its vertically integrated manufacturing footprint to absorb these regulatory burdens directly. Dentsply Sirona sustains broad channel control across chairside and laboratory workflows, while Ivoclar Vivadent specializes in high-aesthetic ceramic systems that command premium positioning in cosmetic restoration segments.
Artificial teeth are prosthetic devices fabricated from acrylic resin, porcelain, metal alloys, or thermoplastic polymers to replace missing natural dentition, with specifications covering flexural strength, wear resistance, and biocompatibility per ISO 20795 and ISO 6871 standards. Their primary purpose spans functional mastication restoration, phonetic correction, and aesthetic facial contour maintenance in edentulous or partially edentulous patients. Complete dentures retain dominant volume share among product types due to entrenched reimbursement pathways, though fixed bridges capture disproportionate margin pools through implant-supported configurations. Acrylic resin leads material selection for cost-sensitive removable applications, while porcelain and zirconia-reinforced ceramics concentrate in premium fixed restorations where durability and translucency determine clinical acceptance.
FDA 510(k) clearances govern material biocompatibility and mechanical performance for US market access, while Europe's MDR and CE marking requirements impose clinical evidence standards that extend approval timelines. Japan's PMDA maintains distinct filing categories for prefabricated versus custom-fabricated prostheses, creating segmented compliance obligations. Stakeholders must monitor evolving reimbursement thresholds for CAD/CAM-manufactured restorations as health technology assessment bodies recalibrate cost-effectiveness benchmarks against traditional laboratory methods.
Market Dynamics
MDR compliance in Europe is forcing artificial teeth manufacturers to absorb validation costs directly, while Japan's PMDA filing categories create segmented obligations for prefabricated versus custom-fabricated prostheses. These dual regulatory pressures are compressing laboratory margins and accelerating consolidation among smaller European operators.
Growth Catalysts
- Japan's geriatric edentulism corridor:The metropolitan belt from Tokyo to Osaka sustains replacement cycle demand as aging populations drive prosthetic service volumes across dental clinics.
- FDA 510(k) pathway for bioactive ceramics:Clearance mechanisms for novel dental materials are redirecting R&D investment toward hybrid composites and zirconia-reinforced systems.
- CAD/CAM chairside integration:Digital manufacturing workflows are shortening turnaround times for same-day restorations in high-volume dental practices.
Market Restraints
- Acrylic resin input volatility:Petrochemical feedstock price swings compress margins for cost-sensitive removable denture production.
- European MDR clinical evidence requirements:Extended approval timelines and validation costs create barriers for mid-sized dental laboratories without captive regulatory affairs capacity.
- Implant-supported fixed bridge substitution:Premium removable denture volumes face displacement from osseointegrated configurations in reimbursed markets.
Strategic Opportunities
- Germany's laboratory consolidation vacuum:MDR-driven exits by smaller operators create acquisition targets for scaled manufacturers with integrated validation infrastructure.
- Health technology assessment recalibration:Cost-effectiveness benchmarks for CAD/CAM-manufactured restorations are shifting reimbursement thresholds in favor of digital production methods.
- Convergence of 3D printing and bioactive surface engineering:Additive manufacturing paired with osteoconductive coatings opens implant-abutment customization for patient-specific anatomies.
Industry Challenges
- CAD/CAM technician certification gaps:Digital dentistry workflows require cross-trained dental technologists proficient in both clinical design software and subtractive manufacturing operations.
- Legacy laboratory management system integration:Small-to-mid-sized prosthetic laboratories face friction migrating from paper-based case tracking to cloud-based production management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Teeth Market |
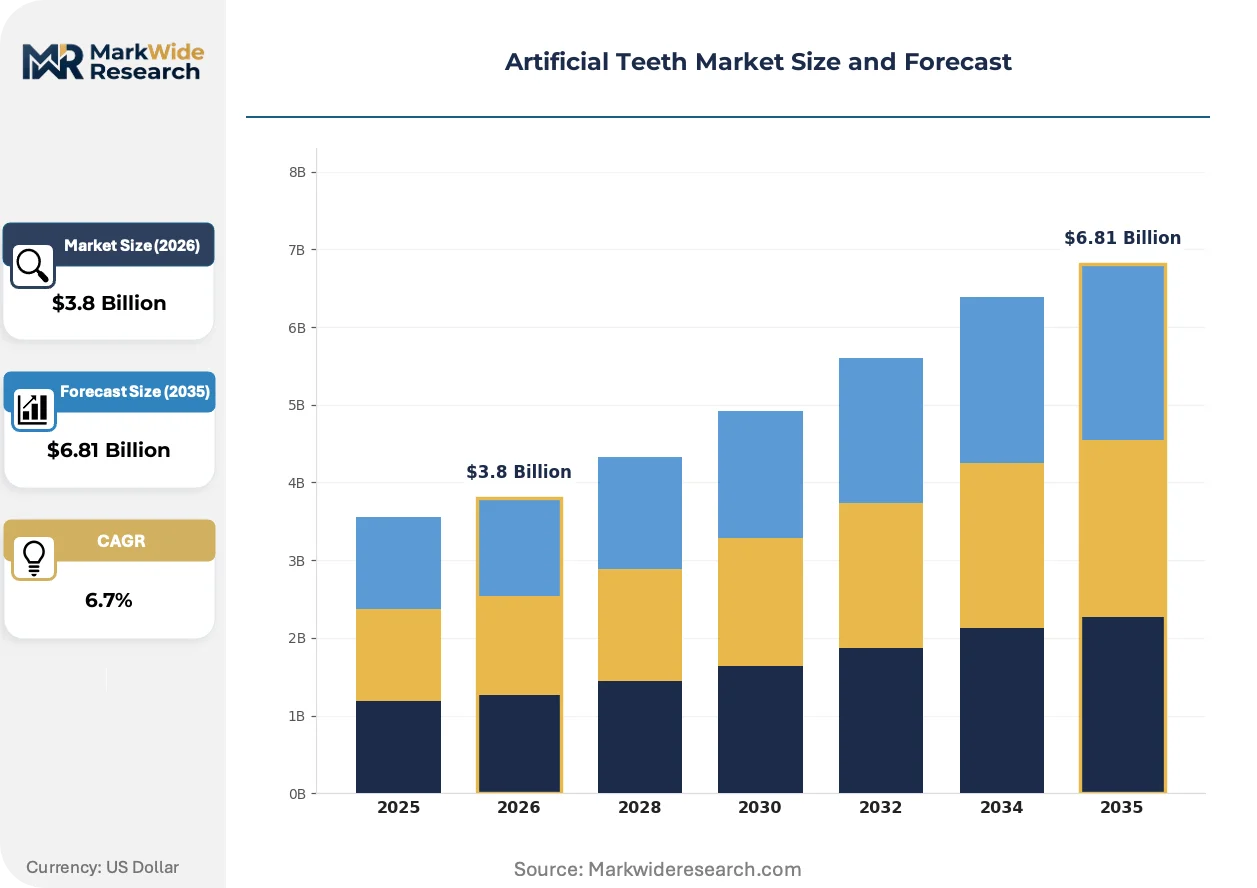
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Complete Dentures, Partial Dentures, Fixed Bridges, Removable Bridges Material: Acrylic Resin, Porcelain, Metal, Thermoplastic End User: Dental Clinics, Hospitals, Laboratories, Home Care Application: Cosmetic Restoration, Functional Restoration, Preventive Care, Orthodontics |
| Companies Covered | Institut Straumann AG, Dentsply Sirona, Envista, Henry Schein, Osstem Implant, Ivoclar Vivadent, ZimVie, Glidewell, GC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Teeth Market Emerging Trajectories
Digital fabrication workflows are fragmenting traditional laboratory hierarchies, while regulatory bodies recalibrate evidence standards for patient-matched devices. Material science advances are compressing the performance gap between economy and premium restoration tiers.
CAD/CAM software for dental prosthetics is modularizing case design into discrete, interoperable components that laboratories can license separately from hardware ecosystems. Mid-sized dental laboratories in Germany and the United States are adopting modular design suites at accelerated pace to avoid full-system capital commitments. This architecture is modularizing supplier relationships, enabling laboratories to mix scanning hardware from Dentsply Sirona with design software from competing vendors without workflow fragmentation.
Europe's MDR is extending clinical evidence requirements for prefabricated dental prostheses beyond prior CE marking self-certification protocols. Manufacturers now face notified body scrutiny for mechanical performance claims previously accepted through ISO 20795 testing alone. High-aesthetic ceramic systems command the most acute compliance burden, as translucent zirconia and lithium disilicate restorations require biocompatibility documentation that acrylic resin dentures escape.
Consolidated procurement by dental service organizations is unbundling after-sales technical support from product supply agreements. Large clinic chains in Japan's metropolitan corridor now negotiate separate service contracts for shade-matching consultation and remounting assistance. This bifurcation is most visible in Tokyo-Osaka corridor practices where group purchasing organizations capture volume discounts while outsourcing technical training to third-party dental education platforms.
Artificial Teeth Market Segmentation
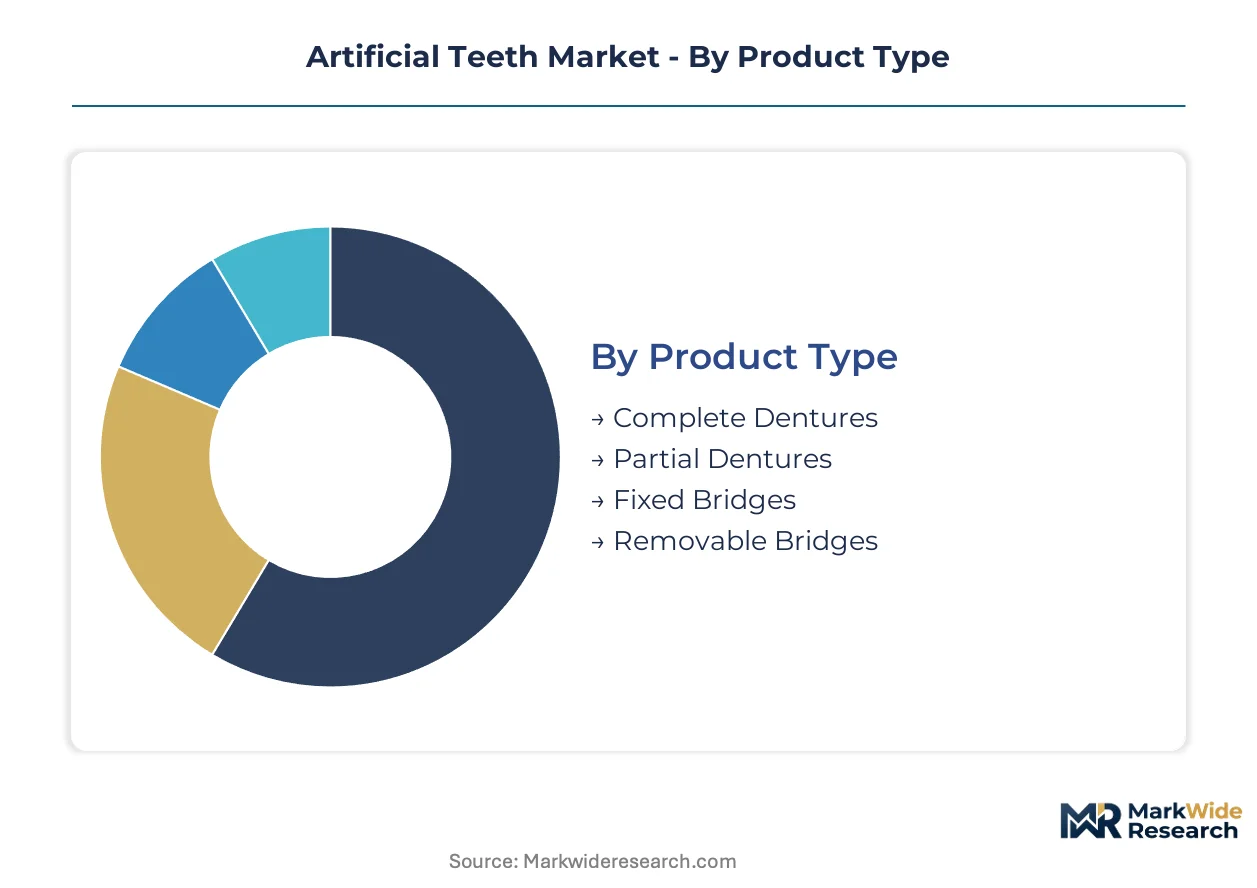
Artificial teeth manufacturers navigate divergent production economics across customization intensities. Standardized prefabricated lines serve high-volume removable applications while patient-matched fabrication commands premium positioning in fixed implantology.
Product Type:
Standardization dominates the removable prosthetic spectrum while fixed configurations demand bespoke laboratory workflows.
- Complete Dentures:Full-arch acrylic or porcelain assemblies replace entire dentition in edentulous patients. Japan's metropolitan corridor from Tokyo to Osaka sustains concentrated demand as geriatric populations drive replacement cycles through dental clinic networks.
- Partial Dentures:Removable frameworks with artificial teeth attached to metal or acrylic bases restore partially edentulous arches. Metal-cast clasps and precision attachments define premium tier differentiation in Germany's consolidated laboratory market.
- Fixed Bridges:Cemented or screw-retained prostheses span edentulous spaces using adjacent teeth or implants as abutments.
- Removable Bridges:Detachable partial restorations combine aesthetic tooth replacement with patient-removable maintenance access.
Leading the category by volume: Complete Dentures. Expanding most quickly: Fixed Bridges.
Material:
Cost tier stratification separates commodity resin volumes from ceramic premium pools.
- Acrylic Resin:Polymer-based compounds formulated with polymethyl methacrylate dominate removable denture bases and artificial tooth fabrication. Petrochemical feedstock volatility compresses margins for cost-sensitive production lines serving high-volume dental clinics.
- Porcelain:Fired ceramic materials deliver translucency and wear resistance for aesthetic anterior restorations. FDA 510(k) clearance pathways for novel bioactive ceramics redirect R&D investment toward hybrid composite formulations.
- Metal:Cobalt-chromium and precious alloys provide structural frameworks for removable partial dentures and implant abutments.
- Thermoplastic:Flexible polyamide and polyester resins enable clasp-free removable partial denture designs.
Highest volume concentration: Acrylic Resin. Steepest margin expansion: Porcelain.
End User:
Channel control patterns diverge between chairside service delivery and outsourced laboratory production.
- Dental Clinics:Chairside service providers constitute the primary demand channel across aging population corridors. CAD/CAM integration enables same-day restoration delivery in high-volume Japanese practices from Tokyo to Osaka.
- Hospitals:Institutional settings manage complex maxillofacial reconstruction and trauma-related prosthetic rehabilitation.
- Laboratories:Independent and manufacturer-affiliated facilities fabricate custom prostheses from digital or analog impressions.
- Home Care:Direct-to-consumer channels serve denture adhesive, cleaning, and temporary repair product demand.
Dominant volume channel: Dental Clinics. Gaining share fastest: Laboratories via digital workflow consolidation.
Application:
Functional necessity drives reimbursement pathways while aesthetic indications command out-of-pocket expenditure.
- Cosmetic Restoration:Aesthetic-focused procedures emphasize shade matching, gingival characterization, and facial contour preservation. High-aesthetic ceramic systems from specialized manufacturers command premium positioning in elective treatment segments.
- Functional Restoration:Masticatory rehabilitation and phonetic correction address edentulism-related quality-of-life impairment. Reimbursement frameworks in Germany and Japan prioritize functional outcomes over aesthetic enhancement.
- Preventive Care:Interim prostheses and space maintainers prevent occlusal drift and ridge resorption progression.
- Orthodontics:Temporary anchorage devices and aesthetic pontics support orthodontic treatment sequencing.
Largest reimbursement-eligible segment: Functional Restoration. Climbing fastest: Cosmetic Restoration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Osaka, Munich, and Seoul concentrate manufacturing incentives for dental prosthetics, drawing capital toward precision fabrication clusters that serve aging metropolitan populations.
United States
FDA 510(k) clearances for bioactive ceramics accelerate material innovation cycles in implant dentistry. The Boston-Cambridge corridor hosts venture-backed startups developing hybrid composite formulations. Dental service organizations in Texas and Florida consolidate procurement volumes, unbundling technical support from product supply agreements.
Germany
Europe's MDR extends clinical evidence requirements for prefabricated prostheses beyond prior CE marking protocols. Notified body scrutiny now governs mechanical performance claims for translucent zirconia systems. North Rhine-Westphalia laboratories absorb validation costs directly or exit to larger integrated manufacturers.
Japan
PMDA filing categories create segmented compliance obligations for prefabricated versus custom-fabricated prostheses. The Tokyo-Osaka metropolitan belt sustains concentrated replacement cycle demand as geriatric edentulism rates climb. Chairside CAD/CAM integration enables same-day restoration delivery in high-volume Kanto region practices.
South Korea
MFDS regulatory pathways align with international standards while maintaining distinct documentation requirements for imported dental materials. Seoul Capital Area dental clinics adopt digital manufacturing workflows at accelerated pace. Busan-Ulsan manufacturing clusters supply precision-milled titanium frameworks for export markets.
Artificial Teeth Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidated procurement by dental service organizations compresses margins for mid-sized independent laboratories. Three archetypes dominate: vertically integrated manufacturers with captive regulatory affairs capacity, modular solution providers licensing design software separately from hardware ecosystems, and high-aesthetic ceramic specialists commanding premium positioning in cosmetic segments. Competitive moves concentrate on M&A absorption of MDR-exited European laboratories and strategic partnerships for CAD/CAM chairside integration.
Among Switzerland-based manufacturers, Institut Straumann AG exemplifies the vertically integrated archetype with manufacturing footprints that absorb regulatory burdens directly. Dentsply Sirona occupies a position spanning chairside and laboratory workflow control. Ivoclar Vivadent represents the high-aesthetic ceramic specialist tier, with Liechtenstein-originated operations concentrating on premium restoration segments where translucency determines clinical acceptance.
| Leading Market Players |
|---|
| Institut Straumann AG |
| Dentsply Sirona |
| Envista |
| Henry Schein |
| Osstem Implant |
| Ivoclar Vivadent |
| ZimVie |
| Glidewell |
| GC Corporation |
| Others |
Supply Flow & Price Mechanics
Dental technician labor pools in North Rhine-Westphalia and Osaka-Kobe corridor anchor production cost structures, with wage differentials between German master technicians and Japanese CAD/CAM operators driving three-tier spreads across premium ceramic, standard acrylic, and economy thermoplastic segments.
Pricing Analysis
Lead-time premiums compress standard pricing bands, with same-day CAD/CAM chairside restorations commanding substantial markups over laboratory-fabricated alternatives with two-week turnaround cycles. Three-tier pricing structure across premium, standard, and economy levels separates zirconia-reinforced ceramic systems from injection-molded acrylic bases and flexible polyamide frameworks. Pricing pressure stems from petrochemical feedstock volatility in acrylic resin supply chains. Dental service organizations exhibit acute price sensitivity in removable denture procurement, while implant-supported fixed bridge buyers prioritize mechanical performance over unit cost.
Supply Chain Analysis
Domestic-content mandates in Japan's PMDA filing categories and Germany's MDR technical documentation requirements reshape sourcing toward validated regional suppliers. Manufacturing concentrates in Germany, Japan, and South Korea, with Busan-Ulsan clusters supplying precision-milled titanium frameworks. Raw material dependencies center on polymethyl methacrylate resins, zirconia powders, and cobalt-chromium alloys. Single-source vulnerability runs through Chinese-sourced rare earth elements in zirconia stabilization. Distribution runs through dental service organization procurement hubs and independent laboratory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified dental technician capacity constraints prop pricing across all tiers, as MDR validation requirements and CAD/CAM cross-training demands outstrip qualified labor formation.
For Market Incumbents: Acquire MDR-validated European laboratory assets to absorb compliance infrastructure directly. Consolidate fragmented German operators facing exit pressure from clinical evidence cost burdens. Channel control through dental service organization procurement contracts defends against implant-supported fixed bridge substitution. For New Entrants and Emerging Players: FDA 510(k) clearance pathway for bioactive ceramics in the United States opens a window for hybrid composite specialists to establish clinical evidence portfolios before European MDR convergence. Target Japan's geriatric edentulism corridor with modular CAD/CAM software licensing models that bypass full-system capital requirements. Go-to-market through third-party dental education platforms unbundles technical support from product supply. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated manufacturers given reimbursement recalibration toward CAD/CAM-manufactured restorations. Long-term viability favors archetypes with captive regulatory affairs capacity spanning FDA, MDR, and PMDA filing categories. Monitor health technology assessment body cost-effectiveness benchmark shifts as inflection signal for digital production method adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Compliance Infrastructure Acquisition | Absorbs validation costs directly while competitors face laboratory exit waves. |
| CAD/CAM Chairside Integration Partnership | Dentsply Sirona hardware ecosystems enable same-day restoration delivery in Tokyo-Osaka corridor. |
| Bioactive Ceramic FDA 510(k) Pathway Investment | Hybrid composite formulations capture premium positioning ahead of European regulatory convergence. |
| Dental Service Organization Procurement Consolidation | Volume discounts unbundle technical support into separate service contract negotiations. |
| 3D Printing and Osteoconductive Coating Convergence | Patient-specific implant-abutment customization opens anatomical matching capabilities. |
Methodological Framework
SEC 10-K filings, FDA 510(k) clearance databases, and PMDA submission records formed the secondary backbone, cross-referenced with ISO 20795 and ISO 6871 standard documentation. Primary interviews with dental laboratory directors, CAD/CAM system engineers, GPO contracts managers, and prosthodontic clinicians validated production cost structures and reimbursement pathway evolution. Bottom-up triangulation across material input costs and top-down reconciliation against dental clinic service volumes anchored market sizing.
Historical trendline analysis of prosthetic service volumes across aging population corridors informed projection modeling across the analysis window. Segmentation dimensions spanned product type, material grade tier, end-user channel, and application indication. CAGRs derived from replacement cycle frequency patterns and digital workflow adoption curves. Forecast inputs incorporated petrochemical feedstock price elasticity and regulatory approval timeline distributions.
The model assumes a particular technology adoption path; alternative pathways for chairside CAD/CAM integration would alter the outlook if technician certification gaps persist unresolved. Forecasts reflect assumptions regarding MDR implementation consistency and reimbursement threshold stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Materials
Remineralizing Gum Market
Dental Materials
Teeth Whitening Market
Dental Materials
Fluoride-Free Toothpaste Market
Dental Materials
Asia-Pacific Toothpaste Market
Dental Materials
Dental Composites Market
Dental Materials
Global Dental Adhesive Market
Dental Materials
Dental Bleaching Materials Market
Dental Materials
Dental Bonding Agent Market
Dental Materials
Dental Biomaterials Market
Dental Materials
Dental Alloys Market
Dental Materials
Dental Resins Market
Dental Materials
Dental Fiberglass Posts Market
Dental Materials
Dental Amalgam Market
Dental Materials
Global Endodontic Consumables Market
Dental Materials
Toothpaste Market
Dental Materials
Dental Impression Material Market