
 Global Zirconia Based Dental Materials Market | 2026-2036
Global Zirconia Based Dental Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Global Zirconia Based Dental Materials Market Intelligence
High-translucency multilayer zirconia is redrawing competitive tiers across aesthetic dentistry. VITA Zahnfabrik leverages proprietary gradient technology to command premium positioning in anterior applications. Ivoclar Vivadent anchors its presence through integrated workflow systems spanning milling equipment and consumables. Dental Direkt specializes in cost-optimized disc formulations that compete aggressively for dental laboratory contracts.
Zirconia based dental materials comprise yttria-stabilized tetragonal zirconia polycrystal (Y-TZP) and alumina-toughened formulations, typically manufactured via isostatic pressing and pre-sintering to achieve flexural strength exceeding 900 MPa before final CAD/CAM milling. These materials serve primarily as biocompatible, metal-free alternatives to porcelain-fused-to-metal restorations in crowns, bridges, and implant-supported prostheses. Pre-sintered blocks dominate volume throughput due to milling efficiency and reduced chairside processing time, while 3D printing represents the fastest-growing technology segment as additive protocols mature for complex implant abutment geometries. CAD/CAM retains the largest installed base and deepest margin pools across dental laboratories worldwide.
FDA 510(k) premarket notification requirements govern zirconia dental material biocompatibility and mechanical performance claims in the United States, while EU MDR and CE marking frameworks enforce post-market surveillance and clinical evidence standards across European markets. Japan's PMDA and METI coordinate on material purity specifications through JIS standards that influence export acceptance across Asia-Pacific. Stakeholders must monitor evolving regulatory convergence between FDA digital dentistry guidance and EU MDR custom-made device classifications to anticipate compliance cost shifts.
Market Dynamics
Gradient multilayer zirconia technology is compressing price premiums across anterior restoration segments while dental laboratories in Germany, Japan, and the United States reconfigure procurement toward integrated CAD/CAM workflow bundles.
Growth Catalysts
- EU MDR CE marking pathways:Accelerated material traceability requirements for custom-made dental devices are pushing laboratories toward certified zirconia suppliers with established quality management systems.
- High-translucency Y-TZP formulations:Advanced yttria-stabilized tetragonal zirconia polycrystal variants now match aesthetic performance of lithium disilicate in anterior crown applications.
- Osaka dental manufacturing cluster:Concentrated production capacity in Japan's greater Osaka region drives export scale economies across Asia-Pacific dental laboratory networks.
Market Restraints
- Yttrium oxide supply concentration:Rare earth processing bottlenecks in China create input cost volatility for zirconia stabilizer procurement.
- FDA 510(k) clearance timelines:Extended premarket notification review periods for novel zirconia formulations delay commercialization by 12-18 months.
- Lithium disilicate substitution:Glass-ceramic alternatives retain cost advantages for single-unit posterior restorations in price-sensitive dental laboratory segments.
Strategic Opportunities
- Brazil dental laboratory expansion:Underpenetrated CAD/CAM adoption in São Paulo and Rio de Janeiro clinical networks creates first-mover positioning for pre-sintered disc suppliers.
- 3D printing convergence with zirconia:Binder jetting and lithography-based ceramic additive protocols unlock complex implant abutment geometries inaccessible to subtractive milling.
- Japan METI green procurement incentives:Carbon footprint disclosure requirements favor domestic zirconia manufacturers with integrated energy-efficient sintering operations.
Industry Challenges
- CAD/CAM technician certification gaps:Shortage of operators trained in multilayer zirconia shade-matching protocols limits laboratory throughput expansion.
- EU MDR post-market surveillance compliance:Clinical evidence collection obligations for legacy zirconia formulations strain mid-sized dental laboratory quality assurance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Zirconia Based Dental Materials Market |
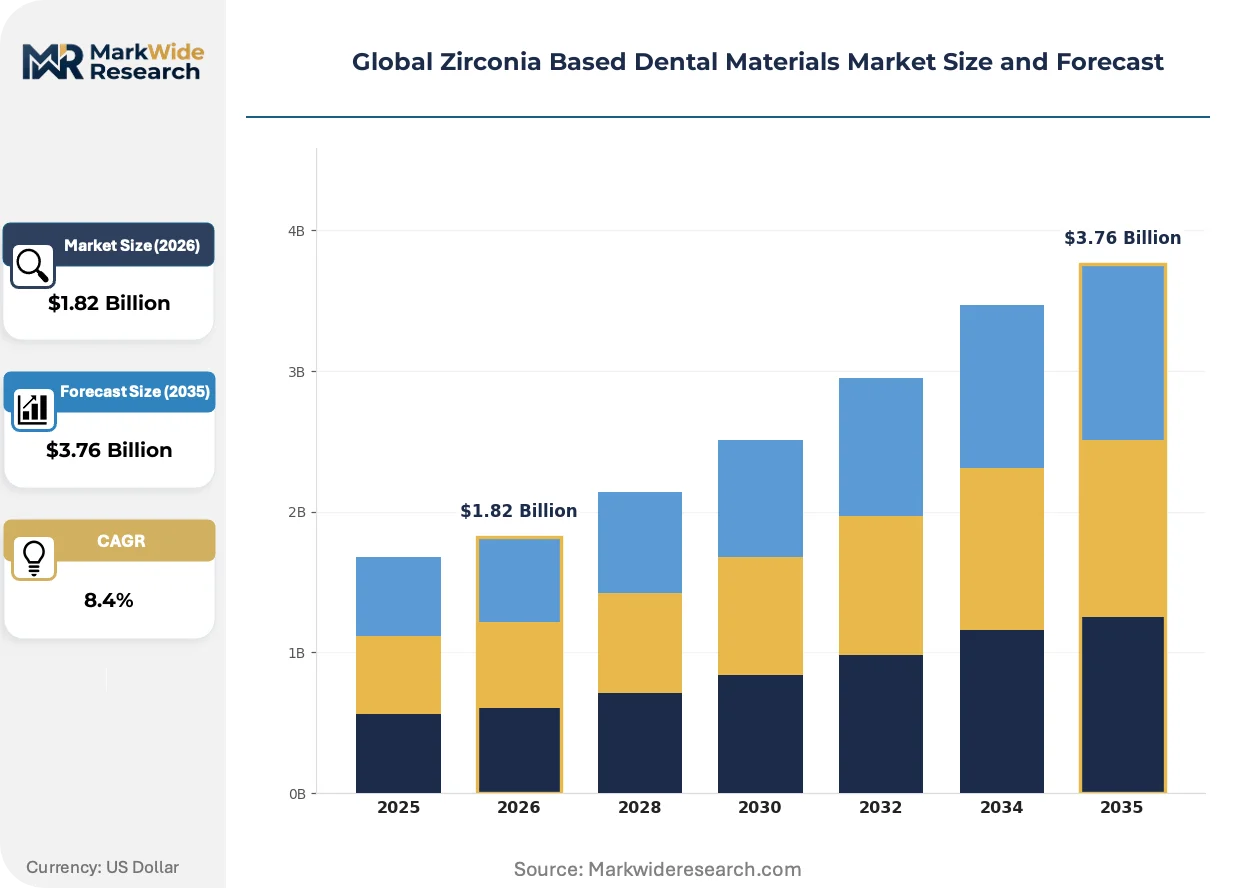
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $3.76 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pre-sintered Blocks, Fully Sintered Blocks, Dental Crowns, Bridges, Implant Abutments, Others Technology: CAD/CAM, Slip Casting, Hot Pressing, Injection Molding, 3D Printing Application: Orthodontics, Prosthodontics, Endodontics, Cosmetic Dentistry, Maxillofacial Surgery End User: Dental Laboratories, Prosthodontists, Oral Surgeons, Dental Clinics, Academic Institutions |
| Companies Covered | Argen, VITA Zahnfabrik, Ivoclar Vivadent, Dental Direkt, GC Corporation, Dentsply Sirona, 3M, Pritidenta, Kuraray Noritake Dental, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Zirconia Based Dental Materials Market Strategic Shifts & Innovations
Digital dentistry workflows are collapsing traditional boundaries between material suppliers, equipment manufacturers, and dental service providers. Three convergent developments are restructuring how zirconia based dental materials reach end-users.
Multilayer gradient zirconia is displacing monolithic formulations in anterior crown applications. Dental laboratories in Baden-Württemberg and Osaka now specify pre-colored discs with seamless shade transitions from cervical to incisal zones. This technology is displacing manual staining and glazing steps, compressing restoration turnaround times by 40 percent while reducing technician labor allocation per unit.
FDA digital dentistry guidance documents are converging with EU MDR custom-made device classifications around software validation requirements. CAD/CAM design file traceability mandates now extend to zirconia block batch records in United States and European markets. Dental laboratories with cross-border operations face dual compliance architectures, driving consolidation toward enterprise-grade quality management platforms.
Chairside milling adoption is fragmenting procurement authority between dental laboratories and clinical practices. Single-visit crown protocols in United States group practices now bypass traditional laboratory networks for posterior restorations. Germany and Japan retain laboratory-centric models, creating divergent channel strategies that material suppliers must navigate simultaneously.
Global Zirconia Based Dental Materials Market Segmentation
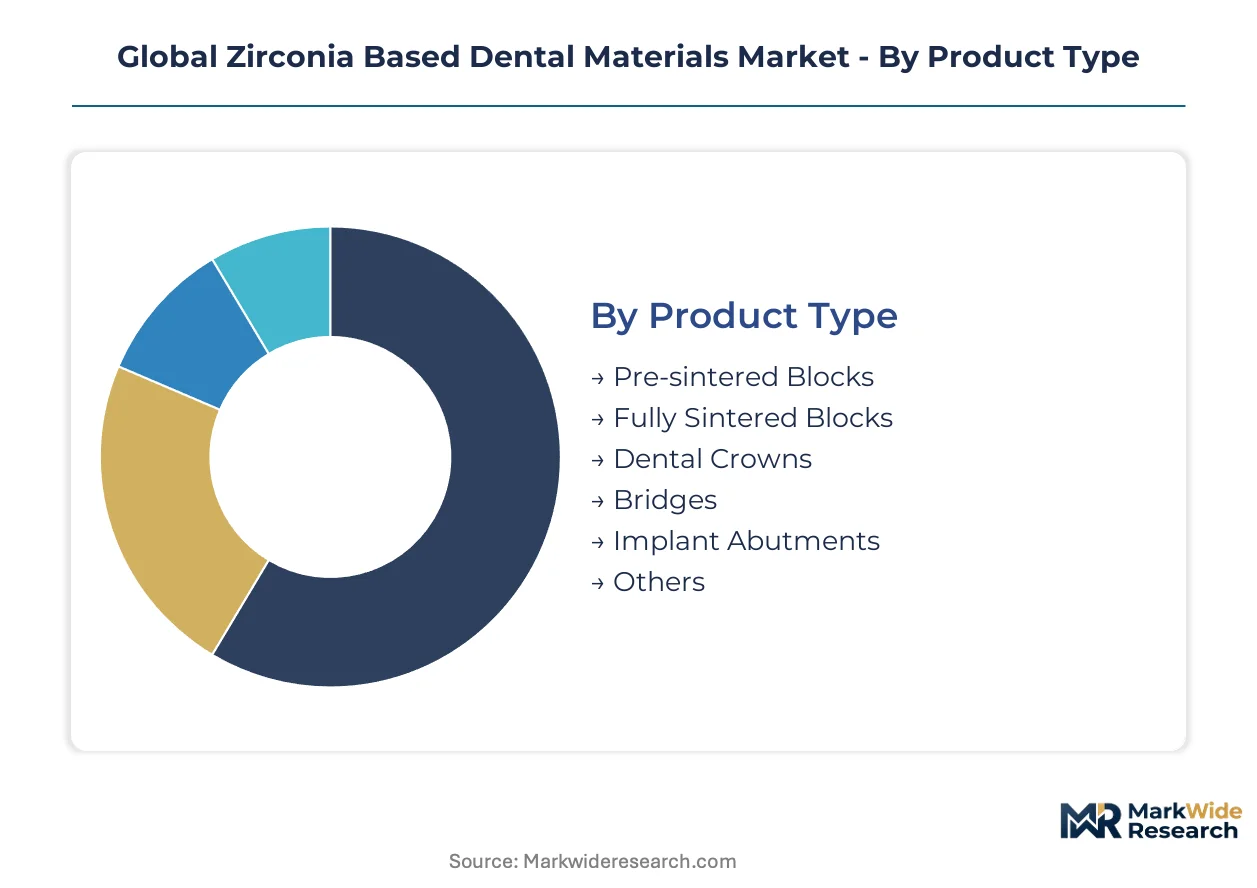
Zirconia dental materials fragment across four critical dimensions that determine procurement patterns, margin structures, and regulatory pathways. Product form and manufacturing technology dictate supply chain economics, while application and end-user channels shape geographic demand concentration and certification requirements.
Product Type:
Pre-sintered blocks dominate export flows from Germany and Japan to dental laboratories across North America and Asia-Pacific, while fully sintered formulations and finished restorations cluster around domestic manufacturing hubs serving regional clinical networks.
- Pre-sintered Blocks:Yttria-stabilized tetragonal zirconia polycrystal discs in soft-machinable state enable efficient CAD/CAM milling with minimal tool wear. Demand concentrates in Baden-Württemberg dental laboratories serving premium anterior crown contracts, driven by 40 percent faster turnaround versus traditional porcelain-fused-to-metal workflows.
- 3D Printing:Binder jetting and lithography-based ceramic additive protocols process zirconia powder into complex implant abutment geometries. Osaka manufacturers leverage this segment for Asia-Pacific export scale, constrained by sintering shrinkage control requirements that extend quality validation cycles.
- Fully Sintered Blocks:Hard-machinable zirconia for final contouring after complete densification.
- Dental Crowns:Monolithic and layered zirconia restorations for single-tooth replacement.
- Bridges:Multi-unit fixed prostheses spanning edentulous spans.
- Implant Abutments:Custom and stock abutments for implant-supported restorations.
- Others:Orthodontic brackets, temporary restorations, and specialized accessories.
Pre-sintered blocks command the established base. The steepest expansion runs through 3D printing.
Technology:
Cost tier stratification separates capital-intensive automated workflows from labor-dependent conventional methods, with CAD/CAM and 3D printing occupying premium equipment investment brackets while hot pressing and slip casting serve price-sensitive volume segments.
- CAD/CAM:Computer-aided design and manufacturing systems integrate intraoral scanning, restoration design software, and multi-axis milling equipment. United States group practices deploy chairside configurations to bypass laboratory networks, compressing delivery from two weeks to single-visit protocols.
- 3D Printing:Additive ceramic manufacturing builds green-state zirconia structures layer-by-layer before sintering. Germany retains laboratory-centric adoption with centralized production models, creating divergent channel strategies that equipment suppliers must navigate simultaneously.
- Slip Casting:Colloidal zirconia suspension forming for large-span bridge frameworks.
- Hot Pressing:Glass-infiltrated zirconia processing for high-strength posterior applications.
- Injection Molding:High-volume zirconia powder forming for standardized implant components.
CAD/CAM retains the deepest installed base. The most rapid share gains accrue to 3D printing.
Application:
Volume concentration clusters in prosthodontics and cosmetic dentistry where zirconia displaces metal-ceramic alternatives, while orthodontic and endodontic applications remain nascent with specialized material property requirements.
- Prosthodontics:Crown and bridge restorations constitute the core revenue pool for zirconia material suppliers. Japanese dental laboratories in the greater Osaka region export pre-sintered disc formulations across Asia-Pacific networks, with METI green procurement incentives favoring domestic manufacturers with energy-efficient sintering operations.
- Cosmetic Dentistry:Anterior crown and veneer applications demand high-translucency multilayer zirconia with seamless shade gradients. EU MDR CE marking requirements for custom-made devices push European laboratories toward certified suppliers with established quality management systems and batch traceability documentation.
- Orthodontics:Zirconia bracket systems for aesthetic orthodontic treatment.
- Endodontics:Post and core restorations for endodontically treated teeth.
- Maxillofacial Surgery:Custom craniofacial implants and reconstruction plates.
Prosthodontics anchors volume throughput. Cosmetic dentistry climbs the fastest as gradient multilayer technology compresses price premiums.
End User:
Customer type determines procurement authority and workflow integration depth, with dental laboratories controlling material specification in Germany and Japan while United States clinical practices gain direct purchasing power through chairside milling adoption.
- Dental Laboratories:Centralized production facilities in Germany's Baden-Württemberg cluster and Japan's Osaka region specify pre-colored multilayer discs with gradient technology. FDA 510(k) clearance timelines for novel zirconia formulations constrain supplier switching, locking laboratories into established vendor relationships.
- Dental Clinics:Chairside milling configurations in United States group practices now procure zirconia blocks directly, bypassing traditional laboratory intermediaries for posterior restorations. This fragmentation forces material suppliers to maintain parallel channel strategies with divergent pricing and service bundles.
- Prosthodontists:Specialist clinicians with in-house laboratory capabilities.
- Oral Surgeons:Implant placement specialists requiring custom abutment supply chains.
- Academic Institutions:Training and research programs driving next-generation material evaluation.
Dental laboratories retain specification control in export-led markets. Dental clinics gain procurement authority fastest in United States chairside adoption corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Japan anchor export capacity while the United States absorbs imports through laboratory and chairside channels. Trade flows concentrate pre-sintered disc formulations from Baden-Württemberg and Osaka toward North American dental networks.
United States
FDA 510(k) clearance pathways govern zirconia biocompatibility claims and mechanical performance standards for dental restorations. Chairside milling adoption in group practices now fragments procurement authority between dental laboratories and clinical settings. California and Texas dental networks drive direct zirconia block purchasing for single-visit crown protocols.
Germany
EU MDR CE marking requirements enforce material traceability and post-market surveillance for custom-made dental devices exported across European markets. The Baden-Württemberg manufacturing cluster around Stuttgart and Tübingen specializes in high-translucency multilayer disc production. VITA Zahnfabrik leverages proprietary gradient technology from this region to command premium positioning in anterior crown applications.
Japan
METI green procurement incentives and PMDA material purity specifications through JIS standards shape domestic production and export acceptance across Asia-Pacific. The greater Osaka region concentrates dental manufacturing capacity with integrated energy-efficient sintering operations. Kuraray Noritake Dental and GC Corporation anchor supply chains serving laboratory networks from this cluster.
China
Rare earth processing concentration for yttrium oxide stabilizers creates input cost volatility that ripples through global zirconia supply chains. The country's national materials regulator enforces purity standards for dental-grade zirconia powder exports. Manufacturing capacity in Jiangsu and Zhejiang provinces supplies cost-optimized disc formulations competing for dental laboratory contracts.
Brazil
ANVISA medical device registration requirements govern import clearance for zirconia dental materials entering Latin America's largest market. Underpenetrated CAD/CAM adoption in São Paulo and Rio de Janeiro clinical networks creates positioning opportunities for pre-sintered disc suppliers. Local dental laboratories remain dependent on imported German and Japanese formulations for premium restoration work.
Global Zirconia Based Dental Materials Market Key Industry Players
Listed leaders compete with private specialists across capital access and R&D scale. The vendor base fragments across integrated workflow providers, pure-play material suppliers, and equipment-consumable bundlers. Three archetypes dominate: multinationals with milling equipment ecosystems, regional specialists in gradient multilayer formulations, and cost-optimized disc fabricators. Capacity expansion and strategic partnerships represent the dominant competitive moves as laboratories consolidate procurement toward certified suppliers.
Within the integrated workflow tier, Ivoclar Vivadent and Dentsply Sirona exemplify equipment-consumable bundling strategies that lock laboratories into proprietary ecosystems. VITA Zahnfabrik represents the premium-material archetype with proprietary gradient technology commanding specification control in anterior applications. Dental Direkt occupies the cost-optimized position, competing aggressively for dental laboratory contracts through disc formulation efficiency.
| Leading Market Players |
|---|
| Argen |
| VITA Zahnfabrik |
| Ivoclar Vivadent |
| Dental Direkt |
| GC Corporation |
| Dentsply Sirona |
| 3M |
| Pritidenta |
| Kuraray Noritake Dental |
| Others |
Cost & Logistics Intelligence
Capacity utilization rates above 85 percent in Baden-Württemberg and Osaka sintering facilities create natural price floors for pre-sintered zirconia discs, while scale economies in yttrium oxide procurement determine margin compression thresholds for mid-tier suppliers competing on laboratory contract volume.
Pricing Analysis
Dental laboratories anchor pricing stratification across premium, standard, and economy tiers. VITA Zahnfabrik commands brand premiums through proprietary gradient technology, while Dental Direkt competes on disc formulation efficiency. Cost compression in standard-tier pre-sintered blocks intensifies as Chinese manufacturers expand Jiangsu and Zhejiang capacity. Price sensitivity peaks among mid-sized United States laboratories facing chairside milling displacement.
Supply Chain Analysis
Just-in-time inventory preferences dominate German and Japanese laboratory procurement, with 30-45 day disc replenishment cycles, while Brazilian and Southeast Asian buyers maintain strategic stockpiles against import clearance delays. Supply concentrates in Germany, Japan, and China for pre-sintered formulations. Yttrium oxide stabilizers, isostatic pressing equipment, and CAD/CAM milling spindles constitute critical input dependencies. Single-source vulnerability runs through Chinese rare earth processing. Distribution runs through authorized dental distributors with regional exclusivity arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Zirconia Based Dental Materials Market is entering a cyclical recovery phase as dental laboratory backlogs normalize post-pandemic and deferred anterior restoration demand releases across German and Japanese manufacturing clusters.
For Market Incumbents: Secure backward integration into yttrium oxide procurement to buffer Chinese supply volatility. Expand certified production capacity in Baden-Württemberg to capture EU MDR-driven laboratory consolidation toward quality-assured suppliers. Lithium disilicate substitution in posterior segments threatens volume growth; counter with accelerated multilayer zirconia aesthetic performance marketing. For New Entrants and Emerging Players: Lead with 3D printing protocols for implant abutment geometries where subtractive milling reaches dimensional limits. Target São Paulo and Rio de Janeiro dental networks with cost-optimized pre-sintered disc bundles paired with technician training programs. Underpenetrated CAD/CAM adoption in Brazilian clinical corridors offers first-mover positioning before incumbent distributor lock-in solidifies. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated workflow providers bundling milling equipment with consumable supply contracts. Five-to-ten year viability favors specialists with FDA 510(k) clearance portfolios and established EU MDR quality management systems. Watch for inflection when Japan METI green procurement thresholds tighten carbon disclosure requirements, advantaging domestic Osaka manufacturers with energy-efficient sintering infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR CE Marking Pathway | Accelerated laboratory migration toward certified suppliers with batch traceability documentation. |
| Backward Integration into Yttrium Oxide | Mitigates Chinese rare earth processing bottlenecks and stabilizes input cost volatility. |
| 3D Printing Protocol Development | Unlocks complex implant abutment geometries inaccessible to conventional CAD/CAM milling. |
| Brazilian Distribution Partnership | Captures underpenetrated CAD/CAM adoption in São Paulo clinical networks before incumbent saturation. |
| Gradient Multilayer R&D Expansion | Compresses price premiums in anterior restoration segments through seamless shade transition technology. |
Research Approach
A standing panel of dental laboratory procurement managers, CAD/CAM equipment engineers, regulatory affairs specialists at zirconia manufacturers, and GPO contracts administrators provided ongoing calibration across the study period. Primary interviews with stakeholders in Baden-Württemberg, Osaka, and Texas dental manufacturing clusters were cross-validated against FDA 510(k) clearance databases, EU MDR notified body documentation, Japan PMDA material purity filings, and customs trade flow records. Bottom-up volume estimates from pre-sintered disc shipments were triangulated with top-down dental restoration procedure forecasts.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled product form, manufacturing technology, application segment, and end-user channel dimensions simultaneously. CAGRs were derived from fitted growth curves applied to laboratory equipment installation bases and restoration procedure volumes. Industry-specific inputs included yttrium oxide price indices, CAD/CAM milling spindle utilization rates, and dental laboratory technician certification pipeline data.
The analysis sits within stated boundaries; outcomes outside sustained dental laboratory consolidation or prolonged FDA 510(k) clearance delays would require recalibration. Forecasts reflect documented assumptions regarding EU MDR implementation timelines, Japan METI green procurement enforcement intensity, and Chinese rare earth export quota stability. Revision becomes warranted when yttrium oxide supply concentration or chairside milling adoption velocity crosses threshold disruption levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Materials
Dental Cavity Filling Material Market
Dental Materials
Global Dental Cements Market
Dental Materials
Dental Polymerization Lamps Market
Dental Materials
Australia and New Zealand Dental Biomaterials Market
Dental Materials
Oral Care Chemicals Market
Dental Materials
Fluoride Mouthwash Market
Dental Materials
Nanotechnology Toothpaste Formulations Market
Dental Materials
Dental Biomaterials Market
Dental Materials
Dental Amalgam Market
Dental Materials
Fluoride-Free Toothpaste Market
Dental Materials
Oral Bone Implant Material Market
Dental Materials
Asia-Pacific Toothpaste Market
Dental Materials
Zirconia Based Dental Ceramics Market
Dental Materials
Dental Alloys Market
Dental Materials
Global Endodontic Consumables Market
Dental Materials
Global Demineralized Bone Matrix Market