
 Dental Restorative and Regenerative Material Market | 2026-2036
Dental Restorative and Regenerative Material Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Restorative and Regenerative Material Market Analysis
Trained dental ceramists and biomaterial scientists is redrawing competitive boundaries in restorative dentistry. Dentsply Sirona leverages its integrated CAD/CAM workflow to dominate chairside composite resin placement. Institut Straumann AG anchors its position through specialized bone regeneration graft portfolios. Ivoclar Vivadent AG differentiates via advanced glass-ceramic formulations that sustain premium pricing in anterior restoration segments.
Dental restorative and regenerative materials encompass synthetic and biologically active substances engineered to repair hard and soft oral tissues, with compositions ranging from methacrylate-based composite resins to hydroxyapatite-doped bioceramics processed through sintering or sol-gel methods, serving the primary purpose of restoring masticatory function and supporting periodontal regeneration. Composite resin formulations occupy the largest product type position due to universal applicability in direct restorations, while bioceramics within the material dimension represent the fastest-growing structural segment as clinicians shift toward bioactive substrates that stimulate dentin bridge formation. Syringe delivery modes lead volume throughput in clinical settings, though capsules gain ground in endodontic obturation where precise apical control determines procedural success.
FDA 510(k) pathways govern premarket notification for novel restorative materials in the United States, while EMA medical device regulations under the EU MDR impose clinical evidence requirements that filter market entrants across European jurisdictions. ISO 10993 biocompatibility testing standards create baseline safety thresholds that all commercialized materials must satisfy before clinical deployment. Stakeholders must monitor evolving reimbursement codes for regenerative procedures as payer acceptance determines whether bioactive premium materials achieve routine clinical adoption.
Market Dynamics
Fee-for-service reimbursement structures in the United States are compressing adoption timelines for premium bioactive materials while European cost-containment measures force price-volume tradeoffs across restorative portfolios.
Growth Catalysts
- FDA 510(k) pathway compression:Expedited premarket notification for bioceramic formulations is shortening commercialization cycles for regenerative graft materials in the United States.
- Private practice consolidation:Dental service organizations are standardizing procurement around CAD/CAM-compatible composite systems that reduce chairside variability.
- Bioactive substrate demand:Hydroxyapatite-doped bioceramics that stimulate dentin bridge formation are capturing preference in endodontic obturation procedures.
Market Restraints
- Zirconia powder supply concentration:Sinter-grade zirconia feedstock dependence on limited ceramic powder suppliers creates input cost volatility for milling centers.
- EMA MDR clinical evidence thresholds:EU medical device regulations impose biocompatibility documentation burdens that filter smaller bioceramic developers from European markets.
- Amalgam substitution ceiling:Mercury-free mandates have largely exhausted easy substitution opportunities, compressing incremental volume from environmental regulations.
Strategic Opportunities
- India dental infrastructure expansion:Government health scheme coverage extension into tertiary dental procedures is opening reimbursement pathways for imported regenerative grafts.
- Chairside 3D printing convergence:Photopolymer resin formulations compatible with desktop vat-polymerization systems are enabling same-day provisional and definitive restorations without laboratory intermediation.
- Japan super-aging demographic:PMDA streamlined review pathways for geriatric-focused periodontal regeneration products are accelerating market access for bone substitute materials.
Industry Challenges
- CAD/CAM workflow integration complexity:Dental clinics face retraining burdens and capital outlay for scanner-milling unit compatibility with proprietary material libraries.
- ISO 10993 testing timeline extension:Biocompatibility validation protocols for novel methacrylate monomers are stretching development schedules for next-generation composite formulations.
- Bioceramic sintering parameter standardization:Variability in furnace calibration across dental laboratories is producing inconsistent crystallization in glass-ceramic restorations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Restorative and Regenerative Material Market |
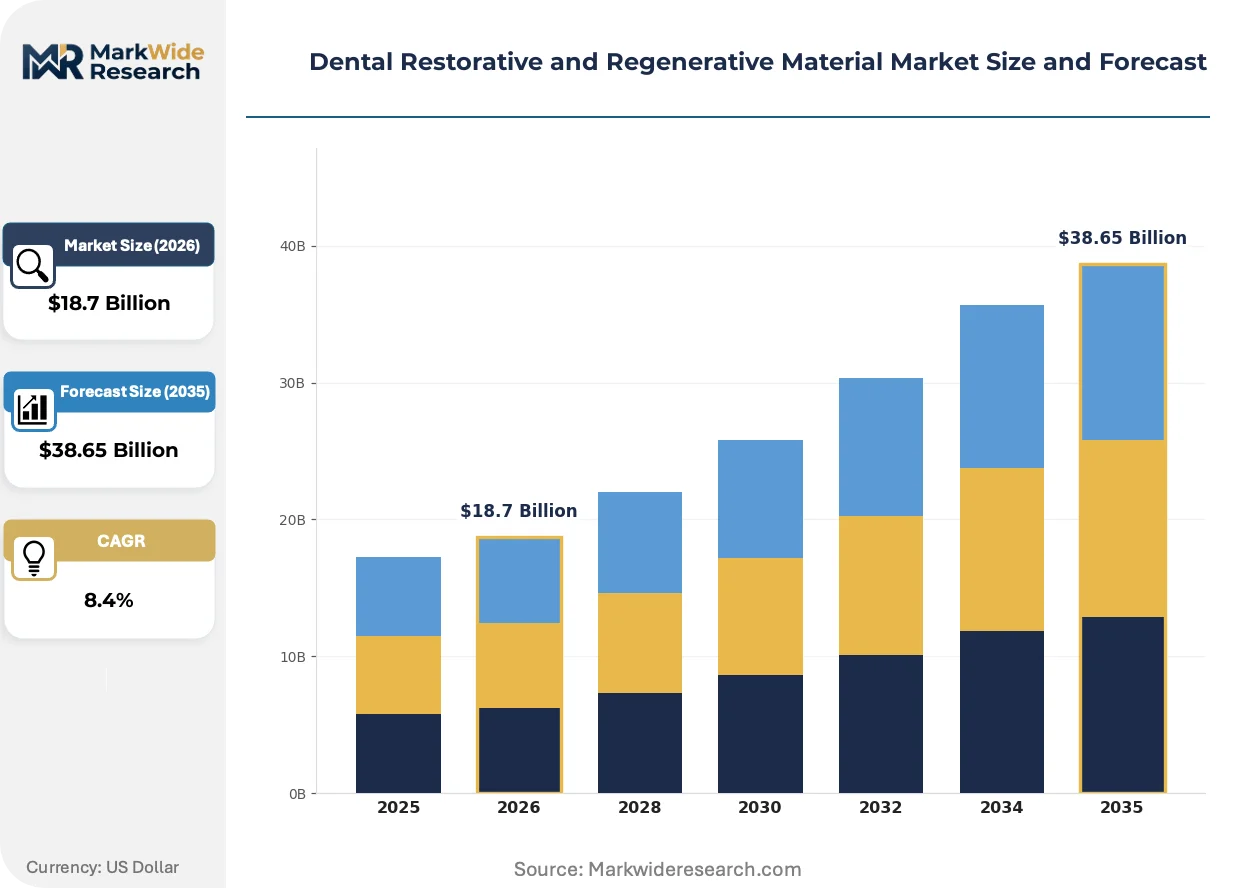
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Composite Resin, Glass Ionomer, Amalgam, Resin Ionomer Application: Oral Restoration, Endodontics, Periodontics, Preventive Dentistry Material: Bioceramics, Metals, Polymers, Ceramics Delivery Mode: Syringe, Capsules, Bulk, Tapes |
| Companies Covered | 3M, Dentsply Sirona, Institut Straumann AG, Zimmer Biomet Holdings, Ivoclar Vivadent AG, Envista Holdings Corporation, Henry Schein, Geistlich Pharma AG, ZimVie Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Restorative and Regenerative Material Market Emerging Trajectories
Digital workflow integration is collapsing the traditional laboratory-clinic boundary while bioactive material chemistry advances enable biological repair rather than passive replacement of dental tissues.
Resin-based bulk-fill composites with optimized photoinitiator packages and modified filler loadings are supplanting incremental layering techniques in posterior direct restorations. General practitioners in high-throughput United States dental service organizations are adopting these materials at accelerating rates. This technology is compressing procedure times and reducing technique sensitivity while maintaining acceptable polymerization shrinkage profiles.
EMA MDR post-market surveillance requirements are mandating clinical follow-up data collection for permanent implantable dental materials. Manufacturers must now maintain vigilance systems tracking bioceramic graft performance across European member states. Bone regeneration portfolios face heightened documentation burdens that favor larger entities with established quality management infrastructure.
Subscription-based material replenishment models are displacing spot purchasing through traditional dental distributors in North American metropolitan markets. Group purchasing organizations are consolidating procurement authority and extracting volume commitments from composite resin suppliers. California and Texas dental service organizations are piloting direct manufacturer arrangements that bypass regional dealer networks entirely.
Dental Restorative and Regenerative Material Market Segmentation
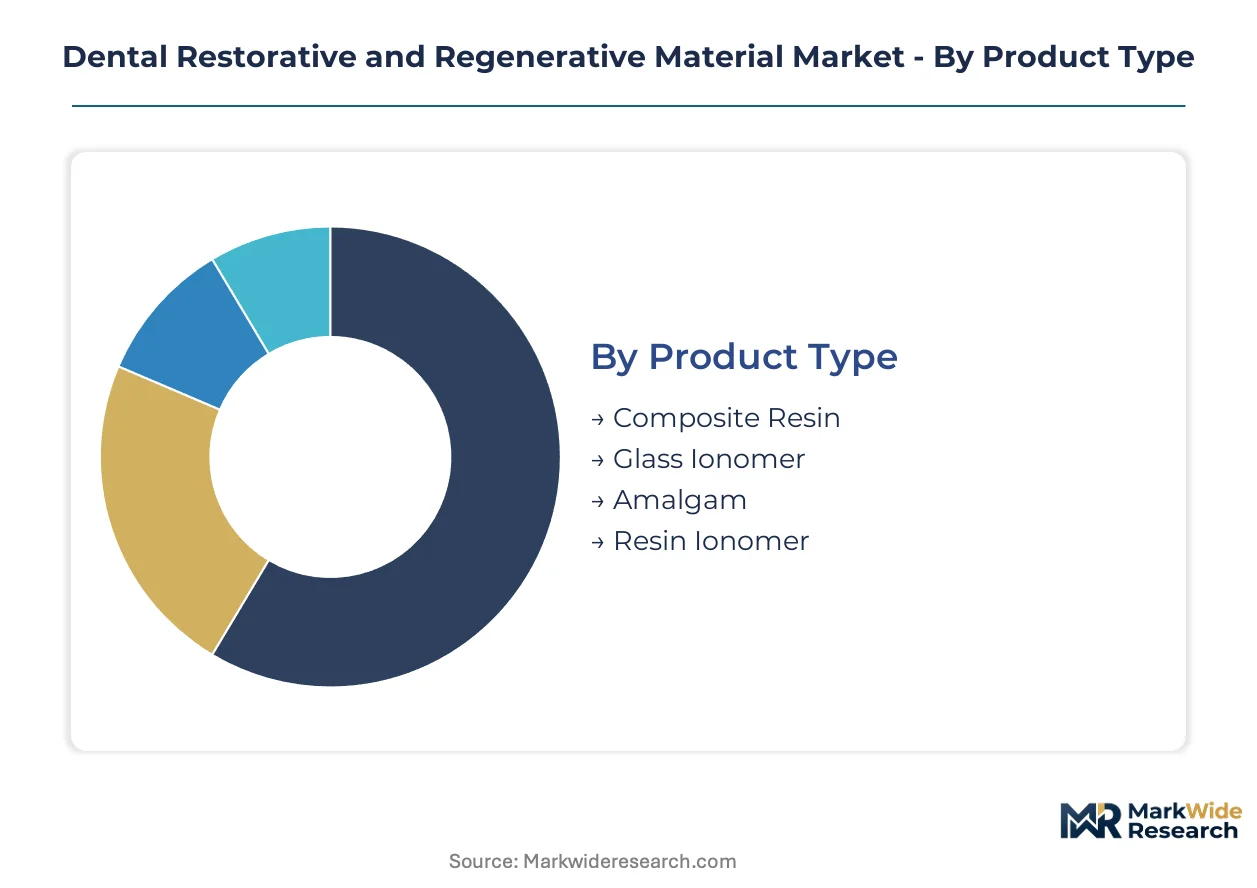
Segmentation in dental restorative materials reveals how procurement authority, clinical workflow integration, and reimbursement codes concentrate value across distinct product configurations. Understanding these divides enables suppliers to align R&D investment with where purchasing decisions actually occur.
Product Type:
Margins pool heavily in formulations that reduce chairside technique sensitivity and support CAD/CAM integration, rewarding suppliers who bundle material with digital workflow compatibility.
- Composite Resin:Methacrylate-based formulations with optimized photoinitiator packages and modified filler loadings enable bulk-fill placement without incremental layering. Demand concentrates in United States dental service organizations where procedure-time compression drives procurement decisions, though polymerization shrinkage management remains a formulation constraint.
- Glass Ionomer:Acid-base reaction cements releasing fluoride ions provide chemical adhesion to tooth structure without etching protocols. United Kingdom and Scandinavian preventive dentistry programs favor these materials for pediatric applications, yet moisture sensitivity limits anterior aesthetic acceptance.
- Amalgam:Mercury-silver alloy restorations retain cost advantages in resource-constrained settings despite environmental disposal regulations.
- Resin Ionomer:Hybrid formulations combining composite handling with glass ionomer fluoride release occupy niche indications at cementation margins.
The dominant share belongs to Composite Resin, while Glass Ionomer is closing the gap fastest through pediatric and geriatric preventive program expansion.
Application:
Volume throughput splits sharply between high-frequency routine procedures and specialized interventions where material costs represent smaller shares of total reimbursement.
- Oral Restoration:Direct and indirect procedures repairing carious lesions or traumatic defects constitute the procedural base load across general dental practices. United States fee-for-service structures support premium material uptake in metropolitan private practices, though reimbursement compression in Medicaid programs constrains material tier selection.
- Endodontics:Root canal obturation and perforation repair demand materials with precise handling characteristics and dimensional stability. Bioceramic sealers gaining preference in German and Japanese endodontic specialty practices for apical third control, with warm vertical compaction techniques reshaping sealer selection criteria.
- Periodontics:Bone regeneration and guided tissue regeneration procedures utilize graft materials and barrier membranes.
- Preventive Dentistry:Pit and fissure sealants, fluoride varnishes, and prophylactic restorations target caries incidence reduction.
Oral Restoration captures the largest procedure volume, yet Endodontics exhibits the steepest expansion trajectory as specialty referral patterns concentrate in urban centers.
Material:
Supply-side concentration varies dramatically by chemistry, with ceramic powder feedstock dependence creating input cost volatility distinct from polymer formulation flexibility.
- Bioceramics:Hydroxyapatite-doped and calcium silicate-based compositions stimulate dentin bridge formation and osteoconduction in regenerative applications. Japanese PMDA streamlined pathways and German university hospital adoption are accelerating clinical integration, though sintering parameter standardization across dental laboratories produces crystallization inconsistency.
- Metals:Precious and non-precious alloys for cast restorations and implant superstructures face substitution pressure from zirconia and polymer alternatives.
- Polymers:Methacrylate and bis-GMA based systems dominate direct restoration matrices.
- Ceramics:Feldspathic, leucite-reinforced, and zirconia-reinforced lithium silicate glass-ceramics serve aesthetic anterior and posterior indications.
Bioceramics command premium positioning in regenerative portfolios, while Polymers maintain volume leadership through universal direct restoration applicability.
Delivery Mode:
Packaging configuration determines inventory management complexity and waste reduction potential, with single-patient-unit formats gaining preference in infection-control-conscious settings.
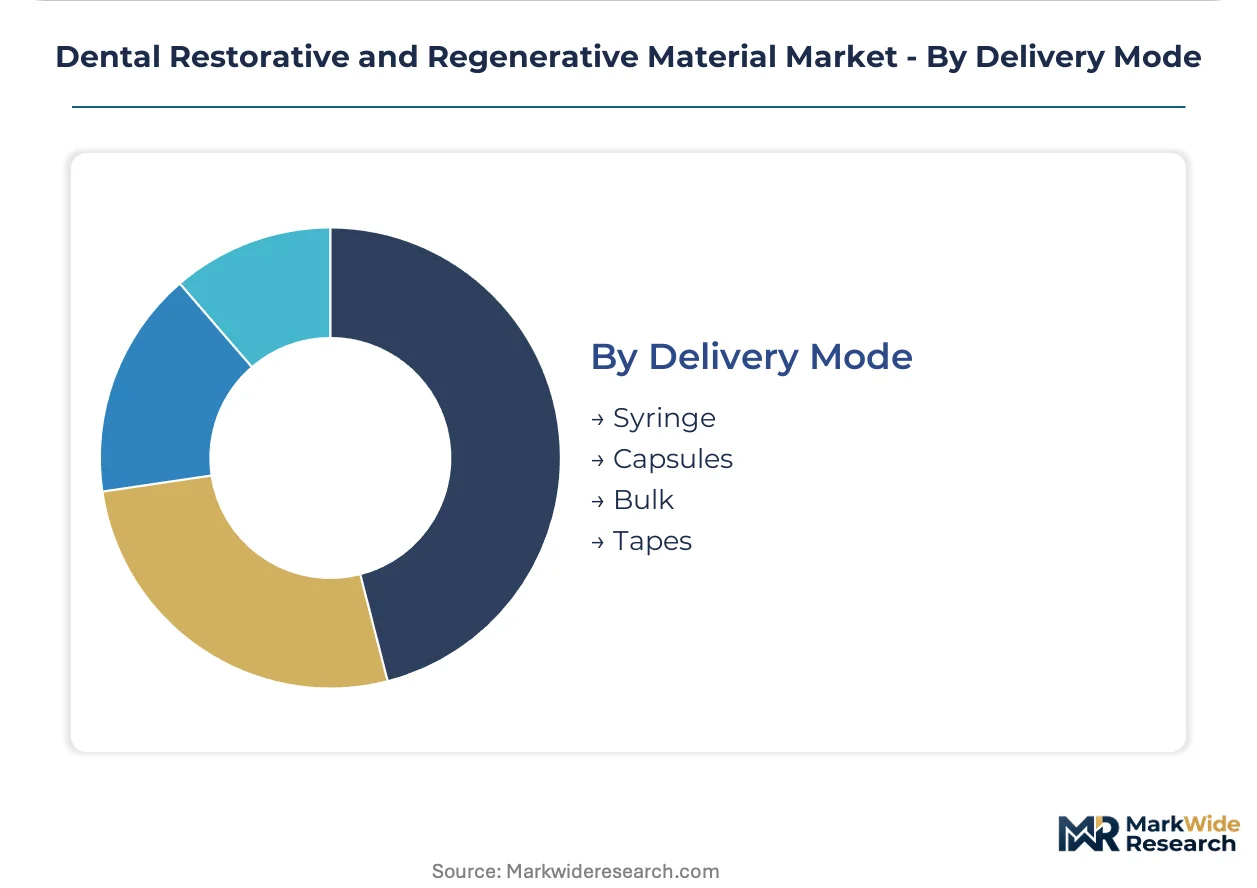
- Syringe:Luer-lock and clicker-dispensed formulations enable direct intraoral placement with controlled extrusion rates. United States high-throughput clinics favor syringe delivery for composite and sealant applications, though tip clogging and material waste at cartridge termination create operational friction.
- Capsules:Pre-dosed single-patient units with triturated amalgam or pre-mixed bioceramic eliminate proportioning error. Endodontic obturation in French and Italian specialist practices prefers capsule formats for apical control precision, with manufacturer-specific applier compatibility creating switching costs.
- Bulk:Jar and cartridge formats serve high-volume laboratory processing and impression material applications.
- Tapes:Pre-formed strips and ropes target orthodontic adhesive and temporary crown fabrication.
Syringe formats dominate clinical throughput, yet Capsules are gaining share fastest through endodontic specialty standardization and infection control protocol tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA clearance pathways for novel bioceramic formulations are compressing time-to-market for restorative innovations in the United States. Fee-for-service reimbursement structures support premium material uptake across metropolitan private practices. Demand concentrates in dental clinics and private practices expanding adoption of bioactive regenerative therapies.
United States
Private practice consolidation through dental service organizations is standardizing procurement around CAD/CAM-compatible composite systems. FDA 510(k) pathway compression shortens commercialization cycles for regenerative graft materials. California and Texas dental service organizations pilot direct manufacturer arrangements that bypass regional dealer networks entirely.
Germany
University hospital adoption of bioceramic sealers is accelerating clinical integration in endodontic specialty practices. EMA MDR post-market surveillance requirements mandate clinical follow-up data collection for permanent implantable dental materials. German milling centers face sinter-grade zirconia feedstock dependence creating input cost volatility.
Japan
Super-aging demographics are driving demand for geriatric-focused periodontal regeneration products. PMDA streamlined review pathways accelerate market access for bone substitute materials. Tokyo and Osaka metropolitan areas concentrate specialty referral patterns for endodontic procedures utilizing precise apical control materials.
India
Government health scheme coverage extension into tertiary dental procedures is opening reimbursement pathways for imported regenerative grafts. CDSCO regulatory frameworks govern premarket approval for novel restorative materials. Maharashtra and Karnataka dental infrastructure expansion is creating procurement scale for international material suppliers.
United Kingdom
Preventive dentistry programs favor glass ionomer materials for pediatric applications across National Health Service contracts. EMA medical device regulations under EU MDR impose clinical evidence requirements filtering market entrants. London and Southeast England metropolitan practices concentrate demand for premium aesthetic restoration materials.
Dental Restorative and Regenerative Material Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the dental restorative material sector. Swiss and German entities anchor premium positioning through specialized regenerative portfolios and advanced ceramic formulations. The market structure rewards integrated CAD/CAM workflow providers alongside focused bioceramic specialists. Consolidation pressures favor larger entities with established quality management infrastructure capable of satisfying heightened documentation burdens. Competitive moves center on portfolio diversification into bioactive substrates and strategic partnerships collapsing laboratory-clinic boundaries.
Among Swiss-based specialists, Institut Straumann AG and Geistlich Pharma AG exemplify the regenerative-focused archetype with concentrated bone graft portfolios. Dentsply Sirona, identifiable by its dual-name structure suggesting merged entities, represents the integrated workflow provider positioning. These three entities occupy positions reflecting distinct strategic bets: biological repair substrates, digital workflow integration, and specialized regeneration materials respectively.
| Leading Market Players |
|---|
| 3M |
| Dentsply Sirona |
| Institut Straumann AG |
| Zimmer Biomet Holdings |
| Ivoclar Vivadent AG |
| Envista Holdings Corporation |
| Henry Schein |
| Geistlich Pharma AG |
| ZimVie Inc. |
| Others |
Supply Flow & Price Mechanics
Amalgam-to-composite substitution across United States dental service organizations is simultaneously shifting procurement geography toward polymer formulation hubs and compressing margin structures for mercury-silver alloy suppliers. This material transition feeds back into supply chain configuration as bulk resin procurement displaces spot metal purchasing.
Pricing Analysis
Metropolitan United States practices command 15-25% premiums over rural clinics for identical CAD/CAM-compatible composite systems. Three-tier pricing structure across premium, standard, and economy levels tracks ISO 10993 certification tier and brand heritage. Pricing pressure stems from group purchasing organization consolidation extracting volume commitments from composite resin suppliers. Dental service organizations exhibit lowest price sensitivity while independent rural practitioners face acute cost compression.
Supply Chain Analysis
Germany and Japan anchor precision milling center equipment and sinter-grade zirconia powder production for glass-ceramic restorations. Raw material flows draw from Chinese rare earth processing for photoinitiator chemicals and Taiwanese electronics-grade filler manufacturing. Single-source vulnerability concentrates in sinter-grade zirconia feedstock where limited ceramic powder suppliers create input cost volatility. Distribution runs through regional dental dealer networks though California and Texas dental service organizations pilot direct manufacturer arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA 510(k) pathway compression for bioceramic formulations is accelerating commercialization velocity beyond historical dental material benchmarks. This regulatory inflection creates asymmetric opportunity for entities with established quality management infrastructure.
For Market Incumbents: Compound CAD/CAM workflow integration advantages through backward integration into scanner-milling unit compatibility layers. Dentsply Sirona's bundled material-library approach exemplifies this defensive posture against standalone composite suppliers. Prioritize ISO 10993 testing capacity expansion to absorb biocompatibility validation burdens filtering smaller bioceramic developers.
For New Entrants and Emerging Players: Chairside 3D printing service gaps in endodontic specialty practices offer white-space penetration where incumbents under-serve precise apical control requirements. Target Japanese metropolitan referral networks where PMDA streamlined pathways reduce regulatory friction for photopolymer resin formulations. Pursue direct manufacturer arrangements with Texas dental service organizations bypassing entrenched dealer networks.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed dental distribution platforms consolidating regional dealer networks. Five-to-ten year viability hinges on bioactive substrate portfolio depth rather than commodity resin volume. Monitor EMA MDR post-market surveillance compliance costs as inflection indicator favoring scaled quality management infrastructure over niche formulation specialists.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Expedited clearance compresses commercialization cycles for hydroxyapatite-doped bioceramics in United States markets. |
| CAD/CAM Workflow Integration | Scanner-milling unit compatibility bundles reduce chairside variability across dental service organization procurement. |
| Bioceramic Sintering Parameter Standardization | Furnace calibration consistency addresses crystallization variability plaguing glass-ceramic restoration quality. |
| Direct Manufacturer Arrangement Pilot | California and Texas dental service organizations bypass regional dealer networks entirely. |
| Reimbursement Strategy Development | Payer acceptance codes determine whether bioactive premium materials achieve routine clinical adoption. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with dental biomaterial scientists, CAD/CAM workflow engineers, GPO contracts managers, and endodontic specialty practitioners; and secondary validation through FDA 510(k) filings, EMA MDR submission databases, ISO 10993 testing protocols, and dental distributor procurement records. Bottom-up volume modeling triangulated against top-down expenditure analysis across fee-for-service and reimbursement-constrained payment environments.
Across the projection horizon, analytical frameworks segmented volume and value by material chemistry, delivery mode configuration, application specialty, and regional regulatory cluster. CAGRs derived from procedure volume elasticity models incorporating dental service organization consolidation rates and bioactive substrate adoption curves. Forecast inputs included sinter-grade zirconia powder supply constraints and PMDA review pathway efficiency differentials.
Underlying assumptions cover sustained FDA 510(k) pathway compression and stable fee-for-service reimbursement structures, with deviation risk concentrated in EMA MDR evidence threshold escalation and group purchasing organization pricing extraction intensity. Recalibration cycles align with material shifts in bioceramic clinical evidence generation and dental service organization procurement authority consolidation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Materials
Dental Zirconia Powder Market
Dental Materials
Dental Plaster Market
Dental Materials
Fluoride Materials Market
Dental Materials
Global Dental Adhesive Market
Dental Materials
Global Dental Membrane and Bone Graft Substitutes Market
Dental Materials
Dental Biomaterials Market
Dental Materials
Dental Materials for 3D Printing Market
Dental Materials
Dental Alginate Market
Dental Materials
Calcium Hydroxylapatite Fillers Market
Dental Materials
Dental Putty Market
Dental Materials
Dental Fluoride Varnish Market
Dental Materials
Global Demineralized Bone Matrix Market
Dental Materials
Teeth Whitening Market
Dental Materials
Zirconia Based Dental Ceramics Market
Dental Materials
Global Endodontic Consumables Market
Dental Materials
Fluoride-Free Toothpaste Market