
 Dental Alloys Market | 2026-2036
Dental Alloys Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Alloys Market Analysis
Prosthodontic clinics are expanding their share of high-precision crown and bridge work, pulling alloy volumes away from general dentistry channels. Dentsply Sirona leverages its integrated CAD/CAM ecosystem to control material workflows from scan to final restoration. Heraeus Holding anchors European supply through its precious metal refining and alloy formulation capabilities. Argen Corporation specializes in digital alloy dispensing systems that reduce waste for high-volume dental laboratories.
Dental alloys are metallic formulations—typically gold-platinum-palladium systems, cobalt-chromium compositions, or nickel-titanium shape-memory variants—engineered to meet ISO 22674 standards for biocompatibility, castability, and occlusal wear resistance, serving primarily as structural substrates for permanent and removable dental prostheses. Noble alloys retain premium positioning in anterior aesthetic cases where tarnish resistance and tissue compatibility justify higher material costs, while base metal alloys capture volume in posterior frameworks where mechanical strength outweighs corrosion concerns. Within applications, implant-supported superstructures represent the fastest-expanding demand pool as titanium-zirconium alloys displace pure titanium in narrow-diameter fixtures.
The FDA governs alloy biocompatibility through 510(k) substantial equivalence reviews and ISO 10993 cytotoxicity testing requirements, while the EU Medical Device Regulation mandates CE marking with enhanced clinical evidence for implantable alloy devices. Japan's PMDA maintains distinct pharmacological metal classification standards that create separate approval pathways for precious versus non-precious alloy systems. Stakeholders must monitor evolving nickel restriction thresholds in European dermatological safety protocols, as these standards directly reshape alloy formulation decisions across export-oriented manufacturers.
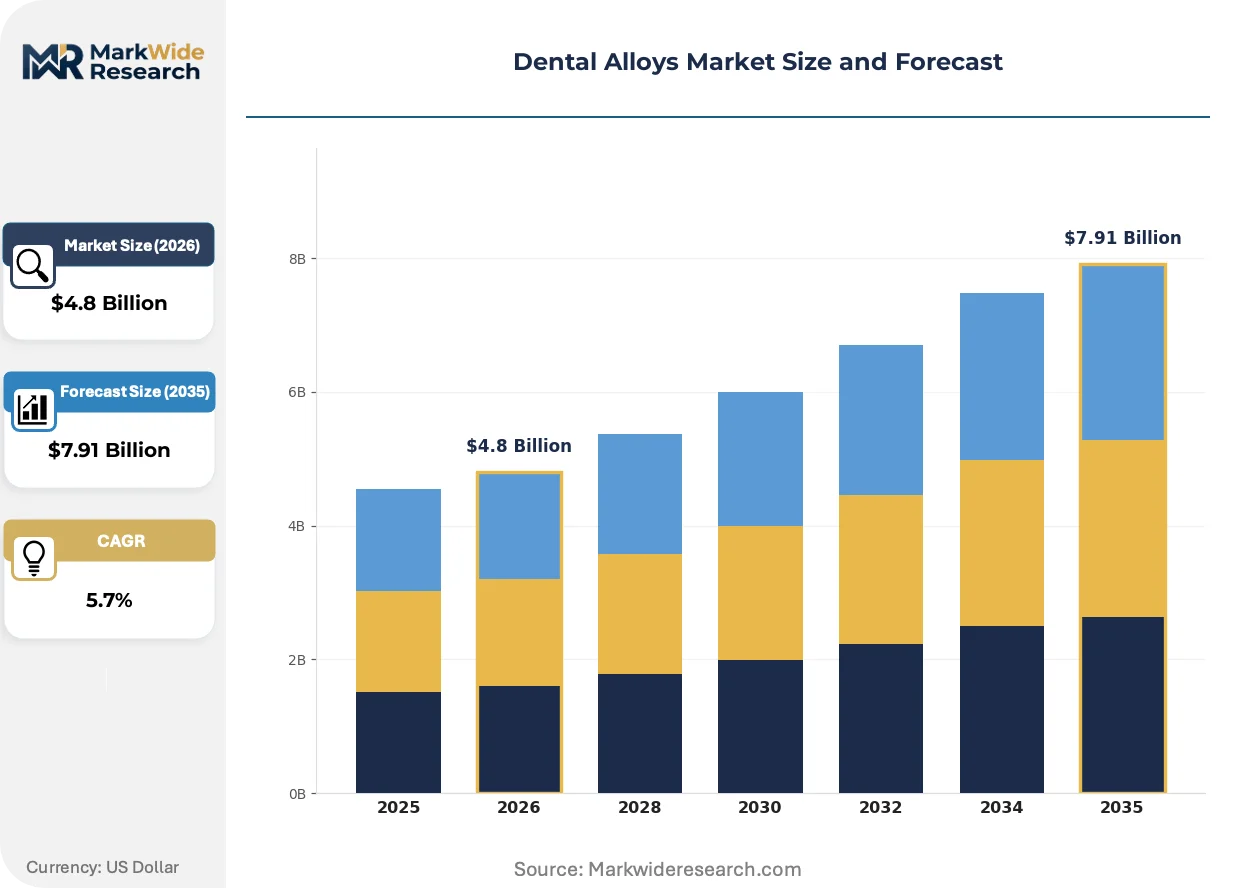
Market Dynamics
Digital milling workflows are compressing turnaround times for crown and bridge frameworks, forcing alloy suppliers to synchronize just-in-time dispensing with laboratory production schedules rather than batch-based casting models.
Growth Catalysts
- CAD/CAM integration:Chairside scanning systems in prosthodontic clinics are pulling alloy volumes toward digitally compatible compositions that machine predictably at high spindle speeds.
- Japan's PMDA pharmacological metal pathways:Distinct approval tracks for precious versus non-precious alloys are accelerating product registration for manufacturers with existing precious metal refining infrastructure.
- Narrow-diameter implant demand:Titanium-zirconium alloys are capturing share in posterior superstructures where mechanical strength requirements exceed pure titanium capabilities.
Market Restraints
- Palladium price volatility:Noble alloy formulations remain exposed to precious metal commodity swings that compress laboratory margins on fixed-fee restoration contracts.
- European nickel restriction thresholds:ECHA dermatological safety protocols are forcing reformulation of cobalt-chromium base metal systems for export-oriented manufacturers.
- ISO 22674 certification timelines:Biocompatibility and castability testing requirements extend new alloy development cycles beyond typical dental product refresh windows.
Strategic Opportunities
- Same-day milling laboratories:Metropolitan hospital networks in the United States require consistent alloy supply chains for chairside production capabilities that bypass traditional casting workflows.
- EU Medical Device Regulation clinical evidence pathways:Enhanced documentation requirements for implantable alloy devices create differentiation potential for manufacturers with existing biocompatibility datasets.
- Additive manufacturing convergence:Selective laser melting of cobalt-chromium powders is opening direct metal printing channels that bypass conventional waxing and casting steps.
Industry Challenges
- Digital workflow integration:Legacy casting technicians require retraining in CAD design and milling parameter optimization to operate hybrid production environments.
- Alloy dispensing precision:High-volume dental laboratories face waste reduction pressures that demand gram-level accuracy in precious metal allocation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Alloys Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Noble Alloys, Base Metal Alloys, Stainless Steel, Dental Ceramics Application: Crowns, Bridges, Implants, Dentures End User: Dental Clinics, Hospitals, Research Institutes, Laboratories Delivery Mode: Direct Sales, Distributors, Online Channels, Wholesalers |
| Companies Covered | Dentsply Sirona, Ivoclar Vivadent, Henry Schein, Straumann, Argen Corporation, Heraeus Holding, Kerr Corporation, Nobel Biocare, Kulzer GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Alloys Market Emerging Trajectories
Material formulation and regulatory classification systems are diverging across major economies, creating parallel development tracks that favor manufacturers with multi-jurisdictional compliance capabilities.
Digital alloy dispensing systems are automating material allocation workflows in high-throughput dental laboratories. Prosthodontic clinics serving metropolitan hospital networks are adopting these systems fastest to minimize precious metal waste on same-day milling schedules. The technology is automating inventory reconciliation processes that previously required manual weighing and logging protocols.
REACH nickel restriction thresholds are tightening dermatological safety standards for cobalt-chromium dental alloys across European export markets. Manufacturers serving Germany and neighboring economies must reformulate base metal compositions or risk market exclusion. Precious alloy systems with palladium-gold matrices are capturing displaced volume in anterior frameworks where tissue compatibility justifies material cost premiums.
Buyer concentration is consolidating procurement leverage among multi-site dental laboratory networks. Independent casting operations serving single practitioners are losing alloy volume to centralized milling centers with captive supply agreements. This concentration is most visible in United States metropolitan corridors where hospital-affiliated prosthodontic departments dominate crown and bridge restoration referrals.
Dental Alloys Market Segmentation
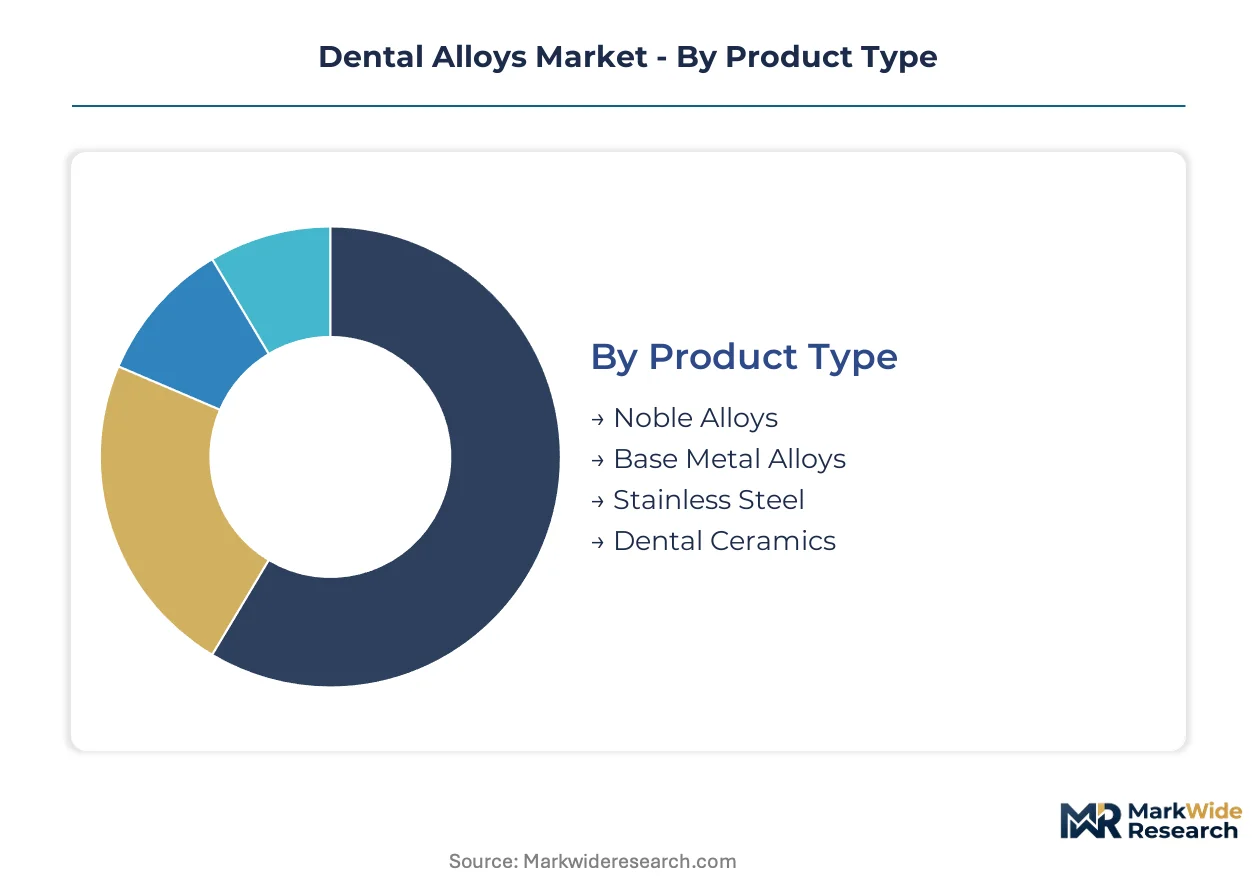
Dental alloy procurement patterns diverge sharply between precision-matched precious metal systems and commodity base metal formulations. Segmentation reveals how digital workflow adoption is redistributing volumes across product tiers and channel structures.
Product Type:
Integration depth separates noble alloys embedded in premium aesthetic restorations from standalone base metal frameworks serving posterior mechanical demands.
- Noble Alloys:Gold-platinum-palladium formulations deliver ISO 22674-compliant biocompatibility with superior tarnish resistance. Demand concentrates in German and Japanese prosthodontic clinics where anterior aesthetics justify material premiums on fixed-fee contracts.
- Base Metal Alloys:Cobalt-chromium compositions provide mechanical strength for posterior frameworks at lower unit economics. European laboratories are reformulating these systems to meet ECHA nickel restriction thresholds without sacrificing castability.
- Stainless Steel:Austenitic grades serve temporary crown applications and orthodontic appliances where corrosion resistance requirements are moderate.
- Dental Ceramics:Zirconia-based systems function as ceramic-alloy hybrids in layered restorations requiring both structural substrates and aesthetic veneering.
Volume placements concentrate in base metal alloys; the faster expansion belongs to noble alloys.
Application:
Clinical complexity tiers separate single-unit crown restorations from multi-unit implant superstructures requiring alloy-to-bone integration.
- Crowns:Single-tooth restorations represent the highest procedure frequency across general dentistry channels. Same-day milling capabilities in United States metropolitan networks are compressing turnaround times for digitally compatible alloy compositions.
- Implants:Titanium-zirconium superstructures are displacing pure titanium in narrow-diameter fixtures where mechanical load-bearing exceeds pure metal capabilities. FDA 510(k) pathways for novel alloy compositions are accelerating material innovation cycles for osseointegrated devices.
- Bridges:Multi-unit frameworks require homogeneous alloy properties across span lengths to prevent flexural fatigue.
- Dentures:Removable partial frameworks utilize cobalt-chromium castings for clasp retention and tissue-bearing bases.
Procedure frequency peaks with crowns; implant-supported restorations are climbing the fastest.
End User:
Capital intensity separates hospital-affiliated prosthodontic departments from independent laboratory operations with constrained equipment footprints.
- Dental Clinics:Chairside CAD/CAM systems are pulling alloy volumes toward digitally compatible compositions. Prosthodontic specialists in Germany and Japan are expanding their share of precision crown and bridge work previously routed to external laboratories.
- Laboratories:High-throughput milling centers serving metropolitan hospital networks require consistent alloy supply chains for just-in-time production schedules. Digital dispensing systems are automating gram-level precious metal allocation to minimize waste.
- Hospitals:Academic medical centers generate demand for research-grade alloy specimens with documented biocompatibility datasets.
- Research Institutes:Materials science programs drive small-volume demand for experimental alloy formulations prior to regulatory submission.
Procurement scale concentrates in laboratories; the steepest expansion trajectory belongs to dental clinics.
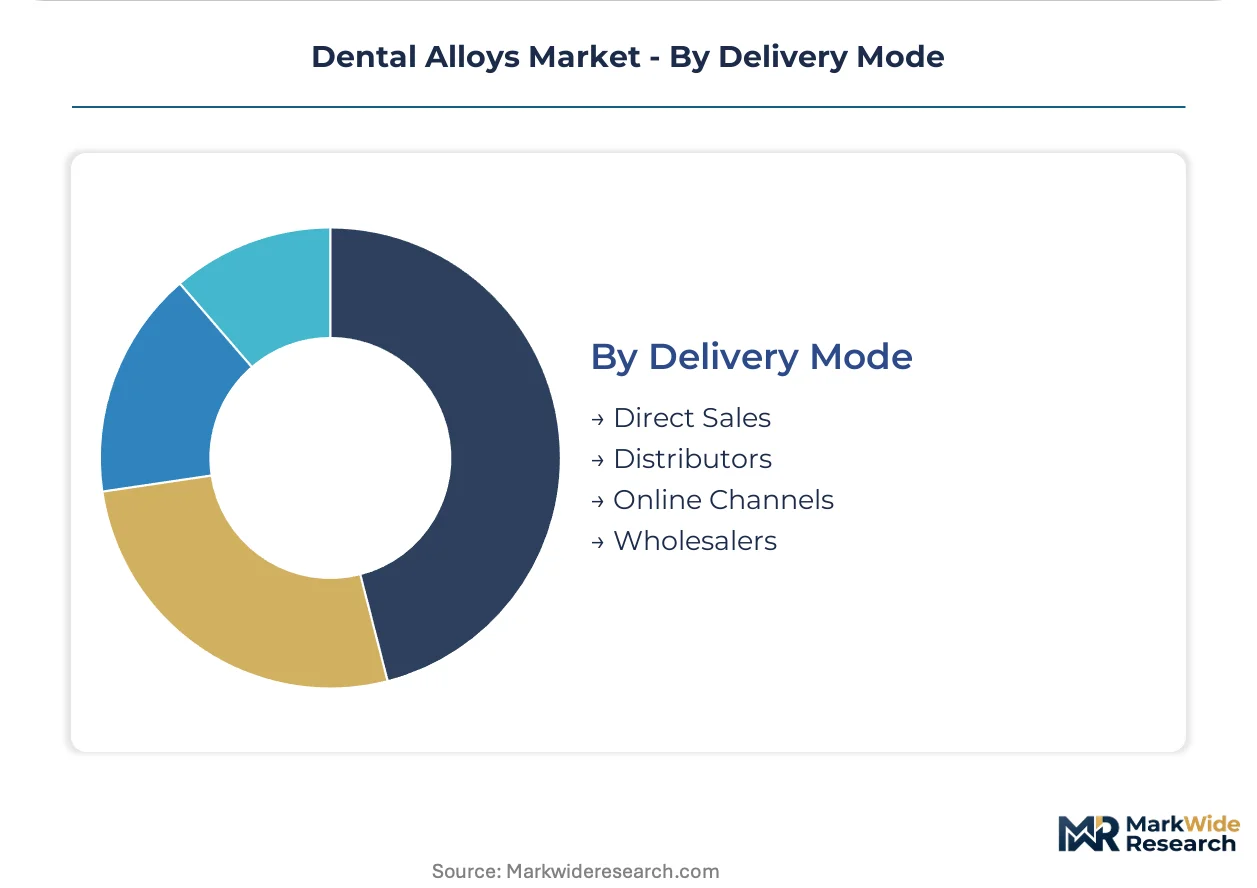
Delivery Mode:
Channel control separates direct manufacturer relationships from fragmented distributor networks with inventory carrying costs.
- Distributors:Regional dental supply networks maintain alloy inventories for small-to-mid laboratories lacking capital for direct manufacturer contracts. These intermediaries absorb precious metal price volatility through hedged inventory positions.
- Direct Sales:Integrated CAD/CAM ecosystem providers control material workflows from scan to final restoration through captive alloy supply agreements. Dentsply Sirona leverages this channel to synchronize dispensing with milling parameter optimization.
- Online Channels:E-commerce platforms serve independent practitioners with standardized alloy compositions and predictable shipping schedules.
- Wholesalers:Bulk procurement aggregators supply multi-site laboratory networks with volume-discounted base metal formulations.
Transaction volume flows through distributors; direct sales channels are gaining share fastest among high-throughput operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free economic zones in Shenzhen and Dubai concentrate precious metal refining capacity for dental alloy manufacturing. Tax incentives in these zones reduce import duties on palladium and gold feedstocks. Manufacturers locate formulation facilities adjacent to these zones to minimize working capital tied to volatile commodity inventories.
United States
Metropolitan hospital networks in New York, Los Angeles, and Chicago drive demand for same-day milling capabilities. The FDA's 510(k) clearance pathways accelerate material innovation cycles for novel alloy compositions. Precision dental laboratories in these corridors require consistent supply chains for digitally compatible noble and base metal formulations.
Germany
Prosthodontic clinics in Munich and Berlin expand digitally milled alloy frameworks for crown and bridge restorations. ECHA dermatological safety protocols force reformulation of cobalt-chromium systems to meet tightening nickel restriction thresholds. Bavarian manufacturing clusters specialize in precious metal refining for export-oriented alloy production.
Japan
Specialized prosthodontic departments in Tokyo and Osaka pull alloy volumes toward high-precision aesthetic restorations. The PMDA maintains distinct pharmacological metal classification standards that create separate approval pathways for precious versus non-precious systems. Nagoya-based suppliers leverage existing precious metal infrastructure to accelerate product registration timelines.
China
Domestic dental laboratory networks in Shanghai and Guangzhou adopt digital dispensing systems to reduce precious metal waste. The NMPA governs alloy biocompatibility through cytotoxicity testing aligned with ISO 10993 standards. Yangtze River Delta manufacturing zones concentrate cobalt-chromium powder production for regional milling centers.
Dental Alloys Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated CAD/CAM ecosystem providers controlling material workflows from scan to final restoration. The vendor base organizes around three strategic archetypes: precious metal refiners with alloy formulation capabilities, digital equipment manufacturers with captive material supply agreements, and specialized alloy dispensers serving high-volume laboratory networks. Consolidation pressures favor multi-jurisdictional compliance capabilities as material formulation standards diverge across FDA, EMA, and PMDA jurisdictions. Dominant competitive moves include backward integration into precious metal refining and strategic partnerships with chairside CAD/CAM system providers.
Among integrated equipment-and-material providers, Dentsply Sirona exemplifies the ecosystem-control archetype through its synchronized dispensing and milling parameter optimization. Heraeus Holding anchors the European precious metal refining tier with its alloy formulation capabilities serving German prosthodontic channels. Argen Corporation occupies a position within the specialized dispensing systems segment, representing automation-focused suppliers targeting waste reduction in high-throughput United States laboratories.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Ivoclar Vivadent |
| Henry Schein |
| Straumann |
| Argen Corporation |
| Heraeus Holding |
| Kerr Corporation |
| Nobel Biocare |
| Kulzer GmbH |
| Others |
Supply Flow & Price Mechanics
Noble-to-base metal bifurcation splits procurement economics across German prosthodontic clinics and high-volume United States laboratories, with ISO 22674 certification tiers commanding premium positioning while commodity cobalt-chromium formulations compete on unit cost. Palladium price volatility feeds directly into laboratory margin structures, compressing returns on fixed-fee restoration contracts when precious metal feedstock costs spike.
Pricing Analysis
Spot inventory discounts reward laboratories with flexible procurement schedules, while premium markups attach to just-in-time dispensing systems synchronized with same-day milling workflows. Three-tier pricing structure across premium noble alloys, standard base metal formulations, and economy stainless steel grades reflects ISO certification intensity and tarnish resistance specifications. Cost compression in base metal tiers is intensifying because ECHA nickel restriction thresholds force reformulation investments. Independent casting operations serving single practitioners exhibit highest price sensitivity; hospital-affiliated prosthodontic departments absorb premiums for biocompatibility documentation.
Supply Chain Analysis
ISO 10993 cytotoxicity testing and FDA 510(k) clearance gates filter supplier eligibility, concentrating qualified manufacturing in Germany, Japan, and United States precision metalworking clusters. Palladium and gold feedstocks draw from Swiss precious metal refiners and South African mining operations, while cobalt-chromium powders source from Yangtze River Delta chemical processing zones. Single-source vulnerability concentrates in titanium-zirconium implant alloy supply where narrow-diameter fixture demand outpaces qualified producer expansion. Distribution runs through regional dental supply networks for small laboratories; direct manufacturer relationships dominate high-throughput milling centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into precious metal refining and captive alloy formulation capabilities defines competitive positioning, with upstream control over palladium and gold feedstocks insulating margin structures from commodity volatility.
For Market Incumbents: Anchor market position through multi-jurisdictional compliance capabilities spanning FDA 510(k), EU MDR, and Japan PMDA pathways as regulatory divergence accelerates. Invest in digital dispensing automation to defend against waste-reduction pressures from high-volume laboratory networks. Threats from additive manufacturing convergence demand selective selective laser melting partnerships to preserve relevance in direct metal printing channels. For New Entrants and Emerging Players: Begin with additive manufacturing alloy powder formulations for cobalt-chromium selective laser melting applications, where incumbent casting expertise transfers poorly to layer-wise deposition parameters. Target United States metropolitan hospital network laboratories with titanium-zirconium narrow-diameter implant alloys, the fastest-climbing demand pool with underserved precision requirements. Go-to-market leverage rests on gram-level dispensing accuracy guarantees that reduce precious metal waste below incumbent system benchmarks. For Investors and Strategic Acquirers: Re-rating potential sits with digital workflow-integrated alloy suppliers given CAD/CAM ecosystem consolidation and chairside milling expansion. Long-term viability over the next decade hinges on multi-jurisdictional regulatory datasets that accelerate product registration timelines. Signal to monitor: PMDA pharmacological metal pathway approval velocity for precious versus non-precious classifications, which indicates regulatory arbitrage opportunity windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precious Metal Refining | Captive palladium and gold feedstock control insulates laboratory margins from commodity price swings. |
| Digital Dispensing System Deployment | Gram-level automation reduces waste for high-throughput United States milling centers operating same-day schedules. |
| Multi-Jurisdictional Regulatory Dataset Buildout | Biocompatibility documentation spanning FDA, EMA, and PMDA accelerates novel alloy registration cycles. |
| Selective Laser Melting Powder Qualification | Cobalt-chromium additive manufacturing formulations bypass conventional waxing and casting workflow steps. |
| Hospital Network Direct Supply Agreements | Captive relationships with metropolitan prosthodontic departments secure volume commitments bypassing distributor intermediaries. |
Methodological Framework
Independent corroboration across prosthodontic clinic operators, dental laboratory procurement managers, and precious metal refining executives underwrites the qualitative findings on alloy workflow transitions. Primary interviews with CAD/CAM system engineers, regulatory affairs specialists at alloy manufacturers, and hospital purchasing committee representatives combined with secondary validation from FDA 510(k) clearance databases, EU MDR technical documentation filings, and Japan PMDA pharmacological metal classification registers. Bottom-up procedure volume estimates and top-down precious metal consumption data triangulate market sizing across the analysis window.
Comparable-period anchoring linked historical crown and bridge restoration frequencies to projected digital milling adoption curves across the projection horizon. Segmentation modeling incorporated product type tiers, application complexity levels, end-user capital intensity, and delivery mode channel structures. CAGRs derived from procedure volume elasticity to chairside CAD/CAM penetration rates and alloy composition shift assumptions for titanium-zirconium implant superstructures. Forecast inputs included palladium price trajectory scenarios and REACH nickel restriction threshold enforcement timelines.
Underlying measurement precision varies by segment; noble alloy procurement volumes carry tighter precision than experimental additive manufacturing powder categories given established distributor reporting channels. Forecasts reflect assumptions on digital workflow adoption velocity and regulatory approval pathway efficiency that material changes in FDA 510(k) review timelines or ECHA dermatological safety protocol revisions would invalidate. A model refresh is warranted upon material change in palladium commodity price volatility or additive manufacturing equipment cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Materials
Teeth Whitening Market
Dental Materials
Dental Biomaterials Market
Dental Materials
Dental Amalgam Market
Dental Materials
Fluoride-Free Toothpaste Market
Dental Materials
Zirconia Based Dental Ceramics Market
Dental Materials
Dental Zirconia Powder Market
Dental Materials
Toothpaste Market
Dental Materials
Dental Bonding Agent Market
Dental Materials
Dental Alginate Market
Dental Materials
Australia and New Zealand Dental Biomaterials Market
Dental Materials
Global Demineralized Bone Matrix Market
Dental Materials
Global Dental Zirconia Block Market
Dental Materials
Charcoal Teeth Whitening Powder Market
Dental Materials
Dental Polymerization Lamps Market
Dental Materials
Global Zirconia Based Dental Materials Market
Dental Materials
Dental Composites Market