
 Africa Tissue Paper Market | 2026-2036
Africa Tissue Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Tissue Paper Market Intelligence
A capital-intensity divergence between integrated pulp producers and converter-reliant competitors is reorganizing competitive tiers across the continent. Sappi Southern Africa Limited leverages its captive pulp supply and integrated mills to sustain cost advantages in virgin-grade output. Kimberly-Clark Worldwide, Inc. anchors premium positioning through branded retail distribution in urban centers. Twinsaver Group competes on scale in South Africa's wholesale channel, while Nova Papers (Pty) Ltd. specializes in regional converter supply to mid-tier retailers.
Africa tissue paper comprises disposable cellulose-based sheets manufactured through wet-laid forming, creping, and embossing processes, typically ranging from 15 to 30 grams per square meter, designed for hygiene absorption and single-use sanitation. Toilet tissue and paper towels lead volume consumption across household and food service end users, with facial tissue capturing margin concentration in hospitality and healthcare channels. Recycled paper and bamboo materials are gaining structural share as virgin pulp cost volatility and sustainability procurement criteria reshape sourcing decisions across supermarkets and wholesale distribution.
South Africa's Department of Forestry, Fisheries and the Environment enforces waste management and recycling standards that elevate post-consumer content requirements, while Nigeria's Standards Organisation of Nigeria sets hygiene product specifications affecting import access and local manufacturing compliance. Kenya's Bureau of Standards certification mandates for tissue products shape quality thresholds that influence both domestic production scale and cross-border trade flows. Stakeholders must monitor evolving national standards alignment and pulp input cost trajectories to calibrate capacity investments and material sourcing strategies.
Market Dynamics
Integrated pulp-to-tissue production chains are compressing cost structures across Africa, forcing converter-reliant competitors to absorb margin erosion or exit virgin-grade segments entirely. This supply-side consolidation is redrawing competitive tiers between captive pulp producers and import-dependent manufacturers.
Growth Catalysts
- Urban hospitality expansion:Hotel chains and food service operators across Nigeria's Lagos-Abuja corridor are pulling premium-grade tissue volumes through centralized procurement contracts.
- Kenya's BIS-aligned standards:Bureau of Standards certification mandates are elevating quality thresholds that favor scaled domestic producers over informal imports.
- Bamboo fiber substitution:Non-wood pulp alternatives are reducing virgin fiber dependency as sustainability procurement criteria harden across supermarket distribution networks.
Market Restraints
- Recycled fiber cost volatility:Post-consumer waste collection infrastructure gaps in secondary cities elevate input price uncertainty for converter-dependent manufacturers.
- South African pulp concentration:Sappi Southern Africa's captive supply dominance creates bottleneck risk for competitors lacking backward integration into pulp production.
- Kenya's cross-border compliance friction:Bureau of Standards certification requirements for imported finished goods extend lead times and elevate working capital needs for regional traders.
Strategic Opportunities
- Nigeria's underpenetrated secondary cities:Ibadan, Kano, and Port Harcourt present whitespace for branded distribution networks currently concentrated in Lagos-Abuja.
- South Africa's recycling mandate tailwinds:Department of Forestry, Fisheries and the Environment post-consumer content requirements create structural demand for recycled-grade production capacity.
- E-commerce B2B channels:Wholesale procurement platforms are disintermediating traditional distributor layers for mid-tier hospitality and healthcare buyers.
Industry Challenges
- Skilled creping technician scarcity:Wet-laid forming and embossing process expertise concentrates in South Africa and Kenya, constraining quality consistency at greenfield mills elsewhere.
- Capex intensity for integrated capacity:Greenfield pulp-to-tissue lines require substantial capital deployment that exceeds regional banking sector project finance appetite.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Tissue Paper Market |
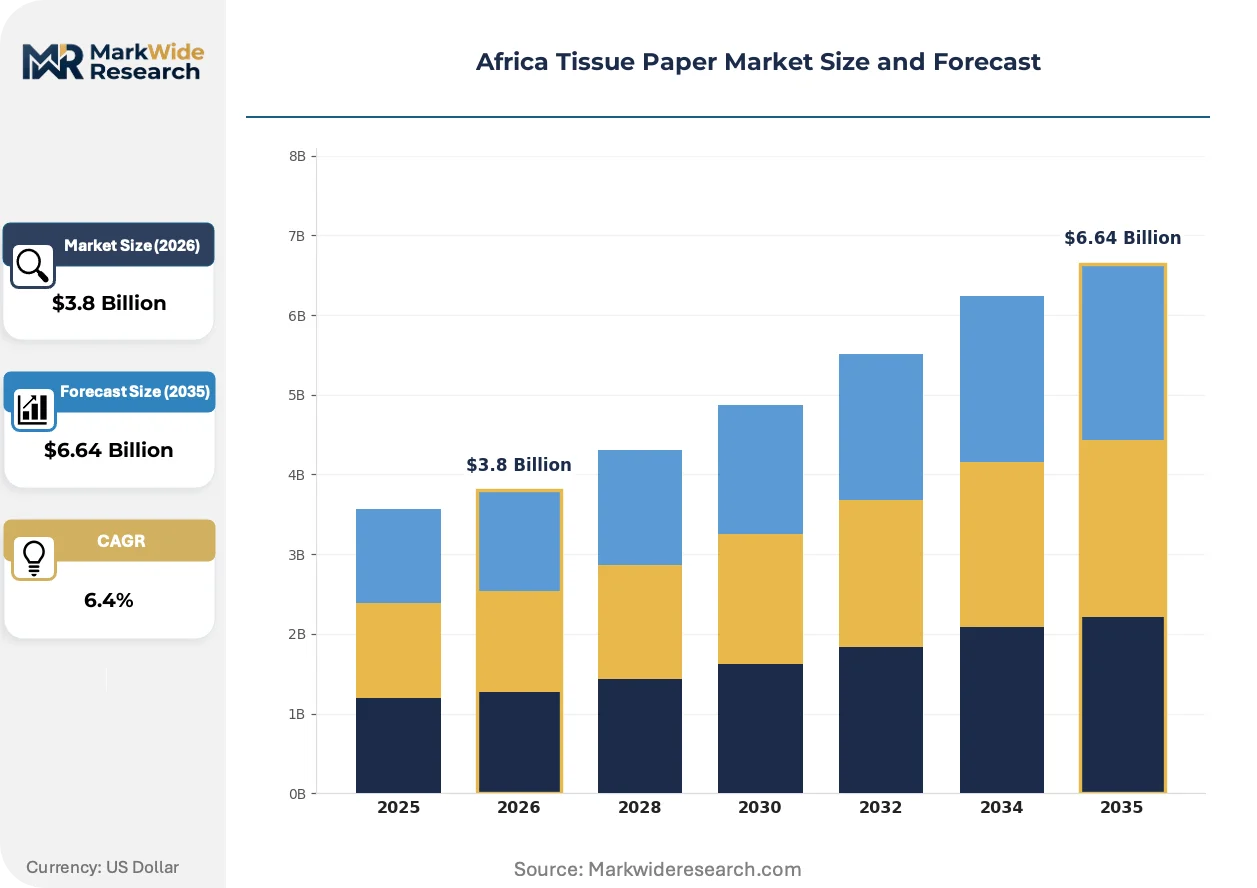
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Facial Tissue, Toilet Tissue, Paper Towels, Napkins End User: Household, Hospitality, Healthcare, Food Service Material: Recycled Paper, Virgin Pulp, Bamboo, Specialty Paper Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Wholesale |
| Companies Covered | Sappi Southern Africa Limited, Universal Paper & Plastics, Kimberly-Clark Worldwide, Inc., Georgia-Pacific, Must Paper Industries, Procter & Gamble Company, Nova Papers (Pty) Ltd., Hengan International Group Co Ltd, Twinsaver Group, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Tissue Paper Market Strategic Shifts & Innovations
Bamboo pulp processing technologies and recycled fiber de-inking advances are converging with tightening environmental procurement standards across African retail and hospitality channels. These forces are compressing the viability window for virgin-grade import strategies while elevating localized circular production models.
Bamboo-based tissue formulations are displacing virgin hardwood pulp in premium product lines as Kenyan and Nigerian supermarket chains adopt sustainability scorecards. Hospitality procurement teams in Nairobi and Lagos are accelerating volume commitments to bamboo-grade suppliers. This material shift is displacing South African virgin pulp imports in East African premium segments and compressing landed-cost advantages previously held by integrated Southern African producers.
South Africa's Department of Forestry, Fisheries and the Environment waste management standards are mandating elevated post-consumer recycled content thresholds across tissue product categories. Local manufacturers are reconfiguring fiber sourcing networks to secure compliant waste paper streams. Converter-reliant competitors without captive recycling infrastructure face margin compression as compliance costs concentrate in Johannesburg-Pretoria manufacturing zones.
Centralized procurement platforms serving hospitality chains are consolidating buyer power and compressing supplier rosters across Nigeria and Kenya. Food service operators are shifting from fragmented distributor relationships to direct mill contracts with volume guarantees. This channel consolidation is most visible in Lagos metropolitan food service procurement, where three-tier pricing stratification across premium, standard, and economy grades is hardening.
Africa Tissue Paper Market Segmentation
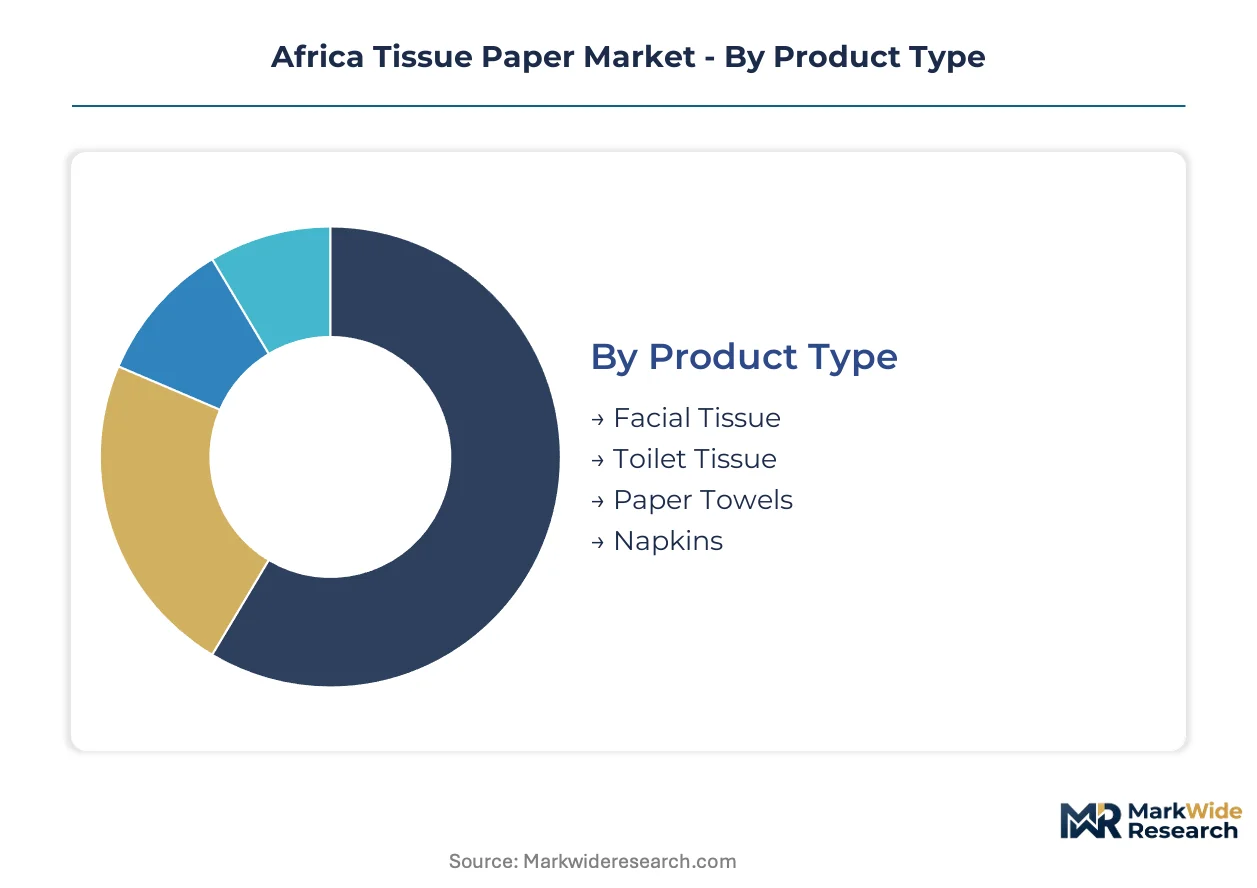
Tissue paper demand fragments across hygiene grades, procurement channels, and fiber inputs that respond differently to Kenya's BIS certification, South Africa's recycling mandates, and Nigeria's import compliance thresholds. Manufacturers calibrate capacity and sourcing strategies against these divergent segment economics.
Product Type:
Kenya's Bureau of Standards and South Africa's Department of Forestry, Fisheries and the Environment impose distinct absorbency and fiber-content specifications across hygiene grades that reshape competitive positioning.
- Toilet Tissue:Virgin and recycled fiber formulations range from 15-22 gsm, with embossed surface patterns for absorbency. Lagos-Abuja corridor households and hospitality chains pull volume through centralized contracts, though Kenya's BIS certification elevates quality thresholds that favor scaled domestic producers over informal imports.
- Paper Towels:Higher-basis-weight sheets at 20-30 gsm with enhanced wet strength for food service and healthcare sanitation. Nairobi metropolitan food service operators are consolidating procurement onto direct mill contracts, compressing distributor margins and hardening three-tier pricing across premium, standard, and economy levels.
- Facial Tissue:Softwood pulp blends with lotion additives for premium hospitality and healthcare channels in Johannesburg-Pretoria and Lagos.
- Napkins:Lower gsm disposable formats for quick-service food outlets across Nigeria's secondary cities.
Toilet tissue handles the majority of throughput; paper towels are expanding most quickly on share as food service procurement centralizes.
End User:
Procurement scale and compliance intensity separate volume buyers from fragmented retail demand across the continent's urban corridors.
- Household:Supermarket and convenience store retail across Lagos, Nairobi, and Johannesburg metropolitan zones. South Africa's recycling mandates are elevating post-consumer content requirements that reshape product availability on shelf.
- Hospitality:Hotel chains and food service operators in Nigeria's Lagos-Abuja corridor pull premium-grade volumes through centralized procurement with volume guarantees.
- Food Service:Quick-service restaurants and catering operations in Nairobi and Lagos metropolitan areas.
- Healthcare:Hospitals and clinics with infection-control specifications in South Africa's urban centers.
Household absorbs the largest volume base; hospitality is climbing the fastest as branded chain expansion accelerates.
Material:
Fiber input costs and sustainability procurement criteria are restructuring sourcing economics across supermarket distribution networks.
- Virgin Pulp:Hardwood and softwood kraft pulp from integrated Southern African mills. Sappi Southern Africa's captive supply dominance creates bottleneck risk for competitors lacking backward integration into pulp production.
- Recycled Paper:Post-consumer waste streams with de-inking processing for tissue-grade fiber. South Africa's Department of Forestry, Fisheries and the Environment waste management standards mandate elevated content thresholds that reconfigure fiber sourcing networks.
- Bamboo:Non-wood pulp alternatives reducing virgin fiber dependency. Kenyan and Nigerian supermarket chains are adopting sustainability scorecards that accelerate volume commitments to bamboo-grade suppliers.
- Specialty Paper:Custom formulations for medical and premium cosmetic applications in Johannesburg-Pretoria manufacturing zones.
Virgin pulp retains the dominant share position; bamboo is gaining share fastest as East African premium segments displace South African imports.
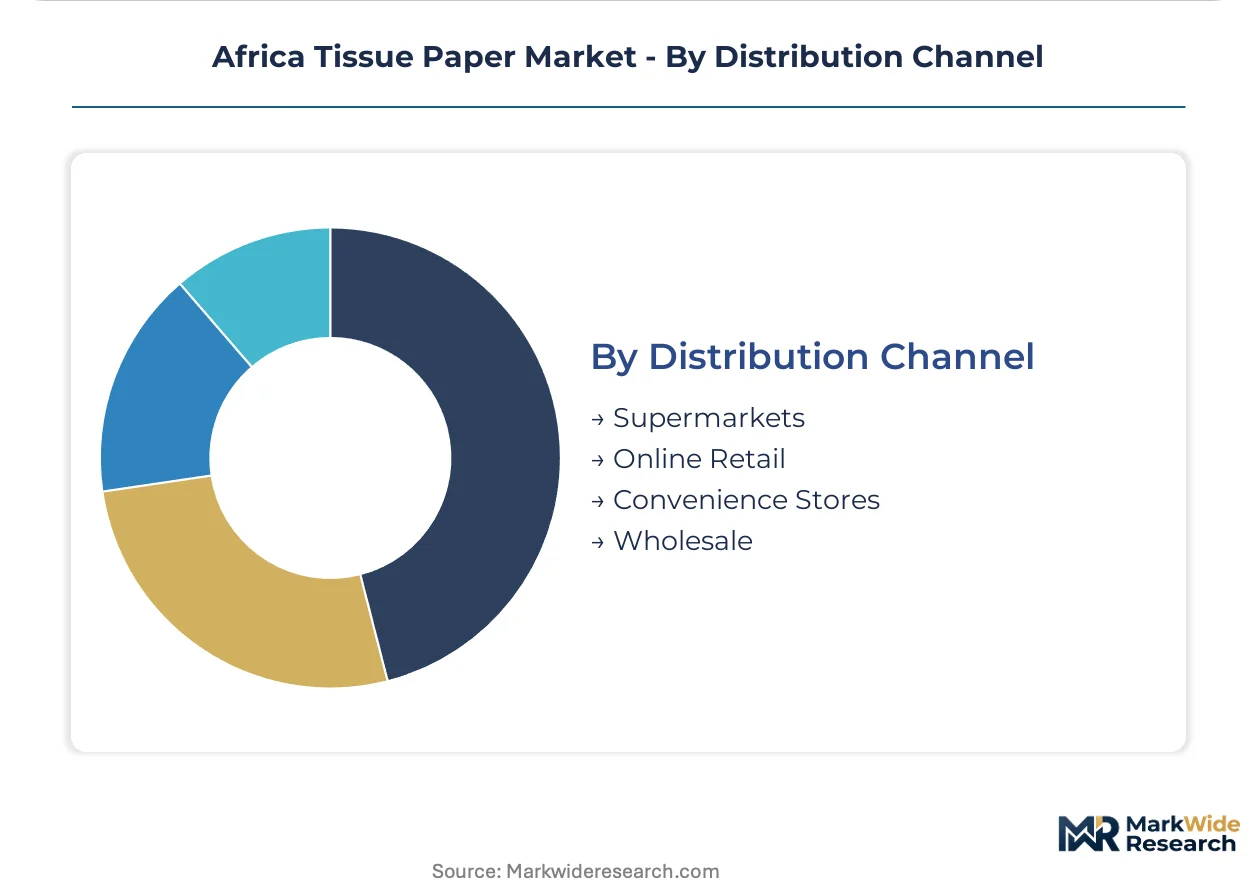
Distribution Channel:
Channel consolidation and platform disintermediation are redrawing access economics for mid-tier buyers across Nigeria and Kenya.
- Supermarkets:Branded retail distribution in urban centers with sustainability scorecards shaping supplier rosters. Kenya's BIS certification requirements extend lead times for imported finished goods, elevating working capital needs.
- Wholesale:Bulk supply to hospitality and healthcare institutional buyers. Food service operators are shifting from fragmented distributor relationships to direct mill contracts with volume guarantees.
- Online Retail:E-commerce B2B platforms disintermediating traditional distributor layers for mid-tier hospitality and healthcare buyers in Lagos and Nairobi.
- Convenience Stores:Small-format retail for household emergency purchases in Nigeria's underpenetrated secondary cities including Ibadan, Kano, and Port Harcourt.
Supermarkets move the highest absolute volumes; online retail shows the steepest expansion trajectory as procurement platforms consolidate buyer power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence across East and West Africa is compressing as integrated pulp capacity expands in Southern Africa, reshaping intra-regional trade flows and redirecting procurement patterns toward localized supply bases.
South Africa
Sappi Southern Africa's captive pulp mills anchor virgin-grade tissue output for export across the continent. The Department of Forestry, Fisheries and the Environment enforces post-consumer recycled content mandates that elevate compliance costs for converter-reliant competitors. Johannesburg-Pretoria manufacturing zones concentrate de-inking infrastructure and skilled creping technician pools.
Nigeria
Lagos-Abuja corridor hospitality chains pull premium tissue volumes through centralized procurement contracts with volume guarantees. The Standards Organisation of Nigeria sets hygiene product specifications affecting import access and local manufacturing compliance. Ibadan, Kano, and Port Harcourt present distribution whitespace as branded networks remain underpenetrated in secondary cities.
Kenya
Nairobi metropolitan supermarkets adopt sustainability scorecards accelerating bamboo-grade supplier commitments. The Bureau of Standards certification mandates elevate quality thresholds that favor scaled domestic producers over informal imports. Mombasa port logistics and cross-border compliance friction extend lead times for regional traders sourcing finished goods.
Ghana
Accra-Tema urban hospitality expansion drives food service tissue consumption through quick-service restaurant chains. The Ghana Standards Authority implements product safety specifications for hygiene goods affecting import clearance timelines. Kumasi and Sekondi-Takoradi emerging manufacturing zones attract converter investment seeking West African market access.
Africa Tissue Paper Market Key Industry Players
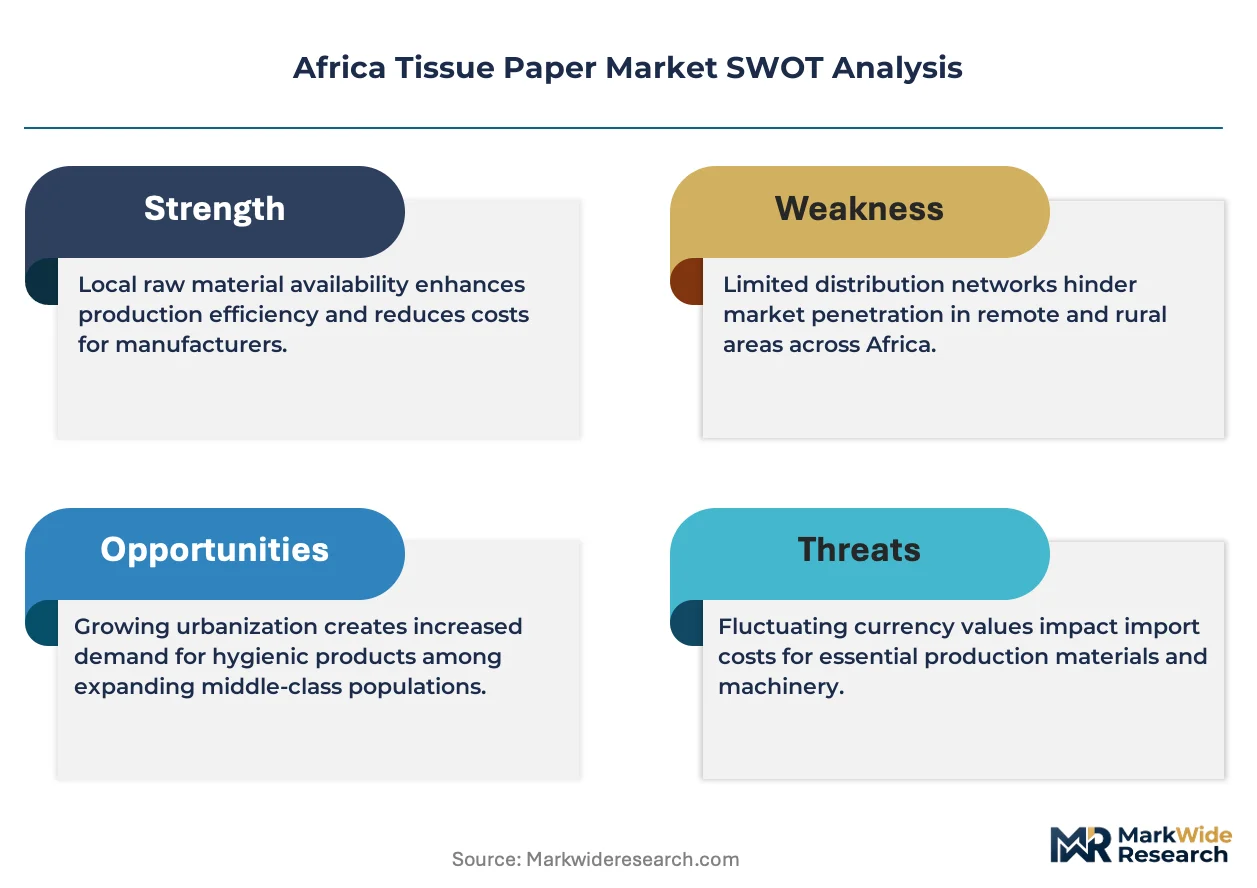
Concentration sits with integrated pulp-to-tissue producers wielding captive fiber supply and cost structures that converter-dependent rivals cannot replicate. Three archetypes populate the competitive map: Southern African integrated mills with backward pulp control, global FMCG multinationals anchoring premium branded distribution, and regional converters serving mid-tier wholesale channels. Dominant competitive moves include capacity expansion into bamboo fiber processing and strategic partnerships with supermarket chains adopting sustainability procurement criteria.
Among Africa-based integrated producers, Sappi Southern Africa Limited exemplifies the captive-supply archetype with in-house pulp production. Twinsaver Group and Nova Papers (Pty) Ltd. occupy positions within South Africa's converter and wholesale supply tier, representing scale-driven competitors navigating recycling mandate compliance. Kimberly-Clark Worldwide, Inc. anchors the multinational branded segment across urban retail channels in Nigeria and Kenya.
| Leading Market Players |
|---|
| Sappi Southern Africa Limited |
| Universal Paper & Plastics |
| Kimberly-Clark Worldwide, Inc. |
| Georgia-Pacific |
| Must Paper Industries |
| Procter & Gamble Company |
| Nova Papers (Pty) Ltd. |
| Hengan International Group Co Ltd |
| Twinsaver Group |
| Others |
Cost & Logistics Intelligence
Mill-scale utilization rates at Sappi's Southern African pulp facilities anchor continent-wide cost floors for virgin-grade tissue output. This captive-supply concentration compresses margins for converter-reliant competitors while elevating price discipline across Lagos-Abuja and Nairobi procurement corridors.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across hospitality and healthcare procurement channels. Price differentiation hinges on Bureau of Standards certification tier and volume scale commitments, with Kenya's BIS-aligned thresholds commanding premiums over informal imports. Cost compression in recycled-grade segments is intensifying because South Africa's Department of Forestry, Fisheries and the Environment mandates elevate compliance expenditures. Food service operators in Lagos metropolitan zones exhibit highest price sensitivity; premium hospitality chains in Johannesburg-Pretoria demonstrate lowest sensitivity due to brand positioning requirements.
Supply Chain Analysis
Mombasa port congestion and container availability constraints on Asia-East Africa trade lanes elevate inbound logistics costs for finished tissue imports. Geographic supply concentration centers on South Africa, Kenya, and Nigeria, with fiber inputs drawing from hardwood kraft pulp, post-consumer waste streams, and bamboo cultivation zones. Single-source vulnerability concentrates around Sappi's captive pulp dominance. Distribution runs through supermarket retail networks, wholesale institutional contracts, and emerging e-commerce B2B platforms disintermediating traditional distributor layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: Kenya's BIS certification and South Africa's recycling mandates erect compliance barriers that favor scaled incumbents with established quality infrastructure.
For Market Incumbents: Consolidate backward integration into bamboo fiber processing to offset virgin pulp cost volatility and capture sustainability procurement tailwinds from Kenyan and Nigerian supermarket chains. Expand de-inking capacity in Johannesburg-Pretoria manufacturing zones to defend margin position against converter-reliant competitors facing Department of Forestry, Fisheries and the Environment compliance cost compression.
For New Entrants and Emerging Players: E-commerce B2B platform under-service in Nigeria's secondary cities presents whitespace for direct mill contracting models targeting mid-tier hospitality buyers in Ibadan, Kano, and Port Harcourt. Penetrate this segment through volume-guarantee procurement structures that bypass fragmented distributor networks concentrated in Lagos-Abuja.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated pulp-to-tissue producers with captive fiber supply and long-term hospitality contracts. Over a multi-year horizon, prioritize acquisition targets possessing Bureau of Standards certification infrastructure and established supermarket shelf presence. Monitor bamboo-grade supplier volume commitments from Nairobi metropolitan retailers as inflection signal for material substitution acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Bamboo Fiber Processing Capacity Expansion | Reduces virgin pulp dependency as Kenyan supermarkets harden sustainability procurement criteria. |
| Bureau of Standards Certification Investment | Secures cross-border trade access for Kenyan producers serving East African retail networks. |
| Direct Mill Contracting with Hospitality Chains | Disintermediates distributor margins across Lagos-Abuja corridor food service procurement. |
| Post-Consumer Recycling Infrastructure Buildout | Aligns with South Africa's Department of Forestry, Fisheries and the Environment content mandates. |
| E-Commerce B2B Platform Partnership | Captures mid-tier buyer consolidation across Nigeria and Kenya wholesale channels. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with tissue mill operations directors, supermarket category buyers, hospitality procurement managers, and Bureau of Standards certification officers. Secondary validation drew from customs trade records, Kenya Bureau of Standards product registrations, South African Department of Forestry, Fisheries and the Environment compliance filings, and hospitality chain procurement disclosures. Bottom-up capacity and consumption estimates were triangulated against top-down macroeconomic indicators across the analysis window.
Across the projection horizon, volume and value outputs were modeled through segmentation across product type, material input, end-user vertical, and distribution channel dimensions. CAGRs were derived from trend extrapolation of pulp input cost trajectories, urbanization-driven consumption intensity, and regulatory compliance cost absorption rates. Bamboo fiber substitution curves and recycling mandate compliance timelines served as industry-specific forecast inputs.
Forecasts assume regulatory continuity in Kenya's Bureau of Standards certification regime and South Africa's waste management standards; material policy shifts would require re-modeling of cross-border trade flows and domestic manufacturing scale assumptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Drum Pulper Market
Paper Products
Chemical Cellulose Market
Paper Products
Paper Pigment Market
Paper Products
Europe Medium-Density Fiberboard Market
Paper Products
Clay Coated Paper Market
Paper Products
Veneer Sheets Market
Paper Products
Plywood Market
Paper Products
Paper and Board Technologies Market
Paper Products
Paper Core Market
Paper Products
Chemical Pulp Market
Paper Products
Insulation Paper Market
Paper Products
Stone Paper Market
Paper Products
Global Dye Sublimation Paper Market
Paper Products
Wood-Based Panel Market
Paper Products
Decor Paper Market
Paper Products
Unbleached Softwood Kraft Pulp Market