
 Dental Fiber Posts Market | 2026-2036
Dental Fiber Posts Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Fiber Posts Market Outlook
Dental distributor networks is reconfiguring around direct-to-clinic digital platforms and consolidated group purchasing organizations. Ivoclar Vivadent leverages integrated CAD/CAM workflows to sustain premium positioning across European and North American channels. Dentsply Sirona anchors its fiber post portfolio within broader endodontic system bundles, competing on cross-selling efficiency rather than standalone pricing. Coltene Holding specializes in niche composite formulations that differentiate its posts for anterior aesthetic zones where optical properties command priority.
Dental fiber posts are cylindrical reinforcements composed of glass or carbon fibers embedded in resin matrices, typically measuring 0.5–2.0 mm in diameter and designed to bond within root canals to support coronal restorations. Their primary commercial purpose centers on restoring endodontically treated teeth where residual dentin requires structural supplementation beneath crowns or direct composite buildups. Prefabricated glass fiber posts dominate volume flows due to standardized sizing and immediate chairside availability, while custom-milled hybrid variants capture margin pools in high-aesthetic anterior cases demanding patient-specific canal adaptation. Carbon fiber formulations have receded to posterior functional applications where radiopacity and flexural strength outweigh translucency requirements.
The FDA's 510(k) premarket notification framework governs fiber post commercialization in the United States, requiring substantial equivalence demonstrations that extend development timelines for novel material compositions. Europe's MDR and CE marking obligations, administered through notified bodies under EMA-aligned vigilance systems, impose post-market surveillance duties that reshape supplier liability structures across Germany, Switzerland, and France. ISO 4049 standards for polymer-based restorative materials provide cross-border testing protocols that manufacturers reference to streamline multi-jurisdiction registrations. Stakeholders must monitor evolving MDR classification debates around permanent implantable dental devices, as reclassification would trigger clinical evidence requirements that alter competitive economics for mid-tier suppliers.
Market Dynamics
Endodontic specialists in private dental clinics are consolidating purchasing power through group purchasing organizations, compressing margins for fiber post suppliers while simultaneously demanding integrated CAD/CAM compatibility that favors vertically integrated manufacturers over standalone component vendors.
Growth Catalysts
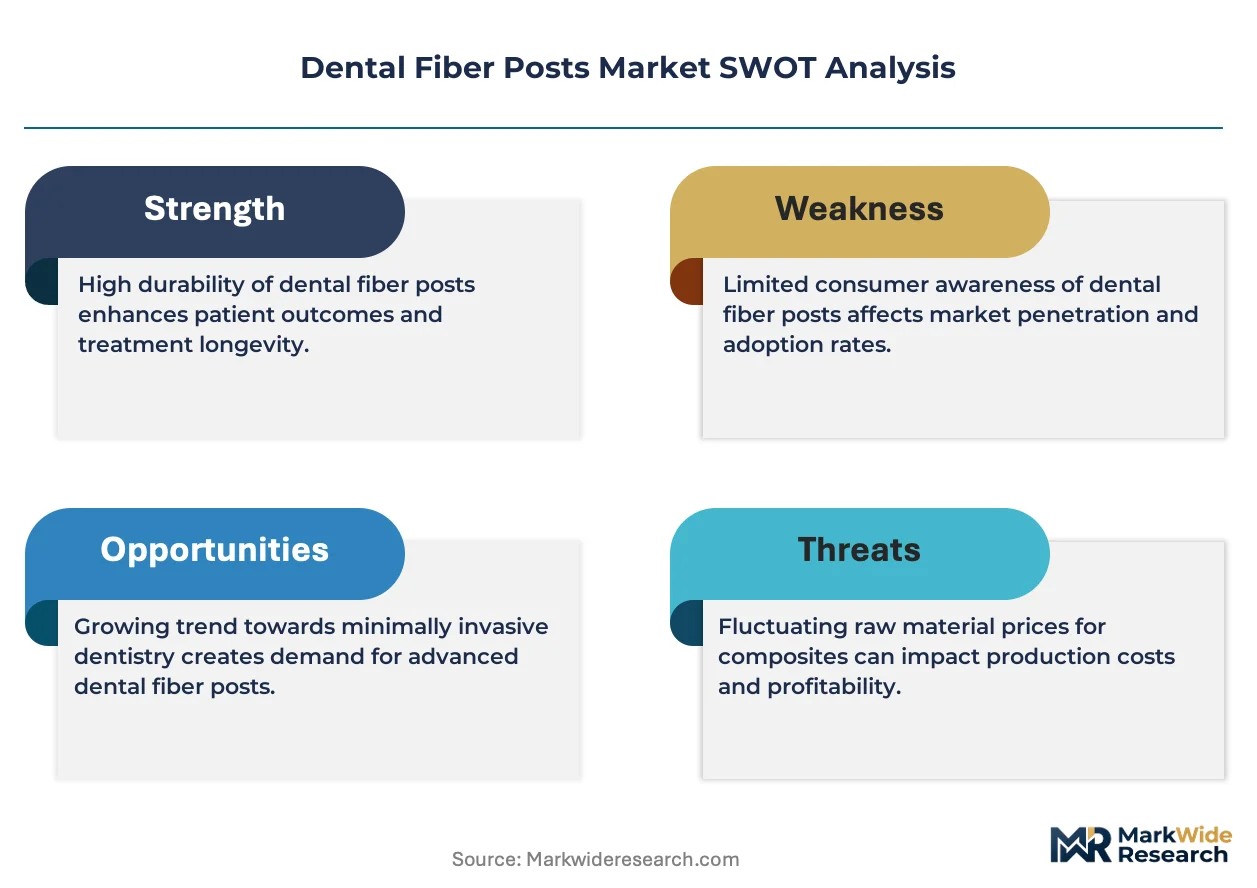
- MDR post-market surveillance obligations:European manufacturers investing in clinical evidence generation for fiber posts are building defensible quality dossiers that accelerate hospital procurement approvals in Germany and Switzerland.
- Glass fiber post standardization:Prefabricated sizing systems enable immediate chairside availability, reducing appointment duration and supporting higher patient throughput in high-volume private practices.
- Core-and-post restoration protocols:Endodontic specialists increasingly specify fiber posts as standard of care for anterior teeth requiring aesthetic layering, expanding addressable procedure volumes beyond posterior functional applications.
Market Restraints
- Zirconia post substitution:Monolithic ceramic alternatives with superior flexural strength capture high-load posterior cases, eroding carbon fiber's remaining functional niche.
- EMA-aligned vigilance systems:Enhanced post-market surveillance duties under Europe's MDR extend liability exposure for mid-tier suppliers lacking dedicated regulatory affairs infrastructure.
- Raw resin volatility:Epoxy and methacrylate matrix materials face petrochemical feedstock price instability, compressing gross margins for composite formulation specialists.
Strategic Opportunities
- Direct-to-clinic digital platforms:Dental distributor networks bypassing traditional wholesaler tiers can capture margin pools while offering real-time inventory visibility to multi-location practice groups.
- Custom-milled hybrid variants:Patient-specific canal adaptation via chairside CAD/C milling addresses high-aesthetic anterior cases where prefabricated posts fail to match optical integration requirements.
- ISO 4049 cross-border harmonization:Manufacturers referencing standardized polymer testing protocols streamline multi-jurisdiction registrations, reducing time-to-market in secondary European markets.
Industry Challenges
- 510(k) substantial equivalence pathways:FDA premarket notification requirements for novel fiber compositions extend development timelines, requiring predicate device matching that constrains material innovation cycles.
- CAD/CAM workflow integration:Fiber post suppliers must validate compatibility across multiple intraoral scanner and milling unit ecosystems, fragmenting R&D resources across platform-specific certification requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Fiber Posts Market |
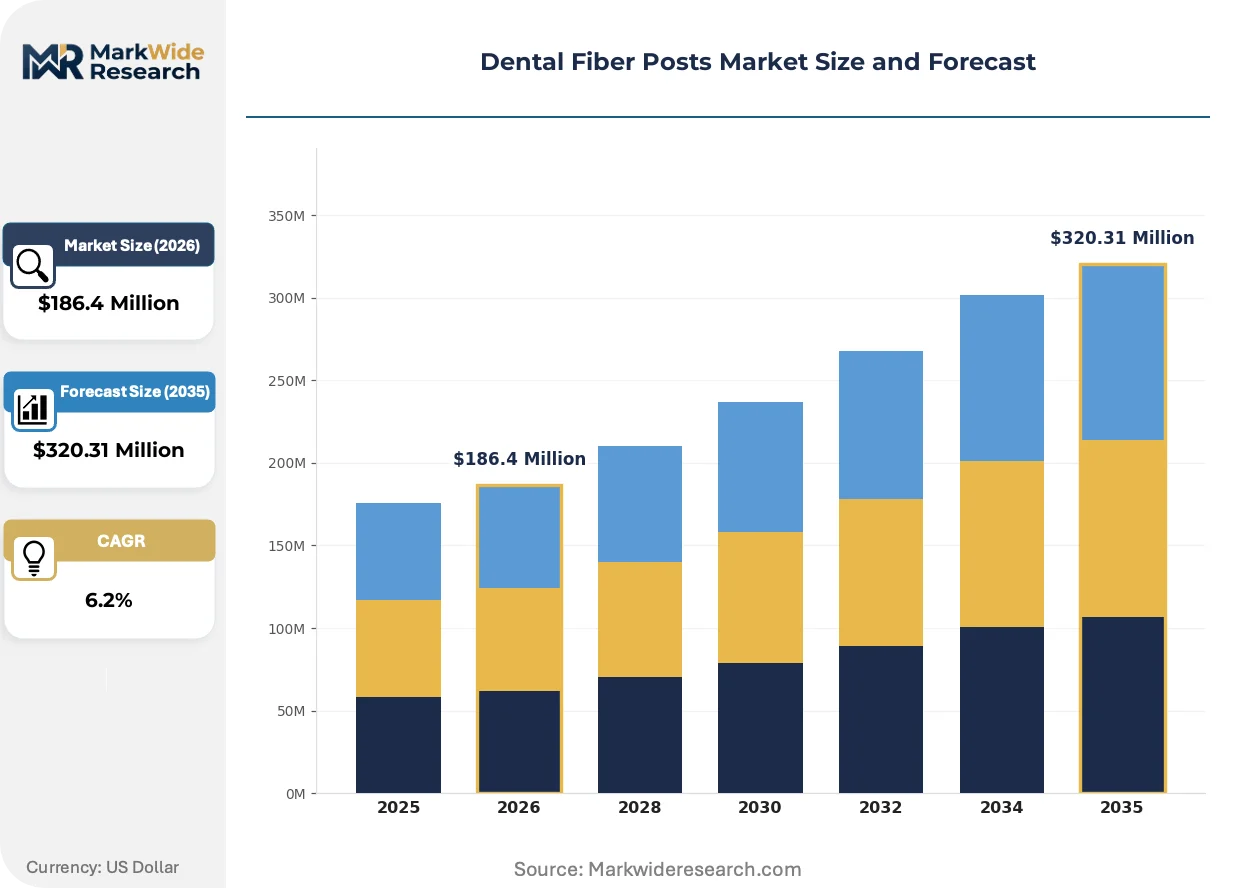
| Market Size in 2026 | $186.4 Million |
| Market Size in 2035 | $320.31 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prefabricated, Custom-Made, Composite, Hybrid End User: Dentists, Dental Clinics, Hospitals, Orthodontists Material: Glass Fiber, Carbon Fiber, Resin, Ceramic Application: Restorative Dentistry, Endodontics, Prosthodontics, Aesthetic Restorations |
| Companies Covered | Ivoclar Vivadent, Dentsply Sirona, Coltene Holding, 3M, VOCO GmbH, FGM Produtos Odontológicos, Angelus, GC Corporation, DMG Dental, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Fiber Posts Market Strategic Shifts
CAD/CAM integration is collapsing traditional boundaries between impression-taking, post selection, and final restoration fabrication, forcing fiber post suppliers to reposition as workflow enablers rather than standalone component vendors.
Translucent glass fiber formulations are collapsing the distinction between structural reinforcement and aesthetic substrate in anterior restorations. High-volume aesthetic practices in Germany and Switzerland now specify optical-grade posts that eliminate shadowing beneath layered composite veneers. This convergence is collapsing standalone post margins while expanding bundled system values.
Europe's MDR classification debates around permanent implantable dental devices are reshaping competitive economics for fiber post commercialization. Reclassification would trigger clinical evidence requirements that favor large manufacturers with dedicated regulatory infrastructure over mid-tier specialists. German notified bodies are already advising clients to prepare enhanced technical documentation for fiber-reinforced composite devices.
Group purchasing organizations are consolidating procurement authority across multi-location dental practice networks. Traditional distributor relationships fragment as purchasing managers centralize supplier negotiations and demand standardized product formularies. This concentration is most visible in North American dental service organizations, where procurement committees now specify approved vendor lists excluding non-integrated post systems.
Dental Fiber Posts Market Segmentation
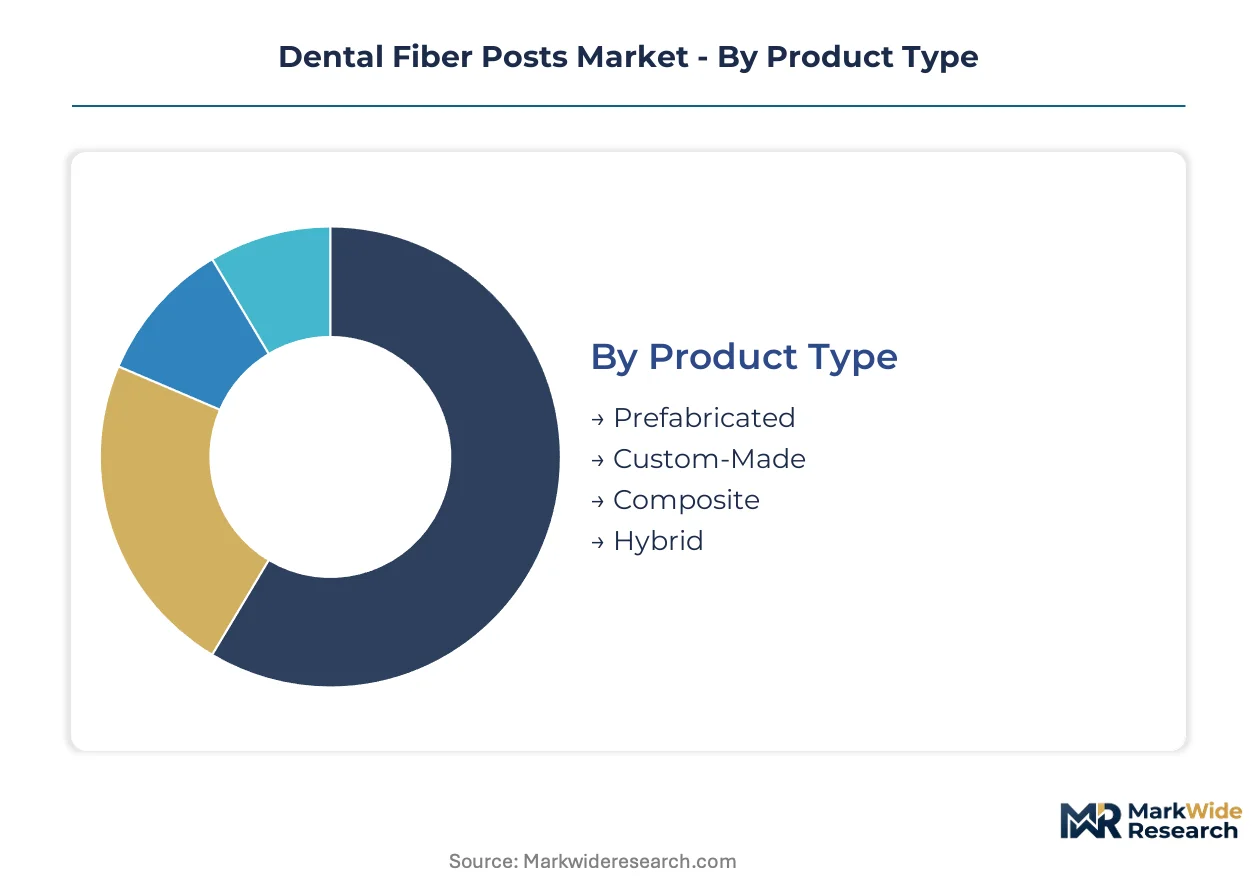
Segmentation in dental fiber posts reveals how clinical workflows, material science, and procurement hierarchies create distinct value pools. Understanding these divisions exposes where suppliers can defend premium positioning versus where volume competition erodes margins.
Product Type:
Use-case spectrum spans immediate chairside availability through to patient-specific anatomical adaptation.
- Prefabricated:Standardized cylindrical forms in graduated diameters enable single-visit restorations without laboratory delays. Demand concentrates in high-volume private practices across Germany and the United States, where appointment throughput directly impacts revenue per operatory.
- Custom-Made:Chairside CAD/CAM milling or laboratory-fabricated posts match individual canal morphology for complex anatomical cases. Swiss and French aesthetic specialists specify these for anterior teeth where prefabricated options risk optical compromise, though per-unit economics limit penetration below 15% of procedures.
- Composite:Fiber-reinforced polymer matrices bond chemically with adhesive cements, simplifying cementation protocols for general practitioners.
- Hybrid:Multi-material constructions combine structural fibers with aesthetic surface layers, targeting the narrowing zone between function and cosmetics.
The dominant share belongs to Prefabricated, while Custom-Made is closing the gap fastest.
End User:
Procurement authority concentrates differently across practice scales and clinical specializations.
- Dentists:General practitioners perform the majority of fiber post placements in routine restorative cases, purchasing through distributor networks or emerging direct-to-clinic platforms.
- Dental Clinics:Multi-location groups in North America centralize purchasing through group purchasing organizations, demanding standardized formularies that exclude non-integrated suppliers.
- Hospitals:Academic medical centers and public health systems in Germany and Switzerland require enhanced technical documentation under MDR post-market surveillance obligations, favoring manufacturers with dedicated regulatory infrastructure.
- Orthodontists:Limited direct engagement with fiber posts except in interdisciplinary cases involving post-orthodontic restoration of traumatized teeth.
Dental Clinics command the largest procurement volume, with Hospitals expanding their share through centralized tender processes.
Material:
Material selection trades off optical properties, radiopacity, and flexural strength against canal geometry and functional load.
- Glass Fiber:Translucent silica-based reinforcements embedded in epoxy or methacrylate matrices transmit light for aesthetic layering. German and Swiss anterior specialists specify optical-grade formulations where shadowing beneath composite veneers would compromise outcomes.
- Carbon Fiber:Graphite reinforcements offer superior flexural strength and radiopacity for posterior functional applications. Demand has retreated to molar restorations where translucency carries no clinical premium, facing displacement from monolithic zirconia alternatives.
- Resin:Pure polymer matrices without fiber reinforcement serve economy segments and temporary restorations.
- Ceramic:Zirconia and alumina posts compete indirectly, though brittleness and retrieval difficulty constrain adoption.
Glass Fiber holds the installed base advantage, though Carbon Fiber retains defensible niches in high-load posterior cases.
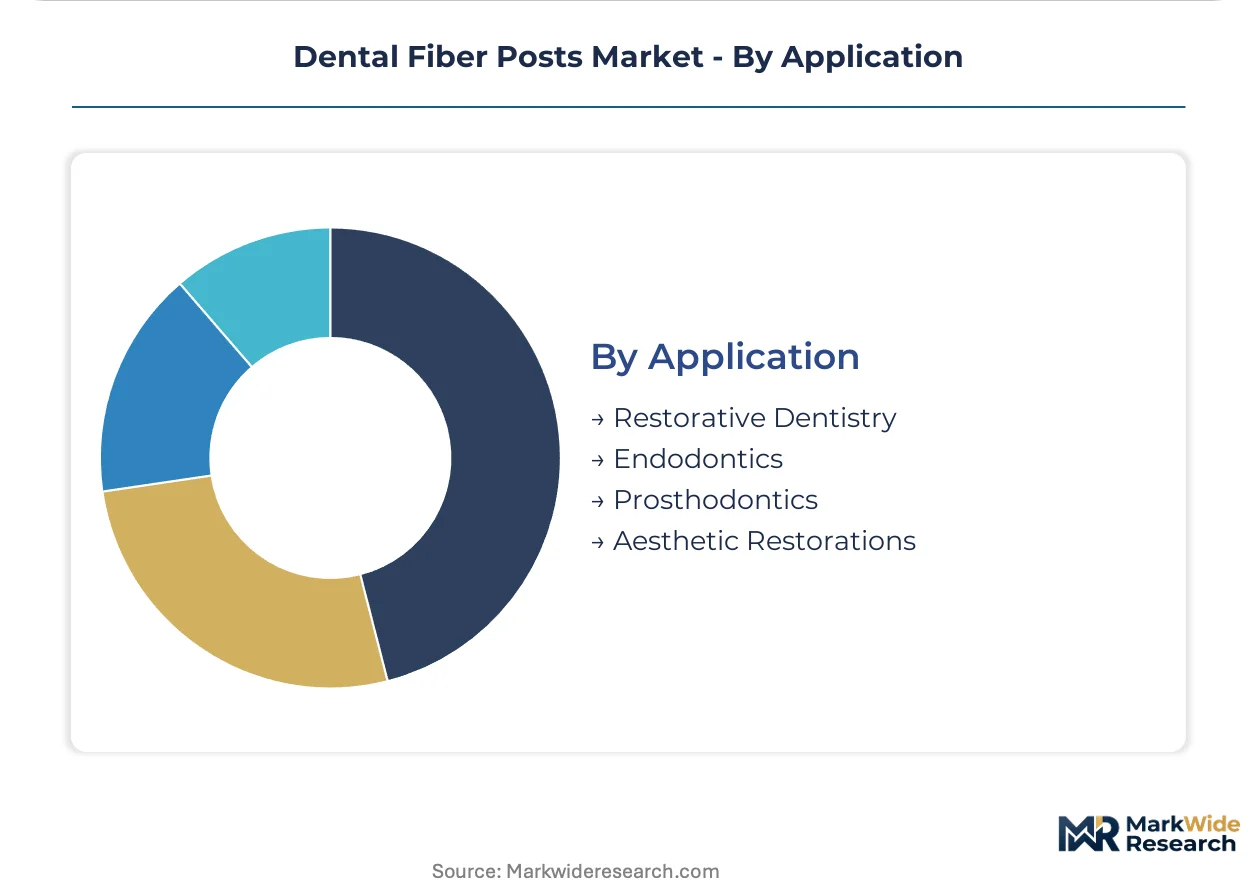
Application:
Clinical indication determines whether structural supplementation or aesthetic integration commands priority.
- Restorative Dentistry:Core-and-post buildups following endodontic therapy represent the foundational use case, with fiber posts replacing metal cast posts in routine crown foundations.
- Endodontics:Specialists specify posts as standard of care for anterior teeth requiring coronal restoration, expanding procedure volumes beyond traditional posterior applications.
- Prosthodontics:Complex rehabilitation cases involving multiple units leverage fiber posts for strategic abutment preservation.
- Aesthetic Restorations:Layered composite veneers over translucent posts demand optical-grade materials, collapsing the distinction between structural and cosmetic components.
Restorative Dentistry generates the highest procedure volume, while Aesthetic Restorations climbs fastest on anterior specialization trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium pricing for fiber post systems while the United States operates on volume-driven procurement contracts through dental service organizations. This asymmetry reflects divergent reimbursement structures and regulatory compliance costs across Atlantic markets.
United States
Group purchasing organizations centralize procurement for multi-location dental service organizations, compressing supplier margins while demanding ISO 4049-compliant documentation. The FDA's 510(k) premarket notification pathway governs fiber post commercialization, requiring substantial equivalence demonstrations that extend development timelines for novel resin matrices. Clinical adoption concentrates in private endodontic practices across Texas, Florida, and California, where appointment throughput economics favor prefabricated glass fiber systems.
Germany
Academic medical centers in Berlin and Munich require enhanced technical documentation under MDR post-market surveillance obligations, favoring manufacturers with dedicated regulatory infrastructure. The country's national pharmaceutical regulator, BfArM, coordinates with notified bodies on device classification debates that could trigger clinical evidence requirements. Manufacturing and clinician training networks anchor in Baden-Württemberg and Bavaria, where Ivoclar Vivadent and VOCO GmbH maintain integrated CAD/CAM workflow facilities.
Switzerland
Swissmedic vigilance systems impose stringent post-market surveillance duties that reshape supplier liability structures for fiber-reinforced composite devices. Aesthetic specialists in Zurich and Geneva specify optical-grade glass fiber posts for anterior restorations where translucency eliminates shadowing beneath layered composite veneers. The country's dental technology clusters emphasize precision milling capabilities for custom-milled hybrid variants.
France
ANSM oversight of dental device safety creates compliance barriers for mid-tier suppliers lacking European regulatory affairs infrastructure. Public hospital procurement in Paris and Lyon centralizes tender processes that demand MDR-aligned quality dossiers. The Île-de-France region hosts distribution hubs serving francophone African markets, extending French regulatory standards to secondary export destinations.
Japan
PMDA marketing authorization requirements for dental materials emphasize biocompatibility testing protocols that align with ISO 7405 standards. The Kanto region surrounding Tokyo concentrates demand from prosthodontic specialists managing complex rehabilitation cases. Japanese dental manufacturers compete through miniaturization expertise and surface treatment technologies for fiber-resin interfacial bonding.
Dental Fiber Posts Market Competitive Environment
Vertically integrated multinationals and specialized composite formulators split the market between bundled system sales and standalone premium positioning. Market concentration favors players with captive regulatory affairs infrastructure capable of navigating MDR transition costs and FDA 510(k) pathways. Three archetypes dominate: workflow-integrated conglomerates anchoring cross-selling efficiency, material-science specialists defending optical-property niches, and regional fabricators competing on distributor relationships. Competitive moves center on CAD/CAM ecosystem certification and direct-to-clinic digital platform development.
Among workflow-integrated conglomerates, Dentsply Sirona exemplifies the cross-selling archetype through endodontic system bundling. Ivoclar Vivadent represents the premium-tier positioning anchored in European manufacturing and training networks. Coltene Holding occupies a specialist position within composite formulation segments. These three entities illustrate how competitive economics diverge between volume-driven procurement channels and aesthetic-zone premium applications.
| Leading Market Players |
|---|
| Ivoclar Vivadent |
| Dentsply Sirona |
| Coltene Holding |
| 3M |
| VOCO GmbH |
| FGM Produtos Odontológicos |
| Angelus |
| GC Corporation |
| DMG Dental |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Chinese epoxy resin production is compressing matrix material costs while European glass fiber manufacturers maintain tighter utilization, creating divergent pricing power across Atlantic supply bases. German and Swiss suppliers leverage constrained silica fiber capacity to defend premium positioning, whereas North American distributors face margin compression from group purchasing organization concentration.
Pricing Analysis
The customization-premium spread separates standard prefabricated glass fiber posts from patient-specific CAD/CAM-milled variants, with optical-grade anterior formulations commanding substantial markups over functional posterior grades. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 4049 certification tiers and brand equity accumulation in German training networks. Cost compression in standard prefabricated lines is intensifying because distributor consolidation eliminates non-integrated suppliers from approved vendor lists. High-volume dental service organizations exhibit greatest price sensitivity, while Swiss aesthetic specialists show least elasticity due to outcome-based procurement protocols.
Supply Chain Analysis
Tariff exposure between Chinese epoxy resin suppliers and European compounders dominates raw material cost volatility for fiber post manufacturers. Production gravity centers on Germany, Switzerland, and Japan, with Baden-Württemberg hosting integrated CAD/CAM workflow facilities and Tokyo-area specialists controlling surface treatment technologies. Feedstock supply draws from petrochemical complexes in China and specialized silica mining operations in Germany. Single-source vulnerability concentrates in optical-grade glass fiber drawing capacity, where Swiss and German facilities lack geographic redundancy. Distribution runs through dental service organization procurement committees and direct-to-clinic digital platforms, bypassing traditional wholesale tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Defensible positioning in this market hinges on captive regulatory affairs infrastructure and certified CAD/CAM ecosystem integration, assets concentrated among a handful of European manufacturers. Mid-tier suppliers without dedicated MDR compliance teams face exclusion from hospital procurement channels.
For Market Incumbents: Entrench workflow integration by validating fiber post compatibility across intraoral scanner and milling unit ecosystems, fragmenting competitor R&D resources across platform-specific certifications. Backward integration into optical-grade glass fiber drawing secures supply continuity against Chinese epoxy volatility. Zirconia post substitution in posterior applications demands defensive innovation in hybrid material formulations. For New Entrants and Emerging Players: Pursue direct-to-clinic digital platforms serving multi-location practice groups in North America, where distributor bypass offers margin capture opportunities absent in European hospital channels. Custom-milled hybrid variants for anterior aesthetic cases represent the most penetrable segment, as prefabricated optical-grade posts fail to match patient-specific canal adaptation requirements. Lead with ISO 4049 cross-border harmonization to accelerate secondary European market entry. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among workflow-integrated conglomerates with captive training network dependencies. Long-term viability over the coming decade favors manufacturers with dedicated regulatory infrastructure capable of absorbing MDR clinical evidence requirements. Acquisition targets should demonstrate notified body relationships and enhanced technical documentation capabilities. The signal to watch is reclassification debates around permanent implantable dental devices, which would trigger step-function changes in competitive economics.| Strategic Initiative | Industry Significance |
|---|---|
| CAD/CAM Ecosystem Certification | Validating compatibility across Ivoclar Vivadent and Dentsply Sirona workflows locks in supplier status. |
| MDR Technical Documentation Investment | Enhanced dossiers satisfy BfArM-coordinated notified body requirements for German hospital tenders. |
| Direct-to-Clinic Platform Development | Bypassing traditional distributors captures margin pools while serving dental service organization procurement committees. |
| Optical-Grade Glass Fiber Backward Integration | Captive silica fiber drawing secures supply against Chinese epoxy resin volatility and tariff exposure. |
| Hybrid Material Formulation R&D | Multi-material constructions defend against zirconia post substitution in high-load posterior applications. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EMA MDR submission databases, ISO 4049 testing protocols, and hospital procurement contract records. Primary interviews engaged endodontic specialists, dental service organization procurement managers, biomedical engineers at academic medical centers, and GPO contracts administrators. Secondary validation drew from notified body technical documentation guidance, customs trade data on epoxy resin flows, and dental technology cluster economic development reports. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue allocations.
Forecast inputs incorporate material substitution elasticities, regulatory compliance cost trajectories, and CAD/CAM adoption curves across the analysis window. Segmentation dimensions modeled include product type, material composition, end-user procurement channel, and application indication. CAGRs derived from logistic diffusion curves fitted to historical procedure data and forward-projected equipment installation bases. Industry-specific inputs capture MDR reclassification probability assessments and group purchasing organization penetration rates in North American dental service organizations.
Sensitivities concentrate around MDR classification outcomes for permanent implantable devices, raw resin price volatility, and zirconia post substitution rates in posterior restorations. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Materials
Zirconia Based Dental Ceramics Market
Dental Materials
Dental Zirconia Powder Market
Dental Materials
Dental Impression Material Market
Dental Materials
Dental Wax Market
Dental Materials
Dental Bonding Agent Market
Dental Materials
Dental Matrix Systems Market
Dental Materials
Fluoride Mouthwash Market
Dental Materials
Dental Amalgam Market
Dental Materials
Calcium Hydroxylapatite Fillers Market
Dental Materials
Dental Putty Market
Dental Materials
Charcoal Teeth Whitening Powder Market
Dental Materials
Asia-Pacific Toothpaste Market
Dental Materials
Nanotechnology Toothpaste Formulations Market
Dental Materials
Sensitive Toothpaste Market
Dental Materials
Dental Resins Market
Dental Materials
Dental Restorative and Regenerative Material Market