
 Global Biomaterials Market | 2026-2036
Global Biomaterials Market Size, Share, and Industry Trends Forecast 2026-2036
Global Biomaterials Market Analysis
Implant surface modification services is reconfiguring margin pools away from commodity metal sales toward value-added coating technologies. BASF SE leverages its polymer science heritage to dominate high-purity synthetic polymer supply for cardiovascular stent substrates. Evonik Industries AG anchors its position through backward integration into amino acid-derived bioresorbable polymer production. Stryker Corporation competes by controlling orthopedic implant distribution networks across North American hospital systems.
Biomaterials encompass engineered substances designed to interface with biological systems for therapeutic or diagnostic purposes, including titanium alloys with osseointegration-promoting surface roughness parameters and poly-lactic-co-glycolic acid copolymers with tunable degradation rates matched to tissue regeneration timelines. Synthetic polymers command the largest revenue share due to batch-to-batch consistency and scalable melt-processing compatibility with injection molding equipment. Ceramics represent the fastest-growing product category as hydroxyapatite-reinforced composites displace pure titanium in dental and cranial implant applications. Nanotechnology-enabled surface modification creates premium pricing tiers for drug-eluting cardiovascular stents and antimicrobial orthopedic coatings.
The FDA enforces biocompatibility testing under ISO 10993 standards, while the EU Medical Device Regulation mandates clinical evidence for permanent implant classifications, collectively elevating barriers for unproven material entrants. Japan's PMDA maintains stringent foreign body reaction assessment protocols that delay market access for novel ceramic formulations. Stakeholders must monitor regulatory divergence between the FDA's regenerative medicine advanced therapy designation and the EMA's adaptive pathway framework to optimize clinical trial investment sequencing.
Market Dynamics
The biomaterials market is reconfiguring around surface engineering capabilities that extract premium pricing from commodity substrates through nanostructured coatings and drug-eluting functionalities.
Growth Catalysts
- Regenerative medicine acceleration:The FDA's regenerative medicine advanced therapy designation compresses clinical trial timelines for tissue-engineered constructs. Cell therapy manufacturers are expanding bioreactor capacity to meet scaffold demand.
- Bioprinting integration:Hospital systems in the United States, Germany, and Japan are embedding 3D bioprinting into pre-surgical planning workflows. Titanium lattice structures with patient-specific geometries now dominate craniomaxillofacial reconstruction.
- Antimicrobial coating mandates:Japan's PMDA has tightened foreign body reaction assessment protocols that favor silver-ion and copper-alloy surface treatments. Implant-associated infection reduction targets are driving coating service procurement.
Market Restraints
- High-purity polymer supply concentration:Medical-grade polycaprolactone and polyglycolic acid production concentrates among three European chemical conglomerates. Batch qualification timelines extend 18-24 months for new entrants.
- Clinical evidence requirements:The EU Medical Device Regulation mandates post-market surveillance for permanent implant classifications. Small manufacturers lack capital to maintain clinical follow-up registries.
- Ceramic brittleness limitations:Hydroxyapatite-reinforced composites face stress-shielding constraints in load-bearing orthopedic applications. Titanium alloys retain dominance in femoral stem and acetabular cup geometries.
Strategic Opportunities
- Bioresorbable stent expansion:Magnesium alloy corrosion control technologies are opening coronary and peripheral vascular applications. Evonik's amino acid-derived polymer platforms enable tunable degradation kinetics.
- India's domestic manufacturing push:The country's PLI scheme for medical devices is attracting contract manufacturing investment. Local orthopedic implant production targets are creating polymer compounding demand.
- Digital surgical planning convergence:CT-to-implant workflow integration is creating bundled service opportunities. Point-of-care 3D printing in German university hospitals is reshaping cranioplasty supply chains.
Industry Challenges
- Biocompatibility testing bottlenecks:ISO 10993 cytotoxicity and sensitization studies require 6-9 month completion timelines. Contract research organization capacity constraints are delaying 510(k) submissions.
- Interoperability with legacy sterilization:Novel polymer formulations face gamma irradiation degradation or ethylene oxide residual compliance conflicts. Validation protocol redevelopment absorbs engineering resources.
- Surface characterization skill scarcity:Atomic force microscopy and X-ray photoelectron spectroscopy expertise concentrates among academic laboratories. Industrial metrology staffing gaps are slowing coating development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Biomaterials Market |
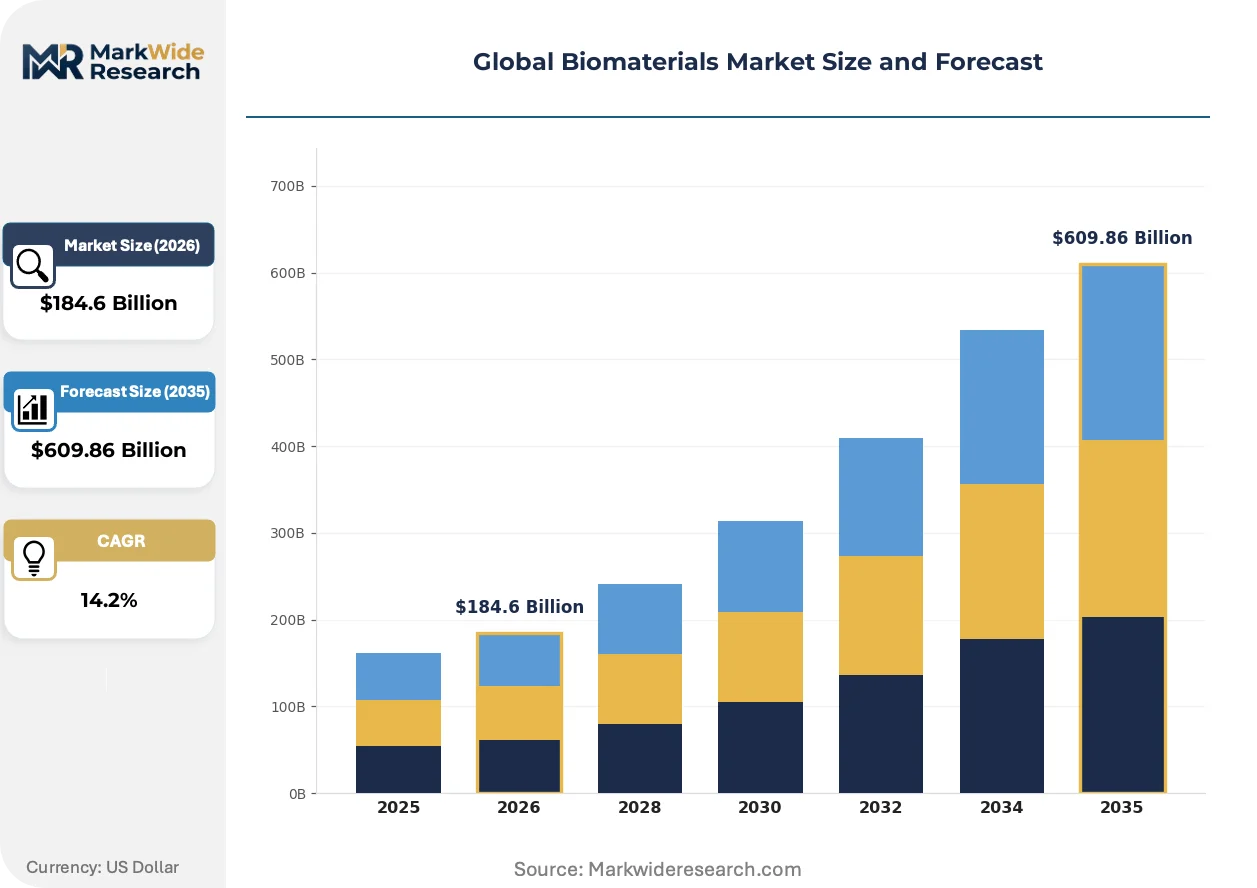
| Market Size in 2026 | $184.6 Billion |
| Market Size in 2035 | $609.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Polymers, Synthetic Polymers, Ceramics, Metals Application: Orthopedics, Cardiovascular, Tissue Engineering, Drug Delivery End User: Hospitals, Clinics, Research Institutions, Pharmaceutical Companies Technology: 3D Printing, Surface Modification, Bioprinting, Nanotechnology |
| Companies Covered | BASF SE, Evonik Industries AG, Carpenter Technology Corporation, Medtronic plc, Zimmer Biomet, Stryker Corporation, Johnson & Johnson, Corbion N.V., CoorsTek Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Biomaterials Market Emerging Trajectories
Electrospinning and melt electrowriting are collapsing the boundary between scaffold architecture and controlled release kinetics, enabling single-process fabrication of drug-device combination products.
4D bioprinting with shape-memory polymers is rendering obsolete static titanium mesh implants in cranial reconstruction. Neurosurgical departments at Johns Hopkins and Charité Berlin are adopting temperature-responsive fixation systems that self-tighten upon implantation. This capability is compressing revision surgery rates and extending implant lifecycle value capture.
The EU Medical Device Regulation's enhanced clinical evidence requirements are fragmenting the competitive landscape between well-capitalized incumbents and specialized contract manufacturers. Medium-sized orthopedic firms are outsourcing biocompatibility dossier preparation to dedicated regulatory consultancies. Cardiovascular stent submissions now require 5-year follow-up data that only polymer science heritage firms can generate retrospectively.
Hospital procurement departments are consolidating vendor panels around full-lifecycle service agreements rather than unit-price negotiations. German hospital chains now bundle implant supply with surface modification and revision surgery liability coverage. This shift is visible most acutely in North Rhine-Westphalia's integrated care networks, where single-source contracts cover trauma, spine, and joint replacement biomaterial needs.
Global Biomaterials Market Segmentation
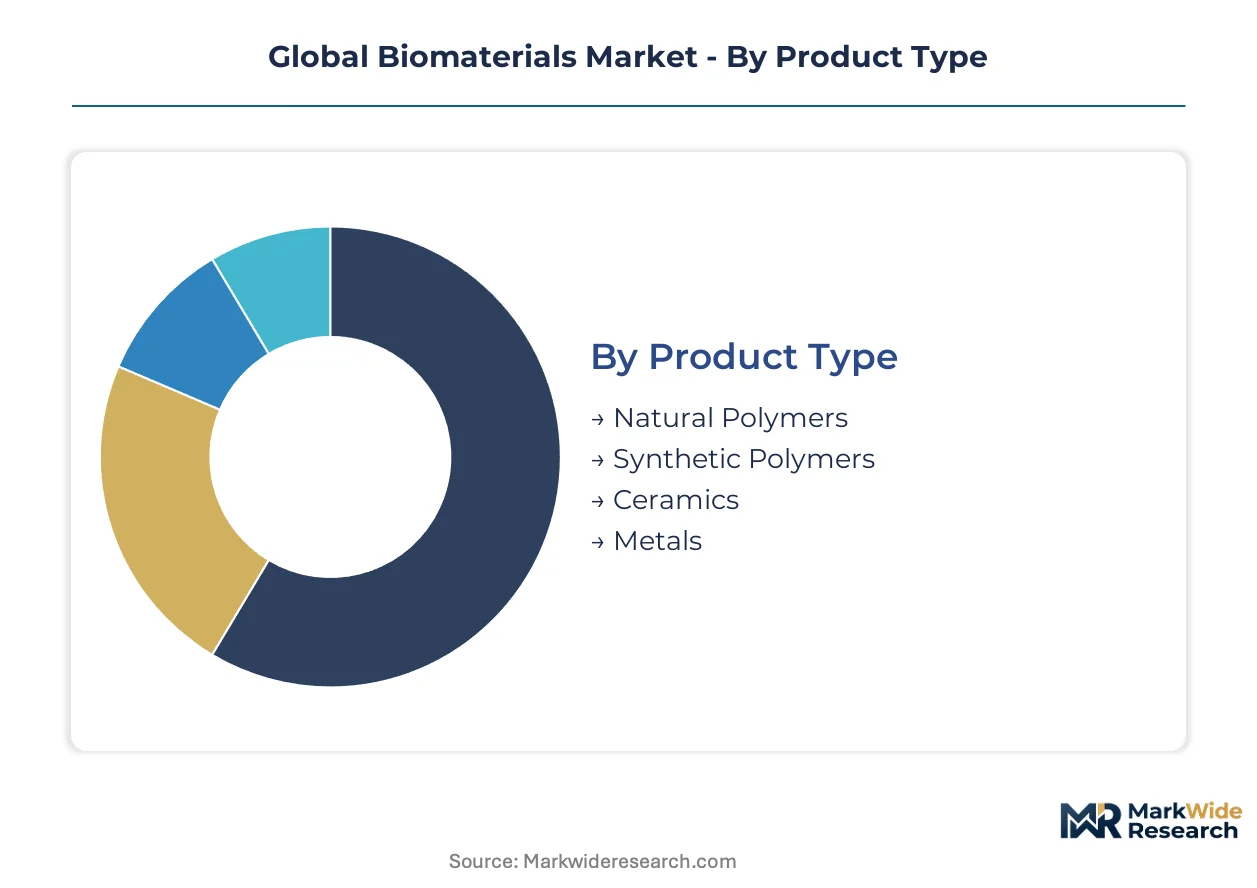
Biomaterial procurement patterns diverge sharply across product categories, with synthetic polymers requiring extensive batch qualification support while ceramics demand fracture-risk counseling services. Hospital systems negotiate service bundles differently for each segment, creating tiered margin structures that reward technical advisory capabilities over commodity supply.
Product Type:
After-sales intensity varies dramatically across material classes, with synthetic polymers demanding 18-24 month batch requalification cycles and ceramics requiring implantation training and fracture-response protocols.
- Synthetic Polymers:Medical-grade polycaprolactone and polyglycolic acid offer tunable degradation kinetics matched to tissue regeneration timelines. Demand concentrates in cardiovascular stent substrates from Germany and Japan, where BASF SE and Evonik Industries AG maintain backward integration into amino acid-derived bioresorbable production.
- Ceramics:Hydroxyapatite-reinforced composites provide osseoconductive properties with modulus closer to native bone than titanium. Japanese dental implant manufacturers and German cranioplasty specialists are displacing pure titanium in non-load-bearing applications despite PMDA's stringent foreign body reaction protocols.
- Metals:Titanium alloys with surface-roughened topography dominate femoral stems and acetabular cups through osseointegration-promoting parameters.
- Natural Polymers:Collagen and chitosan scaffolds serve tissue-engineered constructs with inherent cell-adhesion motifs.
Synthetic polymers holds the largest share; momentum sits with ceramics.
Application:
Cost tier separation distinguishes emergency cardiovascular interventions from elective orthopedic procedures, with stent procurement commanding premium pricing and joint replacement operating on standard episode-based bundles.
- Orthopedics:Implant surface modification services extract value from commodity titanium through nanostructured coatings and antimicrobial functionalities. Stryker Corporation controls distribution networks across North American hospital systems for trauma, spine, and joint replacement portfolios.
- Cardiovascular:Drug-eluting stents require 5-year follow-up data under EU Medical Device Regulation, favoring polymer science heritage firms with retrospective clinical registries. Nanotechnology-enabled surface modification creates premium tiers for coronary and peripheral vascular applications.
- Tissue Engineering:FDA regenerative medicine advanced therapy designation compresses clinical timelines for scaffold-supported cell therapies.
- Drug Delivery:Poly-lactic-co-glycolic acid copolymers enable tunable release kinetics matched to therapeutic windows.
Orthopedics captures the greatest volume; tissue engineering is climbing the fastest.
End User:
Customer type determines contract structure, with pharmaceutical companies seeking technology transfer agreements and hospitals preferring full-lifecycle service bundles with revision surgery liability coverage.
- Hospitals:German hospital chains in North Rhine-Westphalia now bundle implant supply with surface modification and point-of-care 3D printing integration. Johns Hopkins and Charité Berlin neurosurgical departments are adopting temperature-responsive fixation systems that self-tighten upon implantation.
- Pharmaceutical Companies:Cell therapy manufacturers are expanding bioreactor capacity to meet scaffold demand, with Evonik's amino acid-derived polymer platforms enabling tunable degradation kinetics for combination products.
- Clinics:Outpatient settings concentrate on dental and dermal filler applications with lower regulatory burden.
- Research Institutions:Academic laboratories maintain atomic force microscopy and X-ray photoelectron spectroscopy expertise that industrial metrology staffing gaps cannot replicate.
Hospitals dominate procurement value; pharmaceutical companies are gaining share fastest.
Technology:
Supply concentration for specialized equipment creates vendor lock-in, with 3D printing system manufacturers capturing recurring materials revenue and surface modification service providers controlling coating formulation IP.
- 3D Printing:CT-to-implant workflow integration creates bundled service opportunities for titanium lattice structures with patient-specific geometries. German university hospitals are reshaping cranioplasty supply chains through point-of-care production.
- Surface Modification:Silver-ion and copper-alloy treatments command premium pricing as Japan's PMDA tightens foreign body reaction assessment protocols favoring antimicrobial coatings. Coating service procurement is accelerating under implant-associated infection reduction targets.
- Bioprinting:Hospital systems in the United States, Germany, and Japan embed 3D bioprinting into pre-surgical planning workflows.
- Nanotechnology:Electrospinning and melt electrowriting collapse the boundary between scaffold architecture and controlled release kinetics.
Surface modification holds the largest share; bioprinting shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement departments in Germany negotiate full-lifecycle service bundles with revision surgery liability coverage, while Indian contract manufacturers compete primarily on unit economics under the PLI scheme for medical devices.
United States
Johns Hopkins neurosurgical departments are adopting temperature-responsive fixation systems that self-tighten upon implantation, compressing revision surgery rates. The FDA's regenerative medicine advanced therapy designation accelerates commercial timelines for tissue-engineered constructs. Cell therapy manufacturers in Massachusetts and California are expanding bioreactor capacity to meet scaffold demand.
Germany
Hospital chains in North Rhine-Westphalia bundle implant supply with surface modification and point-of-care 3D printing integration for cranioplasty applications. The EU Medical Device Regulation mandates 5-year follow-up data for cardiovascular stent submissions, favoring polymer science heritage firms with retrospective clinical registries. Charité Berlin anchors adoption of 4D bioprinting with shape-memory polymers for cranial reconstruction.
Japan
PMDA tightened foreign body reaction assessment protocols favor silver-ion and copper-alloy antimicrobial surface treatments for implant-associated infection reduction. Dental implant manufacturers in Aichi Prefecture are displacing pure titanium with hydroxyapatite-reinforced composites in non-load-bearing applications. METI supports bioprinting integration into pre-surgical planning workflows at university hospitals.
India
Domestic orthopedic implant production targets under the PLI scheme are creating polymer compounding demand for local manufacturers. CDSCO streamlined medical device registration pathways for contract manufacturers establishing operations in Gujarat and Karnataka. Mumbai-based hospital systems are piloting bundled procurement models adapted from German integrated care networks.
Switzerland
Swissmedic maintains stringent clinical evidence requirements for permanent implant classifications that elevate barriers for novel ceramic formulations. Geneva and Basel clusters concentrate atomic force microscopy and X-ray photoelectron spectroscopy expertise for surface characterization services. Swiss orthopedic distributors are consolidating vendor panels around full-lifecycle agreements with liability coverage.
Global Biomaterials Market Vendor Landscape
Capability concentration sits with polymer science heritage firms possessing backward integration into amino acid-derived bioresorbable production; scale advantage sits with diversified chemical conglomerates with medical-grade polycaprolactone batch qualification infrastructure. The vendor base stratifies across three tiers: integrated material suppliers controlling high-purity polymer supply, orthopedic implant manufacturers dominating distribution networks, and specialized coating service providers extracting value from commodity substrates. Strategic moves center on M&A for regulatory dossier libraries and capacity expansion for bioreactor-compatible scaffold production.
Within the polymer supply tier, BASF SE and Evonik Industries AG exemplify integrated material suppliers with captive production of cardiovascular stent substrates. Among orthopedic-focused manufacturers, Stryker Corporation occupies a position representing distribution network control across North American hospital systems. These three anchors illustrate how competitive positioning depends on either upstream material integration or downstream channel capture.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| Carpenter Technology Corporation |
| Medtronic plc |
| Zimmer Biomet |
| Stryker Corporation |
| Johnson & Johnson |
| Corbion N.V. |
| CoorsTek Inc. |
| Others |
Supply Flow & Price Mechanics
Undercapacity in medical-grade polycaprolactone production across European chemical conglomerates is compressing supplier leverage and elevating batch qualification premiums. This utilization squeeze simultaneously tightens polymer feedstock availability and rewards incumbents with captive amino acid-derived bioresorbable production lines.
Pricing Analysis
After-sales revenue from 18-24 month batch requalification cycles and surface modification service contracts drives lifetime value capture for synthetic polymer suppliers. Three-tier pricing structure across premium, standard, and economy levels separates ISO 10993-certified cardiovascular stent substrates from unqualified experimental grades. Cost compression in commodity titanium alloy supply is intensifying because Indian contract manufacturers are scaling orthopedic implant production under PLI scheme incentives. Hospital procurement committees exhibit lowest price sensitivity for drug-eluting stent substrates requiring 5-year EU Medical Device Regulation follow-up data, while outpatient dental clinics negotiate aggressively on hydroxyapatite-reinforced composite unit costs.
Supply Chain Analysis
Export-control regimes limiting bioreactor-compatible scaffold production technology flows are constraining technology transfer to emerging manufacturing hubs. Supply concentrates in Germany, Japan, and the United States for high-purity synthetic polymer production, with raw material dependencies on amino acid precursors, titanium sponge, and hydroxyapatite feedstock. Single-source vulnerability pervades medical-grade polycaprolactone batch qualification infrastructure, where three European chemical conglomerates control 18-24 month validation timelines. Distribution runs through orthopedic implant manufacturers controlling North American hospital system networks and specialized coating service providers extracting value from commodity substrates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward hospital procurement departments consolidating vendor panels around full-lifecycle service agreements with revision surgery liability coverage. German hospital chains in North Rhine-Westphalia exemplify this consolidation, now bundling implant supply with surface modification and point-of-care 3D printing integration.
For Market Incumbents: Harden regulatory dossier libraries through retrospective clinical registry investments that satisfy EU Medical Device Regulation 5-year follow-up mandates for cardiovascular stent submissions. Deepen backward integration into amino acid-derived bioresorbable polymer production to defend against supply concentration risks from European chemical conglomerates controlling batch qualification timelines. Channel control across North American hospital systems remains the priority lever against emerging coating service providers. For New Entrants and Emerging Players: Pursue white-space opportunities in India's domestic orthopedic implant production ecosystem, where PLI scheme incentives are attracting contract manufacturing investment and creating polymer compounding demand gaps. Target cranioplasty supply chain disruption through point-of-care 3D printing integration at German university hospitals, where CT-to-implant workflow convergence is reshaping procurement patterns. A go-to-market angle anchored in antimicrobial coating formulation IP addresses Japan's PMDA-tightened foreign body reaction assessment protocols. For Investors and Strategic Acquirers: Capital is best deployed toward contract manufacturers with bioreactor-compatible scaffold production capacity and established ISO 10993 biocompatibility testing relationships. Long-term viability across the analysis window favors assets with regulatory dossier libraries rather than commodity metal supply positions. The signal to watch is FDA regenerative medicine advanced therapy designation acceleration compressing commercial timelines for tissue-engineered construct manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Amino Acid-Derived Polymers | Evonik's captive production secures cardiovascular stent substrate supply against European chemical conglomerate concentration. |
| Hospital System Partnership with Full-Lifecycle Bundling | German chains in North Rhine-Westphalia consolidate trauma, spine, and joint replacement procurement under single-source contracts. |
| CE Marking Pathway Investment for Permanent Implants | EU Medical Device Regulation mandates elevate barriers for unproven ceramic formulations without retrospective clinical registries. |
| Software Companion Development for CT-to-Implant Workflows | Point-of-care 3D printing integration at Charité Berlin and Johns Hopkins compresses cranioplasty revision surgery rates. |
| Reimbursement Strategy for Antimicrobial Coatings | Japan's PMDA infection reduction targets favor silver-ion and copper-alloy surface treatments with premium pricing tiers. |
Methodological Framework
The analysis maps synthetic polymers, ceramics, metals, and natural polymers, each validated through biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs leads at cardiovascular stent manufacturers. Primary interviews with these stakeholders combined with secondary validation from FDA 510(k) filings, EMA submission databases, ISO 10993 test report registries, and hospital procurement contract records. Bottom-up demand modeling across application segments triangulated against top-down chemical conglomerate capacity disclosures.
Assumptions held fixed include current FDA regenerative medicine advanced therapy designation timelines and EU Medical Device Regulation post-market surveillance requirements, while variables included bioprinting adoption rates at German university hospitals and PLI scheme participation intensity among Indian contract manufacturers. Segmentation dimensions modeled encompass material class, application category, end-user type, and technology platform across the projection horizon. CAGRs derived from regression analysis of historical procurement volume patterns and capacity expansion announcements from polymer science heritage firms.
Sensitivities concentrate around regulatory divergence between FDA adaptive pathways and EMA clinical evidence requirements, biocompatibility testing bottlenecks at contract research organizations, and ceramic brittleness limitations in load-bearing orthopedic applications. Material shifts in Japan's PMDA foreign body reaction assessment protocols or India's PLI scheme medical device production targets would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomaterials
Hydrogel Market
Biomaterials
Biomimetic Materials Market
Biomaterials
Middle East and Africa Orthopedic Biomaterial Market
Biomaterials
Global Extracellular Matrix Patches Market
Biomaterials
Global Bone Grafts and Substitutes Market
Biomaterials
North America Chitosan Market
Biomaterials
Nerve Repair Biomaterials Market
Biomaterials
Global Hydroxyapatite Market
Biomaterials
Pulp Cells Market
Biomaterials
Global Biocompatible Materials Market
Biomaterials
Bone Distractors Market
Biomaterials
South America Collagen Market
Biomaterials
Crocodile Peptide Market
Biomaterials
Chitosan Market
Biomaterials
Global Absorbable Tissue Spacer Market
Biomaterials
Hydrogel Face Mask Market