
 Asia-Pacific Toothpaste Market | 2026-2036
Asia-Pacific Toothpaste Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Toothpaste Market Outlook
Natural ingredient formulation is fragmenting traditional chemical-based manufacturing across the Asia-Pacific toothpaste industry. Colgate-Palmolive leverages its extensive distribution network to sustain shelf dominance in Indian and Southeast Asian retail channels. Dabur India Ltd. anchors its competitive stance through deep Ayurvedic heritage and herbal product specialization. Kao Corporation differentiates via advanced enzymatic whitening technologies developed for Japanese consumer preferences.
Toothpaste is a dentifrice paste or gel containing abrasives, humectants, binders, detergents, and active therapeutic agents such as fluoride or potassium nitrate, manufactured through high-shear mixing and vacuum deaeration to achieve specified viscosity and stability for mechanical plaque removal and caries prevention. Herbal formulations now command premium positioning as consumers across Thailand and Malaysia shift toward plant-derived surfactants and neem-based antibacterial systems. Sensitivity segments are expanding fastest among aging demographics in Japan and South Korea, where enamel erosion concerns drive potassium nitrate and arginine formulations. Tube packaging still dominates volume, though pump formats gain traction in premium urban retail across Australia and Singapore.
India's BIS certification requirements for fluoride concentration limits directly shape product reformulation costs for manufacturers serving that market. China's SAMR enforces GB standards on labeling claims and active ingredient disclosure, restricting how whitening efficacy is communicated to consumers. Japan's PMDA oversight of quasi-drug classifications creates distinct regulatory pathways for medicated toothpaste variants. Stakeholders must monitor evolving herbal ingredient approval frameworks across ASEAN member states as traditional medicine integration accelerates.
Market Dynamics
India's BIS fluoride concentration mandates and China's GB labeling standards are forcing simultaneous reformulation across multinational and domestic manufacturing footprints, compressing product development cycles while elevating compliance costs for active ingredient disclosure.
Growth Catalysts
- Rural Penetration Acceleration:Indonesia's eastern provinces and Vietnam's Mekong Delta households are adopting packaged oral care as distribution networks extend beyond urban corridors, converting traditional powder users to paste formats.
- Herbal Ingredient Approval Frameworks:ASEAN member states are streamlining traditional medicine integration pathways, enabling neem and clove oil formulations to claim therapeutic positioning without quasi-drug classification delays.
- Enzymatic Whitening Technologies:Japanese consumer preferences for non-abrasive stain removal are pulling advanced catalytic systems into premium tier development, creating technology spillover effects for export-oriented production.
Market Restraints
- Sorbitol Price Volatility:Humectant input costs fluctuate with corn starch supply from Thailand and Indian agricultural output, squeezing margin structures for economy-tier producers dependent on bulk sweetener formulations.
- Fluoride Sourcing Concentration:Sodium fluoride and sodium monofluorophosphate supply clusters in Chinese chemical processing hubs, exposing formulation continuity risks from environmental compliance shutdowns or export licensing shifts.
- Tube Packaging Waste Regulations:Australia's TGA-aligned sustainability mandates and Singapore's extended producer responsibility schemes are constraining conventional laminate tube formats while viable alternatives remain cost-prohibitive at scale.
Strategic Opportunities
- Pump Format Premiumization:Urban retail channels in Australia and Singapore are demonstrating consumer willingness to pay packaging premiums for dispensing convenience, offering margin expansion paths beyond commodity paste positioning.
- Sensitivity Segment Expansion:Japan's aging demographics and South Korea's enamel erosion concerns are creating demand pull for potassium nitrate and arginine formulations that command therapeutic price premiums over standard fluoride variants.
- PLI Scheme Manufacturing Incentives:India's production-linked incentive framework for personal care inputs is attracting backward integration investments into surfactant and abrasive captive supply, reducing import dependency for domestic brands.
Industry Challenges
- Quasi-Drug Classification Complexity:Japan's PMDA oversight creates distinct approval pathways for medicated toothpaste variants, requiring separate stability testing and clinical documentation that extends time-to-market by 18-24 months versus cosmetic classifications.
- Herbal Ingredient Standardization:Ayurvedic and traditional Chinese medicine active sourcing lacks harmonized potency assays across BIS, GB, and ASEAN frameworks, forcing redundant quality verification at each regulatory boundary.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Toothpaste Market |
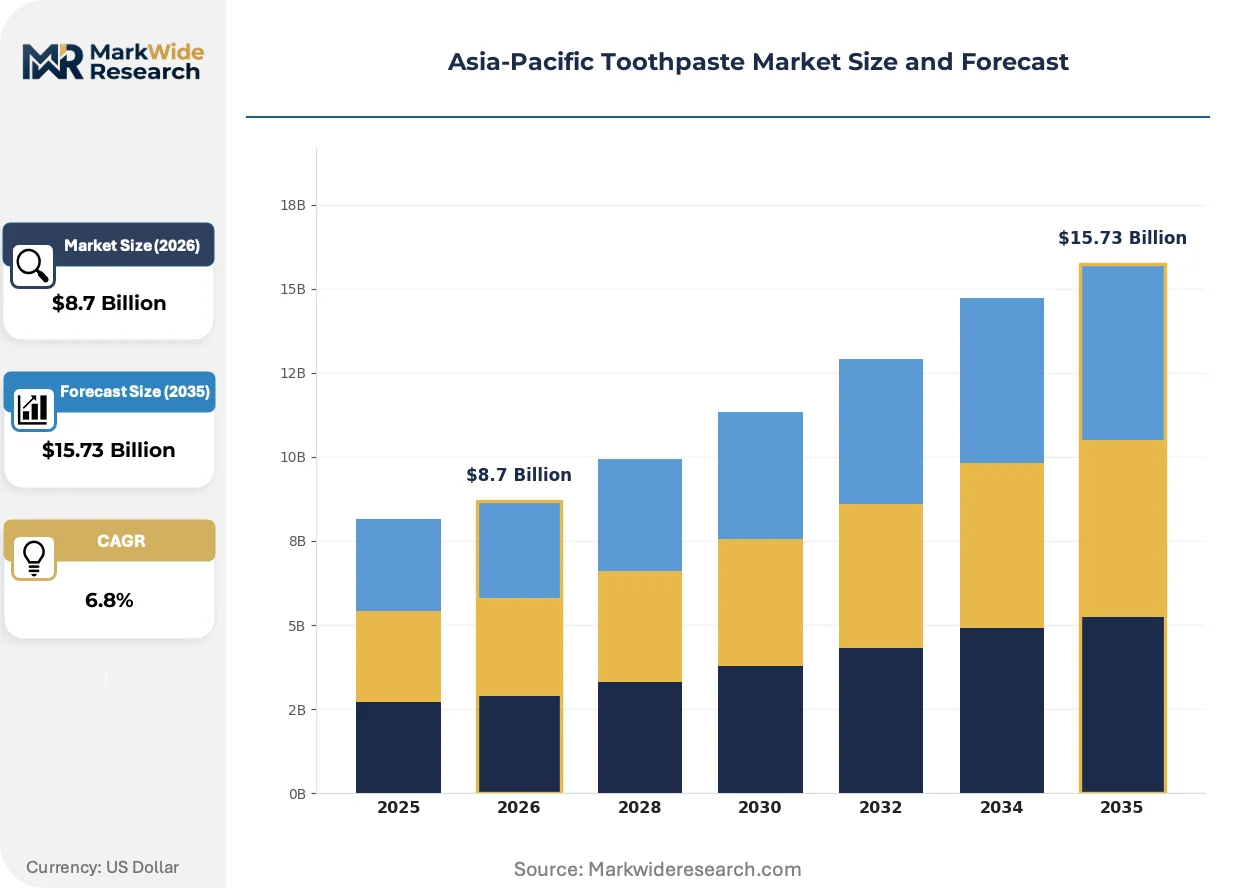
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fluoride, Herbal, Whitening, Sensitivity End User: Adults, Children, Seniors, Teens Packaging Type: Tubes, Pumps, Sachets, Jars Distribution Channel: Supermarkets, Pharmacies, Online, Convenience Stores |
| Companies Covered | GlaxoSmithKline, Johnson & Johnson, Colgate-Palmolive, Dabur India Ltd., Kao Corporation, Procter & Gamble, Lion Corporation, Himalaya Herbal Healthcare, Unilever, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Toothpaste Market Strategic Shifts
Formulation science is converging with digital quality assurance and sustainability mandates, reshaping how active ingredients are validated, how packaging is recovered, and how therapeutic claims are substantiated across heterogeneous regulatory environments.
Near-infrared spectroscopy coupled with blockchain traceability is digitizing raw material verification workflows. Thai and Malaysian herbal suppliers are adopting these systems to prove neem and clove oil provenance for export certification. The technology is digitizing compliance documentation, compressing audit timelines from weeks to hours while reducing adulteration disputes.
China's SAMR enforcement of GB standards on whitening efficacy labeling is restricting comparative advertising claims and mandating clinical substantiation thresholds. Manufacturers must now conduct in-vitro stain removal assays before marketing "whitening" positioning. Premium brands targeting Chinese urban consumers are responding by reformulating toward enzymatic systems that deliver measurable results under standardized test protocols.
Direct-to-consumer subscription models are displacing traditional wholesale pharmacy channels for sensitivity and pediatric specialty formulations. Australian metro buyers and Singaporean expatriate households are adopting auto-replenishment for premium variants, bypassing retail markups. This behavioral pivot is most visible in markets where e-commerce penetration exceeds 35% of personal care spending and same-day delivery infrastructure is mature.
Asia-Pacific Toothpaste Market Segmentation
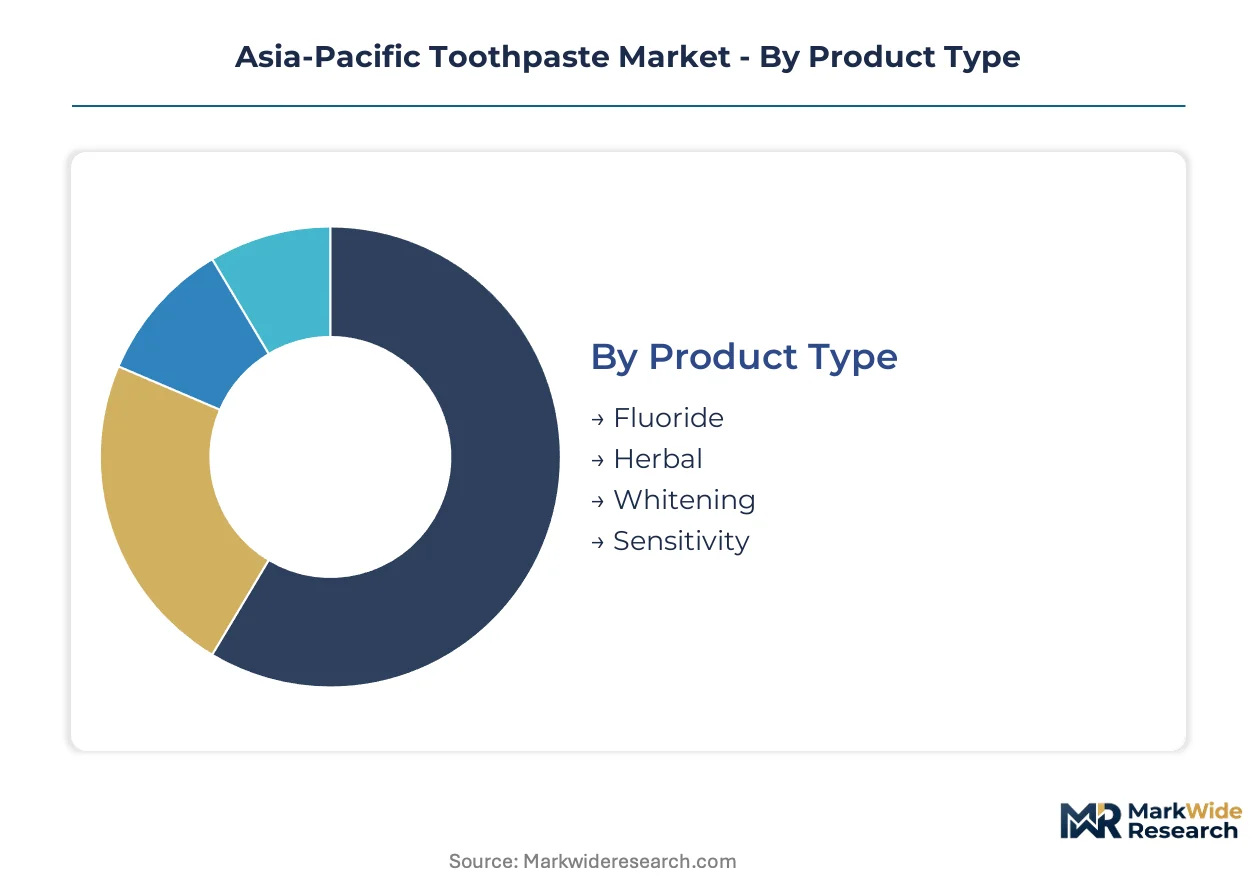
Segmentation in the Asia-Pacific toothpaste market reveals how formulation chemistry, demographic targeting, and retail infrastructure intersect to create distinct competitive battlegrounds. Manufacturers must align R&D investment with channel-specific margin structures and regulatory constraints that vary sharply across Indonesia's rural networks versus Singapore's premium urban retail.
Product Type:
After-sales service intensity varies dramatically across formulation categories, with medicated variants requiring pharmacovigilance support and herbal lines demanding traceability documentation that extends far beyond point-of-sale.
- Fluoride:Standard sodium fluoride and sodium monofluorophosphate formulations dominate volume production, engineered for caries prevention through enamel remineralization. Demand concentrates in India's tier-two cities and Vietnam's provincial capitals where BIS-compliant concentration limits shape reformulation costs for multinational manufacturers.
- Herbal:Neem, clove oil, and Ayurvedic extract systems command premium positioning through plant-derived antibacterial claims. Thai and Malaysian consumers drive category expansion as ASEAN traditional medicine frameworks streamline approval pathways for therapeutic positioning without quasi-drug delays.
- Whitening:Abrasive silica and enzymatic catalytic systems target stain removal efficacy.
- Sensitivity:Potassium nitrate and arginine formulations address dentin hypersensitivity in aging populations.
Fluoride holds the largest share; momentum sits with herbal formulations gaining therapeutic legitimacy.
End User:
Cost tier stratification separates pediatric specialty formulations with controlled fluoride dosing from economy adult variants competing on per-gram pricing in rural Indonesian and Vietnamese markets.
- Adults:The core volume segment spans standard maintenance formulations through premium therapeutic variants. Southeast Asian urban corridors and Indian metropolitan households drive demand for multi-benefit positioning combining whitening and sensitivity management in single formulations.
- Children:Low-fluoride and fluoride-free variants with flavor-optimized palatability profiles address safety-conscious parents. Australian and Singaporean regulatory environments enforce strict labeling for pediatric use, compressing allowable active ingredient ranges below adult thresholds.
- Seniors:Dry mouth and gum recession formulations target enamel erosion concerns.
- Teens:Aesthetic-focused variants with bold flavor profiles and social media-oriented packaging.
Adults generate the dominant revenue base; seniors represent the steepest expansion trajectory as demographic aging accelerates across Japan and South Korea.
Packaging Type:
Volume concentration in tube formats reflects established filling line infrastructure across Chinese and Indian contract manufacturing hubs, while pump systems remain niche due to higher per-unit conversion costs.
- Tubes:Laminate and aluminum barrier tubes retain cost efficiency at scale for economy and standard tiers. Indonesia's rural distribution networks and Vietnam's Mekong Delta retail channels depend on this format's durability through ambient temperature supply chains.
- Pumps:Airless dispensing systems command 40-60% packaging premiums in Australian and Singaporean urban retail. Consumer willingness to pay for convenience and precise dosing drives adoption among premium sensitivity and whitening variants.
- Sachets:Single-use foil pouches serve travel and trial-size demand.
- Jars:Wide-mouth containers dominate professional dental office dispensing channels.
Tubes maintain overwhelming volume dominance; pumps are climbing the fastest as premium retail formats expand.
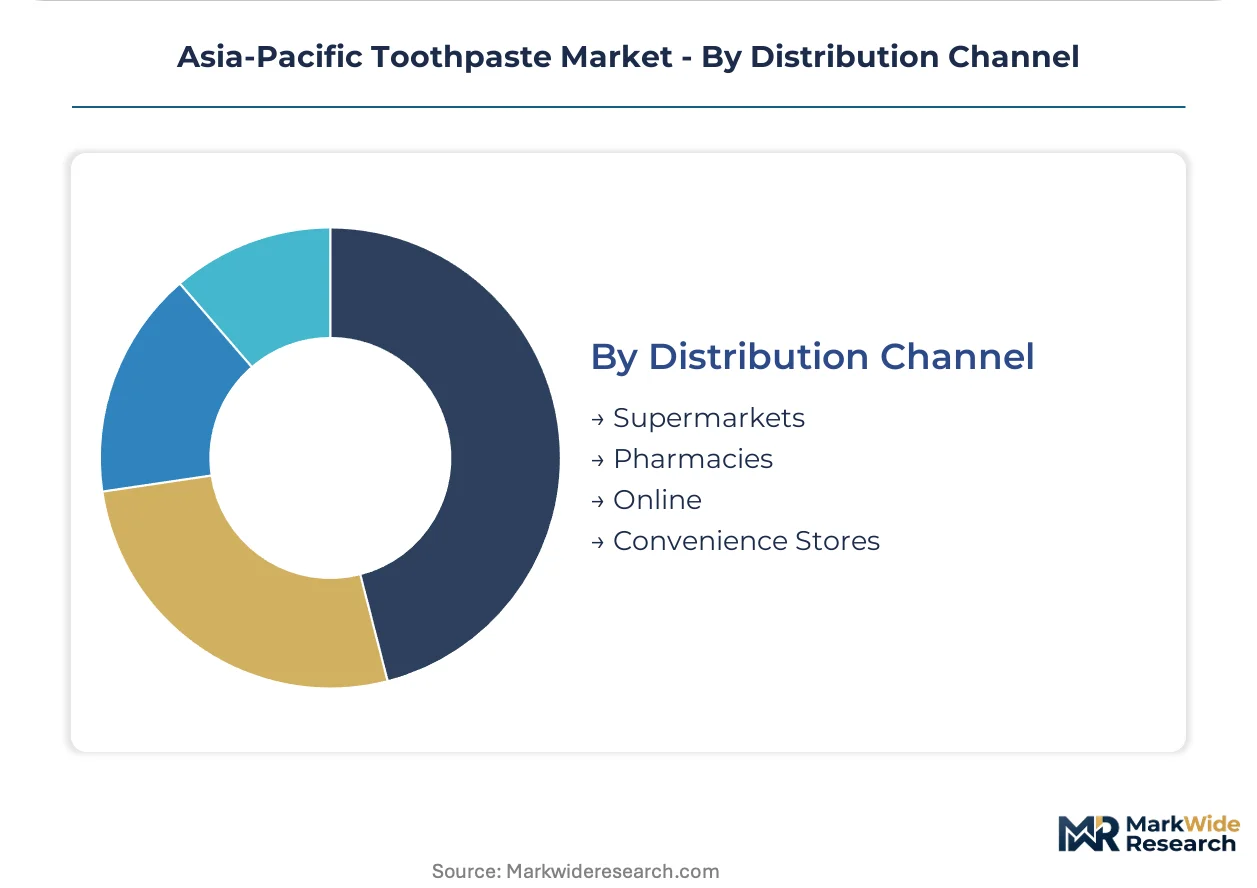
Distribution Channel:
Customer type fragmentation separates pharmacy-dependent medicated variants requiring clinical recommendation from impulse-purchase economy formats moving through convenience store networks.
- Supermarkets:Mass-market volume flows through modern trade formats in Indian tier-two cities and Southeast Asian urban corridors. Shelf space negotiations and promotional slotting fees determine brand visibility for standard fluoride and herbal variants competing on price-per-gram metrics.
- Pharmacies:Sensitivity and medicated formulations require pharmacist consultation in Japan's PMDA-regulated environment and Australia's TGA-aligned retail channels. Clinical substantiation documentation supports premium pricing for therapeutic claims.
- Online:Direct-to-consumer subscription models displace wholesale for specialty formulations.
- Convenience Stores:Emergency purchase and travel-size demand in dense urban catchments.
Supermarkets capture the greatest transaction volume; online channels are gaining share fastest where e-commerce penetration exceeds 35% of personal care spending.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for fluoride precursors and surfactant inputs shapes competitive positioning across Asia-Pacific manufacturing hubs. Export-oriented production in China and Thailand supplies regional formulation demand, while domestic consumption clusters concentrate in Indian tier-two cities and Southeast Asian urban corridors.
China
Fluoride chemical processing clusters in Jiangsu and Shandong provinces supply sodium monofluorophosphate to regional formulators. SAMR enforces GB standards on whitening efficacy claims and active ingredient disclosure. Yangtze River Delta contract manufacturers are expanding enzymatic toothpaste production for Japanese export markets.
India
Tier-two cities in Maharashtra and Gujarat drive volume demand for BIS-compliant fluoride formulations. The PLI scheme for personal care inputs attracts backward integration investments into surfactant and abrasive captive supply. Mumbai-Pune industrial corridors host multinational filling operations serving domestic retail networks.
Japan
Aging demographics in Kanto and Kansai regions pull potassium nitrate sensitivity formulations into pharmacy channels. PMDA quasi-drug classification creates 18-24 month approval timelines for medicated variants. Osaka-based manufacturers specialize in enzymatic whitening systems for premium domestic consumption.
Indonesia
Rural households in East Java and Sulawesi convert from traditional powder to packaged paste formats as distribution networks extend. The national pharmaceutical regulator monitors fluoride concentration in imported formulations. Surabaya logistics hubs coordinate last-mile delivery to provincial retail networks.
Vietnam
Mekong Delta provinces represent underpenetrated demand for economy-tier fluoride toothpaste. Ministry of Health circulars align with ASEAN cosmetic directive harmonization for herbal ingredient approvals. Ho Chi Minh City manufacturing zones assemble imported bulk paste for domestic sachet packaging.
Asia-Pacific Toothpaste Market Competitive Environment
On the supply side, the industry is consolidating around multinational formulators with captive distribution networks and regional specialists with herbal heritage positioning. Three archetypes dominate: scale-driven multinationals leveraging shelf-space negotiations, Ayurvedic heritage specialists commanding premium plant-derived positioning, and Japanese technology-focused developers of enzymatic systems. Competitive moves concentrate on backward integration into surfactant supply and pump-format packaging premiumization.
Within the multinational tier, Colgate-Palmolive and Unilever occupy positions defined by retail channel density and promotional scale across Indian and Southeast Asian markets. Dabur India Ltd. exemplifies the heritage-specialist archetype through Ayurvedic formulation credibility. Kao Corporation anchors the technology-differentiated segment with enzymatic whitening expertise developed for Japanese consumer preferences.
| Leading Market Players |
|---|
| GlaxoSmithKline |
| Johnson & Johnson |
| Colgate-Palmolive |
| Dabur India Ltd. |
| Kao Corporation |
| Procter & Gamble |
| Lion Corporation |
| Himalaya Herbal Healthcare |
| Unilever |
| Others |
Value Chain & Pricing Dynamics
Chinese chemical processing hubs in Jiangsu and Shandong provinces concentrate sodium fluoride and sodium monofluorophosphate production, anchoring margin pools downstream with contract manufacturers and multinational formulators who face reformulation cost spikes when environmental compliance triggers supply interruptions.
Pricing Analysis
Urban retail buyers in Australia and Singapore anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation separates pump-format sensitivity formulations from tube-based fluoride variants through packaging convenience premiums and therapeutic claim substantiation. Cost compression in economy tiers is intensifying because sorbitol input costs fluctuate with Thai and Indian agricultural output. Rural Indonesian households exhibit highest price sensitivity, while aging Japanese consumers in pharmacy channels accept therapeutic premiums for potassium nitrate formulations.
Supply Chain Analysis
Upstream sorbitol feedstock draws from corn starch processing in Thailand and India, while surfactant and abrasive inputs concentrate in Chinese and Indian manufacturing zones. Sodium fluoride supply hinges on environmental licensing stability in Jiangsu province chemical clusters. Single-source vulnerability runs through fluoride precursor dependence on Chinese export licensing. Distribution runs through Surabaya logistics hubs for Indonesian provincial retail and Mumbai-Pune industrial corridors for Indian domestic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Natural ingredient fragmentation across the Asia-Pacific toothpaste market creates multiple niche entry points as consumers in Thailand and Malaysia shift toward plant-derived antibacterial systems.
For Market Incumbents: Build regulatory compliance moats through BIS certification investments in Indian manufacturing footprints and PMDA quasi-drug pathway expertise for Japanese medicated variants. Captive surfactant supply via India's PLI scheme reduces import dependency exposure. Channel control through direct-to-consumer subscription infrastructure in Australian and Singaporean e-commerce corridors defends against retail margin compression. For New Entrants and Emerging Players: Vietnam's Mekong Delta provinces offer underpenetrated demand for economy-tier fluoride toothpaste as distribution networks extend beyond Ho Chi Minh City manufacturing zones. Herbal ingredient approval frameworks across ASEAN member states enable neem and clove oil positioning without quasi-drug classification delays. Pediatric specialty formulations with controlled fluoride dosing target safety-conscious parents through pharmacy channel partnerships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Ayurvedic heritage brands possessing BIS-compliant manufacturing infrastructure but limited Southeast Asian distribution reach. Five-to-ten year viability depends on capturing pump-format premiumization in Australian urban retail and enzymatic technology licensing to Japanese export markets. Watch for fluoride sourcing concentration disruptions in Chinese chemical processing hubs as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Surfactant Supply | India's PLI scheme attracts captive production investments, reducing import dependency for domestic brands. |
| Pump Format Premiumization | Airless dispensing systems command packaging premiums in Australian and Singaporean urban retail channels. |
| Herbal Ingredient Traceability Systems | Near-infrared spectroscopy with blockchain compresses audit timelines for Thai and Malaysian neem suppliers. |
| Direct-to-Consumer Subscription Launch | Auto-replenishment models bypass retail markups for sensitivity formulations in high e-commerce penetration markets. |
| Enzymatic Whitening Technology Licensing | Osaka-based manufacturers export catalytic systems to premium tier developers serving Japanese consumer preferences. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade records, and retail audit databases. Category buyers at Indonesian and Vietnamese distributors, brand managers at multinational formulators, and procurement leads at Chinese fluoride chemical processors provided operational perspectives. BIS certification documentation, SAMR GB standard enforcement records, and ASEAN cosmetic directive harmonization circulars supplied secondary validation. Bottom-up volume modeling triangulates against top-down value estimates across formulation chemistry segments.
Forecast inputs span product type dimensions including fluoride, herbal, whitening, and sensitivity formulations alongside end-user categories and packaging format tiers. CAGRs derive from segment-level growth trajectory analysis calibrated to rural penetration rates and regulatory reformulation cost impacts. Enzymatic technology adoption curves in Japanese premium channels and herbal ingredient approval pathway streamlining across ASEAN frameworks inform projection parameters throughout the forecast period.
Practitioners should monitor fluoride export licensing shifts in Chinese chemical processing hubs and sorbitol agricultural output volatility in Thailand for early signals requiring forecast revision. Cross-checking against Nielsen retail audit data for Indian tier-two city shelf-space dynamics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Materials
Fluoride-Free Toothpaste Market
Dental Materials
Tooth Filling Materials Market
Dental Materials
Teeth Whitening Market
Dental Materials
Global Endodontic Consumables Market
Dental Materials
Dental Biomaterials Market
Dental Materials
Global Dental Zirconia Block Market
Dental Materials
Dental Fiber Posts Market
Dental Materials
Dental Restorative and Regenerative Material Market
Dental Materials
Crack Tooth Syndrome Market
Dental Materials
Global Dental Cements Market
Dental Materials
Charcoal Teeth Whitening Powder Market
Dental Materials
Global Dental Membrane and Bone Graft Substitutes Market
Dental Materials
Dental Bleaching Materials Market
Dental Materials
Dental Putty Market
Dental Materials
Acrylic Dental Material Market
Dental Materials
Dental Fiberglass Posts Market