
 Toothpaste Market | 2026-2036
Toothpaste Market Size, Share, and Industry Trends Forecast 2026-2036
Toothpaste Market Intelligence
Cosmetic chemist expertise in fluoride stabilization and enamel-safe whitening actives is redrawing competitive boundaries in oral care formulation. Colgate-Palmolive Company leverages its captive supply of silica abrasives to control gel-to-paste cost curves across Latin American plants. Unilever PLC anchors its herbal portfolio through ayurvedic ingredient partnerships in Gujarat and Kerala. Procter & Gamble competes on clinical-claim substantiation, sustaining premium positioning in North American pharmacy channels.
Toothpaste comprises a dentifrice preparation containing abrasive agents, humectants, surfactants, and therapeutic actives such as sodium fluoride or potassium nitrate, manufactured through high-shear mixing and vacuum deaeration to achieve rheological stability; its primary commercial purpose is mechanical plaque removal combined with preventive or cosmetic oral health benefits. The whitening product type captures disproportionate margin pools in developed markets where peroxide-based and optical-brightener formulations command shelf-price premiums. Herbal formulations dominate volume in South Asian retail, though gel-based delivery is displacing traditional paste in Southeast Asian convenience channels. Sachet packaging extends trial access in price-sensitive segments without eroding tube-based brand equity.
The FDA regulates anticavity claims and fluoride concentrations through over-the-counter drug monographs, while India's BIS mandates heavy-metal limits for herbal dentifrices, and the EU Green Deal's packaging-waste directives are forcing tube-material transitions across European manufacturing. These overlapping compliance layers elevate R&D spend for multi-market portfolios. Stakeholders must monitor biodegradable polymer scalability and regional claim-substantiation divergence to protect cross-border product architectures.
Market Dynamics
India's BIS certification requirements for herbal toothpaste formulations are compressing formulation timelines and forcing ingredient-traceability investments across South Asian export corridors, while silica abrasive supply concentration in Latin America tightens margin levers for gel-based production.
Growth Catalysts
- Pediatric oral care awareness:School-based dental screening programs in India's urban tier-2 cities are expanding the children's end-user segment faster than adult whitening demand.
- REACH-compliant tube materials:EU Green Deal packaging-waste directives are accelerating biodegradable polymer adoption, creating first-mover advantages for European manufacturers with scalable bio-polymer supply chains.
- Sachet packaging innovation:Single-use sachets are penetrating price-sensitive segments in Southeast Asian convenience channels without cannibalizing tube-based brand equity.
Market Restraints
- Silica abrasive concentration:Captive supply control by integrated multinationals in Brazil and Mexico limits independent brand access to cost-competitive gel formulations.
- Heavy-metal testing costs:India's BIS mandates for herbal dentifrices impose laboratory certification burdens that disproportionately burden small-scale ayurvedic producers.
- Peroxide whitening substitution:Optical brightener formulations are capturing pharmacy-channel shelf space from traditional peroxide systems due to enamel-safety concerns.
Strategic Opportunities
- Ayurvedic ingredient partnerships:Gujarat and Kerala supply clusters offer vertical integration pathways for brands seeking BIS-compliant herbal actives with documented traceability.
- Tier-2 city manufacturing scale:India's regional brands are consolidating production capacity in Indore, Coimbatore, and Lucknow to serve underpenetrated northern and central markets.
- Pharmacy-channel clinical substantiation:North American retailers are prioritizing FDA-monograph-compliant anticavity claims, rewarding brands with invested dental-advisory relationships.
Industry Challenges
- Fluoride stabilization expertise:Cosmetic chemist scarcity in high-shear mixing and vacuum deaeration is extending product-development cycles for therapeutic-claim formulations.
- Multi-jurisdiction dossier management:Overlapping FDA, BIS, and EU regulatory layers are elevating R&D spend for portfolios spanning three or more compliance regimes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Toothpaste Market |
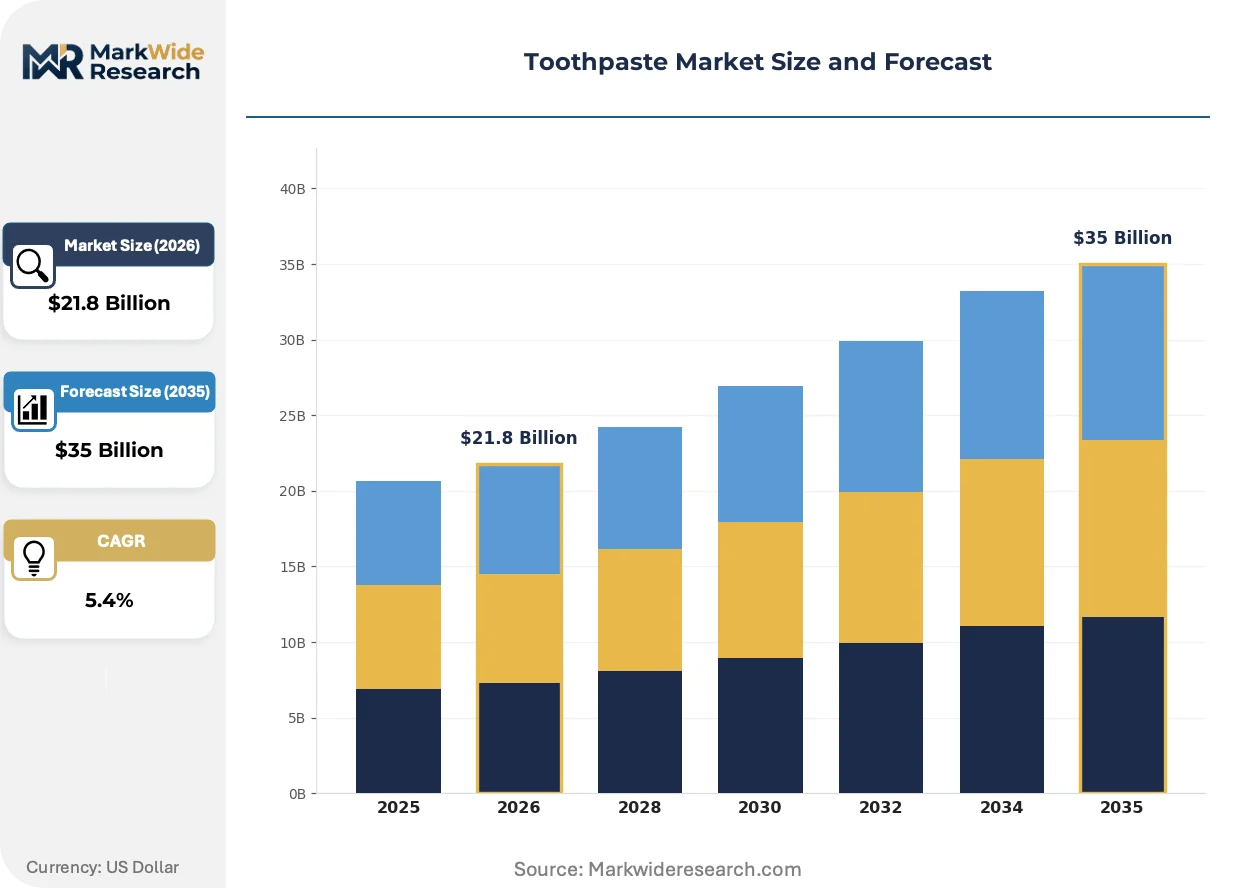
| Market Size in 2026 | $21.8 Billion |
| Market Size in 2035 | $35 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whitening, Sensitivity, Herbal, Fluoride Formulation: Gel, Paste, Powder, Foam Packaging Type: Tube, Bottle, Jar, Sachet End User: Adults, Children, Seniors, Special Needs |
| Companies Covered | Colgate-Palmolive Company, The Procter & Gamble Company, Unilever PLC, Haleon PLC, GlaxoSmithKline PLC, Lion Corporation, Church & Dwight Co., Inc., Dabur Ltd., Tom's of Maine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Toothpaste Market Strategic Shifts & Innovations
Formulation science and packaging material evolution are redrawing competitive boundaries, with regulatory compliance emerging as a product-differentiation mechanism rather than a cost center.
Enzymatic whitening systems are supplanting peroxide-based chemistries in premium European and North American pharmacy channels. Dental professionals are recommending these formulations for patients with enamel sensitivity or restoration work. The shift is compressing traditional peroxide margins while expanding the addressable patient base for cosmetic oral care.
India's BIS heavy-metal limits for herbal dentifrices are forcing ingredient-sourcing restructuring across South Asian export corridors. Manufacturers must now document ayurvedic supply chains from farm to tube, with testing protocols adding six to eight weeks to product launch timelines. Kerala and Gujarat processing facilities are investing in in-house spectrometry to preserve speed-to-market.
Convenience-channel sachet formats are fragmenting traditional retail concentration in Southeast Asian urban markets. Younger consumers in Jakarta, Manila, and Ho Chi Minh City are purchasing single-use packs from street kiosks and transit-station vending, bypassing supermarket distribution entirely. Tube brands are responding with parallel sachet SKUs that maintain price architecture without diluting premium positioning.
Toothpaste Market Segmentation
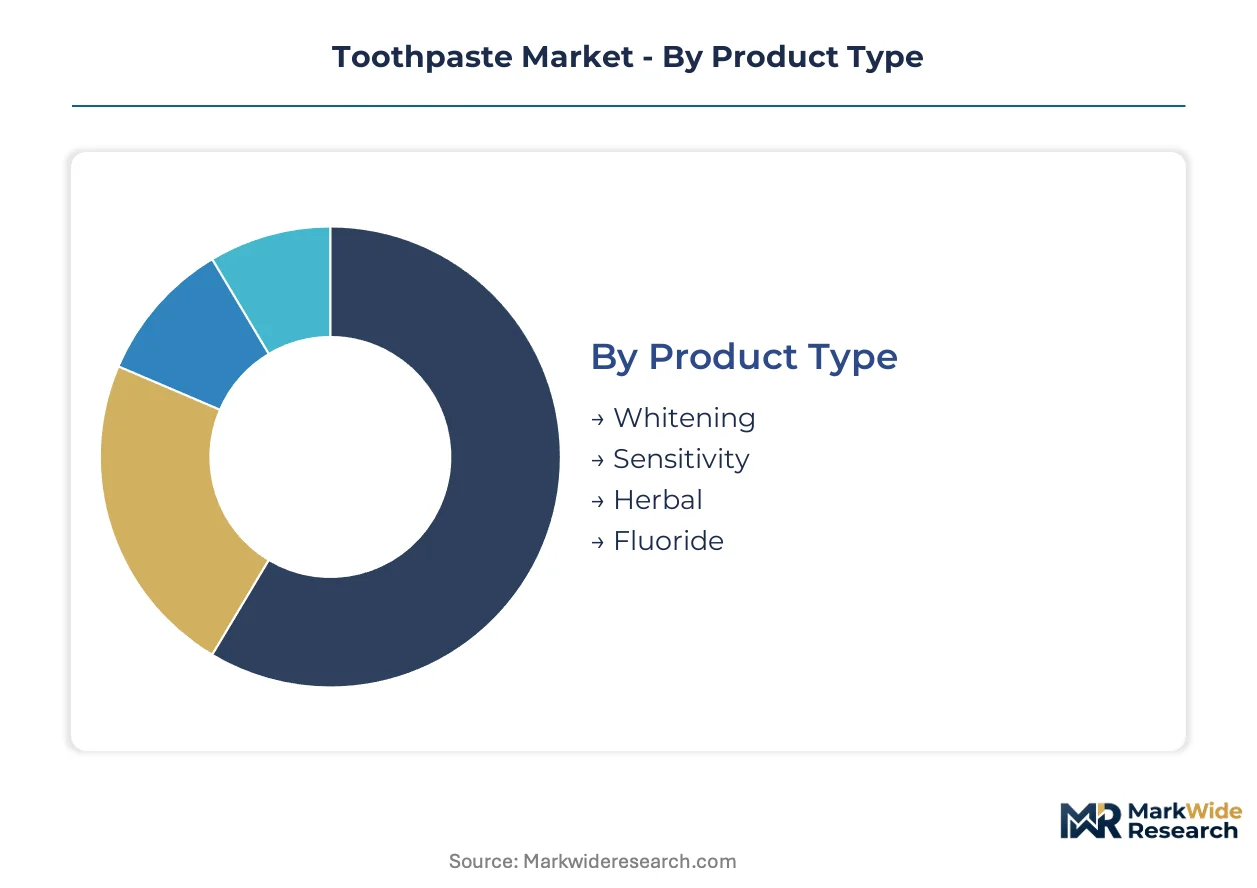
Toothpaste segmentation reveals divergent growth trajectories across formulation science, packaging economics, and demographic targeting. Understanding these fault lines enables precise resource allocation across R&D, manufacturing scale, and channel strategy.
Product Type:
Whitening and herbal formulations operate on fundamentally different geographic circuits—whitening concentrates in pharmacy-led developed markets, while herbal dominates South Asian retail and export corridors.
- Whitening:Peroxide-based and optical-brightener chemistries target enamel aesthetics with clinical-claim substantiation. Demand clusters in North American pharmacy channels where dental professional recommendations drive premium shelf positioning.
- Sensitivity:Potassium nitrate and strontium chloride formulations address dentin hypersensitivity through nerve desensitization. Growth concentrates among aging populations in Western Europe and Japan where enamel erosion prevalence expands the addressable patient base.
- Herbal:Ayurvedic and botanical actives without synthetic fluoride, requiring BIS heavy-metal certification for Indian market access. Kerala and Gujarat processing clusters supply export corridors across South Asia and Middle Eastern markets.
- Fluoride:Sodium fluoride and sodium monofluorophosphate preparations for anticavity claims under FDA monograph regulation. Volume leadership in mass retail across Latin America and Southeast Asia where clinical endorsement carries less purchase influence.
Fluoride formulations hold the largest share; momentum sits with herbal variants as BIS-compliant supply chains achieve export scalability.
Formulation:
Cost tier differentiation separates premium gel delivery systems from economy paste formats, with powder and foam occupying niche functional positions.
- Gel:Silica-thickened aqueous systems with transparent aesthetics and controlled rheology. Silica abrasive supply concentration in Brazil and Mexico tightens margin structures for independent brands seeking Latin American manufacturing scale.
- Paste:Traditional calcium carbonate or dicalcium phosphate abrasives in opaque cream bases. Volume concentration in India's tier-2 cities where regional manufacturers consolidate production capacity in Indore and Lucknow.
- Powder:Dry abrasive and detergent blends requiring consumer reconstitution. Niche positioning in zero-waste retail channels across Germany and Scandinavia where packaging-minimization preferences override convenience expectations.
- Foam:Aerosolized or pump-dispensed formulations with instant lather generation. Limited adoption in Japanese convenience retail where compact packaging dimensions outweigh per-use cost premiums.
Paste maintains volume dominance; gel is climbing the fastest as Southeast Asian consumers shift from traditional cream formats.
Packaging Type:
Application context and price sensitivity fragment packaging selection—tube formats defend brand equity while sachets unlock trial access in emerging channels.
- Tube:Laminated aluminum-plastic or all-plastic extrusions with flip-cap or screw-cap closure. Pharmacy-channel premium positioning in the United States and Canada depends on tube aesthetics and dispensing ergonomics.
- Bottle:Pump or squeeze dispensers for liquid gel or mouthwash-toothpaste hybrid formulations. Limited traction outside South Korean and Thai markets where multi-functional oral care commands shelf space.
- Jar:Wide-mouth containers for powder or tablet formats. Minimal penetration restricted to specialty zero-waste retailers in France and the United Kingdom where refill economics justify packaging investment.
- Sachet:Single-use foil or film pouches containing 5-10 gram portions. Jakarta, Manila, and Ho Chi Minh City transit kiosks drive volume without cannibalizing tube-based brand architecture in supermarket channels.
Tube formats capture the largest share; sachet distribution is gaining share fastest through Southeast Asian convenience fragmentation.
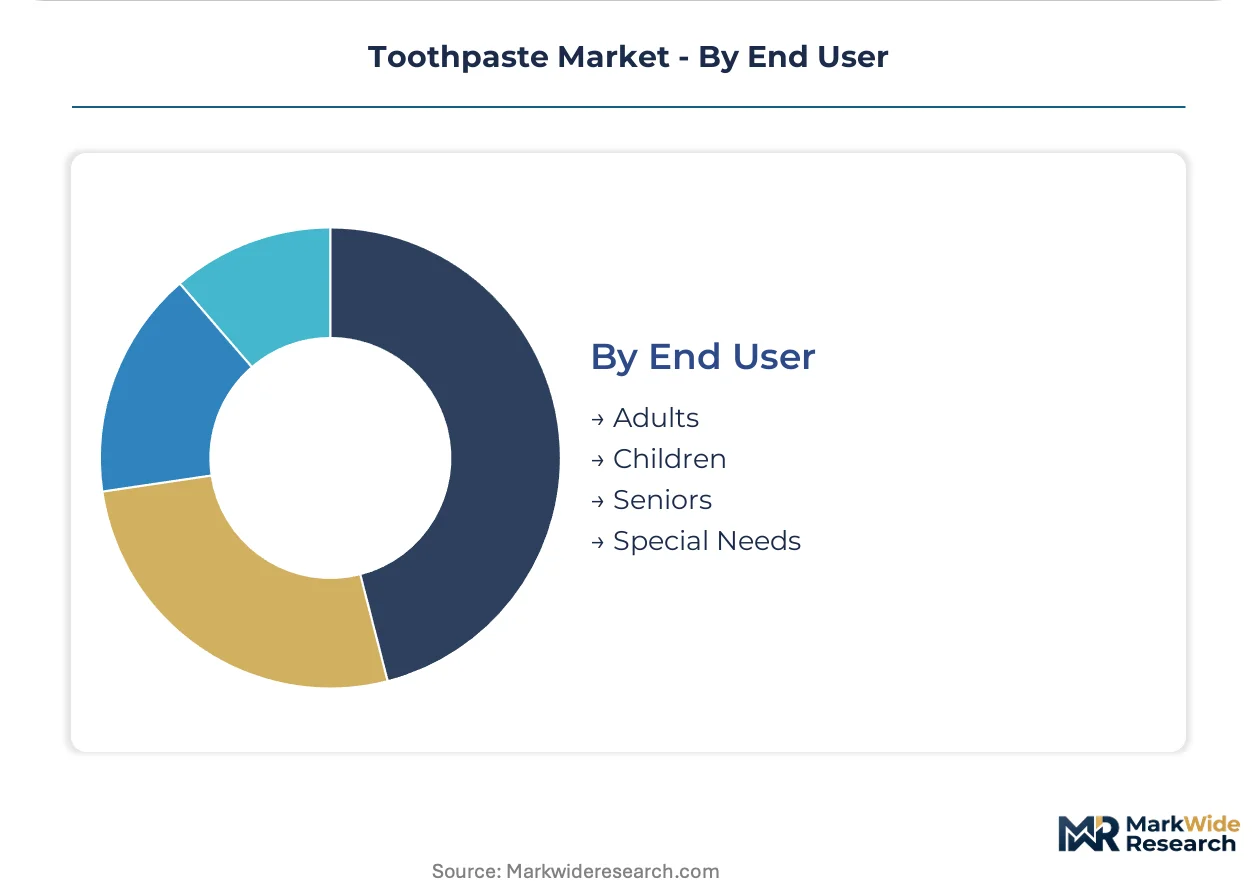
End User:
Customer type segmentation aligns product safety profiles, flavor systems, and clinical claim intensity with physiological life stages and functional requirements.
- Adults:Full-strength fluoride and peroxide formulations with mint-dominant flavor profiles. Whitening and sensitivity subsegments concentrate purchase decisions among urban professionals in São Paulo and Mexico City.
- Children:Low-fluoride or fluoride-free formulations with fruit flavors and swallow-safe ingredient decks. India's school-based dental screening programs in urban tier-2 cities expand this segment faster than adult whitening demand.
- Seniors:Dry-mouth formulations with salivary stimulants and gentle abrasives for recession-exposed root surfaces. Growth correlates with aging demographics in Italy and Spain where pharmacy-channel professional endorsement drives selection.
- Special Needs:Foam and rinse formulations for patients with swallowing difficulties or caregiver-assisted oral hygiene. Institutional procurement through healthcare systems in Australia and the Netherlands determines accessible formulation availability.
Adult segments hold the largest share; children's formulations show the steepest expansion trajectory as pediatric oral care awareness penetrates South Asian middle-income households.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
BIS certification requirements for herbal toothpaste formulations are compressing supply chain timelines across South Asian export corridors, while FDA monograph compliance shapes competitive positioning in North American pharmacy channels. India's tier-2 urban markets and Brazil's silica supply clusters anchor volume concentration. Regulatory divergence between heavy-metal testing mandates and biodegradable packaging directives fragments multi-jurisdiction product architectures.
United States
Pharmacy-channel whitening demand concentrates among dental-professional-recommended brands with clinical-claim substantiation. FDA over-the-counter drug monographs regulate anticavity claims and fluoride concentrations, elevating R&D spend for therapeutic-positioned portfolios. Manufacturing scale clusters in New Jersey and Ohio, where contract manufacturers serve private-label and branded clients with high-shear mixing capacity.
India
School-based dental screening programs in urban tier-2 cities expand pediatric oral care penetration faster than adult whitening adoption. BIS mandates heavy-metal limits for herbal dentifrices, forcing Kerala and Gujarat processing facilities to invest in in-house spectrometry. Indore, Coimbatore, and Lucknow consolidate regional manufacturing capacity to serve underpenetrated northern and central markets.
Brazil
Silica abrasive supply concentration tightens margin structures for gel-based production, with integrated multinationals controlling captive supply chains. ANVISA regulates cosmetic and therapeutic oral care claims, requiring local clinical substantiation for peroxide whitening formulations. São Paulo anchors production gravity for Latin American export corridors, with regional brands scaling capacity to compete on paste-format cost curves.
Germany
EU Green Deal packaging-waste directives accelerate biodegradable polymer adoption, rewarding manufacturers with scalable bio-polymer supply chains. REACH-compliant tube materials command premium positioning in pharmacy and zero-waste retail channels. Bavarian chemical clusters develop enzymatic whitening actives for enamel-sensitive patient segments, displacing traditional peroxide systems in professional recommendations.
Japan
Aging demographics expand sensitivity-formulation demand through pharmacy and convenience channels. METI and PMDA oversight of quasi-drug claims requires local clinical testing for therapeutic oral care positioning. Kansai region manufacturing concentrates on compact foam and liquid formats for convenience retail, where packaging dimensions outweigh per-use cost premiums.
Toothpaste Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes in oral care formulation. Integrated multinationals with captive silica supply and ayurvedic ingredient partnerships command premium positioning through clinical-claim substantiation and regulatory compliance depth. Mid-scale regional manufacturers compete on paste-format cost curves in price-sensitive segments. Dominant competitive moves include strategic partnerships with Kerala and Gujarat processing clusters for BIS-compliant herbal actives, and capacity consolidation in India's tier-2 manufacturing hubs.
Among diversified consumer goods conglomerates, Colgate-Palmolive Company, Unilever PLC, and Procter & Gamble exemplify archetypes spanning integrated supply control, ayurvedic partnership networks, and clinical-claim substantiation respectively. Haleon PLC and GlaxoSmithKline PLC occupy positions anchored in pharmacy-channel professional endorsement. Lion Corporation represents Japanese-scale precision in compact-format innovation, while Dabur Ltd. exemplifies regional herbal leadership with documented South Asian supply chain traceability. Church & Dwight Co., Inc. and Tom's of Maine sit within naturals-positioned tiers, competing on ingredient transparency and sustainability credentials rather than therapeutic-claim intensity.
| Leading Market Players |
|---|
| Colgate-Palmolive Company |
| The Procter & Gamble Company |
| Unilever PLC |
| Haleon PLC |
| GlaxoSmithKline PLC |
| Lion Corporation |
| Church & Dwight Co., Inc. |
| Dabur Ltd. |
| Tom's of Maine |
| Others |
Cost & Logistics Intelligence
Optical brightener substitution for peroxide-based whitening actives is redrawing supply geography toward Bavarian enzymatic chemistry clusters while compressing margin structures for traditional peroxide suppliers in North American pharmacy channels. This ingredient transition simultaneously elevates R&D spend for enamel-safe formulation expertise and fragments procurement leverage across incompatible raw material networks.
Pricing Analysis
Geographic price spreads between pharmacy-channel whitening formulations in the United States and sachet-packaged economy variants in Southeast Asian convenience channels exceed threefold at equivalent volume tiers. Three-tier pricing structure across premium clinical-substantiated, standard mass-retail, and economy sachet levels reflects brand equity intensity and regulatory compliance depth. Cost compression in economy paste segments is intensifying because regional Indian manufacturers consolidate capacity in Indore and Lucknow. Price-sensitive buyers in Southeast Asian transit kiosks drive volume through single-use formats, while least-sensitive purchasers in North American pharmacy channels prioritize dental professional endorsement over per-unit cost.
Supply Chain Analysis
Strategic stockpiling of silica abrasives dominates inventory strategy among integrated multinationals with captive Brazilian and Mexican supply chains, while independent brands maintain lean just-in-time positions vulnerable to spot-market volatility. Geographic supply concentration centers on Brazil and Mexico for silica gel thickeners, India for ayurvedic herbal actives, and Germany for enzymatic whitening precursors. Raw material dependencies hinge on potassium nitrate for sensitivity formulations, peroxide and optical brightener chemistries for whitening, and fluoride compounds for anticavity claims. Single-source vulnerability concentrates in Latin American silica supply where integrated multinationals control captive production. Distribution runs through pharmacy channels in developed markets and fragmented convenience retail in Southeast Asian urban centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based replenishment programs and dental professional recommendation networks represent service-attach layers expanding faster than base toothpaste formulation sales, creating recurring revenue pools with superior retention economics.
For Market Incumbents: Secure BIS-compliant herbal supply chain documentation through Kerala and Gujarat processing partnerships before certification timelines compress further. Defend pharmacy-channel positioning through invested dental-advisory relationships that substantiate clinical claims under FDA monograph requirements. Capacity consolidation in India's tier-2 manufacturing hubs offers cost curve protection against regional brand expansion. For New Entrants and Emerging Players: Anchor in Southeast Asian sachet distribution through transit-kiosk and vending-machine networks that bypass established supermarket gatekeepers. India's urban tier-2 pediatric oral care segment presents the most penetrable white space given school-based screening program expansion. Direct-to-clinic sampling programs build dental professional familiarity without competing for pharmacy shelf space against entrenched clinical brands. For Investors and Strategic Acquirers: The market sits at a regulatory-intensification phase that favors vertically integrated manufacturers with multi-jurisdiction compliance dossiers. Long-term viability over the next decade rests on backward integration into ayurvedic ingredient sourcing and biodegradable polymer supply chains. Acquisition targets should demonstrate documented heavy-metal testing protocols and scalable bio-polymer tube material relationships. The signal to watch is BIS certification timeline compression that would strand non-compliant herbal inventory.| Strategic Initiative | Industry Significance |
|---|---|
| Ayurvedic Supply Chain Integration | Kerala and Gujarat processing partnerships ensure BIS heavy-metal compliance for herbal export corridors. |
| Enzymatic Whitening R&D Investment | Bavarian chemistry clusters develop enamel-safe actives displacing peroxide in professional recommendations. |
| Biodegradable Polymer Scale-Up | EU Green Deal compliance creates first-mover advantage for REACH-certified tube material supply chains. |
| Tier-2 Manufacturing Consolidation | Indore, Coimbatore, and Lucknow capacity serves underpenetrated northern and central Indian markets. |
| Pharmacy-Channel Clinical Substantiation | FDA-monograph-compliant anticavity claims defend premium positioning against mass-retail private labels. |
Research Approach
Operator-level perspectives from cosmetic chemists, toothpaste plant managers, pharmacy category buyers, and BIS certification laboratory directors anchored the qualitative base for this study. Primary field engagement combined structured interviews with secondary validation through FDA over-the-counter drug monographs, BIS dentifrice standards documentation, EU Green Deal packaging directives, and retail audit data from Nielsen and Circana. Bottom-up volume modeling from individual product SKUs and top-down macroeconomic triangulation ensured cross-verified outputs across the analysis window.
Sensitivity analysis tested forecast robustness against regulatory timeline compression, raw material price volatility, and channel-shift scenarios throughout the projection horizon. Segmentation dimensions modeled include product type, formulation science, packaging format, end-user demographic, and regional regulatory cluster. CAGRs derived from historical trajectory analysis and forward-looking adoption curve assumptions incorporated enzymatic whitening substitution rates and sachet packaging penetration in Southeast Asian convenience channels as industry-specific inputs.
Decision-makers should treat outputs as directional under stable regulatory enforcement intensity and intact silica supply chain configurations; material deviation would warrant model refresh. Forecasts reflect assumptions regarding BIS certification timeline adherence, EU biodegradable polymer scalability, and pharmacy-channel clinical endorsement continuity. Revision becomes warranted when BIS heavy-metal testing protocol changes or EU packaging-waste directive enforcement thresholds cross materiality boundaries.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Materials
Dental Impression Material Market
Dental Materials
Global Endodontic Consumables Market
Dental Materials
Artificial Teeth Market
Dental Materials
Cold Light Teeth Whitening Kit Market
Dental Materials
Dental Fiber Posts Market
Dental Materials
Dental Polymerization Lamps Market
Dental Materials
Australia and New Zealand Dental Biomaterials Market
Dental Materials
Dental Fluoride Varnish Market
Dental Materials
Global Dental Zirconia Block Market
Dental Materials
Dental Alloys Market
Dental Materials
Dental Materials for 3D Printing Market
Dental Materials
Charcoal Teeth Whitening Powder Market
Dental Materials
Remineralizing Gum Market
Dental Materials
Global Dental Cements Market
Dental Materials
Dental Amalgam Market
Dental Materials
Sensitive Toothpaste Market