
 Zirconia Ceramic Balls Market | 2026-2036
Zirconia Ceramic Balls Market Size, Share, and Industry Trends Forecast 2026-2036
Zirconia Ceramic Balls Market Analysis
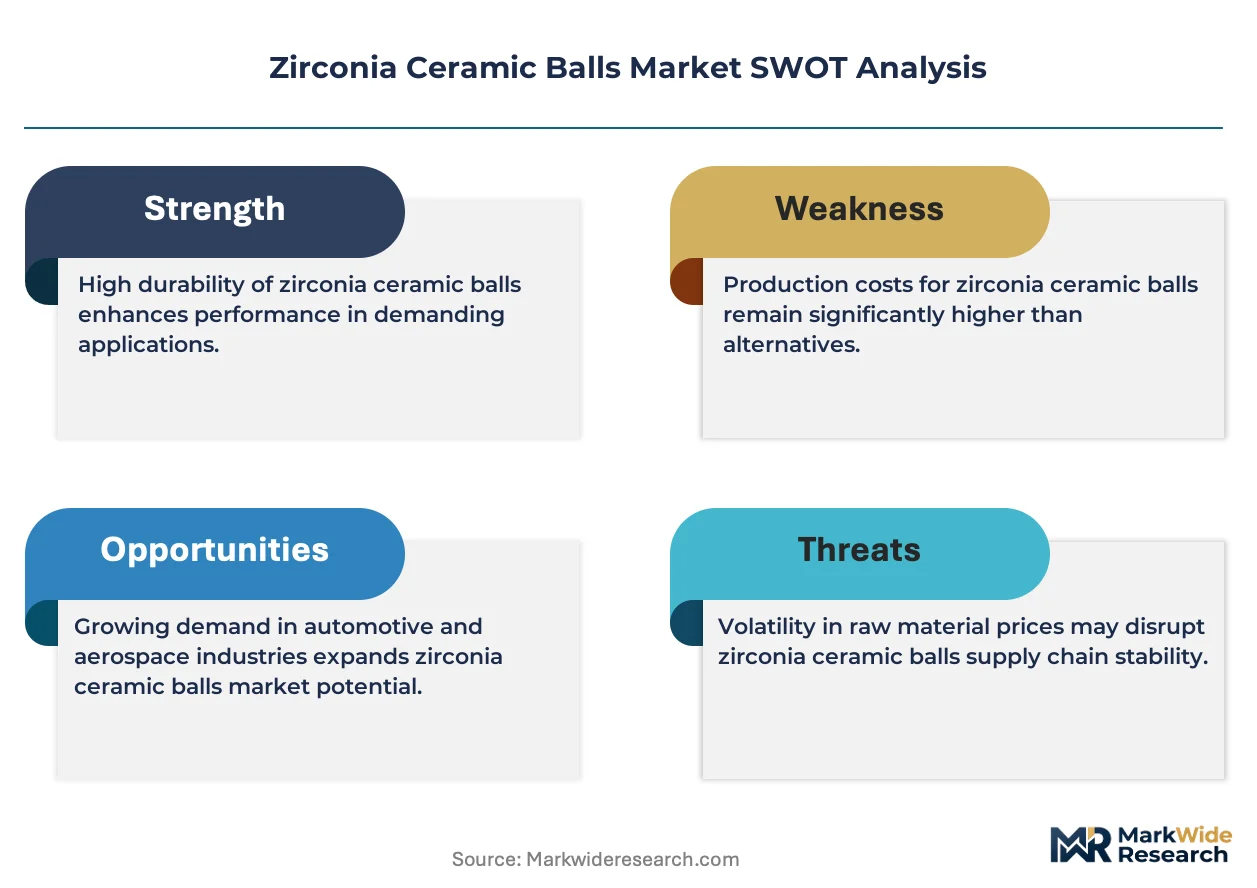
Asset-light leasing models for precision grinding equipment is reconfiguring capital barriers for mid-size ceramic processors. CoorsTek, Inc. leverages captive supply chains across North American technical ceramics to sustain pricing power in yttria-stabilized grades. Kyocera Corporation anchors its position through in-house powder synthesis that reduces lot-to-lot variability for medical device customers. Toshiba Materials Co., Ltd. competes on dimensional tolerances below one micron for semiconductor polishing applications.
Zirconia ceramic balls are precision-engineered spheres manufactured from zirconium dioxide, typically stabilized with yttria to achieve fracture toughness exceeding 10 MPa·m½ and density near 6.0 g/cm³, serving primarily as wear-resistant media, bearing components, and grinding elements in aggressive chemical or thermal environments. Yttria-stabilized zirconia dominates volume due to its phase stability across temperature swings, while coated zirconia commands margin premiums in oil & gas downhole tools where corrosive fluids degrade unprotected surfaces. Solid balls anchor the form category for standard bearing retrofits, though hollow balls are gaining traction in aerospace weight-reduction programs where every gram of unsprung mass affects fuel efficiency.
FDA biocompatibility protocols for implantable devices and EPA emissions standards for ceramic firing kilns are elevating certification costs for new entrants. REACH substance restrictions in the European Union limit certain stabilizer chemistries, pushing reformulation toward cleaner yttria-dopant systems. ISO 13356 for surgical implant-grade zirconia and JIS standards in Japan create multi-jurisdictional testing burdens that favor established laboratories with accredited metrology suites. Stakeholders must track evolving purity thresholds across medical and aerospace qualification pathways to avoid stranded inventory.
Market Dynamics
Ball bearing manufacturers in Germany and Japan are consolidating orders for yttria-stabilized grades around tighter purity benchmarks, while REACH compliance and FDA material standards force ceramic processors to reconfigure supply chains and testing protocols.
Growth Catalysts
- REACH substance restrictions:European Union limits on certain stabilizer chemistries are pushing reformulation toward cleaner yttria-dopant systems, opening premium positioning for compliant suppliers.
- Semiconductor polishing demand:Sub-micron dimensional tolerances required for advanced wafer processing are pulling volume toward specialized zirconia grades with controlled surface finishes.
- Osaka prefecture cluster:Concentrated precision machining infrastructure creates dense supplier-buyer networks that accelerate qualification cycles for medical device applications.
Market Restraints
- Yttria input volatility:Rare earth supply concentration and processing bottlenecks create margin pressure for stabilized zirconia producers without captive powder synthesis.
- ISO 13356 testing burden:Surgical implant-grade certification requires accredited metrology suites that favor established laboratories and erect barriers for new entrants.
- Silicon nitride substitution:Alternative ceramic bearings gain traction in lower-temperature applications where fracture toughness requirements relax.
Strategic Opportunities
- Asset-light equipment leasing:Precision grinding machinery rental models reduce capital barriers for mid-size ceramic processors entering medical-grade production.
- Aerospace hollow ball adoption:Weight-reduction programs in commercial aviation create demand for unsprung mass reduction where every gram affects fuel efficiency.
- EPA emissions standards:Tighter kiln firing regulations favor processors with advanced thermal management, creating consolidation opportunities for compliant facilities.
Industry Challenges
- Multi-jurisdictional qualification:Simultaneous ISO 13356, JIS, and FDA biocompatibility testing creates stranded inventory risk when purity thresholds shift mid-certification.
- Lot-to-lot variability control:In-house powder synthesis capabilities remain concentrated among integrated manufacturers, forcing independent processors into supply dependency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zirconia Ceramic Balls Market |
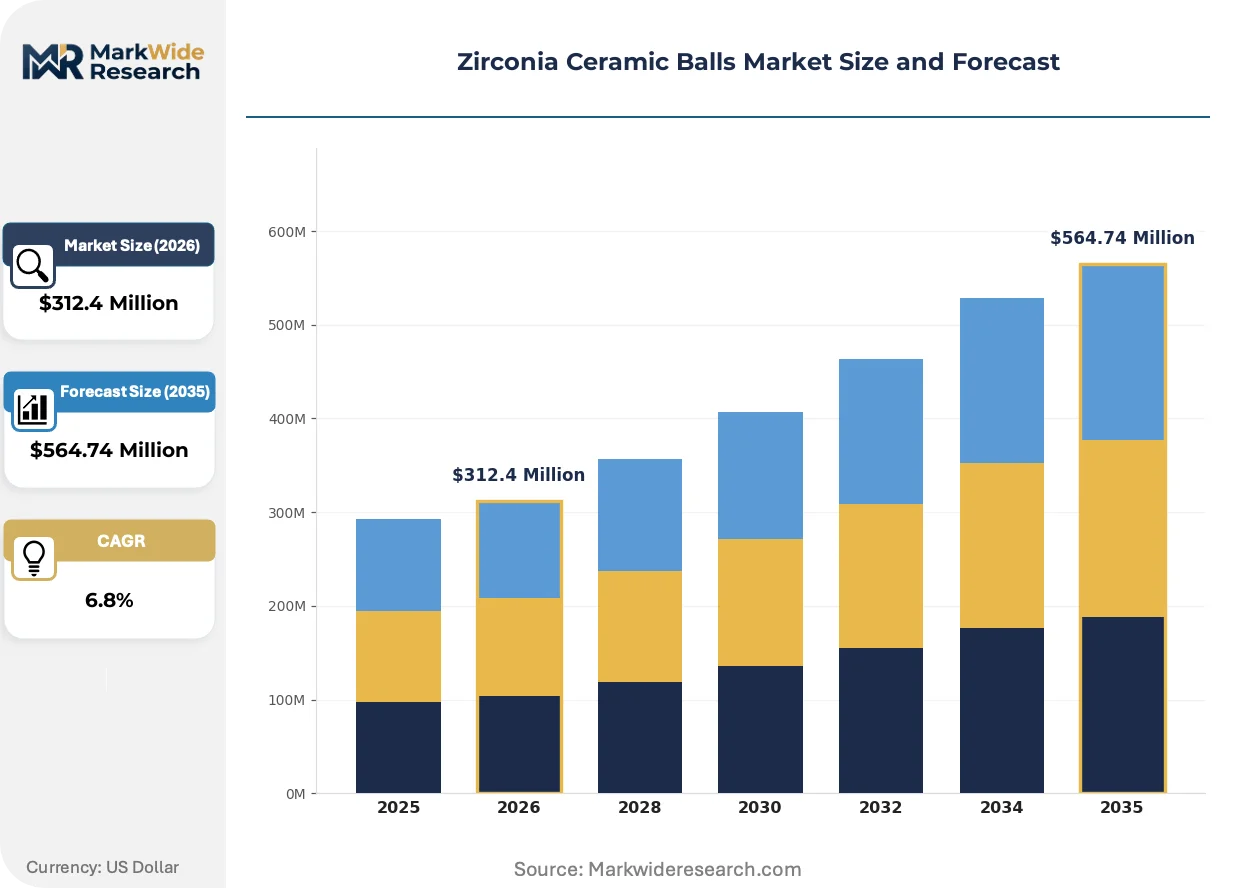
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yttria-Stabilized, Pure Zirconia, Zirconia Toughened, Coated Zirconia Application: Aerospace, Automotive, Medical Devices, Oil & Gas End User: Manufacturers, Research Institutions, Laboratories, Construction Form: Solid Balls, Hollow Balls, Custom Shapes, Pre-formed |
| Companies Covered | CeramTec GmbH, CoorsTek, Inc., Saint-Gobain, NGK Spark Plug Co., Ltd., Kyocera Corporation, Jinsheng Ceramic, Redhill, Ortech, Toshiba Materials Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zirconia Ceramic Balls Market Emerging Trajectories
Active reshaping in this market centers on process intensification, regulatory harmonization pressures, and the unbundling of traditional equipment ownership models.
Nano-powder sintering with microwave-assisted densification is collapsing conventional firing cycle times from days to hours. Medical device manufacturers in Bavaria are piloting these systems for implant-grade ball production. The compression of thermal processing windows is enabling just-in-time inventory models that reduce working capital requirements for precision bearing suppliers.
MDR implementation in the European Union is tightening traceability requirements for implantable device materials. Ceramic processors must now document supply chain provenance through raw material batch records. Surgical-grade zirconia ball suppliers with integrated powder synthesis are capturing preference share as downstream manufacturers seek single-source accountability for biocompatibility documentation.
After-sales service unbundling is fragmenting traditional equipment supply relationships. Precision grinding machinery vendors in Michigan's automotive corridor now offer predictive maintenance subscriptions separate from hardware procurement. Tier-two ceramic processors are adopting these arrangements to access advanced metrology without capital deployment, shifting supplier stickiness from equipment finance to data-enabled service continuity.
Zirconia Ceramic Balls Market Segmentation
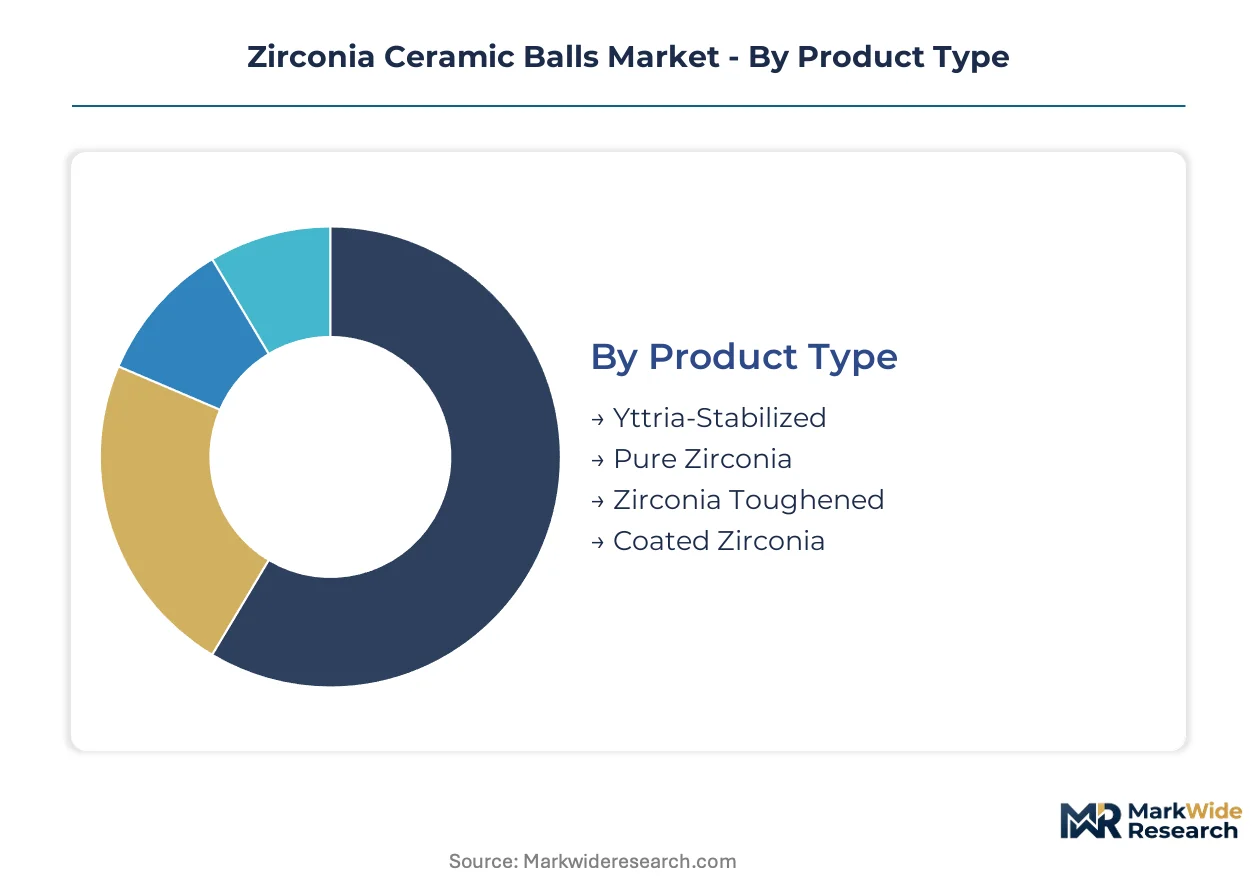
Segmentation in zirconia ceramic balls reflects divergent service intensity requirements across product grades and end-use applications. After-sales technical support varies dramatically between implant-grade medical specifications and standard industrial bearing retrofits.
Product Type:
After-sales-service intensity tracks closely with stabilization chemistry complexity, as yttria-doped grades demand ongoing metallurgical consultation that pure zirconia variants rarely require.
- Yttria-Stabilized:Tetragonal phase structure stabilized with yttria content between 3-8 mol% delivers fracture toughness exceeding 10 MPa·m½ for bearing applications. Ball bearing manufacturers in Germany and Japan are consolidating orders around tighter purity benchmarks for this grade. Demand concentrates in precision machining clusters where REACH compliance forces reformulation toward cleaner dopant systems.
- Coated Zirconia:Surface-engineered layers of alumina or diamond-like carbon protect against corrosive downhole fluids in oil & gas extraction. Margin premiums of 15-40% apply where unprotected surfaces degrade rapidly. Procurement patterns favor suppliers with integrated coating facilities that eliminate inter-facility contamination risks.
- Pure Zirconia:Monoclinic phase material without stabilizer additions serves lower-stress grinding media applications.
- Zirconia Toughened:Alumina-matrix composites with zirconia dispersions balance hardness and toughness for wear-resistant components.
By volume, Yttria-Stabilized leads. By growth pace, Coated Zirconia is ahead.
Application:
Application segmentation maps directly onto certification burden tiers, with medical devices demanding multi-jurisdictional testing that aerospace and automotive segments approach differently.
- Medical Devices:Implant-grade balls for hip and dental prostheses require ISO 13356 compliance plus FDA biocompatibility protocols. Bavaria's medical device manufacturers are piloting microwave-assisted densification to compress firing cycles. The MDR implementation in the European Union tightens traceability requirements that favor suppliers with captive powder synthesis.
- Aerospace:Weight-reduction programs in commercial aviation pull demand toward hollow ball configurations where every gram of unsprung mass affects fuel efficiency. Dimensional tolerances below one micron command specialized metrology investments that fragment supplier tiers.
- Automotive:Michigan's automotive corridor drives bearing retrofit volume for electric vehicle powertrains.
- Oil & Gas:Downhole tool applications prioritize corrosion resistance over dimensional precision.
Medical Devices captures the highest unit margins. Aerospace is expanding most quickly.
End User:
End user categories separate capital-intensive manufacturers from asset-light research entities with fundamentally different procurement rhythms and technical support expectations.
- Manufacturers:Tier-one bearing producers and medical device OEMs drive volume through multi-year supply agreements with embedded quality audits. Osaka prefecture's precision machining infrastructure creates dense supplier-buyer networks that accelerate qualification cycles.
- Research Institutions:Materials science departments and national laboratories pilot novel sintering techniques with small-batch, high-specification orders.
- Laboratories:Quality control and analytical testing facilities consume standard grades for calibration purposes.
- Construction:Grinding media for cement and mineral processing represents price-sensitive commodity demand.
Manufacturers dominate absolute consumption. Research Institutions are gaining share fastest.
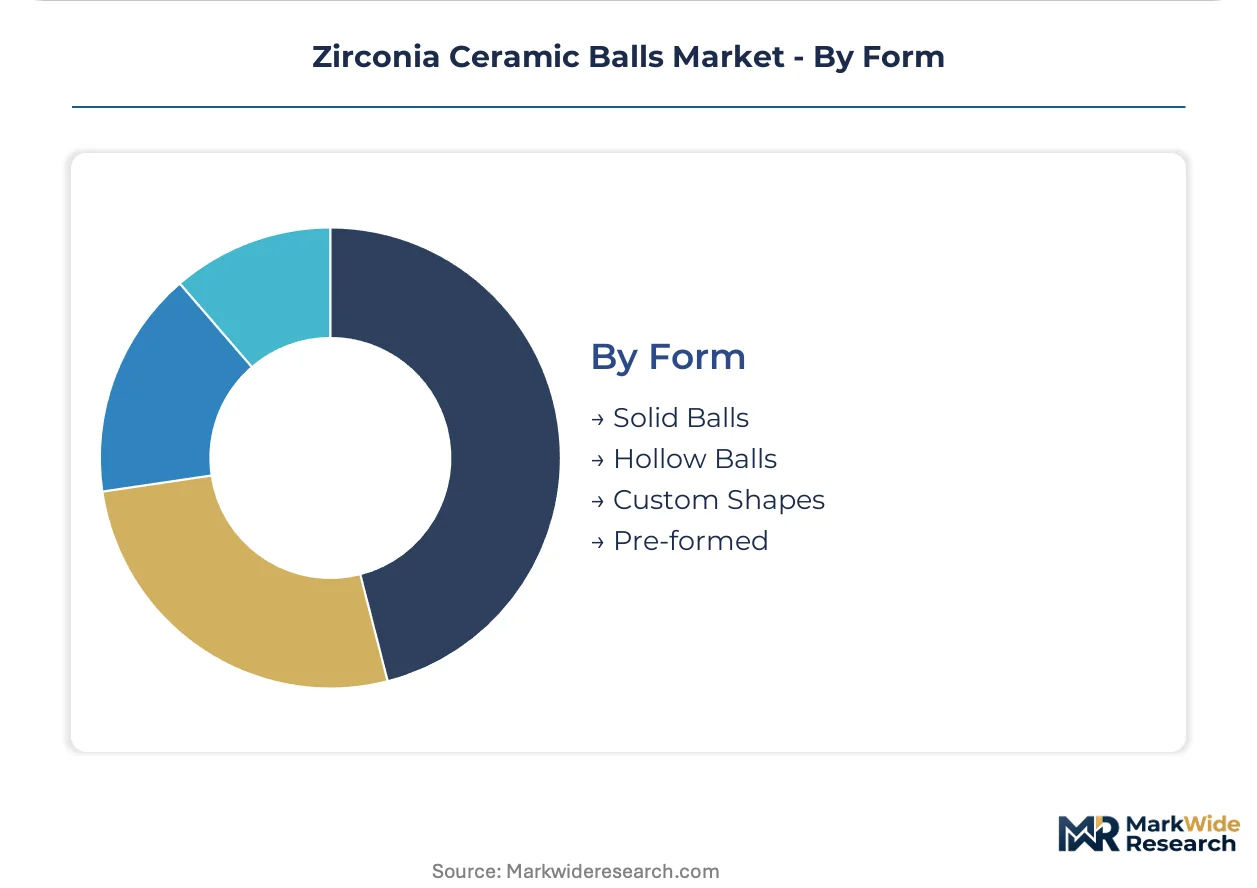
Form:
Form factor selection hinges on mass-critical versus stiffness-critical design constraints, with hollow configurations requiring specialized fixturing that alters supplier economics.
- Solid Balls:Standard bearing retrofits and grinding media applications anchor volume for this mature configuration. Solid balls tolerate broader dimensional tolerance bands than hollow variants, enabling higher-throughput production from conventional isostatic pressing equipment.
- Hollow Balls:Thin-wall spherical shells reduce mass by 40-60% versus solid equivalents of equivalent outer diameter. Aerospace weight-reduction programs in Germany and Japan are pulling adoption curves forward for this form factor.
- Custom Shapes:Non-spherical geometries for specialized valve and pump applications.
- Pre-formed:Near-net-shape blanks requiring minimal final grinding.
Solid Balls maintain volume leadership. Hollow Balls show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision bearing manufacturers and Japan's medical device clusters anchor demand concentration for yttria-stabilized grades, while REACH and FDA protocols reshape qualification pathways across processing hubs.
Germany
Bavaria's medical device manufacturers pilot microwave-assisted densification for implant-grade production. ECHA's REACH substance restrictions force reformulation toward cleaner yttria-dopant systems. Stuttgart's automotive corridor drives bearing retrofit volume for electric powertrain applications.
Japan
Osaka prefecture's precision machining infrastructure accelerates qualification cycles for surgical-grade balls. METI oversees JIS standards that create multi-jurisdictional testing burdens alongside ISO 13356. Kyushu's ceramic processors concentrate captive powder synthesis capabilities.
United States
Michigan's automotive corridor sustains demand for standard bearing retrofits and grinding media applications. EPA emissions standards for ceramic firing kilns elevate certification costs for new entrants. Greater Boston's research institutions pilot novel sintering techniques with small-batch orders.
China
Zhengzhou-based ceramic processors serve price-sensitive grinding media demand for cement and mineral processing. MIIT's GB standards govern industrial ceramic quality benchmarks. Yangtze River Delta clusters concentrate mid-size processors seeking asset-light equipment leasing models.
Zirconia Ceramic Balls Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered supply relationships. Integrated manufacturers with captive powder synthesis capabilities anchor premium positioning, while independent processors depend on external stabilizer supply. Three archetypes dominate: backward-integrated material-science conglomerates, regional fabrication specialists, and asset-light precision grinding service providers. Competitive moves concentrate on M&A for accredited metrology suites and strategic partnerships for hollow ball aerospace qualification.
Within the integrated-manufacturer tier, Kyocera Corporation and Toshiba Materials Co., Ltd. exemplify positions sustained by in-house powder synthesis that reduces lot-to-lot variability. CoorsTek, Inc. anchors North American technical ceramics through captive supply chain control. Among Germany-based fabricators, CeramTec GmbH occupies a position aligned with REACH-compliant yttria-stabilized grades. These named entities represent archetype patterns rather than exhaustive market coverage.
| Leading Market Players |
|---|
| CeramTec GmbH |
| CoorsTek, Inc. |
| Saint-Gobain |
| NGK Spark Plug Co., Ltd. |
| Kyocera Corporation |
| Jinsheng Ceramic |
| Redhill |
| Ortech |
| Toshiba Materials Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Yttria input volatility from rare earth supply concentration determines both pricing tier spreads and supply chain shape across yttria-stabilized zirconia grades. REACH substance restrictions and FDA material standards force processors to absorb certification costs that widen spreads between implant-grade and industrial-grade offerings.
Pricing Analysis
Cost-plus contracts indexed to rare earth oxide benchmarks dominate long-term supply agreements between integrated manufacturers and medical device OEMs. Price differentiation separates ISO 13356-certified implant grades from standard bearing retrofits, with after-sales technical support bundled into premium tiers. Pricing pressure stems from silicon nitride substitution in lower-temperature applications where fracture toughness requirements relax. Research institutions and construction grinding media buyers exhibit highest price sensitivity, while surgical-grade medical device manufacturers prioritize lot-to-lot consistency over unit cost.
Supply Chain Analysis
Tariff exposure between China and Western markets dominates supply chain risk calculations for rare earth oxide feedstocks. Geographic supply concentration centers on Germany, Japan, and China, with Kyushu's ceramic processors anchoring captive powder synthesis capabilities. Raw material dependencies draw from yttrium oxide, zirconium oxychloride, and specialized stabilizer chemistries. Single-source vulnerability persists for medical-grade powder suppliers with accredited metrology suites. Distribution runs through precision machining clusters in Bavaria, Osaka prefecture, and Michigan's automotive corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated ball bearing manufacturers in Germany and Japan who are tightening purity benchmarks and consolidating order volumes around fewer qualified suppliers.
For Market Incumbents: Harden quality audit protocols to defend against silicon nitride substitution in lower-stress bearing applications. Deepen backward integration into yttria powder synthesis to reduce lot-to-lot variability that medical device OEMs now penalize. Prioritize M&A for accredited metrology suites that accelerate multi-jurisdictional qualification cycles. For New Entrants and Emerging Players: Build out asset-light precision grinding service models targeting mid-size ceramic processors in China's Yangtze River Delta. The most penetrable white space sits in hollow ball aerospace qualification where dimensional tolerances below one micron fragment supplier tiers. Pursue strategic partnerships with established powder suppliers rather than capital-intensive synthesis buildouts. For Investors and Strategic Acquirers: MDR implementation in the European Union reshapes the acquisition landscape toward surgical-grade zirconia ball suppliers with integrated powder synthesis and batch traceability systems. Long-term viability favors processors with demonstrated FDA biocompatibility documentation and REACH-compliant reformulation capabilities. Watch for EPA emissions standard enforcement as a consolidation trigger that elevates costs for kiln-dependent facilities without advanced thermal management.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Powder Synthesis | Captive yttria supply reduces lot-to-lot variability for ISO 13356 medical device customers. |
| Microwave-Assisted Densification Deployment | Compression of firing cycles from days to hours enables just-in-time inventory for Bavaria manufacturers. |
| Hollow Ball Aerospace Qualification | Thin-wall configurations address unsprung mass reduction targets in commercial aviation weight programs. |
| Accredited Metrology Suite Acquisition | Multi-jurisdictional testing capability accelerates FDA, JIS, and ISO 13356 parallel certification pathways. |
| Predictive Maintenance Service Unbundling | Data-enabled service contracts shift supplier stickiness from equipment finance to continuity guarantees. |
Methodological Framework
Cross-validation between primary interviews with ceramic processing plant managers, medical device procurement leads, precision bearing OEM technical directors, and aftermarket service heads anchors the qualitative findings. Secondary validation draws from SEC filings of listed ceramics manufacturers, ECHA REACH substance restriction updates, FDA biocompatibility guidance documents, and JIS standards publications. Bottom-up demand modeling across application segments triangulates against top-down supply-side capacity assessments.
Calibration against historical volume trajectories and capacity expansion announcements informs the analytical framework across the projection horizon. Segmentation dimensions modeled include stabilization chemistry grade, end-use application tier, form factor configuration, and regional regulatory cluster. CAGRs derive from slope-intercept fitting of normalized growth patterns, with industry-specific inputs incorporating rare earth oxide price indices and kiln emissions compliance cost curves.
Sensitivities concentrate around rare earth supply disruptions, REACH substance restriction amendments, and FDA biocompatibility protocol updates that could accelerate or delay qualification cycles. Forecasts reflect documented assumptions about powder synthesis capacity buildouts and aerospace hollow ball adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Calcined Kaolin Market
Ceramics
Calcined Alumina Market
Ceramics
Tetramethyl Orthosilicate Market
Ceramics
Hot-Pressed Aluminum Titanate Ceramics Market
Ceramics
Ceramic Ware Market
Ceramics
Ceramic Injection Molding Market
Ceramics
Co-Fired Ceramic Market
Ceramics
China Clay Market
Ceramics
Brazil Ceramic Tiles Market
Ceramics
Global Pseudo Boehmite Market
Ceramics
US Kaolin Market
Ceramics
Global Metal and Ceramic Injection Molding Market
Ceramics
Lithium Silicate Market
Ceramics
Thermal Spray Powder Market
Ceramics
Dielectric Ceramics Market
Ceramics
Ceramics Market