
 Dental Bleaching Materials Market | 2026-2036
Dental Bleaching Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Bleaching Materials Market Outlook
China is reshaping manufacturing capacity for peroxide-based dental bleaching gels and delivery systems, with new production clusters serving both domestic cosmetic dentistry growth and export markets. Philips leverages vertical integration across light-activated bleaching devices and consumable chemistry to sustain premium positioning. Ultradent Products anchors its competitiveness in dentist-dispensed take-home systems through specialized tray fabrication protocols. Dentsply Sirona operates across chairside and laboratory channels, extending its reach into digital shade-matching workflows that drive bleaching case acceptance.
Dental bleaching materials comprise hydrogen peroxide, carbamide peroxide, or alternative oxidative agents formulated into gels, strips, or pastes designed to degrade chromogenic organic compounds within enamel and dentin matrices, typically employing concentrations between three percent and forty percent depending on clinical setting and contact duration. In-office bleaching dominates value generation due to higher peroxide concentrations and professional supervision requirements, while at-home kits capture volume through direct-to-consumer channel expansion. Whitening strips differentiate on convenience and per-unit affordability, though gel formulations retain margin advantages in dentist-dispensed protocols where custom tray fabrication adds service revenue.
FDA oversight of peroxide concentrations in over-the-counter dental bleaching products constrains formulation freedom in the United States, while EU REACH registration requirements for hydrogen peroxide imports impose compliance costs on non-European suppliers. ISO standards for dental materials testing provide a baseline for international market access, though national pharmacopeias diverge on maximum allowable concentrations for unsupervised use. Stakeholders must monitor evolving peroxide classification debates across regulatory jurisdictions, as reclassification would force channel restructuring and reformulation investments without advance warning.
Market Dynamics
Professional supervision requirements and concentration limits under FDA and EU REACH are bifurcating the market into high-margin chairside protocols and commoditized direct-to-consumer strips, reshaping competitive positioning across formulation tiers.
Growth Catalysts
- Cosmetic dentistry clinic expansion:Brazil, Germany, and the United States are seeing aesthetic dental procedure volumes climb as disposable incomes rise and social media visibility intensifies demand for professional-grade outcomes.
- REACH registration compliance:European hydrogen peroxide import rules are consolidating supplier bases, advantaging incumbent formulators with established ECHA dossiers and certified manufacturing.
- Light-activated device chemistry pairing:LED and laser activation systems are accelerating peroxide degradation kinetics, shortening chairside treatment windows and justifying premium pricing.
Market Restraints
- Raw material concentration caps:FDA limits on over-the-counter hydrogen peroxide levels constrain formulation freedom in the United States, compressing margins on mass-market strips.
- Supply concentration in Chinese manufacturing:Peroxide gel production clusters in Zhejiang and Jiangsu provinces create geographic vulnerability for Western brands dependent on imported oxidative precursors.
- Enamel sensitivity as technical ceiling:Higher-concentration protocols risk dentin hypersensitivity, capping clinical adoption despite efficacy advantages.
Strategic Opportunities
- Underpenetrated Indian cosmetic dentistry:Tier-2 and Tier-3 cities present whitespace for dentist-dispensed take-home systems as BIS standards harmonize with ISO dental materials testing protocols.
- Digital shade-matching workflow integration:Chairside spectrophotometry and 3D scanning are converging with bleaching treatment planning, enabling outcome visualization that drives case acceptance.
- Subscription direct-to-consumer channels:Recurring gel refill models bypass retail shelf constraints and capture lifetime value from at-home users.
Industry Challenges
- Specialized tray fabrication technician scarcity:Custom-fitted bleaching tray production requires dental laboratory expertise that concentrates in urban centers, limiting rural service penetration.
- ISO 10993 biocompatibility certification timelines:Extended cytotoxicity and sensitization testing protocols delay new gel formulation launches by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Bleaching Materials Market |
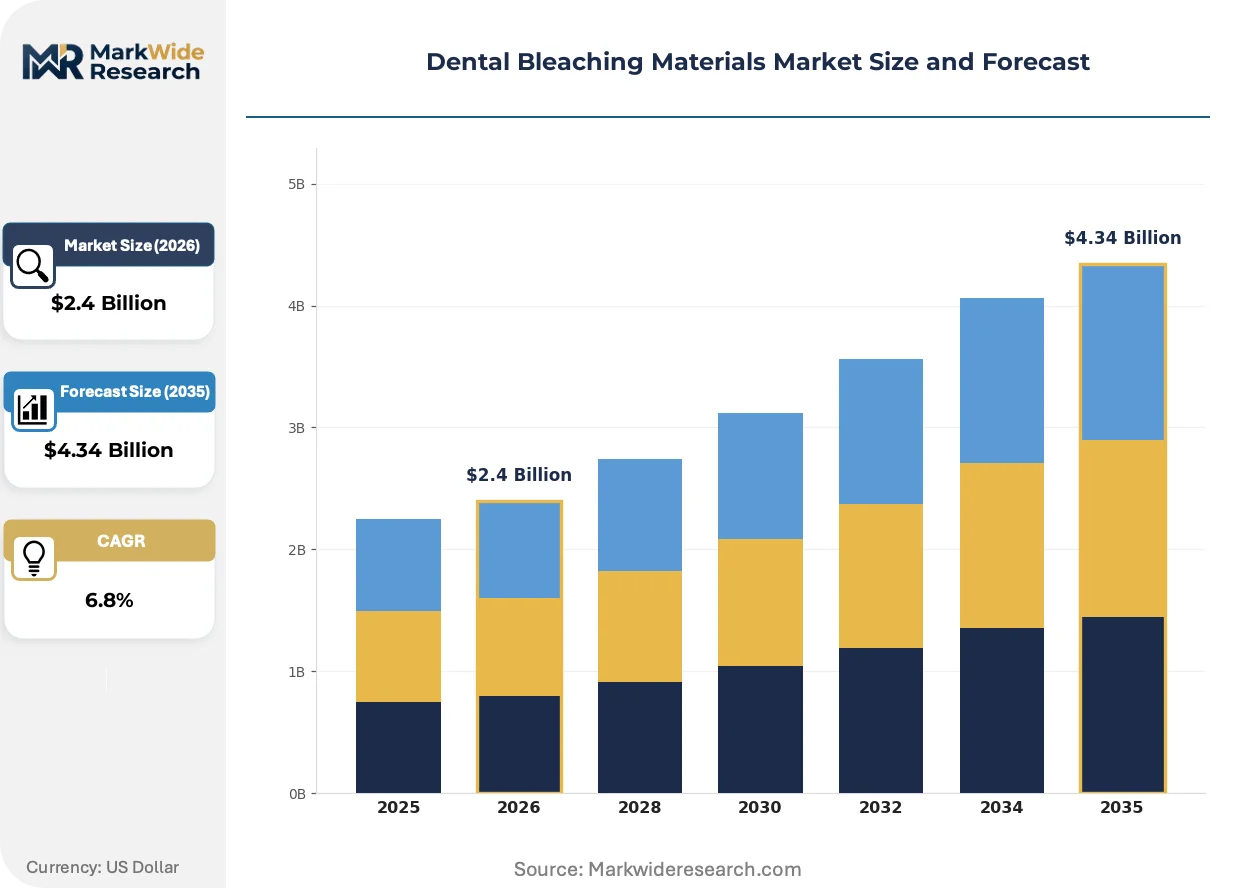
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: In-office Bleaching, At-home Kits, Whitening Toothpaste, Whitening Strips Formulation: Hydrogen Peroxide, Carbamide Peroxide, Sodium Bicarbonate, Gel End User: Dentists, Cosmetic Clinics, Home Users, Dental Laboratories Application: Stain Removal, Teeth Whitening, Cosmetic Dentistry, Oral Hygiene |
| Companies Covered | Philips, GlaxoSmithKline, Procter & Gamble, Ivoclar Vivadent, Johnson & Johnson, Colgate-Palmolive, Ultradent Products, 3M Oral Care, Dentsply Sirona, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Bleaching Materials Market Strategic Shifts
Formulation science, regulatory classification debates, and channel restructuring are converging to redefine how bleaching materials reach end users and how value is captured across the value chain.
AI-powered shade prediction software is digitizing treatment outcome visualization. Cosmetic dentistry clinics in Seoul and São Paulo are adopting these platforms to simulate post-bleaching results during initial consultations. The technology is compressing patient decision cycles and reducing case abandonment rates.
EU REACH peroxide reclassification proceedings are forcing formulation hedging strategies. ECHA's ongoing review of hydrogen peroxide hazard classifications threatens to trigger mandatory professional-use-only labeling across member states. German and French suppliers are pre-emptively diversifying into non-peroxide oxidative alternatives.
Social media-driven aesthetic consciousness is fragmenting buyer segments into clinical purists and convenience seekers. Direct-to-consumer brands on TikTok and Instagram are displacing pharmacy shelf dominance in the United States and Brazil. This channel rotation is compressing traditional distributor margins while accelerating volume concentration among digitally native entrants.
Dental Bleaching Materials Market Segmentation
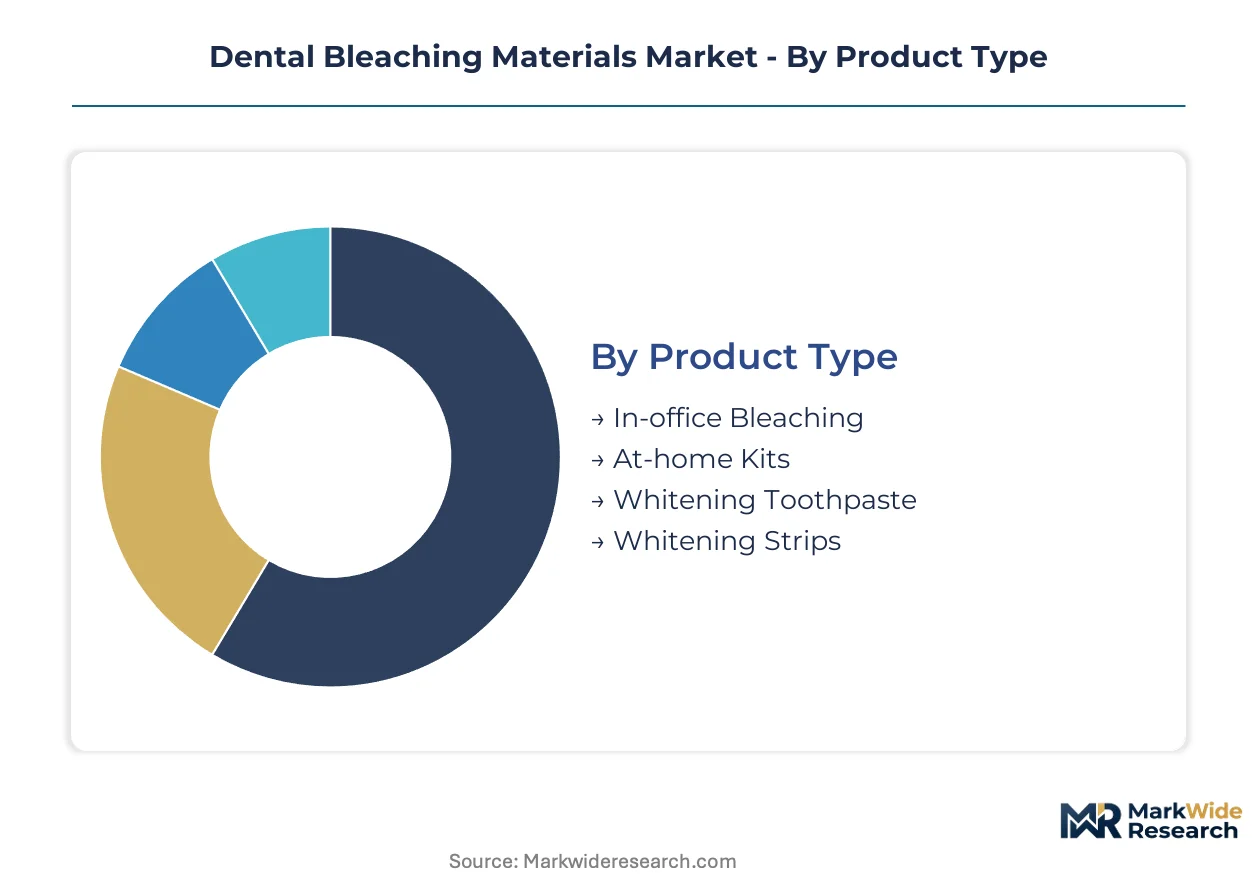
Dental bleaching materials fragment across four distinct axes that determine formulation chemistry, regulatory pathway, and margin capture. Product type and formulation chemistry together dictate whether materials flow through professional channels or direct-to-consumer retail.
Product Type:
Cost tier separates professional-supervised protocols from self-administered convenience formats.
- In-office Bleaching:High-concentration hydrogen peroxide gels (15-40%) activated by LED or laser systems require chairside supervision. Demand concentrates in São Paulo and Seoul cosmetic dentistry clinics where social media visibility drives case volume.
- At-home Kits:Dentist-dispensed systems pair custom-fabricated trays with moderate-concentration carbamide peroxide. Germany and the United States show concentration in this segment as dental laboratories expand tray production capacity.
- Whitening Toothpaste:Low-abrasion formulations with sodium bicarbonate or mild peroxides target daily maintenance users.
- Whitening Strips:Pre-formed polyethylene strips with 6-14% hydrogen peroxide dominate mass retail in Brazil and the United States.
In-office bleaching commands the established base. The steepest expansion runs through at-home kits as dental laboratories scale tray fabrication.
Formulation:
Active chemistry determines regulatory classification and professional access requirements.
- Hydrogen Peroxide:The oxidative standard for professional systems, with concentrations capped at 0.1-6% for over-the-counter sale under FDA and EU REACH frameworks. Chairside protocols in the United States and Germany utilize 25-40% formulations.
- Carbamide Peroxide:Slower-release precursor decomposing to hydrogen peroxide and urea, enabling extended-contact protocols. Cosmetic clinics in Brazil favor 10-22% concentrations for overnight tray systems.
- Sodium Bicarbonate:Mild abrasive alternative for enamel-safe maintenance pastes and non-peroxide strips.
- Gel:Viscosity-optimized delivery vehicle enabling precise application and controlled release kinetics.
Hydrogen peroxide retains the professional standard position. Carbamide peroxide is gaining share fastest as overnight protocols expand.
End User:
Customer type dictates purchasing authority, reimbursement eligibility, and regulatory exposure.
- Dentists:Licensed practitioners prescribing chairside and take-home protocols, capturing service revenue alongside material margins.
- Cosmetic Clinics:Aesthetic-focused facilities in Seoul and São Paulo driving light-activated system adoption.
- Home Users:Self-directed consumers purchasing strips and pastes through pharmacy and e-commerce channels.
- Dental Laboratories:Specialized fabricators producing custom bleaching trays from intraoral scans.
Dentists anchor the revenue base. Cosmetic clinics are expanding most quickly as aesthetic procedure volumes climb.
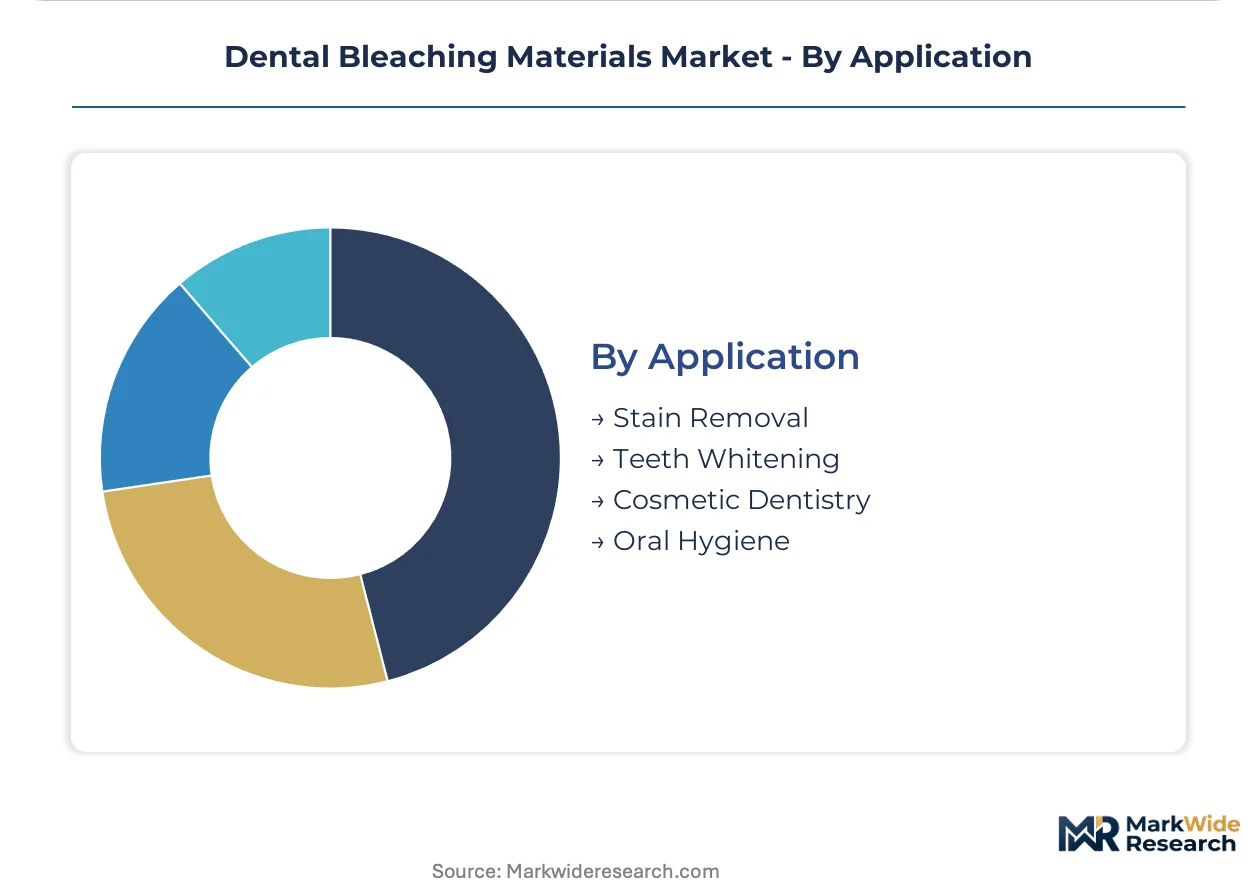
Application:
Clinical objective shapes formulation selection and treatment duration.
- Stain Removal:Targeted protocols addressing extrinsic discoloration from coffee, tobacco, and wine.
- Teeth Whitening:General shade enhancement across the full dental arch, the primary revenue driver.
- Cosmetic Dentistry:Pre-restorative bleaching to establish shade reference for veneers and crowns.
- Oral Hygiene:Maintenance-oriented applications integrating whitening into daily care routines.
Teeth whitening holds the volume base. Cosmetic dentistry applications are climbing the fastest as pre-restorative protocols standardize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA concentration limits on over-the-counter hydrogen peroxide formulations anchor the United States as the regulatory benchmark geography, while EU REACH registration requirements reshape European supplier bases and Chinese manufacturing clusters serve export demand across formulation tiers.
United States
Cosmetic dentistry clinics in Los Angeles and New York Metro drive professional-grade bleaching system adoption as social media visibility intensifies aesthetic demand. FDA oversight caps over-the-counter hydrogen peroxide at 6%, bifurcating the market into supervised chairside protocols and mass-market strips. Dental laboratories in the Pacific Northwest expand custom tray fabrication capacity to serve dentist-dispensed take-home growth.
Germany
REACH-registered formulators in Baden-Württemberg consolidate supply positions as ECHA dossier requirements filter non-compliant imports. Dentist-dispensed carbamide peroxide systems dominate in Bavaria, where dental laboratories scale overnight tray production. The country's aesthetic dentistry sector benefits from harmonized ISO 10993 biocompatibility testing protocols that accelerate product registration.
Brazil
São Paulo cosmetic clinics generate dense demand for light-activated bleaching devices paired with high-concentration hydrogen peroxide gels. ANVISA oversight aligns with international concentration standards, enabling parallel registration strategies for professional and consumer segments. Manufacturing partnerships in Minas Gerais supply gel formulations to Latin American export markets.
China
Zhejiang and Jiangsu province production clusters manufacture peroxide-based gels and delivery systems for domestic cosmetic dentistry expansion and Western brand supply. NMPA registration pathways for dental materials are harmonizing with ISO standards, reducing time-to-market for compliant formulators. Shanghai-based distributors are consolidating import channels for European professional-grade systems.
India
Tier-2 cities in Maharashtra and Karnataka present whitespace for dentist-dispensed take-home systems as disposable incomes rise and aesthetic consciousness spreads. BIS standards are converging with ISO dental materials testing protocols, reducing technical barriers for imported formulations. Mumbai cosmetic dentistry clinics are adopting digital shade-matching workflows that drive bleaching case acceptance.
Dental Bleaching Materials Market Competitive Environment
Capability concentration sits with specialized dental material formulators; scale advantage sits with diversified consumer health conglomerates. The market structures around three tiers: premium professional-system integrators, mid-market dentist-dispensed specialists, and mass-market direct-to-consumer brands. Strategic moves center on backward integration into peroxide precursor supply and technology licensing partnerships that bridge device-chemistry pairings.
Among diversified consumer health giants, Procter & Gamble and Colgate-Palmolive occupy positions that exemplify scale-driven strip and paste distribution through retail pharmacy dominance. Philips and Dentsply Sirona represent the professional-system integrator archetype, anchoring premium positioning across light-activated devices and chairside chemistry protocols. Ultradent Products sits within the dentist-dispensed specialist tier, with its take-home system focus reflecting the segment's reliance on custom tray fabrication partnerships.
| Leading Market Players |
|---|
| Philips |
| GlaxoSmithKline |
| Procter & Gamble |
| Ivoclar Vivadent |
| Johnson & Johnson |
| Colgate-Palmolive |
| Ultradent Products |
| 3M Oral Care |
| Dentsply Sirona |
| Others |
Value Chain & Pricing Dynamics
Shanghai-Ningbo port freight corridors govern landed costs for hydrogen peroxide precursors, concentrating margin pressure on Western brands dependent on Zhejiang gel manufacturing while enabling sharp price differentiation between dentist-dispensed and direct-to-consumer tiers.
Pricing Analysis
Geographic price spreads of three-to-five times separate German chairside protocols from Brazilian mass-market strips. Three-tier pricing structure across premium, standard, and economy levels reflects concentration differentials and professional supervision requirements. Pricing pressure stems from REACH compliance costs and raw material concentration caps, with home users exhibiting highest price sensitivity and cosmetic clinics showing lowest.
Supply Chain Analysis
Export-control regimes under EU REACH restrict hydrogen peroxide flows above 12% concentration to licensed professional channels. Supply concentrates in China, Germany, and the United States, with carbamide peroxide precursors and LED activation devices as critical inputs. Single-source vulnerability runs through Zhejiang gel clusters. Distribution runs through dental laboratories for custom trays and pharmacy retail for strips.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as social media-driven aesthetic consciousness splits buyer segments between clinical purists and convenience seekers.
For Market Incumbents: Entrench position through backward integration into peroxide precursor supply and captive dental laboratory networks. Threat from digitally native direct-to-consumer brands demands channel control investments. Certification leverage under FDA and REACH frameworks protects premium tiers. For New Entrants and Emerging Players: Establish a beachhead in India's Tier-2 cosmetic dentistry whitespace before BIS-ISO harmonization completes. Dentist-dispensed take-home systems offer lowest competitive density. Go-to-market through dental laboratory partnerships bypasses incumbent retail shelf dominance. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified consumer health conglomerates with undermonetized dental material divisions. Long-term viability hinges on professional-system integration capabilities. Watch ECHA peroxide reclassification proceedings as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Peroxide Supply | Captive sourcing from Zhejiang clusters insulates margin from REACH import volatility. |
| Dental Laboratory Network Acquisition | Custom tray fabrication control locks in dentist-dispensed channel loyalty. |
| Non-Peroxide Oxidative R&D Program | ECHA reclassification hedging opens alternative chemistry pathways for EU markets. |
| Direct-to-Consumer Subscription Launch | Recurring gel refill models bypass pharmacy shelf constraints in Brazil and the United States. |
| Digital Shade-Matching Platform Partnership | AI-powered outcome visualization drives case acceptance in Seoul and São Paulo clinics. |
Study Parameters
A standing panel of cosmetic dentistry clinic directors, dental laboratory technicians, regulatory affairs specialists, and pharmacy category managers provided ongoing calibration. Primary interviews combined with secondary validation against FDA 510(k) filings, ECHA registration databases, ANVISA submission records, and ISO 10993 test protocols. Bottom-up and top-down triangulation anchored volume estimates.
Scenario-bracketing framed demand projections across the analysis window, with segmentation modeling across product type, formulation chemistry, end-user category, and regional regulatory cluster. CAGRs derived from procedure volume elasticity and per-treatment material intensity. Forecast inputs included dental laboratory capacity expansion timelines and social media engagement metrics as demand proxies.
Sensitivities concentrate around ECHA peroxide reclassification outcomes and NMPA registration pathway harmonization. Forecasts reflect assumptions on professional supervision requirements and concentration limit stability. Material shifts in hydrogen peroxide hazard classification would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Materials
Dental Matrix Systems Market
Dental Materials
Dental Composites Market
Dental Materials
Toothpaste Market
Dental Materials
Crack Tooth Syndrome Market
Dental Materials
Global Teeth Whitening Product Market
Dental Materials
Solid Toothpaste Market
Dental Materials
Fluoride Materials Market
Dental Materials
Tooth Filling Materials Market
Dental Materials
Remineralizing Gum Market
Dental Materials
Artificial Teeth Market
Dental Materials
Asia-Pacific Toothpaste Market
Dental Materials
Dental Amalgam Market
Dental Materials
Dental Alginate Market
Dental Materials
Cold Light Teeth Whitening Kit Market
Dental Materials
Dental Polymerization Lamps Market
Dental Materials
Dental Fluoride Varnish Market