
 Australia and New Zealand Dental Biomaterials Market | 2026-2036
Australia and New Zealand Dental Biomaterials Market Size, Share, and Industry Trends Forecast 2026-2036
Australia and New Zealand Dental Biomaterials Market Intelligence
Modular kit configurations is decoupling from traditional bundled supply arrangements in the Australia and New Zealand Dental Biomaterials Market, forcing clinics to evaluate component-level purchasing against full-system contracts. Straumann Holding AG leverages its implant-biomaterial integration to sustain premium positioning across Australian metropolitan practices. Dentsply Sirona competes through broad restorative portfolios that anchor its distribution network throughout New Zealand. Henry Schein Inc. controls channel access via its dental supply infrastructure, extending logistics coverage into regional Australian markets.
Australia and New Zealand Dental Biomaterials comprise synthetic and biologically derived substances engineered for tissue repair, regeneration, and restoration within oral environments, typically meeting ISO 10993 biocompatibility standards and TGA medical device classifications. These materials serve primary commercial purposes in restorative dentistry, orthodontic anchorage, periodontal defect management, and endodontic obturation. Composites and ceramics dominate current value generation due to their aesthetic performance in anterior restorations and established reimbursement pathways across Australian private health frameworks. CAD/CAM technology integration is accelerating production efficiency for ceramic restorations, while nanotechnology-enhanced adhesives represent an emerging margin pool as practitioners seek improved bond durability and reduced technique sensitivity.
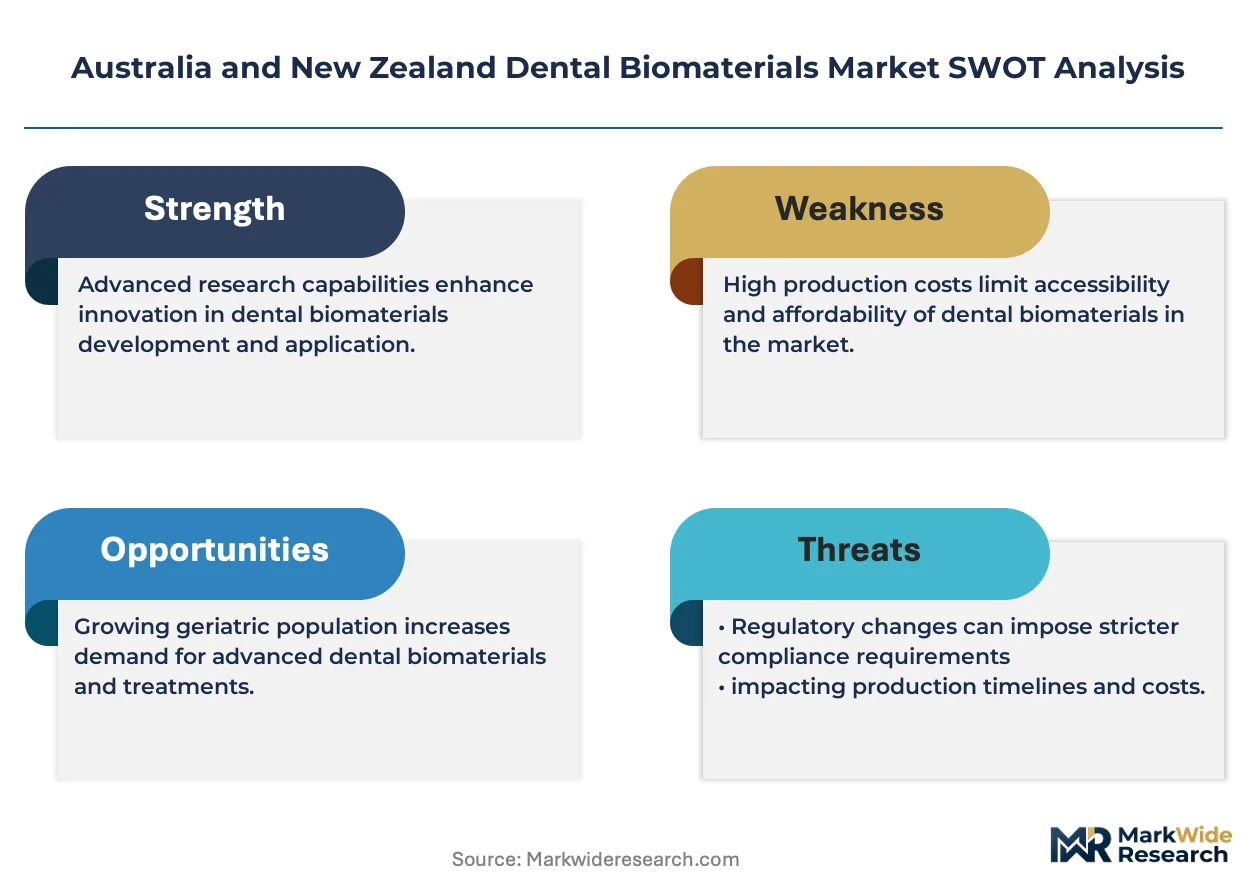
TGA's medical device regulations, ISO 13485 quality management requirements, and New Zealand's Medsafe oversight collectively govern market access, with biocompatibility testing protocols extending product registration timelines and elevating compliance costs for new entrants. The Therapeutic Goods Administration's reclassification of certain bone graft substitutes has tightened clinical evidence requirements, redirecting manufacturer investment toward local trial infrastructure. Stakeholders must monitor evolving reimbursement negotiations between Australian private health insurers and dental clinic networks, as these agreements will determine patient out-of-pocket exposure and subsequent biomaterial selection patterns across both countries.
Market Dynamics
Modular kit configurations are decoupling from traditional bundled supply arrangements across Australian and New Zealand dental practices, forcing clinics to evaluate component-level purchasing against full-system contracts while TGA's tightened biocompatibility standards extend product registration timelines.
Growth Catalysts
- Digital dentistry integration:CAD/CAM systems are streamlining ceramic restoration production across Sydney and Melbourne metropolitan practices, reducing chairside time and laboratory outsourcing dependency.
- TGA reclassification protocols:The Therapeutic Goods Administration's updated medical device framework for bone graft substitutes is redirecting manufacturer investment toward local clinical trial infrastructure, accelerating evidence generation for novel biomaterials.
- Private health insurance negotiations:Reimbursement agreements between Australian insurers and dental clinic networks are expanding patient access to premium restorative procedures, directly stimulating biomaterial consumption in crown and bridge applications.
Market Restraints
- Input cost volatility:Zirconia and specialized ceramic precursor prices fluctuate with global rare earth supply disruptions, compressing margins for restoration manufacturers serving the Australian market.
- Regulatory friction:ISO 10993 biocompatibility testing protocols combined with TGA's extended review cycles add eighteen to twenty-four months to product commercialization timelines for new entrants.
- Substitution threat:Direct-to-consumer aligner systems and preventive dental technologies are reducing invasive restoration volumes among younger patient demographics in New Zealand urban centers.
Strategic Opportunities
- Regional Australian penetration:Henry Schein's logistics infrastructure extension creates channel access for biomaterial suppliers targeting underserviced Queensland and Western Australia regional markets outside metropolitan dental clusters.
- Nanotechnology convergence:Nanoparticle-enhanced adhesive systems combining improved bond durability with reduced technique sensitivity represent an emerging margin pool as practitioners seek clinical efficiency gains.
- MedSafe harmonization:New Zealand's regulatory alignment with Australian TGA standards under trans-Tasman mutual recognition agreements simplifies dual-market product registration for compliant manufacturers.
Industry Challenges
- CAD/CAM technician scarcity:Digital restoration design and milling operation skills lag equipment installation rates across Australian regional practices, creating workflow bottlenecks and underutilized capital investments.
- Legacy system integration:Established practice management software and inventory systems in mature Sydney and Melbourne clinics resist seamless connectivity with newer biomaterial ordering platforms, complicating supply chain digitization efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia and New Zealand Dental Biomaterials Market |
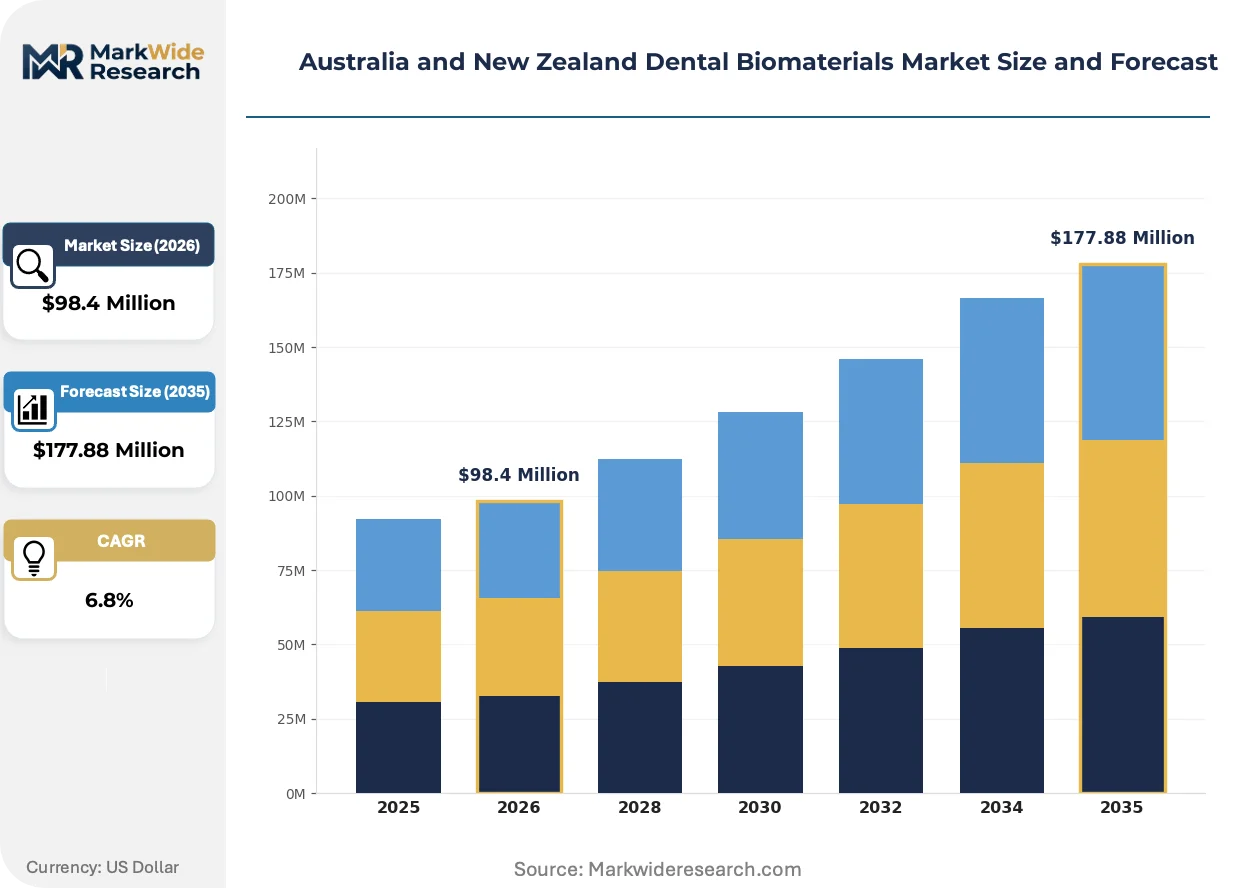
| Market Size in 2026 | $98.4 Million |
| Market Size in 2035 | $177.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Composites, Ceramics, Adhesives, Alloys End User: Dental Clinics, Hospitals, Research Institutions, Laboratories Application: Restorative Dentistry, Orthodontics, Periodontics, Endodontics Technology: 3D Printing, CAD/CAM, Bioprinting, Nanotechnology |
| Companies Covered | Straumann Holding AG, Zimmer Biomet Holdings, Dentsply Sirona, 3M Company, Geistlich Pharma AG, Ivoclar Vivadent AG, GC Corporation, Kuraray Co., Ltd., Henry Schein Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia and New Zealand Dental Biomaterials Market Strategic Shifts & Innovations
Ceramic restoration workflows, regulatory evidence requirements, and procurement models are simultaneously transforming how Australian and New Zealand dental practices source and apply biomaterials.
Chairside CAD/CAM ceramic milling is overtaking traditional laboratory-fabricated crown production in Australian metropolitan practices. Sydney and Melbourne private clinics are adopting intraoral scanning and same-day milling systems at accelerating rates. This technology compression is eliminating multi-appointment restoration protocols and reducing laboratory outsourcing revenue pools.
TGA's reclassification of certain bone graft substitutes under stricter clinical evidence requirements is extending product registration timelines for manufacturers. The Therapeutic Goods Administration's framework now demands local trial participation for novel regenerative materials. Periodontal defect management applications face the most significant compliance burden as sponsors build Australian investigator networks.
Component-level purchasing is displacing bundled supply contracts across New Zealand dental clinic networks. Procurement officers are negotiating direct relationships with ceramic and composite manufacturers, bypassing traditional full-system distributors. This channel disintermediation is most visible in Auckland and Wellington group practices consolidating supplier relationships for cost transparency.
Australia and New Zealand Dental Biomaterials Market Segmentation
Biomaterial selection across Australian and New Zealand dental practices follows distinct procurement logics tied to reimbursement pathways, equipment compatibility, and regulatory burden. Understanding how segments intersect with TGA classification tiers and private health insurance coverage determines commercial prioritization for suppliers.
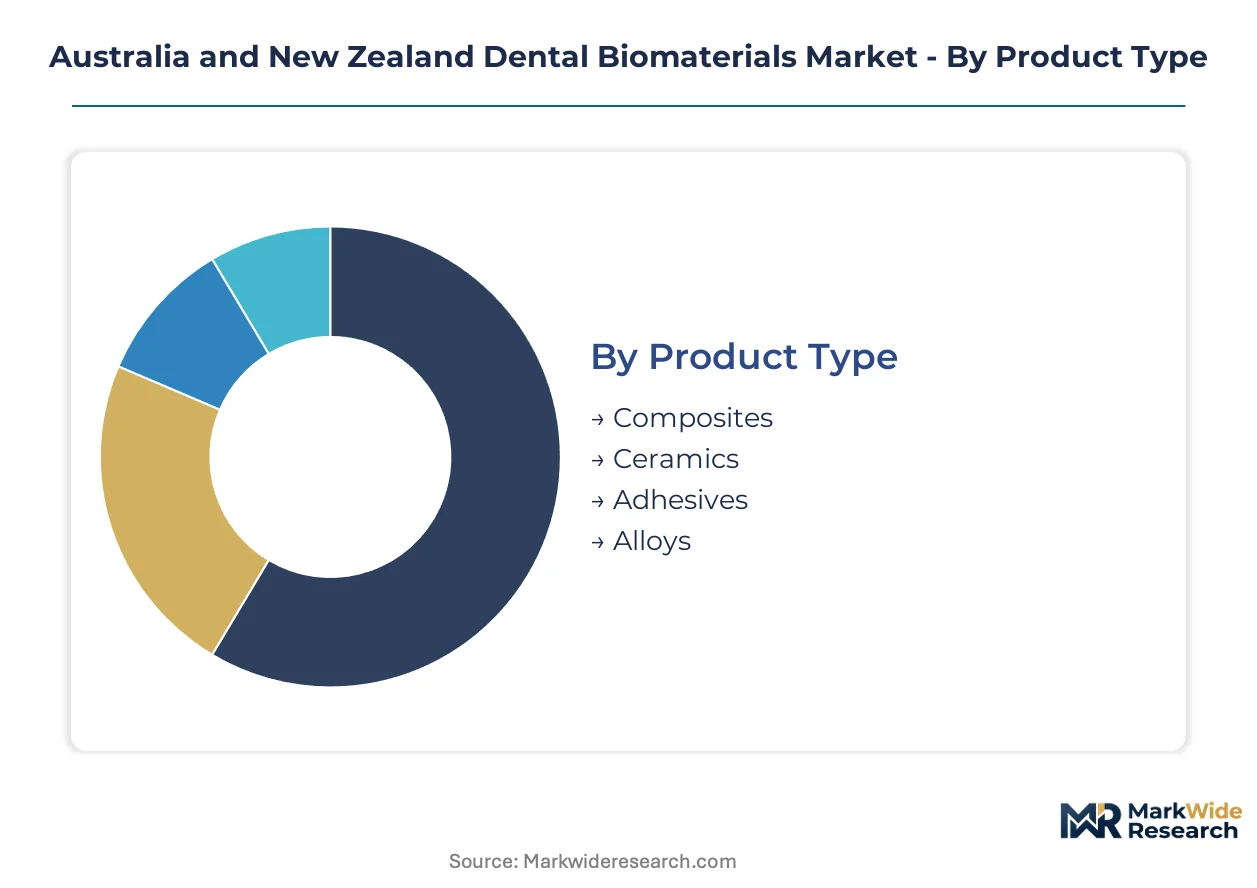
Product Type:
TGA's medical device classifications impose divergent evidence requirements across material categories, with Class III bone-contacting products facing substantially extended registration timelines compared to surface-restorative materials.
- Composites:These resin-based restorative materials incorporate silica or zirconia fillers for aesthetic matching and wear resistance. Sydney and Melbourne private clinics drive volume through direct posterior restorations and core buildups, with nanohybrid formulations commanding premium positioning due to improved polishability and shade stability under Australian private health reimbursement tiers.
- Ceramics:Zirconia, lithium disilicate, and feldspathic porcelain systems serve crown, bridge, and veneer applications. CAD/CAM-milled ceramic restorations are displacing traditional laboratory fabrication across Australian metropolitan practices as chairside milling investments accelerate, though zirconia precursor cost volatility compresses manufacturer margins.
- Adhesives:Etch-and-rinse, self-etch, and universal bonding agents enable substrate-specific adhesion protocols.
- Alloys:Precious and non-precious metal compositions persist in crown substructures and removable partial denture frameworks.
Leading the category by volume: Composites. Growing fastest: Ceramics.
End User:
Procurement authority concentrates differently across customer types, with group practice networks exercising centralized purchasing leverage that individual operators cannot match.
- Dental Clinics:Private practices across Australian capital cities and New Zealand urban centers generate the dominant consumption share, with Sydney and Melbourne group practices consolidating supplier relationships for ceramic and composite procurement transparency.
- Hospitals:Public and private hospital dental departments manage complex trauma, oncology, and maxillofacial reconstruction cases requiring specialized biomaterial protocols.
- Research Institutions:University dental schools and clinical trial centers in Brisbane, Perth, and Auckland evaluate novel regenerative materials under TGA's tightened evidence requirements.
- Laboratories:Commercial dental laboratories fabricate indirect restorations from impressions submitted by referring clinicians, with digital workflow adoption fragmenting traditional outsourcing revenue pools.
Highest procurement sophistication: Dental Clinics. Fastest channel evolution: Laboratories.
Application:
Clinical indication determines reimbursement eligibility and biomaterial specification intensity, with restorative procedures commanding the most established private health insurance pathways.
- Restorative Dentistry:Crown, bridge, inlay, and direct filling applications consume the majority of composite and ceramic volumes across Australian practices.
- Orthodontics:Temporary anchorage devices and bracket bonding systems utilize specialized alloy and adhesive formulations.
- Periodontics:Bone graft substitutes and guided tissue regeneration membranes face TGA's stricter clinical evidence requirements following reclassification, redirecting manufacturer investment toward Australian investigator network development.
- Endodontics:Root canal obturation materials including gutta-percha and bioceramic sealers serve pulp therapy protocols.
Deepest regulatory complexity: Periodontics. Steepest expansion trajectory: Restorative Dentistry.
Technology:
Capital equipment integration creates vendor lock-in effects that constrain biomaterial switching costs and shape procurement consolidation patterns.
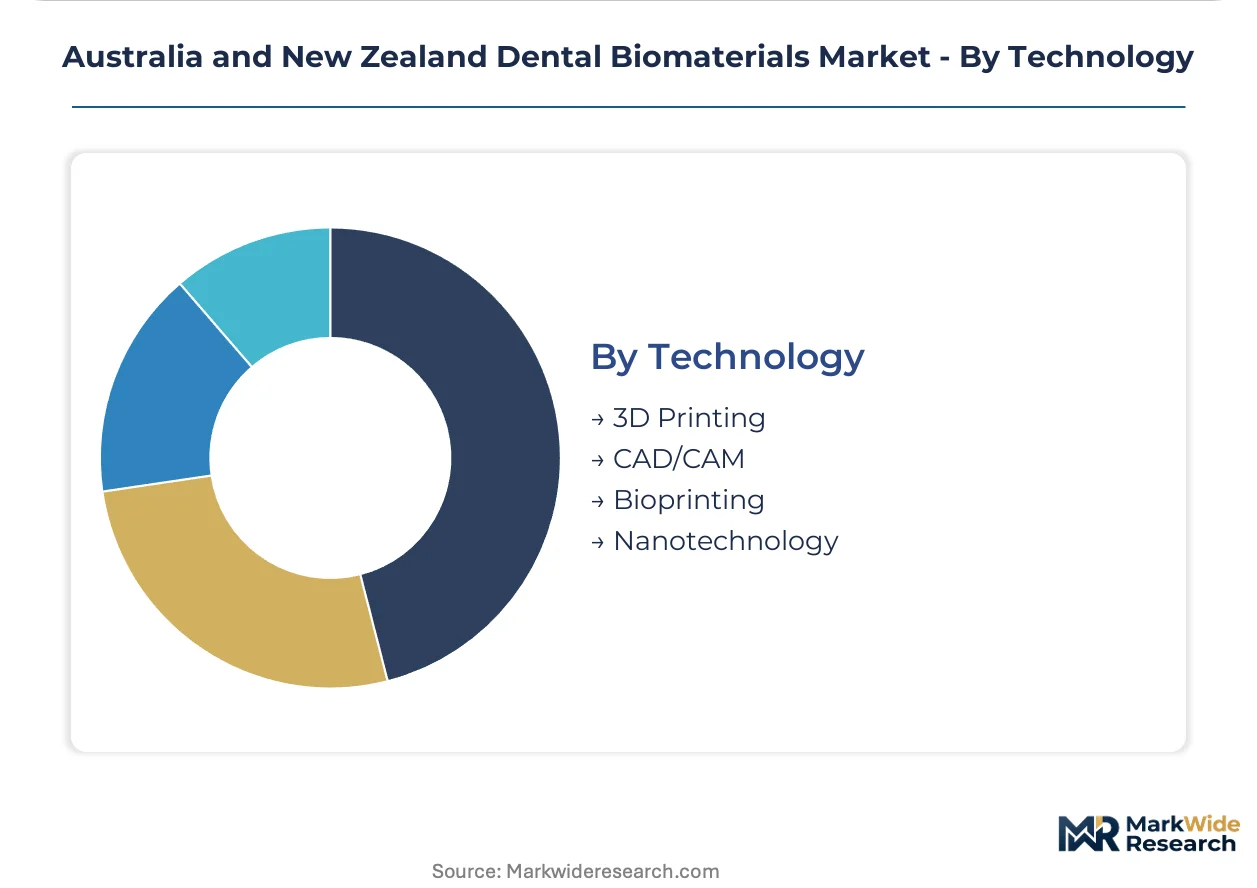
- 3D Printing:Photopolymer and metal additive manufacturing systems produce surgical guides, models, and provisional restorations.
- CAD/CAM:Chairside intraoral scanning and milling systems streamline ceramic restoration production across Australian metropolitan practices, reducing multi-appointment protocols and laboratory dependency while creating technician skill bottlenecks in regional markets.
- Bioprinting:Experimental tissue engineering approaches target periodontal and alveolar bone regeneration.
- Nanotechnology:Nanoparticle-enhanced adhesive systems combining improved bond durability with reduced technique sensitivity represent an emerging margin pool as practitioners seek clinical efficiency gains in Sydney and Melbourne high-volume practices.
Widest installed base: CAD/CAM. Most emergent positioning: Nanotechnology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australian biomaterial production concentrates in Sydney and Melbourne manufacturing clusters, while New Zealand relies on import channels through Auckland distribution hubs. Consumption patterns diverge between metropolitan private practices and regional clinics facing supply chain extension challenges.
New South Wales
Sydney dental clinic networks drive composite and ceramic procurement volumes through consolidated group purchasing arrangements. TGA's medical device framework governs all product registrations entering NSW distribution channels. Parramatta and North Sydney implant-biomaterial integration specialists are expanding chairside CAD/CAM capacity.
Victoria
Melbourne metropolitan practices generate concentrated demand for nanohybrid composite systems and lithium disilicate ceramic restorations. The Therapeutic Goods Administration's biocompatibility testing protocols extend registration timelines for novel regenerative materials seeking Victorian market entry. Box Hill and Southbank dental technology clusters are attracting CAD/CAM equipment distributors.
Queensland
Brisbane group practices are consolidating supplier relationships for cost transparency in ceramic restoration procurement. Henry Schein's regional logistics infrastructure extension creates channel access for biomaterial suppliers targeting underserviced Gold Coast and Sunshine Coast markets. Queensland Health procurement frameworks influence public hospital dental department purchasing patterns.
Western Australia
Perth private clinics exhibit growing ceramic restoration demand alongside persistent technician scarcity for digital workflow operation. Medsafe harmonization with Australian TGA standards under trans-Tasman mutual recognition agreements simplifies product registration for WA-imported materials. Fremantle and Subiaco dental clusters are experiencing CAD/CAM equipment installation rates outpacing skilled operator availability.
New Zealand
Auckland and Wellington dental networks are decoupling from traditional bundled supply contracts toward component-level purchasing arrangements. New Zealand's Medsafe oversight aligns with Australian regulatory standards, reducing dual-market compliance burden for compliant manufacturers. Christchurch practices are adopting intraoral scanning systems at accelerating rates, fragmenting traditional laboratory outsourcing revenue pools.
Australia and New Zealand Dental Biomaterials Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the Australia and New Zealand Dental Biomaterials Market, creating a tiered competitive structure. Swiss and German implant-biomaterial integrators occupy premium positioning through metropolitan practice penetration. Broad restorative portfolio suppliers anchor distribution networks throughout both countries. Supply chain specialists control regional channel access via logistics infrastructure extension. Dominant competitive moves include strategic partnerships with CAD/CAM equipment vendors and portfolio diversification into nanotechnology-enhanced adhesive systems.
Within the premium-tier implant-biomaterial segment, Straumann Holding AG and Geistlich Pharma AG exemplify Swiss-based specialists leveraging integration capabilities across Australian metropolitan practices. Among diversified restorative portfolio suppliers, Dentsply Sirona and 3M Company occupy positions spanning composite, ceramic, and adhesive categories throughout New Zealand distribution channels. Henry Schein Inc. represents the supply chain archetype, anchoring regional market access through logistics infrastructure extension into Queensland and Western Australia.
| Leading Market Players |
|---|
| Straumann Holding AG |
| Zimmer Biomet Holdings |
| Dentsply Sirona |
| 3M Company |
| Geistlich Pharma AG |
| Ivoclar Vivadent AG |
| GC Corporation |
| Kuraray Co., Ltd. |
| Henry Schein Inc. |
| Others |
Cost & Logistics Intelligence
Zirconia precursor costs trace from Chinese rare earth refineries through German ceramic manufacturers into Australian dental laboratory pricing tiers, with TGA biocompatibility certification premiums separating premium restorative materials from economy-grade alternatives.
Pricing Analysis
Margin tightening in nanohybrid composite tiers reflects zirconia filler cost volatility and ISO 10993 testing surcharge pass-throughs. Three-tier pricing structure across premium, standard, and economy levels stratifies by TGA registration pathway complexity and chairside CAD/CAM compatibility. Pricing pressure intensifies in ceramic restoration segments as Auckland group practices consolidate procurement volumes for direct manufacturer negotiation. Dental clinics in Queensland and Western Australia regional markets exhibit highest price sensitivity due to freight cost absorption, while Sydney metropolitan implant-biomaterial integrators maintain lowest sensitivity through premium patient out-of-pocket structures.
Supply Chain Analysis
Single-source vulnerability sits with Chinese rare earth oxide suppliers feeding zirconia precursor production for Australian ceramic restoration manufacturers. Manufacturing concentration spans Germany, Switzerland, and Japan for precision-milled ceramic blanks and nanocomposite resin formulations. Raw material dependencies include yttrium-stabilized zirconia, lithium disilicate ingots, and silane coupling agents. Supply chain risk centers on trans-Pacific logistics chokepoints affecting Perth and Auckland distribution timelines. Distribution runs through Henry Schein's regional warehousing infrastructure with last-mile extension into Queensland and Western Australia dental clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where upstream ceramic precursor supply and downstream CAD/CAM equipment lock-in determine margin capture across Australian and New Zealand dental practices.
For Market Incumbents: Acquire chairside milling equipment distribution rights to anchor biomaterial consumable pull-through across Sydney and Melbourne metropolitan practices. Consolidate nanotechnology adhesive patent positions against emerging Korean and Japanese entrants seeking TGA fast-track pathways. Defensive priority rests on backward integration into zirconia precursor supply through offtake agreements with Australian rare earth processors, neutralizing Chinese supply volatility exposure. For New Entrants and Emerging Players: Nanotechnology-enhanced universal bonding agents with reduced technique sensitivity offer the most penetrable wedge for Queensland and Western Australia regional clinic acquisition. Target underserviced Perth and Gold Coast dental clusters where technician scarcity creates demand for simplified adhesive protocols. Go-to-market angle emphasizes TGA pre-submission consultation investment to compress registration timelines against established competitor product cycles. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap ceramic restoration manufacturers with existing ISO 13485 certification infrastructure in Victoria and New South Wales. Long-term viability hinges on dual-market TGA-Medsafe registration asset value through trans-Tasman mutual recognition pathway exploitation. Acquisition target archetype combines CAD/CAM equipment integration capabilities with established Australian investigator networks for bone graft substitute clinical evidence generation. Signal to watch is private health insurer reimbursement tier expansion for premium ceramic restorations, indicating patient out-of-pocket tolerance inflection.| Strategic Initiative | Industry Significance |
|---|---|
| CAD/CAM Equipment Integration Partnership | Locks in biomaterial consumable demand through chairside milling system installation across Sydney and Melbourne practices. |
| TGA Pre-Submission Consultation Investment | Compresses novel adhesive registration timelines against competitors relying on standard review cycles. |
| Regional Logistics Infrastructure Extension | Henry Schein's Queensland and Western Australia warehousing creates channel access for nanotechnology product launches. |
| Australian Investigator Network Development | Builds clinical evidence capacity for bone graft substitute reclassification compliance under tightened TGA frameworks. |
| Backward Integration into Zirconia Precursor Supply | Neutralizes Chinese rare earth volatility exposure for ceramic restoration manufacturers serving Australian laboratories. |
Research Approach
Document review covered TGA medical device registration databases, ISO 10993 biocompatibility testing protocols, and Australian private health insurance reimbursement schedules, complemented by interviews with dental clinic procurement officers, CAD/CAM equipment distributors, ceramic restoration manufacturers, and TGA regulatory consultants. Secondary validation drew from hospital procurement databases, dental laboratory outsourcing revenue disclosures, and Medsafe harmonization guidance documents. Bottom-up demand modeling from clinic-level biomaterial consumption patterns triangulated against top-down manufacturer shipment data across the analysis window.
Market size and growth trajectory outputs reflect segment-level modeling across product type, end user, application, and technology dimensions with regional disaggregation for New South Wales, Victoria, Queensland, Western Australia, and New Zealand. CAGRs derived from procedure volume elasticity to private health insurance coverage expansion, CAD/CAM equipment installation rates, and TGA registration pipeline throughput. Industry-specific forecast inputs incorporated zirconia precursor price indices and dental technician labor availability metrics for regional Australian markets.
Several conditions sit outside the modeled scope, including unannounced TGA reclassification decisions, abrupt private health insurer reimbursement policy shifts, and disruptive preventive dental technology substitution effects. Forecasts reflect documented assumptions regarding trans-Tasman regulatory harmonization continuity and rare earth supply chain stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Materials
Fluoride-Free Toothpaste Market
Dental Materials
Global Dental Membrane and Bone Graft Substitutes Market
Dental Materials
Dental Fluoride Varnish Market
Dental Materials
Dental Zirconia Powder Market
Dental Materials
Remineralizing Gum Market
Dental Materials
Dental Fiber Posts Market
Dental Materials
Oral Care Chemicals Market
Dental Materials
Fluoride Mouthwash Market
Dental Materials
Dental Cavity Filling Material Market
Dental Materials
Acrylic Dental Material Market
Dental Materials
Dental Restorative and Regenerative Material Market
Dental Materials
Dental Resins Market
Dental Materials
Calcium Hydroxylapatite Fillers Market
Dental Materials
Nanotechnology Toothpaste Formulations Market
Dental Materials
Global Demineralized Bone Matrix Market
Dental Materials
Zirconia Based Dental Ceramics Market