
 Dental Composites Market | 2026-2036
Dental Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Composites Market Outlook
Cosmetic dentistry is pivoting toward minimally invasive composite veneers and direct bonding procedures, displacing traditional crown preparations in elective cases. Dentsply Sirona leverages its integrated CAD/CAM ecosystem to bundle composite materials with chairside milling workflows. Kerr Corporation anchors the North American professional channel through dense distributor relationships with group dental practices. Ivoclar Vivadent differentiates via its sustained R&D intensity in nanohybrid and bulk-fill resin formulations.
Dental composites are tooth-colored restorative materials comprising a resin matrix—typically bis-GMA, UDMA, or TEGDMA—reinforced with inorganic filler particles such as silica, zirconia, or barium glass, with filler loading by weight commonly ranging from 70% to 85% to optimize mechanical properties and polishability. These materials polymerize via light-curing activation to restore form and function in carious or fractured teeth while matching natural tooth aesthetics. The product type dimension shows fillings commanding the volume base due to recurrent caries incidence, while adhesives capture disproportionate margin contribution from universal bonding agent premiums. Within application, restorative dentistry remains the mature workhorse segment, whereas cosmetic dentistry exhibits the fastest trajectory as social media visibility and patient-funded elective spending reshape practice economics.
The FDA regulates dental composites as Class II medical devices requiring 510(k) premarket notification, while the EU MDR imposes strengthened clinical evidence and post-market surveillance obligations on resin-based restorative products. ISO 4049 sets international standards for polymer-based restorative materials, governing properties such as flexural strength, water sorption, and color stability that manufacturers must demonstrate for market access. Stakeholders should monitor evolving biocompatibility scrutiny around bisphenol-A derivatives and unpolymerized monomer leachables, as regulatory tightening on endocrine-disrupting chemicals could force reformulation investments across incumbent supplier portfolios.
Market Dynamics
The EU Medical Device Regulation (MDR) and REACH compliance frameworks are forcing manufacturers to restructure clinical evidence portfolios and supply chain chemical management, compressing margins for resin monomer suppliers while elevating certification barriers for new entrants.
Growth Catalysts
- Amalgam phase-out directives:European environmental regulations restricting mercury-containing dental materials are accelerating composite substitution in public health systems and private clinics across Germany, France, and Italy.
- Minimally invasive technique adoption:Direct composite bonding and no-prep veneer protocols are displacing traditional crown preparations in elective cosmetic cases, expanding addressable procedure volumes.
- Silica nanofiller R&D intensity:Advances in surface-treated silica and zirconia-silica hybrid particles are improving wear resistance and polish retention, justifying premium pricing in aesthetic restoration segments.
Market Restraints
- Bis-GMA monomer cost volatility:Petrochemical feedstock fluctuations and bisphenol-A supply constraints are compressing formulation margins for conventional resin matrices.
- Photoinitiator supply concentration:German and Swiss specialty chemical producers dominate camphorquinone and TPO photoinitiator supply, creating single-source vulnerability for light-cure composite manufacturers.
- Polymerization shrinkage limitations:Residual stress from volumetric contraction during curing continues to compromise marginal integrity in large Class II restorations, restricting bulk-fill material applicability.
Strategic Opportunities
- Brazilian private dental clinic expansion:Underpenetrated middle-class cosmetic dentistry demand in São Paulo and Rio de Janeiro clinic networks offers volume growth outside saturated European markets.
- Bioactive glass convergence:Integration of calcium-silicate and fluoride-releasing fillers with conventional resin matrices enables therapeutic positioning for high-caries-risk patient segments.
- Chairside CAD/CAM bundling:Direct-to-practice material workflows tied to intraoral scanning and milling systems are bypassing traditional dental distributor markups.
Industry Challenges
- Shade-matching technician scarcity:Artistic layering and custom characterization skills required for anterior aesthetic cases outpace vocational training pipeline output in most markets.
- ISO 4049 certification timelines:Extended flexural strength and water sorption testing protocols delay product launch windows by 18-24 months for reformulated nanohybrid lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Composites Market |
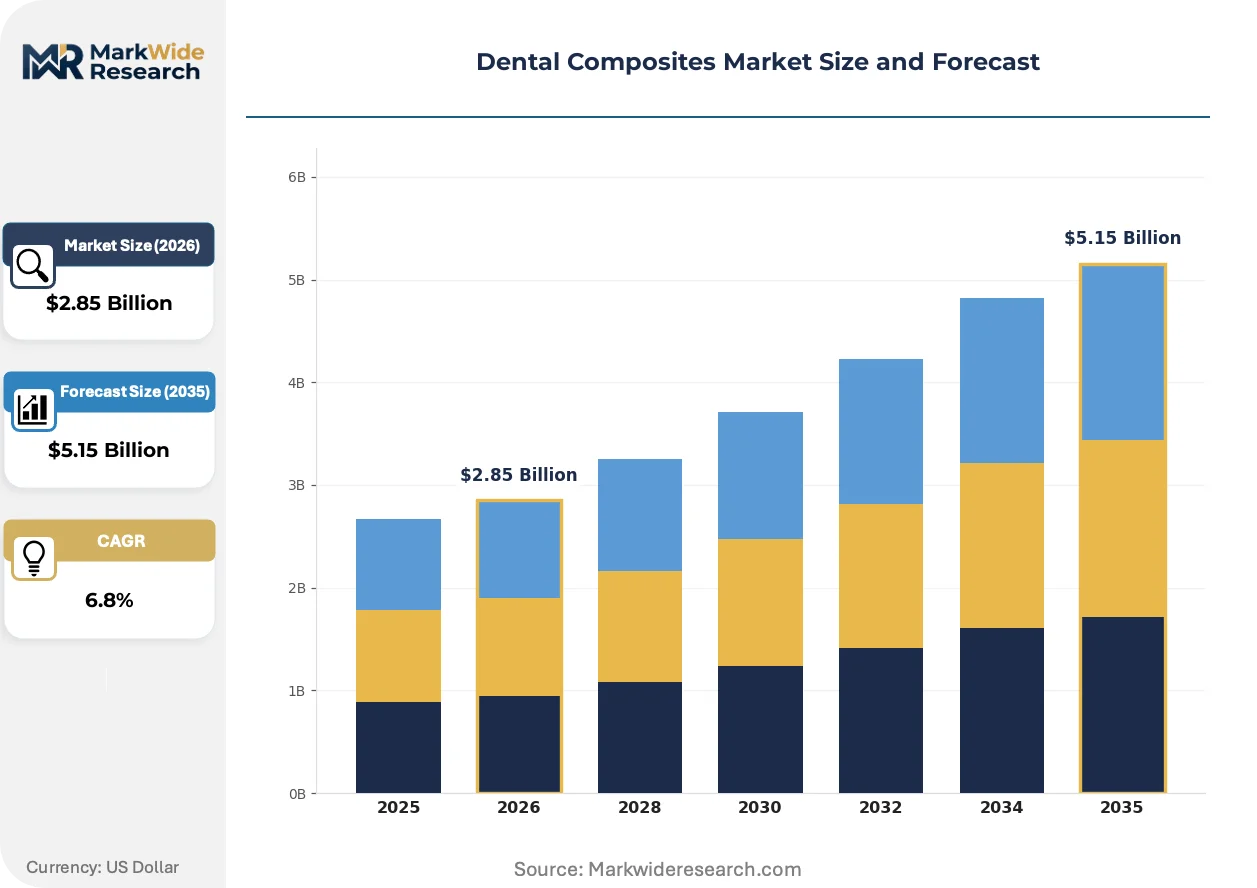
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $5.15 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fillings, Adhesives, Sealants, Core Build-up End User: Dental Clinics, Hospitals, Research Laboratories, Dental Schools Application: Cosmetic Dentistry, Restorative Dentistry, Preventive Care, Surgical Procedures Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | Kerr Corporation, Kuraray Noritake Dental, 3M, Shofu Dental, VOCO GmbH, Dentsply Sirona, GC Corporation, BISCO Dental, Ivoclar Vivadent, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Composites Market Strategic Shifts
Material science breakthroughs and regulatory chemical scrutiny are converging to redefine performance benchmarks and biocompatibility thresholds across restorative and aesthetic applications.
Bulk-fill resin technology is rewriting procedural economics in high-volume general practice settings. These formulations permit 4-5mm incremental placement without compromising cure depth, cutting chair time by 30-40% for posterior restorations. German and Dutch group dental practices are standardizing on bulk-fill protocols for routine Class I and II cases, compressing demand for incremental layering systems.
REACH authorization requirements for bisphenol derivatives are forcing systematic monomer substitution across European supply chains. Manufacturers must demonstrate safe use for TEGDMA and UDMA alternatives or secure sunset date extensions, diverting R&D expenditure from performance innovation toward toxicological dossier preparation. German dental material suppliers with captive chemical synthesis capabilities are internalizing regulatory compliance costs that toll compounders cannot absorb.
Patient-funded aesthetic spending is fragmenting procurement authority within dental practices. Social media-driven smile makeover demand empowers individual clinicians to specify premium nanohybrid and microfill materials regardless of group purchasing organization contracts. This pattern concentrates in urban UK and US coastal markets where elective procedure penetration exceeds national averages by 2-3x.
Dental Composites Market Segmentation
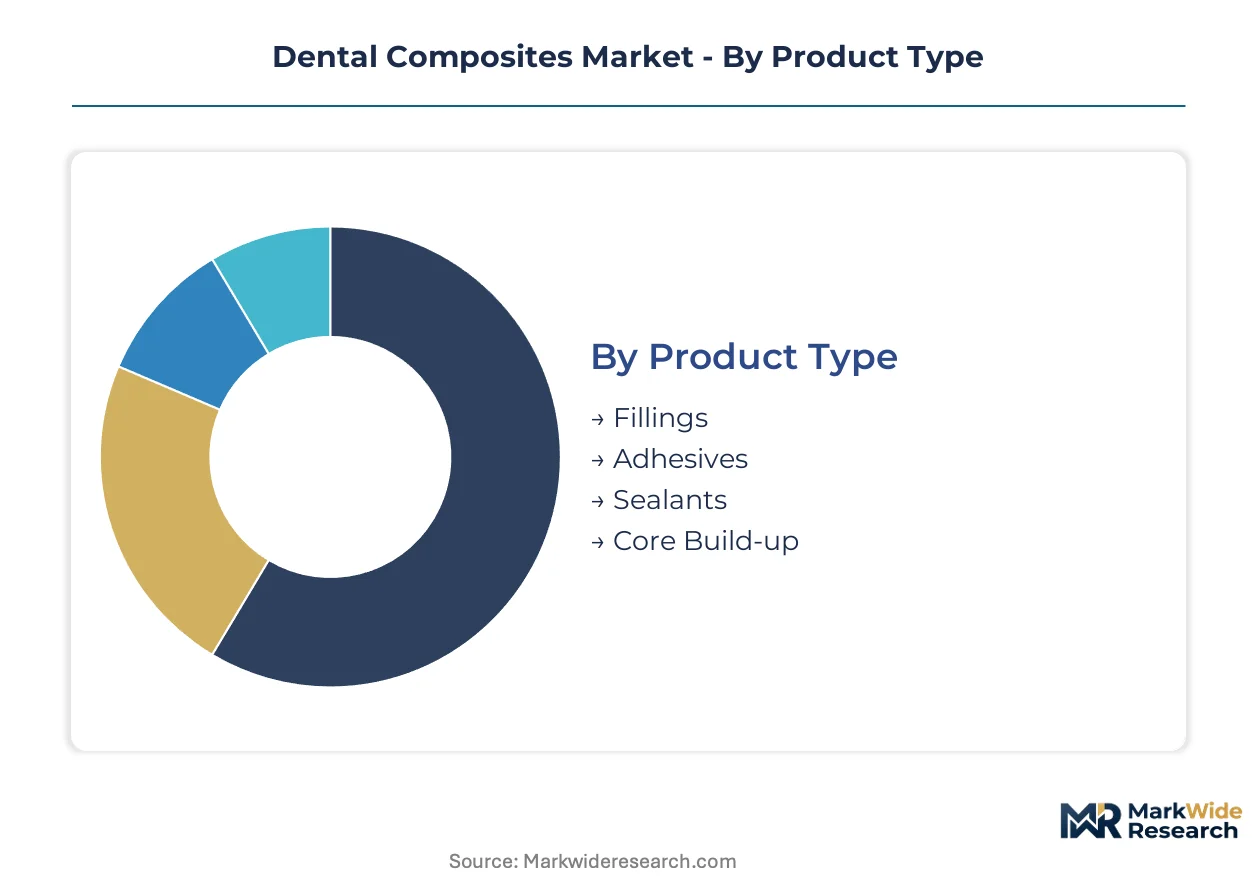
Dental composites manufacturers configure production assets around resin viscosity grades and filler loading specifications that align with distinct clinical workflows. Segmentation discipline separates high-throughput restorative materials from premium aesthetic formulations requiring artisanal handling.
Product Type:
Supply concentration in bis-GMA and UDMA monomer synthesis favors integrated chemical producers with captive filler surface-treatment capabilities.
- Fillings:Nanohybrid and microhybrid composites dominate posterior restorations with filler loadings of 75-85% by weight for optimized wear resistance. German private dental clinics and Dutch group practices absorb the highest volumes as amalgam substitution accelerates under EU environmental directives. Demand concentrates in high-caries-risk adult populations requiring durable Class I and II restorations.
- Adhesives:Universal bonding agents command disproportionate margin contribution through simplified clinical protocols and reduced technique sensitivity. North American group purchasing organizations negotiate exclusive supply contracts for etch-and-rinse and self-etch systems, concentrating procurement authority in distributor networks serving multi-location practices.
- Sealants:Low-viscosity resin formulations with reduced filler content enable flowable application in pediatric and orthodontic indications.
- Core Build-up:High-compressive-strength materials support crown foundation preparations in endodontically treated teeth.
Fillings absorb the bulk of installed capacity; adhesives is expanding most quickly.
End User:
Cost tier stratification separates premium chairside materials from economy bulk formulations serving institutional procurement.
- Dental Clinics:Private single-operator and group practices drive specification authority for nanohybrid and bulk-fill composites through clinician-directed purchasing. Urban UK and US coastal markets exhibit 2-3x elective procedure penetration versus national averages, concentrating demand for characterization kits and shade-matching accessories.
- Hospitals:Academic medical centers and public health systems standardize on value-engineered formulations through centralized procurement, prioritizing infection control compatibility and storage stability over aesthetic performance.
- Research Laboratories:Dental material science departments at universities in Switzerland and Japan evaluate experimental monomer systems and bioactive filler integrations.
- Dental Schools:Vocational training institutions in Brazil and India consume high volumes of economy-grade composites for student technique development.
Dental clinics command the dominant share of premium product flow; dental schools represent the steepest volume expansion trajectory in emerging markets.
Application:
Volume concentration in restorative procedures contrasts with margin expansion in patient-funded aesthetic segments.
- Cosmetic Dentistry:Direct composite veneers and no-prep bonding protocols displace traditional crown preparations in elective cases, requiring artistic layering skills and custom characterization. Social media visibility drives patient-funded demand in São Paulo, Dubai, and Los Angeles aesthetic clinics.
- Restorative Dentistry:Recurrent caries treatment and fracture repair constitute the mature workhorse segment with predictable reimbursement pathways.
- Preventive Care:Pit-and-fissure sealants and preventive resin restorations target pediatric and adolescent populations in school-based programs.
- Surgical Procedures:Guided bone regeneration and periodontal defect repair utilize composite barrier membranes with specialized handling properties.
Restorative dentistry anchors volume throughput; cosmetic dentistry gains share fastest.
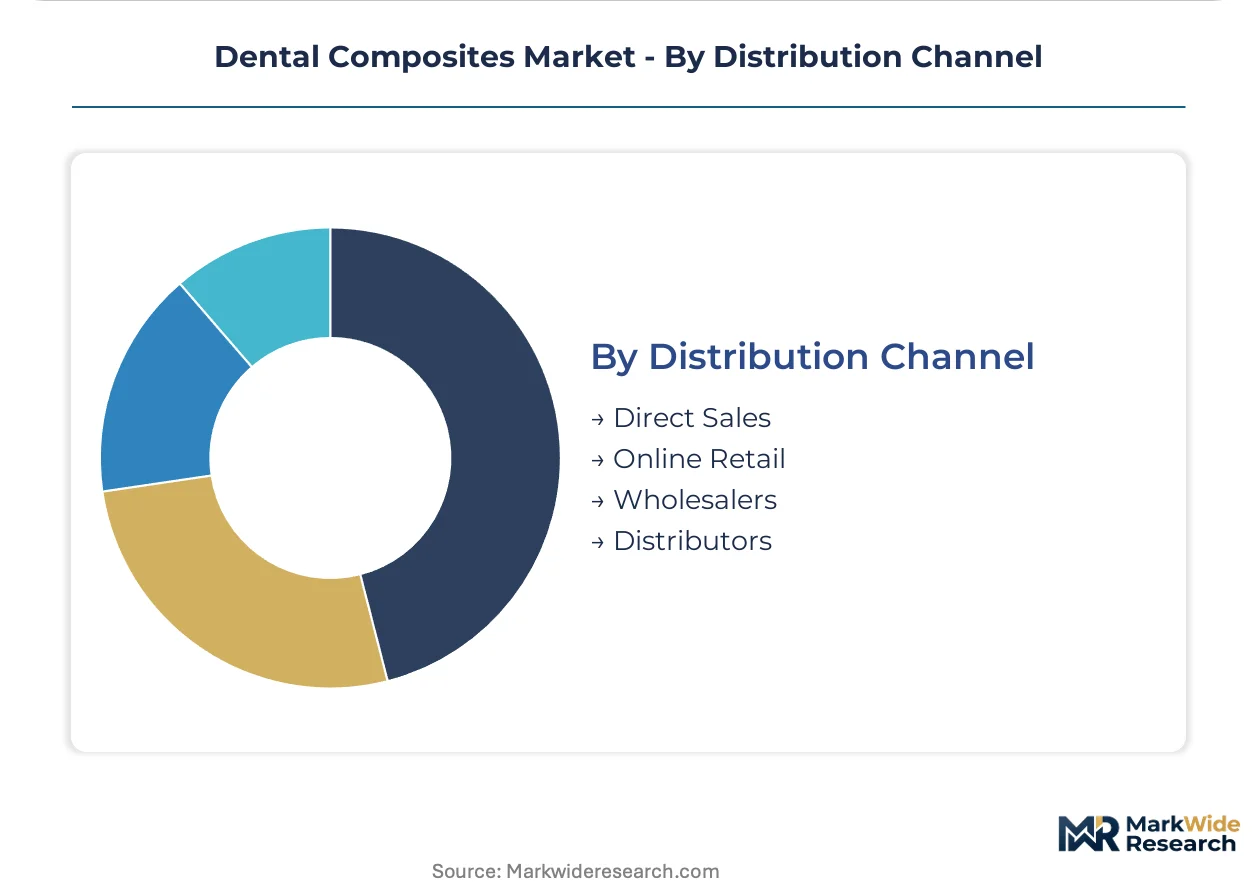
Distribution Channel:
Customer type fragmentation between independent clinicians and consolidated group practices reshapes channel economics.
- Direct Sales:Manufacturers with chairside CAD/CAM ecosystems bypass traditional distributor markups through integrated material-and-equipment bundling. Dentsply Sirona and Ivoclar Vivadent deploy dedicated field representatives to high-volume group practices.
- Online Retail:E-commerce platforms capture growing share of consumables and small-equipment sales from solo practitioners.
- Wholesalers:Regional dental supply houses maintain inventory positions for routine restorative materials.
- Distributors:National distributor networks like Henry Schein and Patterson Dental dominate North American professional channel logistics.
Distributors handle the majority of transaction volume; direct sales is climbing the fastest as equipment bundling expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German dental laboratory clusters in the Rhine-Ruhr and Bavaria regions concentrate premium composite formulation capacity, while REACH authorization zones for bisphenol derivatives reshape monomer supply economics across European manufacturing nodes.
Germany
Private dental clinics in Munich and Hamburg drive nanohybrid composite volumes for aesthetic restorations, supported by statutory health insurance reimbursement for posterior composite fillings. The EU MDR imposes strengthened clinical evidence requirements on resin-based products manufactured in Baden-Württemberg formulation plants. The Lake Constance dental technology corridor anchors CAD/CAM material bundling workflows for chairside restoration systems.
United States
Group dental practices in Texas and Florida absorb bulk-fill composite volumes for high-throughput posterior restorations, displacing amalgam in pediatric and adult populations. The FDA's 510(k) premarket notification pathway governs Class II medical device clearance for light-cure resin materials. Henry Schein and Patterson Dental distribution networks concentrate procurement authority across multi-location practice chains in the Southeast and Southwest.
Japan
Universities in Osaka and Tokyo evaluate experimental monomer systems and bioactive glass integrations for next-generation restorative materials. METI industrial standards coordination influences JIS specification adoption for polymer-based dental materials. The Nagoya medical device manufacturing cluster houses precision filler surface-treatment facilities serving pan-Asian composite supply chains.
Brazil
Private aesthetic clinics in São Paulo and Rio de Janeiro expand direct composite veneer volumes for patient-funded smile makeover procedures. ANVISA medical device registration requirements create compliance barriers for imported resin formulations. The Campinas dental materials industrial park hosts regional compounding operations for Latin American distribution networks.
Switzerland
Swissmedic oversight of dental material biocompatibility elevates certification standards for monomer leachable testing protocols. Geneva and Basel dental research institutes pioneer fluoride-releasing filler integrations for high-caries-risk patient segments. The Swiss chemical synthesis corridor supplies surface-treated silica and zirconia particles to German and Italian composite manufacturers.
Dental Composites Market Competitive Environment
Top-tier vendors anchor integrated material-equipment ecosystems, while mid-tier compounders compete on formulation specialization and regional distributor relationships. The vendor base separates into three strategic archetypes: multinational dental conglomerates with captive chemical synthesis, regional specialists with deep professional channel penetration, and emerging bioactive material innovators. Capacity consolidation and M&A activity concentrate formulation assets among integrated players, while technology licensing agreements proliferate for photoinitiator and nanofiller patents.
Within the multinational conglomerate tier, Dentsply Sirona, Kerr Corporation, and Ivoclar Vivadent occupy positions defined by equipment bundling capabilities and professional channel density. Dentsply Sirona exemplifies the CAD/CAM-integrated archetype through chairside workflow material lock-in. Kerr Corporation represents North American distributor-centric positioning with dense group practice relationships. Ivoclar Vivadent anchors premium nanohybrid and bulk-fill formulation specialization. These three entities collectively illustrate how competitive advantage in dental composites converges on either workflow integration, channel control, or material science depth.
| Leading Market Players |
|---|
| Kerr Corporation |
| Kuraray Noritake Dental |
| 3M |
| Shofu Dental |
| VOCO GmbH |
| Dentsply Sirona |
| GC Corporation |
| BISCO Dental |
| Ivoclar Vivadent |
| Others |
Value Chain & Pricing Dynamics
EU mercury phase-out directives and REACH authorization protocols for bisphenol derivatives gate qualified supply access and premium-tier pricing power. Manufacturers absorbing toxicological dossier preparation costs for TEGDMA and UDMA alternatives recoup through nanohybrid formulation premiums, while uncertified compounders face exclusion from German and Dutch clinic procurement.
Pricing Analysis
Short lead-time premiums for camphorquinone photoinitiator spot purchases compress margins for light-cure composite producers facing German and Swiss specialty chemical supply bottlenecks. Three-tier pricing structure across premium nanohybrid, standard microhybrid, and economy bulk-fill levels separates ISO 4049-certified formulations from uncertified imports. Price differentiation hinges on filler surface-treatment sophistication and REACH compliance documentation depth. Cost compression in economy-grade segments intensifies as Brazilian and Indian dental schools drive volume procurement of training materials. Group purchasing organizations in North America exhibit highest price sensitivity; private aesthetic clinics in São Paulo and Dubai demonstrate lowest sensitivity for characterization kits.
Supply Chain Analysis
Bis-GMA and UDMA monomer supply rests on German and Swiss captive chemical synthesis facilities with integrated filler surface-treatment capabilities. Raw material dependencies include surface-treated silica particles from the Lake Constance corridor, zirconia-silica hybrid fillers from Nagoya precision treatment plants, and TPO photoinitiators from Basel specialty producers. Single-source vulnerability in photoinitiator supply creates structural risk for light-cure formulation manufacturers. Distribution runs through Henry Schein and Patterson Dental networks for North American group practices, while direct sales channels expand for CAD/CAM-integrated material bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive monomer synthesis and filler surface-treatment capabilities determine margin defense. Players pursuing upstream control over bis-GMA supply and downstream lock-in through chairside workflow bundling capture sustainable positioning.
For Market Incumbents: Extend formulation asset control through backward integration into photoinitiator supply or exclusive filler surface-treatment partnerships with Swiss chemical producers. Dentsply Sirona and Ivoclar Vivadent should deepen CAD/CAM ecosystem lock-in to defend against distributor-disintermediation threats from direct-to-practice digital workflows. Certification investment in EU MDR clinical evidence portfolios creates switching costs for German clinic procurement committees. For New Entrants and Emerging Players: Mid-tier group dental practices in Brazil's São Paulo corridor represent an underserved buyer archetype with expanding cosmetic procedure volumes and limited loyalty to incumbent distributor networks. Bioactive glass composite formulations for high-caries-risk pediatric segments offer white-space positioning outside saturated nanohybrid competition. ANVISA regulatory compliance partnerships with Campinas industrial park compounders provide go-to-market acceleration for Latin American distribution. For Investors and Strategic Acquirers: REACH sunset date extensions for bisphenol derivative monomers are the leading indicator that reformulation R&D intensity will concentrate among integrated chemical producers with toxicological dossier capabilities. Five-to-ten year viability favors manufacturers with captive synthesis assets over toll compounders exposed to raw material cost volatility. Acquisition targets should display ISO 4049 certification pipelines and Brazilian or Indian clinic channel relationships. Watch for EU MDR notified body capacity constraints delaying competitor product launches.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Synthesis | German suppliers internalize REACH compliance costs that toll compounders cannot absorb. |
| CE Marking Pathway Investment | EU MDR clinical evidence requirements elevate barriers for resin-based restorative products. |
| Chairside CAD/CAM Bundling | Dentsply Sirona and Ivoclar Vivadent bypass distributor markups through integrated workflows. |
| Bioactive Glass Formulation Development | Calcium-silicate filler integrations enable therapeutic positioning in high-caries-risk segments. |
| ANVISA Registration Partnership | Campinas industrial park alliances accelerate Brazilian market access for imported formulations. |
Study Parameters
Independent corroboration across dental material procurement managers at German group practices, regulatory affairs leads at Swiss chemical suppliers, and biomedical engineers at Japanese university laboratories underwrites the qualitative findings. Primary interviews with GPO contracts managers, distributor sales directors, and clinic operations heads combined with secondary validation from FDA 510(k) filings, EU MDR notified body documentation, and ISO 4049 certification records. Bottom-up procedure volume estimates and top-down manufacturer shipment data triangulate market sizing.
Rate-of-change decomposition across product type, application, end user, and distribution channel dimensions structures the analytical framework. Segmentation modeling incorporates filler loading specifications, resin viscosity grades, and regional regulatory cluster variations. CAGRs derive from procedure volume growth trajectories, amalgam substitution rates under environmental directives, and premium material penetration in patient-funded cosmetic segments. Inputs include photoinitiator supply constraints, REACH authorization timelines, and CAD/CAM equipment installation bases.
Revisions become necessary when EU MDR notified body capacity constraints materialize, REACH sunset dates force accelerated monomer substitution, or photoinitiator supply disruptions propagate through light-cure formulation production. Forecasts reflect assumptions around regulatory compliance cost absorption, distributor channel stability, and clinic procurement authority fragmentation. A small set of named triggers—bisphenol derivative toxicological reclassification, Brazilian ANVISA registration pathway changes, and German statutory insurance reimbursement shifts—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Materials
Dental Plaster Market
Dental Materials
Dental Matrix Systems Market
Dental Materials
Dental Cavity Filling Material Market
Dental Materials
Calcium Hydroxylapatite Fillers Market
Dental Materials
Global Zirconia Based Dental Materials Market
Dental Materials
Dental Alginate Market
Dental Materials
Cold Light Teeth Whitening Kit Market
Dental Materials
Asia-Pacific Toothpaste Market
Dental Materials
Dental Gypsum Market
Dental Materials
Dental Impression Material Market
Dental Materials
Oral Bone Implant Material Market
Dental Materials
Dental Bonding Agent Market
Dental Materials
Australia and New Zealand Dental Biomaterials Market
Dental Materials
Global Dental Membrane and Bone Graft Substitutes Market
Dental Materials
Tooth Filling Materials Market
Dental Materials
Dental Fiberglass Posts Market