

Oral Bone Implant Material Market Size, Share, and Industry Trends Forecast 2026-2036
Oral Bone Implant Material Market Insights
Synthetic hydroxyapatite production in Japan is repositioning toward higher-purity grades for dental ridge preservation. Geistlich Pharma leverages its Swiss heritage in collagen-based matrices to sustain premium positioning across European implant centers. Zimmer Biomet anchors North American supply through captive biologics manufacturing, while Dentsply Sirona competes via integrated digital surgical workflows that bundle graft materials with guided implant planning.
Oral bone implant materials comprise biocompatible substances engineered to restore or augment alveolar and maxillofacial bone defects, typically featuring porous architectures with 100-500 μm interconnecting channels to support vascularization and osteoconduction. Hydroxyapatite dominates value share due to its chemical homology with native mineralized tissue, though beta-tricalcium phosphate exhibits faster resorption kinetics that appeal to clinicians pursuing staged implant protocols. Alveolar ridge augmentation commands the largest application segment, while sinus lift procedures represent the fastest-growing indication as edentulous patients seek fixed rehabilitations.
FDA 510(k) premarket notifications and EU MDR conformity assessments govern biocompatibility and sterility standards, with EMA guidance on animal-derived materials shaping collagen matrix acceptance in Europe. Japan's PMDA enforces JIS-compliant mechanical testing for load-bearing maxillofacial applications, creating divergent approval timelines across jurisdictions. Stakeholders must monitor evolving regulatory science on 3D-printed patient-specific graft scaffolds, where novel characterization methods could redefine equivalence benchmarks.
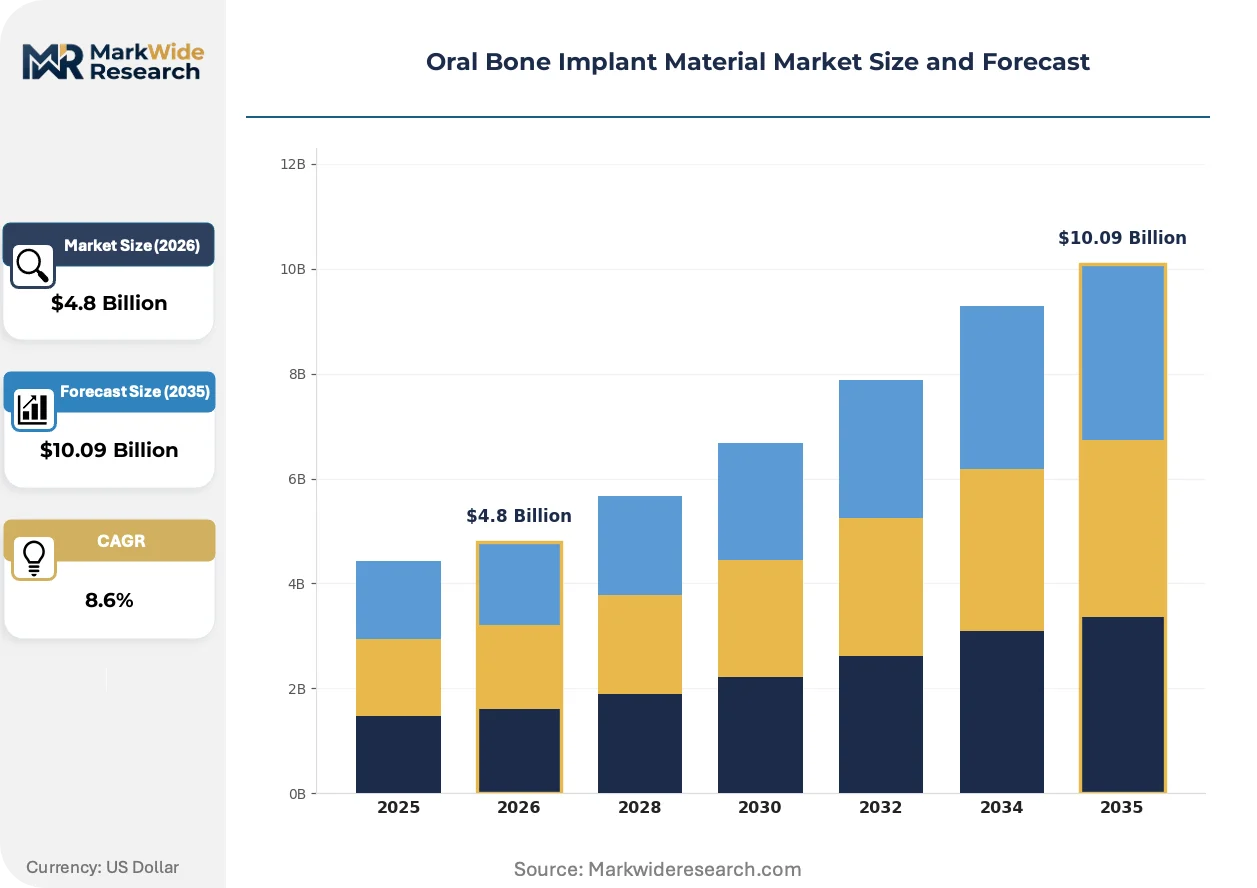
Market Dynamics
The FDA's 510(k) clearance pathway is compressing product development timelines for synthetic graft substitutes, while dental clinics accelerate adoption of ridge preservation materials ahead of implant placement. This regulatory efficiency is reshaping competitive entry patterns and material sourcing strategies across the value chain.
Growth Catalysts
- Synthetic Hydroxyapatite Advancement:Higher-purity grades manufactured in Japan are displacing xenograft dependence in ridge preservation protocols, with dental clinics in Germany and the United States expanding procurement of mineralized alloplasts.
- EU MDR Conformity Pathways:Streamlined biocompatibility assessments for collagen-based matrices are accelerating product registration across Swiss and German implant centers, reducing time-to-market for regenerative materials.
- Sinus Lift Procedure Expansion:Edentulous patient demand for fixed rehabilitations is driving uptake of beta-tricalcium phosphate in staged implant protocols, particularly in specialized oral surgery clinics.
Market Restraints
- Animal-Derived Material Scrutiny:EMA guidance on collagen matrix sourcing is creating compliance friction for xenograft suppliers, forcing reformulation toward synthetic alternatives with higher R&D burdens.
- Supply Concentration in Biologics:Captive manufacturing networks in North America limit third-party access to demineralized bone matrix, constraining price competition and material availability for independent dental distributors.
- Resorption Rate Mismatch:Clinicians report unpredictable degradation kinetics in composite grafts combining hydroxyapatite with beta-tricalcium phosphate, complicating treatment planning and revision rates.
Strategic Opportunities
- 3D-Printed Patient-Specific Scaffolds:Additive manufacturing convergence with computed tomography data is enabling custom-fit graft architectures for complex maxillofacial defects, with regulatory science at FDA and PMDA still defining equivalence benchmarks.
- Digital Surgical Workflow Bundling:Guided implant planning software integration creates attachment points for graft material placement, with Dentsply Sirona and competitors embedding biologics into CAD/CAM treatment sequences.
- Japan's PMDA Mechanical Testing Standards:JIS-compliant load-bearing specifications for maxillofacial applications are creating premium positioning opportunities for high-strength synthetic grafts in Asian markets.
Industry Challenges
- Biofabrication Talent Scarcity:Tissue engineering expertise required for scaffold vascularization design remains concentrated in academic medical centers, limiting commercial-scale production of advanced graft architectures.
- Sterilization Validation Complexity:Terminal sterilization of collagen matrices without compromising osteoinductive properties demands specialized gamma irradiation protocols, extending batch release timelines.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oral Bone Implant Material Market Trends and Innovations
Additive manufacturing of patient-specific graft scaffolds is redrawing the boundary between off-the-shelf biomaterials and personalized regenerative devices. This technological pivot is forcing recalibration of regulatory frameworks, manufacturing economics, and clinical training pathways.
Three-dimensional printing of ceramic-polymer composite scaffolds is rewriting the economics of complex alveolar defect reconstruction. Oral surgery departments at university hospitals in Germany and Japan are piloting these patient-specific implants for severe ridge atrophy cases. The technology is compressing the traditional multi-stage grafting protocol into single-procedure interventions, threatening conventional particulate graft volumes.
Japan's PMDA enforcement of JIS T 0306 mechanical testing standards for load-bearing maxillofacial grafts is creating divergent approval requirements across jurisdictions. European manufacturers must now maintain separate characterization datasets for Asian market entry, increasing regulatory compliance costs. Synthetic hydroxyapatite producers with existing JIS certification are capturing preferential positioning in Japanese dental implant centers.
Dental clinic procurement of graft materials is consolidating through integrated distributor networks that bundle biologics with implant hardware. Independent oral surgeons in the United States are losing direct purchasing access to specialized regenerative products, instead receiving materials through Dentsply Sirona and Zimmer Biomet captive supply arrangements. This channel restructuring is most visible in metropolitan markets where group dental practices dominate implant volume.
Oral Bone Implant Material Market Segmentation
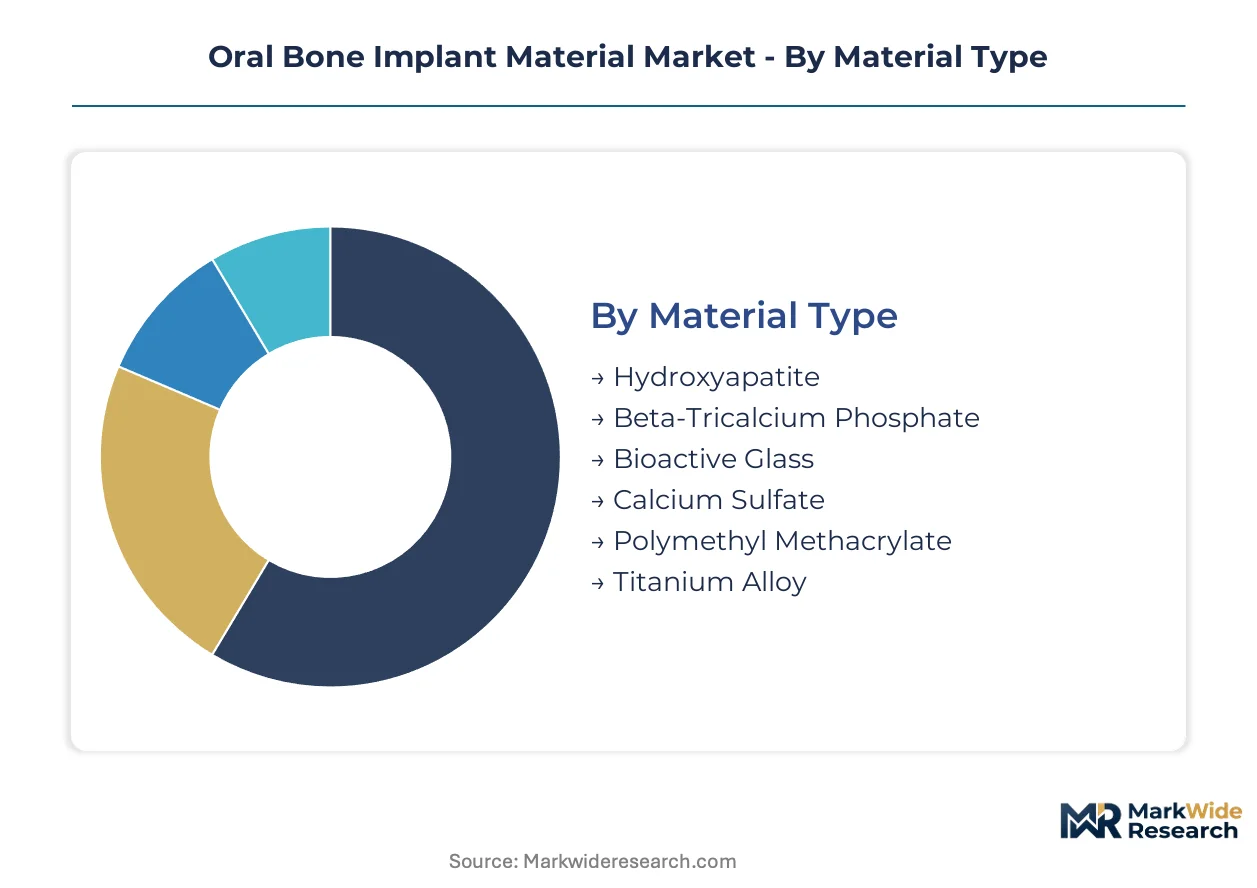
Segmentation in oral bone implant materials determines regulatory pathways, pricing tiers, and procurement channels. Material composition dictates biocompatibility testing requirements, while application type shapes clinical training needs and reimbursement positioning.
Material Type:
FDA 510(k) clearance timelines vary by material chemistry, with synthetic alloplasts moving faster than xenograft alternatives. EMA MDR conformity assessments impose additional scrutiny on animal-derived matrices.
- Hydroxyapatite:Synthetic hydroxyapatite mirrors the calcium-phosphate ratio of native bone mineral, enabling direct osteoconduction without inflammatory response. German and Japanese implant centers favor higher-purity grades for ridge preservation, displacing xenograft dependence amid EMA sourcing guidance.
- Beta-Tricalcium Phosphate:Faster resorption kinetics appeal to clinicians pursuing staged implant protocols with shorter healing windows. Oral surgery clinics in the United States report expanding procurement for sinus lift procedures where rapid remodeling accelerates treatment sequences.
- Bioactive Glass:Silicate-based compositions bond chemically with host tissue, finding niche use in periodontal defect regeneration.
- Calcium Sulfate:Rapid dissolution properties suit temporary space maintenance applications.
- Polymethyl Methacrylate:Acrylic-based permanent fillers serve load-bearing maxillofacial reconstruction.
- Titanium Alloy:Metallic scaffolds integrate with orthopedic trauma fixation systems for severe mandibular defects.
Leading the category by volume: Hydroxyapatite. Growing fastest: Beta-Tricalcium Phosphate.
Form:
Physical configuration determines handling characteristics, sterilization validation complexity, and shelf stability. Putty and paste forms command premium pricing for surgical convenience.
- Granules:Particulate formats with 100-500 μm porosity enable vascularization across defect sites. Dental clinics in metropolitan United States markets receive granules through integrated distributor networks bundling biologics with implant hardware.
- Putty:Moldable consistency eliminates mixing steps chairside, reducing procedure time. Specialized implant centers in Germany pay premium positioning for carrier-mediated delivery systems combining mineral phase with collagen binders.
- Blocks:Pre-formed geometries suit contained ridge defects with intact cortical walls.
- Powder:Reconstitutable formats offer extended shelf life and freight economy.
- Collagen Matrix:Organic scaffolds require gamma irradiation protocols that extend batch release timelines.
- Paste:Injectable rheology enables minimally invasive delivery through trephine sites.
Granules dominate procurement volume. Putty formats are expanding most quickly as group dental practices standardize surgical workflows.
Application:
Procedure complexity determines material selection, with load-bearing applications demanding JIS-compliant mechanical testing for Japanese market entry.
- Alveolar Ridge Augmentation:Horizontal and vertical bone gain procedures consume the largest material volumes across implant dentistry. Ridge preservation protocols in German specialized centers drive synthetic hydroxyapatite uptake ahead of delayed implant placement.
- Sinus Lift:Maxillary sinus elevation for posterior fixed rehabilitation represents the steepest expansion trajectory. Beta-tricalcium phosphate displacement of autograft in two-stage protocols reduces morbidity while maintaining implant survival rates.
- Periodontal Defects:Intrabony and furcation lesions require smaller material quantities per procedure.
- Cleft Palate Repair:Pediatric craniofacial reconstruction demands bioresorbable formats that accommodate growth.
- Maxillofacial Reconstruction:Trauma and oncologic defects require load-bearing scaffolds with defined compressive strength.
- Dental Ridge Preservation:Extraction socket management prevents alveolar collapse prior to implant therapy.
Alveolar Ridge Augmentation leads by procedure volume. Sinus Lift procedures are gaining share fastest as edentulous patients seek fixed alternatives to removable prosthetics.
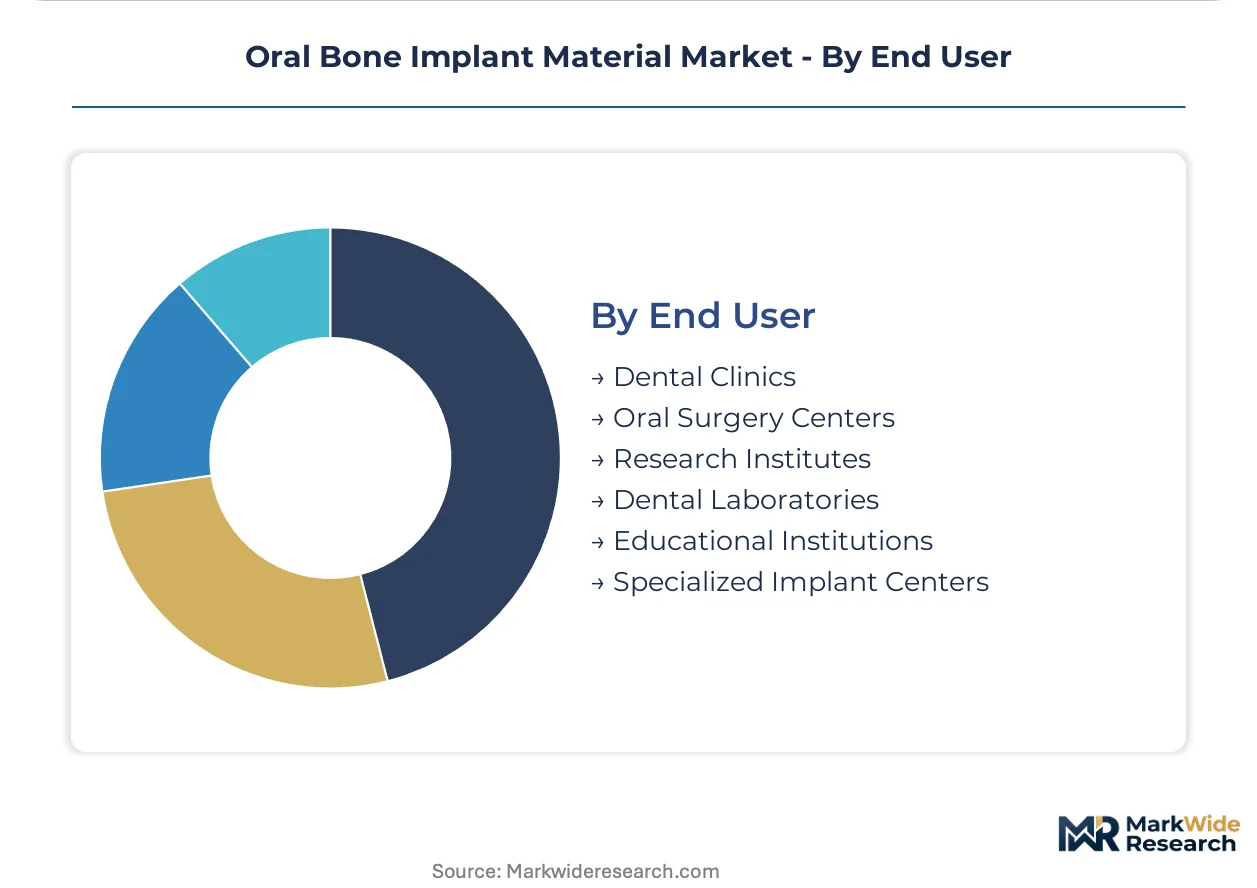
End User:
Procurement authority concentrates through captive supply arrangements, with independent practitioners losing direct purchasing access to specialized regenerative products.
- Dental Clinics:General practice settings perform the majority of routine implant placements and ridge preservation procedures. Consolidation through Dentsply Sirona and Zimmer Biomet distributor networks restricts independent material sourcing in United States metropolitan markets.
- Specialized Implant Centers:Concentrated surgical volume justifies premium material positioning and custom graft architectures. University hospitals in Germany and Japan pilot 3D-printed patient-specific scaffolds for severe ridge atrophy.
- Oral Surgery Centers:Hospital-affiliated departments manage complex maxillofacial trauma and pathology.
- Dental Laboratories:Fabrication partners receive graft materials for integration with CAD/CAM surgical guides.
- Research Institutes:Academic tissue engineering programs drive scaffold vascularization innovation.
- Educational Institutions:Training programs consume materials for resident competency development.
Dental Clinics account for the largest procurement volume. Specialized Implant Centers are climbing the fastest as procedure complexity migrates from general practice.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hydroxyapatite feedstock from Japanese mineral processors anchors Asia-Pacific supply quality, while Swiss collagen purification heritage shapes European premium tier positioning. German specialized implant centers and United States metropolitan dental clinics concentrate demand for ridge preservation materials.
United States
FDA 510(k) premarket notifications compress synthetic graft substitute approval timelines, accelerating product entry for dental clinics. The regulatory pathway favors mineralized alloplasts over xenograft alternatives, reshaping procurement patterns. Metropolitan markets witness consolidation through captive distributor networks bundling biologics with implant hardware.
Germany
Specialized implant centers in Bavaria and North Rhine-Westphalia drive premium material uptake for alveolar ridge augmentation procedures. EU MDR conformity assessments streamline biocompatibility validation for collagen-based matrices, reducing registration friction. University hospitals in Berlin and Munich pilot 3D-printed patient-specific scaffolds for severe ridge atrophy cases.
Japan
PMDA enforcement of JIS T 0306 mechanical testing standards creates divergent approval requirements for load-bearing maxillofacial grafts. Higher-purity synthetic hydroxyapatite grades manufactured in Osaka and Nagoya displace xenograft dependence in ridge preservation protocols. Tokyo dental implant centers capture preferential positioning for JIS-certified materials.
Switzerland
Swissmedic oversight of animal-derived materials shapes collagen matrix acceptance across European implant centers. Geistlich Pharma leverages domestic heritage in collagen-based matrices to sustain premium positioning. Basel and Zurich clusters concentrate regenerative material R&D for dental ridge preservation applications.
South Korea
MFDS biocompatibility assessments govern synthetic graft entry for Seoul Capital Area dental clinics. Local manufacturers compete on cost positioning for beta-tricalcium phosphate granules used in sinus lift procedures. Busan-Ulsan industrial corridors supply ceramic precursor materials to regional graft fabricators.
Oral Bone Implant Material Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital surgical workflow integration and patient-specific scaffold fabrication. The vendor base stratifies across three archetypes: diversified dental conglomerates with captive biologics manufacturing, specialized regenerative material houses with heritage collagen expertise, and regional ceramic processors serving cost-sensitive markets. Competitive moves concentrate on backward integration into raw material supply and technology licensing for additive manufacturing capabilities.
Within the heritage-specialist tier, Geistlich Pharma exemplifies Swiss collagen matrix positioning anchored in European implant center networks. Zimmer Biomet and Dentsply Sirona represent diversified dental conglomerates with North American supply chain density, the former through captive biologics manufacturing and the latter via integrated digital surgical workflows. These three entities occupy distinct competitive vectors: heritage premium positioning, manufacturing scale, and software-hardware-biologics bundling respectively.
| Leading Market Players |
|---|
| Geistlich Pharma |
| Zimmer Biomet |
| Dentsply Sirona |
| Medtronic |
| Envista Holdings |
| BioHorizons |
| Henry Schein |
| Dentium |
| Orthogen |
| Others |
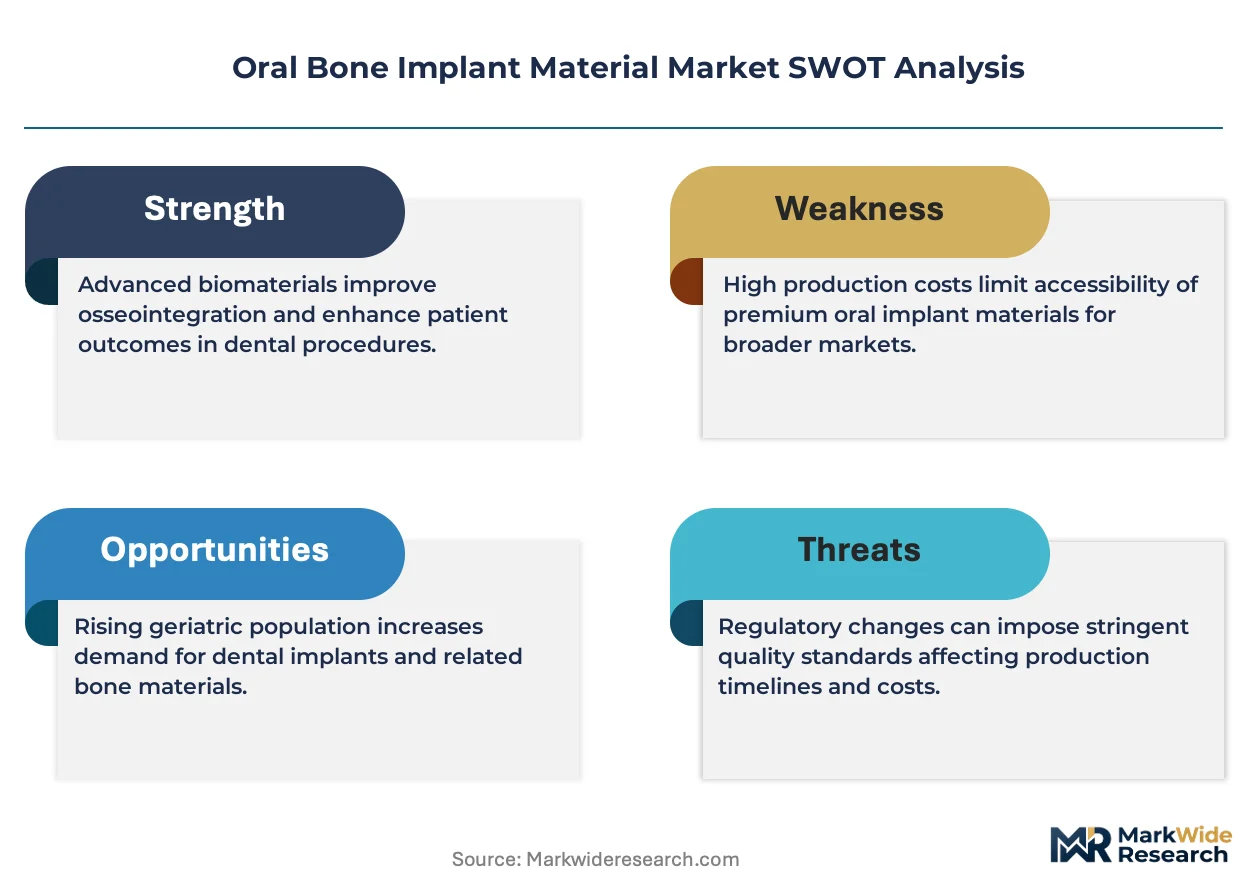
Pricing and Supply Chain Analysis
Additive manufacturing adoption for patient-specific scaffolds is compressing batch economics for traditional particulate grafts while concentrating procurement leverage among integrated dental conglomerates with captive biologics production. This technological pivot simultaneously elevates R&D cost barriers for synthetic hydroxyapatite grades and consolidates distributor margins through bundled hardware-biologics contracts.
Pricing Analysis
Warranty and regulatory certification bundling separates premium-tier collagen matrices from unbundled synthetic granules in German and Swiss implant center procurement. Three-tier pricing structure across premium, standard, and economy levels tracks JIS certification status and gamma irradiation validation depth. Cost compression in standard-grade synthetic hydroxyapatite intensifies as Osaka-based mineral processors expand higher-purity output. Group dental practices in United States metropolitan markets exhibit greatest price sensitivity, while university hospital oral surgery departments accept premium positioning for custom scaffold architectures.
Supply Chain Analysis
Regional distribution centers in Basel, Nagoya, and Warsaw orchestrate hub-and-spoke replenishment to European and Asian implant centers with 48-hour service commitments. Manufacturing concentrates in Japan for ceramic precursor refinement, Switzerland for collagen purification, and Germany for sterile finished goods packaging. Raw material flows draw from phosphate rock processors in North Africa, bovine collagen abattoir networks in Australasia, and silicate mineral deposits in Scandinavia. Single-source vulnerability persists in gamma irradiation terminal sterilization capacity. Distribution runs through captive implant hardware networks rather than independent dental distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA 510(k) premarket notification requirements and EU MDR conformity assessments erect substantial compliance cost barriers that protect incumbent positions while constraining bootstrap entrants lacking regulatory affairs infrastructure.
For Market Incumbents: Deploy backward integration into phosphate precursor mining and ceramic sintering capacity to secure feedstock cost positioning against Japanese mineral processor expansion. Fortify JIS T 0306 certification portfolios ahead of PMDA mechanical testing standard enforcement for load-bearing maxillofacial applications. Channel control through digital surgical workflow bundling defends against independent distributor disintermediation.
For New Entrants and Emerging Players: Begin with beta-tricalcium phosphate formulation for sinus lift procedures in South Korean and Indian dental clinics where cost positioning outweighs brand heritage requirements. Target oral surgery centers in secondary German cities underserved by Geistlich Pharma's premium channel density. Pursue white-label supply arrangements with Asian dental implant hardware manufacturers seeking biologics portfolio completion.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified dental conglomerates seeking additive manufacturing capabilities and JIS-certified production assets. Five-to-ten year viability hinges on regulatory science convergence for 3D-printed scaffold equivalence benchmarks. Acquisition target archetype: mid-cap ceramic processors with existing PMDA mechanical testing datasets and university hospital pilot relationships. Signal to watch: FDA draft guidance on patient-specific graft scaffold characterization methods.
| Strategic Initiative | Industry Significance |
|---|---|
| JIS T 0306 Certification Investment | PMDA compliance unlocks premium positioning in Tokyo and Osaka implant centers. |
| Gamma Irradiation Protocol Validation | Terminal sterilization without osteoinductive compromise extends batch release timelines. |
| Digital Surgical Workflow Integration | CAD/CAM bundling with Dentsply Sirona and Zimmer Biomet captive networks secures channel access. |
| Additive Manufacturing Capacity Buildout | Patient-specific scaffold fabrication compresses multi-stage grafting protocols for severe ridge atrophy. |
| Phosphate Precursor Backward Integration | Upstream control over ceramic feedstock insulates margin pressure from Japanese mineral processor expansion. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside structured interviews with dental implant center procurement directors, oral surgery department heads, biomedical engineering faculty, GPO contracts managers, and regulatory affairs specialists at collagen matrix manufacturers. Primary fieldwork covered FDA 510(k) notification databases, EMA MDR conformity assessment registries, and PMDA approval documentation. Bottom-up volume modeling triangulated against top-down expenditure estimates from national dental association procedure surveys.
Granularity-level modeling tracked material chemistry, physical form, application procedure, and end-user facility type across the projection horizon. Synthetic hydroxyapatite, beta-tricalcium phosphate, and collagen matrix segments carried discrete growth assumptions based on resorption kinetics and regulatory pathway friction. Sinus lift and alveolar ridge augmentation applications modeled separately for staged versus immediate implant protocols. CAGRs derived from procedure volume elasticity to edentulous population demographics and implant penetration rates.
Underlying measurement precision varies by segment; synthetic alloplast volumes carry tighter precision than xenograft alternatives subject to EMA sourcing guidance volatility. Forecasts reflect documented assumptions regarding EU MDR implementation timelines and PMDA mechanical testing standard enforcement. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.