
 Cold Light Teeth Whitening Kit Market | 2026-2036
Cold Light Teeth Whitening Kit Market Size, Share, and Industry Trends Forecast 2026-2036
Cold Light Teeth Whitening Kit Market Outlook
Direct-to-consumer e-commerce is reshaping how cold light teeth whitening kits reach buyers, bypassing traditional dental retail channels entirely. Philips leverages its brand strength across pharmacy and online platforms in Western Europe. GLO Science anchors its position through professional-grade systems that bridge clinic and home use. Colgate-Palmolive competes via mass-market shelf presence and bundled oral care routines.
A cold light teeth whitening kit combines a peroxide-based bleaching agent with LED, UV, or laser activation to accelerate enamel stain decomposition without thermal damage. Most systems employ carbamide peroxide concentrations between six and twenty-two percent, delivered through custom-fit trays or disposable strips paired with blue-spectrum light emitters. LED technology dominates unit economics due to lower component costs and safer thermal profiles for unsupervised home application. Trays capture premium positioning through dental-customized molding, while strips sustain volume leadership in convenience retail. E-commerce platforms represent the fastest-growing end-user channel as algorithm-driven personalization replaces in-store discovery.
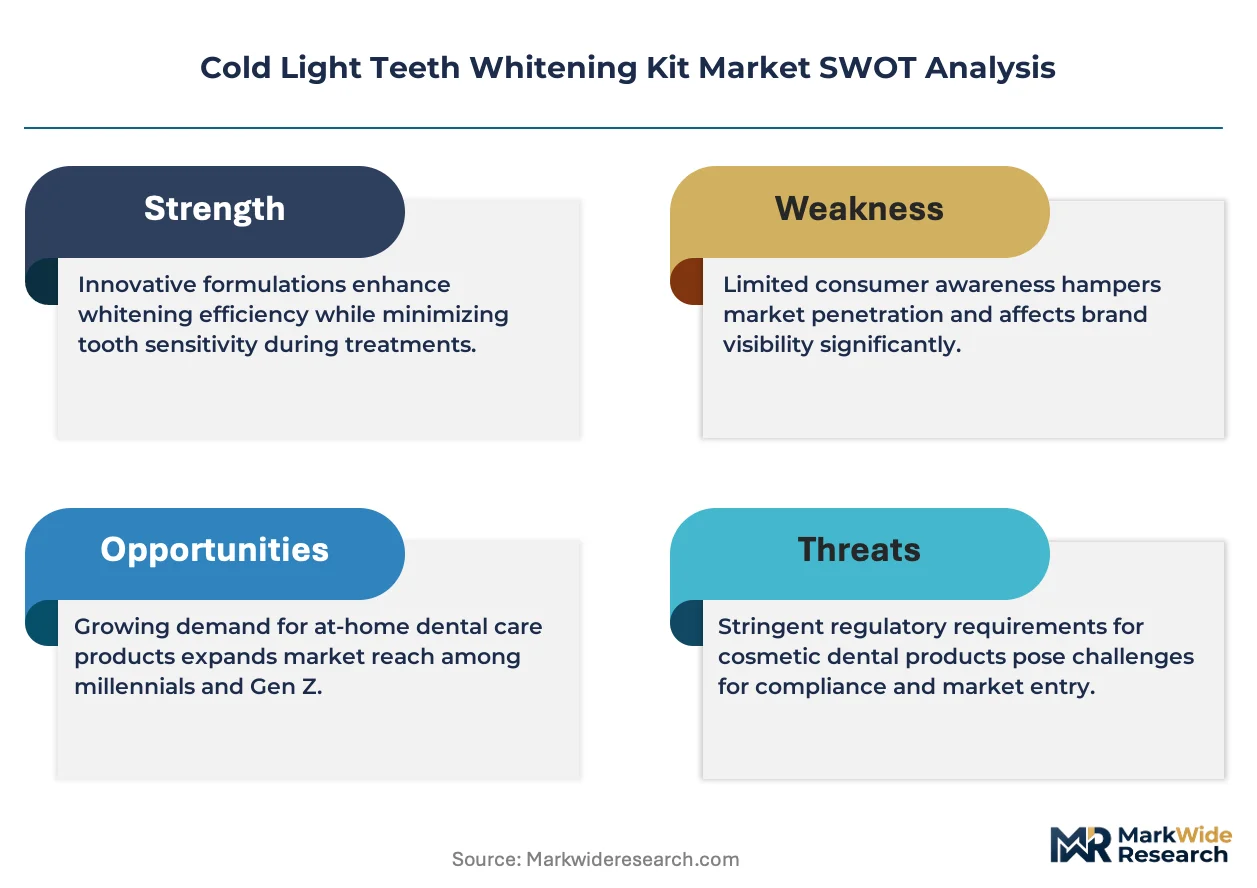
FDA oversight of peroxide limits and CE marking under the EU Medical Device Regulation constrain formulation freedom and market entry timelines for new entrants. ISO standards for biocompatibility testing add certification costs that favor scaled manufacturers with established quality systems. China's NMPA and SAMR enforce parallel registration requirements for imported devices sold through domestic e-commerce. Stakeholders must monitor regulatory divergence between peroxide-classification regimes as this determines which formulations can ship cross-border without reformulation.
Market Dynamics
LED-based cold light activation systems are compressing treatment times from weeks to single sessions, forcing reformulation strategies around peroxide concentration limits and thermal safety thresholds for home-use devices.
Growth Catalysts
- EU Medical Device Regulation (MDR) CE marking pathways:Harmonized certification frameworks enable cross-border e-commerce distribution into Germany, France, and the Netherlands without redundant national approvals.
- Carbamide-free peroxide alternatives:Hydrogen peroxide gels stabilized with bioadhesive polymers satisfy FDA concentration caps while maintaining efficacy thresholds for salon-grade applications.
- Seoul and Los Angeles beauty clusters:Walk-in cosmetic treatment venues stock LED systems for impulse purchases, creating physical touchpoints that drive online search volume and direct-to-consumer conversion.
Market Restraints
- ISO 10993 biocompatibility testing costs:Scaled manufacturers absorb certification expenses that exclude micro-brands from pharmacy and professional dental channels.
- China NMPA parallel registration:Imported devices face 12-18 month approval timelines for domestic e-commerce, advantaging local OEMs with existing SAMR clearances.
- Enamel sensitivity thresholds:Peroxide concentrations above 15% trigger adverse event reporting requirements that limit formulation flexibility for high-performance home kits.
Strategic Opportunities
- India BIS standards alignment:Early compliance with forthcoming medical device classification rules positions entrants before formal peroxide regulation implementation.
- Subscription replenishment models:Gel cartridge auto-ship programs lock in recurring revenue and reduce customer acquisition costs for direct-to-consumer brands.
- AI-powered shade-matching apps:Smartphone camera integration personalizes treatment duration and intensity, differentiating premium tiers from mass-market strips.
Industry Challenges
- Dental professional channel resistance:Licensed practitioners view OTC whitening as competitive erosion, limiting co-branded endorsement opportunities for home-use systems.
- Cross-border customs classification ambiguity:Peroxide-based gels trigger hazardous material handling requirements that disrupt fulfillment speed and increase reverse logistics costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold Light Teeth Whitening Kit Market |
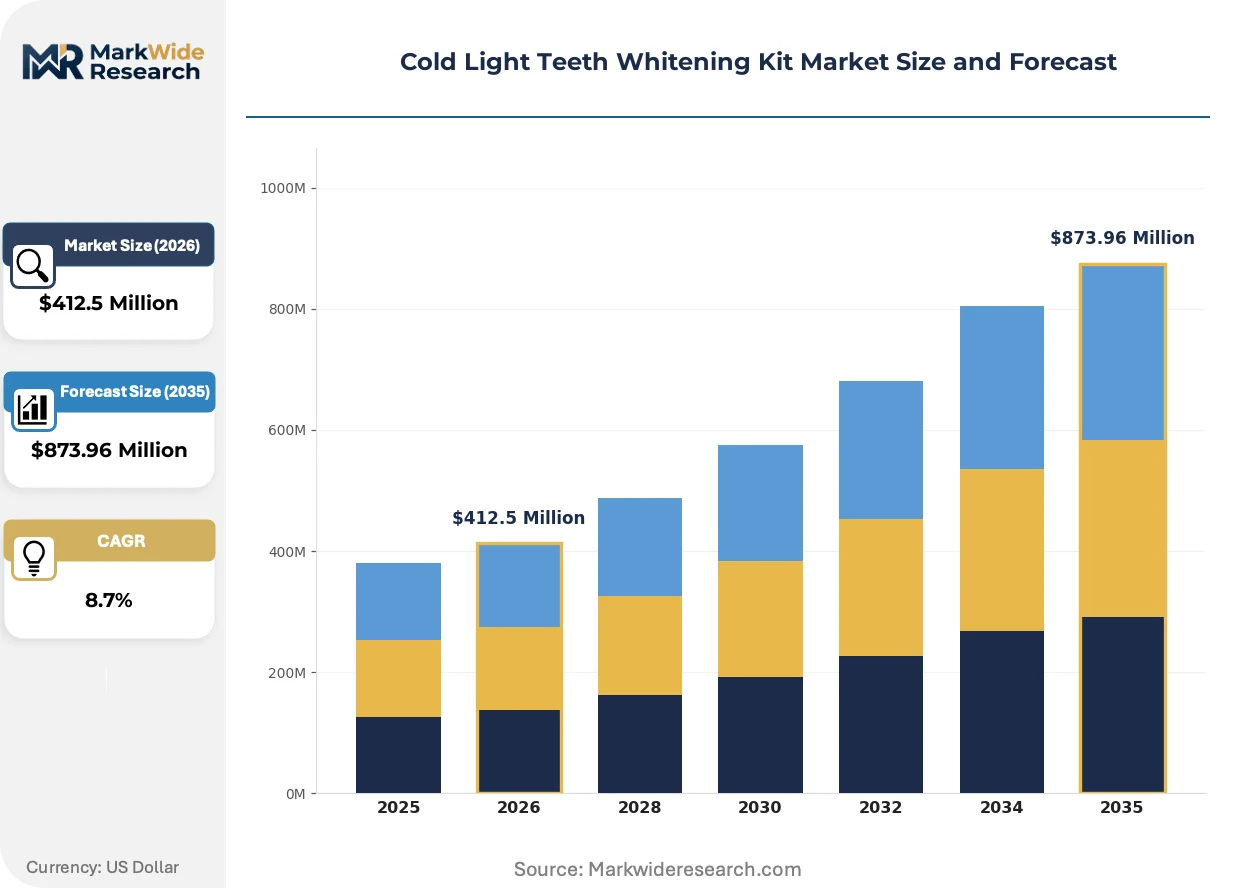
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gels, Strips, Trays, Pens Technology: LED, UV, Laser, Infrared End User: Consumers, Dental Clinics, Beauty Salons, E-commerce Platforms Packaging Type: Box, Tube, Sachet, Bottle |
| Companies Covered | Philips, Procter & Gamble, GLO Science, Danaher Corporation, Dentsply Sirona, Colgate-Palmolive, Beyond International, Golfend Eagles, YLX Beauty, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold Light Teeth Whitening Kit Market Strategic Shifts
Digital diagnostics and connected hardware are fragmenting the traditional whitening value chain, enabling personalized protocols that bypass standardized tray systems entirely.
Blue-spectrum LED arrays with integrated photoinitiator chemistry are hybridizing professional-grade acceleration into handheld home devices. Korean and Chinese OEMs dominate component supply for these systems, shipping modules to Western brands at 40% cost advantage over domestic sourcing. The technology is hybridizing treatment outcomes previously restricted to dental clinics into unsupervised consumer environments.
China's SAMR enforcement of GB standards for cosmetic device safety is tightening documentation requirements for peroxide-based imports. Domestic brands leverage pre-existing test data to compress registration timelines versus foreign competitors. E-commerce platforms within China now require NMPA registration numbers for listing eligibility, filtering unapproved cross-border sellers from search results.
Algorithm-driven personalization engines on TikTok Shop and Amazon are displacing in-store discovery for whitening kit purchases. Influencer-generated before-and-after content reduces information asymmetry that previously favored pharmacy consultations. This shift concentrates marketing spend on short-form video production rather than retail slotting fees, with conversion rates highest among 25-34 age demographics in urban China and the United States.
Cold Light Teeth Whitening Kit Market Segmentation
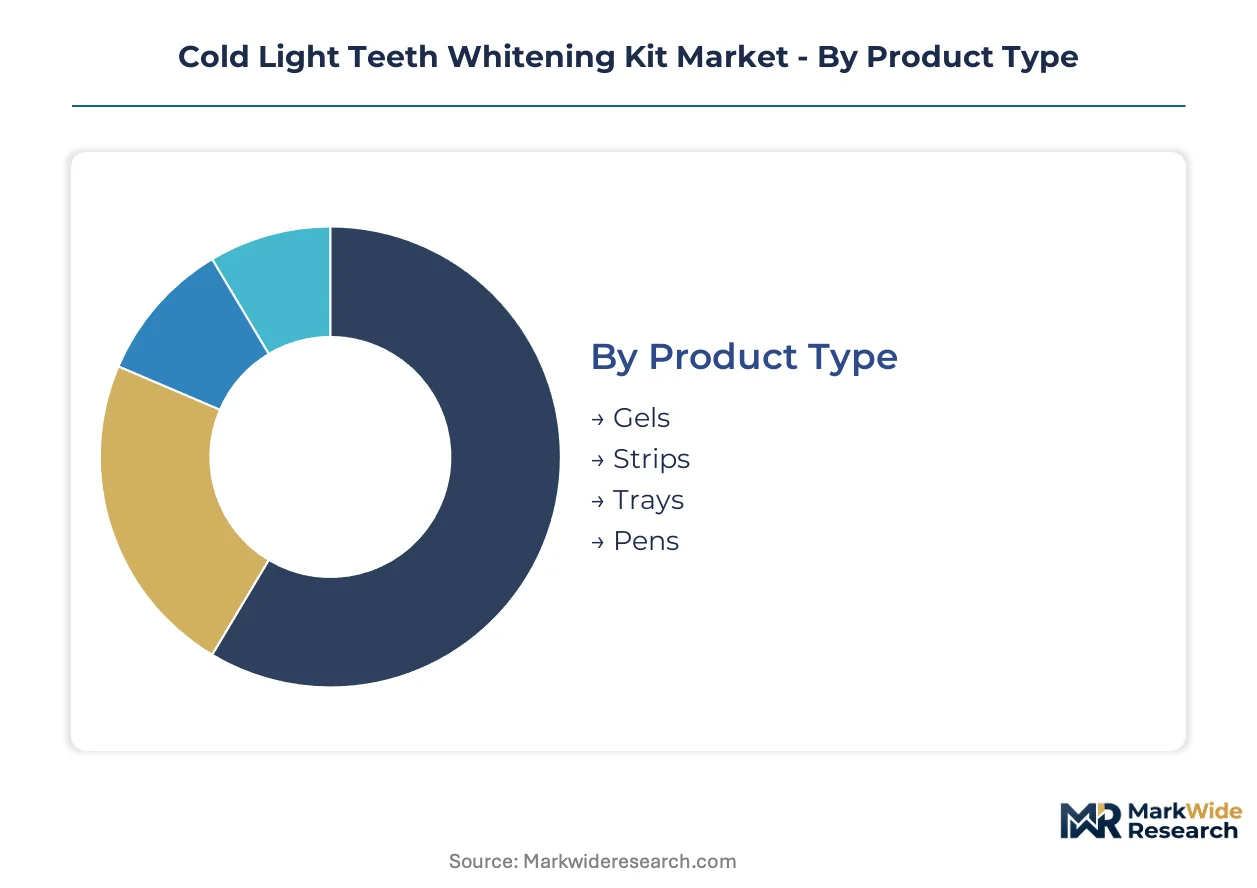
Cold light teeth whitening kits fragment across four distinct dimensions that determine formulation chemistry, device specifications, and channel economics. Understanding these segment boundaries reveals where margin pools concentrate and which technology transitions threaten incumbent positioning.
Product Type:
Use-case spectrum spans from professional-grade dental customization to impulse convenience retail, with each format demanding different peroxide concentrations and activation hardware.
- Gels:Carbamide or hydrogen peroxide suspensions delivered in syringes or brush-tip applicators, typically paired with LED trays for home activation. Demand clusters in China through cross-border e-commerce where consumers seek salon-equivalent potency without clinic visits, though FDA concentration caps limit US import formulations.
- Strips:Thin polymer films pre-loaded with peroxide gel, designed for direct enamel contact without supplemental hardware. Mass-market shelf presence in US and Western European pharmacies sustains volume leadership, with Colgate-Palmolive and pharmacy private labels capturing repeat purchase cycles through bundled oral care routines.
- Trays:Custom-molded or thermoplastic dental appliances that concentrate bleaching agent against enamel while housing LED emitters. Dental clinics in Seoul and Los Angeles prescribe these for supervised home continuation of in-office treatments, commanding premium pricing through professional endorsement.
- Pens:Portable twist-dispense applicators targeting touch-up applications and travel use cases. Korean OEMs dominate component supply for these systems, shipping modules to Western brands at cost advantage over domestic sourcing.
The dominant share belongs to Strips, while Gels are closing the gap fastest.
Technology:
Cost tier stratification separates consumer-accessible LED systems from clinic-grade laser platforms, with thermal safety profiles determining home-use eligibility.
- LED:Blue-spectrum arrays operating at 450-480nm wavelength to activate photoinitiator chemistry without thermal enamel damage. Component economics favor mass-market penetration, with Korean and Chinese manufacturers supplying modules that compress treatment times from weeks to single sessions.
- UV:Ultraviolet activation systems historically deployed in dental clinics, now restricted for home use due to soft tissue exposure risks. Regulatory divergence between FDA and CE marking regimes determines which formulations can ship cross-border without reformulation.
- Laser:Diode-based systems requiring licensed practitioner operation, generating highest per-session revenue in cosmetic dentistry channels. Professional-grade acceleration outcomes previously restricted to clinics now hybridize into handheld home devices through LED technology substitution.
- Infrared:Emerging wavelength protocols claiming reduced sensitivity response through deeper tissue penetration without surface heating. Early compliance with forthcoming medical device classification rules in India positions entrants before formal peroxide regulation implementation.
LED captures the volume base, though Laser retains the margin premium in professional channels.
End User:
Customer type determines regulatory pathway complexity and pricing architecture, from OTC retail to prescription-grade clinical protocols.
- Consumers:Direct purchasers through Amazon, TikTok Shop, and pharmacy retail seeking unsupervised home treatment. Algorithm-driven personalization engines on these platforms displace in-store discovery, with conversion rates highest among 25-34 age demographics in urban China and the United States.
- Dental Clinics:Licensed practitioners prescribing professional-grade systems or supervising in-office activation. This channel views OTC whitening as competitive erosion, limiting co-branded endorsement opportunities for home-use systems despite higher peroxide authorization.
- Beauty Salons:Walk-in cosmetic treatment venues in Seoul and Los Angeles stocking LED systems for impulse purchases. Physical touchpoints drive online search volume and direct-to-consumer conversion through before-and-after content generation.
- E-commerce Platforms:Marketplace operators imposing listing eligibility requirements including NMPA registration numbers in China. These gatekeeping functions filter unapproved cross-border sellers from search results, advantaging domestic OEMs with existing SAMR clearances.
Consumers represent the addressable base, while Dental Clinics extract highest lifetime value per patient.
Packaging Type:
Supply concentration in Asian contract manufacturing shapes format availability, with sustainability pressures emerging in European pharmacy channels.
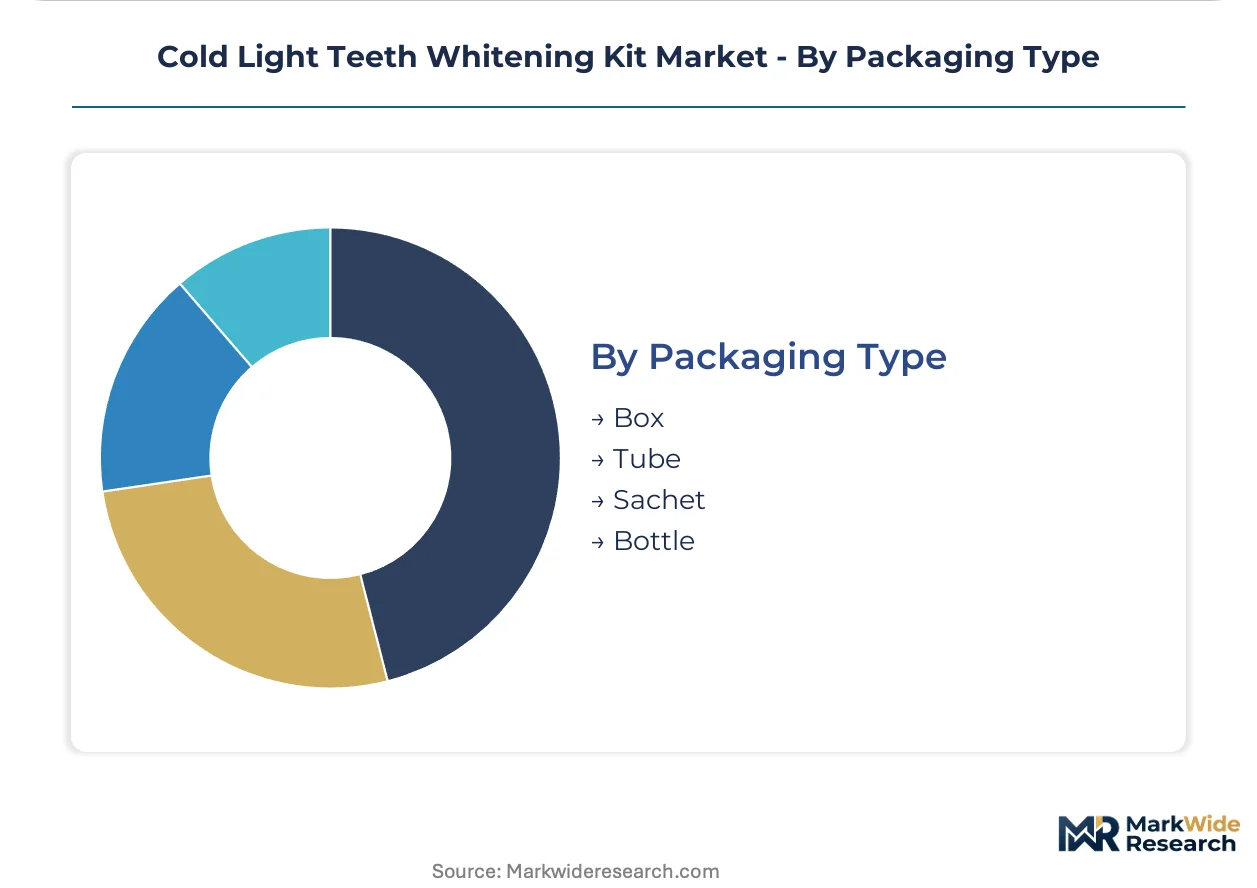
- Box:Rigid paperboard containment for multi-component kits including tray, LED device, and gel supply. Standard for premium tier positioning in Western European pharmacy and online platforms.
- Tube:Collapsible aluminum or plastic extrusion for gel replenishment cartridges. Subscription auto-ship programs lock in recurring revenue and reduce customer acquisition costs for direct-to-consumer brands.
- Sachet:Single-dose foil pouches for travel and trial formats. Korean beauty salon distribution favors this portability for impulse purchase economics.
- Bottle:Pump or dropper dispensers for larger-volume gel refills. Bulk packaging sustains cost positioning in mass-market retail though peroxide stability concerns limit shelf life.
Box formats dominate kit assembly, while Tube configurations are expanding most quickly through subscription mechanics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA concentration caps for peroxide-based formulations anchor United States market entry protocols, while China's NMPA registration requirements filter cross-border sellers from domestic e-commerce platforms.
United States
Pharmacy retail chains and Amazon's algorithm-driven discovery engines drive consumer kit purchases, with FDA oversight of hydrogen peroxide limits constraining formulation potency for home-use devices. Licensed dental practitioners in Los Angeles operate walk-in cosmetic venues that stock LED systems, creating physical touchpoints that generate online search volume and direct-to-consumer conversion.
China
Domestic brands leverage pre-existing SAMR test data to compress NMPA registration timelines versus foreign competitors seeking cross-border e-commerce access. TikTok Shop and Tmall require NMPA registration numbers for listing eligibility, filtering unapproved sellers from search results. Seoul beauty salon operators source LED modules from Korean and Chinese OEMs at component cost advantages over Western domestic sourcing.
Germany
EU Medical Device Regulation CE marking pathways enable harmonized distribution into France and the Netherlands without redundant national approvals. Pharmacy retail in Western Europe sustains premium positioning for multi-component box kits. Berlin-based e-commerce operators utilize CE marking to access cross-border markets with single certification compliance.
South Korea
MFDS oversight of cosmetic device safety parallels China's tightening documentation requirements, though domestic OEMs dominate LED module supply for global brands. Seoul's beauty cluster anchors walk-in cosmetic treatment venues that hybridize professional-grade acceleration into handheld consumer environments. Component manufacturers ship modules to Western brands at cost advantages over domestic sourcing alternatives.
India
BIS standards alignment for forthcoming medical device classification rules positions early entrants before formal peroxide regulation implementation. Mumbai and Delhi-NCR e-commerce platforms concentrate algorithm-driven personalization engines that displace in-store discovery for whitening kit purchases. Domestic brands exploit regulatory preparation windows to establish market presence ahead of foreign competitors facing extended approval timelines.
Cold Light Teeth Whitening Kit Market Competitive Environment
Multinational conglomerates and specialized dental technology firms split the market across mass-market retail and professional-grade channels. The vendor base concentrates around scaled manufacturers with established ISO quality systems that absorb biocompatibility testing costs excluding micro-brands from pharmacy and professional dental channels. Two strategic archetypes dominate: diversified consumer health conglomerates leveraging cross-category brand equity, and dental-focused specialists bridging clinic and home-use applications. Competitive moves center on subscription replenishment models for gel cartridges and AI-powered shade-matching apps that personalize treatment protocols.
Within the diversified consumer health tier, Philips and Procter & Gamble occupy positions anchored by pharmacy and online platform presence across Western Europe. GLO Science exemplifies the dental-specialist archetype, representing professional-grade system positioning that bridges supervised clinic protocols with unsupervised home continuation. Colgate-Palmolive sits within the mass-market convenience vector, sustaining volume leadership through bundled oral care routines and repeat purchase cycles in pharmacy retail. These three anchors illustrate how brand architecture and channel access determine competitive positioning rather than technology differentiation alone.
| Leading Market Players |
|---|
| Philips |
| Procter & Gamble |
| GLO Science |
| Danaher Corporation |
| Dentsply Sirona |
| Colgate-Palmolive |
| Beyond International |
| Golfend Eagles |
| YLX Beauty |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in LED module fabrication across South Korea and China's Pearl River Delta compresses component pricing while concentrating bargaining power with downstream kit assemblers. This utilization dynamic forces Korean OEMs to absorb margin erosion on diode arrays while Western brands capture pricing flexibility in end-market positioning.
Pricing Analysis
Price spreads between salon-grade tray systems and mass-market strips span threefold multiples across United States and Western European pharmacy channels. Three-tier pricing structure across premium, standard, and economy levels separates dental-customized kits with ISO 13485 certification from disposable strip formats. Pricing pressure stems from Chinese domestic brands undercutting cross-border imports through pre-existing SAMR clearance advantages. Mass-market consumers exhibit highest price sensitivity, while dental clinic procurement tolerates premium positioning for professional endorsement leverage.
Supply Chain Analysis
Peroxide gel feedstock production clusters in China and India, with hydrogen peroxide stabilization chemistry requiring pharmaceutical-grade manufacturing infrastructure. LED emitter modules and photoinitiator compounds draw from South Korean component specialists and Chinese PCB fabricators. Single-source vulnerability concentrates in blue-spectrum diode arrays where three Korean suppliers dominate global capacity. Distribution runs through cross-border e-commerce platforms and pharmacy retail chains, with customs classification ambiguity for peroxide concentrations disrupting fulfillment velocity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity in integrated regulatory-affairs capabilities—spanning FDA 510(k) pathways, CE marking under EU MDR, and China's NMPA registration—creates sustainable differentiation for manufacturers with established quality systems and multi-jurisdiction filing experience.
For Market Incumbents: Build certification moats by accelerating ISO 10993 biocompatibility testing investments that micro-brands cannot absorb, while expanding backward integration into peroxide gel formulation to defend against Chinese OEMs with captive SAMR clearances. Lock in dental clinic channel relationships before licensed practitioners escalate competitive resistance against OTC whitening erosion. For New Entrants and Emerging Players: Pursue white-space penetration in India's BIS pre-compliance window before formal medical device classification rules crystallize, targeting algorithm-driven personalization apps that differentiate premium tiers from mass-market strips. Leverage subscription auto-ship mechanics for gel cartridge replenishment to reduce customer acquisition costs in direct-to-consumer channels. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer brands with locked-in subscription replenishment models and AI-powered shade-matching companion apps. Long-term viability favors acquisition targets with established multi-jurisdiction regulatory dossiers and pre-existing relationships with Seoul or Los Angeles beauty salon clusters. Watch NMPA registration velocity as the inflection signal—accelerating domestic clearances in China foreshadows margin compression for cross-border dependent competitors.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | Harmonized EU MDR certification unlocks pharmacy distribution across Germany, France, and Netherlands. |
| Direct-to-Consumer Launch | TikTok Shop algorithmic discovery displaces retail slotting fees for 25-34 urban demographics. |
| Backward Integration | In-house peroxide gel production insulates against Chinese SAMR-cleared competitor pricing. |
| Software Companion Development | AI shade-matching apps personalize treatment duration, differentiating premium tiers. |
| Subscription Replenishment Model | Gel cartridge auto-ship locks recurring revenue and compresses customer acquisition costs. |
Study Parameters
A spread of perspectives from dental device regulatory consultants, LED component procurement managers at Korean OEMs, pharmacy category buyers, and e-commerce platform listing compliance officers converged on the working assumptions. Primary interview insights combined with secondary validation against FDA 510(k) filings, CE marking databases, China's NMPA registration records, and customs trade data for peroxide-based cosmetic devices. Bottom-up unit economics modeling triangulated against top-down market sizing across the analysis window.
Demand-supply-balance framing anchored the analytical framework, with segmentation dimensions spanning product type, activation technology, end-user channel, and geographic regulatory cluster. CAGRs derived from fitted growth curves applied to per-country adoption rates, with specific inputs including LED module cost compression trajectories and NMPA registration timeline differentials between domestic and imported devices.
Macroeconomic conditions sit as an overlay; deviation in cross-border e-commerce tariff regimes or peroxide concentration reclassification would shift the trajectory. Forecasts reflect documented assumptions about regulatory pathway stability and component supply concentration. Cross-checking against SAMR enforcement intensity on GB standards compliance is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Materials
Dental Composites Market
Dental Materials
Tooth Filling Materials Market
Dental Materials
Global Dental Adhesive Market
Dental Materials
Global Dental Cements Market
Dental Materials
Dental Materials for 3D Printing Market
Dental Materials
Global Dental Membrane and Bone Graft Substitutes Market
Dental Materials
Dental Gypsum Market
Dental Materials
Global Demineralized Bone Matrix Market
Dental Materials
Fluoride Materials Market
Dental Materials
Asia-Pacific Toothpaste Market
Dental Materials
Dental Polymerization Lamps Market
Dental Materials
Dental Cavity Filling Material Market
Dental Materials
Toothpaste Market
Dental Materials
Oral Care Chemicals Market
Dental Materials
Fluoride-Free Toothpaste Market
Dental Materials
Dental Plaster Market