
 Defoaming Coating Additives Market | 2026-2036
Defoaming Coating Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Defoaming Coating Additives Market Intelligence
EU REACH restrictions on volatile organic compounds is restructuring formulation priorities across European coating operations. Dow leverages its silicone polymer expertise to sustain supply relationships with marine coating producers in Northern Europe. Evonik Industries AG anchors its position through specialized polyether architectures that navigate increasingly stringent environmental compliance thresholds. BASF SE competes by extending its water-based additive portfolio into architectural segments where low-VOC mandates now dominate procurement criteria.
Defoaming coating additives are surface-active compounds, predominantly silicone oils, polyethers, or mineral oil dispersions, engineered to rupture foam lamellae during pigment grinding, application, or curing stages. These additives typically function at concentrations between 0.1% and 1.0% by weight to prevent surface defects such as cratering, pinholing, and gloss reduction in cured films. Silicone-based products lead the product type landscape due to their superior efficiency at low dosages across high-shear industrial coating lines. Water-based formulation types represent the fastest-expanding category as architectural and automotive OEM coating operations accelerate solvent system phase-outs. Marine coatings applications concentrate margin pools where extreme environmental exposure demands specialized defoamer durability.
EPA regulations under the National Volatile Organic Compound Emission Standards for Architectural Coatings constrain solvent-based formulation access across the United States. ECHA maintains REACH registration requirements that compel full toxicological dossiers for silicone and polyether chemistries entering European coating supply chains. China's MEE enforces dual carbon goals that pressure domestic coating producers toward water-based system conversions. Stakeholders must monitor evolving biocide restrictions under the EU BPR, as defoamer formulations containing preservative actives face reauthorization cycles that could disrupt qualified product lists without advance regulatory tracking.
Market Dynamics
EU REACH restrictions on volatile organic compounds are forcing coating formulators across Europe to abandon solvent-based systems, accelerating demand for water-compatible defoaming chemistries that maintain performance under reduced-VOC constraints.
Growth Catalysts
- Water-based formulation mandates:EPA National Volatile Organic Compound Emission Standards for Architectural Coatings in the United States and EU REACH restrictions in Europe are compelling coating manufacturers to reformulate with water-based defoamers.
- Marine coating durability requirements:Extreme environmental exposure in offshore oil platforms and ship hull applications demands silicone-based defoamers that withstand high-shear application conditions.
- Dual carbon goals enforcement:China's MEE is pressuring domestic coating producers toward water-based system conversions, expanding addressable market for compatible additive portfolios.
Market Restraints
- Silicone raw material concentration:Specialty silicone polymer supply concentrates among limited chemical producers, exposing formulators to input cost volatility and allocation risk.
- REACH registration burden:ECHA requirements for full toxicological dossiers on silicone and polyether chemistries create regulatory friction that delays product qualification cycles.
- Mineral oil substitution pressure:Bio-based and synthetic alternatives are displacing mineral oil dispersions in sensitive architectural applications where odor and staining concerns persist.
Strategic Opportunities
- EU biocide reauthorization tracking:Defoamer formulations containing preservative actives face EU BPR reauthorization cycles; advance regulatory monitoring creates competitive positioning for compliant suppliers.
- Automotive OEM waterborne transition:Original equipment manufacturers in Germany and Japan are accelerating solvent system phase-outs, opening specification opportunities for high-performance water-compatible defoamers.
- Polyether-silicone hybrid architectures:Convergence of polyether flexibility with silicone efficiency is enabling single-additive solutions that reduce formulation complexity and inventory requirements.
Industry Challenges
- Formulation compatibility testing:Each water-based coating system requires customized defoamer screening across pigment grinding, application, and curing stages, extending technical service demands.
- Biocide-free preservation:Eliminating preservative actives from defoamer packages to preempt EU BPR restrictions demands alternative stabilization chemistries with unproven long-term stability profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Defoaming Coating Additives Market |
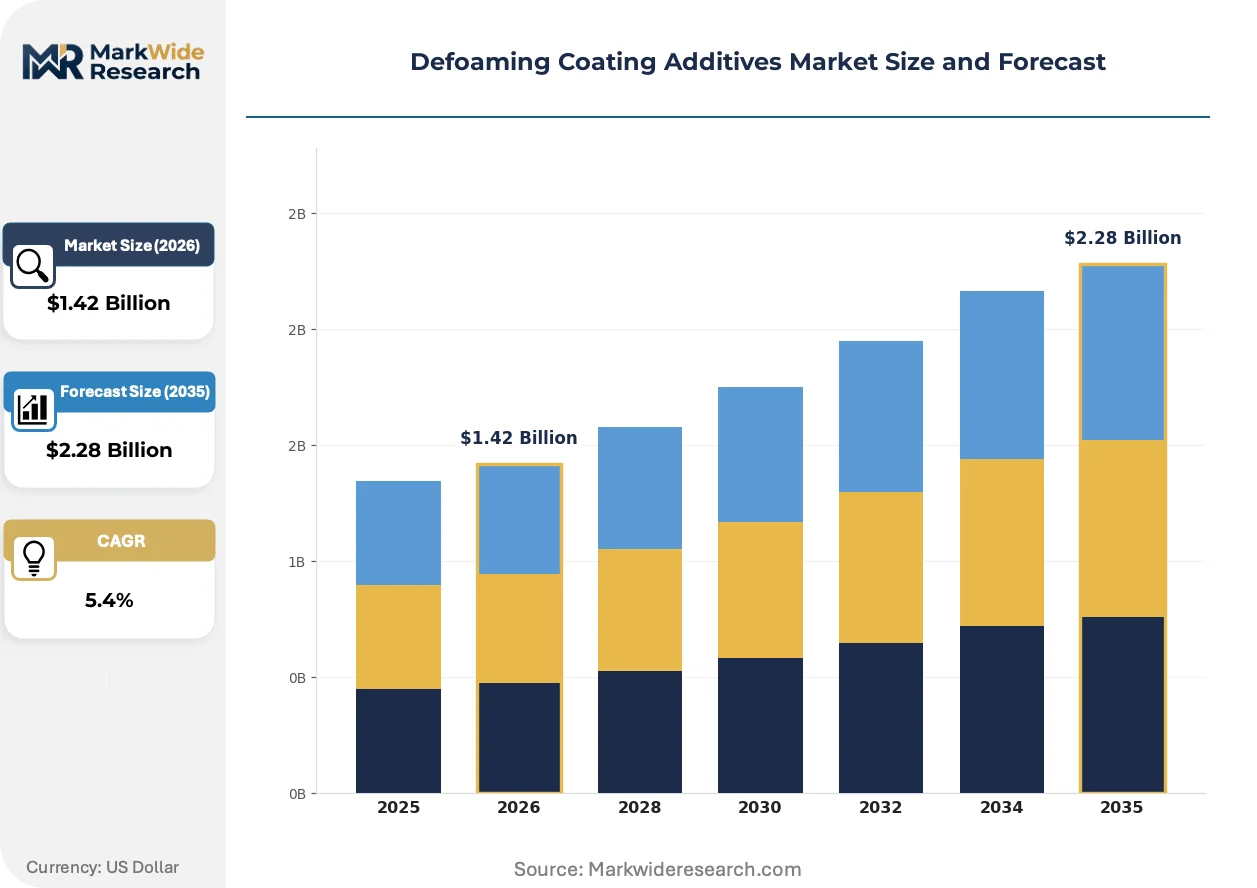
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.28 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone-Based, Polyether, Polyol, Acrylic End User: Paints, Adhesives, Inks, Cosmetics Application: Industrial Coatings, Architectural Coatings, Marine Coatings, Automotive Coatings Formulation Type: Water-Based, Solvent-Based, Powder Coatings, Functional Additives |
| Companies Covered | Dow, Evonik Industries AG, BASF SE, ALTANA, Arkema, BYK-Chemie GmbH, Momentive, MÜNZING Corporation, Wacker Chemie AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Defoaming Coating Additives Market Strategic Shifts & Innovations
Formulation chemistry is converging with regulatory compliance architecture, as additive suppliers engineer single-molecule solutions that simultaneously address foam control, VOC reduction, and preservation requirements.
Hybrid polyether-modified silicone defoamer technology is unifying the efficiency advantages of silicone with the compatibility benefits of polyether architectures. Automotive OEM coating operations in Germany and Japan are adopting these hybrids at accelerated specification cycles. This unification is compressing the traditional trade-off between defoamer performance and formulation latitude that previously forced additive blending.
EPA enforcement of National Volatile Organic Compound Emission Standards for Architectural Coatings is constraining solvent-based formulation access across the United States. Coating manufacturers are responding by qualifying water-based defoamers that maintain cratering and pinholing resistance at lower dosage levels. Architectural segments in California and the Northeast are most affected, with procurement criteria now prioritizing low-VOC qualified product lists.
Specification-driven procurement is consolidating buyer influence among large coating formulators who maintain centralized additive qualification programs. Distributors serving mid-tier regional manufacturers are losing technical specification authority to direct supplier relationships. This concentration is most visible in France and the United Kingdom, where water-based architectural coating procurement now routes through approved supplier lists managed by major formulator technical centers.
Defoaming Coating Additives Market Segmentation
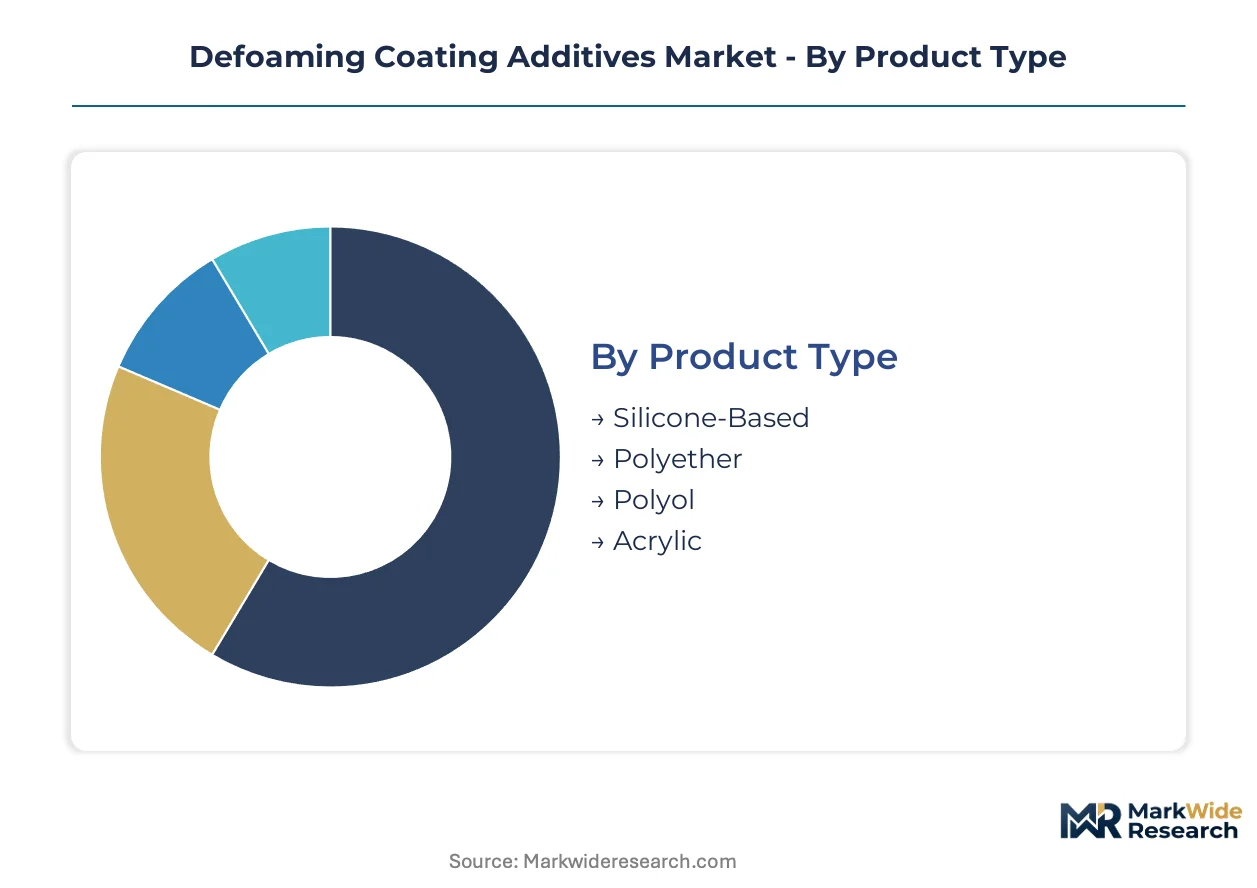
Defoaming coating additives serve divergent performance requirements across formulation chemistries and end-use environments. Segmentation reveals how silicone efficiency, water compatibility, and marine durability command premium positioning in procurement decisions.
Product Type:
Reformulation cycles driven by VOC regulations are accelerating upgrade demand from mineral oil systems to high-performance synthetic chemistries.
- Silicone-Based:Silicone oils and modified siloxanes deliver superior foam knockdown at concentrations as low as 0.1% by weight. Marine coating producers in Germany and Japan specify these chemistries for high-shear spray applications where film integrity under extreme conditions determines warranty coverage.
- Polyether:Block copolymer architectures combine hydrophobic and hydrophilic segments for controlled incompatibility with water-based resins. ECHA REACH registration requirements for full toxicological dossiers create qualification friction that favors established polyether suppliers with existing dossier libraries.
- Polyol:Polyester and polyether polyol derivatives offer intermediate defoaming efficiency with broader formulation latitude in sensitive architectural coatings.
- Acrylic:Acrylic-based defoamers serve niche applications requiring minimal surface tension disturbance in high-gloss finishes.
Volume placements concentrate in Silicone-Based; the faster expansion belongs to Polyether.
End User:
Customer procurement sophistication varies sharply, with automotive OEMs running centralized qualification programs while cosmetics formulators prioritize sensory performance over cost optimization.
- Paints:Architectural and industrial paint manufacturers represent the dominant consumption base, with water-based system conversions driving specification shifts across European and North American operations.
- Adhesives:Pressure-sensitive and structural adhesive producers require defoamers compatible with high-shear mixing and rapid cure cycles.
- Inks:Flexographic and gravure ink formulators demand defoamers that prevent foam without compromising print clarity or substrate adhesion.
- Cosmetics:Personal care applications impose additional regulatory constraints around skin contact and preservative content under EU BPR frameworks.
Procurement scale peaks with Paints; Cosmetics commands the steepest premium pricing tier.
Application:
Environmental exposure severity creates a performance hierarchy where offshore marine specifications cascade technology requirements downward into less demanding segments.
- Industrial Coatings:Protective coatings for machinery, infrastructure, and equipment require defoamers that maintain performance across wide temperature and humidity ranges.
- Architectural Coatings:Interior and exterior building finishes are absorbing expanded water-based defoamer volumes as EPA and EU REACH restrictions tighten solvent system access.
- Marine Coatings:Antifouling and protective hull coatings for offshore platforms and shipping fleets demand silicone-based defoamers engineered for salt spray resistance and extreme shear durability.
- Automotive Coatings:OEM clearcoats and basecoats require defoamers that eliminate microfoam without compromising distinctness of image or color match precision.
Margin pools concentrate in Marine Coatings; Architectural Coatings is climbing the fastest.
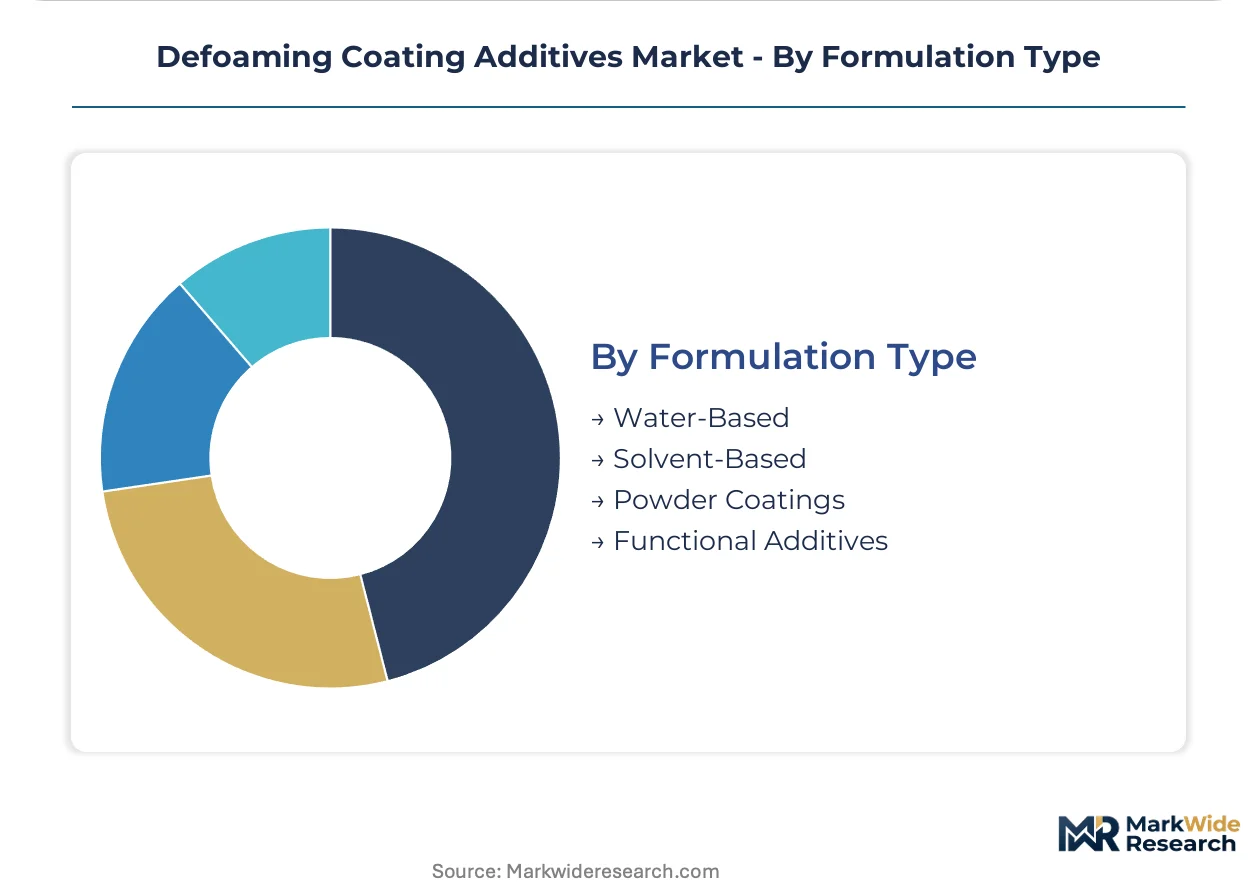
Formulation Type:
Regulatory pressure on volatile organic compound emissions is restructuring the formulation mix, with powder systems gaining traction in heat-curable industrial segments.
- Water-Based:Emulsion and dispersion systems are capturing specification share as coating manufacturers abandon solvent-based alternatives under EPA National VOC Emission Standards and EU REACH constraints.
- Solvent-Based:Declining access in architectural segments is concentrating remaining demand in specialized industrial applications where water compatibility remains technically prohibitive.
- Powder Coatings:Thermoset powder systems require defoamer chemistries stable through extrusion and bake cycles without outgassing or surface contamination.
- Functional Additives:Multi-purpose formulations combining defoaming with wetting, leveling, or rheology modification are reducing additive inventory complexity for mid-tier formulators.
Specification authority concentrates in Water-Based; Powder Coatings is gaining share fastest in heat-curable industrial segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in Germany and the United States while consumption expands fastest in China and India where water-based coating conversions accelerate. This geographic split creates trade flows of specialized silicone intermediates from Western producers to Asian formulators. Regulatory fragmentation across EPA, REACH, and China's MEE forces multinational suppliers to maintain parallel product portfolios.
Germany
Marine coating producers in Hamburg and Bremerhaven drive silicone defoamer specification for offshore wind farm protection systems. ECHA REACH registration requirements for full toxicological dossiers favor established suppliers with existing compliance libraries. The North Rhine-Westphalia chemical corridor hosts concentrated formulation R&D where hybrid polyether-silicone architectures undergo accelerated qualification.
United States
Architectural coating manufacturers in California and the Northeast absorb expanded water-based defoamer volumes under EPA National VOC Emission Standards. The agency's enforcement constrains solvent-based system access, compressing qualification timelines for low-dosage alternatives. Gulf Coast petrochemical complexes supply specialty silicone intermediates that feed domestic marine and industrial coating operations.
China
MEE dual carbon goals pressure domestic coating producers toward water-based system conversions, expanding addressable market for compatible additive portfolios. Yangtze River Delta manufacturing clusters in Jiangsu and Zhejiang provinces concentrate automotive OEM coating operations where solvent phase-outs proceed fastest. Local suppliers compete on price while Western multinationals defend position through technical service relationships with joint-venture formulators.
Japan
METI industrial standards for low-VOC coatings accelerate automotive OEM specification changes at Toyota, Honda, and Nissan supplier networks. Kansai region chemical producers in Osaka and Hyogo prefectures develop polyether-modified silicone hybrids for clearcoat applications. Technical partnerships between Japanese coating formulators and German additive suppliers concentrate specification authority in Nagoya and Tokyo technical centers.
India
Bureau of Indian Standards notification on VOC limits in architectural coatings drives reformulation demand among Mumbai and Ahmedabad paint manufacturers. Maharashtra and Gujarat industrial corridors absorb expanded water-based defoamer volumes as decorative coating producers abandon solvent systems. Import dependence for specialty silicone intermediates exposes formulators to currency volatility and landed cost fluctuations.
Defoaming Coating Additives Market Key Industry Players
The competitive structure tilts toward diversified chemical conglomerates with captive silicone polymer supply. Three to five multinational suppliers command specification authority in marine and automotive OEM segments where qualification cycles extend 18-24 months. Strategic archetypes include integrated silicone producers, specialized additive formulators, and regional distributors with technical service capabilities. Competitive moves concentrate on hybrid technology licensing and backward integration into silicone intermediate production.
Among integrated chemical conglomerates, Dow, BASF SE, and Evonik Industries AG occupy positions that exemplify divergent strategic approaches to coating additive markets. Dow leverages upstream silicone polymer capabilities that anchor supply relationships with marine coating producers. BASF SE extends water-based additive portfolios through formulation chemistry integration. Evonik Industries AG represents specialization in polyether architectures that navigate environmental compliance thresholds. These three entities sit within a competitive set where technical specification authority matters more than price competition in qualified product segments.
| Leading Market Players |
|---|
| Dow |
| Evonik Industries AG |
| BASF SE |
| ALTANA |
| Arkema |
| BYK-Chemie GmbH |
| Momentive |
| MÜNZING Corporation |
| Wacker Chemie AG |
| Others |
Cost & Logistics Intelligence
Specialty silicone polymer feedstock costs cascade through three distinct pricing tiers as raw material volatility concentrates margin pressure on formulators lacking backward integration into upstream siloxane production. Water-based architectural coating buyers in Germany and France absorb premium positioning for REACH-compliant polyether alternatives, while mineral oil dispersion suppliers compete on landed cost in price-sensitive Indian decorative paint segments.
Pricing Analysis
Defoamer pricing anchors to film integrity outcomes under high-shear marine application conditions, with silicone-based formulations commanding premium positioning against polyether and mineral oil alternatives. Price differentiation rests on ECHA REACH registration status and ISO 9001-certified manufacturing protocols, separating qualified suppliers from commodity traders. Cost compression in standard-grade architectural segments intensifies as Chinese domestic producers expand water-compatible additive capacity. Regional paint manufacturers in India and Southeast Asia exhibit highest price sensitivity, while automotive OEM technical centers in Germany and Japan prioritize specification compliance over unit cost.
Supply Chain Analysis
Reverse-logistics flows for defoamer packaging and expired inventory remain underdeveloped, creating waste liability exposure for formulators managing EU BPR-compliant preservative actives. Silicone intermediate production concentrates in Germany, the United States, and China, with specialty polyether block copolymers sourcing from Japan and South Korea. The supply chain draws from chlorosilane feedstocks, ethylene oxide derivatives, and mineral oil bases, exposing formulators to petrochemical price volatility. Single-source vulnerability pervades high-purity silicone polymer supply, particularly for marine coating specifications requiring extreme shear durability. Distribution runs through direct technical service relationships with major formulators, bypassing traditional distributor channels in consolidated European and North American markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU REACH registration burdens and ECHA toxicological dossier requirements are forcing sub-scale additive suppliers toward exit or acquisition, consolidating specification authority among integrated chemical conglomerates with captive compliance infrastructure.
For Market Incumbents: Anchor market position through backward integration into silicone intermediate production, securing supply continuity for marine coating producers in Northern Europe. Invest in hybrid polyether-silicone R&D capacity at North Rhine-Westphalia technical centers to preempt formulation complexity demands from automotive OEMs. Defend against mineral oil substitution pressure by accelerating biocide-free preservation chemistry qualification ahead of EU BPR reauthorization cycles. For New Entrants and Emerging Players: Mid-tier regional paint manufacturers in India and Southeast Asia represent the most penetrable buyer archetype, underserved by technical service-intensive direct supplier relationships dominating European markets. Target water-based architectural coating conversions in Maharashtra and Gujarat industrial corridors where Bureau of Indian Standards VOC enforcement is accelerating solvent system abandonment. Pursue joint-venture distribution partnerships with established local chemical distributors to bypass 18-24 month automotive OEM qualification barriers. For Investors and Strategic Acquirers: EU BPR reauthorization delays for preservative-containing defoamer formulations are the leading indicator that compliance-capable additive suppliers will command scarcity premiums. Position for five-to-ten year holding periods centered on specialty chemical platforms with existing REACH dossier libraries and marine coating specification relationships. Monitor ECHA registration status changes as the critical inflection signal for distressed acquisition opportunities among sub-scale European formulators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Intermediates | Captive supply of chlorosilane feedstocks insulates margin from petrochemical volatility and allocation risk. |
| Hybrid Polyether-Silicone R&D Expansion | Single-additive solutions reduce formulation complexity for automotive OEM clearcoat specifications at Toyota and Honda supplier networks. |
| EU BPR Compliance Infrastructure Investment | Advance regulatory tracking capabilities position suppliers ahead of biocide reauthorization disruptions affecting preservative actives. |
| Water-Based Defoamer Capacity Addition in China | Yangtze River Delta manufacturing presence captures MEE dual carbon goal-driven conversions among domestic coating producers. |
| Technical Service Partnership with Marine Coating Producers | Direct relationships with Hamburg and Bremerhaven formulators secure long-term specification authority for offshore wind farm protection systems. |
Research Approach
Independent corroboration across formulation chemists at marine coating producers, procurement leads at architectural paint manufacturers, and regulatory affairs specialists at additive suppliers underwrites the qualitative findings in this study. Primary interviews with plant managers at German chemical corridors, technical R&D directors at Japanese automotive coating operations, and distribution channel partners in Indian industrial clusters combined with secondary validation from ECHA registration databases, EPA National VOC Emission Standards filings, and ACC/Cefic industry reports. Bottom-up volume estimates from end-use consumption patterns triangulate against top-down silicone intermediate production capacity assessments.
Rate-of-change decomposition across the projection horizon separates volume growth drivers from price-mix effects in water-based versus solvent-based formulation transitions. The analytical framework models segmentation dimensions including product chemistry type, end-use industry, application environment severity, and regional regulatory cluster. CAGRs derive from regression analysis of historical formulation conversion rates correlated with enforcement intensity of EPA, REACH, and MEE restrictions. Industry-specific forecast inputs incorporate marine coating warranty specification durability requirements and automotive OEM solvent phase-out commitment timelines.
Revisions become necessary when ECHA accelerates REACH registration dossier requirements, EPA expands VOC restriction scope beyond architectural coatings, or MEE enforcement disrupts Chinese domestic silicone intermediate supply. Material deviation in these named triggers warrants pause and re-evaluation of volume and value assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Feed Additives Market
Additives
Metal Deactivators Market
Additives
Global Synthetic Tackifier Market
Additives
Biosaccharide Gum Market
Additives
Global Carboxylic Acids Based Esters Market
Additives
Sorbitan Tristearate Market
Additives
Americas Coating Additives Market
Additives
Feed Additive Nosiheptide Premix Market
Additives
Canada Anti-Caking Market
Additives
Cosmetic Grade Color Additives Market
Additives
Global Ester Gum Market
Additives
Caprylyl Glycol Market
Additives
North America Phosphate Esters Market
Additives
Global Feed Acidulants Market
Additives
Choline Chloride Market
Additives
Global Pour Point Depressant Market