
 Metal Deactivators Market | 2026-2036
Metal Deactivators Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Deactivators Market Intelligence
Subscription-based supply and technical support models are hardening the value proposition beyond simple chemical sales. These service-oriented contracts ensure consistent quality and performance for end-users in critical applications. The Lubrizol Corporation leverages its deep expertise in lubricant additive packages to secure long-term agreements with major clients. BASF SE competes on its global manufacturing scale and R&D investment in high-performance specialty chemicals. Meanwhile, Innospec Inc. specializes in fuel additives, creating differentiated products for specific refinery and fleet operator requirements.
Metal deactivators are chemical additives, often based on triazole derivatives like benzotriazole, designed to passivate metal surfaces such as copper and its alloys. Their primary function is to inhibit the catalytic effect of metal ions, thereby preventing the oxidative degradation of lubricants, fuels, and hydraulic fluids. Demand for aminic compounds is growing for use in high-temperature lubricant applications where thermal stability is paramount. The lubricants segment remains the largest consumer, driven by performance requirements in the petrochemical and heavy machinery industries.
Regulations such as the EU's REACH framework and EPA guidelines in the United States govern the chemical composition and registration of these additives. In China, adherence to national GB standards for fuel and lubricant quality mandates the use of effective stabilizers, influencing formulation choices for both domestic and foreign suppliers. Decisions on R&D investment into bio-based or less hazardous deactivator chemistries will determine long-term market positioning for manufacturers.
Market Dynamics
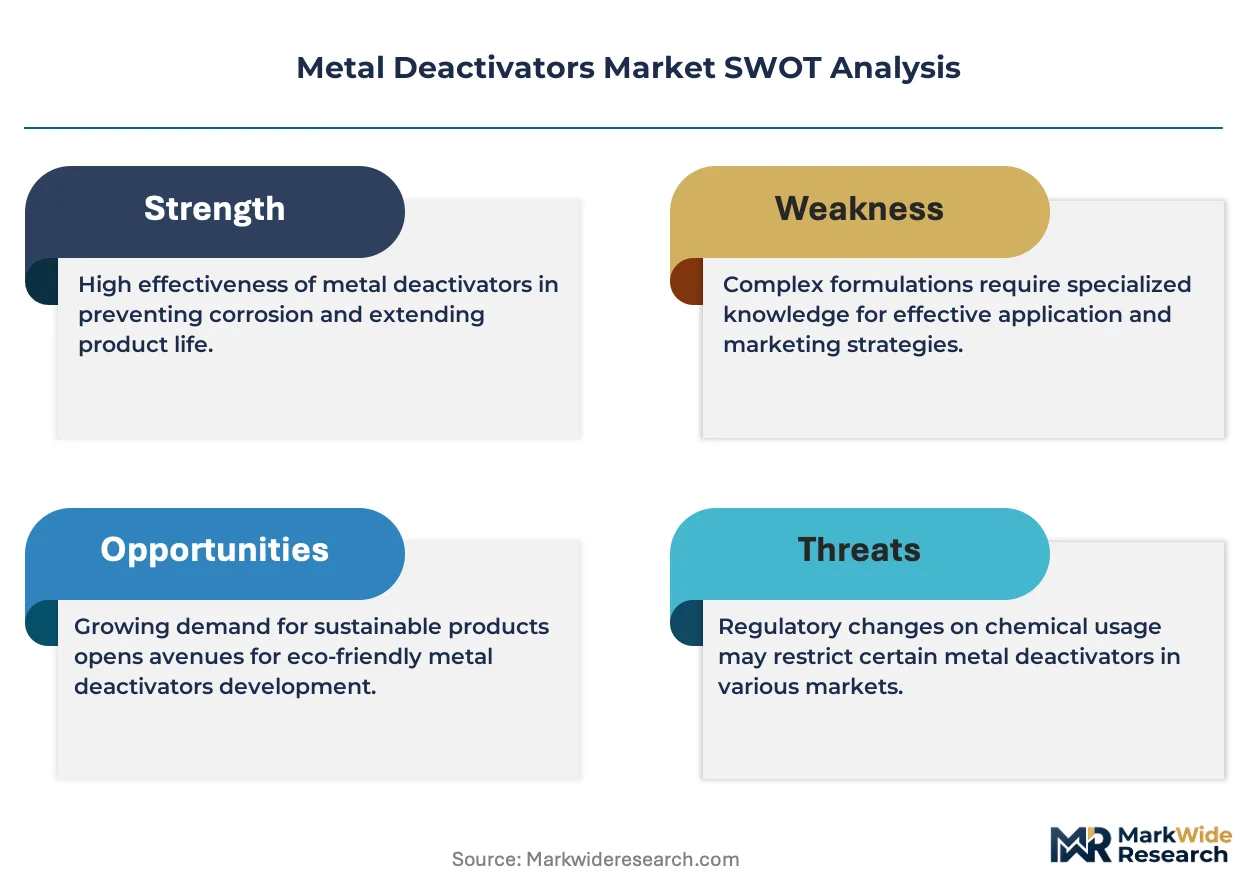
The central dynamic in the metal deactivators market is the escalating tension between performance demands for equipment longevity in harsh industrial settings and the tightening web of global chemical safety regulations. This forces continuous reformulation to meet stricter environmental and health standards without compromising technical efficacy.
Growth Catalysts
- Automotive Sector Evolution:The need for advanced lubricants in high-performance engines and specialized fluids for electric vehicles (EVs) requires effective metal deactivators to protect sensitive components like copper wiring and heat exchangers.
- Stringent Quality Mandates:In China, national GB standards for fuel and lubricant quality compel refiners and blenders to incorporate high-performance additives, including metal deactivators, to meet oxidative stability and equipment protection criteria.
- High-Temperature Applications:Demand from the petrochemical and power generation sectors for lubricants and hydraulic fluids that can withstand extreme heat drives consumption of thermally stable aminic and triazole-based deactivators.
Market Restraints
- Raw Material Price Volatility:The cost structure for many triazole-based deactivators is sensitive to fluctuations in the price of chemical precursors, which can impact final product pricing and margin stability for manufacturers.
- Regulatory Compliance Burden:The significant cost and time required to comply with chemical registration frameworks like the EU's REACH and the EPA's TSCA can slow innovation and limit the entry of new, potentially more effective, chemistries.
- Threat of Multifunctional Additives:Ongoing development of single-molecule additives that combine metal deactivation with other functions, such as anti-wear or corrosion inhibition, presents a substitution risk for standalone deactivator products.
Strategic Opportunities
- Bio-Based Lubricant Compatibility:The development of novel metal deactivators that are effective and stable within bio-based or biodegradable lubricant formulations opens a new growth avenue aligned with sustainability goals.
- Industrialization in Southeast Asia:Expanding manufacturing and infrastructure projects in countries like Vietnam and Indonesia create new demand for industrial lubricants and fuels, representing an underpenetrated market for performance additives.
- Synergistic Formulation Packages:There is an opportunity to design and market pre-blended additive packages that combine metal deactivators with specific antioxidants and corrosion inhibitors, simplifying the formulation process for lubricant blenders.
Industry Challenges
- Formulation Expertise Scarcity:A limited pool of experienced formulation chemists who understand the complex interactions between different additives, base oils, and metal surfaces creates a talent bottleneck for product development.
- Supply Chain Transparency:Ensuring the purity and consistent quality of specialized chemical precursors sourced globally is a persistent operational challenge, with impurities potentially compromising final product performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Deactivators Market |
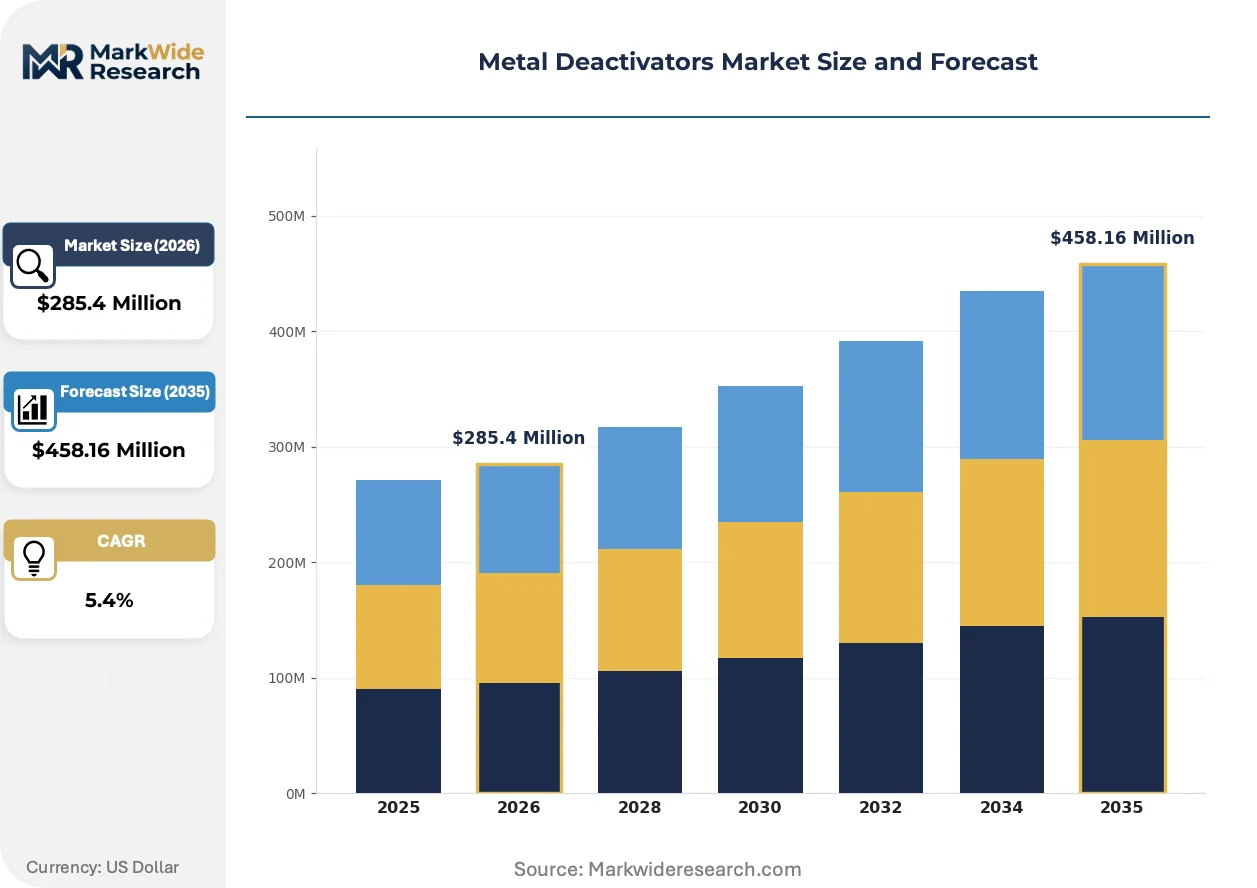
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $458.16 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benzotriazole, Tolyltriazole, Triazole Derivatives, Aminic Compounds Application: Lubricants, Fuels, Coatings, Hydraulic Fluids End User Industry: Petrochemical Plants, Power Generation, Marine Vessels, Heavy Machinery Packaging Type: Drums, Bulk Containers, Intermediate Bulk Containers, Carboys |
| Companies Covered | BASF SE, Afton Chemical, Lubrizol Corporation, Chevron Oronite, Innospec Inc., Dorf Ketal Chemicals, Infineum International Limited, LANXESS AG, Evonik Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Deactivators Market Strategic Shifts & Innovations
The market is shifting toward multifunctional and more sustainable additive chemistries. This evolution is a direct response to simultaneous pressures from regulators demanding safer chemical profiles and end-users requiring higher performance and longer fluid life in demanding applications.
Advanced aminic chemistries, originally developed for high-temperature stability, are seeing wider adoption. Lubricant formulators are specifying these compounds for demanding synthetic engine oils, turbine fluids, and hydraulic systems where thermal stress is a primary failure mode. This technology is expanding into new formulations for electric vehicle fluids, where effective thermal management and material compatibility are essential for component reliability.
Regulatory frameworks like the EU's REACH program are actively shaping product development. The regulation's stringent data requirements and substance authorization lists compel manufacturers to invest heavily in toxicological testing and seek safer-by-design alternatives. The industrial lubricants segment is most affected, with formulators prioritizing the adoption of fully REACH-compliant additive packages to maintain access to the European market.
A transition toward total fluid management contracts is altering commercial relationships. Instead of simple transactional sales, end-users in capital-intensive sectors are demanding service-oriented agreements that include ongoing fluid analysis, technical support, and performance guarantees. This shift is most prominent within the North American and European heavy machinery and power generation industries, where equipment uptime is paramount.
Metal Deactivators Market Segmentation
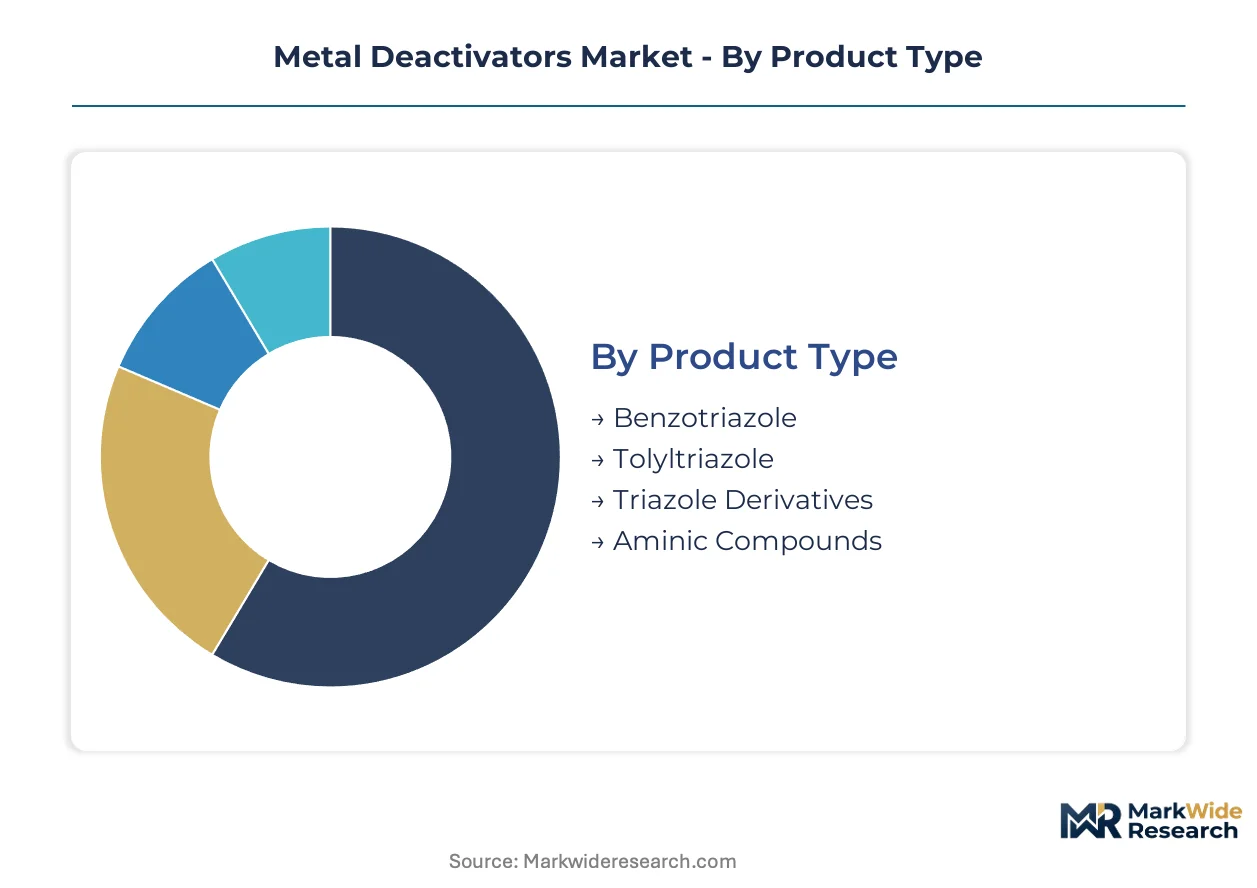
The metal deactivators market categorizes its offerings to address diverse industrial needs and regulatory landscapes. Understanding these segments reveals specific demand patterns for chemical formulations protecting critical equipment. This granular view highlights where performance requirements intersect with supply chain logistics.
Product Type:
The market for metal deactivators differentiates extensively by chemical composition and specific performance attributes.
- Benzotriazole:Benzotriazole represents a foundational triazole derivative, primarily employed for its efficacy in passivating copper and its alloys. Demand for this compound concentrates heavily in industrial lubricants, particularly for heavy machinery, where it prevents oxidative degradation and extends fluid life.
- Aminic Compounds:Aminic compounds provide superior thermal stability, making them critical for high-temperature lubricant applications. Their use is expanding into advanced synthetic engine oils and electric vehicle fluids due to stringent thermal management requirements in Europe.
- Tolyltriazole:Tolyltriazole offers similar metal passivation properties to benzotriazole, often used in industrial oils.
- Triazole Derivatives:This broader category encompasses various triazole-based chemistries providing corrosion inhibition and metal deactivation.
Benzotriazole leads on scale; Aminic Compounds leads on momentum.
Application:
Product application dictates the specific performance profile required from metal deactivators, influencing formulation choices.
- Lubricants:Lubricants form the largest consumption segment for metal deactivators, protecting engine components and industrial machinery from wear. Performance demands from the petrochemical and power generation sectors drive significant volumes in the United States.
- Fuels:Metal deactivators in fuels prevent catalytic oxidation and gum formation, preserving fuel quality and engine performance. China's national GB standards for fuel quality mandate their inclusion, particularly for diesel and gasoline.
- Coatings:Coatings utilize deactivators for corrosion protection on metal substrates, extending the lifespan of painted surfaces.
- Hydraulic Fluids:Hydraulic fluids incorporate these additives to maintain system cleanliness and prevent metal-catalyzed fluid breakdown.
The lubricants segment maintains significant volume; fuel applications are expanding most quickly.
End User Industry:
End-user industry requirements significantly shape the demand for metal deactivators, driven by operational environments.
- Heavy Machinery:The heavy machinery sector demands robust metal deactivators for lubricants in construction, mining, and agricultural equipment. Equipment longevity and uptime are critical drivers for advanced additive packages in North America.
- Petrochemical Plants:Petrochemical plants require deactivators for high-temperature lubricant and hydraulic fluid stability in extreme processing conditions. Stringent safety protocols and continuous operation necessitate reliable formulations, particularly in the Middle East.
- Power Generation:Power generation facilities use deactivators in turbine oils and transformer fluids to prevent metal-catalyzed degradation.
- Marine Vessels:Marine vessels rely on these chemicals to protect engine oils and fuel systems from corrosion in harsh saltwater environments.
Heavy machinery constitutes the largest end-use; petrochemical plants demonstrate the steepest expansion trajectory.
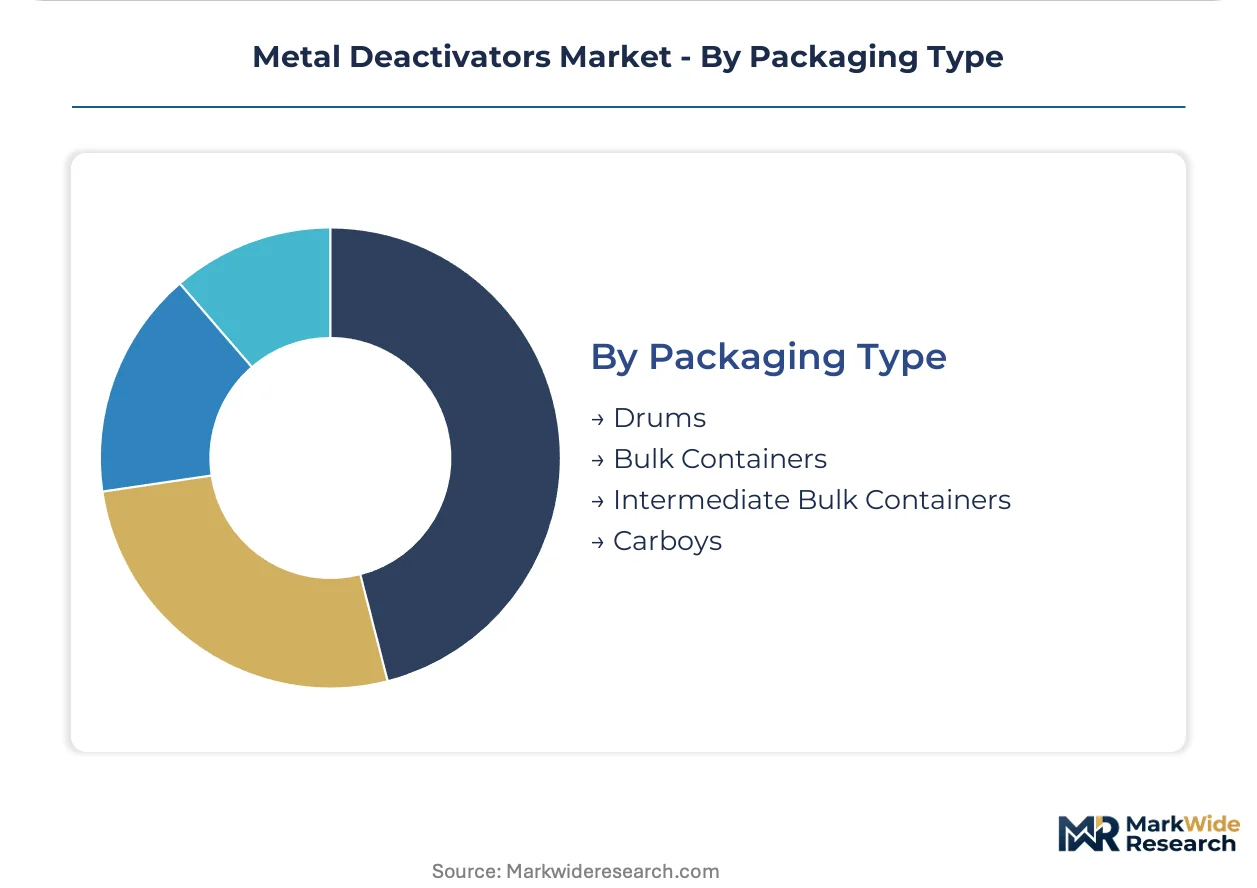
Packaging Type:
Packaging type reflects the volume of product handled by customers and influences logistics and supply chain efficiency.
- Bulk Containers:Bulk containers, including tank trucks and railcars, serve large industrial users requiring high volumes of metal deactivators. This packaging is prevalent for major lubricant blenders and fuel refiners in Asia-Pacific economies.
- Drums:Drums offer a versatile packaging solution for medium-volume users and specialized additive blends. Their widespread use facilitates distribution to lubricant formulators and industrial maintenance operations across Europe.
- Intermediate Bulk Containers:IBCs provide an efficient option for quantities larger than drums but smaller than full bulk shipments.
- Carboys:Carboys cater to laboratories, R&D facilities, and smaller-scale specialty chemical users with precise volume needs.
Bulk containers account for the largest volume; intermediate bulk containers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While the United States drives metal deactivator demand through its robust petrochemical sector, China's rapid industrialization and stringent fuel standards necessitate high volumes of advanced additives. These distinct regional pressures highlight the diverse regulatory and industrial landscapes influencing market consumption patterns for chemical additives globally.
United States
Demand for metal deactivators in the United States stems from the heavy machinery and petrochemical industries, requiring robust lubricants and hydraulic fluids. EPA guidelines influence the formulation of new deactivator chemistries, prioritizing environmental safety alongside performance. Major industrial clusters in Texas and Louisiana drive significant consumption for refining and offshore drilling operations.
China
China's automotive and industrial sectors are primary demand drivers for metal deactivators, particularly in advanced lubricants and fuels. National GB standards for fuel and lubricant quality mandate the inclusion of effective stabilizers to ensure equipment longevity. The Yangtze River Delta region, a hub for manufacturing and automotive production, sees concentrated demand for these performance additives.
Germany
Germany's sophisticated manufacturing and automotive industries require high-performance metal deactivators for synthetic lubricants and specialized industrial fluids. The EU's REACH framework significantly shapes product development, compelling manufacturers to invest in compliant and safer-by-design chemistries. The industrial heartlands of Bavaria and North Rhine-Westphalia are key consumption areas for advanced additive packages.
India
Industrialization and automotive sector expansion in India are fueling demand for metal deactivators in lubricants and fuels. BIS standards ensure quality and performance in various industrial applications, influencing additive selection. Manufacturing hubs in Maharashtra and Gujarat exhibit strong demand for deactivators used in heavy machinery and power generation.
Japan
Japan's advanced automotive and electronics manufacturing sectors require specialized metal deactivators for precision lubricants and functional fluids. JIS standards dictate the quality and performance parameters for these chemical additives, promoting innovation. The Kanto region, including Tokyo, serves as a significant consumption area due to its dense industrial and automotive base.
Metal Deactivators Market Key Industry Players
Top-tier vendors anchor the global metal deactivators market, while a diverse array of specialized chemical manufacturers contributes to a tiered competitive structure. The market is characterized by global chemical giants and niche additive specialists. Strategic partnerships and continuous R&D investment represent dominant competitive moves.
Within the global chemical giants, BASF SE leverages its extensive manufacturing scale and substantial R&D investment in high-performance specialty chemicals. Lubrizol Corporation, a prominent player, secures long-term agreements with major clients by demonstrating deep expertise in lubricant additive packages. Both exemplify the trend towards offering comprehensive solutions rather than simple chemical sales.
| Leading Market Players |
|---|
| BASF SE |
| Afton Chemical |
| Lubrizol Corporation |
| Chevron Oronite |
| Innospec Inc. |
| Dorf Ketal Chemicals |
| Infineum International Limited |
| LANXESS AG |
| Evonik Industries |
| Others |
Cost & Logistics Intelligence
The development of advanced aminic chemistries simultaneously reshapes cost economics and supply concentration by demanding specialized precursors and manufacturing processes. This shift influences both the price structure and the geographic sourcing of metal deactivators.
Pricing Analysis
Capacity additions in China are reshaping price floors for commodity-grade metal deactivators, particularly benzotriazole. The market primarily utilizes value-based pricing for specialized formulations and contract-based long-term offtake agreements for bulk volumes. Price differentiation stems from performance certification (e.g., REACH compliance) and technical support services. Pricing softness for standard triazoles reflects raw material price volatility. End-users in critical applications like petrochemicals exhibit lower price sensitivity compared to smaller industrial lubricant blenders.
Supply Chain Analysis
Single-source vulnerability sits with specialized chemical precursor suppliers, particularly for advanced aminic compounds. Geographic supply concentration for key raw materials draws from China and certain European producers. Raw material dependencies include triazole derivatives and specific amine intermediates. Logistics chokepoints, particularly for hazardous chemicals, pose a structural risk. Distribution runs through a hybrid model combining bulk shipments for major refiners and lubricant blenders, alongside drums and intermediate bulk containers for smaller formulators across Europe and Asia-Pacific.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Metal Deactivators Market presents a geographic-arbitrage play, driven by the higher regulatory compliance costs in Europe versus the rapid industrial growth in Southeast Asia.
For Market Incumbents: Extend long-term technical support contracts with major clients to deepen relationships and defend market share against emerging multifunctional additives. Invest heavily in R&D for bio-based or less hazardous deactivator chemistries to mitigate future regulatory threats. Expand manufacturing capabilities in high-growth regions like Southeast Asia to capture new demand and optimize logistics.
For New Entrants and Emerging Players: Digital platforms for technical data and product specifications offer a viable route to market. Target the underpenetrated Southeast Asian industrial lubricants segment with cost-effective, performance-validated formulations. Focus on developing synergistic formulation packages that simplify blending for smaller customers, offering a clear go-to-market advantage.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-sized specialty chemical firms with strong R&D pipelines in sustainable chemistries. The market offers long-term viability, driven by persistent equipment protection needs and evolving regulatory mandates. A key signal to watch is the adoption rate of electric vehicle fluids, indicating shifts in high-performance additive demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Bio-Based Deactivator R&D | Secures future market access under stricter environmental regulations like EU REACH. |
| Expand Technical Support Models | Enhances customer loyalty and ensures consistent performance in critical industrial applications. |
| Develop Synergistic Additive Packages | Simplifies formulation processes for lubricant blenders, attracting new clients. |
| Target Southeast Asian Industrialization | Captures new demand from expanding manufacturing and infrastructure projects in the region. |
| Secure Key Precursor Supply Agreements | Mitigates raw material price volatility and ensures consistent production for core products. |
Research Approach
Direct dialogue with R&D directors at additive manufacturers, procurement leads at lubricant blenders, and regulatory affairs specialists informed the qualitative grounding. This primary research was validated through secondary data sources including EU REACH documentation, EPA guidelines, China GB standards, and industry association reports, employing both bottom-up and top-down triangulation.
A bottom-up market sizing approach, validated through top-down checks, formed the analytical framework across the projection horizon. The modeling integrated segmentation across product type, application, end-user industry, packaging type, and regional regulatory compliance status. CAGRs were derived from historical growth analysis and future demand drivers such as EV adoption and industrialization trends, with lubricant consumption trends serving as a key industry-specific forecast input.
Raw material price volatility, evolving regulatory frameworks, and rapid shifts in automotive technology are the dominant revision risks for market forecasts. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Benzoates Market
Additives
Global Carboxylic Acids Based Esters Market
Additives
Chelated Selenium Market
Additives
Driveline Additives Market
Additives
Global Hindered Amine Light Stabilizers Market
Additives
United Kingdom Sodium Reduction Ingredient Market
Additives
Amino Acids Premixes Market
Additives
Plastic Antioxidants Market
Additives
Green Chelates/Natural Chelating Agents Market
Additives
Organic Friction Modifier Additives Market
Additives
Global Sizing Agents Market
Additives
Europe Choline Chloride Market
Additives
Nucleating Agents Market
Additives
Anti-Wear Additives Market
Additives
Sodium Metabisulfite Market
Additives
Global Polyurethane Additives Market