
 Global Carboxylic Acids Based Esters Market | 2026-2036
Global Carboxylic Acids Based Esters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Carboxylic Acids Based Esters Market Foresight
Modular solvent blends for low-VOC coatings is realigning procurement patterns across industrial finishers. BASF SE leverages its integrated C1 chemistry platform to secure feedstock flexibility for acetate esters. Eastman Chemical Company anchors North American supply through its Kingsport manufacturing complex. Celanese Corporation competes on acetyl chain depth, extending captive methanol and acetic acid into derivative ester output.
Carboxylic acids based esters comprise organic compounds formed through esterification of aliphatic carboxylic acids with alcohols, typically exhibiting boiling points between 50°C and 150°C and polarity indices suited for precision dissolution. These substances serve primarily as reaction media, extraction solvents, and formulation carriers across coatings, pharmaceuticals, and polymer processing. Ethyl acetate and butyl acetate dominate volume flows through paints and coatings applications, where technical grade specifications command the largest share of commodity offtake. Pharmaceutical grade esters carry premium positioning due to USP and EP compliance burdens, while solvent applications in inks and dyes represent a faster-growing niche driven by waterborne system migration.
EPA VOC regulations under the Clean Air Act constrain permissible solvent emissions in architectural and industrial maintenance coatings, redirecting formulators toward exempt ester compounds. REACH registration requirements and ECHA substance evaluation impose full toxicological dossiers on European manufacturers, elevating compliance costs for import-dependent buyers. FDA pharmaceutical excipient standards govern USP-grade ester purity thresholds for oral and topical drug delivery systems. Stakeholders must monitor bio-based feedstock certification schemes and regional carbon border adjustments as these frameworks reshape raw material sourcing economics.
Market Dynamics
EU F-Gas Regulation and EPA VOC constraints are forcing solvent substitution toward bio-based ester chemistry, compressing demand for conventional petroleum-derived acetates while elevating certified bio-esters in coatings procurement.
Growth Catalysts
- REACH Registration Mandates:Full toxicological dossier requirements under ECHA substance evaluation are redirecting European formulators toward compliant ester suppliers with pre-registered portfolios.
- Automotive Refinishing Recovery:Collision repair volume concentration in Germany, China, and the United States is pulling technical-grade butyl acetate through OEM-certified coating systems.
- Bio-Feedstock Certification:ISCC PLUS and RSB certification schemes for renewable acetic acid are unlocking premium positioning in pharmaceutical-grade ethyl acetate segments.
Market Restraints
- Methanol Feedstock Volatility:Captive methanol supply dependence among integrated acetyl producers exposes margin compression when natural gas benchmarks fluctuate.
- Acetic Acid Supply Concentration:Gulf Coast and Northeast Asian methanol-to-acetic acid capacity clusters create geographic vulnerability for derivative ester output.
- Aqueous System Substitution:Waterborne coating technologies are eroding solvent-borne ester volumes in architectural applications where performance specifications permit.
Strategic Opportunities
- Indian Pharmaceutical Excipient Demand:CDSCO and USP dual-compliance requirements for oral drug delivery systems are opening specialized ester purification investments.
- EU Green Deal Carbon Border Adjustments:Embedded carbon accounting for imported petrochemical esters is creating first-mover advantage for bio-based domestic producers.
- Digital Formulation Platforms:AI-driven solvent blend optimization tools are enabling custom ester portfolios for low-VOC industrial maintenance specifications.
Industry Challenges
- Process Safety Expertise Scarcity:Esterification reactor hazard management and ATEX compliance certification timelines are extending commissioning schedules for new capacity.
- Legacy Equipment Retrofit Costs:Continuous esterification technology migration from batch systems demands capital deployment for heat integration and distillation efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Carboxylic Acids Based Esters Market |
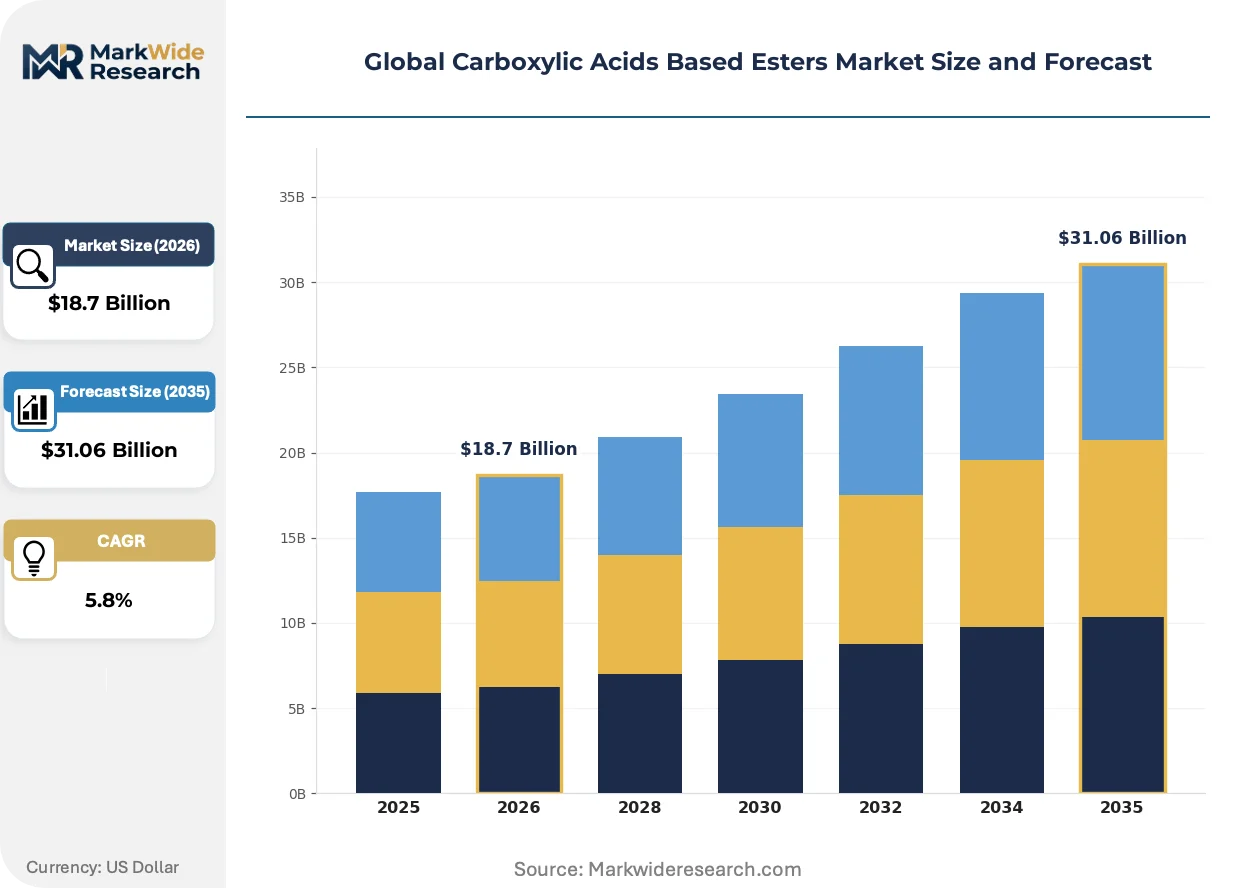
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ethyl Acetate, Butyl Acetate, Isopropyl Acetate, Propyl Acetate, Methyl Acetate Grade: Pharmaceutical Grade, Technical Grade, Food Grade, Industrial Grade, Cosmetic Grade Application: Paints & Coatings, Plasticizers, Solvents, Personal Care Products, Inks & Dyes End Use Industry: Pharmaceuticals, Agriculture, Construction, Textile Manufacturing, Electronics |
| Companies Covered | BASF SE, Eastman Chemical Company, Celanese Corporation, Sasol Limited, Wacker Chemie AG, Dow Inc., Perstorp Holding AB, LyondellBasell Industries N.V., Green Biologics Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Carboxylic Acids Based Esters Market Shifts & Advancements
Reaction engineering advances and regulatory chemistry mandates are compressing the innovation cycle for solvent-grade esters, with bio-catalytic routes and modular production architectures now competing against conventional petrochemical scale economics.
Enzymatic esterification using immobilized lipase biocatalysts is electrifying specialty ester production for fragrance and pharmaceutical applications. Flavor and fragrance houses in Switzerland and Germany are adopting these routes for chiral ester specificity. The technology is compressing capital requirements for small-batch pharmaceutical-grade output while elevating purity thresholds beyond conventional sulfuric acid catalysis.
REACH authorization sunset dates for conventional solvents are forcing coating formulators toward exempt ester compounds with favorable toxicological profiles. Industrial maintenance finishers in the Netherlands and Belgium are reformulating ahead of 2025-2027 restriction timelines. The segment is responding through pre-registration of bio-based alternatives and supply chain qualification of certified renewable feedstock sources.
Direct-to-formulator digital channels are fragmenting traditional distributor control over solvent blend specifications. Mid-sized coatings producers in the United States are sourcing single-specification esters through integrated supplier portals rather than regional chemical distributors. The shift is most visible in automotive refinishing clusters where just-in-time inventory and technical service integration determine supplier selection.
Global Carboxylic Acids Based Esters Market Segmentation
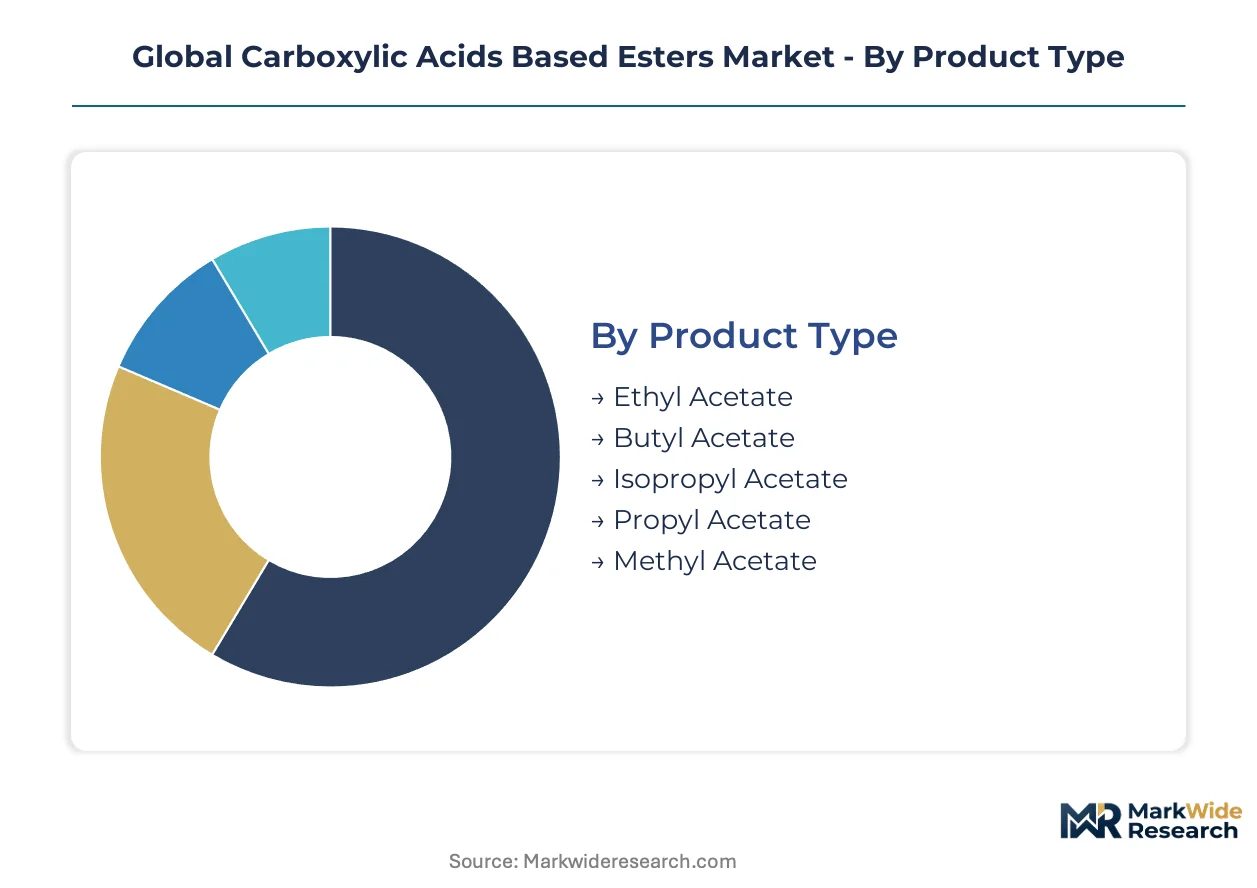
Carboxylic acids based esters fragment across five distinct product chemistries, each demanding specialized reactor configurations and distillation trains. Grade differentiation separates commodity solvent flows from high-purity pharmaceutical and food-certified streams. Application concentration in coatings and plastics processing determines regional capacity placement, while end-use industry exposure shapes regulatory compliance burdens across manufacturing footprints.
Product Type:
Capital intensity escalates with carbon chain length and separation complexity, with C4 derivatives requiring more sophisticated purification infrastructure than C2 alternatives.
- Ethyl Acetate:The C2 acetate ester dominates commodity solvent flows through its 77°C boiling point and favorable polarity index for coatings dissolution. Demand concentrates in automotive refinishing clusters across Germany, China, and the United States, where OEM-certified coating systems pull technical-grade volumes through certified supply chains.
- Butyl Acetate:This C4 ester commands premium positioning in high-solids coatings where slower evaporation rates enable flow and leveling control. Construction activity in the United States and infrastructure spending in China absorb the majority of industrial-grade offtake for architectural and protective coatings.
- Isopropyl Acetate:Branched-chain structure delivers intermediate volatility for specialty ink formulations and adhesive systems.
- Propyl Acetate:Straight-chain C3 variant serves niche fragrance and flavor applications requiring specific odor profiles.
- Methyl Acetate:Lowest molecular weight acetate finds use in polyurethane foam blowing agents and rapid-evaporation cleaner formulations.
Ethyl acetate absorbs the bulk of installed capacity; butyl acetate is expanding most quickly.
Grade:
Cost tiers stratify sharply around certification burdens, with pharmaceutical and food grades carrying 3-4x purification overhead versus technical specifications.
- Pharmaceutical Grade:USP and EP compliance mandates residual solvent testing, microbial limits, and heavy metals screening for oral and topical drug delivery systems. CDSCO dual-registration requirements in India are opening specialized purification investments for export-oriented manufacturers.
- Technical Grade:The commodity tier supplies industrial coatings, adhesives, and general-purpose solvent applications with basic purity specifications. EPA VOC regulations under the Clean Air Act constrain permissible emissions, redirecting formulators toward exempt ester compounds with favorable toxicological profiles.
- Food Grade:FSSAI and FDA food additive compliance enables flavor carrier and extraction solvent applications in beverage and confectionery processing.
- Industrial Grade:Broad-spectrum specifications serve metal degreasing, equipment cleaning, and maintenance solvent markets.
- Cosmetic Grade:INCI listing and safety dossier requirements govern personal care formulation incorporation.
Technical grade commands the largest volume position; pharmaceutical grade climbs the fastest on excipient demand expansion.
Application:
Volume concentration aligns with coatings and plastics processing cycles, while customer type fragmentation distinguishes between formulation houses and direct industrial users.
- Paints & Coatings:The dominant application channel consumes acetate esters as active solvents in solvent-borne systems and co-solvents in waterborne technologies. REACH authorization sunset dates for conventional solvents are forcing industrial maintenance finishers in the Netherlands and Belgium toward exempt ester compounds ahead of restriction timelines.
- Plasticizers:Ester chemistry enables flexible PVC compound formulation for wire insulation, flooring, and medical tubing. Construction activity in the United States and automotive wire harness demand in Germany absorb specialized plasticizer ester flows.
- Solvents:General-purpose dissolution and extraction applications span pharmaceutical synthesis, agrochemical formulation, and chemical processing.
- Personal Care Products:Fragrance dilution and cosmetic formulation incorporation require odor-neutral ester specifications.
- Inks & Dyes:Publication gravure and flexographic printing depend on controlled evaporation profiles for dot fidelity and drying speed.
Paints and coatings anchor the application mix; inks and dyes gain share fastest on waterborne system migration.
End Use Industry:
Supply concentration clusters around pharmaceutical and agricultural chemical manufacturing hubs, with construction and electronics representing emerging demand pockets.
- Pharmaceuticals:Oral drug delivery systems, topical formulations, and API synthesis consume USP-grade esters under FDA and EMA oversight. The sector's quality systems impose batch documentation, stability testing, and supplier audit requirements that elevate procurement costs.
- Agriculture:Pesticide emulsifiable concentrates and herbicide formulations utilize ester solvents for active ingredient dissolution and field application compatibility. Brazil's ANVISA and the United States EPA jointly govern residue limits and environmental fate assessments for agrochemical ester carriers.
- Construction:Architectural coatings, sealants, and adhesives absorb technical-grade volumes tied to housing starts and commercial building activity.
- Textile Manufacturing:Dye carrier and printing auxiliary applications serve fabric finishing and coloration processes.
- Electronics:Precision cleaning and photoresist stripping operations demand ultra-high-purity ester specifications with controlled particulate and moisture content.
Pharmaceuticals concentrate the highest-value offtake; agriculture is expanding most quickly on crop protection formulation demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in Germany, China, and the United States while consumption spreads across automotive refinishing hubs and pharmaceutical manufacturing zones. Feedstock access and regulatory stringency divide regional competitiveness.
United States
Automotive collision repair volume in Michigan and Ohio pulls technical-grade butyl acetate through OEM-certified coating systems. EPA VOC regulations under the Clean Air Act constrain permissible solvent emissions in architectural and industrial maintenance coatings. The Gulf Coast methanol-to-acetic acid corridor supplies derivative ester output to domestic formulators.
Germany
REACH authorization sunset dates for conventional solvents are forcing industrial maintenance finishers toward exempt ester compounds ahead of 2025-2027 restriction timelines. The EU F-Gas Regulation and ECHA substance evaluation impose full toxicological dossiers on manufacturers. BASF SE leverages its integrated C1 chemistry platform at Ludwigshafen to secure feedstock flexibility for acetate esters.
China
Infrastructure spending absorbs industrial-grade butyl acetate for architectural and protective coatings across construction activity. The country's national environmental regulator enforces dual carbon goals that reshape raw material sourcing economics. Yangtze River Delta chemical parks concentrate esterification capacity serving domestic coatings producers.
India
CDSCO and USP dual-compliance requirements for oral drug delivery systems are opening specialized ester purification investments. The national pharmaceutical regulator mandates batch documentation and supplier audit requirements that elevate procurement costs. Maharashtra and Gujarat host export-oriented manufacturers targeting pharmaceutical-grade ethyl acetate segments.
Switzerland
Flavor and fragrance houses adopt enzymatic esterification routes for chiral ester specificity in specialty applications. Swissmedic oversight governs pharmaceutical excipient standards for regional drug delivery systems. Basel-area chemical clusters concentrate biocatalytic production capacity for small-batch pharmaceutical-grade output.
Global Carboxylic Acids Based Esters Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct value chain positions. The vendor base stratifies into three tiers: integrated petrochemical majors with captive acetic acid supply, regional esterification specialists serving coating formulators, and bio-based technology developers targeting certified renewable segments. Strategic moves center on backward integration into methanol feedstock and portfolio diversification toward pharmaceutical-grade purification capabilities.
Within the integrated petrochemical tier, BASF SE and Eastman Chemical Company exemplify divergent geographic anchoring strategies. BASF SE occupies a position tied to European regulatory compliance and bio-feedstock certification schemes. Eastman Chemical Company anchors North American supply through its Tennessee manufacturing footprint. Celanese Corporation sits within the acetyl chain depth archetype, extending captive methanol and acetic acid positions into derivative ester output.
| Leading Market Players |
|---|
| BASF SE |
| Eastman Chemical Company |
| Celanese Corporation |
| Sasol Limited |
| Wacker Chemie AG |
| Dow Inc. |
| Perstorp Holding AB |
| LyondellBasell Industries N.V. |
| Green Biologics Limited |
| Others |
Supply & Pricing Matrix
Captive acetyl chain integration among methanol-to-ester producers anchors both supply security and pricing power for derivative acetate output. BASF SE's Ludwigshafen complex and Eastman Chemical Company's Kingsport facility exemplify how backward control over methanol and acetic acid insulates margin structures from feedstock volatility while compressing procurement leverage for non-integrated buyers.
Pricing Analysis
Margin tightening in technical-grade acetates reflects methanol benchmark volatility and aqueous coating substitution pressure. Three-tier pricing structure across pharmaceutical, technical, and industrial grades separates USP-compliant purification overhead from commodity solvent specifications. Certification burden and volume scale differentiate price bands, with pharmaceutical-grade buyers least sensitive due to regulatory compliance lock-in while architectural coatings formulators face acute cost-down pressure from waterborne technology migration.
Supply Chain Analysis
Direct-to-formulator digital channels handle custom solvent blend specifications for automotive refinishing clusters. Production gravity centers on Germany, China, and the United States, with methanol-to-acetic acid capacity concentrated along the Gulf Coast and Yangtze River Delta. Feedstock dependence draws from natural gas benchmarks and bio-based acetic acid certification schemes. Single-source vulnerability in methanol supply exposes derivative ester output to commodity price swings. Distribution runs through integrated supplier portals and regional chemical distributors serving coating formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic esterification biocatalysts are displacing sulfuric acid catalysis in pharmaceutical-grade production, compressing capital requirements for small-batch chiral specificity while elevating purity thresholds beyond conventional routes.
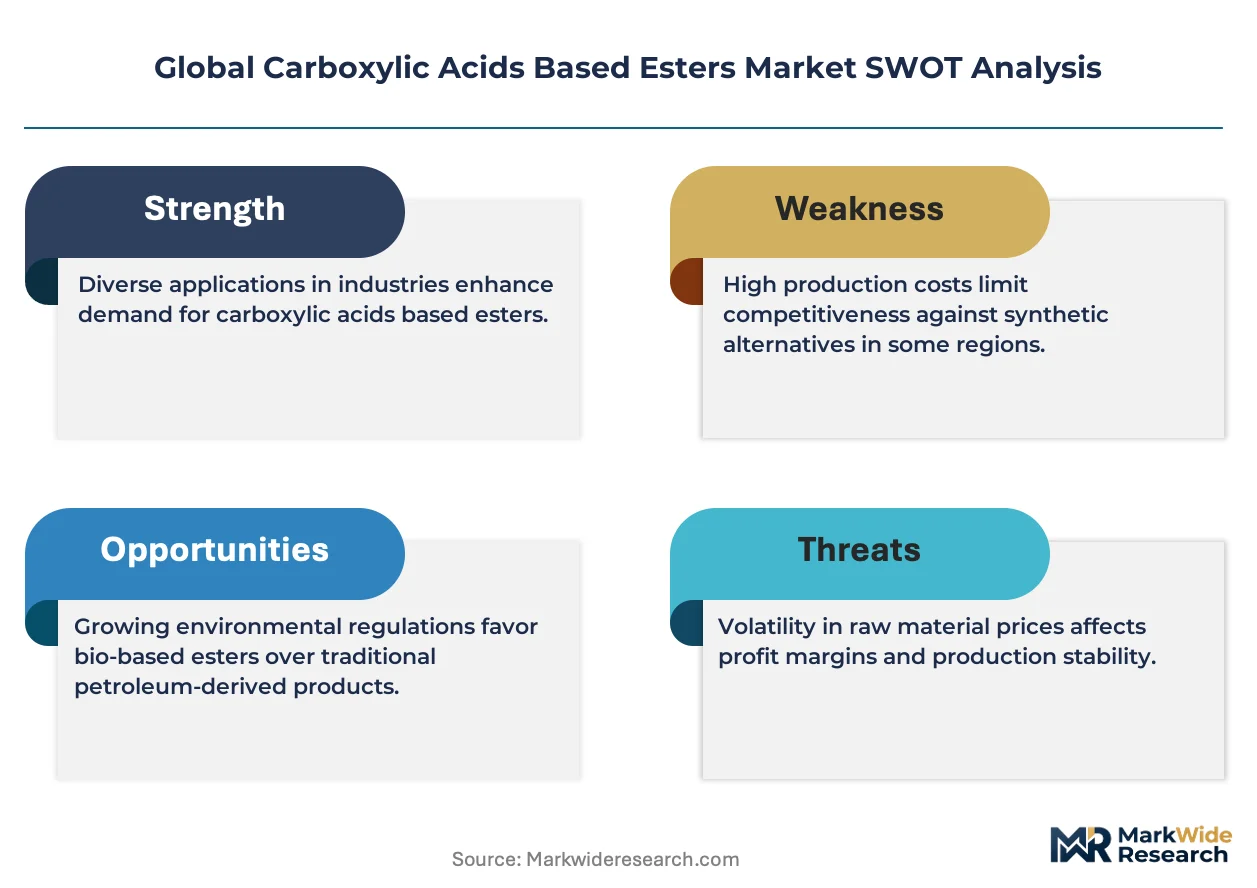
For Market Incumbents: To counter aqueous system substitution in architectural coatings, BASF SE and Celanese Corporation should deepen captive methanol positions through Gulf Coast feedstock agreements while accelerating ISCC PLUS certification for bio-based ethyl acetate portfolios targeting EU Green Deal carbon border adjustments. For New Entrants and Emerging Players: Biocatalytic production platforms offer entry wedge into Swiss and German fragrance houses demanding chiral ester specificity. White-space concentration sits in Indian pharmaceutical excipient supply, where CDSCO-USP dual-compliance requirements strain existing purification capacity. Go-to-market positioning should emphasize enzymatic route purity advantages and batch documentation automation. For Investors and Strategic Acquirers: Exit pathways concentrate in bio-based technology developers with certified renewable feedstock positions and pharmaceutical-grade purification capabilities. Long-term viability favors assets with backward integration into acetic acid and established ECHA pre-registration portfolios. The signal to watch is EU F-Gas Regulation enforcement timing and REACH authorization sunset date acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Methanol Feedstock | Gulf Coast natural gas corridor access secures margin insulation against commodity volatility. |
| ISCC PLUS Certification Investment | Bio-based acetic acid sourcing unlocks premium positioning under EU carbon border adjustments. |
| Enzymatic Esterification Scale-Up | Immobilized lipase biocatalysts enable chiral specificity for Swiss fragrance and pharmaceutical demand. |
| Pharmaceutical-Grade Purification Expansion | USP-EP compliance infrastructure captures Indian CDSCO dual-registration export requirements. |
| Direct-to-Formulator Digital Channel | Integrated supplier portals bypass regional distributors in automotive refinishing clusters. |
Research Methodology
SEC 10-K filings, Cefic industry reports, and customs trade data formed the secondary backbone, cross-referenced with primary interviews involving esterification plant managers, coatings procurement leads at automotive OEMs, distribution channel partners, and pharmaceutical regulatory affairs directors. Bottom-up capacity modeling and top-down demand triangulation validated volume estimates across the analysis window.
Historical trendline analysis of ethyl acetate and butyl acetate production volumes established baseline growth patterns, with CAGR derivation incorporating grade tier, end-use industry exposure, and regional production hub dynamics. Forecast inputs included REACH authorization timelines, EPA VOC regulatory stringency indices, and bio-feedstock certification adoption curves.
Several conditions sit outside the modeled scope, including unannounced capacity additions, geopolitical trade restriction escalations, and breakthrough aqueous coating technologies. Forecasts reflect documented assumptions on regulatory enforcement pacing and feedstock cost trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Dipotassium Guanylate Market
Additives
United States Citric Acid Market
Additives
Calcium Acetate Market
Additives
Glycyrrhizic Acid Glycosides Market
Additives
Alginic Acid Market
Additives
Citrate Ester Market
Additives
Silage Additives Market
Additives
Global Dicalcium Phosphate (Feed Grade) Market
Additives
Europe Fuel Additives Market
Additives
Crystal Growth Modifier Market
Additives
Indonesia Feed Additives Market
Additives
Global Sodium Acetate Trihydrate Market
Additives
Grease Additives Market
Additives
Sorbitan Tristearate Market
Additives
Global UV Absorbers Market
Additives
High Performing Matting Agents Market