
 North America Polyether Ether Ketone (Peek) Market | 2026-2036
North America Polyether Ether Ketone (Peek) Market Size, Share, and Industry Trends Forecast 2026-2036
North America Polyether Ether Ketone (Peek) Market Insights
Mexico is narrowing its PEEK compounding deficit through new extrusion investments in Querétaro and Tijuana. Victrex PLC leverages its Texas distribution hub to sustain just-in-time supply chains across the continent. Syensqo anchors its North American position through specialized medical-grade resin production. Evonik Industries AG differentiates via high-purity formulations targeting semiconductor fabrication equipment.
Polyether ether ketone is a semi-crystalline thermoplastic polymer synthesized through step-growth polymerization of 4,4'-difluorobenzophenone and hydroquinone, exhibiting a melting point near 343°C and continuous service temperature up to 260°C. Its aromatic backbone delivers chemical resistance, flame retardancy, and mechanical retention for metal replacement in extreme environments. Filled and reinforced PEEK grades command premium positioning as aerospace OEMs substitute aluminum and titanium in bracketry and fasteners. Medical device end users represent the fastest-expanding demand pool as spinal implants and orthopedic instruments shift toward radiolucent polymer solutions. Powder and pellet forms dominate volume flows, though rod stock for precision machining carries disproportionate margin contribution.
FDA 21 CFR biocompatibility requirements and NHTSA crashworthiness standards shape material qualification timelines and testing burdens for suppliers seeking automotive and medical entry. EPA emissions regulations under the Clean Air Act indirectly pressure molders toward PEEK as a durable, lightweight alternative that reduces vehicle mass and fuel consumption. Stakeholders must monitor evolving FAA airworthiness directives for polymer matrix composites and FDA guidance on long-term implantable device materials as these frameworks will determine certification pathways and capital allocation priorities.
Market Dynamics
PEEK demand in North America is being fundamentally restructured by the FAA's airworthiness directives for polymer matrix composites, which are accelerating metal substitution timelines in commercial aerospace while simultaneously lengthening material qualification cycles.
Growth Catalysts
- FAA Airworthiness Directives:Updated polymer matrix composite standards are compelling Boeing and Gulfstream to expand PEEK fastener and bracket applications in next-generation airframes.
- Medical Device Radiolucency Requirements:Spinal implant OEMs are converting titanium instrumentation to carbon-fiber-reinforced PEEK for improved post-operative imaging clarity under FDA 21 CFR biocompatibility frameworks.
- Great Lakes Automotive Belt Concentration:Ford and GM lightweighting mandates for electric vehicle battery enclosures are pulling unfilled PEEK grades into structural thermal management components.
Market Restraints
- Fluorobenzophenone Feedstock Volatility:4,4'-difluorobenzophenone supply concentrates among European specialty chemical producers, exposing compounders to currency and energy cost swings.
- Qualification Timeline Compression:NHTSA crashworthiness testing for automotive PEEK components extends development cycles 18-24 months beyond conventional polymer approvals.
- High-Performance Polyamide Substitution:PA46 and PPA grades from DSM and DuPont capture price-sensitive connector and under-hood applications where thermal requirements marginally permit.
Strategic Opportunities
- Querétaro Medical Device Cluster:Mexico's expanding orthopedic manufacturing base offers captive compounding partnerships for FDA-registered resin supply to Tijuana and Juárez maquiladoras.
- Semiconductor Fabrication Equipment:Wafer handling components and chamber hardware represent an emerging high-purity PEEK application as domestic chip fabrication expands under CHIPS Act incentives.
- Additive Manufacturing Convergence:Laser sintering and fused filament fabrication of PEEK are opening patient-specific spinal cages and aerospace ducting without conventional machining waste.
Industry Challenges
- Polymer Processing Expertise Gap:Molders capable of maintaining 380-400°C melt temperatures with tight crystallinity control remain scarce in the U.S. Gulf Coast corridor.
- FDA Long-Term Implantable Guidance Uncertainty:Draft guidance on 10-year biocompatibility data requirements for permanent implants is freezing capital allocation decisions among device startups.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Polyether Ether Ketone (Peek) Market |
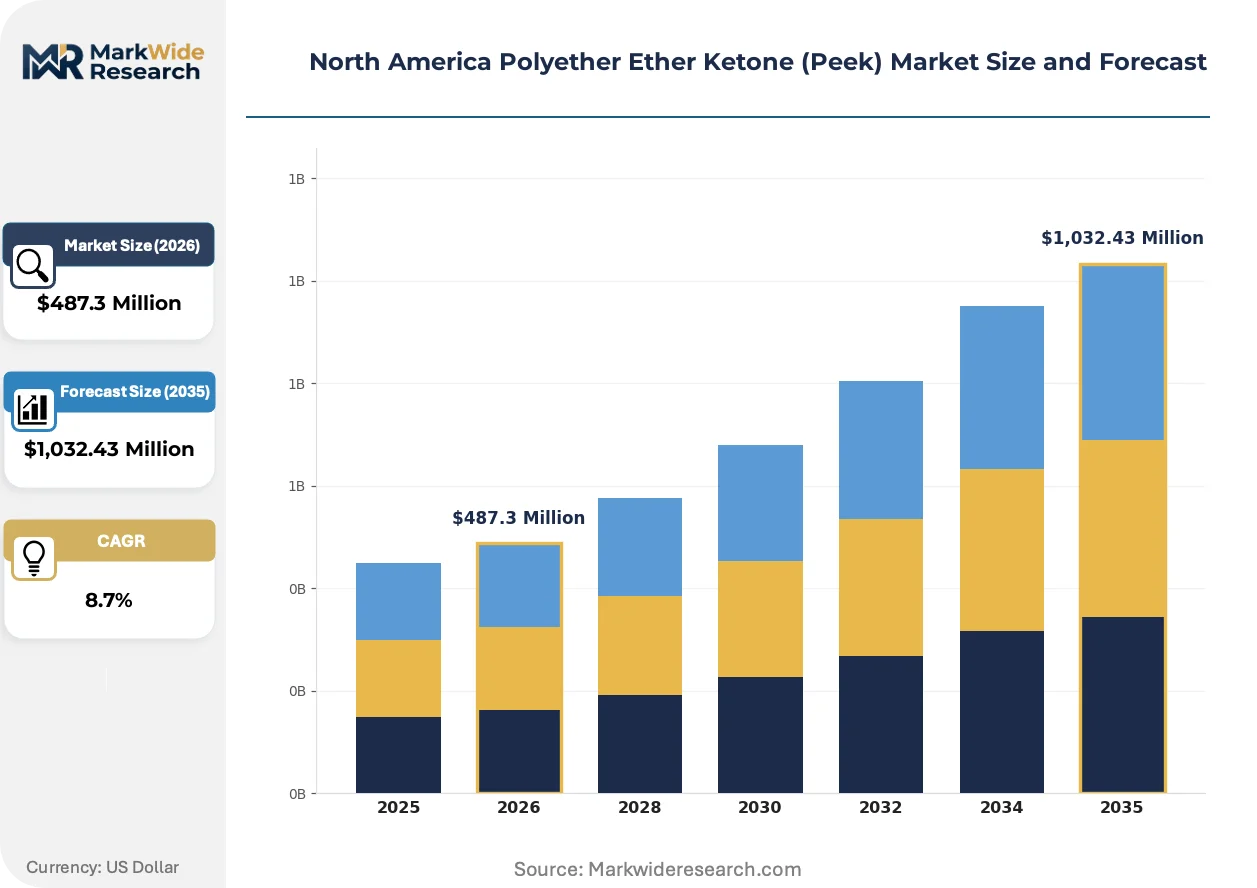
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unfilled, Filled, Reinforced, Blends End User: Aerospace, Automotive, Medical Devices, Electronics Form: Pellets, Powder, Sheets, Rods Application: Structural Components, Insulation, Seals, Aerospace Parts |
| Companies Covered | Victrex PLC, Syensqo, Evonik Industries AG, SABIC, Celanese Corporation, Solvay SA, RTP Company, Ensinger, Ferguson PLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Polyether Ether Ketone (Peek) Market Trends and Innovations
Material formulation and manufacturing process boundaries are dissolving as aerospace OEMs demand structural performance previously reserved for metals, while medical device engineers exploit PEEK's imaging transparency for precision surgical navigation.
Carbon-fiber-reinforced PEEK is migrating from secondary bracketry to primary structural members in regional jet programs. Bombardier and Embraer procurement teams are qualifying braided sleeve and unidirectional tape formats for wing rib and floor beam applications. This migration from metal-intensive legacy designs is compressing airframe weight targets by 12-15% in targeted subassemblies while extending supplier qualification timelines.
EPA Clean Air Act enforcement under the current administration is tightening fleet average fuel economy standards for light-duty vehicles. Automakers are responding by substituting PEEK for metal in throttle bodies, water pump housings, and transmission components where heat and chemical resistance converge. The Great Lakes manufacturing belt shows the most aggressive specification changes as Ford and Stellantis redesign platforms for electrification.
Hospital procurement consortiums are consolidating orthopedic implant sourcing around vertically integrated suppliers capable of delivering instrument kits, trials, and permanent implants from common resin lots. This concentration is squeezing independent distributors and forcing compounders to validate complete supply chain traceability from monomer to sterilized device. The shift is most visible in Midwest hospital networks where Premier and Vizient group purchasing organizations dominate spine and joint reconstruction categories.
North America Polyether Ether Ketone (Peek) Market Segmentation
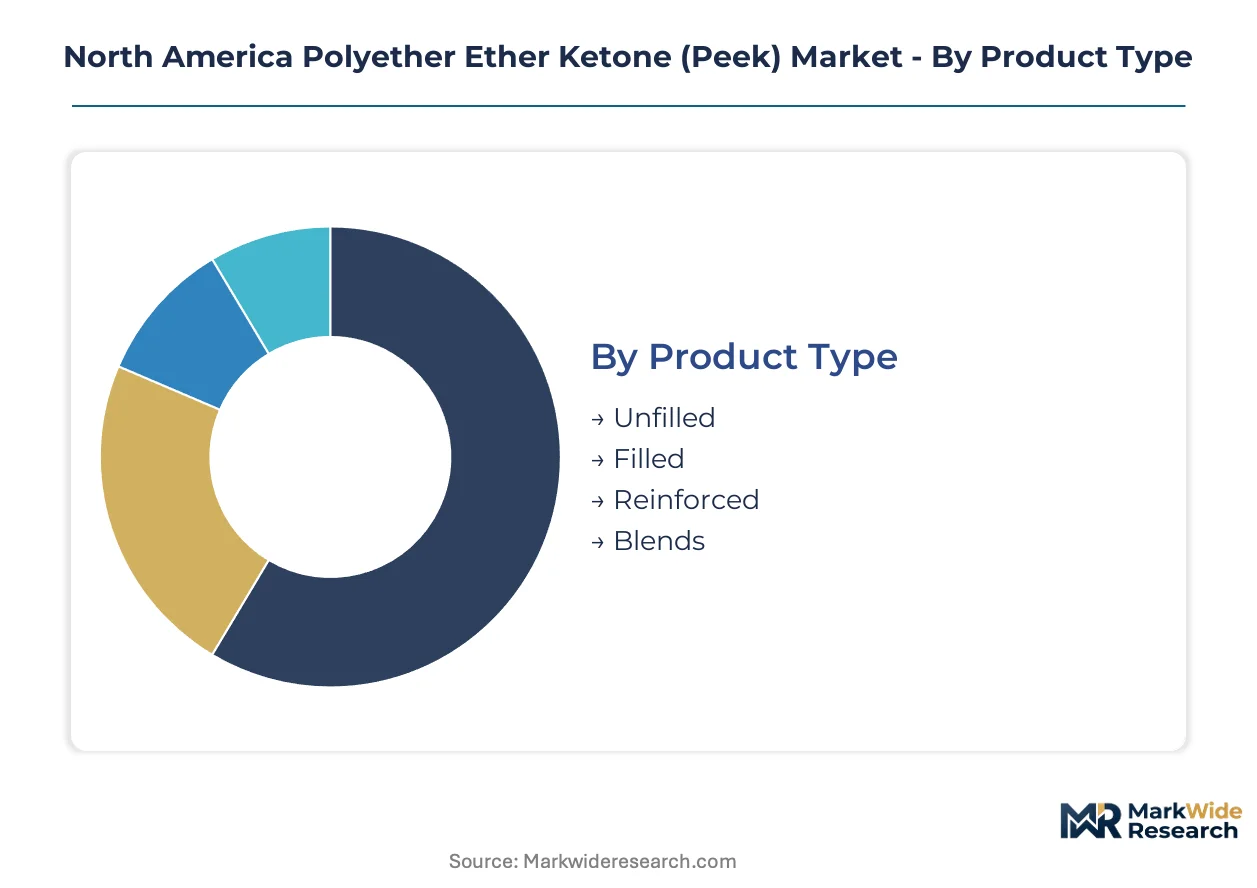
PEEK grade selection dictates processing complexity, regulatory qualification burden, and aftermarket technical support intensity. Compounders structure service contracts around crystallinity control requirements and FDA submission support, creating tiered engagement models that mirror material performance tiers.
Product Type:
After-sales service intensity escalates sharply with filler loading and reinforcement complexity, as crystallization kinetics become harder to control and part-to-part consistency demands rise.
- Unfilled:Virgin resin maintains the simplest processing window with melt temperatures near 360°C and straightforward crystallinity management. Automotive thermal management components in the Great Lakes belt pull unfilled grades for battery enclosure brackets where dimensional stability must coexist with cost discipline.
- Reinforced:Carbon-fiber and glass-fiber loadings between 30-40% demand precision temperature control across mold cooling phases to prevent fiber orientation defects and warpage. Aerospace OEMs in Wichita and Seattle specify reinforced grades for primary structural brackets where NADCAP certification requires extensive batch traceability and technical field support.
- Filled:Mineral and PTFE fillers modify friction and wear properties for bearing surfaces and pump components. Medical device molders in Massachusetts and Minnesota favor filled grades for spinal implant trials requiring radiopacity tuning.
- Blends:PEEK-PEI and PEEK-PPS alloys target price-performance gaps in connector housings and semiconductor wafer carriers. Electronics fabricators in Texas and Arizona specify blends where pure PEEK thermal properties exceed requirements.
Reinforced grades hold the largest share; momentum sits with unfilled grades as EV thermal management specifications proliferate.
End User:
Cost tier segmentation separates qualification-intensive medical and aerospace applications from price-sensitive automotive and electronics volumes.
- Medical Devices:Spinal implants, orthopedic instruments, and trauma fixation devices demand ISO 10993 biocompatibility validation and FDA 510(k) submission support. The Midwest hospital procurement consolidation around Premier and Vizient GPOs is concentrating demand among compounders offering complete supply chain documentation.
- Aerospace:Commercial airframe brackets, fasteners, and ducting require NADCAP-accredited processing and FAA airworthiness directive compliance. Boeing and Gulfstream procurement teams are expanding PEEK specifications for next-generation narrowbody and business jet platforms.
- Automotive:Throttle bodies, transmission components, and water pump housings compete with high-performance polyamides on cost. Ford and Stellantis lightweighting mandates under EPA fleet standards are pulling PEEK into under-hood applications previously metal-dominated.
- Electronics:Connector bodies, wafer handling hardware, and test socket applications prioritize dimensional stability and outgassing control. CHIPS Act fabrication investments in Arizona and Texas are expanding semiconductor-grade resin demand.
Medical devices hold the largest share; aerospace is climbing the fastest as primary structural qualifications advance.
Form:
Volume concentration versus margin capture divides the form landscape, with bulk pellets driving tonnage and precision rod stock commanding premium positioning.
- Pellets:Standard injection molding feedstock dominates volume flows to automotive and electronics molders. Gulf Coast petrochemical corridor distributors maintain pellet inventories for just-in-time delivery to Texas and Louisiana processors.
- Rods:Extruded bar stock for precision machining carries disproportionate margin contribution in medical and aerospace job shops. Swiss-type lathe houses in Connecticut and California prefer rod formats for spinal implant and bracket production.
- Powder:Compression molding and additive manufacturing feedstock serves semiconductor wafer carriers and patient-specific spinal cages. Laser sintering service bureaus in Ohio and North Carolina are expanding powder consumption.
- Sheets:Compression-molded plate stock targets chemical processing equipment and analytical instrument housings. Lab equipment fabricators in New Jersey and Pennsylvania specify sheet formats for chamber components.
Pellets hold the largest share; powder is gaining share fastest as additive manufacturing qualifications mature.
Application:
Customer type segmentation separates OEM direct specifications from tier supplier conversions, with structural applications demanding deeper technical integration.
- Structural Components:Load-bearing brackets, battery enclosures, and implantable devices require finite element analysis support and failure mode validation. EV battery pack designers specify structural PEEK for thermal runaway containment.
- Aerospace Parts:Wing ribs, floor beams, and ducting represent the migration from metal replacement to primary structure. Bombardier and Embraer programs are qualifying braided sleeve formats for regional jet applications.
- Seals:Oil and gas downhole packers, semiconductor chamber gaskets, and automotive transmission seals exploit chemical resistance and creep resistance. Permian Basin drilling operations specify PEEK seals for high-pressure high-temperature environments.
- Insulation:Wire coatings, motor slot liners, and connector housings leverage dielectric stability across temperature extremes. EV motor manufacturers specify PEEK insulation for 800V architectures.
Structural components hold the largest share; aerospace parts show the steepest expansion trajectory as primary load-bearing qualifications advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA airworthiness directives and FDA biocompatibility frameworks anchor demand concentration across the continent. The United States dominates volume flows through aerospace corridors and medical device clusters. Mexico and Canada occupy specialized positions in compounding and distribution.
United States
Boeing and Gulfstream procurement teams are expanding PEEK specifications for next-generation airframes under updated FAA polymer matrix composite standards. EPA Clean Air Act enforcement tightens fleet fuel economy mandates, pulling PEEK into Ford and Stellantis EV battery enclosures. The Great Lakes automotive belt and Wichita aerospace corridor concentrate specification activity.
Mexico
Orthopedic manufacturing expansion in Querétaro and Tijuana maquiladoras is narrowing the national compounding deficit through new extrusion investments. COFEPRIS medical device registration alignment with FDA 21 CFR frameworks accelerates resin qualification timelines. The Bajío Region and Northern Border States anchor captive supply partnerships for spinal implant production.
Canada
Bombardier regional jet programs are qualifying braided sleeve PEEK formats for primary wing rib applications under Transport Canada airworthiness oversight. Health Canada medical device licensing requirements parallel FDA biocompatibility validation for spinal implant suppliers. The Quebec aerospace cluster and Ontario medical device corridor concentrate demand.
North America Polyether Ether Ketone (Peek) Market Competitive Landscape
Integrated resin producers and specialized compounders split the market between captive polymerization assets and toll compounding services. Three archetypes dominate: European-headquartered polymerization specialists with North American distribution hubs, regional compounders serving FDA-registered medical device molders, and diversified chemical conglomerates leveraging high-purity formulations for semiconductor fabrication. Competitive moves center on CHIPS Act-aligned capacity expansion and medical-grade supply chain traceability investments.
Within the polymerization-specialist tier, Victrex PLC exemplifies the European-origin, hub-and-spoke distribution model through its Texas logistics presence. Syensqo and Evonik Industries AG occupy positions emphasizing medical-grade and high-purity semiconductor-grade resin archetypes respectively. These three anchors represent distinct competitive vectors: continental distribution scale, healthcare regulatory depth, and electronics fabrication purity standards.
| Leading Market Players |
|---|
| Victrex PLC |
| Syensqo |
| Evonik Industries AG |
| SABIC |
| Celanese Corporation |
| Solvay SA |
| RTP Company |
| Ensinger |
| Ferguson PLC |
| Others |
Pricing and Supply Chain Analysis
European specialty chemical producers concentrate 4,4'-difluorobenzophenone supply, anchoring margin pools in medical-grade compounding and aerospace qualification services downstream. Currency volatility and energy cost swings in feedstock regions transmit directly to North American compounder margins, privileging integrated resin producers with captive polymerization assets.
Pricing Analysis
Geographic price spreads between U.S. Gulf Coast petrochemical distributors and Midwest medical device molders reflect logistics premiums and FDA submission support bundling. Three-tier pricing structure across medical-grade, aerospace-certified, and industrial-standard resin levels dominates, with differentiation driven by batch traceability depth and NADCAP accreditation status. Cost compression in automotive unfilled grades is intensifying because PA46 and PPA substitution threats from DSM and DuPont squeeze specification margins. Tier suppliers in the Great Lakes belt exhibit highest price sensitivity; spinal implant OEMs under Premier and Vizient GPO contracts show lowest sensitivity due to biocompatibility lock-in.
Supply Chain Analysis
Extended payment terms from Boeing and Gulfstream procurement teams cascade through tier suppliers, compressing working capital for regional compounders without balance-sheet depth. Feedstock dependence draws from Germany, Belgium, and the United Kingdom for difluorobenzophenone monomer; compounding capacity concentrates in Texas, Massachusetts, and Minnesota. Single-source vulnerability in European monomer supply creates tariff exposure risk under transatlantic trade friction scenarios. Distribution runs through hub-and-spoke logistics anchored by Texas inventory positions serving just-in-time aerospace and medical device corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as high-performance polyamides from DSM and DuPont capture price-sensitive automotive connector applications previously PEEK-specified.
For Market Incumbents: Entrench medical-grade supply chain traceability investments to defend against emerging Asian resin producers seeking FDA 510(k) pathway entry. Deepen backward integration into difluorobenzophenone feedstock through European tolling partnerships or captive supply agreements, insulating margin pools from energy cost volatility in monomer production regions. For New Entrants and Emerging Players: Build out additive manufacturing powder capabilities in Ohio and North Carolina service bureau clusters, the most penetrable white-space as laser sintering qualifications mature for patient-specific spinal cages. Target semiconductor fabrication equipment segments under CHIPS Act capacity expansion in Arizona and Texas, leveraging high-purity formulation requirements as entry wedge against established medical-grade incumbents. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across medical-grade resin production as FDA long-term implantable guidance demands 10-year biocompatibility data infrastructure. Acquisition candidates with NADCAP-accredited processing and existing FDA master files offer strongest 5-10 year viability positioning. Monitor FAA airworthiness directive finalization timelines as inflection signal for aerospace specification acceleration or qualification freeze.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock | Secures difluorobenzophenone supply against European energy cost volatility. |
| Medical-Grade Capacity Expansion | Captures spinal implant demand under Premier and Vizient GPO consolidation. |
| Additive Manufacturing Powder Qualification | Opens patient-specific orthopedic applications without machining waste. |
| Semiconductor-Grade Purity Investment | Aligns with CHIPS Act wafer handling component demand in Arizona fabs. |
| NADCAP Accreditation Pursuit | Enables primary structural bracket supply to Bombardier and Embraer programs. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EPA Clean Air Act enforcement records, and aerospace procurement databases. Interviews with polymerization plant managers, medical device procurement leads at Premier-affiliated hospital networks, distribution channel partners in the Gulf Coast corridor, and NADCAP-accredited processing technical directors inform demand calibration. SEC 10-K disclosures from European resin producers and U.S. customs trade data provide supply-side validation. Bottom-up grade-by-grade volume builds triangulate against top-down end-use industry consumption estimates.
Forecast inputs include unfilled, reinforced, filled, and blend grade trajectories; medical device, aerospace, automotive, and electronics end-use splits; pellet, rod, powder, and sheet form factors; and structural component, aerospace part, seal, and insulation applications across the analysis window. CAGRs derive from segment-level elasticity modeling against FAA airworthiness directive implementation pace, EPA fleet standard enforcement intensity, and CHIPS Act fabrication capacity buildout schedules.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Asian resin producers or accelerated PA46 substitution in automotive thermal management would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Flexible Bio-Foams Market
Advanced Materials
APAC Advanced Building Materials Market
Advanced Materials
Rigid Foam Market
Advanced Materials
Cathode Materials Market
Advanced Materials
Long-Range Ordered Porous Carbon (LOPC) Market
Advanced Materials
Liquid Thermal Interface Materials Market
Advanced Materials
Superconducting Materials Market
Advanced Materials
Vacuum Insulation Panels Market
Advanced Materials
Hexagonal Boron Nitride (HBN) Market
Advanced Materials
Si-C Anode Material Market
Advanced Materials
Artificial Marble Products Market
Advanced Materials
Europe Next Generation Anode Materials Market
Advanced Materials
High-Purity Amorphous Boron Market
Advanced Materials
Nomex Honeycomb Market
Advanced Materials
Global Graphene Market
Advanced Materials
Cold Plasma Market