
 Canada Anti-Caking Market | 2026-2036
Canada Anti-Caking Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Anti-Caking Market Outlook
Health Canada's evolving Food and Drug Regulations is realigning the cost-of-entry calculus for anti-caking suppliers seeking food-grade certification. Cargill Inc. leverages its integrated agricultural supply chain to dominate bulk sodium bicarbonate distribution across Canadian food processors. BASF competes through specialized silicon dioxide formulations engineered for pharmaceutical tableting applications. Huber Engineered Materials anchors its position in industrial-grade calcium silicate for road salt and fertilizer treatments.
Anti-caking agents are hygroscopic or hydrophobic compounds, typically manufactured through precipitation, thermal decomposition, or surface-modification processes, that prevent particle agglomeration in powdered and granular materials. These additives maintain flowability, dosing accuracy, and shelf stability across formulations ranging from table salt to vitamin premixes. Silicon dioxide and calcium silicate variants command premium positioning in pharmaceutical and high-purity food applications where Health Canada purity standards are most stringent. The powder form leads volume across all application categories, though granule and pellet formats are gaining traction in automated agricultural blending systems where dust control and precise metering drive procurement decisions.
Health Canada, the Canadian Food Inspection Agency, and the Pest Management Regulatory Agency collectively govern anti-caking agent approval, residue limits, and labeling requirements across food, pharmaceutical, and agricultural end uses. PMRA registration requirements for fertilizer-grade additives create distinct compliance pathways that separate agricultural suppliers from food-grade specialists. Stakeholders must monitor pending amendments to the Food and Drug Regulations that could tighten heavy metal thresholds and force reformulation investments across the supplier base.
Market Dynamics
Health Canada's tightening purity thresholds for food-grade anti-caking agents are forcing suppliers to rebuild qualification protocols from raw material sourcing through finished product testing, compressing margins for non-integrated distributors.
Growth Catalysts
- Prairie fertilizer demand:Saskatchewan and Alberta agricultural cooperatives are scaling automated blending systems that require dust-controlled granule formats, pulling silicon dioxide and calcium silicate volumes upward.
- Processed food expansion:Ontario and Quebec seasoning manufacturers face shelf-stability mandates from major retail chains, mandating anti-caking incorporation in spice blends and dairy powders.
- PMRA registration pathways:The Pest Management Regulatory Agency's distinct fertilizer-grade approval process creates captive demand from agricultural suppliers seeking compliant salt and nutrient treatments.
Market Restraints
- Sodium bicarbonate input volatility:Soda ash price swings and energy-intensive Solvay process costs transmit directly to food-grade sodium bicarbonate margins, squeezing mid-tier distributors.
- Silicon dioxide supply concentration:High-purity precipitated silica for pharmaceutical tableting depends on concentrated North American production, exposing buyers to allocation risk during capacity constraints.
- Heavy metal threshold friction:Pending Food and Drug Regulations amendments threaten to disqualify legacy calcium silicate sources, forcing costly reformulation or supplier switches.
Strategic Opportunities
- Atlantic Canada underpenetration:Nova Scotia and New Brunswick food processing clusters show minimal anti-caking agent sourcing sophistication, presenting first-mover positioning for technical sales specialists.
- Clean-label convergence:Natural anti-caking alternatives derived from rice hull ash or plant cellulose intersect with Health Canada organic certification rules, opening premium positioning in natural channel distribution.
- Direct-to-cooperative distribution:Prairie agricultural cooperatives are consolidating procurement through shared service entities, creating channel bypass opportunities for qualified bulk suppliers.
Industry Challenges
- Analytical chemistry skill scarcity:Health Canada-mandated heavy metal testing and purity verification require ICP-MS and XRF competency that smaller distributors struggle to staff internally.
- Dual-grade certification timelines:Suppliers seeking simultaneous food-grade and fertilizer-grade approvals face PMRA and Canadian Food Inspection Agency review queues that extend commercialization timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Anti-Caking Market |
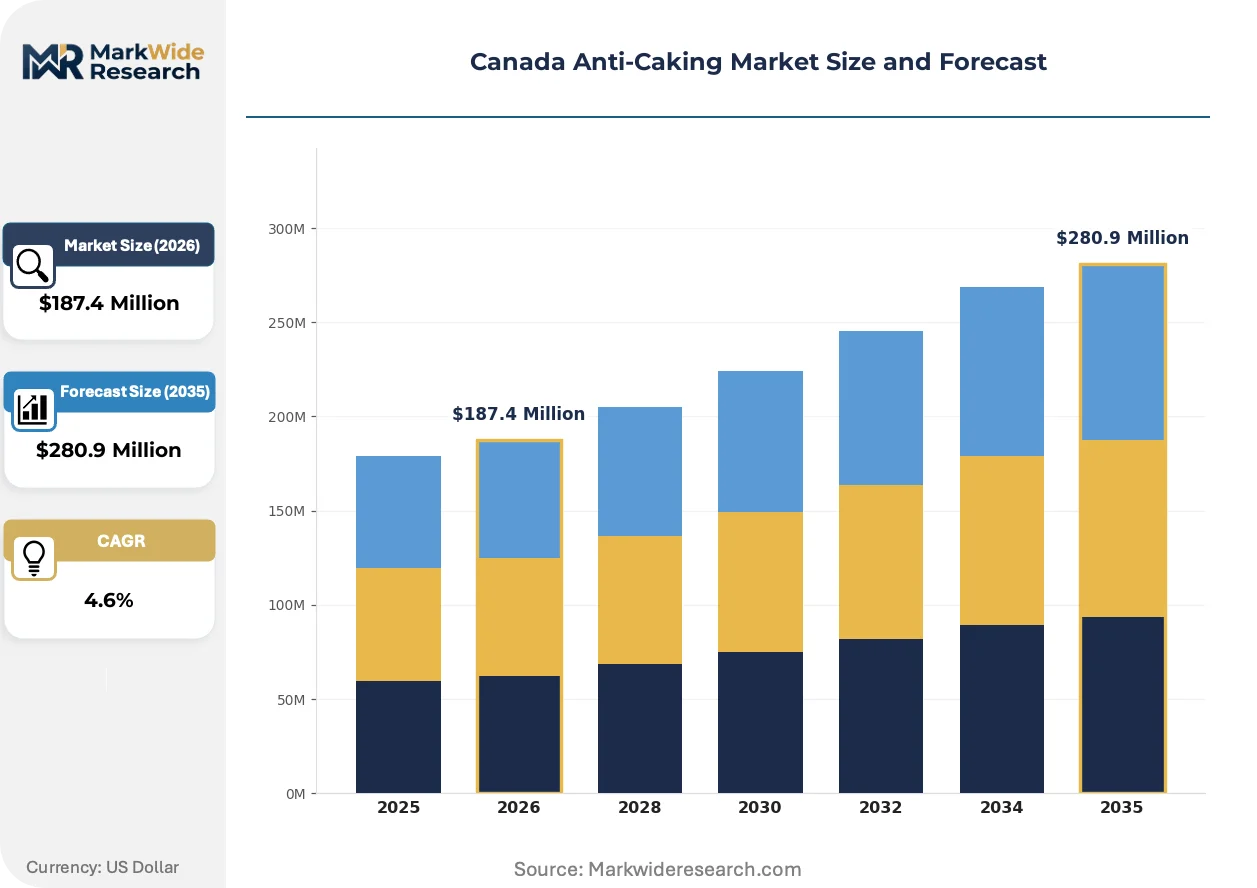
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $280.9 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Bicarbonate, Calcium Silicate, Magnesium Carbonate, Silicon Dioxide Application: Food & Beverage, Pharmaceuticals, Cosmetics, Agriculture Form: Powder, Granules, Pellets, Liquid End User: Food Manufacturers, Drug Manufacturers, Cosmetic Companies, Agricultural Firms |
| Companies Covered | Cargill Inc., Corbion Purac, BASF, IMAC Inc., ABITEC Association, Agropur Ingredients, Huber Engineered Materials, PQ Corporation, Univar Solutions, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Anti-Caking Market Strategic Shifts
Surface-modified anti-caking technologies are displacing conventional precipitated formulations across high-value pharmaceutical and premium food segments, compressing the viable shelf for unmodified commodity grades.
Engineered silicon dioxide with controlled particle size distribution and hydrophobic surface treatment is consolidating market share in pharmaceutical tableting applications. Contract manufacturers serving Toronto and Montreal generic drug producers are specifying these grades exclusively to meet Health Canada dissolution and content uniformity requirements. The technology is consolidating supplier tiers by collapsing the price premium between food-grade and pharmaceutical-grade specifications.
Health Canada's pending Food and Drug Regulations amendments targeting heavy metal thresholds in food additives are compressing the qualified supplier base for calcium silicate and natural zeolite variants. Manufacturers in Ontario and Quebec are pre-emptively auditing raw material provenance to avoid disqualification. The regulatory shift most acutely affects imported mineral sources, driving domestic toll processing investments.
Consolidated procurement through Prairie agricultural cooperative buying groups is compressing distributor margins while expanding volume commitments for qualified suppliers. Saskatchewan and Alberta fertilizer blenders now specify granule format, dust suppression, and automated metering compatibility as bundled requirements. This behavioral shift favors suppliers with in-house compaction and surface-coating capabilities over commodity traders.
Canada Anti-Caking Market Segmentation
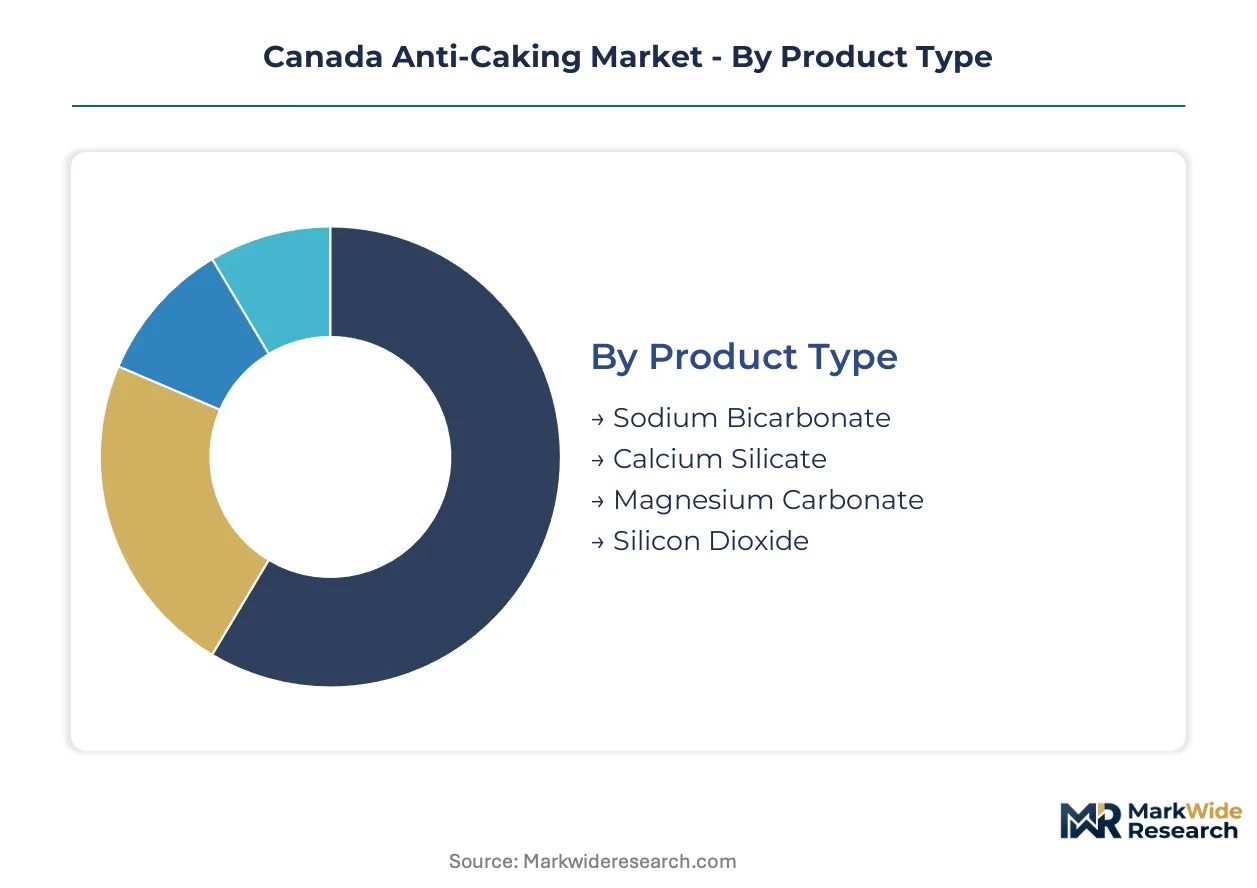
Anti-caking agent procurement in Canada fragments across four distinct category hierarchies, each carrying divergent certification burdens and margin profiles. Buyers navigate trade-offs between Health Canada food-grade purity standards, PMRA fertilizer-grade registrations, and pharmaceutical dissolution specifications when selecting product formats and supplier tiers.
Product Type:
Procurement decisions pivot on end-use certification requirements and raw material input volatility.
- Sodium Bicarbonate:Manufactured through the Solvay process using soda ash and carbon dioxide, this hygroscopic salt absorbs moisture to prevent clumping in powdered formulations. Food manufacturers across Ontario and Quebec specify this grade for seasoning blends and dairy powders, though energy-intensive production transmits margin pressure during natural gas price spikes.
- Silicon Dioxide:Precipitated and surface-modified variants with controlled particle size distribution deliver hydrophobic performance for pharmaceutical tableting. Toronto and Montreal contract manufacturers specify these grades exclusively to meet Health Canada content uniformity mandates, consolidating supplier tiers through technical qualification barriers.
- Calcium Silicate:Porous mineral absorbent derived from diatomaceous earth or synthetic precipitation, favored for road salt and fertilizer treatments in Prairie provinces.
- Magnesium Carbonate:Light, fluffy powder with high oil absorption capacity, specified in cosmetic formulations and select food applications requiring neutral taste profiles.
Volume sits with sodium bicarbonate across food processing; growth tilts toward silicon dioxide as pharmaceutical contract manufacturing expands.
Application:
Regulatory jurisdiction determines supplier qualification pathways and testing protocol investments.
- Food & Beverage:Seasoning manufacturers and dairy powder processors incorporate anti-caking agents to maintain flowability through distribution cycles. Health Canada's Food and Drug Regulations mandate heavy metal thresholds that disqualify legacy mineral sources, forcing Ontario and Quebec formulators toward audited supply chains.
- Pharmaceuticals:Tablet compression and capsule filling operations require excipients meeting Health Canada dissolution and content uniformity standards. Surface-modified silicon dioxide with specified particle morphology dominates this segment as generic drug producers in Toronto and Montreal consolidate procurement.
- Cosmetics:Face powders and mineral makeup formulations utilize oil-absorbing grades to prevent caking during consumer use.
- Agriculture:Fertilizer blending and road salt treatment applications pull industrial-grade calcium silicate volumes, with Saskatchewan and Alberta cooperatives driving dust-controlled format specifications.
Revenue concentrates in food and pharmaceutical applications; agricultural volumes are expanding most quickly through Prairie cooperative consolidation.
Form:
Material handling requirements and automation compatibility shape format selection across end-use segments.
- Powder:Fine particulate with maximum surface area for moisture absorption, dominant across food and pharmaceutical formulations where dosing precision and rapid dissolution matter.
- Granules:Compacted particles with controlled dust suppression, specified by Saskatchewan and Alberta fertilizer cooperatives for automated blending systems where precise metering and worker safety converge.
- Pellets:Dense, spherical agglomerates designed for slow-release agricultural applications and bulk handling efficiency.
- Liquid:Suspension or solution formats for specialized coating applications and continuous processing lines.
Powder commands installed base across food and drug manufacturing; granules are climbing the fastest through agricultural automation adoption.
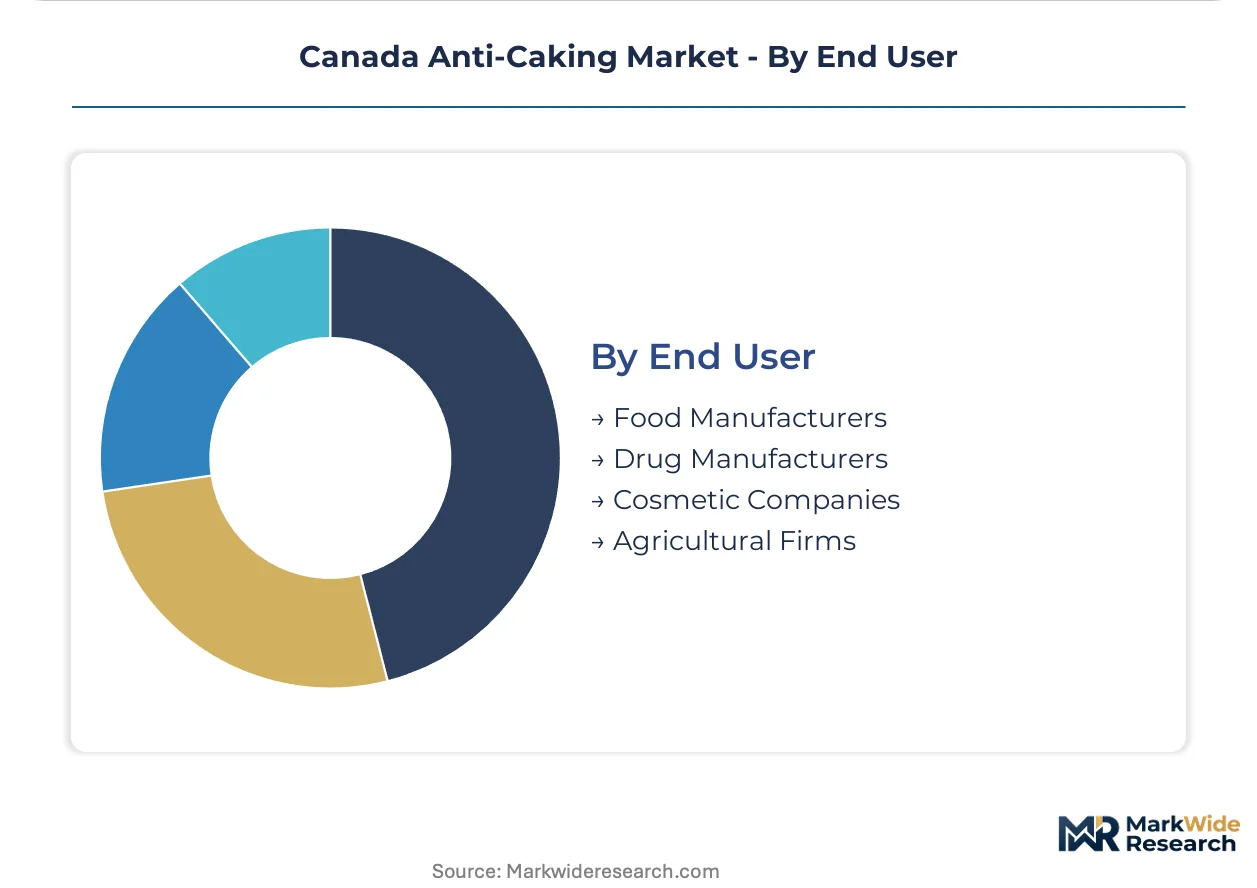
End User:
Scale and integration level determine whether buyers source through distributors or direct from manufacturers.
- Food Manufacturers:Seasoning blenders and dairy powder processors in Ontario and Quebec face retail chain shelf-stability mandates that mandate anti-caking incorporation, with mid-tier operators struggling to staff ICP-MS and XRF competency for Health Canada compliance.
- Drug Manufacturers:Toronto and Montreal generic drug producers specify pharmaceutical-grade silicon dioxide exclusively, collapsing price premiums between food-grade and pharmaceutical specifications through consolidated contract manufacturing procurement.
- Cosmetic Companies:Formulators of mineral makeup and powder products prioritize sensory performance and label positioning over regulatory burden.
- Agricultural Firms:Prairie cooperatives consolidate procurement through shared service entities, creating channel bypass opportunities for qualified bulk suppliers with in-house compaction capabilities.
Food manufacturers anchor volume demand; agricultural firms are gaining share fastest through cooperative buying group expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ontario's Accelerated Investment Incentive and Quebec's Investissement Québec tax credits concentrate food-grade anti-caking procurement in Central Canada. Provincial fertilizer programs and prairie agricultural automation drive divergent demand patterns across sub-regions.
Ontario
Seasoning manufacturers and dairy powder processors in the Golden Horseshoe anchor food-grade sodium bicarbonate consumption. Health Canada's Food and Drug Regulations heavy metal thresholds force Toronto-area formulators toward audited mineral supply chains. Mississauga and Brampton distribution clusters now require ICP-MS competency from qualified suppliers.
Quebec
Montreal's generic pharmaceutical contract manufacturers specify surface-modified silicon dioxide for tablet compression operations. Investissement Québec funding for clean-label ingredient processing accelerates natural anti-caking pilot projects. Quebec City's emerging natural products cluster intersects with Health Canada organic certification rules.
Alberta
Fertilizer cooperatives in the Red Deer corridor scale automated blending systems requiring dust-controlled calcium silicate granules. The province's Carbon Capture Utilization and Storage investment framework indirectly shapes energy-intensive anti-caking production economics. Calgary-based agricultural procurement consortia consolidate volumes through shared service entities.
Saskatchewan
Potash fertilizer blenders in the Saskatoon-Regina corridor drive industrial-grade silicon dioxide specifications for automated metering compatibility. Provincial nutrient management regulations under PMRA jurisdiction create captive demand for registered fertilizer-grade additives. Rural cooperative buying groups now bundle format, dust suppression, and delivery requirements.
Atlantic Canada
Nova Scotia and New Brunswick food processing clusters show minimal anti-caking sourcing sophistication relative to Central Canada. Provincial economic development incentives for agri-food manufacturing attract secondary processing investment. Halifax distribution infrastructure offers first-mover positioning for technical sales specialists targeting underpenetrated accounts.
Canada Anti-Caking Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across certification tiers, creating a bifurcated supplier structure. Food-grade purity requirements and PMRA registration pathways split the vendor base into integrated manufacturers and qualified distributors. Three archetypes dominate: agricultural supply chain integrators, pharmaceutical excipient specialists, and industrial mineral toll processors. Competitive moves center on backward integration into raw material sourcing and geographic expansion through cooperative procurement channels.
Within the agricultural supply chain tier, Cargill Inc. exemplifies integrated distribution leverage across prairie fertilizer cooperatives. BASF occupies a position among pharmaceutical-grade formulation specialists serving Toronto and Montreal contract manufacturers. Huber Engineered Materials anchors the industrial mineral processor archetype with compaction capabilities for road salt and fertilizer applications.
| Leading Market Players |
|---|
| Cargill Inc. |
| Corbion Purac |
| BASF |
| IMAC Inc. |
| ABITEC Association |
| Agropur Ingredients |
| Huber Engineered Materials |
| PQ Corporation |
| Univar Solutions |
| Others |
Value Chain & Pricing Dynamics
Prairie agricultural cooperative consolidation around bundled procurement specifications is forcing suppliers to absorb compaction and surface-coating investments, compressing margins for distributors without in-house processing capabilities. Health Canada's pending heavy metal threshold amendments are simultaneously disqualifying legacy mineral sources, creating tiered pricing separation between audited supply chains and commodity traders.
Pricing Analysis
Short lead-time premiums for pharmaceutical-grade silicon dioxide command substantial markups over standard food-grade sodium bicarbonate contracts, with Toronto and Montreal contract manufacturers paying expedited delivery rates to secure allocation during capacity constraints. Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial-grade certifications anchors differentiation, with purity verification and PMRA registration status as primary value drivers. Pricing pressure stems from energy-intensive Solvay process costs transmitting directly to sodium bicarbonate margins. Agricultural cooperatives exhibit highest price sensitivity through volume consolidation, while pharmaceutical buyers prioritize specification compliance over unit cost.
Supply Chain Analysis
Health Canada food-grade certification and PMRA fertilizer-grade registration create dual gating mechanisms that fragment supplier qualification pathways and extend commercialization timelines. High-purity precipitated silica production concentrates in the United States, with sodium bicarbonate sourcing anchored in domestic Solvay process facilities and select European imports. Raw material dependencies center on soda ash, diatomaceous earth, and specialized silicate precursors. Single-source vulnerability for pharmaceutical-grade silicon dioxide exposes buyers to allocation risk during North American capacity constraints. Distribution runs through integrated agricultural supply chains in Prairie provinces and qualified chemical distributors serving Ontario and Quebec processing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified supplier scarcity for dual-grade certification is propping pricing power among integrated manufacturers with captive analytical chemistry capabilities. Capacity bottlenecks in high-purity precipitated silica production are constraining pharmaceutical-grade availability.
For Market Incumbents: Lock in backward integration into diatomaceous earth and silicate raw material sourcing to secure supply against pending Health Canada heavy metal disqualifications. Expand compaction and surface-coating capacity in Saskatchewan and Alberta to capture Prairie cooperative procurement consolidation. Prioritize ICP-MS and XRF analytical competency investments to maintain certification eligibility as regulatory thresholds tighten. For New Entrants and Emerging Players: Direct-to-cooperative digital procurement platforms offer the lowest-friction entry path for qualified bulk suppliers seeking to bypass traditional distributor channels. Atlantic Canada food processing clusters present underpenetrated white-space with minimal incumbent technical sales presence. Clean-label natural alternatives derived from rice hull ash intersect with Health Canada organic certification rules, enabling premium positioning in Quebec's emerging natural products channel. For Investors and Strategic Acquirers: The window for entry favors industrial mineral toll processors with in-house compaction capabilities and existing PMRA registration pathways. Long-term viability hinges on supply chain control over audited raw material provenance and dual-grade certification infrastructure. Watch for Health Canada Food and Drug Regulations amendment finalization as the inflection signal triggering supplier base consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Material Sourcing | Captive diatomaceous earth supply secures qualification against Health Canada heavy metal thresholds. |
| Compaction and Surface-Coating Capacity Expansion | Granule format capability unlocks Prairie cooperative procurement consolidation in Saskatchewan and Alberta. |
| Analytical Chemistry Competency Investment | ICP-MS and XRF infrastructure maintains PMRA and Health Canada dual-grade certification eligibility. |
| Direct-to-Cooperative Distribution Channel | Bypass of traditional distributors captures margin from agricultural buying group consolidation. |
| Clean-Label Natural Alternative Development | Rice hull ash and plant cellulose formulations intersect with Health Canada organic certification rules. |
Study Parameters
Document review covered Health Canada Food and Drug Regulations amendments, PMRA registration databases, and Prairie agricultural cooperative procurement disclosures, complemented by interviews with food manufacturing procurement directors, pharmaceutical contract manufacturing executives, fertilizer blending plant managers, and chemical distribution channel specialists. Secondary validation drew from Canadian Food Inspection Agency guidance documents, customs trade data, and industry association technical specifications. Bottom-up volume modeling and top-down market sizing triangulated across segmentation dimensions.
Cross-referencing of historical procurement patterns against expert panel input anchored the analytical framework across the projection horizon. Segmentation modeling incorporated product type, application category, form specification, and end-user integration level. CAGRs were derived through regression analysis of volume trajectories and input cost elasticity. Forecast inputs included energy price sensitivity for Solvay process economics and regulatory timeline assumptions for Health Canada amendment implementation.
Inputs from Health Canada pre-market notification filings and PMRA registration databases were available through the study window; gaps in real-time cooperative procurement transaction data introduce uncertainty bands around Prairie volume allocations. Forecasts reflect documented assumptions regarding regulatory implementation timing and raw material cost transmission. A model refresh is warranted upon material change in Health Canada heavy metal threshold finalization or North American precipitated silica capacity additions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Ascorbyl Stearate Market
Additives
Global Isononanoic Acid Market
Additives
Performance Minerals Additives Market
Additives
Propyl Gallate Market
Additives
Europe Citric Acid Market
Additives
North America Phosphate Esters Market
Additives
Asia-Pacific Feed Acidifiers Market
Additives
Green Chelates/Natural Chelating Agents Market
Additives
Triazine UV Absorber Market
Additives
Printing Ink Additives Market
Additives
Nucleotide Premix Market
Additives
Lead Stearate Market
Additives
Metal Deactivators Market
Additives
Battery Additives Market
Additives
Tamarind Gum Derivatives Market
Additives
Global Anti-Fog Additives Market