
 Global Ester Gum Market | 2026-2036
Global Ester Gum Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ester Gum Market Analysis
Advanced glycerol esterification and hydrogenation techniques are reshaping how rosin-derived resins achieve color stability and low odor profiles for premium applications. Eastman Chemical Company leverages integrated terpene resin operations to sustain supply security across adhesive and chewing gum base markets. Arakawa Chemical Industries anchors its position through specialized hydrogenated rosin ester production serving Japanese and Southeast Asian customers. Kraton Corporation differentiates via controlled molecular architecture in tackifier resins that compete directly with conventional ester gum in pressure-sensitive adhesives.
Ester gum comprises glycerol or pentaerythritol esters of wood rosin or gum rosin, typically exhibiting acid values below 10 mg KOH/g and softening points ranging from 80°C to 120°C, functioning primarily as tackifiers, stabilizers, and film-forming agents across food, cosmetic, and industrial formulations. The rosin ester category dominates value generation owing to its entrenched use in chewing gum bases and beverage emulsions where FDA and JIS food-grade certifications command premium positioning. Synthetic alternatives are gaining fastest in paints and coatings as formulators seek batch-to-batch consistency unavailable in natural resin feeds. Hydrocarbon tackifiers remain structurally important in hot-melt adhesives though margin pools are compressing amid petrochemical feedstock volatility.
REACH registration requirements from ECHA govern rosin ester import volumes into Europe, while FDA food additive regulations under CFR 172.735 dictate permissible use levels in citrus-flavored beverages sold in the United States. China's SAMR enforces GB standards for food-grade resins that domestic producers such as Foshan Baolin Chemical Industry must meet to supply national beverage chains. Stakeholders should monitor how evolving biobased content mandates across multiple jurisdictions reshape sourcing strategies between pine-derived and petroleum-derived tackifier alternatives.
Market Dynamics
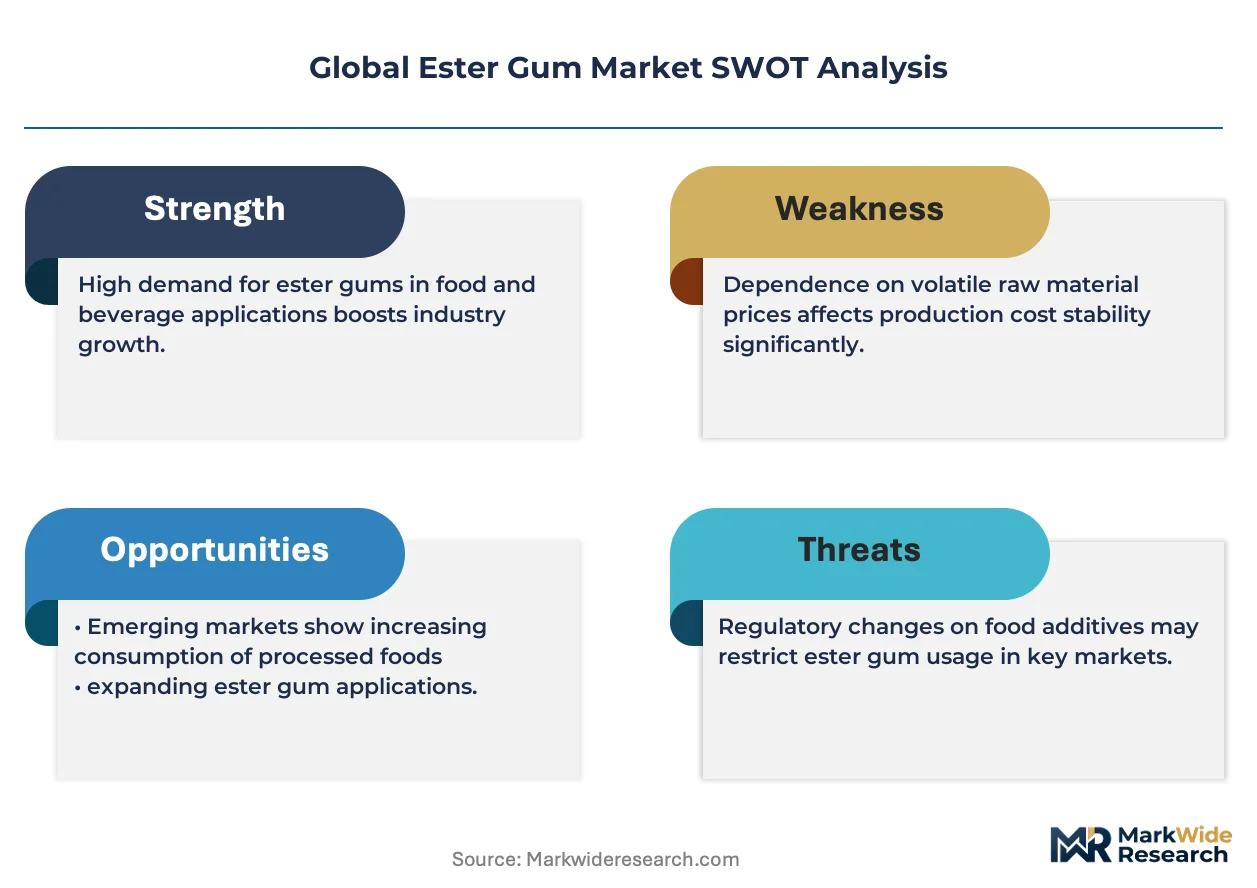
Food-grade certification requirements from FDA and JIS are compressing supplier margins while hydrogenated rosin ester production concentrates among integrated chemical manufacturers with captive pine resin supply chains.
Growth Catalysts
- Citrus Beverage Stabilization:Food and beverage manufacturers are expanding ester gum incorporation as a weighting agent in clouding emulsions for carbonated and still drinks, with FDA CFR 172.735 compliance enabling premium positioning in the United States.
- REACH Registration:ECHA compliance requirements are filtering out non-specialized traders, creating protected volume pools for registered European importers of hydrogenated rosin esters.
- Domestic Capacity Buildout:Chinese beverage production scaling is concentrating demand within domestic rosin ester supply chains, with SAMR GB standards enforcement favoring local producers such as Foshan Baolin Chemical Industry.
Market Restraints
- Pine Resin Feedstock Volatility:Gum rosin harvest fluctuations in China and Brazil create input cost instability that synthetic hydrocarbon tackifier producers exploit in adhesive contract negotiations.
- Batch-to-Batch Inconsistency:Natural resin color variation limits ester gum penetration into premium automotive coatings where synthetic alternatives guarantee reproducible viscosity profiles.
- Biobased Mandate Complexity:Divergent renewable content thresholds across EU Green Deal implementation, US IRA biobased procurement rules, and China's dual carbon goals fragment formulation strategies for multinational adhesive suppliers.
Strategic Opportunities
- Underpenetrated Southeast Asian Beverage Markets:Vietnamese and Indonesian citrus-flavored soft drink production growth outpaces local rosin ester supply, creating import substitution openings for Thai and Malaysian distributors.
- Cosmetic Film-Forming Applications:Hydrogenated rosin esters with acid values below 5 mg KOH/g are penetrating color cosmetic formulations as silicone alternatives, with JIS certification enabling premium pricing in Japanese skincare.
- Controlled Molecular Architecture:Styrenic block copolymer tackifiers are converging with selective hydrogenation to deliver odor-free, low-color pressure-sensitive adhesive performance that challenges conventional ester gum in medical tape applications.
Industry Challenges
- Specialized Hydrogenation Engineering Talent:The scarcity of process engineers experienced in selective rosin ester hydrogenation limits capacity expansion timelines for mid-scale producers.
- Multi-Jurisdiction Certification Timelines:Simultaneous FDA food additive petition review, ECHA REACH dossier updates, and SAMR GB standard compliance create 18-24 month product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ester Gum Market |
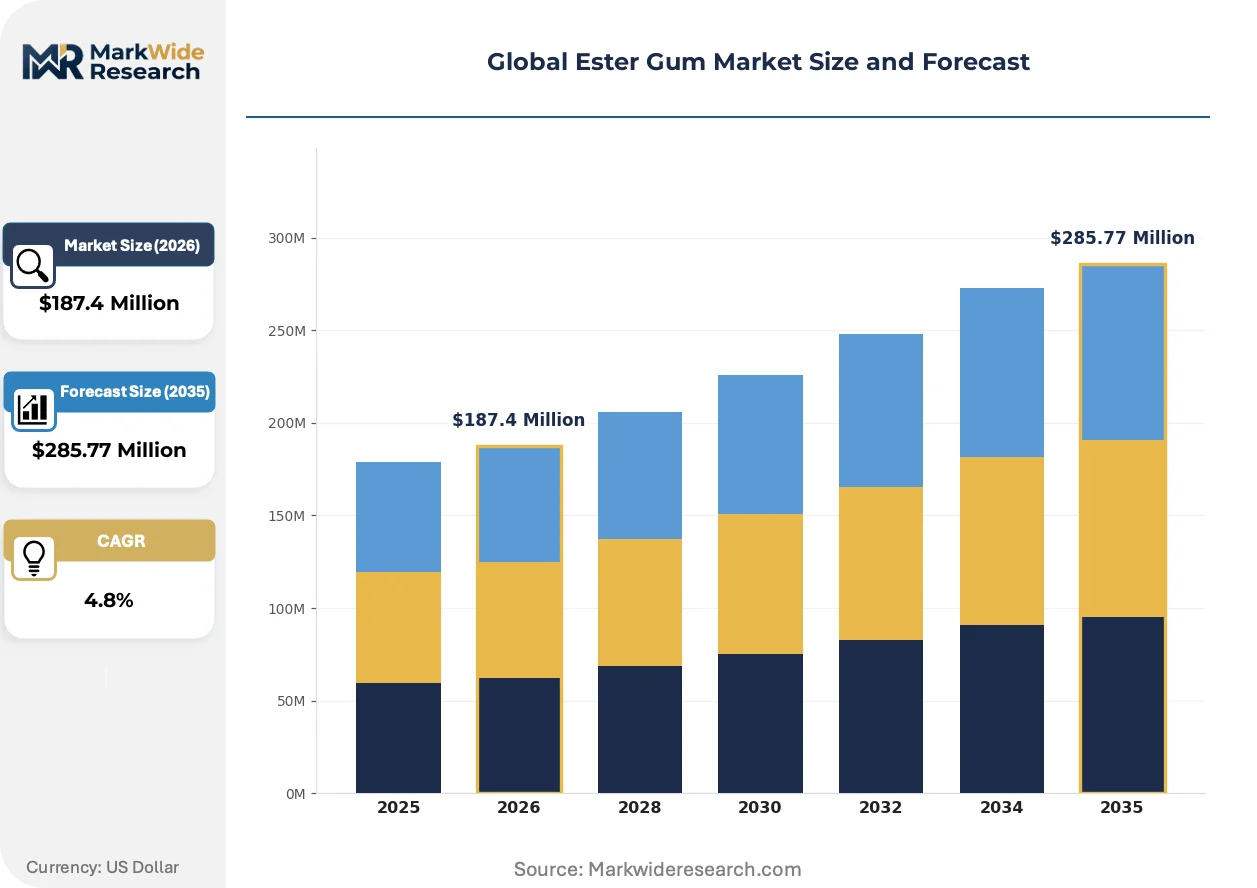
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrocarbon, Rosin Ester, Natural, Synthetic End Use Industry: Food & Beverage, Cosmetics, Adhesives, Paints Functionality: Thickening Agent, Stabilizer, Emulsifier, Binder Packaging Type: Bags, Drums, Bulk Containers, Cans |
| Companies Covered | Eastman Chemical Company, Arakawa Chemical Industries, dsm-firmenich, Kraton Corporation, Ingevity Corporation, DRT, Jubilant, Foshan Baolin Chemical Industry Co., Ltd, Shree Resins, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ester Gum Market Emerging Trajectories
Advanced glycerol esterification and selective hydrogenation are redefining performance benchmarks for rosin-derived resins across food-grade and industrial applications.
Hydrogenated rosin ester technology is migrating from conventional chewing gum base applications toward premium cosmetic film-formers and low-odor pressure-sensitive adhesives. Japanese and South Korean cosmetic formulators are adopting acid-value-controlled grades at accelerating rates. This migration is compressing market share for partially hydrogenated alternatives in segments where odor and color stability command price premiums.
REACH registration requirements from ECHA are tightening purity specifications for rosin ester imports into Europe. Industrial consequence includes accelerated consolidation among distributors unable to maintain dossier compliance costs. Adhesive compounders serving automotive and tape markets are responding by qualifying alternative tackifier chemistries or securing long-term supply agreements with registered European producers.
Buyer concentration among multinational beverage corporations is compressing supplier negotiation leverage and extending payment terms. Large citrus-flavored drink manufacturers are consolidating rosin ester procurement through integrated chemical distributors, displacing direct mill relationships. This pattern is most visible in China where domestic beverage chain expansion coincides with SAMR enforcement of centralized supplier qualification systems.
Global Ester Gum Market Segmentation
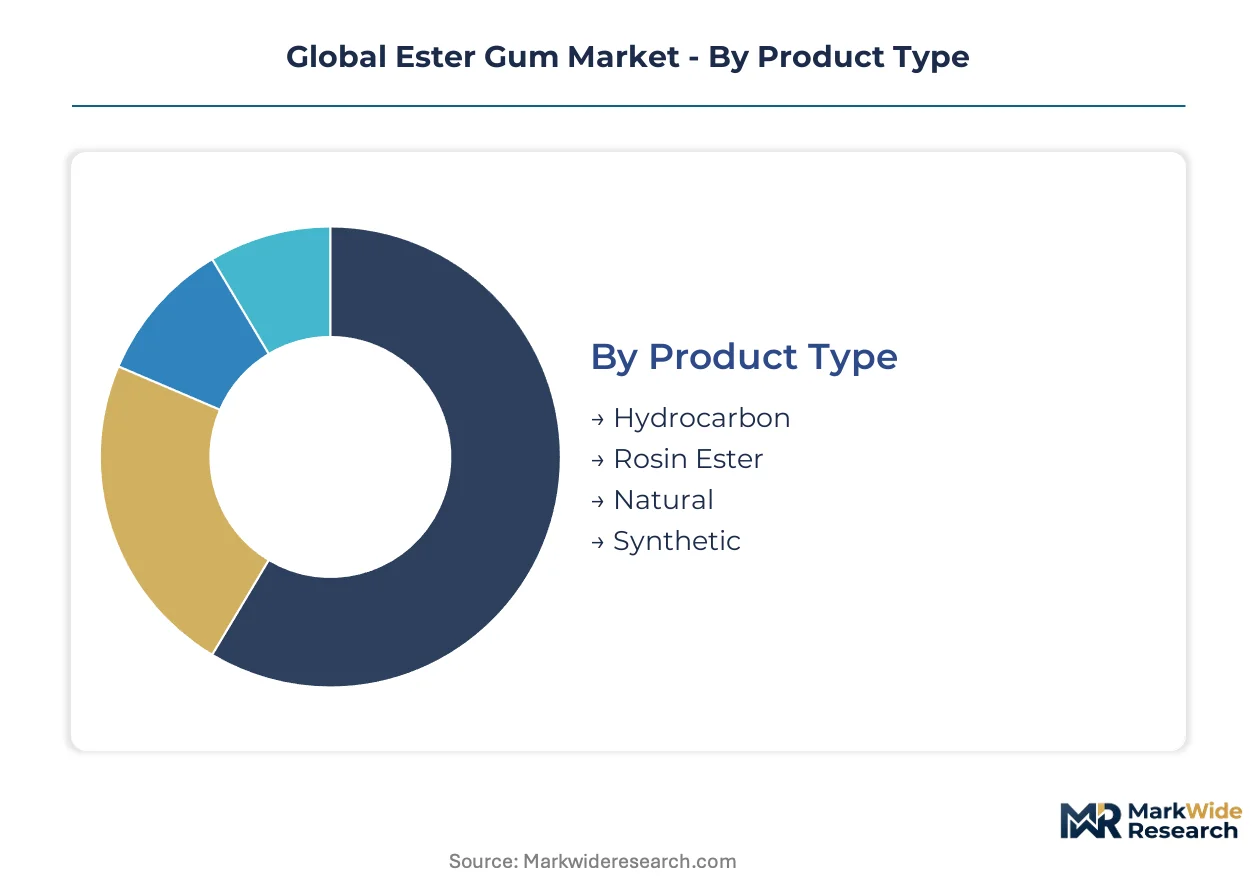
Ester gum market segmentation reveals how technical specifications, regulatory pathways, and supply chain configurations create distinct competitive arenas. Manufacturers configure production assets around certification tiers rather than geographic proximity alone.
Product Type:
Mature hydrogenated grades dominate premium positioning while emerging synthetic alternatives reshape cost-sensitive adhesive applications.
- Rosin Ester:Glycerol and pentaerythritol esters of wood or gum rosin with acid values below 10 mg KOH/g and softening points of 80°C to 120°C. Demand concentrates in chewing gum bases and citrus beverage emulsions where FDA CFR 172.735 and JIS food-grade certifications enable premium pricing in the United States and Japan.
- Hydrocarbon:Petroleum-derived tackifiers including aliphatic and aromatic resins with superior batch-to-batch consistency. Adhesive compounders in Germany and the United States favor these for automotive tape applications where natural resin color variation creates formulation risks.
- Natural:Unmodified gum rosin and wood rosin derivatives retaining higher acid values and characteristic odor profiles. Chinese rosin collectors supply domestic beverage stabilizer manufacturers meeting SAMR GB standards at lower cost points than hydrogenated alternatives.
- Synthetic:Styrenic block copolymer tackifiers and specialized petroleum resins engineered for controlled molecular architecture. South Korean and Japanese adhesive producers deploy these in medical-grade pressure-sensitive tapes where odor-free performance commands specification premiums.
Rosin ester retains volume leadership; synthetic alternatives hold the steepest expansion curve in industrial adhesive segments.
End Use Industry:
Application-driven cost tiers separate commodity stabilizer demand from premium film-forming specifications across consumer and industrial markets.
- Food & Beverage:Weighting agents and clouding emulsifiers in carbonated and still citrus-flavored drinks. FDA-compliant hydrogenated grades from Eastman Chemical and Arakawa Chemical anchor supply to multinational beverage corporations in the United States and Japan.
- Adhesives:Tackifiers for hot-melt and pressure-sensitive formulations in packaging, tape, and construction applications. German automotive suppliers and Chinese electronics manufacturers drive specification divergence between rosin esters and synthetic hydrocarbon alternatives.
- Cosmetics:Film-forming agents in color cosmetics and skincare replacing silicone derivatives. Japanese formulators specify acid values below 5 mg KOH/g for premium skincare, with JIS certification creating import barriers for non-compliant suppliers.
- Paints:Viscosity modifiers and gloss enhancers in industrial and decorative coatings. Brazilian and Indian paint producers favor natural rosin esters for cost-sensitive architectural applications despite batch color inconsistency limitations.
Food and beverage maintains revenue concentration; cosmetics demonstrates the most rapid specification upgrading toward pharmaceutical-grade purity.
Functionality:
Volume distribution across functional roles reflects how processing requirements and certification burdens concentrate margin capture among integrated manufacturers.
- Stabilizer:Density adjustment and suspension maintenance in citrus oil emulsions for carbonated beverages. SAMR enforcement of centralized supplier qualification in China has consolidated procurement through distributors serving domestic beverage chains.
- Thickening Agent:Viscosity building in cosmetic formulations and industrial adhesives. South Korean skincare brands specify hydrogenated rosin esters with controlled acid values to replace carbomer and silicone alternatives.
- Emulsifier:Oil-water interface stabilization in chewing gum bases and food-grade coatings. FDA petition requirements and ECHA REACH dossier compliance create 18-24 month barriers for new supplier entry.
- Binder:Film formation and substrate adhesion in paints, inks, and pressure-sensitive tapes. German and Japanese automotive tape manufacturers prioritize synthetic tackifiers for reproducible viscosity under temperature cycling.
Stabilizer functionality commands the largest volume position; thickening agent applications are climbing the fastest as cosmetic formulators seek biobased silicone replacements.
Packaging Type:
Customer scale and handling infrastructure determine packaging configuration, with bulk formats concentrating among integrated adhesive producers and drum specifications dominating food-grade distribution.
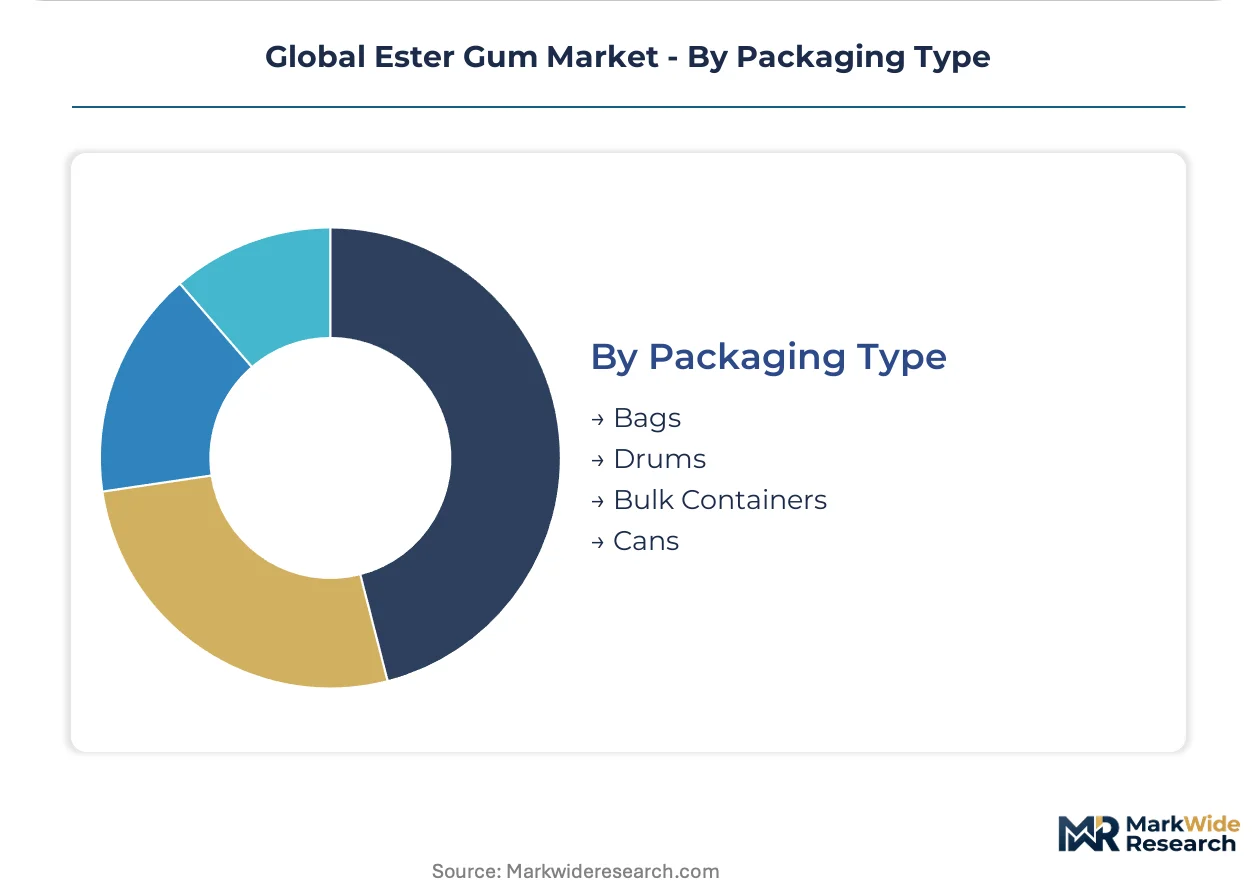
- Drums:Standard 200-liter steel and plastic containers for food-grade and cosmetic-grade ester gum. Japanese and European distributors favor drum packaging for REACH-registered hydrogenated rosin esters requiring batch traceability.
- Bulk Containers:Intermediate bulk containers and tanker deliveries for high-volume adhesive compounders. German hot-melt adhesive producers receive hydrocarbon tackifiers in bulk to minimize handling costs and contamination risk.
- Bags:Multi-layer paper and polymer bags for powdered or flaked natural rosin derivatives. Chinese domestic rosin ester producers supply SAMR-compliant grades to regional beverage manufacturers in 25-kilogram bag formats.
- Cans:Smaller metal and plastic containers for specialty cosmetic and laboratory quantities. South Korean cosmetic compounders procure JIS-certified hydrogenated grades in 5-20 liter cans to match formulation batch sizes.
Drum packaging retains the widest application coverage; bulk containers are gaining share fastest among vertically integrated adhesive manufacturers with dedicated unloading infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese rosin ester producers export hydrogenated grades to Japanese and Southeast Asian beverage manufacturers, establishing the dominant trade corridor in the Asia-Pacific region. This flow pattern concentrates procurement leverage among integrated chemical distributors serving multinational citrus drink brands.
United States
Carbonated beverage manufacturers in Georgia and Texas drive hydrogenated rosin ester consumption for clouding emulsions. FDA CFR 172.735 compliance requirements filter supplier qualification to registered importers with established food additive petition histories. Eastman Chemical's integrated operations in Tennessee anchor domestic supply security for chewing gum base and adhesive markets.
China
Domestic beverage production scaling in Guangdong and Zhejiang provinces concentrates rosin ester demand within local supply chains. SAMR enforcement of GB standards for food-grade resins favors producers such as Foshan Baolin Chemical Industry serving national drink chains. Gum rosin harvest fluctuations in Fujian and Guangxi create periodic feedstock cost instability.
Japan
Cosmetic formulators in Osaka and Tokyo specify acid values below 5 mg KOH/g for premium skincare film-formers. JIS certification requirements create import barriers for non-compliant hydrogenated rosin ester suppliers. Arakawa Chemical Industries anchors domestic production capacity serving Southeast Asian export markets.
Germany
Automotive tape manufacturers in Baden-Württemberg prioritize synthetic hydrocarbon tackifiers for reproducible viscosity under temperature cycling. ECHA REACH registration requirements filter non-specialized traders from rosin ester import channels. Adhesive compounders in Bavaria are qualifying alternative chemistries or securing long-term supply agreements with registered European producers.
Brazil
Paint producers in São Paulo favor natural rosin esters for cost-sensitive architectural applications despite batch color inconsistency. Gum rosin harvests in Minas Gerais and Paraná supply domestic beverage stabilizer manufacturers. ANVISA pharmaceutical-grade certification timelines extend product launch cycles for cosmetic-grade hydrogenated alternatives.
Global Ester Gum Market Vendor Landscape
On the supply side, the industry is consolidating around integrated chemical manufacturers with captive pine resin supply chains and specialized hydrogenation capabilities. Food-grade certification requirements from FDA and JIS compress margins while filtering out non-specialized distributors. Three archetypes dominate: integrated terpene resin operators, hydrogenation specialists, and synthetic tackifier producers. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure long-term feedstock agreements and multi-jurisdiction regulatory dossiers.
Within the integrated terpene resin tier, Eastman Chemical Company and Arakawa Chemical Industries exemplify supply security strategies across adhesive and food-grade markets. Kraton Corporation occupies a position among synthetic tackifier specialists competing via controlled molecular architecture. Chinese domestic capacity is represented by Foshan Baolin Chemical Industry Co., Ltd, which sits within the regional supplier archetype serving SAMR-compliant beverage chains.
| Leading Market Players |
|---|
| Eastman Chemical Company |
| Arakawa Chemical Industries |
| dsm-firmenich |
| Kraton Corporation |
| Ingevity Corporation |
| DRT |
| Jubilant |
| Foshan Baolin Chemical Industry Co., Ltd |
| Shree Resins |
| Others |
Supply Flow & Price Mechanics
Fujian province's gum rosin harvest volatility transmits directly into hydrogenated rosin ester pricing power, with downstream beverage manufacturers absorbing cost swings through long-term offtake contracts while adhesive compounders shift toward synthetic hydrocarbon alternatives.
Pricing Analysis
Conventional glycerol esterification versus selective hydrogenation versus next-generation controlled molecular architecture creates a three-tier pricing structure across premium, standard, and economy levels. FDA and JIS certification tiers command substantial premiums over SAMR-compliant domestic Chinese grades, with brand reputation and volume scale as secondary differentiation drivers. Cost compression in standard-grade rosin esters is intensifying because Brazilian gum rosin supply fluctuations destabilize input costs. Food and beverage manufacturers exhibit lowest price sensitivity due to regulatory lock-in, while paint producers in emerging markets demonstrate highest elasticity.
Supply Chain Analysis
Extended payment terms from multinational beverage corporations now stretch 90-120 days, forcing mid-scale producers toward supply-chain finance facilities or captive banking arrangements. China, Brazil, and Portugal concentrate gum rosin feedstock supply, with downstream hydrogenation capacity clustering in Tennessee, Osaka, and Guangdong. Pine resin harvests, glycerol purity grades, and palladium catalyst availability constitute critical input dependencies. Single-source vulnerability runs through Brazilian gum rosin collectors facing climate-induced yield variance. Distribution runs through integrated chemical distributors serving qualified supplier lists rather than direct mill relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized hydrogenation engineering talent scarcity constrains capacity expansion timelines, with selective rosin ester hydrogenation expertise concentrated among Japanese and US integrated chemical manufacturers.
For Market Incumbents: Insulate market position through backward integration into captive pine resin supply chains in Fujian and Minas Gerais, while accelerating JIS and FDA certification investments to defend against synthetic tackifier substitution in medical tape applications. Secure long-term offtake agreements with Southeast Asian beverage distributors before Thai and Malaysian competitors establish regional hydrogenation capacity. For New Entrants and Emerging Players: Vietnamese and Indonesian citrus-flavored soft drink production growth represents the most penetrable entry point, with local rosin ester supply deficits creating import substitution openings for REACH-registered European producers. Cosmetic film-forming applications in South Korean skincare offer secondary white-space, with acid-value-controlled grades below 5 mg KOH/g replacing silicone derivatives. A go-to-market angle anchored on JIS certification and 5-20 liter can packaging for formulation-scale procurement bypasses bulk-container infrastructure disadvantages. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated terpene resin operators with established regulatory dossiers over synthetic tackifier pure-plays facing biobased mandate complexity. Long-term viability over the analysis window rests on multi-jurisdiction certification assets and captive feedstock access rather than scale alone. The signal to watch is Chinese domestic beverage chain consolidation accelerating SAMR supplier qualification timelines and compressing distributor margins.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pine Resin Supply | Captive gum rosin access in Fujian and Paraná insulates margin volatility from harvest fluctuations. |
| Multi-Jurisdiction Certification Investment | Simultaneous FDA petition, REACH dossier, and JIS compliance creates 18-24 month competitive moats. |
| Long-term Supply Agreement with Beverage Distributors | Fixed-price offtake contracts with Thai and Malaysian distributors lock in Southeast Asian volume growth. |
| Capacity Expansion in Hydrogenated Grades | Acid-value-controlled production below 5 mg KOH/g captures cosmetic film-former specification upgrading. |
| Joint Venture with Regional Rosin Collectors | Partnerships with Brazilian cooperatives secure gum rosin priority allocation during harvest shortfalls. |
Methodological Framework
Desk research of customs/trade data, SEC 10-K filings, ECHA REACH registration databases, and SAMR GB standard disclosures preceded structured interviews with hydrogenation process engineers, beverage procurement directors, adhesive compounder technical leads, and cosmetic formulator R&D heads. Primary fieldwork across Tennessee, Osaka, Guangdong, and Baden-Württemberg validated secondary estimates through bottom-up capacity assessments and top-down demand reconciliation.
Base-case assumptions held pine resin harvest yields, regulatory certification timelines, and synthetic tackifier substitution rates within historical bands while varying beverage production scaling intensity and biobased mandate enforcement rigor across the projection horizon. Segmentation modeling incorporated product type tiers, end-use industry cost sensitivity, functionality specifications, and packaging format infrastructure requirements. CAGRs derived from production capacity buildout schedules, customer qualification pipeline visibility, and cross-elasticity estimates between rosin esters and hydrocarbon alternatives.
Macroeconomic conditions sit as an overlay; deviation in Brazilian real exchange rates, Chinese domestic consumption growth, or EU Green Deal implementation pace would shift the trajectory. Forecasts reflect documented assumptions regarding feedstock availability and regulatory stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Thallium Acetate Market
Additives
China Feed Additives Market
Additives
Extrusion Aids Market
Additives
Global Isosorbide Market
Additives
Tris Nonylphenyl Phosphite Market
Additives
Inorganic Filler Market
Additives
Viscosity Reducing Agents Market
Additives
United Kingdom Sodium Reduction Ingredient Market
Additives
South America Sodium Reduction Agents Market
Additives
Flux Injection System Market
Additives
United States Citric Acid Market
Additives
Allura Red AC Market
Additives
Tocopheryl Acetate Market
Additives
Competitive Inhibitors Market
Additives
North America Citric Acid Market
Additives
Anti-Foaming Agent Market