
 Global Feed Acidulants Market | 2026-2036
Global Feed Acidulants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Feed Acidulants Market Analysis
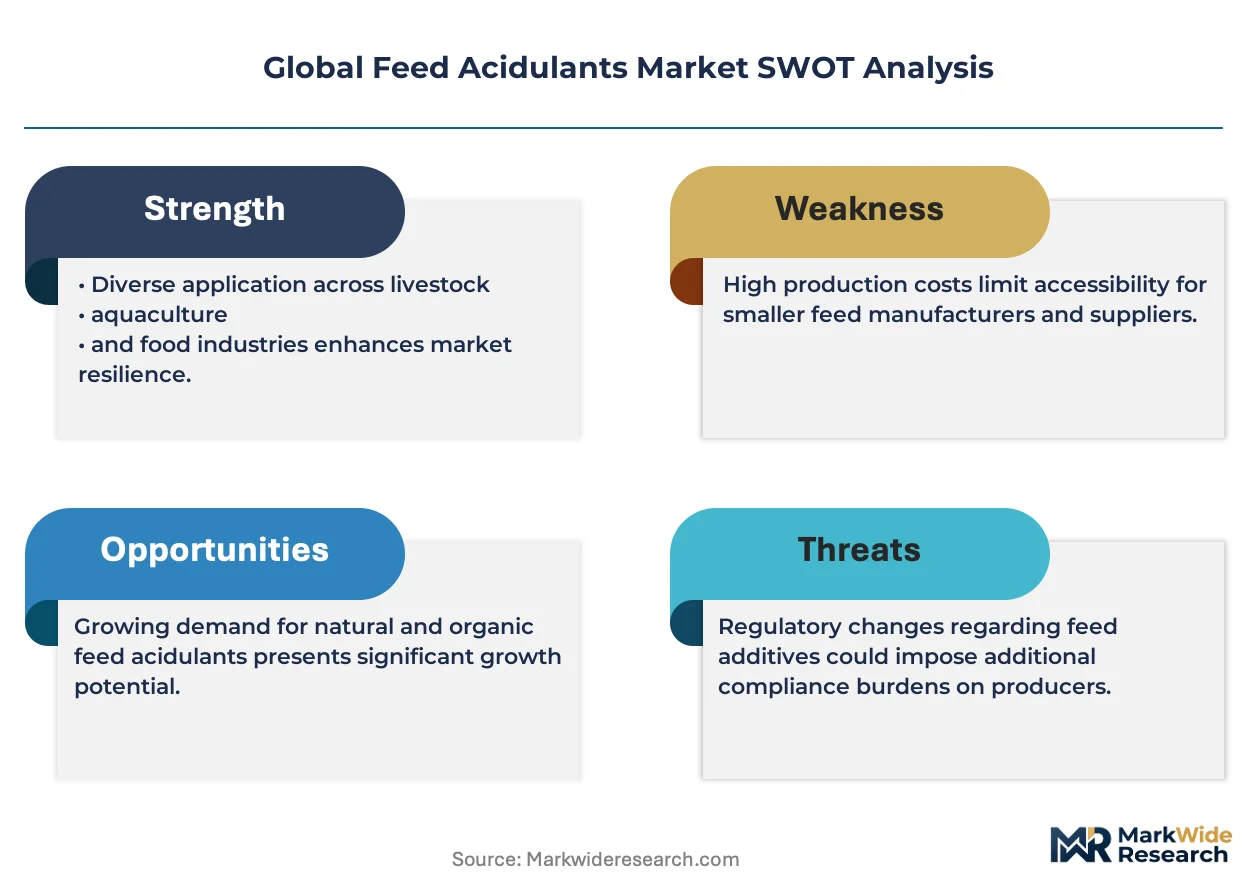
Formulation licensing revenue is reshaping margin capture across the feed acidulants value chain. BASF SE leverages its backward integration into citric acid fermentation to sustain cost leadership in liquid formulations. Kemin Industries anchors its position through specialized mineral-acid complexes for poultry gut health. Corbion differentiates via controlled-release lactic acid technologies that command premium positioning in swine applications.
Feed acidulants comprise organic and inorganic acids added to animal feed at concentrations typically ranging from 0.5% to 3.0% by weight to reduce gastric pH, inhibit pathogenic bacteria, and improve nutrient digestibility in monogastric and ruminant systems. Their primary commercial purpose centers on replacing antibiotic growth promoters while maintaining feed conversion efficiency in intensive livestock operations. Citric acid and lactic acid dominate volume flows due to established fermentation supply chains and broad regulatory acceptance across import jurisdictions. The powdered formulation segment captures disproportionate margin pools through extended shelf stability and ease of blending into mineral premixes. Aquaculture end-use represents the fastest-growing demand vector as shrimp and salmon producers acidify feeds to manage Vibrio loads in high-density systems.
The FDA's Veterinary Feed Directive and the EU Green Deal's Farm to Fork strategy are converging to accelerate antibiotic-free production systems, directly expanding acidulant incorporation rates in compound feeds. REACH registration requirements for imported acidulant grades and China's GB standards for feed additives collectively shape market access conditions and product specification floors. Brazil's MAPA and India's FSSAI enforcement on feed safety are adding compliance layers that favor suppliers with multi-jurisdiction certification portfolios. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether centralized or regional formulation strategies offer superior capital efficiency.
Market Dynamics
Antibiotic-free production mandates from the FDA and EU Green Deal are restructuring acidulant incorporation rates across intensive livestock systems. Poultry integrators in Brazil and the United States now specify acidified premixes as standard inputs, compressing the timeline for supplier qualification and multi-jurisdiction certification.
Growth Catalysts
- EU Green Deal Farm to Fork strategy:Binding targets for antibiotic reduction in livestock create direct substitution demand for organic acids in swine and poultry compound feeds across member states.
- Shrimp aquaculture intensification:High-density Vibrio management protocols in Vietnam and Indonesia drive acidified feed adoption at rates outpacing terrestrial livestock applications.
- Citric acid fermentation scale:Established bioprocessing infrastructure in China and Brazil secures cost-competitive supply chains for liquid acidulant formulations.
Market Restraints
- Input cost volatility:Molasses and corn steep liquor prices fluctuate with Brazilian sugarcane harvests and U.S. ethanol policy, compressing fermentation margins for lactic and citric acid producers.
- REACH registration concentration:European chemical compliance costs favor incumbent suppliers with dedicated regulatory affairs teams, raising barriers for Asian acidulant exporters.
- Mineral acid substitution:Phosphoric acid remains cost-preferred in ruminant buffering applications, limiting organic acid penetration in cattle feedlot systems.
Strategic Opportunities
- India FSSAI enforcement expansion:Feed safety mandate implementation creates first-mover advantage for suppliers with pre-certified acidulant portfolios in a historically informal premix market.
- Controlled-release acid complexes:Encapsulation technologies enabling targeted gastric release command premium positioning in weanling piglet diets where pH modulation timing is critical.
- Direct-to-integrator digital channels:Bypassing traditional distributor networks allows acidulant formulators to capture formulation licensing revenue from large Brazilian and Thai poultry operations.
Industry Challenges
- Multi-jurisdiction certification timelines:Synchronized FDA, EFSA, and China's SAMR approvals for novel acidulant salts extend product launch cycles beyond typical capital planning horizons.
- Formulation chemist scarcity:Specialized expertise in mineral-acid complex stability and gastric pH modeling concentrates among legacy European and North American technical service teams.
- Legacy ERP integration:Premix manufacturers in Southeast Asia face friction embedding acidulant traceability modules into existing batch control systems for export compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Feed Acidulants Market |
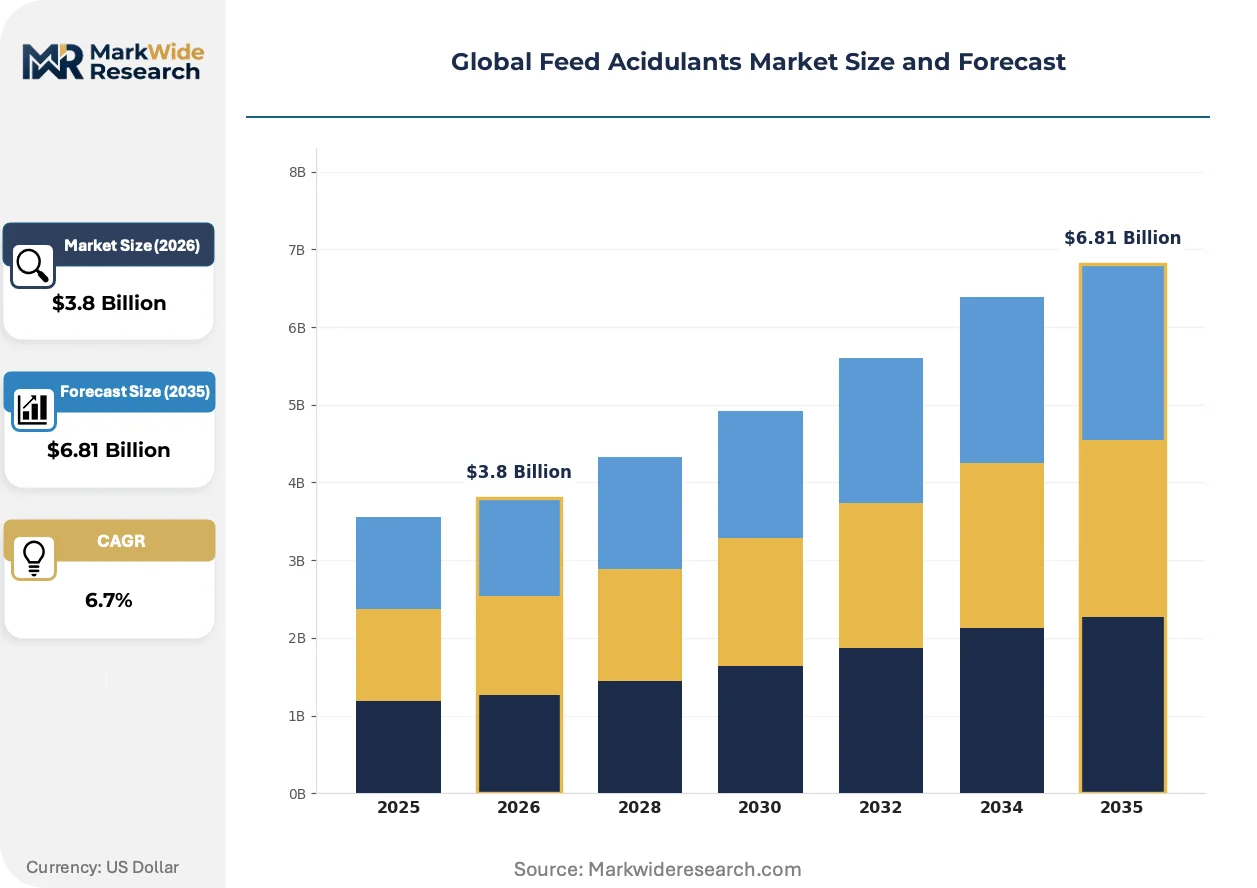
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citric Acid, Lactic Acid, Phosphoric Acid, Acetic Acid End User: Poultry, Swine, Ruminants, Aquaculture Formulation Type: Liquid, Solid, Powdered, Granular Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | BASF SE, Yara International ASA, Eastman Chemical Company, Kemin Industries, Corbion, Perstorp, Cargill Incorporated, ADM, dsm-firmenich, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Feed Acidulants Market Emerging Trajectories
Digital formulation platforms and precision delivery systems are compressing the gap between laboratory acidulant development and commercial feed mill deployment. These shifts favor suppliers with integrated technical service capabilities over commodity traders.
Near-infrared spectroscopy coupled with cloud-based formulation software is digitizing real-time acidulant inclusion optimization in commercial feed mills. Large Brazilian integrators deploy these systems to adjust organic acid dosing based on incoming grain mycotoxin loads. The technology is digitizing quality control workflows that previously required centralized laboratory analysis, enabling decentralized decision-making at regional production sites.
REACH registration requirements for imported acidulant grades are tightening specification floors for non-European suppliers. ECHA enforcement of substance data sharing obligations extends compliance timelines for new market entrants. Asian fermentation-based acidulant exporters now pre-register formulations in Rotterdam and Hamburg to maintain continental market access, restructuring competitive positioning toward certification-heavy portfolios.
Buyer concentration among top-ten global poultry integrators is consolidating procurement leverage and unbundling technical service from product supply. Thai and Brazilian operations now specify acidulant performance guarantees tied to feed conversion metrics rather than standard ingredient purchasing. This shift is most visible in antibiotic-free broiler programs where integrators internalize formulation expertise and source acids as fungible inputs.
Global Feed Acidulants Market Segmentation
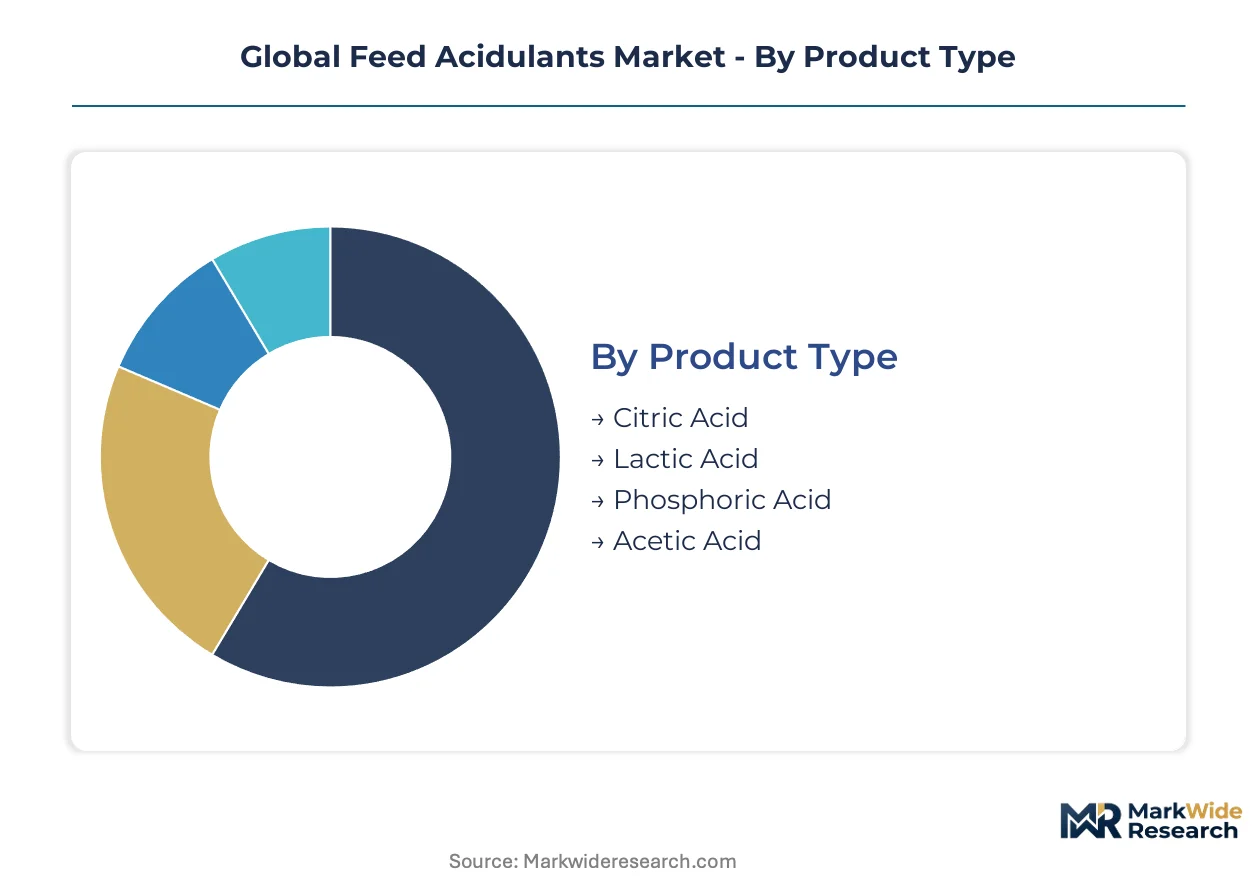
Feed acidulant suppliers configure product portfolios across four intersecting dimensions. Each segmentation layer carries distinct margin profiles, certification requirements, and customer concentration patterns that determine competitive positioning.
Product Type:
Cost tier determines fermentation scale economics and backward integration depth across acidulant categories.
- Citric Acid:Fermentation-derived from Aspergillus niger on molasses substrate. Brazilian sugarcane processors and Chinese corn-based biorefineries anchor global supply. Demand concentrates in liquid formulations for poultry drinking water acidification, where integrators specify minimum purity grades for antibiotic-free programs.
- Lactic Acid:Bacterial fermentation of carbohydrate feedstocks yields chiral-specific grades. Corbion and Galactic control proprietary lactobacillus strains that enable controlled-release complexes for swine gut health. European weanling piglet diets specify buffered lactic acid salts for gastric pH modulation timing.
- Phosphoric Acid:Wet-process mineral acid dominates ruminant buffering applications. Feed-grade specifications compete with fertilizer and industrial grades for phosphate rock allocation.
- Acetic Acid:Petrochemical and bio-based routes supply vinegar-standard grades for silage preservation and mold inhibition. Methanol carbonylation economics favor synthetic production in most jurisdictions.
Citric acid holds installed capacity. Lactic acid is rotating up the share rankings.
End User:
Application-specific performance requirements drive formulation complexity and technical service intensity.
- Poultry:Broiler integrators specify acidified premixes as standard inputs across Brazil, Thailand, and the United States. Drinking water acidification protocols require liquid citric and formic acid blends compatible with automated dosing systems. Brazilian operations lead incorporation rates following MAPA enforcement on feed safety.
- Swine:Post-weaning diarrhea control demands precise gastric pH reduction. Encapsulated butyric and lactic acid complexes command premium positioning in European farrow-to-finish operations governed by EU Green Deal antibiotic reduction mandates.
- Ruminants:Buffering applications favor phosphoric acid and sodium bicarbonate combinations. Organic acid penetration remains limited by cost-performance ratios against mineral alternatives in cattle feedlot systems.
- Aquaculture:Shrimp producers in Vietnam and Indonesia deploy acidified feeds for Vibrio management in high-density ponds. Salmon operations in Norway specify acidulant grades compatible with extrusion temperatures and pellet water stability requirements.
Poultry holds installed capacity. Aquaculture is climbing the fastest.
Formulation Type:
Volume handling characteristics and shelf stability requirements segment manufacturing investment and distribution economics.
- Liquid:Bulk tanker delivery to integrated feed mills minimizes packaging costs. Corrosion-resistant storage and automated dosing infrastructure favor large-scale poultry operations with dedicated technical staff.
- Solid:Compressed blocks and tablets serve ruminant self-feeding applications. Mineral acid complexes in solid form extend field stability in tropical climates.
- Powdered:Extended shelf stability and ease of blending into mineral premixes capture disproportionate margin pools. Segregated production lines prevent cross-contamination with coccidiostats and other feed additives.
- Granular:Dust-free handling properties suit automated premix operations. Coated granules enable controlled-release kinetics critical for gastric pH timing in weanling diets.
Powdered holds installed capacity. Granular is gaining share fastest.
Distribution Channel:
Customer type and procurement scale determine channel economics and supplier margin capture.
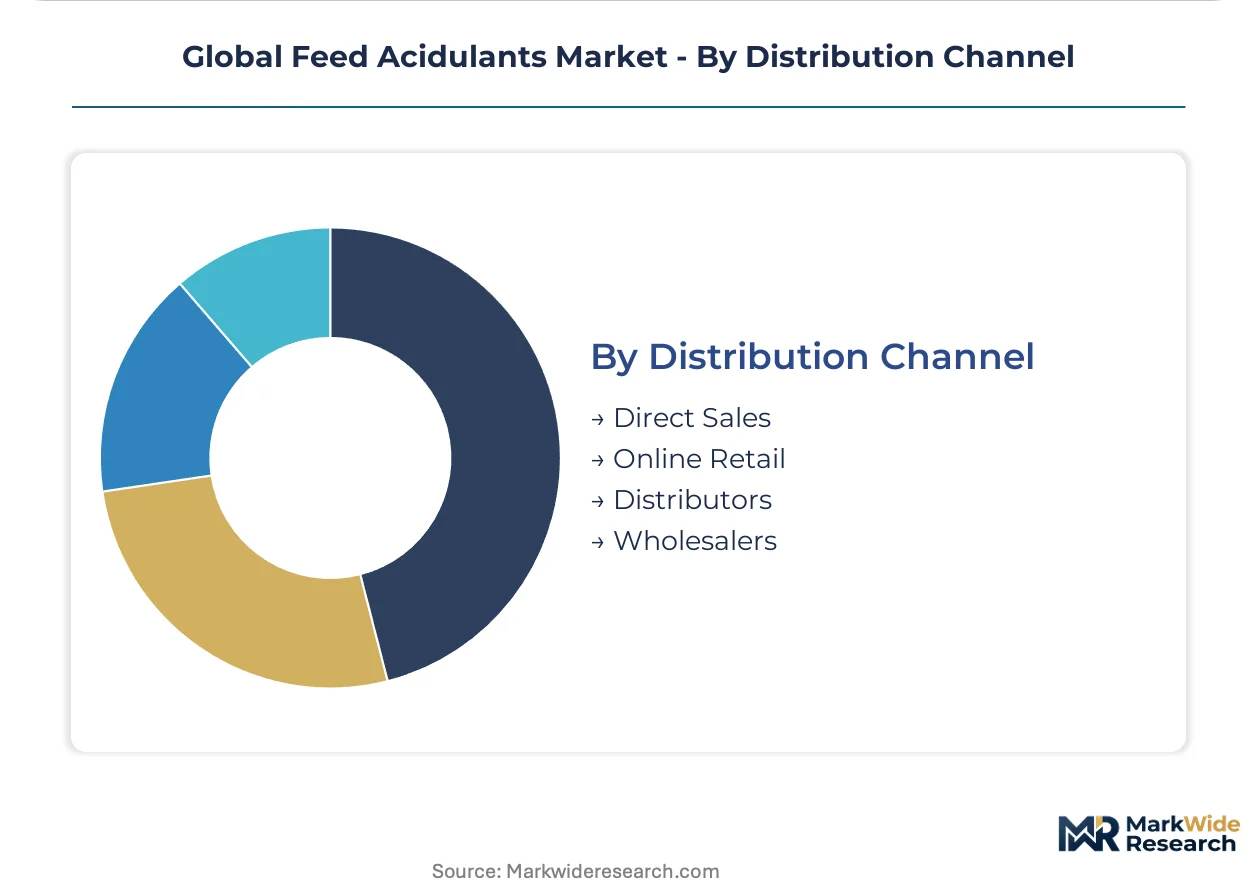
- Direct Sales:Top-ten global poultry integrators unbundle technical service from product supply. Brazilian and Thai operations source acids as fungible inputs against performance guarantees tied to feed conversion metrics.
- Distributors:Regional premix manufacturers rely on stocked inventory and formulation support. Multi-jurisdiction certification portfolios favor established distributors with regulatory affairs capabilities.
- Wholesalers:Smaller compound feed operations purchase standard grades through agricultural supply cooperatives. Price transparency from commodity exchanges limits value-added service capture.
- Online Retail:Digital platforms serve niche organic livestock producers and hobby farmers. Limited volumes constrain supplier qualification investments for e-commerce-specific packaging and logistics.
Direct sales holds installed capacity. Distributors is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Brazil and Southeast Asia demonstrate the highest price elasticity, sourcing acidulants as fungible inputs against feed conversion guarantees. German and Dutch integrators exhibit lower sensitivity, paying premiums for controlled-release formulations and REACH-certified grades. Chinese buyers occupy the middle tier, balancing cost against GB standard compliance.
Brazil
Integrated poultry operations in São Paulo and Paraná specify acidified premixes as standard inputs following MAPA enforcement on feed safety. The Brazilian regulator mandates traceability modules for export-bound compound feeds. Campinas anchors the country's fermentation supply chain, with sugarcane processors converting molasses into citric acid for domestic acidulant formulations.
United States
Broiler integrators in Georgia and Arkansas unbundle technical service from acidulant supply, sourcing acids against performance guarantees. The FDA's Veterinary Feed Directive accelerates antibiotic-free program adoption. The Delmarva Peninsula concentrates contract grower operations deploying automated drinking water acidification systems.
Germany
Weanling piglet producers in Lower Saxony specify encapsulated lactic acid complexes for precise gastric pH timing. ECHA enforcement of REACH substance data sharing obligations extends compliance timelines for imported grades. The Hamburg-Rotterdam corridor hosts pre-registration activities for Asian fermentation-based acidulant exporters maintaining continental market access.
China
Domestic citric acid biorefineries supply cost-competitive liquid formulations for regional poultry and swine operations. SAMR's GB standards for feed additives shape product specification floors for compound feed manufacturers. Shandong Province concentrates fermentation capacity converting corn starch into organic acid feedstocks.
Vietnam
Shrimp aquaculture intensification in the Mekong Delta drives acidified feed adoption for Vibrio management in high-density ponds. The country's national feed safety regulator tightens import specifications for acidulant grades. Ho Chi Minh City anchors technical service operations supporting delta-based pond managers.
Global Feed Acidulants Market Vendor Landscape
Capability concentration sits with European specialists mastering encapsulation and controlled-release technologies; scale advantage sits with diversified chemical conglomerates operating fermentation assets across multiple continents. The vendor base stratifies into three tiers: backward-integrated fermentation majors, mineral-acid complex specialists, and regional formulation distributors. Strategic moves center on direct-to-integrator channel development and certification portfolio expansion across FDA, EFSA, and SAMR jurisdictions.
Within the fermentation-major tier, BASF SE and Corbion exemplify divergent positioning strategies. BASF leverages its Ludwigshafen-based chemical complex and Brazilian sugarcane processing assets to sustain cost leadership in liquid citric acid formulations. Corbion occupies a premium-tier position through specialized lactobacillus strain control enabling controlled-release lactic acid complexes. Kemin Industries represents the mineral-acid specialist archetype, anchoring its competitive position through technical service intensity in poultry gut health applications rather than fermentation scale.
| Leading Market Players |
|---|
| BASF SE |
| Yara International ASA |
| Eastman Chemical Company |
| Kemin Industries |
| Corbion |
| Perstorp |
| Cargill Incorporated |
| ADM |
| dsm-firmenich |
| Others |
Supply Flow & Price Mechanics
Commodity volatility in Brazilian sugarcane and Chinese corn steep liquor determines both the spread between liquid and powdered formulation tiers and the geographic shape of fermentation asset placement. Buyers facing this input cost uncertainty structure long-term offtake agreements that lock in acidulant supply security against feed conversion performance guarantees.
Pricing Analysis
Formulation licensing revenue drives lifetime value capture for specialized acidulant suppliers serving integrated poultry operations. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified controlled-release complexes from commodity citric acid grades and unbranded mineral acid blends. Cost compression in standard liquid formulations is intensifying because Brazilian sugarcane processors are redirecting molasses toward ethanol mandates. Small compound feed operations in Southeast Asia exhibit highest price sensitivity, while German weanling piglet producers accept premiums for gastric pH timing precision.
Supply Chain Analysis
Tariff exposure between Chinese citric acid biorefineries and European compound feed manufacturers dominates supply chain risk planning for acidulant distributors. Manufacturing gravity centers on China, Brazil, and Germany, with fermentation capacity drawing from molasses, corn starch, and phosphate rock feedstocks respectively. Single-source vulnerability concentrates in proprietary lactobacillus strain control for controlled-release lactic acid complexes. Distribution runs through direct tanker delivery to large integrators and regional premix distributor networks for mid-scale compound feed operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized expertise in mineral-acid complex stability and gastric pH modeling concentrates among legacy technical service teams, creating a bottleneck that determines competitive outcomes. Suppliers lacking this capability must acquire or partner to participate in premium formulation tiers.
For Market Incumbents: Entrench position by deepening backward integration into fermentation feedstocks in Brazil and China, securing molasses and corn starch supply priority against ethanol policy competition. Expand multi-jurisdiction certification portfolios across FDA, EFSA, and SAMR to extend qualification timelines for emerging Asian exporters. Prioritize technical service team retention as the primary defensive asset against mineral-acid substitution in ruminant applications.
For New Entrants and Emerging Players: Pursue white-space opportunity in India's FSSAI enforcement expansion, where pre-certified acidulant portfolios command first-mover advantage in a historically informal premix market. Target Vietnam's shrimp aquaculture intensification with acidified feed formulations for Vibrio management, bypassing saturated poultry segments. Deploy direct-to-integrator digital channels to capture formulation licensing revenue from Thai and Brazilian operations unbundling technical service from product supply.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mineral-acid complex specialists with proprietary encapsulation capabilities over commodity fermentation scale. Long-term viability across the analysis window rests on controlled-release technology differentiation rather than raw material cost position. Monitor ECHA enforcement intensity on REACH substance data sharing obligations as the signal indicating inflection toward certification-heavy competitive outcomes.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Feedstocks | Molasses security from Brazilian sugarcane processors insulates against ethanol policy competition. |
| Multi-Jurisdiction Certification Expansion | Pre-registration in Hamburg and Rotterdam maintains continental access for Asian exporters. |
| Controlled-Release Technology Development | Encapsulated lactic acid complexes command premium positioning in EU Green Deal piglet diets. |
| Direct-to-Integrator Channel Development | Digital platforms capture formulation licensing revenue from Thai and Brazilian poultry operations. |
| Technical Service Team Expansion | Gastric pH modeling expertise concentrates competitive advantage in weanling diet applications. |
Methodological Framework
Operator-level perspectives from poultry integration nutritionists, swine gut health specialists, aquaculture pond managers, premix manufacturing plant managers, and fermentation process engineers anchored the qualitative base for this study. Primary interview insights combined with secondary validation from customs and trade data, feed industry association reports, SEC filings of diversified chemical conglomerates, and regulatory submission databases. Bottom-up volume modeling across citric acid, lactic acid, phosphoric acid, and acetic acid categories triangulated against top-down market sizing from fermentation capacity disclosures.
Scenario-bracketing around EU Green Deal enforcement intensity, FDA Veterinary Feed Directive implementation pace, and Brazilian MAPA traceability mandate timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include acidulant product type, end-use species, formulation physical state, and distribution channel structure. CAGRs derived from installed capacity expansion plans, antibiotic-free program adoption curves, and aquaculture intensification rates in Vietnam and Indonesia.
Sensitivities concentrate around molasses price volatility, REACH registration timeline extensions, and shrimp aquaculture disease outbreak patterns. Forecasts reflect documented assumptions on regulatory convergence and fermentation technology diffusion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Japan Sodium Reduction Ingredient Market
Additives
Inhibited Propylene Glycol Market
Additives
Crystal Growth Modifier Market
Additives
Feedstuff Additives Market
Additives
Hydrogen Peroxide Chemical Indicator Market
Additives
Cetane Improver Additives Market
Additives
Anti-Settling Agents Market
Additives
Dry-Mix Mortar Additives and Chemicals Market
Additives
Global Silica-Based Matting Agents Market
Additives
Polyoxyethylene Sorbitan Monostearate Market
Additives
Adjustive Agents Market
Additives
Lactic Acid Ester Market
Additives
Grinding Aids Market
Additives
Ruminant Feed Additive Market
Additives
Ultraviolet Light Stabilizer Market
Additives
2-Ethylhexyl Nitrate (2EHN) Market