
 PE Resins Market | 2026-2036
PE Resins Market Size, Share, and Industry Trends Forecast 2026-2036
PE Resins Market Outlook
Aftermarket technical service revenue is reconfiguring margin capture across the PE Resins value chain. Dow Inc. leverages its polymer science expertise to anchor premium technical support contracts with packaging converters. LyondellBasell Industries sustains its position through proprietary catalyst licensing that extends beyond commodity resin sales. SABIC competes on feedstock-integrated scale at its Jubail complex, while INEOS Group controls European distribution through its pipeline-connected manufacturing network.
PE Resins comprise thermoplastic polymers derived from ethylene polymerization, with densities ranging from ultra-low-density polyethylene below 0.915 g/cm³ to high-density polyethylene above 0.940 g/cm³, produced via slurry, solution, or gas-phase processes primarily for film, blow-molded, and injection-molded applications. High-Density Polyethylene occupies the most mature margin pool in pipe and rigid container applications where specification compliance locks in long-term supply agreements. Linear Low-Density Polyethylene leads growth in stretch film and agricultural mulch films where down-gauging requirements favor its superior toughness. Food & Beverage end users concentrate procurement around direct sales channels with certified food-contact resin grades.
REACH registration requirements in Europe and FDA food-contact notifications in the United States constrain market access for non-compliant resin producers, while China's SAMR enforces GB standards that increasingly reference migration limits for packaging applications. The EU Green Deal and state-level extended producer responsibility frameworks in California and New York are redirecting investment toward mechanically recycled and bio-based polyethylene grades. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded capacity in non-compliant resin technologies.
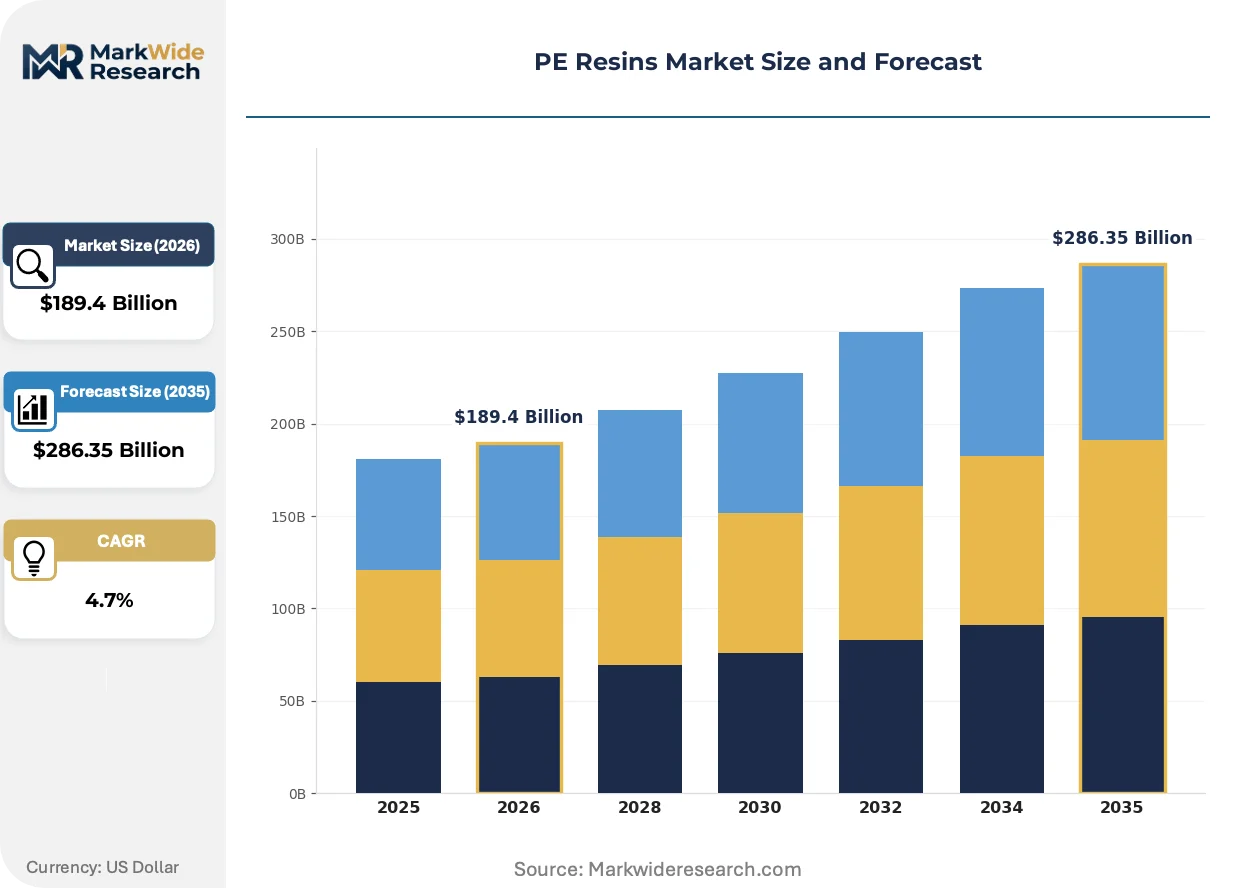
Market Dynamics
Food-contact compliance requirements from China's SAMR and India's FSSAI are forcing resin producers to requalify polymer grades, while packaging converters in Gujarat and Maharashtra demand certified supply chains that lock in multi-year procurement contracts.
Growth Catalysts
- GB Standard Migration Limits:China's evolving food-contact material regulations under SAMR enforcement are compelling domestic and import resin suppliers to upgrade certification documentation, expanding the addressable market for compliant HDPE and LLDPE grades.
- Agricultural Film Down-Gauging:Stretch film and mulch film producers favor LLDPE's superior toughness-to-thickness ratio, driving specification shifts across India's western industrial corridor where Reliance Industries anchors downstream conversion capacity.
- Emerging Economy Packaging Demand:Food and beverage producers across Southeast Asia and Latin America are expanding polyethylene film consumption for shelf-stable and flexible packaging applications.
Market Restraints
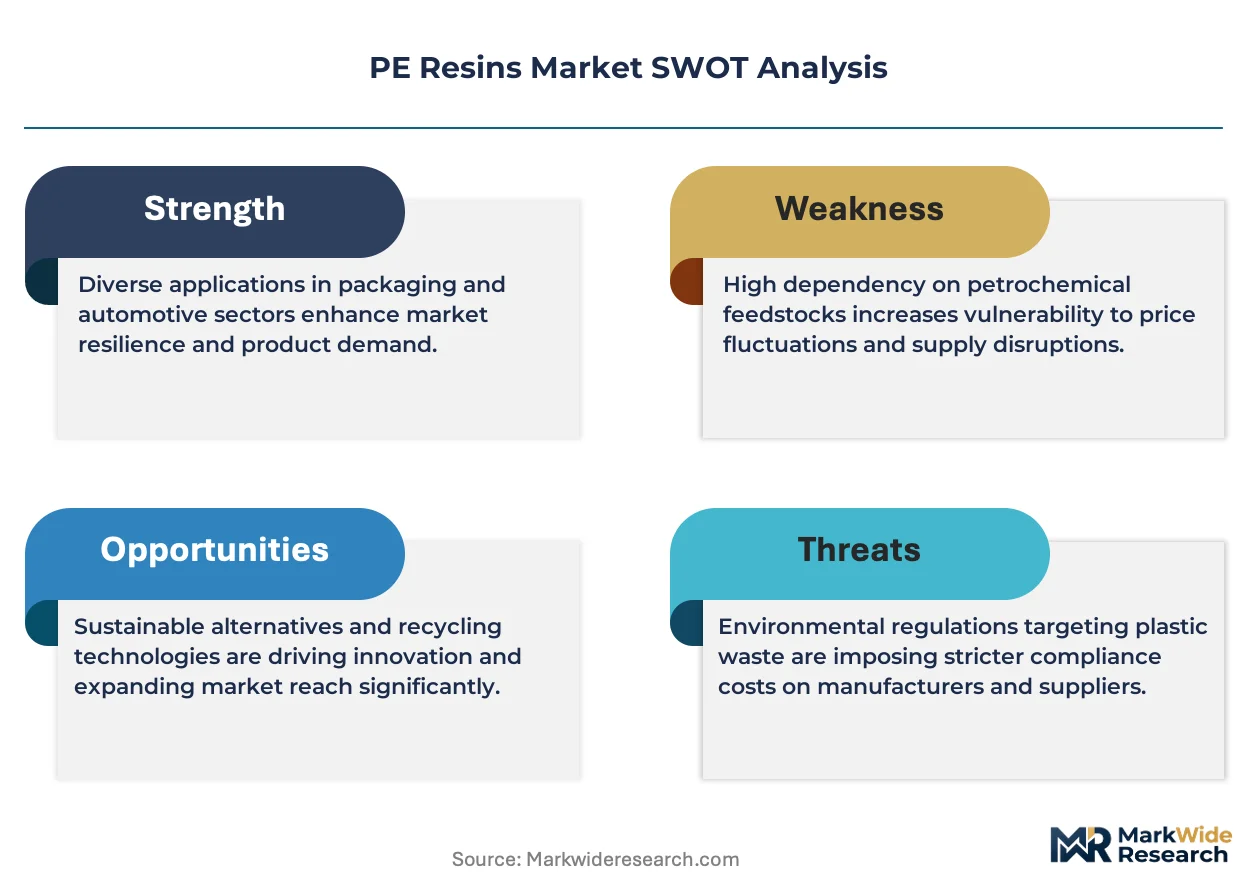
- Ethylene Feedstock Volatility:Naphtha and ethane price swings compress margin predictability for non-integrated resin producers lacking captive cracker capacity.
- REACH Registration Barriers:ECHA compliance costs and extended substance evaluation timelines restrict market access for smaller resin exporters targeting European flexible packaging converters.
- Mechanical Recycling Substitution:Post-consumer recycled polyethylene flakes from European and North American collection streams are displacing virgin resin in non-food-contact film applications where specification tolerances permit.
Strategic Opportunities
- Bio-Based Ethylene Feedstocks:Sugar cane-derived and waste-to-ethylene pathways offer resin producers a route to differentiate premium grades under EU Green Deal carbon accounting frameworks and California's extended producer responsibility mandates.
- Pipeline-Connected Distribution:European converters adjacent to INEOS Group's integrated manufacturing network gain logistics cost advantages that resin suppliers can replicate through dedicated terminal arrangements in Rotterdam and Antwerp.
- Technical Service Unbundling:Dow Inc.'s polymer science expertise demonstrates that aftermarket support contracts capture margin beyond commodity resin sales, creating a template for specialty-grade producers to monetize application engineering.
Industry Challenges
- Catalyst Licensing Complexity:Proprietary Ziegler-Natta and metallocene intellectual property from LyondellBasell Industries and other licensors creates negotiation friction for new market entrants seeking competitive polymerization technology.
- Multi-Jurisdiction Certification Timelines:Simultaneous FDA food-contact notification, EU REACH registration, and China's NMPA filing requirements strain regulatory affairs capacity and extend product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PE Resins Market |
| Market Size in 2026 | $189.4 Billion |
| Market Size in 2035 | $286.35 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low-Density Polyethylene, High-Density Polyethylene, Linear Low-Density Polyethylene, Ultra-Low-Density Polyethylene Application: Packaging, Automotive, Agriculture, Consumer Goods End User: Food & Beverage, Construction, Electronics, Healthcare Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | China Petroleum & Chemical Corporation, Dow Inc., LyondellBasell Industries, Reliance Industries Limited, Chevron Phillips Chemical Company, ExxonMobil Corporation, INEOS Group, Formosa Plastics Corporation, SABIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PE Resins Market Strategic Shifts
Polyethylene resin technology is converging with circular economy infrastructure and digital supply chain tools, reshaping how producers compete on specification compliance rather than volume scale alone.
Advanced catalyst systems is hybridizing gas-phase and slurry polymerization processes to produce multimodal polyethylene with tailored molecular weight distributions. Pipe and rigid container manufacturers in Germany and the Netherlands are adopting these grades for pressure-rated applications. This convergence is compressing the performance gap between commodity HDPE and engineered thermoplastics in specified infrastructure projects.
The EU Green Deal's packaging and packaging waste regulation is mandating recycled content minimums and extended producer responsibility fees across member states. European resin distributors are restructuring procurement portfolios to blend mechanically recycled flakes with virgin polymer. Food-contact film converters face the steepest compliance burden, as current recycling technologies struggle to meet EFSA migration limit requirements.
Direct sales channel consolidation is concentrating procurement power among multinational food and beverage packaging groups. These buyers are unbundling technical service contracts from resin supply agreements, forcing producers to compete on application support separately from polymer pricing. This pattern is most visible in India's western industrial corridor, where Reliance Industries and Gujarat-based converters negotiate integrated supply-and-service arrangements.
PE Resins Market Segmentation
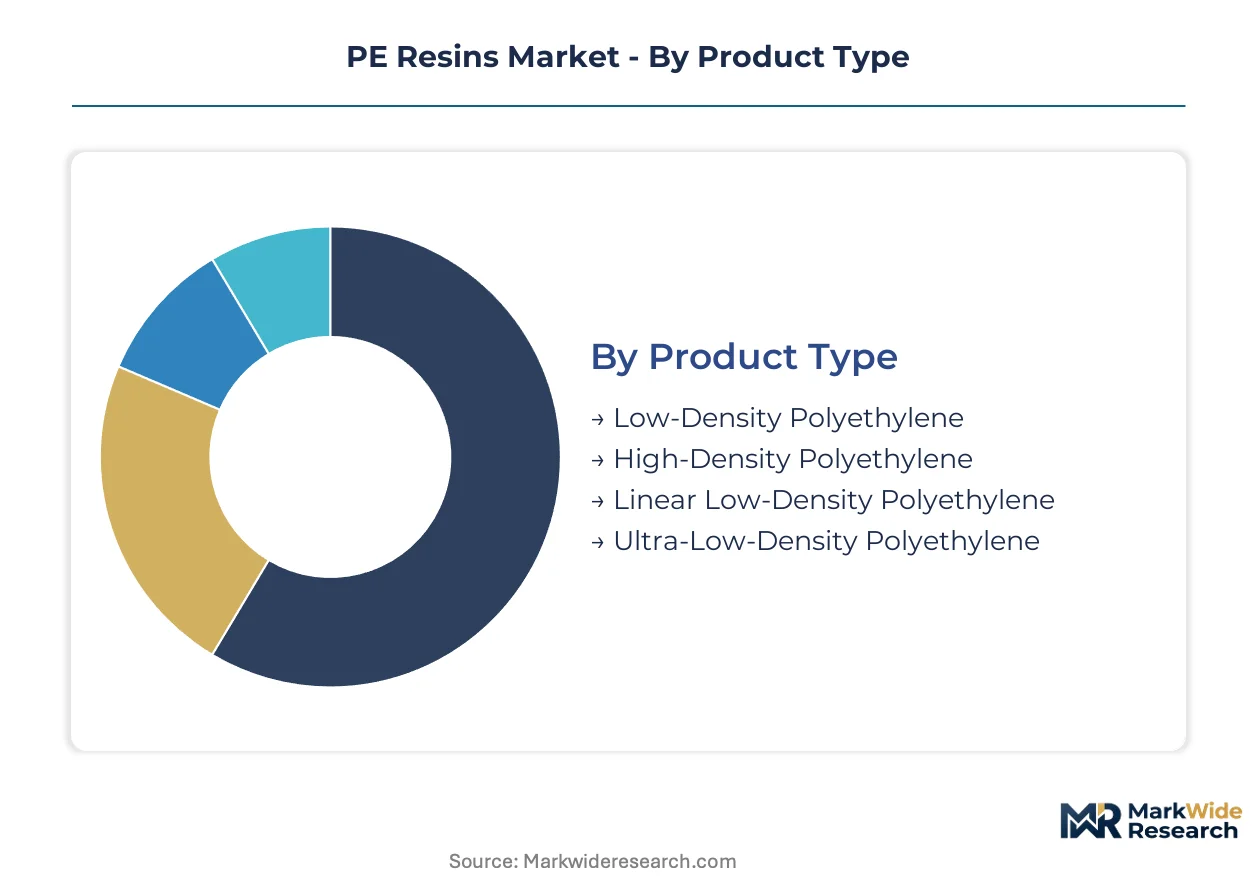
PE Resins demand fragments across density grades, end-use specifications, and procurement channels that each carry distinct compliance burdens and margin profiles. Understanding these divisions reveals where producers capture premium pricing versus commodity volume.
Product Type:
Mature infrastructure grades dominate current procurement volumes while emerging specialty densities reshape competitive positioning.
- High-Density Polyethylene:Dense crystalline structure above 0.940 g/cm³ delivers rigidity for pressure-rated pipe and rigid container applications. German and Dutch infrastructure contractors specify multimodal HDPE grades for water distribution networks where long-term creep resistance locks in supply agreements.
- Linear Low-Density Polyethylene:Linear polymer chains with short branching enable superior puncture resistance at reduced film gauges. India's western industrial corridor concentrates demand from agricultural mulch film producers who down-gauge to meet cost targets while maintaining field durability.
- Low-Density Polyethylene:Highly branched amorphous structure below 0.930 g/cm³ serves extrusion coating and flexible film laminates where clarity and sealability matter.
- Ultra-Low-Density Polyethylene:Density below 0.915 g/cm³ penetrates impact-modified compounds and soft-touch consumer goods where rubber-like flexibility replaces thermoplastic elastomers.
High-Density Polyethylene retains volume leadership; Ultra-Low-Density Polyethylene holds the steepest expansion curve.
Application:
Cost tier stratification separates specification-intensive applications from price-sensitive commodity segments.
- Packaging:Film, blow-molded containers, and injection-molded closures constitute the largest demand pool with divergent compliance requirements. Food-contact film converters in Gujarat and Maharashtra demand certified supply chains that lock in multi-year procurement contracts with full traceability documentation.
- Agriculture:Greenhouse films, mulch films, and irrigation pipe drive specification shifts toward UV-stabilized and down-gauged grades. Stretch film producers across India's western industrial corridor favor LLDPE's toughness-to-thickness ratio for mechanized wrapping operations.
- Automotive:Fuel tanks, under-hood components, and interior trim require heat-resistant and chemically inert formulations that meet OEM material qualification protocols.
- Consumer Goods:Housewares, toys, and furniture components compete primarily on colorability and processing efficiency rather than performance specifications.
Packaging commands the widest margin spread across certification tiers; Agriculture climbs fastest on down-gauging adoption.
End User:
Customer type determines whether procurement emphasizes direct technical partnership or distributor-mediated spot purchasing.
- Food & Beverage:Multinational packaging groups concentrate procurement power through unbundled technical service contracts. China's SAMR and India's FSSAI force resin producers to requalify polymer grades with migration limit documentation.
- Construction:Pipe manufacturers and geomembrane installers specify pressure-rated HDPE with decades-long performance warranties that cement supplier relationships.
- Healthcare:Medical device and pharmaceutical packaging demand US FDA food-contact notifications and EU REACH registration compliance that restrict eligible resin sources.
- Electronics:Cable jacketing and semiconductor packaging require clean-room compatible grades with ultra-low ionic contamination profiles.
Food & Beverage drives premium grade absorption; Healthcare gains share fastest on regulatory compliance tightening.
Distribution Channel:
Supply concentration shapes whether producers capture margin through captive logistics or cede value to intermediaries.
- Direct Sales:Large-volume converters negotiate integrated supply-and-service arrangements with dedicated technical support. Dow Inc. anchors premium contracts with packaging converters through polymer science expertise separate from resin pricing.
- Distributors:Regional stockists manage inventory for small-to-mid converters lacking storage infrastructure or multi-grade procurement sophistication.
- Online Retail:E-procurement platforms aggregate spot demand from specialty compounders and prototype developers seeking rapid sample fulfillment.
- Wholesalers:Volume aggregators serve secondary processors in fragmented industrial clusters where direct mill relationships prove uneconomical.
Direct Sales captures the highest margin per ton; Online Retail expands most quickly on digital procurement adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Packaging converters in India and China absorb price volatility with limited elasticity, while European pipe contractors and North American agricultural film buyers negotiate rigid long-term contracts that resist margin compression.
China
SAMR enforcement of GB standards for food-contact materials compels resin requalification across flexible packaging supply chains. NMPA filing requirements extend product launch timelines for import suppliers targeting dairy and beverage converters. The Yangtze River Delta concentrates downstream film extrusion capacity where certified HDPE and LLDPE grades command procurement premiums.
India
FSSAI migration limit documentation forces polymer grade recertification for domestic and import resin streams. Agricultural mulch film producers across Maharashtra and Gujarat favor down-gauged LLDPE specifications for mechanized field operations. Reliance Industries anchors downstream conversion clusters near Jamnagar where multi-year supply contracts lock in certified supply chains.
Germany
Pressure-rated pipe manufacturers specify multimodal HDPE grades for water distribution infrastructure with decades-long performance warranties. ECHA REACH registration requirements constrain eligible resin sources for flexible packaging converters serving EU Green Deal compliance mandates. The Ruhr industrial corridor hosts compounders blending mechanically recycled flakes with virgin polymer for non-food-contact applications.
United States
FDA food-contact notification requirements restrict resin sourcing for dairy and meat packaging converters in the Midwest and Southeast. California's extended producer responsibility framework redirects investment toward post-consumer recycled content minimums. The Gulf Coast petrochemical corridor supplies ethane-integrated resin producers with feedstock cost advantages over naphtha-dependent competitors.
Saudi Arabia
Feedstock-integrated scale at Jubail complex exports resin grades across Middle Eastern and African packaging markets. SAMR-equivalent standards in target export jurisdictions drive certification documentation investments for food-contact grade producers. The Eastern Province industrial zone connects pipeline logistics to Red Sea and Gulf shipping terminals serving Indian and East African converters.
PE Resins Market Competitive Environment
Capability concentration sits with catalyst licensors and technical service providers; scale advantage sits with feedstock-integrated producers and pipeline-connected distribution networks. The market structures around three tiers: proprietary technology licensors, integrated petrochemical majors, and regional distribution specialists. Strategic moves center on catalyst licensing extensions and dedicated terminal arrangements that replicate INEOS Group's European logistics model.
Within the integrated petrochemical tier, Dow Inc. and SABIC exemplify divergent geographic anchoring strategies—Dow Inc. through polymer science expertise and technical service contracts, SABIC through feedstock-integrated scale at its Eastern Province complex. LyondellBasell Industries occupies a licensing-focused position where proprietary Ziegler-Natta and metallocene intellectual property extends competitive reach beyond commodity resin sales. These three represent how capability and scale combine across different vectors.
| Leading Market Players |
|---|
| China Petroleum & Chemical Corporation |
| Dow Inc. |
| LyondellBasell Industries |
| Reliance Industries Limited |
| Chevron Phillips Chemical Company |
| ExxonMobil Corporation |
| INEOS Group |
| Formosa Plastics Corporation |
| SABIC |
| Others |
Value Chain & Pricing Dynamics
Ethane-integrated Gulf Coast crackers anchor feedstock cost advantages that concentrate margin capture among producers with captive upstream capacity, while naphtha-dependent Asian converters absorb volatility through long-term offtake structures with specified volume floors.
Pricing Analysis
Aftermarket technical service contracts drive lifetime value beyond resin tonnage. Three-tier pricing structure across premium certified, standard industrial, and economy commodity levels separates food-contact grades with full migration documentation from general-purpose extrusion resins. Price differentiation hinges on certification tier and after-sales application engineering. Cost compression in standard industrial grades is intensifying because mechanical recycling substitution erodes virgin resin premiums. Small-to-mid converters in fragmented industrial clusters exhibit highest price sensitivity, while multinational food packaging groups prioritize specification compliance over unit economics.
Supply Chain Analysis
Extended payment terms from 60 to 90 days strain working capital for distributors serving small converters without storage infrastructure. Geographic supply concentrates in Saudi Arabia, China, and the United States where feedstock-integrated complexes achieve scale economies. Raw material dependencies center on ethane, naphtha, and proprietary catalyst systems licensed from technology holders. Single-source vulnerability around metallocene catalyst intellectual property creates negotiation friction for new resin producers. Distribution runs through pipeline-connected terminal networks in Rotterdam and Antwerp, supplemented by dedicated logistics arrangements at Jubail and Jamnagar.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: multi-jurisdiction certification timelines and proprietary catalyst licensing create structural barriers that protect incumbent positions.
For Market Incumbents: Pre-empt mechanical recycling substitution by accelerating bio-based ethylene pilot capacity under EU Green Deal carbon accounting frameworks. Deepen backward integration into waste-to-ethylene feedstock pathways to defend margin position against naphtha price volatility. Lock in multi-year technical service contracts with Gujarat-based converters before emerging specialty-grade producers replicate Dow Inc.'s aftermarket revenue model.
For New Entrants and Emerging Players: Pursue white-space opportunities in ultra-low-density polyethylene compounds for soft-touch consumer goods where rubber-like flexibility commands specification premiums. India's western industrial corridor offers the most penetrable geography given Reliance Industries' downstream conversion cluster and unmet demand from agricultural mulch film producers. Lead with certified food-contact grade positioning to capture procurement contracts from FSSAI-compliant packaging converters in Maharashtra.
For Investors and Strategic Acquirers: Capital is best deployed toward catalyst licensors with proprietary metallocene intellectual property extending beyond commodity resin sales, given the long-term viability of technology licensing revenue streams across the analysis window. Monitor SAMR enforcement intensity as the signal indicating whether import resin requalification timelines will compress addressable market access for non-integrated producers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Feedstocks | Sugar cane-derived ethylene pathways secure premium positioning under EU Green Deal frameworks. |
| Catalyst Licensing Extension | Proprietary metallocene IP from LyondellBasell Industries extends competitive reach beyond resin sales. |
| Pipeline-Connected Distribution Expansion | Rotterdam and Antwerp terminal arrangements replicate INEOS Group's logistics cost advantages. |
| Multi-Jurisdiction Certification Investment | Simultaneous FDA, REACH, and NMPA filings accelerate product launch cycles for food-contact grades. |
| Technical Service Unbundling | Separate application engineering contracts capture margin beyond commodity polyethylene pricing. |
Study Parameters
A spread of perspectives from resin plant managers, procurement leads at flexible packaging converters, distribution channel partners, and technical R&D directors converged on the working assumptions shaping demand trajectories. Primary interviews combined with secondary validation from customs trade data, ACC and Cefic industry reports, SEC 10-K filings, and FDA food-contact notification databases established baseline volume estimates. Bottom-up grade-by-grade demand modeling triangulated against top-down ethylene derivative consumption analysis.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework. Segmentation dimensions modeled include density grade tier, end-use industry application, food-contact certification status, and regional production hub concentration. CAGRs derived from fitted growth curves applied to baseline consumption data, with cross-validation against cracker capacity expansion announcements and downstream conversion investment patterns. Forecast inputs incorporated regulatory compliance timeline assumptions and mechanical recycling displacement rates in non-food-contact film applications.
Sensitivities concentrate around SAMR enforcement intensity, ethane-naphtha price spreads, and catalyst licensing availability. Forecasts reflect documented assumptions on feedstock cost trajectories and certification timeline standardization. Macroeconomic contraction, regulatory divergence between jurisdictions, or breakthrough advances in chemical recycling would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Cathodic Acrylic Market
Polymers & Resins
Global Amorphous Polyalphaolefin (APAO) for Hot Melt Market
Polymers & Resins
Polymers for Electric Vehicle (EV) Market
Polymers & Resins
Plastic Resins Market
Polymers & Resins
Global Vinyl Ester Market
Polymers & Resins
Middle-East and Africa Epoxy Resins Market
Polymers & Resins
Synthetic Latex Polymers Market
Polymers & Resins
Indonesia Polypropylene Market
Polymers & Resins
Polymer Seals Market
Polymers & Resins
Global Polymerization Initiator Market
Polymers & Resins
Global Polyamide 6 Market
Polymers & Resins
Polymethacrylimide Foam Market
Polymers & Resins
Middle East Polyamide Market
Polymers & Resins
Polyvinyl Alcohol Resins Market
Polymers & Resins
Europe Polyolefin Market
Polymers & Resins
Global Opaque Polymers Market