
 Cement Paints Market | 2026-2036
Cement Paints Market Size, Share, and Industry Trends Forecast 2026-2036
Cement Paints Market Analysis
Water-based polymer modification of cement paint chemistry is narrowing the performance gap between traditional lime-cement coatings and acrylic emulsion systems. Asian Paints leverages its distribution depth across tier-2 and tier-3 Indian cities to sustain volume leadership in waterproof cement paint variants. Berger Paints anchors its position through backward integration into white cement sourcing, while Kansai Nerolac competes on tinting-system compatibility with its broader decorative portfolio.
Cement paint comprises a water-dispersible coating of white Portland cement, mineral fillers, and proprietary additives that bond chemically with masonry substrates to provide breathable, alkaline-resistant surface protection. Exterior cement paint typically achieves 50-100 micron dry film thickness and requires 8-12 hours curing before second-coat application, serving primarily as a cost-effective weatherproofing layer for concrete and plaster surfaces in high-humidity climates. Waterproof paint commands the largest volume share due to chronic moisture ingress problems in tropical monsoon zones, while nano-coating technology represents the fastest-expanding segment as hydrophobic silica additives gain commercial scale. Residential application dominates absolute consumption, though institutional demand yields higher per-project margins through specification-driven procurement.
BIS mandates IS 5410 standards for cement paint covering opacity, scrub resistance, and fungal resistance parameters, directly influencing manufacturer R&D allocation toward biocide-enhanced formulations. EPA VOC emission limits in the United States restrict solvent-based cement paint formulations, channeling investment toward water-based and eco-friendly technology platforms. REACH compliance in Europe imposes disclosure requirements on titanium dioxide nanoparticle content, adding testing costs that favor larger producers with dedicated regulatory affairs teams. Stakeholders must monitor how evolving green building certification schemes in India and Southeast Asia redefine acceptable volatile content thresholds for masonry coatings.
Market Dynamics
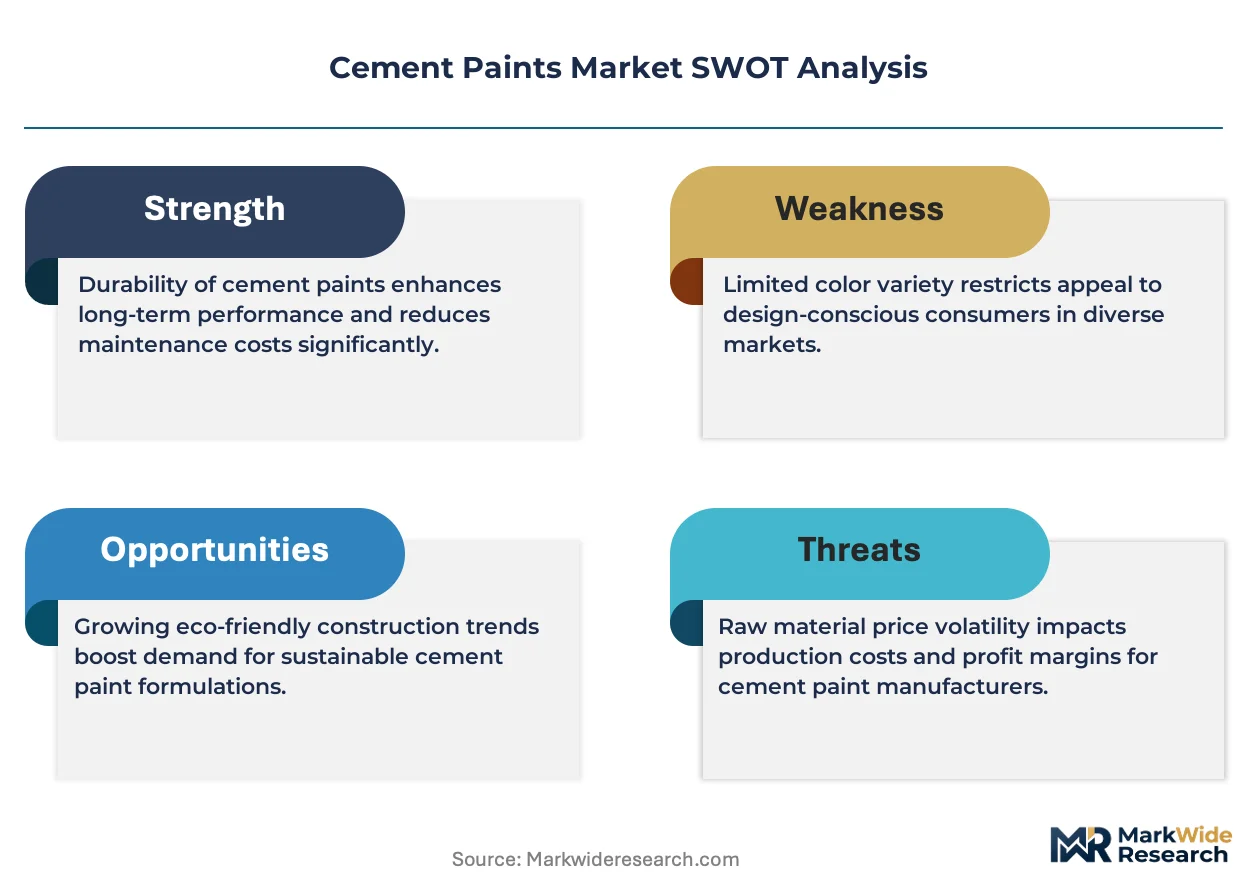
Water-based polymer modification is compressing the performance gap between traditional lime-cement coatings and acrylic emulsion systems, forcing incumbents to defend volume positions through distribution depth rather than formulation premium.
Growth Catalysts
- Monsoon-driven waterproofing mandates:BIS certification requirements for exterior durability in India are tightening opacity and fungal resistance standards, pulling demand toward biocide-enhanced formulations.
- REACH compliance spillover:European disclosure requirements on titanium dioxide nanoparticle content are accelerating testing investment among export-oriented Indian manufacturers.
- Nano-coating commercialization:Hydrophobic silica additives are achieving production scale, enabling breathable moisture barriers that outperform conventional cement paint in tropical humidity.
Market Restraints
- White cement supply concentration:Backward integration into clinker sourcing remains limited to three domestic producers, creating input cost volatility during energy price spikes.
- Acrylic emulsion substitution:Water-based polymer systems are capturing specification-driven institutional projects where 8-12 hour cure times disadvantage cement chemistry.
- EPA VOC friction:United States emission limits channel R&D toward water-based platforms that sacrifice the alkaline resistance cement paint provides masonry substrates.
Strategic Opportunities
- Tier-3 city distribution gaps:India's northeastern states and secondary cities in Bihar and Uttar Pradesh remain underserved by organized retail paint networks.
- Green building certification tailwinds:GRIHA and IGBC rating systems in India are embedding volatile content thresholds that favor low-VOC cement formulations over solvent-based alternatives.
- Institutional specification channels:Government housing and infrastructure procurement is consolidating toward pre-qualified vendor lists that reward BIS-certified producers with multi-year supply agreements.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in mineral filler dispersion and biocide stability is concentrating among retiring technical staff at established manufacturers.
- Dual certification timelines:Concurrent BIS IS 5410 and export-market REACH compliance is extending product launch cycles by 14-18 months for mid-scale producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cement Paints Market |
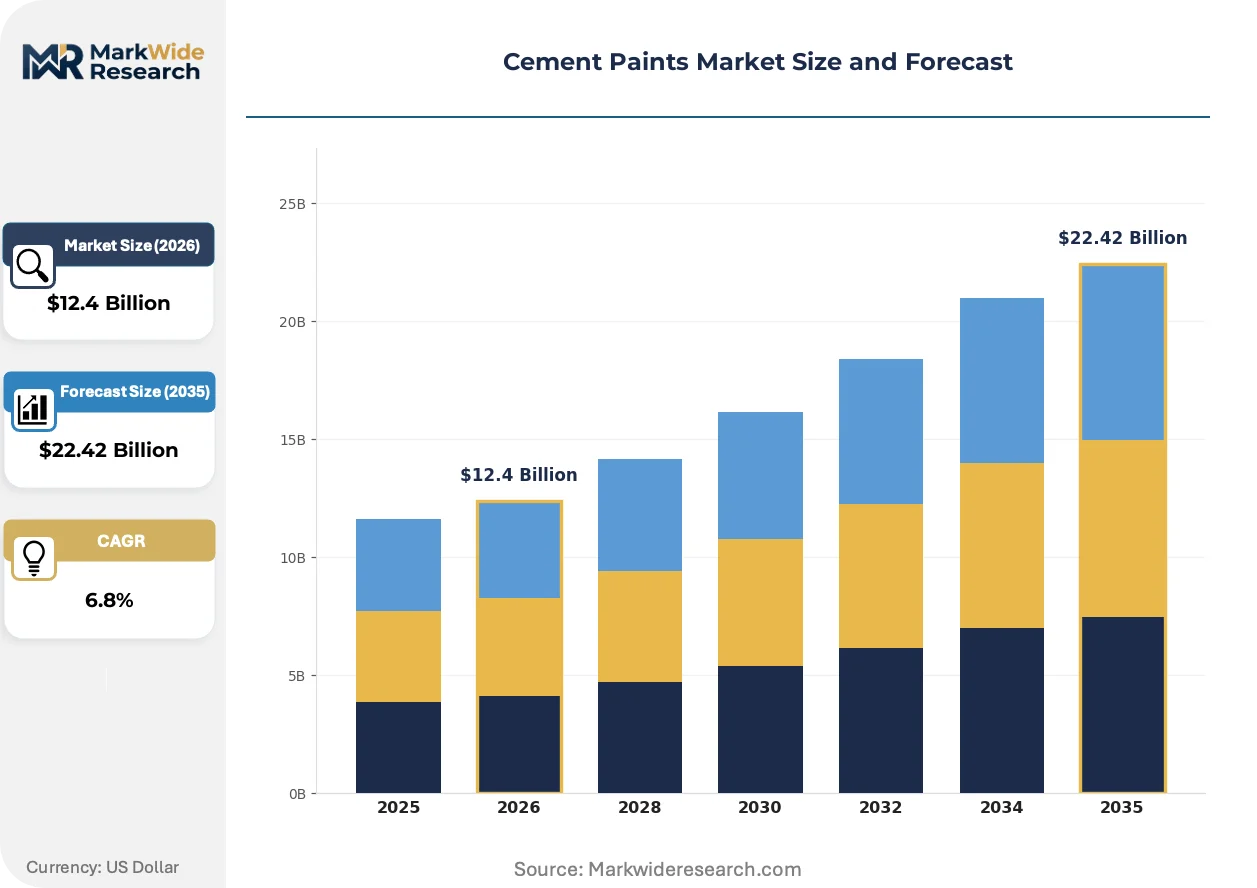
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Exterior Paint, Interior Paint, Waterproof Paint, Textured Paint Application: Residential, Commercial, Industrial, Institutional Technology: Water-based, Solvent-based, Eco-friendly, Nano-coating Color Type: Standard Colors, Custom Colors, Pastel Shades, Bright Shades |
| Companies Covered | Asian Paints, Berger Paints, Kansai Nerolac Paints, PPG Industries, Jotun Group, Sherwin-Williams, AkzoNobel, BASF Coatings, Acro Paints, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cement Paints Market Emerging Trajectories
Formulation chemistry and procurement patterns are diverging across residential and institutional channels, with performance specifications hardening in commercial projects while cost compression dominates renovation demand.
Silica-based hydrophobic nano-additives are migrating from laboratory validation to commercial masonry coatings. High-specification institutional buyers in Kerala and coastal Karnataka are specifying these formulations for sea-facing concrete structures. The technology is migrating from premium niche applications toward mid-tier waterproofing segments as additive costs decline and toll-manufacturing capacity expands.
India's BIS has tightened IS 5410 scrub resistance and fungal resistance parameters effective for exterior-grade certification. Manufacturers are reallocating R&D budgets toward biocide-enhanced and polymer-modified lines that can pass accelerated weathering protocols. Export-oriented producers face parallel pressure from REACH titanium dioxide disclosure rules, favoring larger competitors with dedicated regulatory affairs functions.
Specification-driven procurement is consolidating institutional demand around pre-qualified vendor lists and multi-year framework agreements. Government housing authorities and infrastructure developers are displacing spot-market purchasing with centralized tendering that rewards BIS certification and proven cure-time performance. This pattern is most visible in Maharashtra and Tamil Nadu urban development projects where contractor liability for coating failure has sharpened quality thresholds.
Cement Paints Market Segmentation
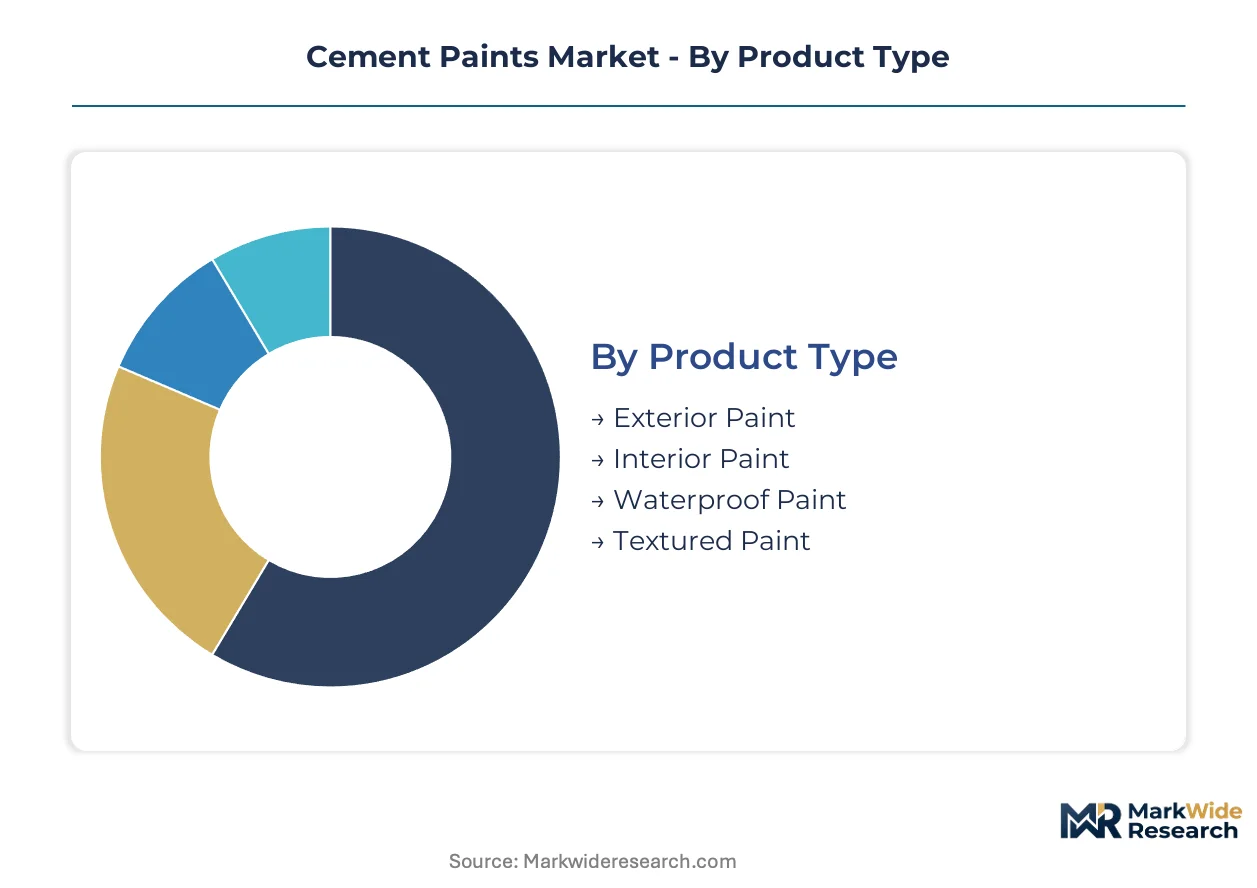
Segmentation in cement paints reveals how formulation chemistry, application environment, and procurement channels split demand across distinct performance tiers. Understanding these divides exposes where volume concentrates versus where margins expand.
Product Type:
Cost tier determines formulation investment, cure time tolerance, and durability specifications across residential renovation and new construction channels.
- Waterproof Paint:Comprises white Portland cement with hydrophobic mineral fillers and polymer modifiers that achieve breathable moisture barriers on masonry substrates. Demand concentrates in India's western and southern states where monsoon-driven water ingress destroys conventional coatings, pulling specification toward BIS-certified exterior durability grades.
- Exterior Paint:Engineered for 50-100 micron dry film thickness with alkaline resistance against concrete carbonation and sulfate attack. Institutional procurement in Maharashtra and Tamil Nadu urban development projects specifies these formulations for contractor liability protection on government housing.
- Interior Paint:Lower polymer loading prioritizes cost compression over weathering resistance for protected indoor plaster surfaces.
- Textured Paint:Incorporates coarse mineral aggregates for aesthetic surface relief on feature walls and commercial facades.
Waterproof paint commands the established base. The steepest expansion runs through textured paint as architectural specification hardens.
Application:
Customer type separates spot-market retail purchasing from framework-agreement procurement with divergent quality thresholds and payment terms.
- Residential:Dominates absolute consumption through renovation-driven spot purchases in tier-2 and tier-3 Indian cities. Homeowners prioritize cost-per-square-foot over cure-time performance, accepting 8-12 hour drying intervals between coats.
- Institutional:Government housing authorities and infrastructure developers consolidate demand through pre-qualified vendor lists and multi-year supply agreements. BIS IS 5410 certification and proven cure-time performance unlock these channels.
- Commercial:Office and retail developers specify faster-curing alternatives where downtime costs exceed material premiums.
- Industrial:Manufacturing facilities demand chemical-resistant formulations for plant floor and storage area protection.
Residential channels capture volume scale. Institutional procurement yields the highest per-project margins through specification-driven quality premiums.
Technology:
Maturity divides legacy chemistry from emerging platforms with divergent regulatory compliance burdens and performance trade-offs.
- Nano-coating:Hydrophobic silica additives achieve production scale for breathable moisture barriers that outperform conventional cement paint in tropical humidity. High-specification buyers in Kerala and coastal Karnataka specify these for sea-facing concrete structures.
- Water-based:Polymer-modified formulations narrow the performance gap with acrylic emulsion systems while maintaining alkaline resistance. EPA VOC emission limits in the United States channel R&D investment toward these platforms.
- Solvent-based:Faster cure times persist in export markets where VOC regulations remain permissive.
- Eco-friendly:Low-VOC formulations align with GRIHA and IGBC green building certification thresholds in Indian commercial construction.
Water-based technology anchors current production. Nano-coating platforms are climbing the fastest as additive costs decline and toll-manufacturing capacity expands.
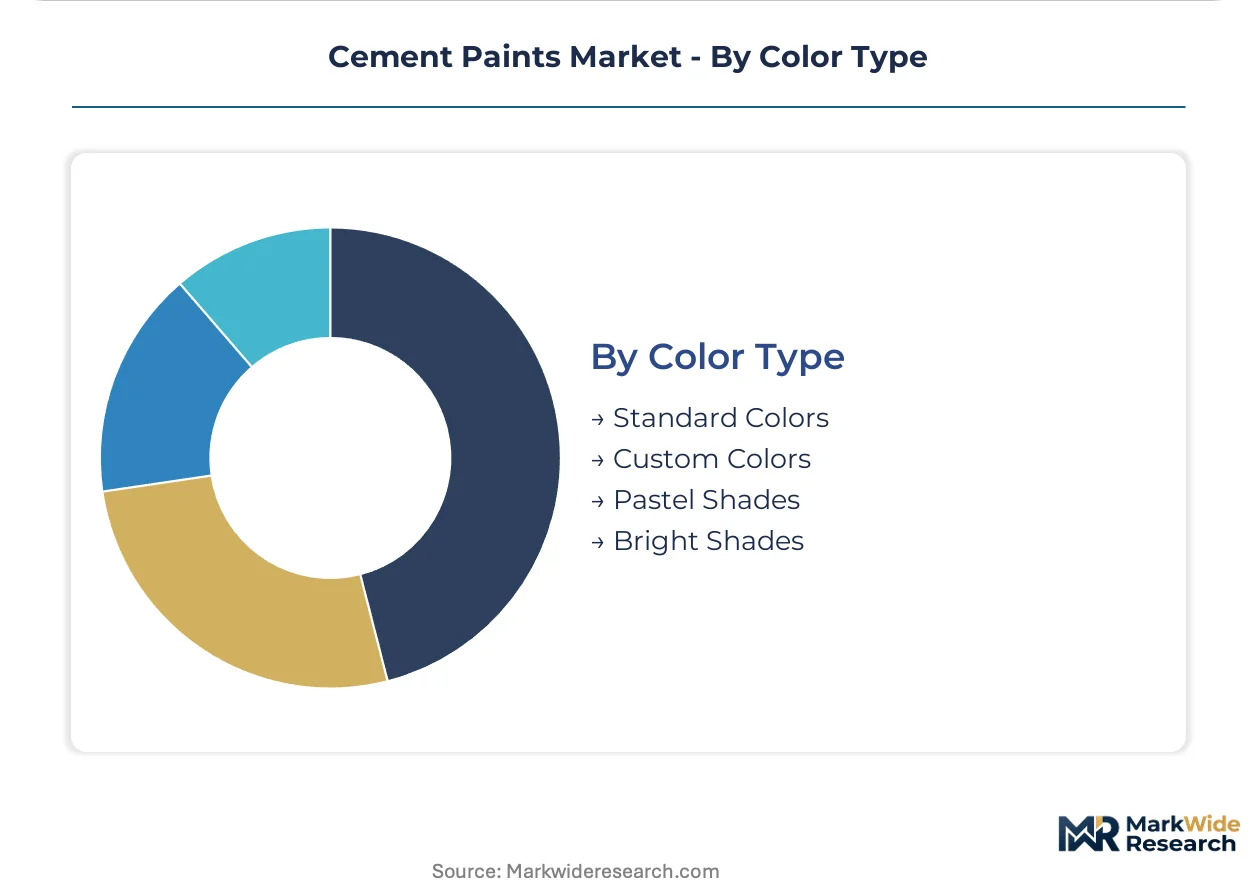
Color Type:
Supply concentration in white cement sourcing shapes tinting-system economics and custom formulation feasibility.
- Standard Colors:Pre-formulated white, off-white, and earth-tone bases minimize tinting infrastructure requirements. Volume production runs through established distribution networks serving cost-sensitive renovation demand.
- Custom Colors:Computerized tinting systems compatible with broader decorative portfolios enable specification matching. Kansai Nerolac competes through integration with its institutional color-matching infrastructure.
- Pastel Shades:Require controlled titanium dioxide loading with REACH disclosure compliance for export-oriented production.
- Bright Shades:Organic pigment stabilization challenges biocide-enhanced formulations under accelerated weathering protocols.
Standard colors dominate unit economics. Custom color capability is gaining share fastest as institutional specification hardens around aesthetic coordination requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian cement paint manufacturers export hydrophobic formulations to Bangladesh, Nepal, and Sri Lanka, where monsoon-driven waterproofing needs replicate domestic demand patterns. Trade flows concentrate through Kolkata and Chennai ports serving South Asian construction markets.
India
Western and southern states generate sustained demand through chronic monsoon exposure and urban housing density. BIS IS 5410 certification mandates for exterior durability pull formulation investment toward biocide-enhanced lines. Mumbai and Bangalore anchor production clusters where government housing procurement consolidates around pre-qualified vendor lists.
China
Infrastructure renewal in coastal provinces drives specification-grade cement paint consumption for concrete protection. GB standards for masonry coatings align with stricter VOC thresholds under dual carbon goals. Shanghai and Guangzhou manufacturing bases supply domestic projects while testing nano-additive scale-up for breathable moisture barriers.
United States
EPA emission limits channel R&D toward water-based platforms that sacrifice alkaline resistance cement chemistry provides. Southwest and Gulf Coast construction activity sustains import demand for tropical-grade waterproofing formulations. Texas and Florida distribution networks handle spot procurement from export-oriented Asian producers.
Germany
REACH titanium dioxide disclosure requirements impose testing costs that favor producers with dedicated regulatory affairs functions. Industrial heritage restoration in North Rhine-Westphalia specifies breathable masonry coatings compatible with historic substrate chemistry. Cologne and Düsseldorf technical centers validate formulation compliance for re-export to EU markets.
Brazil
Tropical humidity in coastal urban corridors drives waterproof paint specification for residential renovation. ANVISA alignment with international chemical disclosure standards extends product registration timelines. São Paulo and Rio de Janeiro construction markets absorb volume from organized retail networks penetrating secondary cities.
Cement Paints Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered market strata. The structure fragments between scale-driven incumbents with distribution depth and mid-tier formulators serving regional procurement clusters. Three archetypes dominate: backward-integrated white cement producers, polymer-modification specialists, and toll-manufacturing operators leveraging shared production assets. Competitive moves center on distribution network expansion into underserved tier-3 cities and regulatory certification pre-positioning for institutional tender participation.
Among India-based decorative coating specialists, Asian Paints, Berger Paints, and Kansai Nerolac Paints occupy positions spanning the volume-premium spectrum. Asian Paints exemplifies channel-control archetype through tier-2 and tier-3 city penetration. Berger Paints represents backward-integration positioning into white cement sourcing. Kansai Nerolac Paints sits within tinting-system compatibility specialization, leveraging institutional color-matching infrastructure. These three anchors illustrate how domestic incumbents defend position against multinational entrants through regulatory familiarity and distribution density.
| Leading Market Players |
|---|
| Asian Paints |
| Berger Paints |
| Kansai Nerolac Paints |
| PPG Industries |
| Jotun Group |
| Sherwin-Williams |
| AkzoNobel |
| BASF Coatings |
| Acro Paints |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Gujarat and Rajasthan white cement clinker operations is compressing input costs for domestic formulators while simultaneously eroding supplier pricing power in the spot market. This utilization slack propagates through contract structures that index raw material baskets to energy and mineral filler costs, creating divergent margin trajectories between backward-integrated producers and toll-manufacturing operators.
Pricing Analysis
Cost-plus contracts with white cement indexation dominate institutional procurement, where BIS-certified exterior grades command premiums over standard renovation formulations. Price differentiation separates biocide-enhanced waterproof lines from economy interior coatings based on cure-time performance and fungal resistance certification. Cost compression in residential spot markets intensifies as Asian Paints and Berger Paints leverage captive sourcing to undercut regional formulators. Homeowners in tier-3 cities exhibit highest price sensitivity, while government housing authorities prioritize proven durability over per-liter cost in multi-year framework agreements.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard as organized distributors finance inventory carrying costs for tier-2 and tier-3 retail networks. Supply concentrates in India, China, and Vietnam, with white Portland cement sourcing anchored in Gujarat and Rajasthan clinker operations. Raw material dependencies center on titanium dioxide for opacity, hydrophobic silica additives for nano-coating platforms, and biocide packages for fungal resistance compliance. Single-source vulnerability in specialized mineral filler dispersion creates supply risk during monsoon logistics disruptions. Distribution runs through organized paint retail networks in western and southern India, with project-direct channels serving institutional procurement clusters in Maharashtra and Tamil Nadu.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cement paints market is recovering from cyclical trough conditions as monsoon-driven renovation cycles and government housing procurement normalize post-pandemic construction schedules.
For Market Incumbents: Insulate formulation margins through captive white cement sourcing and biocide package pre-qualification for accelerated BIS certification timelines. Acrylic emulsion substitution in institutional channels threatens volume retention; defend position through distribution depth in underserved northeastern states and Bihar secondary cities. Polymer-modified R&D investment narrows performance gaps while preserving alkaline resistance differentiation. For New Entrants and Emerging Players: Pursue toll-manufacturing partnerships with established clinker producers to bypass capital-intensive backward integration requirements. Tier-3 city distribution gaps in Uttar Pradesh and northeastern India offer lowest competitive density for organized retail penetration. Specification-driven institutional procurement rewards BIS pre-certification investment with multi-year government housing supply agreements. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among backward-integrated producers with captive white cement supply and pre-qualified vendor status in Maharashtra and Tamil Nadu urban development projects. Long-term viability over a 5-10 year window favors formulators with dedicated regulatory affairs capabilities managing concurrent BIS and REACH compliance timelines. Watch nano-coating additive cost curves as inflection signal for technology migration from premium niche toward mid-tier waterproofing segments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into White Cement Sourcing | Berger Paints exemplifies how captive clinker supply insulates margin compression during energy price volatility. |
| BIS IS 5410 Pre-Certification Investment | Government housing procurement consolidation around pre-qualified vendor lists rewards early compliance with multi-year framework agreements. |
| Nano-Coating Technology Licensing | Hydrophobic silica additive partnerships enable mid-tier formulators to access premium waterproofing performance without proprietary R&D scale. |
| Tier-3 City Distribution Expansion | Asian Paints demonstrates how secondary city penetration in Bihar and Uttar Pradesh captures renovation-driven spot demand with limited organized competition. |
| Polymer-Modification R&D Scale-Up | Water-based formulation investment narrows performance gaps with acrylic emulsion systems while preserving alkaline resistance for masonry substrates. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of BIS certification databases, customs trade records, and white cement producer disclosures to validate market sizing and competitive positioning. Interviews with formulation chemists, procurement leads at government housing authorities, distribution channel partners, and technical R&D directors at established manufacturers informed demand segmentation and pricing dynamics. Secondary sources included SEC filings of multinational coating producers, Indian Paint Association industry reports, and clinker production statistics from Cement Manufacturers' Association. Bottom-up volume estimates from state-level construction activity data were triangulated against top-down value projections derived from manufacturer revenue disclosures.
Forecast inputs incorporate product type segmentation across waterproof, exterior, interior, and textured formulations; application channels spanning residential renovation, institutional procurement, commercial development, and industrial protection; technology platforms including nano-coating, water-based, solvent-based, and eco-friendly chemistry; and regional demand clusters across Indian states and export markets. CAGRs were derived from regression analysis of historical construction spending correlation with coating consumption intensity, adjusted for BIS regulatory implementation timelines and nano-additive commercialization curves. Energy price volatility in clinker production and monsoon seasonality effects on renovation timing served as industry-specific forecast modifiers.
Sensitivities concentrate around BIS standard revision schedules, REACH titanium dioxide disclosure enforcement intensity, and white cement capacity utilization swings in Gujarat and Rajasthan. Forecasts reflect documented assumptions regarding government housing procurement continuity and nano-coating additive cost decline trajectories. Macroeconomic construction slowdown, regulatory timeline acceleration, or breakthrough acrylic emulsion performance parity would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
United Arab Emirates (UAE) Paints and Coatings Market
Paints & Coatings
Europe Automotive Paints and Coatings Market
Paints & Coatings
South America Architectural Coatings Market
Paints & Coatings
South Africa Paints and Coatings Market
Paints & Coatings
Hybrid Paint Cans Market
Paints & Coatings
Metal Paint Tray Market
Paints & Coatings
Bahrain Paints and Coatings Market
Paints & Coatings
Water-Borne Latex Paints Market
Paints & Coatings
Low VOC Paints and Coatings Market
Paints & Coatings
Food Grade Epoxy Paint Market
Paints & Coatings
Architectural Coatings Market
Paints & Coatings
Interior Architectural Coatings Market
Paints & Coatings
Global Decorative Coatings Market
Paints & Coatings
Global Construction Paints and Coatings Market
Paints & Coatings
UAE Architectural Paints and Coatings Market
Paints & Coatings
North America Paints and Coatings Market