
 Paint Defoamers Market | 2026-2036
Paint Defoamers Market Size, Share, and Industry Trends Forecast 2026-2036
Paint Defoamers Market Analytics
Automotive coatings is realigning the paint defoamers value chain as OEMs convert solvent lines to water-based systems. Dow Inc. leverages its silicone chemistry portfolio to anchor supply relationships with tier-one coating formulators in North America. Evonik Industries specializes in polyether-ester hybrids that sustain foam control under high-shear application conditions. BASF SE competes through backward integration into key raw material streams, reducing feedstock cost volatility for European customers.
Paint defoamers are surface-active additives, typically comprising silicone oils, mineral oils, or polyether-modified siloxanes delivered at active contents between 10% and 100%, designed to destabilize foam lamellae during manufacturing and application of liquid coatings. Silicone-based products dominate volume in industrial coatings where extreme defoaming efficiency offsets premium pricing, while acrylic variants lead architectural segments on compatibility with water-based latex systems. Emulsion formulations are gaining share as coating producers seek pourable, low-viscosity concentrates that simplify dosing in automated batch operations.
EPA regulations on volatile organic compound emissions from coating operations constrain solvent-based defoamer use in the United States, while EU REACH and the F-Gas Regulation restrict fluorosilicone chemistries in European formulations. China's MEE enforces progressively tighter limits on hazardous air pollutants from coating facilities, pushing domestic producers toward compliant water-based alternatives. Stakeholders must monitor how regional enforcement intensity shifts manufacturing location decisions and defoamer specification requirements across supply chains.
Market Dynamics
Automotive OEMs in Germany, China, and the United States are converting solvent-based coating lines to water-based systems under tightening EPA and EU REACH volatile organic compound limits. This conversion is concentrating formulation demand around defoamers compatible with high-shear waterborne application equipment.
Growth Catalysts
- EPA VOC regulations:United States coating facilities face progressively stricter emission ceilings. Water-based system adoption accelerates defoamer demand for compliant automotive and industrial applications.
- Automotive OEM coating conversion:Tier-one suppliers in Germany and China are expanding waterborne capacity. This concentrates procurement of silicone-polyether hybrid defoamers for high-speed robotic application lines.
- MEE hazardous air pollutant enforcement:China's Ministry of Ecology and Environment tightens facility-level discharge monitoring. Domestic producers pivot toward compliant water-based alternatives, expanding addressable market for formulated defoamers.
Market Restraints
- Silicone feedstock volatility:Precursor siloxane prices fluctuate with energy costs in European and Chinese manufacturing clusters. Formulators face margin compression when passing through raw material swings.
- EU F-Gas Regulation restriction:Fluorosilicone chemistries face phasedown timelines. European formulators must reformulate with alternative actives, extending qualification cycles and freezing specification decisions.
- Mineral oil substitution ceiling:Architectural coatings in cost-sensitive segments tolerate only limited silicone loading. Price-performance tradeoffs cap premium defoamer penetration in residential construction applications.
Strategic Opportunities
- India industrial coatings expansion:Domestic automotive and protective coatings output rises under PLI scheme incentives. Defoamer suppliers can establish formulation partnerships before specification standards crystallize.
- Emulsion concentrate format adoption:Automated batch operations favor pourable, low-viscosity products. Suppliers capturing dosing-system integration relationships gain switching friction against incumbent drum deliveries.
- EU Green Deal sustainable chemistry mandate:Bio-based polyether feedstocks qualify for preferential procurement scoring. Early certification with ECHA-recognized assessment frameworks opens premium specification channels.
Industry Challenges
- Application engineering talent scarcity:Formulation chemists with simultaneous expertise in silicone chemistry and waterborne rheology command premium compensation. Hiring bottlenecks slow regional technical service expansion.
- Multi-regulatory qualification overlap:Suppliers serving automotive OEMs must maintain parallel EPA, REACH, and GB standard registrations. Documentation maintenance consumes technical resources without incremental revenue capture.
- Legacy solvent-system inventory amortization:Coatings producers with sunk capital in solvent-based lines delay full waterborne conversion. Defoamer suppliers face extended dual-formulation support obligations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paint Defoamers Market |
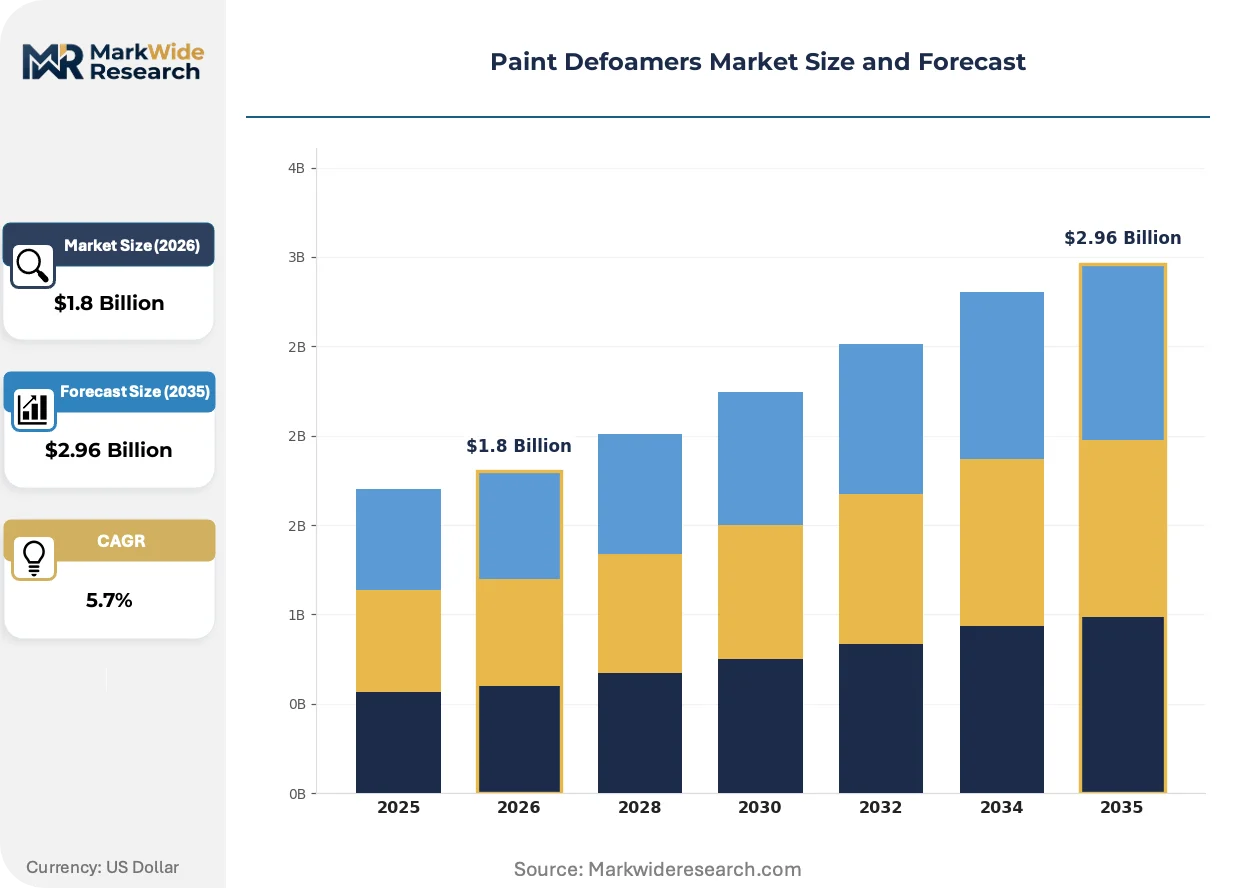
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Silicone, Polyether, Others Application: Architectural Coatings, Industrial Coatings, Wood Coatings, Automotive Coatings Formulation Type: Water-Based, Solvent-Based, Powder-Based, Emulsion End User Industry: Construction, Automotive, Marine, Aerospace |
| Companies Covered | Dow Inc., Shin-Etsu Chemical, Evonik Industries, Wacker Chemie AG, Momentive Performance Materials, BYK-Chemie GmbH, Elementis PLC, Lubrizol Corporation, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paint Defoamers Market Evolving Landscape
Waterborne coating chemistry is absorbing innovation investment as regulatory pressure and application performance requirements converge. Formulation technology, compliance architecture, and procurement systems are each undergoing structural recalibration.
Polyether-modified siloxane technology is absorbing the bulk of automotive OEM qualification resources. These hybrids deliver defoaming efficiency under high-shear spray conditions while maintaining compatibility with waterborne resin systems. Tier-one formulators in Germany and the United States are locking in multi-year supply agreements for validated grades. The technology is absorbing volume share from legacy mineral oil products in industrial maintenance coatings.
EU REACH authorization requirements are extending compliance timelines for novel silicone chemistries. Substance evaluation dossiers now demand expanded ecotoxicology data packages before industrial use approvals. Specialty coatings segments serving aerospace and marine applications face the longest qualification delays. Formulators are responding by accelerating substitution programs toward pre-registered polyether-ester architectures.
Coatings producers are consolidating supplier panels to reduce formulation complexity and audit burden. Single-source relationships with defoamer suppliers offering integrated technical service are displacing multi-vendor spot purchasing. This concentration is most visible in United States automotive OEM supply chains, where tier-one formulators prioritize suppliers with in-house application laboratories and rapid batch troubleshooting capability.
Paint Defoamers Market Segmentation
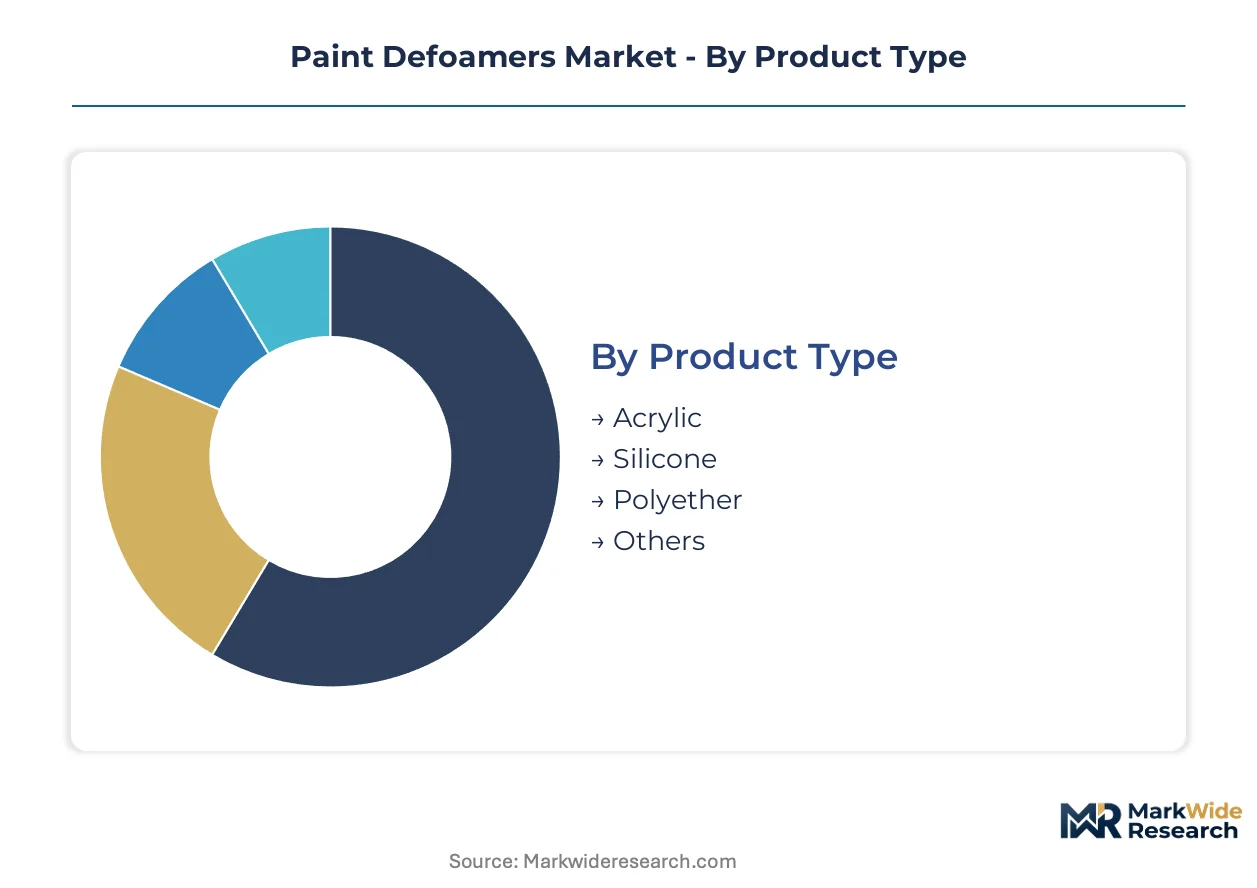
Defoamer specification varies sharply across coating chemistries and application equipment. Formulators select active ingredients and delivery formats based on shear intensity, resin compatibility, and regulatory constraints governing the end-use environment.
Product Type:
Silicone chemistry dominates industrial specifications while acrylic variants anchor architectural compatibility requirements.
- Silicone:Polydimethylsiloxane and modified siloxane actives deliver maximum defoaming efficiency under extreme shear. Demand concentrates in automotive OEM clearcoat lines in Germany and the United States, where robotic spray systems generate foam at pressures exceeding 200 bar.
- Acrylic:Hydrophobic acrylic copolymers provide controlled foam suppression without surface defects in latex systems. Procurement clusters with residential construction formulators in China, driven by MEE enforcement pushing waterborne interior paint adoption.
- Polyether:Block copolymer architectures balance compatibility across diverse resin chemistries.
- Others:Mineral oil and vegetable oil derivatives serve cost-sensitive industrial maintenance segments.
Mature deployment sits with Silicone. Newer deployment is concentrated in Acrylic.
Application:
End-use performance requirements create divergent specification hierarchies based on film quality tolerances and production speeds.
- Automotive Coatings:Multi-layer waterborne systems demand defoamers validated through OEM qualification protocols. Specification authority rests with tier-one formulators in Stuttgart, Shanghai, and Detroit who maintain approved supplier lists with 18-24 month validation cycles.
- Industrial Coatings:Protective and marine applications prioritize defoaming persistence through extended pot life. Demand concentrates in shipyard clusters along China's eastern seaboard and the US Gulf Coast, where high-build epoxy applications generate sustained foam.
- Architectural Coatings:Volume leadership in residential and commercial building finishes.
- Wood Coatings:Furniture and flooring segments requiring stain resistance compatibility.
Specification maturity clusters with Automotive Coatings. Volume expansion is climbing the fastest in Industrial Coatings.
Formulation Type:
Carrier chemistry determines regulatory compliance pathways and equipment integration options.
- Water-Based:Surfactant-stabilized dispersions integrate directly into waterborne resin systems. Procurement is accelerating with automotive OEM conversions in Germany and the United States under EPA and EU REACH VOC limits.
- Emulsion:Low-viscosity pourable concentrates enable automated dosing in batch operations. Adoption concentrates with large-scale architectural producers in China seeking labor cost reduction through dosing system integration.
- Solvent-Based:Declining share constrained by emissions regulations across major manufacturing regions.
- Powder-Based:Solid carrier systems for powder coating applications.
Established volume sits with Water-Based. Format innovation is concentrating in Emulsion.
End User Industry:
Industry-specific certification requirements and exposure conditions shape defoamer selection criteria.
- Automotive:OEM specification systems mandate traceable batch consistency and application laboratory support. Procurement relationships lock in with suppliers maintaining technical service centers near production clusters in Wolfsburg, Shanghai, and Michigan.
- Construction:Architectural coating demand tracks residential and commercial building cycles. Specification authority rests with national distributors in China and the United States who influence contractor-grade product selection.
- Marine:Antifouling and protective systems requiring saltwater resistance validation.
- Aerospace:Qualification-intensive segment with extended approval timelines under OEM material specifications.
Procurement consolidation is most advanced with Automotive. Specification evolution is gaining share fastest in Construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in China's Yangtze River Delta and Germany's industrial heartland concentrate defoamer formulation capacity near automotive OEM coating clusters. Tax incentives and streamlined environmental permitting in these zones accelerate supplier co-location with tier-one formulators.
United States
Automotive OEM conversion to waterborne coating lines in Michigan and Ohio drives formulation demand. EPA VOC emission ceilings under the National Emission Standards for Hazardous Air Pollutants tighten facility-level compliance. Detroit-area technical service centers from major suppliers support robotic spray line qualification.
Germany
Stuttgart and Wolfsburg automotive clusters anchor European demand for high-shear compatible defoamers. EU REACH substance authorization timelines extend qualification cycles for novel silicone chemistries. BASF SE's Ludwigshafen complex exemplifies backward integration into siloxane feedstocks serving regional formulators.
China
Shanghai and Guangzhou coating formulators expand waterborne capacity under MEE hazardous air pollutant enforcement. GB standards alignment with international automotive OEM specifications enables export-oriented production. Yangtze River Delta special economic zones offer preferential treatment for imported silicone precursor processing.
India
PLI scheme incentives accelerate domestic automotive and protective coatings output in Maharashtra and Gujarat. BIS certification requirements for imported defoamer formulations create localization pressure. Pune and Chennai industrial corridors attract technical service investments from multinational suppliers.
Japan
Kansai region automotive suppliers maintain stringent OEM qualification protocols for coating additives. METI industrial standards guide defoamer specification in export-oriented production. Osaka-based chemical companies specialize in polyether-modified siloxane architectures for precision application equipment.
Paint Defoamers Market Competitive Landscape
Top-tier vendors anchor supply relationships with tier-one coating formulators, while mid-scale specialists occupy niche compatibility segments. The market exhibits moderate consolidation around integrated silicone producers and diversified chemical conglomerates. Three archetypes dominate: backward-integrated feedstock controllers, application-technical-service specialists, and regional formulation partners. Competitive moves concentrate on multi-year supply agreement lock-ins and in-house application laboratory expansion near OEM clusters.
Among German chemical conglomerates, BASF SE and Evonik Industries exemplify contrasting strategic positions. BASF SE occupies the integrated-feedstock archetype through captive siloxane production. Evonik Industries represents the application-engineering specialist model with polyether-ester hybrid focus. Dow Inc. anchors the North American tier-one supplier position through silicone chemistry breadth. These three entities illustrate how geographic origin and corporate structure shape competitive positioning in automotive OEM qualification channels.
| Leading Market Players |
|---|
| Dow Inc. |
| Shin-Etsu Chemical |
| Evonik Industries |
| Wacker Chemie AG |
| Momentive Performance Materials |
| BYK-Chemie GmbH |
| Elementis PLC |
| Lubrizol Corporation |
| BASF SE |
| Others |
Value Network & Pricing Analysis
Siloxane precursor costs cascade through three pricing tiers as automotive OEMs in Germany and China negotiate multi-year supply agreements with tier-one formulators. Premium grades validated for high-shear robotic lines command sustained margins, while mineral oil alternatives face compression in residential construction segments.
Pricing Analysis
Short lead-time premiums separate validated silicone-polyether hybrids from spot-market mineral oil alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with automotive OEM procurement locking in long-term contracts. Cost compression in economy tiers is intensifying because architectural formulators in China tolerate limited silicone loading. Residential construction buyers exhibit highest price sensitivity; automotive tier-one suppliers show lowest.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme and China's MEE enforcement are reshaping sourcing toward localized formulation capacity. Manufacturing concentrates in Germany, China, and the United States near automotive coating clusters. Supply chains draw from siloxane feedstocks, polyether intermediates, and surfactant carriers. Single-source vulnerability sits with European siloxane production exposed to energy cost volatility. Distribution runs through technical service centers co-located with OEM formulator laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Waterborne coating chemistry is displacing solvent-based systems as the dominant technology platform, creating asymmetric opportunities across incumbent defense and entrant attack strategies.
For Market Incumbents: To counter mineral oil substitution ceilings in cost-sensitive architectural segments, BASF SE and Dow Inc. should deepen backward integration into siloxane feedstocks and expand application laboratories near Stuttgart and Shanghai automotive clusters. Certification investment in ECHA-recognized bio-based polyether frameworks secures preferential EU Green Deal procurement scoring.
For New Entrants and Emerging Players: Tier-two architectural distributors in India's Maharashtra and Gujarat industrial corridors represent the most penetrable channel partner type for establishing formulation partnerships before BIS certification standards crystallize. White-space targets include emulsion concentrate dosing-system integration and PLI-linked domestic production incentives.
For Investors and Strategic Acquirers: Multi-year supply agreement announcements between silicone producers and automotive OEM formulators are the leading indicator that qualification cycles are closing and switching costs are hardening. Long-term viability favors application-engineering specialists with polyether-ester hybrid portfolios over commodity mineral oil suppliers. Watch for EPA enforcement intensity shifts as the signal for regional manufacturing relocation decisions.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Siloxane Feedstocks | BASF SE's Ludwigshafen complex reduces feedstock cost volatility for European automotive formulators. |
| Emulsion Concentrate Format Development | Low-viscosity pourable products enable automated dosing integration with Chinese architectural producers. |
| Application Laboratory Expansion | Technical service centers near Detroit and Shanghai support robotic spray line qualification cycles. |
| Bio-Based Polyether Certification | ECHA-recognized assessment frameworks open premium specification channels under EU Green Deal mandates. |
| Long-Term Supply Agreement Lock-Ins | Multi-year contracts with tier-one formulators harden switching costs in automotive OEM qualification channels. |
Research Methodology
Multi-period observation of EPA enforcement actions, EU REACH authorization timelines, and MEE facility discharge monitoring anchored the trend analysis, supplemented by interviews with coating formulator procurement leads, technical R&D directors at silicone producers, automotive OEM platform engineers, and architectural distributor category managers. Secondary validation drew from EPA National Emission Standards filings, ECHA substance evaluation dossiers, Chinese customs trade data, and SEC 10-K disclosures from listed chemical conglomerates. Bottom-up volume modeling triangulated against top-down market sizing across product type, application, and regional production hub dimensions.
Input-output matrices mapped siloxane feedstock availability through formulation capacity to end-use demand across the analysis window. Segmentation dimensions modeled include chemistry type, coating application, formulation carrier, and end-user industry vertical. CAGRs were derived from regression analysis of historical volume trends against regulatory enforcement intensity indices and OEM capacity conversion announcements. Forecast inputs incorporated automotive production forecasts and residential construction permit data.
Caveats apply where EPA enforcement intensity shifts, EU F-Gas Regulation phasedown acceleration, or Chinese MEE audit schedule changes could materially shift the outlook. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Epoxy Paint Thinner Market
Paints & Coatings
Middle East and Africa Floor Coatings Market
Paints & Coatings
India Automotive Paints and Coatings Market
Paints & Coatings
Radar Absorbing Paint Market
Paints & Coatings
GCC Paints and Coatings Market
Paints & Coatings
Wall Putty Powder Market
Paints & Coatings
Low VOC Paints and Coatings Market
Paints & Coatings
Fire Resistant Paints Market
Paints & Coatings
Road Marking Paint Market
Paints & Coatings
Refinish Paint Market
Paints & Coatings
Food Grade Epoxy Paint Market
Paints & Coatings
Mosquito-Repellent Paints Market
Paints & Coatings
Nordic Countries Architectural Coatings Market
Paints & Coatings
Asia-Pacific Paints and Coatings Additives Market
Paints & Coatings
Global Antifouling Paints and Coatings Market
Paints & Coatings
Faux Finish Coatings Market