
 Global Synthetic Tackifier Market | 2026-2036
Global Synthetic Tackifier Market Size, Share, and Industry Trends Forecast 2026-2036
Global Synthetic Tackifier Market Outlook
Asian petrochemical producers is recalibrating synthetic tackifier supply chains as regional refinery integration deepens. Kraton Corporation leverages hydrogenated styrenic block copolymer technology to sustain premium positioning in medical and hygiene adhesives. ExxonMobil Chemical anchors global polybutylene capacity through Gulf Coast cracking infrastructure and downstream derivative control. Eastman Chemical Company differentiates via specialized amorphous polyolefin grades for pressure-sensitive tape applications.
Synthetic tackifiers are low-molecular-weight resins, typically with softening points between 80°C and 150°C, formulated to enhance the tack and peel adhesion of elastomer-based adhesive systems. These materials function by reducing the elastic modulus of the base polymer matrix, enabling instantaneous surface wetting and bond formation under light pressure. Styrenic block copolymers command the largest volume share due to their compatibility with both SIS and SBS rubber platforms across hot melt and solvent-borne applications. Water-based formulations are gaining fastest as environmental compliance tightens, though solvent-based systems still capture margin pools in high-performance automotive and electronics bonding where drying speed and moisture resistance dominate specification requirements.
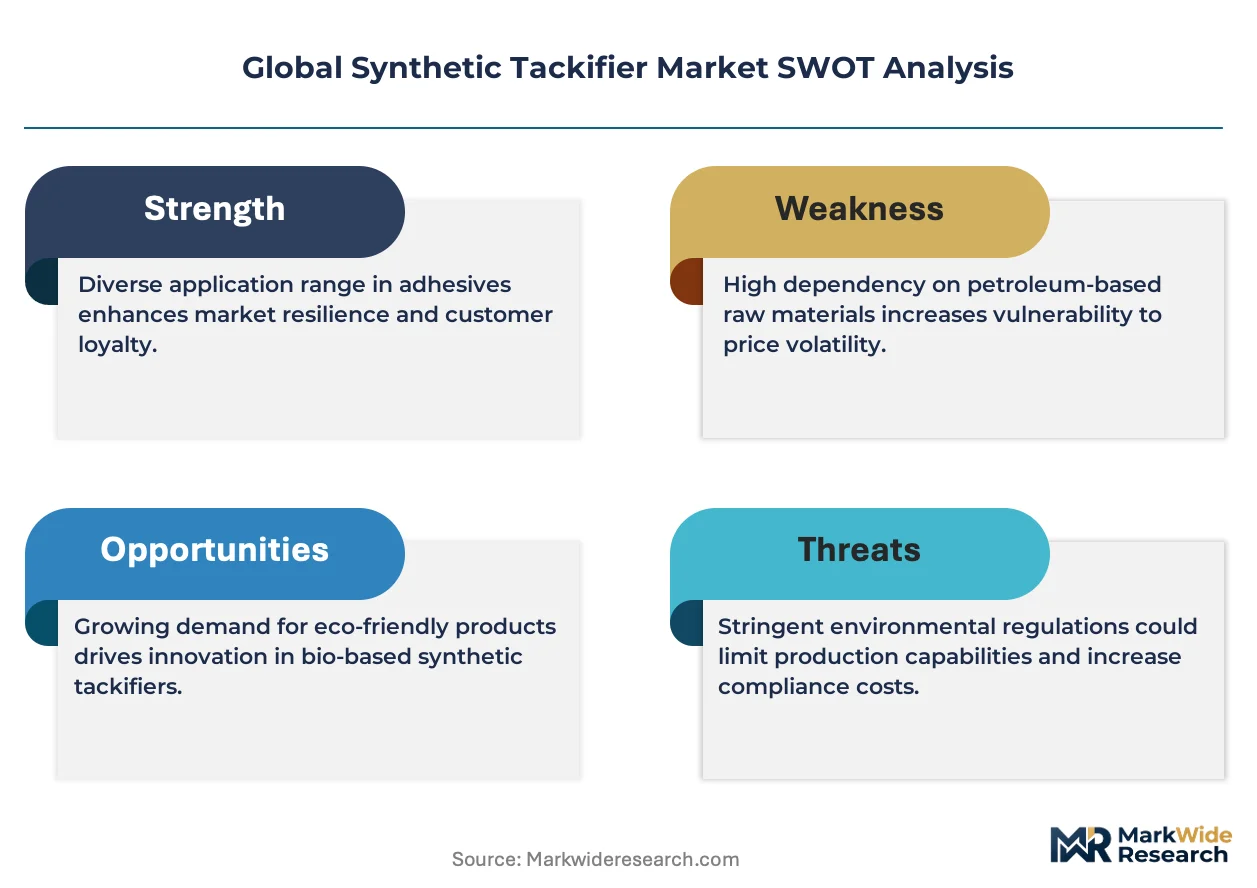
EPA VOC emission standards and REACH substance restrictions are forcing reformulation across North American and European adhesive operations, elevating demand for hydrogenated and water-dispersible tackifier grades. China's MEE environmental enforcement and GB standards on industrial emissions are similarly constraining conventional aromatic resin production, redirecting investment toward hydrogenated polycyclopentadiene and pale-colored polyterpene alternatives. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance asymmetries are fragmenting product portfolios and reshaping regional supply qualifications.
Market Dynamics
Hot melt adhesive consumption in automotive assembly is compressing formulation windows, forcing tackifier producers to balance hydrogenation depth against softening point precision while EPA VOC rules and REACH substance restrictions simultaneously tighten.
Growth Catalysts
- Automotive lightweighting mandates:Hot melt adhesive bonding of composite panels in electric vehicle manufacturing is pulling hydrogenated styrenic block copolymer grades into structural applications previously dominated by mechanical fasteners.
- REACH authorization timelines:European chemical substance restrictions on conventional aromatic tackifiers are redirecting formulation investment toward pale-colored polyterpene and hydrogenated polycyclopentadiene alternatives.
- China packaging sector scale:Domestic adhesive production expansion around Shanghai and Guangdong is absorbing polyamide and polyethylene tackifier resins at volumes that reshape regional import dependency.
Market Restraints
- Crude C5 fraction volatility:Aliphatic resin feedstock costs swing with naphtha cracking economics, compressing margin predictability for producers without backward integration into refinery operations.
- South Korean supply concentration:Hydrogenated tackifier capacity clusters among three petrochemical groups, creating qualification bottlenecks when plant turnarounds coincide with seasonal demand peaks.
- Water-based performance ceiling:Moisture resistance and open-time limitations prevent water-dispersible grades from penetrating high-speed electronics bonding where solvent-based systems retain specification lock-in.
Strategic Opportunities
- India medical adhesive localization:CDSCO device manufacturing incentives and tariff structures on imported resins create openings for domestic hydrogenated tackifier production serving hygiene and wound-care applications.
- Reactive polyurethane hot melts:Moisture-curing PUR technology convergence with tackified formulations is opening durable goods assembly segments requiring structural bond strength with thermoset characteristics.
- EU Green Deal carbon border adjustments:Embedded emissions accounting for imported resins favors European producers with renewable feedstock integration and hydrogen supply from electrolysis.
Industry Challenges
- Hydrogenation catalyst expertise scarcity:Precious metal catalyst management and selective hydrogenation process control require specialized chemical engineering talent concentrated among legacy petrochemical operators.
- Multijurisdictional qualification timelines:Separate EPA SNAP, REACH registration, and China MEE new chemical notification processes extend product commercialization cycles to 24-36 months for novel tackifier grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Synthetic Tackifier Market |
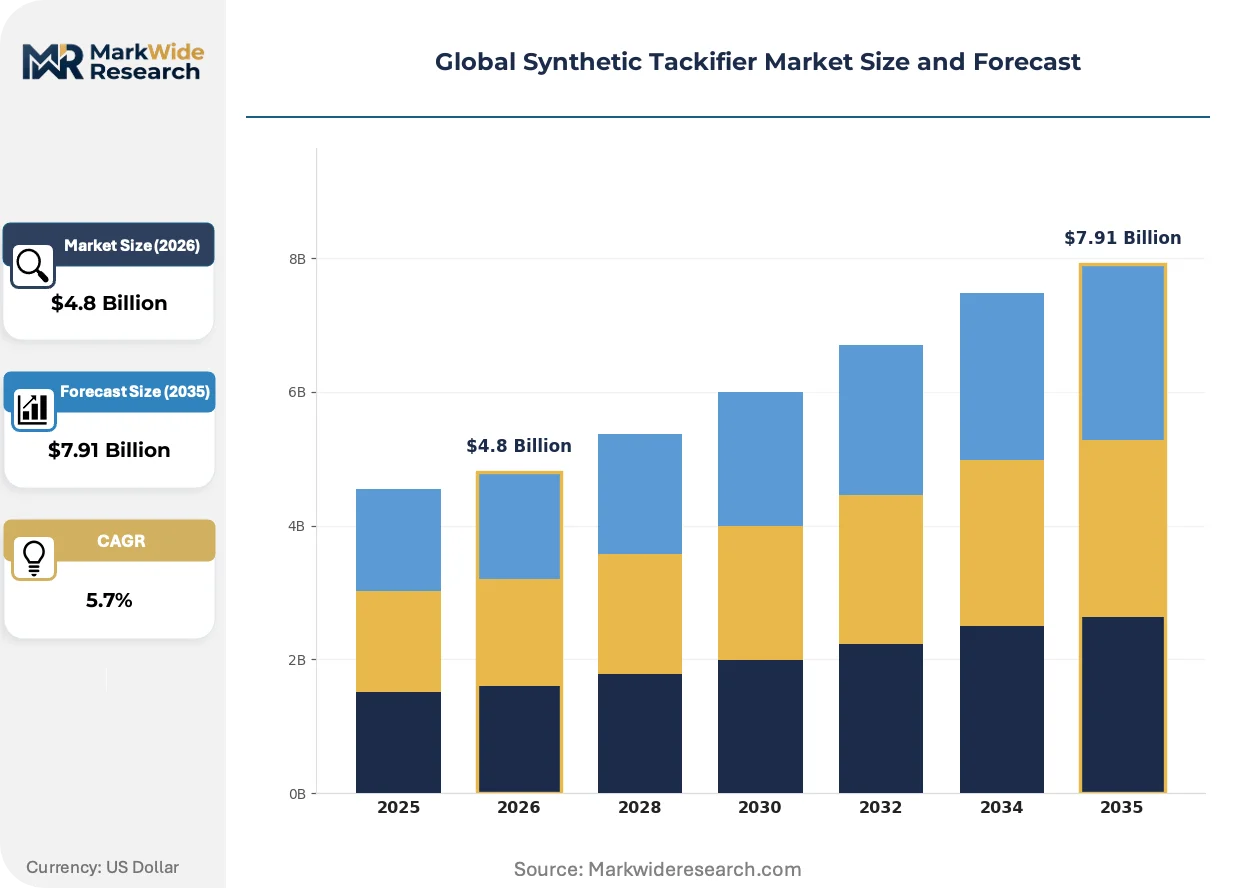
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyamide, Polybutylene, Styrenic Block Copolymers, Polyethylene Application: Adhesives, Coatings, Sealants, Printing Inks End User: Construction, Automotive, Electronics, Packaging Formulation: Water-Based, Solvent-Based, Hot Melt, Reactive |
| Companies Covered | Kraton Corporation, ZEON Corporation, ExxonMobil Chemical, Arakawa Chemical Industries, DRT, Eastman Chemical Company, Arkema, SI Group, Kolon Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Synthetic Tackifier Market Strategic Shifts
Formulation chemistry is pivoting toward reactive and hydrogenated architectures as environmental compliance tightens across adhesive-consuming industries. Three interconnected developments are compressing traditional product lifecycles.
Partially hydrogenated dicyclopentadiene resin technology is rewriting specification standards in pressure-sensitive tape and label applications. Packaging converters in Germany and Japan are adopting these grades at accelerating rates to meet recycled-content adhesives mandates. The technology is rewriting competitive positioning by enabling pale color and oxidative stability without full hydrogenation cost burdens.
EPA VOC emission standards under the Clean Air Act are forcing North American adhesive compounders to eliminate aromatic solvent carriers from spray and roll-coat operations. Industrial consequence includes accelerated capital deployment into water-borne dispersion equipment and hot melt tank systems. Pressure-sensitive adhesive manufacturers in Ohio and Michigan are responding with qualified hydrogenated hydrocarbon resin grades that maintain tack performance in high-solids formulations.
Consolidated buying by multinational hygiene product manufacturers is compressing supplier qualification cycles and unbundling technical service from resin supply contracts. Tier-one adhesive compounders now demand direct raw material integration with real-time inventory visibility replacing quarterly purchase orders. This pattern is most visible in the US Southeast and coastal China where Procter & Gamble, Kimberly-Clark, and their contract manufacturers concentrate purchasing leverage.
Global Synthetic Tackifier Market Segmentation
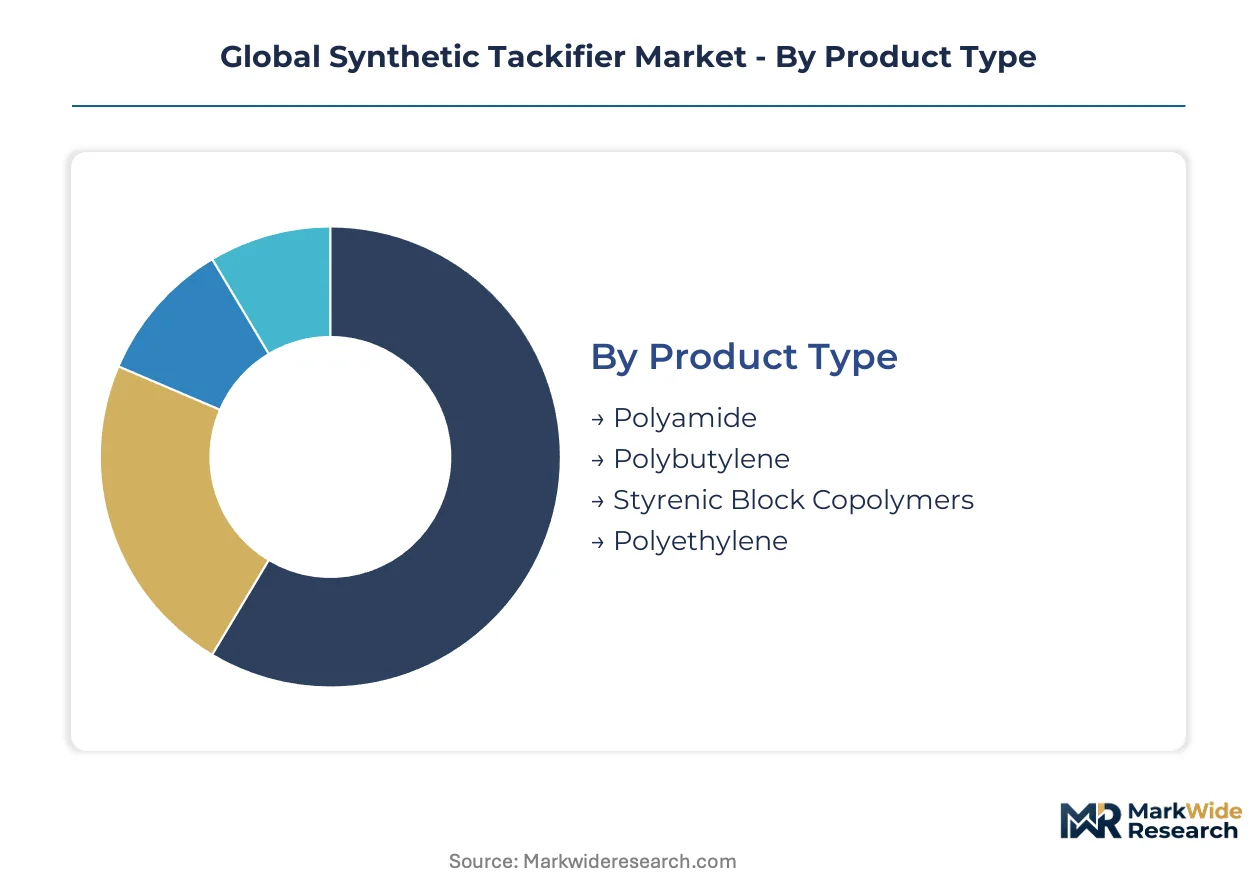
Synthetic tackifier procurement patterns diverge sharply across product chemistry, application performance requirements, and environmental compliance obligations. Buyers segment supply by hydrogenation depth, softening point precision, and regulatory qualification status rather than commodity resin characteristics alone.
Product Type:
Cost tier differentiation separates specification-grade buyers seeking oxidative stability from volume purchasers prioritizing feedstock proximity.
- Styrenic Block Copolymers:Hydrogenated SEBS and SIS grades dominate hot melt adhesive formulations with softening points between 85°C and 140°C. Automotive assembly plants in Stuttgart, Shanghai, and Detroit specify these resins for composite panel bonding where VOC compliance and thermal stability converge.
- Polybutylene:Amorphous polyolefin tackifiers derived from C4 cracking streams offer low color and narrow molecular weight distribution. Pressure-sensitive tape manufacturers in Osaka and Cleveland qualify these grades for medical and electronics applications demanding minimal extractables.
- Polyamide:Dimer acid-based resins serve high-temperature hot melt packaging adhesives with softening points exceeding 150°C.
- Polyethylene:Oxidized PE grades provide cost-positioned tackification for construction adhesives and carpet backing compounds.
Styrenic block copolymers lead volumes today; polybutylene is gaining share fastest in medical and hygiene qualification pipelines.
Application:
Volume concentration tracks directly to end-use moisture resistance requirements and line speed economics.
- Adhesives:Hot melt and pressure-sensitive systems consume the majority of hydrogenated hydrocarbon resin output. German packaging converters and US Southeast hygiene manufacturers drive specification toward pale-colored, low-odor grades meeting recycled-content mandates.
- Sealants:Construction and automotive seam sealers require tackifiers with plasticizer compatibility and UV resistance. Japanese automotive suppliers specify hydrogenated DCPD resins for body-in-white applications.
- Coatings:Industrial maintenance and protective coatings incorporate aliphatic tackifiers for adhesion promotion on low-energy substrates.
- Printing Inks:Flexographic and gravure ink formulations utilize rosin ester and hydrocarbon tackifiers for solvent release and gloss control.
Adhesives commands absolute volume; sealants shows the steepest expansion trajectory as automotive structural bonding displaces mechanical fasteners.
End User:
Customer type determines qualification burden, with medical and automotive segments imposing 18-36 month approval timelines versus commodity packaging.
- Automotive:Electric vehicle lightweighting mandates are pulling hydrogenated tackifiers into structural bonding applications. Tesla, BYD, and Volkswagen Group assembly operations specify SEBS-based hot melts for battery module encapsulation and composite body panels.
- Packaging:E-commerce fulfillment expansion and corrugated box demand in China, Germany, and the US Southeast are compressing adhesive open-time requirements. Domestic Chinese resin production is displacing imports for polyamide hot melt grades.
- Construction:Flooring, carpet, and insulation adhesives utilize cost-optimized aliphatic and aromatic hydrocarbon tackifiers.
- Electronics:Miniaturization and thermal management requirements limit tackifier penetration to specialized thermal interface and display bonding applications.
Packaging leads volumes today; automotive is climbing the fastest as structural adhesive specifications proliferate.
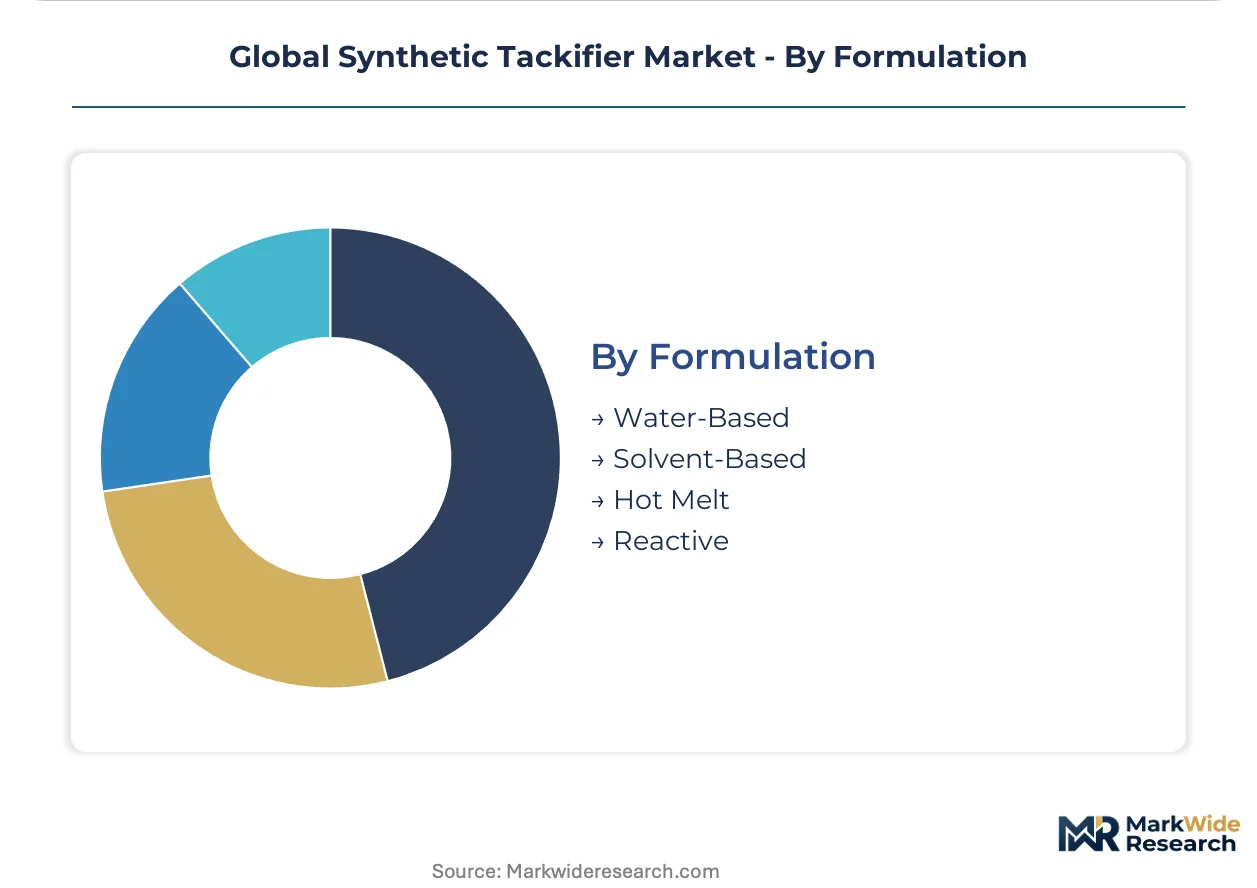
Formulation:
Margin structure inverts across formulation types, with water-based systems capturing sustainability premiums despite performance constraints.
- Hot Melt:100% solids formulations dominate automotive, packaging, and hygiene applications for instant green strength and solvent-free operation. European REACH compliance and EPA VOC regulations are accelerating hydrogenated hydrocarbon resin adoption.
- Water-Based:Emulsion tackifiers are gaining share in paper converting and label applications where sprayable application and cleanup economics matter. Performance ceilings in moisture resistance and open time constrain electronics penetration.
- Solvent-Based:High-solids aromatic systems retain specification lock-in for electronics bonding and aerospace applications where drying speed and chemical resistance dominate.
- Reactive:Moisture-curing polyurethane hot melts with tackified formulations are opening durable goods assembly requiring structural bond strength with thermoset characteristics.
Hot melt leads volumes today; water-based is expanding most quickly as environmental compliance tightens across North American and European operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's packaging sector expansion contrasts with Germany's automotive-driven specification tightening, while the United States balances EPA VOC enforcement against Gulf Coast feedstock advantages. Each geography shapes distinct procurement patterns for hydrogenated and water-based tackifier grades.
China
Domestic adhesive production around Shanghai and Guangdong is absorbing polyamide and polyethylene tackifier resins at volumes that reshape regional import dependency. MEE environmental enforcement and GB standards on industrial emissions constrain conventional aromatic resin production. Hydrogenated polycyclopentadiene capacity is expanding in Jiangsu province to serve e-commerce fulfillment and corrugated box demand.
United States
EPA VOC regulations under the Clean Air Act are redirecting formulation investment toward water-based and reactive systems in Ohio and Michigan industrial corridors. REACH compliance asymmetries fragment product portfolios for exporters serving European automotive customers. Gulf Coast cracking infrastructure anchors ExxonMobil Chemical's polybutylene capacity and downstream derivative control.
Germany
REACH authorization timelines on conventional aromatic tackifiers are accelerating pale-colored polyterpene and hydrogenated DCPD adoption among Stuttgart-area automotive assembly plants. EU Green Deal carbon border adjustments favor domestic producers with renewable feedstock integration. Packaging converters in Bavaria specify partially hydrogenated resins to meet recycled-content adhesives mandates.
Japan
Osaka-based pressure-sensitive tape manufacturers qualify polybutylene grades for medical and electronics applications demanding minimal extractables. METI industrial standards shape hydrogenation depth requirements for hygiene product adhesives. Japanese automotive suppliers specify hydrogenated DCPD resins for body-in-white seam sealing applications.
South Korea
Hydrogenated tackifier capacity clusters among three petrochemical groups, creating qualification bottlenecks when plant turnarounds coincide with seasonal demand peaks. MFDS medical device regulations extend approval timelines for hygiene and wound-care adhesive formulations. Busan-Ulsan industrial complexes concentrate hydrogenation catalyst expertise and selective process control capabilities.
Global Synthetic Tackifier Market Competitive Environment
United States producers anchor one tier; Asian specialists hold hydrogenation depth advantages. The vendor base separates into consolidated petrochemical majors with refinery integration and focused resin specialists with formulation chemistry expertise. Three archetypes dominate: Gulf Coast-integrated hydrocarbon resin producers, Japanese and Korean hydrogenation technology specialists, and European pale-grade innovators serving REACH-constrained markets. Capacity expansion and strategic partnerships represent the dominant competitive moves as qualification timelines extend.
Among United States-based chemical majors, ExxonMobil Chemical and Eastman Chemical Company exemplify the integrated archetype with Gulf Coast feedstock access and downstream derivative control. Kraton Corporation represents the specialty hydrogenated styrenic block copolymer tier serving medical and hygiene adhesive specifications. Asian specialists including ZEON Corporation, Arakawa Chemical Industries, and Kolon Industries occupy positions concentrated in hydrogenation catalyst expertise and selective process control. These groupings reflect geographic clustering of technical capabilities rather than uniform strategic approaches.
| Leading Market Players |
|---|
| Kraton Corporation |
| ZEON Corporation |
| ExxonMobil Chemical |
| Arakawa Chemical Industries |
| DRT |
| Eastman Chemical Company |
| Arkema |
| SI Group |
| Kolon Industries |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal carbon border adjustments gate qualified supply and premium-tier pricing access for hydrogenated tackifier grades, favoring European producers with renewable feedstock integration while Asian exporters face embedded emissions accounting penalties that compress margin structures.
Pricing Analysis
Capacity additions in Jiangsu province are reshaping price floors for hydrogenated polycyclopentadiene grades, compressing margins for legacy producers without refinery integration. Three-tier pricing structure across premium hydrogenated, standard pale-grade, and economy aromatic tiers separates specification buyers from volume purchasers. Price differentiation hinges on hydrogenation depth and REACH qualification status. Cost compression in economy aromatic tiers is intensifying because MEE environmental enforcement in China constrains conventional resin production.
Supply Chain Analysis
Regional distribution centers in Busan, Rotterdam, and Houston anchor hub-and-spoke patterns for hydrogenated tackifier grades serving automotive and hygiene adhesive compounders. Geographic supply concentrates in South Korea, China, and the United States Gulf Coast. Raw material flows draw from C5 cracking streams, precious metal catalysts, and dimer acid feedstocks. Single-source vulnerability clusters around three South Korean petrochemical groups. Distribution runs through qualified direct-supply contracts with real-time inventory visibility replacing quarterly purchase orders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The synthetic tackifier market functions as a geographic-arbitrage play between South Korean hydrogenation expertise and Chinese domestic production scale, with EPA VOC compliance costs in the United States creating 15-20% cost differentials against imported Asian resins.
For Market Incumbents: Lock in backward integration into Gulf Coast C5 fraction supply or Jiangsu province hydrogenation capacity to defend margin position against emerging Chinese domestic producers. Secure REACH registration renewals ahead of authorization timelines to maintain European automotive qualification pipelines. For New Entrants and Emerging Players: Begin with India medical adhesive localization targeting CDSCO device manufacturing incentives and tariff-protected hygiene resin demand. The most penetrable white-space sits in domestic hydrogenated tackifier production for wound-care applications, accessed through joint development agreements with contract manufacturers. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap hydrogenation technology specialists because qualification timelines extend to 24-36 months and create captive customer relationships. Long-term viability favors targets with selective hydrogenation process control and precious metal catalyst management capabilities. The signal to watch is EPA SNAP approval velocity for novel water-dispersible grades.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into C5 Cracking | ExxonMobil Chemical anchors margin control through Gulf Coast refinery infrastructure. |
| Hydrogenation Capacity Expansion | Kolon Industries concentrates selective process expertise in Busan-Ulsan industrial complexes. |
| REACH-Compliant Grade Development | Eastman Chemical captures premium positioning via pale-colored polyterpene alternatives for German automotive. |
| Water-Dispersible Formulation Investment | Kraton Corporation sustains medical and hygiene specifications through hydrogenated SEBS technology. |
| Regional Distribution Hub Establishment | ZEON Corporation qualifies polybutylene grades for Osaka pressure-sensitive tape manufacturers. |
Study Parameters
Multiple input streams — primary interviews with adhesive compounders and procurement leads, secondary validation through customs trade data and SEC chemical sector filings, and technical specification review — were reconciled to construct demand estimates. Stakeholder roles included hot melt adhesive R&D directors, automotive Tier 1 supplier procurement managers, hygiene product contract manufacturing executives, and hydrogenation plant operations heads. Secondary sources encompassed ECHA REACH registration databases, EPA VOC compliance filings, China MEE emission standard disclosures, and industry association reports from ACC and Cefic. Bottom-up resin consumption modeling and top-down adhesive market sizing were triangulated for convergence.
Data-stream reconciliation across product chemistry, application performance tiers, and regional regulatory clusters shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include hydrogenation depth, softening point precision, formulation type, and end-use qualification burden. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion schedules. Industry-specific forecast inputs incorporated electric vehicle lightweighting mandates and e-commerce packaging demand trajectories.
Several conditions sit outside the modeled scope, including unannounced regulatory timeline accelerations, breakthrough bio-based tackifier commercialization, and geopolitical trade restriction escalations. Forecasts reflect documented assumptions regarding refinery integration economics and catalyst technology diffusion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Zinc Dialkyldithiophosphates Additive Market
Additives
North America Fuel Additives Market
Additives
Ammonium Acetate Market
Additives
Gasoline Additives Market
Additives
Anti-Settling Agents Market
Additives
Inorganic Rheology Modifiers Market
Additives
Powder Induction and Dispersion Systems Market
Additives
Cetane Improver Additives Market
Additives
Russia Sodium Reduction Ingredient Market
Additives
Low VOC Coating Additives Market
Additives
Tamarind Gum Derivatives Market
Additives
Asia-Pacific Fuel Additives Market
Additives
United Kingdom Sodium Reduction Ingredient Market
Additives
Printing Ink Additives Market
Additives
Trioctyldodecyl Citrate Market
Additives
Low Melt Inclusions Market