
 Biosaccharide Gum Market | 2026-2036
Biosaccharide Gum Market Size, Share, and Industry Trends Forecast 2026-2036
Biosaccharide Gum Market Analytics
Buyer concentration among multinational cosmetic formulators is realigning procurement leverage toward fermented biopolymer suppliers. Solabia Group anchors European supply through specialized fermentation infrastructure for cosmetic-grade polysaccharides. Lucas Meyer Cosmetics (IFF) leverages its integrated flavor and fragrance network to cross-sell biosaccharide gum into prestige skincare channels. Seppic competes through differentiated marine biotechnology expertise, particularly in sulfated polysaccharide extraction.
Biosaccharide gum comprises high-molecular-weight exopolysaccharides produced via microbial fermentation, typically achieving viscosities between 1,000 and 50,000 cP depending on strain and substrate; these biopolymers function primarily as rheology modifiers, stabilizers, and moisture-retention agents across cosmetic and pharmaceutical matrices. Xanthan gum dominates volume shipments due to mature fermentation economics and broad pH tolerance, while gellan gum captures accelerating demand in clear-acid beverage systems and ophthalmic formulations where thermal-reversible gelation proves critical. Powder form maintains the largest share of industrial transactions, though liquid concentrates gain traction in continuous-manufacturing personal care operations.
FDA cosmetic ingredient scrutiny under the Modernization of Cosmetics Regulation Act converges with REACH substance evaluation and China's GB standards for microbial polysaccharide purity, collectively elevating analytical certification burdens for market entry. ECHA's evolving polymer registration requirements and South Korea's MFDS biopolyderm guidelines further fragment compliance pathways across major demand centers. Stakeholders must monitor regulatory divergence between fermentation-derived and plant-extracted hydrocolloids, as classification decisions will reshape competitive access and reformulation costs.
Market Dynamics
Fermentation-derived hydrocolloids face intensifying traceability mandates as the EU Green Deal and REACH polymer registration requirements tighten documentation burdens across cosmetic and pharmaceutical supply chains. This regulatory compression is redrawing competitive access for microbial exopolysaccharide suppliers.
Growth Catalysts
- Clean-label fermentation:South Korea's MFDS biopolyderm guidelines validate microbial polysaccharide safety profiles, accelerating prestige skincare adoption of biosaccharide gum as a plant-extract alternative.
- Thermal-reversible gelation demand:Ophthalmic formulation manufacturers specify gellan gum for sustained-release eye drops, exploiting its unique sol-gel transition properties.
- REACH substance evaluation:ECHA's evolving polymer registration creates first-mover certification advantages for European fermentation facilities with pre-registered hydrocolloid dossiers.
Market Restraints
- Substrate cost volatility:Glucose and sucrose feedstock prices fluctuate with Brazilian sugarcane harvest cycles, compressing fermentation margins for xanthan gum producers.
- Supply concentration risk:Three specialized fermentation facilities in France and Germany control over half of cosmetic-grade biosaccharide gum capacity in Europe.
- Plant-extract substitution:Carrageenan and locust bean gum suppliers target clear-label beverage applications with comparable viscosity profiles at lower price points.
Strategic Opportunities
- Underpenetrated pharmaceutical excipients:India's CDSCO fast-track approval pathways for novel excipients enable biosaccharide gum entry into generic drug matrix formulations.
- Continuous manufacturing integration:Liquid concentrate biosaccharide gum formats align with single-use bioreactor workflows in Singaporean and Swiss contract manufacturing organizations.
- Marine biotechnology convergence:Sulfated polysaccharide extraction from macroalgae combines with microbial fermentation to create hybrid hydrocolloids with enhanced bioadhesion.
Industry Challenges
- Fermentation scale-up expertise:Aerobic biopolymer production requires rare combinations of biochemical engineering and GMP compliance skills concentrated in Basel and Boston clusters.
- Multi-jurisdiction certification timelines:Simultaneous FDA cosmetic ingredient notification, REACH polymer registration, and China's NMPA microbial polysaccharide approval extend commercialization cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biosaccharide Gum Market |
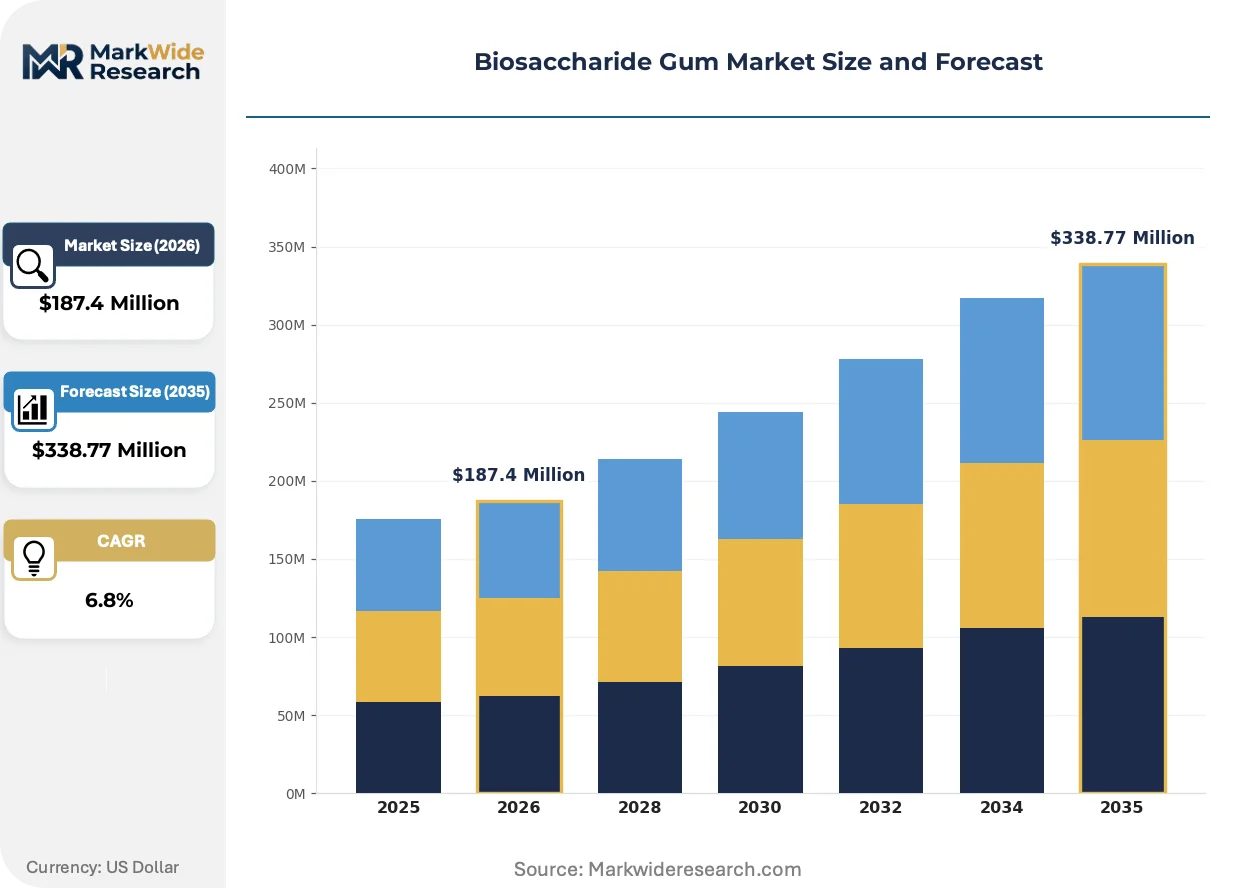
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Agar, Guar Gum, Xanthan Gum, Gellan Gum Application: Food & Beverage, Pharmaceuticals, Personal Care, Industrial Form: Powder, Liquid, Gel, Granular End User: Food Manufacturers, Cosmetic Companies, Pharmaceutical Firms, Research Institutions |
| Companies Covered | Solabia Group, Lucas Meyer Cosmetics (IFF), Clariant AG, Ashland Inc., Guangzhou Chuanyan Chemical, Seppic, Givaudan, CP Kelco, Cargill, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biosaccharide Gum Market Evolving Landscape
Precision fermentation and downstream processing advances are compressing the cost gap between microbial exopolysaccharides and plant-derived hydrocolloids. Three developments are restructuring how biosaccharide gum penetrates formulation markets.
Cell-free enzymatic synthesis of xanthan gum precursors is electrifying pilot-scale production economics by eliminating sterilization energy costs and shortening batch cycles from days to hours. Specialty chemical manufacturers in the Netherlands and California are licensing this technology for cosmetic-grade output. The approach is compressing capital requirements for new market entrants previously blocked by fermentation infrastructure barriers.
REACH polymer registration deadlines are forcing European suppliers to consolidate analytical certification investments or exit the market entirely. ECHA's substance evaluation criteria now demand full monomer disclosure and biodegradation data for hydrocolloid imports. Cosmetic formulators in Germany and France are pre-qualifying suppliers with complete dossiers, excluding late-registrants from tender processes.
Direct procurement contracts between fermentation facilities and multinational formulators are displacing traditional distributor networks in East Asian personal care clusters. Buyers in Osaka and Seoul now negotiate volume commitments with Solabia Group and comparable suppliers for three-year supply security. This channel compression is visible most acutely in prestige skincare, where traceability documentation requirements exceed distributor capabilities.
Biosaccharide Gum Market Segmentation
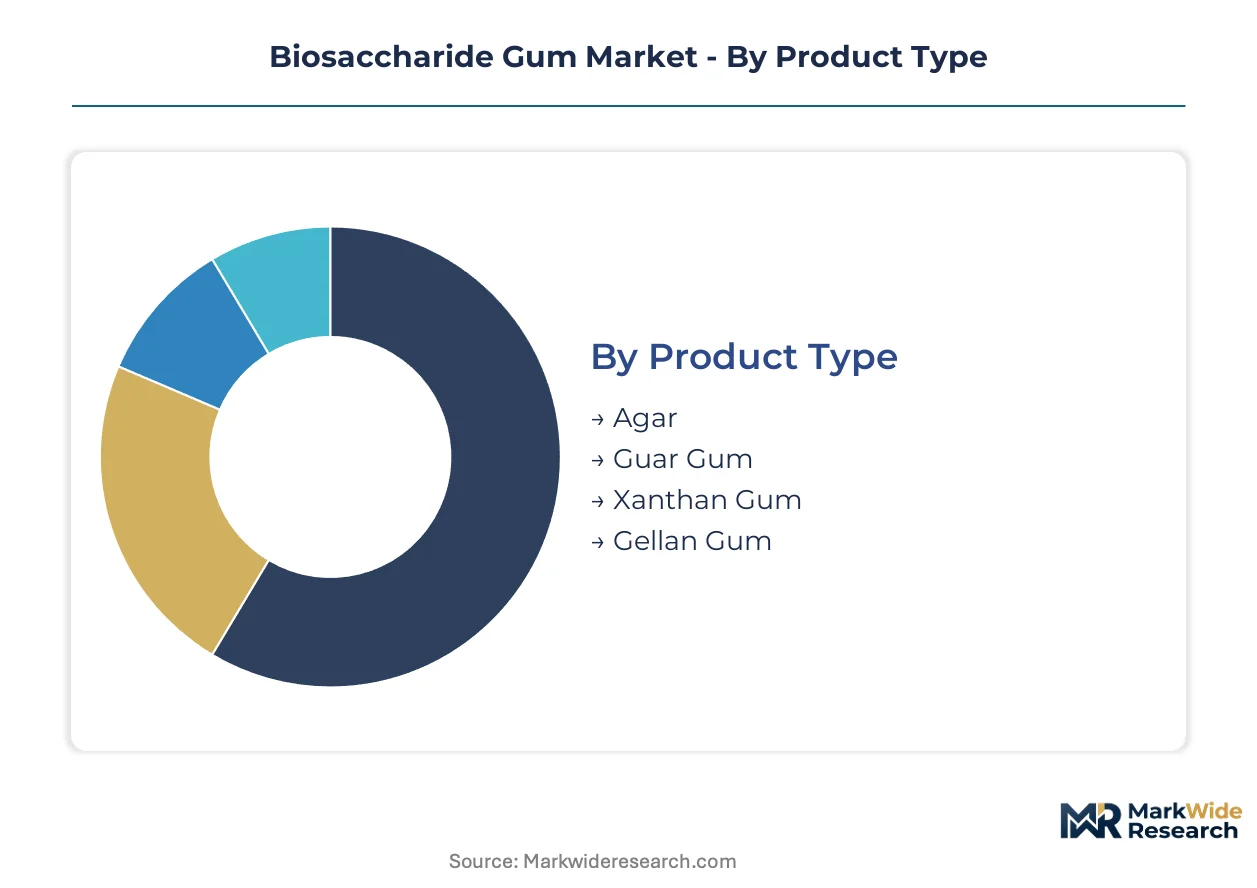
Biosaccharide gum segmentation reveals how fermentation economics and formulation requirements split procurement patterns across industries. Supply concentration in specialized bioreactor facilities creates divergent cost structures for each product category.
Product Type:
Fermentation capacity for high-viscosity exopolysaccharides concentrates in facilities with GMP-certified aerobic bioreactor infrastructure.
- Xanthan Gum:High-molecular-weight polysaccharide produced via Xanthomonas campestris fermentation achieves viscosities between 1,000 and 50,000 cP with broad pH tolerance from 1 to 13. Food manufacturers in Brazil and corn belt US states anchor volume demand; glucose feedstock price volatility from sugarcane harvest cycles compresses margin structures during Q3 procurement windows.
- Gellan Gum:Sphingomonas elodea-derived biopolymer forms thermal-reversible gels with unique sol-gel transition properties critical for sustained-release matrices. Ophthalmic formulators in Singapore and Swiss contract manufacturing organizations specify low-acyl grades; CDSCO fast-track excipient approvals in India are opening generic drug penetration channels.
- Agar:Macroalgae-extracted polysaccharide from Gelidium and Gracilaria species provides thermoplastic gelation for microbiological media and confectionery applications.
- Guar Gum:Legume seed endosperm polysaccharide competes on cost in hydraulic fracturing and textile sizing despite microbial gum substitution pressure in food systems.
Xanthan gum absorbs the bulk of installed capacity; gellan gum is expanding most quickly.
Application:
Formulation complexity and regulatory certification burdens stratify demand intensity across end-use sectors.
- Personal Care:Prestige skincare brands in Seoul and Osaka specify biosaccharide gum for fermented formulation positioning under clean-label positioning. MFDS biopolyderm guidelines validate microbial polysaccharide safety profiles; three-year direct procurement contracts with Solabia Group and comparable suppliers are displacing traditional distributor networks.
- Pharmaceuticals:Sustained-release matrix and ophthalmic drop applications exploit gellan gum's ion-sensitive gelation kinetics. FDA Modernization of Cosmetics Regulation Act scrutiny converges with REACH substance evaluation to elevate analytical certification burdens for excipient entry.
- Food & Beverage:Clear-acid beverage systems and plant-based dairy alternatives drive viscosity modification demand from xanthan and gellan grades.
- Industrial:Oilfield drilling fluids and textile printing thickeners consume commodity-grade guar and xanthan volumes at price-sensitive contract terms.
Personal care commands premium positioning; pharmaceuticals is climbing the fastest on regulatory validation tailwinds.
Form:
Downstream processing intensity and logistics economics determine format selection for continuous versus batch manufacturing environments.
- Powder:Spray-dried and drum-dried particulate grades dominate industrial transactions with extended shelf stability and containerized shipping efficiency. Cosmetic-grade powder requires micronization and endotoxin control investments that concentrate supply among French and German fermentation facilities.
- Liquid:Preserved aqueous concentrates align with single-use bioreactor workflows and continuous-manufacturing personal care operations in Singaporean and Swiss contract manufacturing organizations. Cold-chain logistics constraints limit geographic reach to regional processing clusters.
- Gel:Pre-hydrated dispersions eliminate dust handling and dissolution time for small-batch cosmetic compounding.
- Granular:Agglomerated grades improve dispersibility in high-shear food processing equipment without lump formation.
Powder maintains dominant share; liquid concentrates are gaining share fastest in continuous manufacturing integration.
End User:
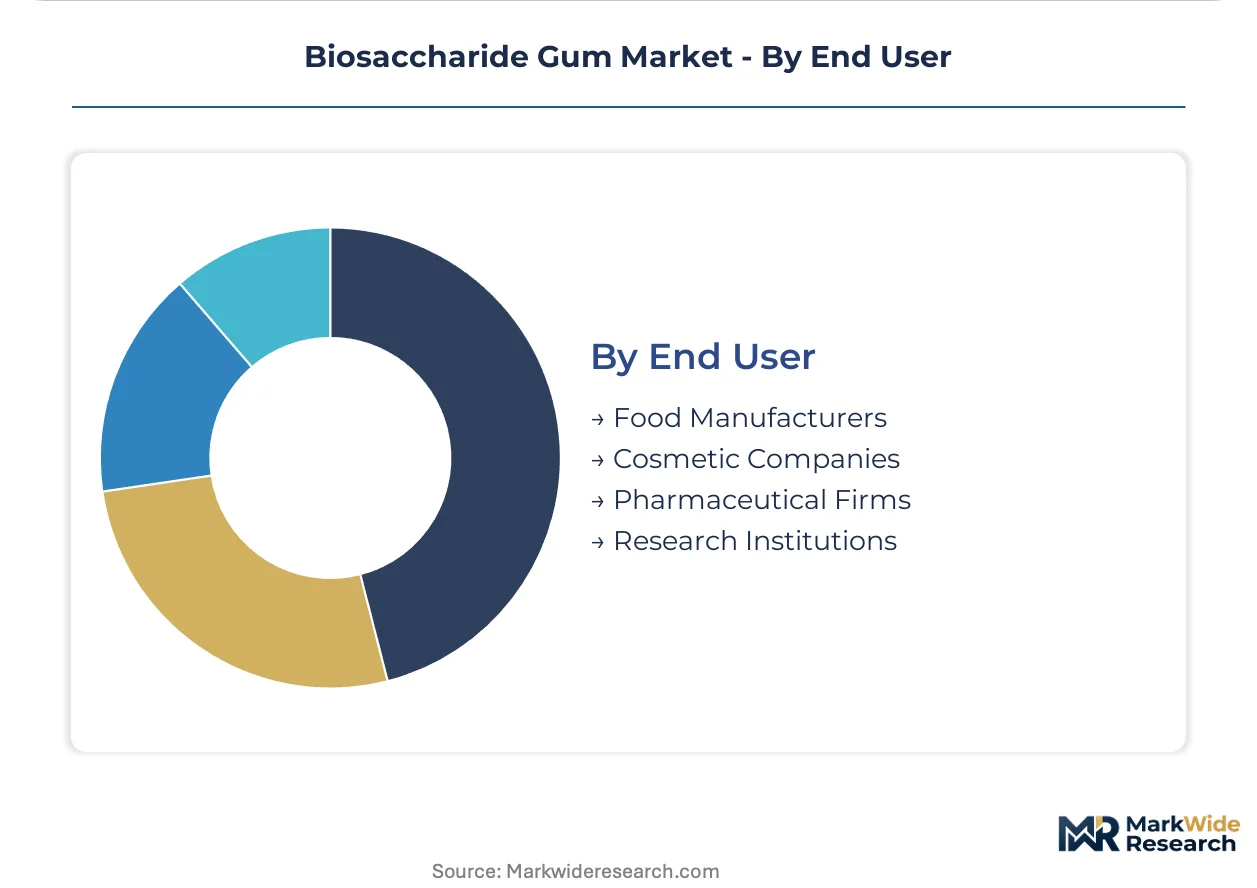
Procurement sophistication and traceability documentation requirements fragment customer tiers across formulation industries.
- Cosmetic Companies:Multinational formulators in South Korea and Japan leverage integrated flavor and fragrance networks to cross-sell biosaccharide gum into prestige skincare channels. ECHA polymer registration dossiers and REACH substance evaluation criteria now exclude late-registrant suppliers from German and French tender processes.
- Pharmaceutical Firms:Generic drug manufacturers in India exploit CDSCO fast-track excipient pathways; novel matrix formulations require simultaneous FDA notification, REACH registration, and NMPA microbial polysaccharide approval extending commercialization cycles.
- Food Manufacturers:Clean-label positioning drives substitution of synthetic thickeners with fermentation-derived alternatives in beverage and dairy applications.
- Research Institutions:Microbiological media and diagnostic reagent producers specify agar and specialty gellan grades at lower volume scales.
Cosmetic companies absorb the bulk of high-margin capacity; pharmaceutical firms are expanding most quickly on excipient validation investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for biosaccharide gum concentrates most acutely in East Asian personal care clusters, where clean-label fermentation-derived ingredients command premium positioning. South Korea and Japan anchor procurement volume for prestige skincare formulations. European regulatory tightening under REACH and the EU Green Deal is redrawing supplier access patterns.
South Korea
Seoul-based cosmetic formulators specify biosaccharide gum for fermented skincare positioning under MFDS biopolyderm guidelines. The regulator validates microbial polysaccharide safety profiles, accelerating plant-extract substitution. Direct procurement contracts with Solabia Group and comparable suppliers now displace traditional distributor networks in the capital region.
Japan
Osaka and Tokyo cosmetic clusters drive gellan gum demand for clear-acid beverage systems and ophthalmic formulations. METI standards for biopolymer purity elevate analytical certification burdens for import suppliers. Japanese formulators leverage three-year volume commitments with European fermentation facilities to secure traceability documentation.
Germany
ECHA polymer registration requirements and REACH substance evaluation criteria exclude late-registrant hydrocolloid suppliers from tender processes. Cosmetic compounders in Hamburg and Frankfurt pre-qualify vendors with complete dossiers. German fermentation facilities control substantial cosmetic-grade biosaccharide gum capacity through GMP-certified aerobic bioreactor infrastructure.
United States
FDA Modernization of Cosmetics Regulation Act scrutiny converges with state-level clean-label mandates to elevate entry barriers for microbial polysaccharide suppliers. Boston and Basel-area biochemical engineering clusters concentrate rare fermentation scale-up expertise. Domestic formulators face extended commercialization cycles for novel excipient applications.
India
CDSCO fast-track approval pathways for novel excipients enable biosaccharide gum penetration into generic drug matrix formulations. Mumbai and Hyderabad pharmaceutical clusters specify gellan gum for sustained-release ophthalmic drops. Indian manufacturers exploit regulatory arbitrage between FDA notification timelines and domestic approval pathways.
Biosaccharide Gum Market Competitive Landscape
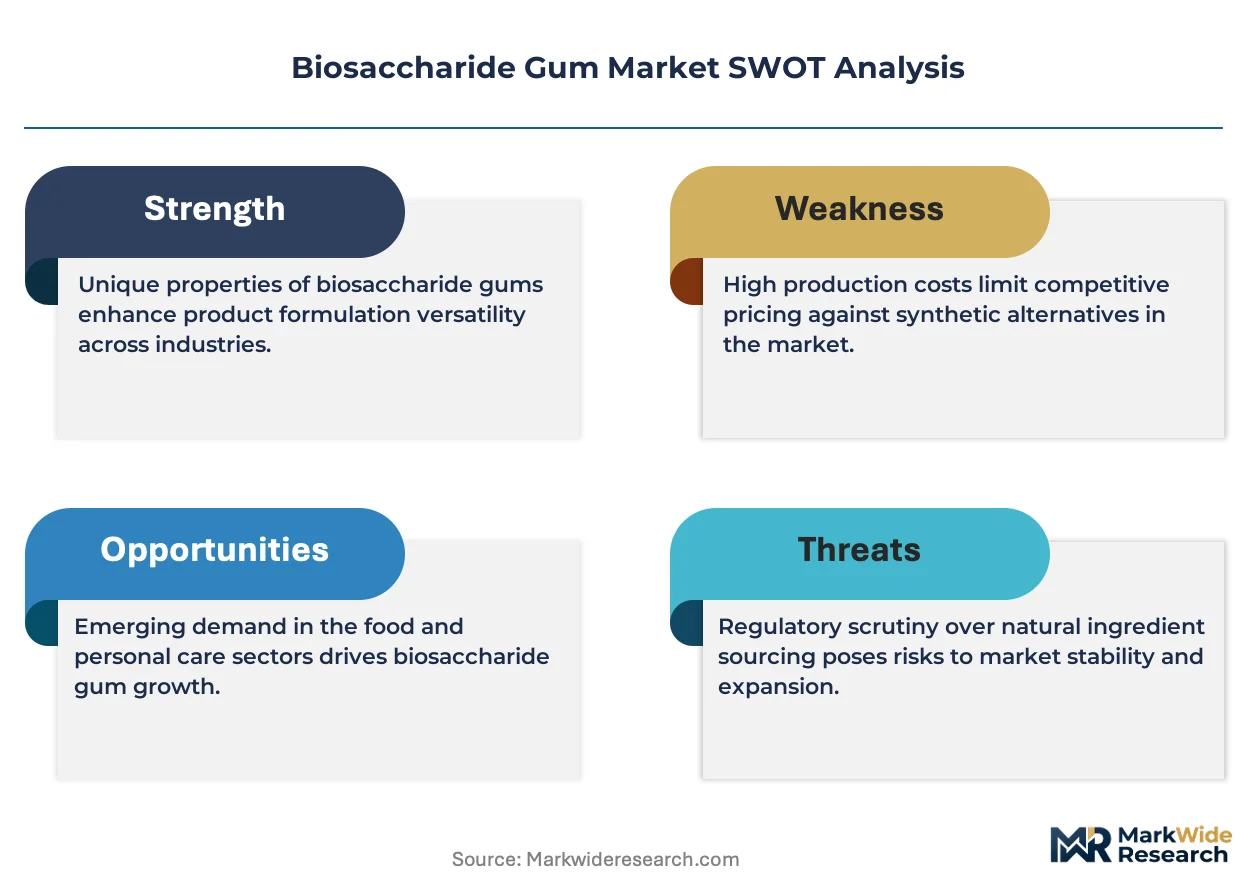
Established producers occupy the standard tier; emerging entrants pursue cell-free enzymatic synthesis and marine biotechnology hybrids. The vendor base stratifies across three tiers: integrated multinational suppliers with flavor-and-fragrance networks, specialized fermentation houses with GMP-certified infrastructure, and regional chemical distributors facing REACH registration exclusion. Two strategic archetypes dominate: certification-first incumbents leveraging pre-registered ECHA dossiers, and technology-forward challengers licensing enzymatic production methods. Capacity expansion and direct procurement contracting constitute the primary competitive vectors.
Within the integrated multinational tier, Solabia Group and Lucas Meyer Cosmetics (IFF) exemplify divergent positioning strategies. Solabia anchors European supply through specialized fermentation infrastructure, while Lucas Meyer leverages cross-selling opportunities across flavor, fragrance, and prestige skincare channels. Among pure-play fermentation specialists, Seppic occupies a position defined by marine biotechnology expertise in sulfated polysaccharide extraction. These three entities represent the competitive archetypes reshaping procurement relationships in East Asian personal care clusters.
| Leading Market Players |
|---|
| Solabia Group |
| Lucas Meyer Cosmetics (IFF) |
| Clariant AG |
| Ashland Inc. |
| Guangzhou Chuanyan Chemical |
| Seppic |
| Givaudan |
| CP Kelco |
| Cargill |
| Others |
Value Network & Pricing Analysis
Three-year direct procurement contracts between East Asian cosmetic formulators and European fermentation facilities are compressing distributor margins while elevating price premiums for traceability-certified grades. This buyer-driven consolidation forces supply-side specialization around GMP-certified aerobic bioreactor capacity, bifurcating the market between documented premium tiers and undocumented commodity flows.
Pricing Analysis
Volume shipments of xanthan gum absorb commodity pricing pressure from Brazilian sugarcane harvest cycles, while gellan gum and cosmetic-grade specialty polysaccharides sustain margin premiums through REACH registration scarcity and MFDS biopolyderm certification. Three-tier pricing structure across premium, standard, and economy levels stratifies by documentation completeness: cosmetic-grade powder with endotoxin control and ECHA dossiers commands substantial premiums over industrial fluid grades. Cost compression in standard-tier xanthan runs through glucose feedstock volatility, particularly during Q3 procurement windows. Food manufacturers exhibit highest price sensitivity; ophthalmic formulators and prestige skincare brands show lowest sensitivity due to regulatory substitution constraints.
Supply Chain Analysis
Reverse-logistics flows for liquid concentrate returns are minimal given cold-chain degradation risks, though powder-grade returns for re-micronization circulate through specialized French and German processing facilities. Supply concentrates in France, Germany, and South Korea, with GMP-certified fermentation infrastructure anchored in Basel-area and Boston biochemical engineering clusters. Raw material dependencies rest on Brazilian glucose and sucrose feedstocks, Chinese mineral nutrients for bioreactor media, and Indonesian macroalgae for hybrid marine-microbial grades. Single-source vulnerability concentrates in three European cosmetic-grade facilities controlling over half of regional capacity. Distribution runs through direct procurement contracts displacing traditional distributor networks in Seoul and Osaka clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell-free enzymatic synthesis is displacing legacy aerobic fermentation for xanthan gum precursors, compressing capital barriers for new entrants while threatening incumbent fermentation infrastructure valuations. This technology transition favors agile licensing players over sunk-cost-heavy facility operators.
For Market Incumbents: Deepen GMP-certified capacity concentration in Basel and Boston clusters to defend against cell-free enzymatic challengers licensing technology from Netherlands and California specialty chemical manufacturers. Prioritize REACH polymer registration dossier completeness to exclude late-registrants from German and French cosmetic tender processes. Anchor supply security through backward integration into glucose feedstock sourcing or long-term offtake agreements with Brazilian suppliers. For New Entrants and Emerging Players: Launch via CDSCO fast-track excipient approval pathways in Indian generic drug markets, where regulatory arbitrage between FDA notification timelines and domestic approval creates white-space penetration opportunities. Target sustained-release ophthalmic formulations in Mumbai and Hyderabad pharmaceutical clusters. Exploit marine biotechnology convergence by licensing sulfated polysaccharide extraction capabilities for hybrid hydrocolloid development. For Investors and Strategic Acquirers: The window for entry favors cell-free enzymatic synthesis technology licensors and marine biotechnology hybrid developers over traditional fermentation facility operators facing stranded asset risk. Long-term viability centers on defensible intellectual property in enzymatic production methods or exclusive macroalgae supply agreements. Monitor ECHA polymer registration deadline compliance rates as inflection indicator for supplier consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Polymer Registration Completion | ECHA dossier completeness excludes late entrants from German cosmetic tender processes. |
| Cell-Free Enzymatic Synthesis Licensing | Netherlands and California technology licensors compress batch cycles from days to hours. |
| Direct Procurement Contracting | Three-year volume commitments with Seoul and Osaka formulators displace distributor networks. |
| Marine Biotechnology Hybrid Development | Sulfated polysaccharide extraction from macroalgae creates bioadhesion-enhanced hydrocolloids. |
| CDSCO Fast-Track Excipient Approval | Indian generic drug penetration opens sustained-release matrix formulation channels. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews with fermentation facility plant managers, cosmetic procurement leads at multinational formulators, pharmaceutical excipient specialists, and distribution channel partners. Secondary validation drew from ECHA registration databases, MFDS biopolyderm guidelines, FDA cosmetic ingredient notifications, and CDSCO excipient approval records. Bottom-up capacity modeling and top-down demand triangulation cross-verified volume estimates across the analysis window.
Granularity-level modeling operated at strain-specific fermentation economics, grade-tier purity specifications, and end-use regulatory certification requirements. Segmentation dimensions included product type, application, physical form, and end-user procurement sophistication, with regional production hub clustering for supply-side constraints. CAGRs derived from capacity expansion pipelines, substitution elasticity estimates, and regulatory timeline assumptions. Industry-specific inputs incorporated Brazilian sugarcane harvest cycle impacts on glucose pricing and East Asian clean-label formulation adoption curves.
Regulatory timeline delays, feedstock price volatility, and technology transition acceleration are the dominant revision risks to forecast outputs. Forecasts reflect assumptions around REACH registration compliance rates and enzymatic synthesis licensing velocity. Practitioners should monitor ECHA substance evaluation criteria updates and cell-free production scale-up announcements for early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Plastic Fillers Market
Additives
Additives for Floor Coatings Market
Additives
Global UV Absorbers Market
Additives
Metal Modifiers Market
Additives
Alkyl Ketene Dimers (AKD) Wax Market
Additives
Binder Excipients Market
Additives
Sorbitan Laurate Market
Additives
Metallic Stearate Market
Additives
Iso-Butyric Acid Market
Additives
Chelated Selenium Market
Additives
Global Asphalt Additives Market
Additives
Rheological Additives Market
Additives
Packaging Coating Additives Market
Additives
Adjustive Agents Market
Additives
Tackifier Market
Additives
Pearlizers Market